
 Hazardous Disposal Bag Market | 2026-2036
Hazardous Disposal Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Hazardous Disposal Bag Market Foresight
Modular bag-and-container bundling is consolidating buyer preference across hospital and laboratory procurement channels. Stericycle Inc leverages its integrated waste collection infrastructure to anchor national service contracts. Clean Harbors Inc competes through specialized hazardous waste treatment capabilities that extend beyond bag supply into downstream disposal. Veolia Environnement dominates European environmental service networks with closed-loop containment logistics.
Hazardous disposal bags are engineered containment vessels manufactured from polyethylene, polypropylene, or vinyl formulations with specified tensile strength and puncture resistance ratings for regulated waste segregation. Their primary industrial purpose is to prevent exposure to biohazardous, chemical, or sharps waste during generation, transport, and terminal treatment. Closure Bags and biohazard bag categories lead volume due to universal adoption in medical facilities, while High-Density Polyethylene formulations capture margin pools through superior chemical compatibility in manufacturing plant applications. Research Laboratories represent the fastest-growing application segment as biopharma R&D expansion drives specialized containment protocols.
EPA hazardous waste regulations and OSHA bloodborne pathogen standards govern material specifications and worker handling protocols in the United States market. FDA medical device classification requirements for sharps containers intersect with DOT transport rules to create multi-layer compliance obligations for manufacturers. Stakeholders must monitor evolving state-level hazardous waste designation changes and antimicrobial additive restrictions that will reshape material selection and certification investments.
Market Dynamics
Healthcare procurement consolidation is compressing vendor margins while demanding integrated containment-to-disposal service bundles from single-source contractors.
Growth Catalysts
- EPA hazardous waste designation expansion:Broader classification of pharmaceutical residues as RCRA hazardous waste mandates specialized containment infrastructure across hospital networks.
- Biopharma manufacturing capacity expansion:Cell therapy production facilities in Singapore and Switzerland require closed-loop bag systems for live viral vector handling.
- Color-coded segregation protocols:WHO infection control guidelines standardize yellow-red-black bag systems, driving replacement cycles in developing health systems.
Market Restraints
- Linear low-density polyethylene price volatility:Ethylene feedstock costs tied to naphtha cracking margins compress bag manufacturer margins unpredictably.
- Antimicrobial additive regulatory friction:ECHA biocidal product regulation restricts silver-ion and triclosan formulations used in premium bag grades.
- Autoclave-resistant film substitution:Reusable rigid container systems displace single-use bags in high-volume surgical waste streams at major academic medical centers.
Strategic Opportunities
- Indian hospital accreditation mandates:NABH certification requirements for biomedical waste management create first-time demand in tier-2 and tier-3 cities.
- Radioactive pharmaceutical waste containment:Lutetium-177 and actinium-225 radioligand therapy expansion requires lead-lined bag systems with specialized closure mechanisms.
- Reverse logistics integration:Digital tracking platforms combining RFID bag tagging with blockchain manifesting enable outcome-based service pricing models.
Industry Challenges
- Multilayer film coextrusion expertise scarcity:Seven-layer barrier film production requires polymer science specialists concentrated at limited compounder facilities.
- DOT special permit certification timelines:UN-certified packaging approvals for Category A infectious substance bags extend 18-24 months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hazardous Disposal Bag Market |
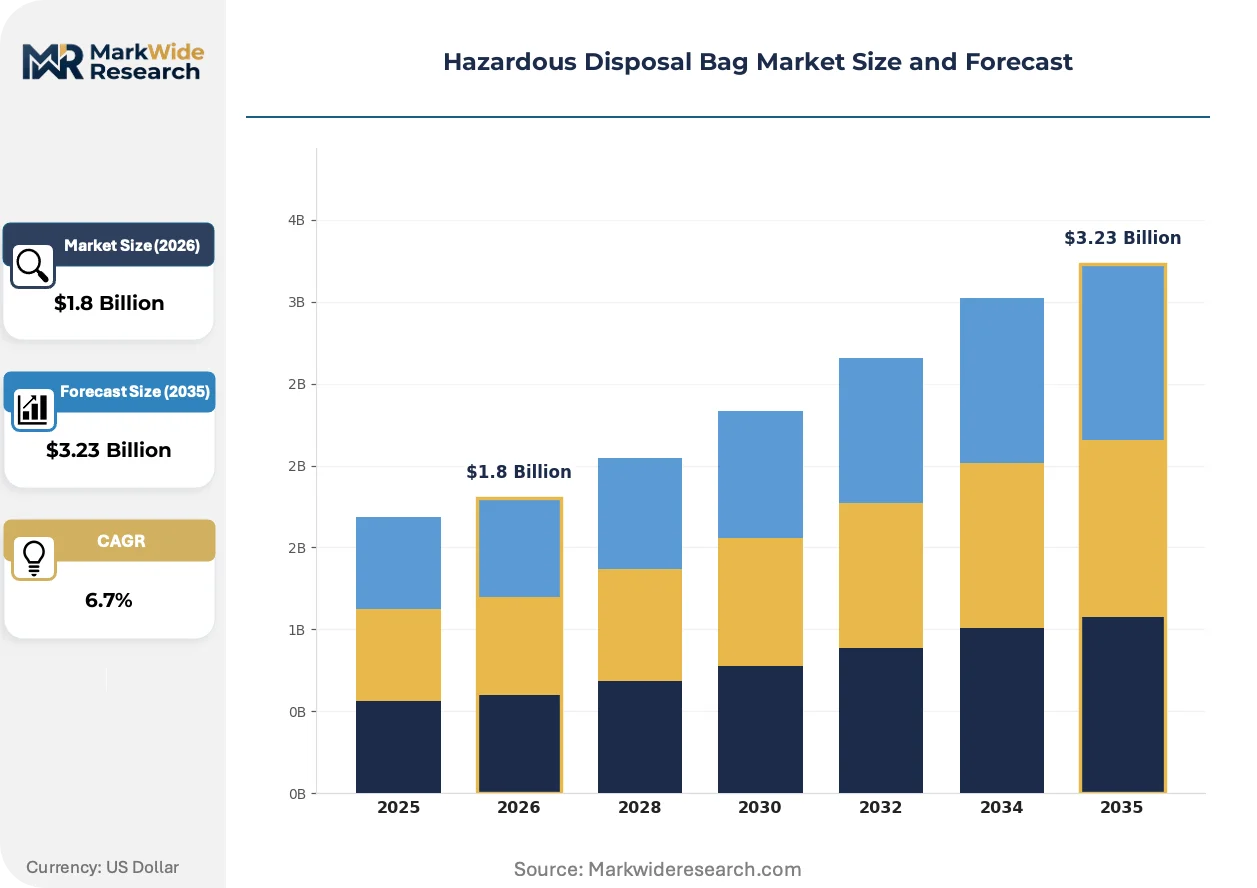
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closure Bags, Biohazard Bags, Hazardous Waste Bags, Sharps Containers Material: Polyethylene, Polypropylene, High-Density Polyethylene, Vinyl Application: Medical Facilities, Manufacturing Plants, Research Laboratories, Waste Management Size: Small, Medium, Large, Extra Large |
| Companies Covered | Stericycle Inc, Clean Harbors Inc, Veolia Environnement, Waste Management Inc, Republic Services Inc, Daniels Sharpsmart Inc, Sharps Compliance Inc, Biomedical Waste Solutions LLC, Suez Environment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hazardous Disposal Bag Market Shifts & Advancements
Material science breakthroughs are collapsing the functional gap between commodity polyethylene bags and engineered multilayer barriers, reshaping procurement criteria across regulated waste streams.
Multilayer coextrusion technology is unifying puncture resistance, chemical compatibility, and autoclave sterilization tolerance in single-film structures. Research laboratories and biopharma manufacturing suites are adopting these advanced formulations to reduce SKU complexity and inventory overhead. The convergence is compressing demand for standalone high-density polyethylene chemical bags and vinyl sharps alternatives into unified procurement specifications.
REACH restriction proposals targeting per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant medical waste bags used in pathology laboratories. Manufacturers face substitution timelines for fluoropolymer barrier coatings while maintaining ASTM tear-strength benchmarks. German and French hospital procurement consortiums are accelerating qualification of silicone-modified polyethylene alternatives ahead of anticipated 2027 enforcement windows.
Consolidated service contracts now bundle bag supply with collection logistics and treatment disposal, displacing standalone product purchasing. Specialty waste service providers capture multi-year agreements with integrated pricing per bed or per procedure. This restructuring concentrates buying power in the hands of Stericycle, Veolia, and regional treatment facility networks across North American metropolitan hospital systems.
Hazardous Disposal Bag Market Segmentation
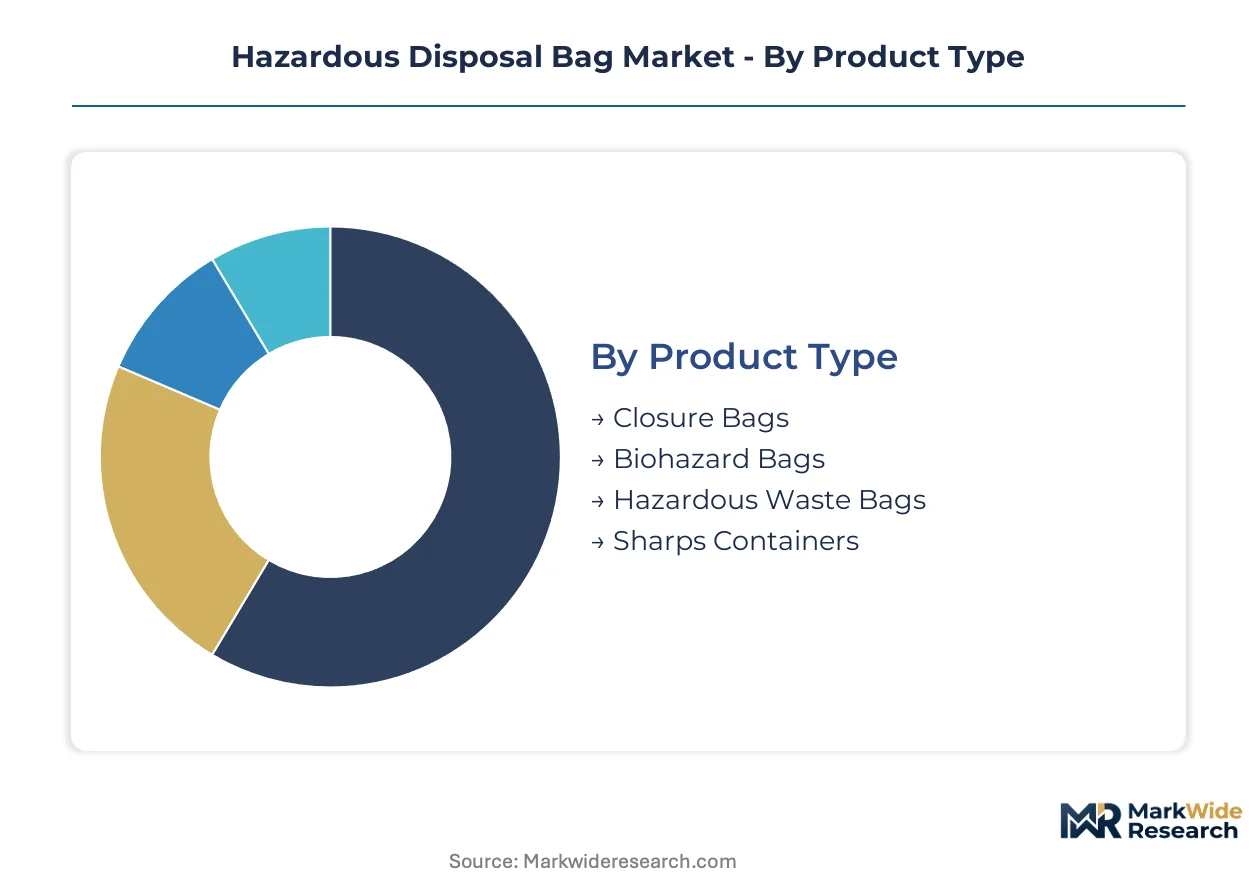
Segmentation in hazardous disposal bags reflects divergent technical specifications across waste streams, with procurement teams balancing containment performance against disposal pathway economics. Material selection and bag geometry directly determine compliance eligibility for specific regulated waste categories.
Product Type:
Hospital procurement teams prioritize closure integrity and color-coding standardization when selecting containment systems for regulated waste streams.
- Closure Bags:Heat-sealable polyethylene constructions with zip-tie or adhesive strip sealing mechanisms satisfy DOT transport requirements for Category B infectious substances. Demand concentrates in outpatient surgical centers and dialysis clinics across the United States where generator status limits storage duration.
- Biohazard Bags:Red or orange pigmented films meeting OSHA bloodborne pathogen standard 29 CFR 1910.1030 specifications dominate infectious waste segregation in acute care hospitals. EPA hazardous waste designation expansion for pharmaceutical residues is driving specification upgrades in hospital pharmacy departments.
- Hazardous Waste Bags:Chemical-resistant formulations for RCRA-regulated solvent and reagent containment in manufacturing environments.
- Sharps Containers:Rigid puncture-resistant enclosures for needles and surgical instruments, often paired with flexible secondary containment bags.
Volume sits with Biohazard Bags; growth tilts toward Closure Bags.
Material:
Feedstock cost volatility and chemical compatibility requirements shape compounder formulation strategies across end-use applications.
- High-Density Polyethylene:Superior tensile strength and chemical resistance properties support solvent containment in pharmaceutical manufacturing suites. Singapore and Switzerland biopharma clusters specify HDPE formulations for live viral vector handling protocols.
- Polyethylene:Linear low-density variants balance puncture resistance with cost efficiency for general medical waste streams. Ethylene feedstock costs tied to naphtha cracking margins compress manufacturer margins unpredictably.
- Polypropylene:Autoclave sterilization tolerance supports reusable container liner applications in academic medical centers.
- Vinyl:Legacy formulations for pathology laboratory grease-resistant applications facing REACH substitution timelines.
Volume concentrates in Polyethylene commodity grades; margin expansion tracks High-Density Polyethylene adoption in chemical processing.
Application:
Regulatory enforcement intensity and waste generator status determine specification stringency across facility types.
- Research Laboratories:Multilayer coextrusion formulations with seven-layer barrier structures support biopharma R&D containment protocols. Cell therapy production expansion in Singapore and Switzerland requires closed-loop bag systems with specialized closure mechanisms.
- Medical Facilities:Universal adoption of color-coded segregation systems under WHO infection control guidelines drives replacement cycles in developing health systems. NABH certification requirements in India create first-time demand in tier-2 and tier-3 cities.
- Manufacturing Plants:Chemical compatibility specifications for industrial solvent and reagent waste streams.
- Waste Management:Collection logistics providers specifying standardized containment for transport efficiency.
Medical Facilities anchor current procurement volume; Research Laboratories display the steepest expansion trajectory.
Size:
Container geometry and handling ergonomics dictate dimensional selection across point-of-generation workflows.
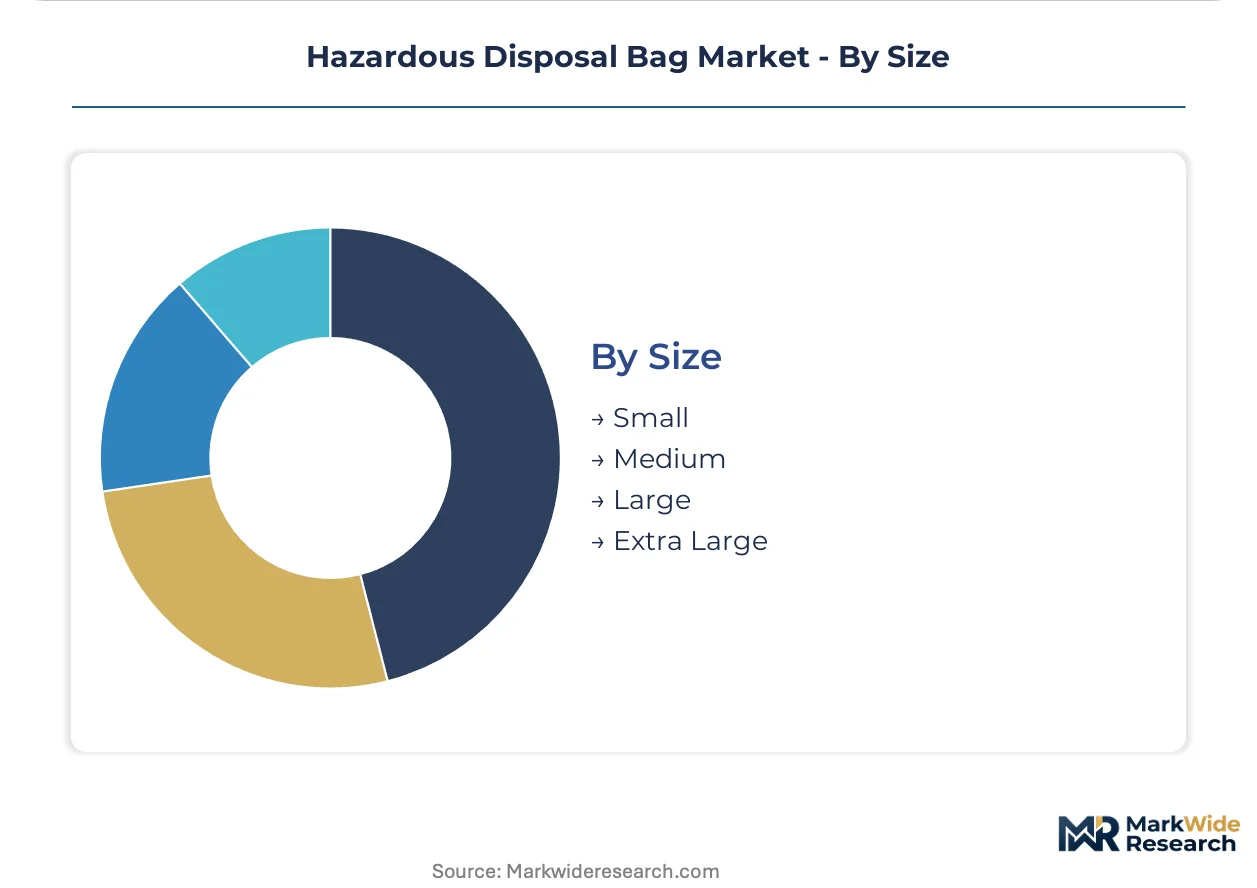
- Large:30-40 gallon capacities for central waste accumulation points in hospital soiled utility rooms. Integrated service contracts with Stericycle and Veolia specify large-format bags for collection route efficiency.
- Small:3-8 gallon capacities for point-of-care generation in patient rooms and procedure suites. Color-coded small bag systems support bedside segregation compliance in United States hospital networks.
- Medium:Intermediate capacities for departmental collection stations.
- Extra Large:Bulk transport configurations for treatment facility intake operations.
Large formats dominate hospital network procurement; small bag demand expands with point-of-care segregation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of hazardous disposal bags concentrates in polymer compounding hubs across Germany, China, and the United States, while consumption patterns track hospital network density and biopharma manufacturing expansion in Switzerland, Singapore, and India.
United States
EPA hazardous waste designation expansion for pharmaceutical residues drives specialized containment procurement across hospital pharmacy departments. OSHA bloodborne pathogen standard 29 CFR 1910.1030 mandates red or orange pigmented films for infectious waste segregation. Boston and San Francisco biopharma clusters specify multilayer barrier formulations for cell therapy production protocols.
Germany
REACH restriction proposals targeting per- and polyfluoroalkyl substances force reformulation of grease-resistant pathology laboratory bags. ECHA biocidal product regulation restricts silver-ion and triclosan formulations used in premium grades. Frankfurt and Munich hospital procurement consortiums accelerate qualification of silicone-modified polyethylene alternatives ahead of anticipated enforcement windows.
Switzerland
Live viral vector handling protocols in cell therapy production facilities require closed-loop bag systems with specialized closure mechanisms. Swissmedic medical device classification requirements intersect with DOT transport rules for Category A infectious substance packaging. Basel and Zurich biopharma manufacturing suites specify seven-layer barrier film structures to reduce SKU complexity.
Singapore
Biopharma manufacturing capacity expansion for radioligand therapy drives demand for lead-lined bag systems with specialized closure mechanisms. The country's national environmental regulator enforces stringent hazardous waste containment specifications for pharmaceutical manufacturing. Tuas Biomedical Park facilities adopt multilayer coextrusion formulations to unify puncture resistance with autoclave sterilization tolerance.
India
NABH certification requirements for biomedical waste management create first-time demand for color-coded segregation systems in tier-2 and tier-3 cities. Central Pollution Control Board biomedical waste management rules mandate puncture-resistant containment for sharps and infectious streams. Hyderabad and Bangalore hospital networks expand procurement of yellow-red-black bag systems under WHO infection control guidelines.
Hazardous Disposal Bag Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the hazardous disposal bag value chain, creating a tiered structure where integrated waste service providers capture multi-year hospital network contracts while regional fabricators supply standalone product orders. The market consolidates around three strategic archetypes: national service contractors bundling containment-to-disposal logistics, specialized hazardous waste treatment operators extending upstream into bag supply, and polymer compounders selling commodity-grade films to distributor channels. Dominant competitive moves include backward integration into polymer compounding capacity and strategic partnerships between bag manufacturers and RFID tracking platform providers.
Among North American integrated service providers, Stericycle Inc and Clean Harbors Inc exemplify the national contractor archetype, anchoring procurement relationships through bundled collection logistics and treatment disposal capabilities. Veolia Environnement represents the European environmental service network model, occupying a position built on closed-loop containment logistics across metropolitan hospital systems. These three companies sit within the tier capturing multi-year agreements with integrated pricing per bed or per procedure, while specialized operators like Daniels Sharpsmart Inc and Sharps Compliance Inc occupy positions focused on point-of-care containment solutions for outpatient and ambulatory settings.
| Leading Market Players |
|---|
| Stericycle Inc |
| Clean Harbors Inc |
| Veolia Environnement |
| Waste Management Inc |
| Republic Services Inc |
| Daniels Sharpsmart Inc |
| Sharps Compliance Inc |
| Biomedical Waste Solutions LLC |
| Suez Environment |
| Others |
Supply & Pricing Matrix
Ethylene feedstock costs tied to naphtha cracking margins cascade through compounding facilities in Germany and China, stratifying bag pricing across premium multilayer formulations and commodity linear low-density polyethylene grades. Hospital procurement consolidation concentrates buyer power, compressing vendor margins while demanding integrated containment-to-disposal bundles from single-source contractors.
Pricing Analysis
Margin tightening in commodity polyethylene tiers reflects ethylene feedstock volatility and hospital GPO consolidation. Three-tier pricing structure across premium, standard, and economy levels separates seven-layer barrier films for biopharma applications from color-coded infectious waste bags and generic clinical liners. Certification grade under DOT special permits and UN packaging standards commands substantial premia. Cost-down pressure on standard-grade manufacturers accelerates because integrated service providers bundle bag supply with collection logistics at fixed per-bed rates. Dialysis clinics and outpatient surgical centers exhibit highest price sensitivity; cell therapy production suites in Singapore and Switzerland demonstrate lowest sensitivity due to containment protocol stringency.
Supply Chain Analysis
Freight cost escalation from polymer compounding hubs to hospital networks reshapes regional sourcing strategies for North American distributors. Manufacturing concentrates in Germany, China, and the United States, with seven-layer coextrusion expertise anchored at limited compounder facilities in these markets. Raw material flows draw from ethylene crackers, masterbatch pigment suppliers, and adhesive closure component manufacturers. Single-source vulnerability sits with multilayer film coextrusion capacity, where polymer science specialist scarcity constrains expansion. Distribution runs through integrated waste service providers, regional medical distributors, and direct hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
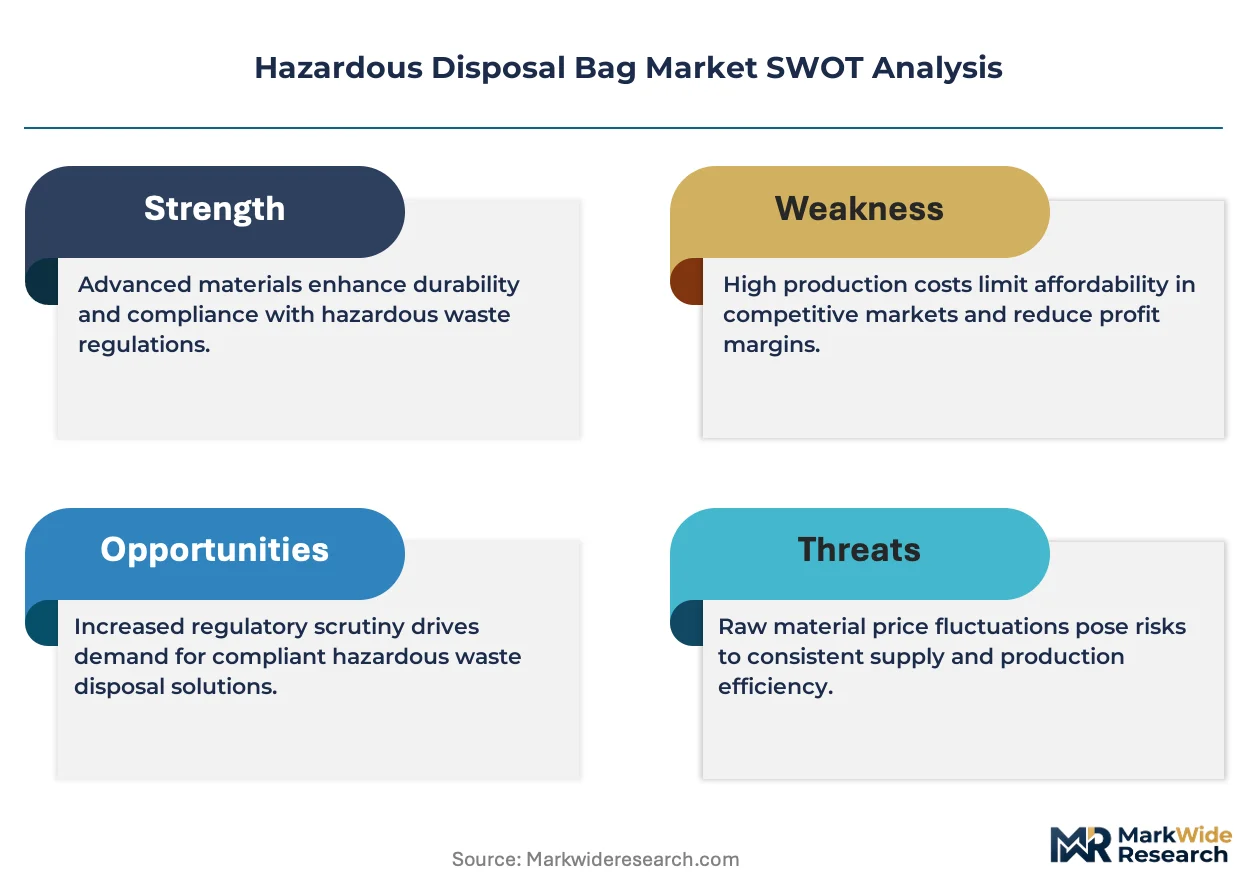
This market functions as a cost-of-compliance story where EPA hazardous waste designation expansion and OSHA bloodborne pathogen standards erect regulatory moats favoring incumbent players with established certification infrastructure and DOT special permit holdings.
For Market Incumbents: Acquire multilayer coextrusion compounder capacity to secure seven-layer barrier film supply for biopharma manufacturing growth. Backward integration into captive polyethylene production mitigates ethylene feedstock volatility exposure. Reinforce DOT special permit certification timelines as competitive barrier against rapid entrant scaling. Channel control through integrated RFID tracking platform partnerships locks in multi-year hospital network contracts. For New Entrants and Emerging Players: RFID-enabled digital tracking platforms offer technology-first entry into reverse logistics integration, displacing legacy manifesting systems. White-space targets concentrate in Indian tier-2 and tier-3 cities under NABH certification mandates, and in lead-lined bag systems for radioligand therapy expansion. The most penetrable segment is specialty containment for research laboratories, where specification complexity deters commodity players. Go-to-market angle emphasizes outcome-based pricing per procedure rather than per-unit product sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor polymer compounders with stranded multilayer film capacity in German industrial regions facing REACH substitution timelines. Long-term viability over the next decade hinges on antimicrobial additive reformulation capabilities and radiopharmaceutical waste containment certifications. Acquisition target archetype: mid-cap specialists with existing DOT Category A infectious substance approvals and biopharma manufacturing relationships. Signal to watch: state-level hazardous waste designation changes accelerating pharmaceutical residue reclassification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive ethylene supply secures margin stability against naphtha cracking volatility. |
| RFID Tracking Platform Partnership | Digital manifesting integration enables outcome-based service pricing with hospital networks. |
| DOT Special Permit Certification Investment | UN packaging approvals create 18-24 month barriers against rapid competitive entry. |
| Antimicrobial Additive Reformulation | ECHA biocidal regulation compliance maintains premium bag grade market access. |
| Radiopharmaceutical Containment Development | Lutetium-177 therapy expansion demands lead-lined bag systems with specialized closures. |
Research Methodology
Trade databases, hospital procurement records, and EPA regulatory filings formed the secondary backbone, cross-referenced with primary interviews conducted with polymer compounding executives, hospital GPO contracts managers, biomedical waste logistics directors, and biopharma manufacturing facility engineers. Bottom-up volume estimates derived from bag consumption rates per hospital bed and per manufacturing suite were triangulated against top-down market sizing from waste service provider revenue disclosures.
Historical trendline analysis of ethylene feedstock pricing, hospital network expansion, and biopharma manufacturing capacity buildouts informed the projection framework. Segmentation dimensions modeled include product type, material formulation, application setting, and regional regulatory cluster. CAGRs were derived from regression analysis of correlated demand drivers across the projection horizon. Industry-specific forecast inputs incorporated REACH restriction timelines for per- and polyfluoroalkyl substances and NABH accreditation rollout pace in Indian secondary cities.
Several conditions sit outside the modeled scope, including abrupt antimicrobial additive bans, autoclave-resistant rigid container substitution acceleration, and geopolitical disruption to ethylene supply chains. Forecasts reflect documented assumptions about regulatory enforcement intensity and hospital procurement consolidation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Face Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Process Safety System Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Splash Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Sports Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
Public Address and Voice Alarm Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
China Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Road Flares Market
Safety Equipment and Personal Protective Equipment (PPE)
Healthcare Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Alarm Management System Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respiratory Protection Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety IO Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Respirator Market