
 Magnetorheological Fluid Market | 2026-2036
Magnetorheological Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetorheological Fluid Market Intelligence
Buyer concentration among aerospace firms and defense contractors is expanding as prime contractors consolidate supplier lists for mission-critical damping systems. Parker Hannifin Corp leverages its channel control across North American aerospace distribution to sustain long-term supply agreements. Ferrotec Corporation anchors its position through in-house production of magnetic particle precursors, reducing feedstock vulnerability. QED Technologies competes in precision optics polishing, a niche where MR fluid performance directly determines surface finish yields.
Magnetorheological fluid consists of micron-sized magnetizable particles suspended in a carrier liquid, typically hydrocarbon oil or synthetic ester, with viscosity modulated by applied magnetic fields up to several hundred millitesla within milliseconds. Its primary industrial purpose lies in semi-active control systems where real-time stiffness or damping adjustment replaces passive mechanical solutions. Standard fluid formulations occupy the mature volume base across automotive and industrial sectors, while high-temperature fluid variants capture margin pools in aerospace propulsion and turbine applications where thermal degradation limits conventional alternatives. Biocompatible fluid development serves prosthetics and medical robotics, though regulatory pathways through FDA and EMA prolong commercialization timelines relative to industrial grades.
FDA device classification requirements shape prosthetics segment entry, while EMA's MDR framework extends compliance burdens for European medical applications. EPA and OSHA standards govern worker exposure limits during particle handling and manufacturing operations in the United States. REACH registration obligations in Europe constrain formulation flexibility for suppliers serving multiple geographies. Stakeholders must weigh regulatory capital requirements against segment-specific margin profiles when allocating R&D resources across medical, aerospace, and industrial verticals.
Market Dynamics
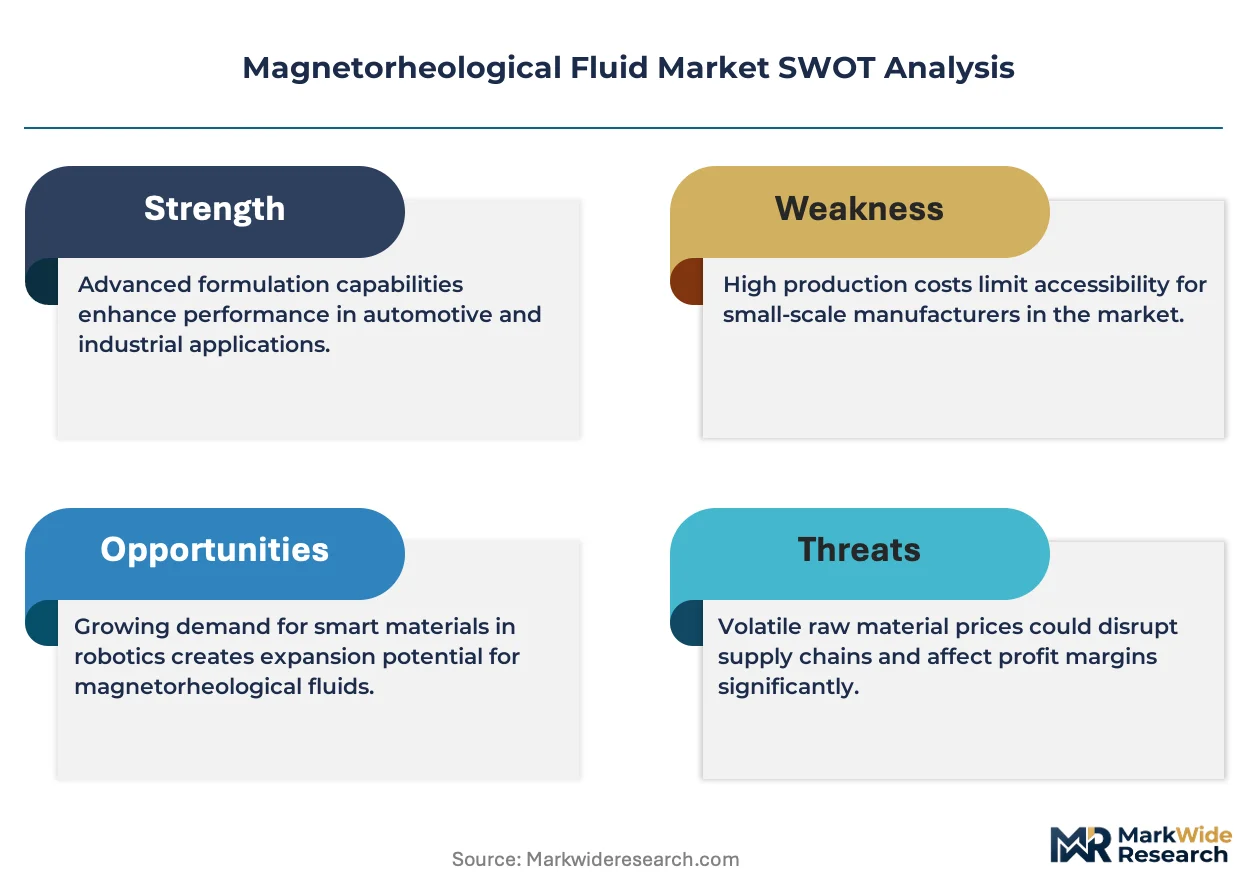
Buyer consolidation among aerospace primes and defense contractors is concentrating procurement leverage, while REACH compliance costs in Europe and FDA pathways for medical grades are fragmenting supplier economics across application tiers.
Growth Catalysts
- EU Green Deal material mandates:REACH-registered bio-based carrier oils are displacing hydrocarbon formulations in European automotive procurement, opening premium positioning for compliant suppliers.
- Aerospace adaptive damping:Boeing and Airbus platform specifications for semi-active landing gear are pulling high-temperature MR fluid volumes into qualification pipelines.
- Prosthetics robotics integration:Biocompatible fluid demand from powered exoskeleton developers in Germany and Japan is creating specialized formulation requirements beyond industrial grades.
Market Restraints
- Iron particle supply concentration:Carbonyl iron precursor production clusters in China and Germany expose formulators to freight cost volatility and geopolitical supply interruptions.
- Silicone oil substitution:Electrorheological fluids with faster response times are capturing select industrial damping applications below 150°C operating thresholds.
- EMA MDR compliance burden:Medical device classification timelines extend prosthetics commercialization by 24-36 months versus industrial grade launches.
Strategic Opportunities
- Wind turbine pitch control:Offshore installations in the North Sea and Baltic are specifying MR dampers for blade load management, creating marine-grade formulation demand.
- India PLI scheme alignment:Automotive component localization incentives under the Production Linked Incentive scheme are drawing joint venture proposals for domestic MR damper manufacturing.
- Digital twin convergence:Real-time viscosity modeling integrated with predictive maintenance platforms is enabling fluid-as-a-service contracting models in precision manufacturing.
Industry Challenges
- Magnetic particle dispersion expertise:Formulation chemists with micron-scale suspension stability experience command premium compensation, constraining R&D team scaling.
- Legacy damper retrofit compatibility:Semi-active MR systems require controller hardware upgrades that complicate aftermarket penetration in installed industrial bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetorheological Fluid Market |
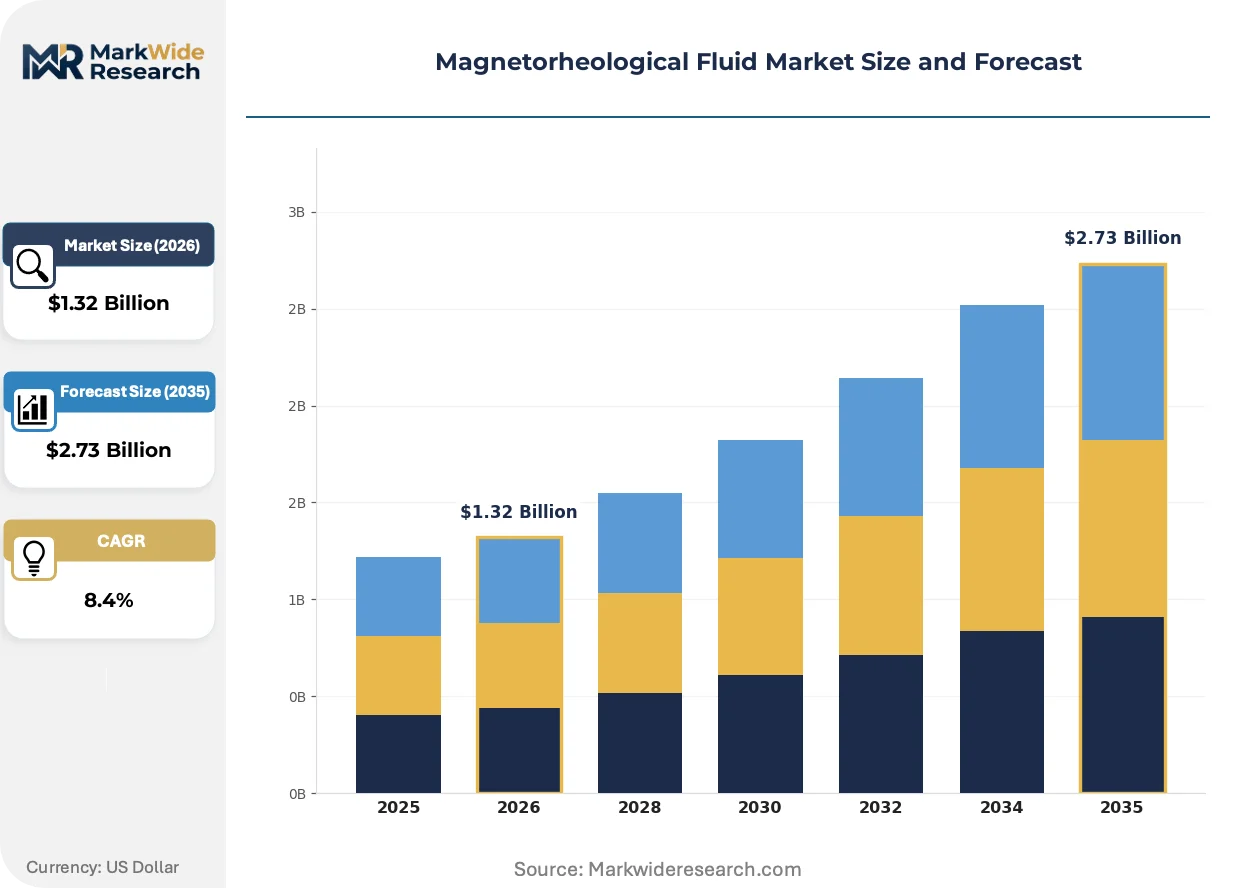
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.73 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Fluid, High-Temperature Fluid, Biocompatible Fluid, Self-Healing Fluid Technology: Electromagnetic, Hydraulic, Pneumatic, Mechanical Application: Vibration Control, Seismic Protection, Prosthetics, Industrial Automation End User: Consumer Electronics Manufacturers, Aerospace Firms, Defense Contractors, Scientific Research Institutions |
| Companies Covered | ARUS MR TECH, CK Materials Lab Co., Ltd., Parker Hannifin Corp, Akebono Brake Industry Co., Ltd., Ferrotec Corporation, QED Technologies, KURIMOTO, LTD., ABM Nano LLC., Liquids Research Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetorheological Fluid Market Strategic Shifts & Innovations
Synthetic ester carrier chemistry, computational fluid modeling, and servitized contracting models are compressing development cycles while expanding addressable application spaces beyond traditional damping.
Nano-engineered surface coatings on carbonyl iron particles are unifying sedimentation resistance with magnetic saturation performance. Aerospace formulators in Germany and the United States are qualifying these modified particles for 10,000-hour service intervals in turbine applications. The technology is unifying previously separate premium and standard fluid tiers into single-platform formulations.
REACH authorization requirements for persistent organic pollutants are tightening permissible additive chemistries in European-sourced fluids. Formulators are reformulating surfactant packages to maintain shear stability under restricted substance lists. Medical device manufacturers serving EMA-regulated markets face the steepest reformulation costs due to biocompatibility validation requirements.
Long-term fluid supply agreements with embedded technical service components are displacing spot procurement in automotive tier-one supply chains. German and Japanese OEMs are consolidating vendor lists to three approved suppliers per region, bundling formulation customization with predictive viscosity monitoring. This concentration is most visible in precision engineering clusters where damping performance directly impacts manufacturing yield rates.
Magnetorheological Fluid Market Segmentation
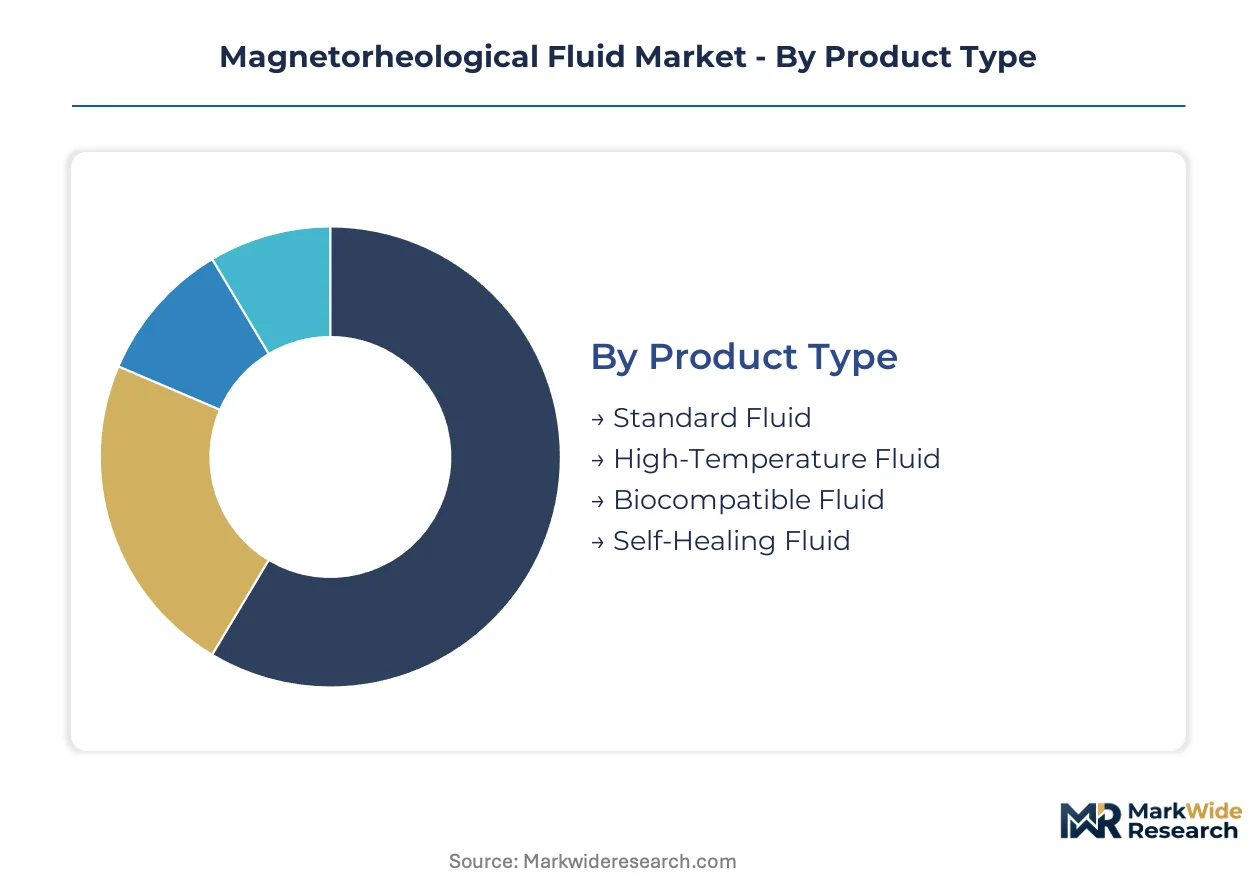
MR fluid procurement patterns diverge sharply across application tiers, with thermal tolerance and biocompatibility requirements fragmenting supplier economics. Formulators must align R&D allocation with distinct qualification pipelines rather than unified product platforms.
Product Type:
Cost tier drives buyer selection, with qualification expense and carrier chemistry determining contract value.
- Standard Fluid:Hydrocarbon or synthetic ester carriers suspend carbonyl iron particles at 20-40% volume fraction. Automotive damper manufacturers in Germany and Japan anchor procurement volumes through multi-year supply agreements with embedded technical service.
- High-Temperature Fluid:Oxidation-resistant synthetic ester bases maintain shear stability above 150°C for turbine and propulsion applications. Boeing and Airbus platform specifications are pulling volumes into aerospace qualification pipelines against 10,000-hour service intervals.
- Biocompatible Fluid:Medical-grade carriers meet FDA device classification and EMA MDR biocompatibility validation for prosthetics integration.
- Self-Healing Fluid:Microencapsulated additive packages autonomously repair shear-induced particle agglomeration in extended-cycle industrial deployments.
Volume sits with Standard Fluid; growth tilts toward High-Temperature Fluid.
Technology:
Application maturity separates proven electromagnetic architectures from emerging mechanical hybrids.
- Electromagnetic:Coil-generated fields up to 300 millitesla modulate viscosity within 5-10 milliseconds. Vibration control systems in precision manufacturing clusters across Germany and Japan deploy this architecture for real-time damping adjustment.
- Hydraulic:MR valve integration with conventional fluid power circuits enables force amplification in heavy machinery. Construction equipment OEMs specify these systems for operator cab isolation.
- Pneumatic:Compressed air interfaces with MR dampers in cleanroom automation where oil contamination risks exclude hydraulic alternatives.
- Mechanical:Passive magnetic bias configurations eliminate active power requirements for safety-critical aerospace deployments.
Electromagnetic captures the dominant revenue base; Mechanical gains share in aerospace redundancy specifications.
Application:
Performance requirements determine formulation chemistry, with medical and seismic segments demanding specialized validation.
- Vibration Control:Semi-active damping in automotive suspension and industrial machinery represents the established volume anchor. German automotive tier-one suppliers bundle formulation customization with predictive viscosity monitoring.
- Seismic Protection:Civil infrastructure base isolation systems deploy large-scale MR dampers for earthquake energy dissipation. Japanese building codes mandate performance certification through METI-recognized testing protocols.
- Prosthetics:Powered exoskeleton and adaptive limb systems require biocompatible formulations with EMA MDR compliance timelines extending commercialization 24-36 months versus industrial grades.
- Industrial Automation:Robotic end-effector force control and precision positioning systems utilize MR clutches and brakes for programmable compliance.
Vibration Control holds the installed base; Prosthetics climbs the fastest on robotics integration demand.
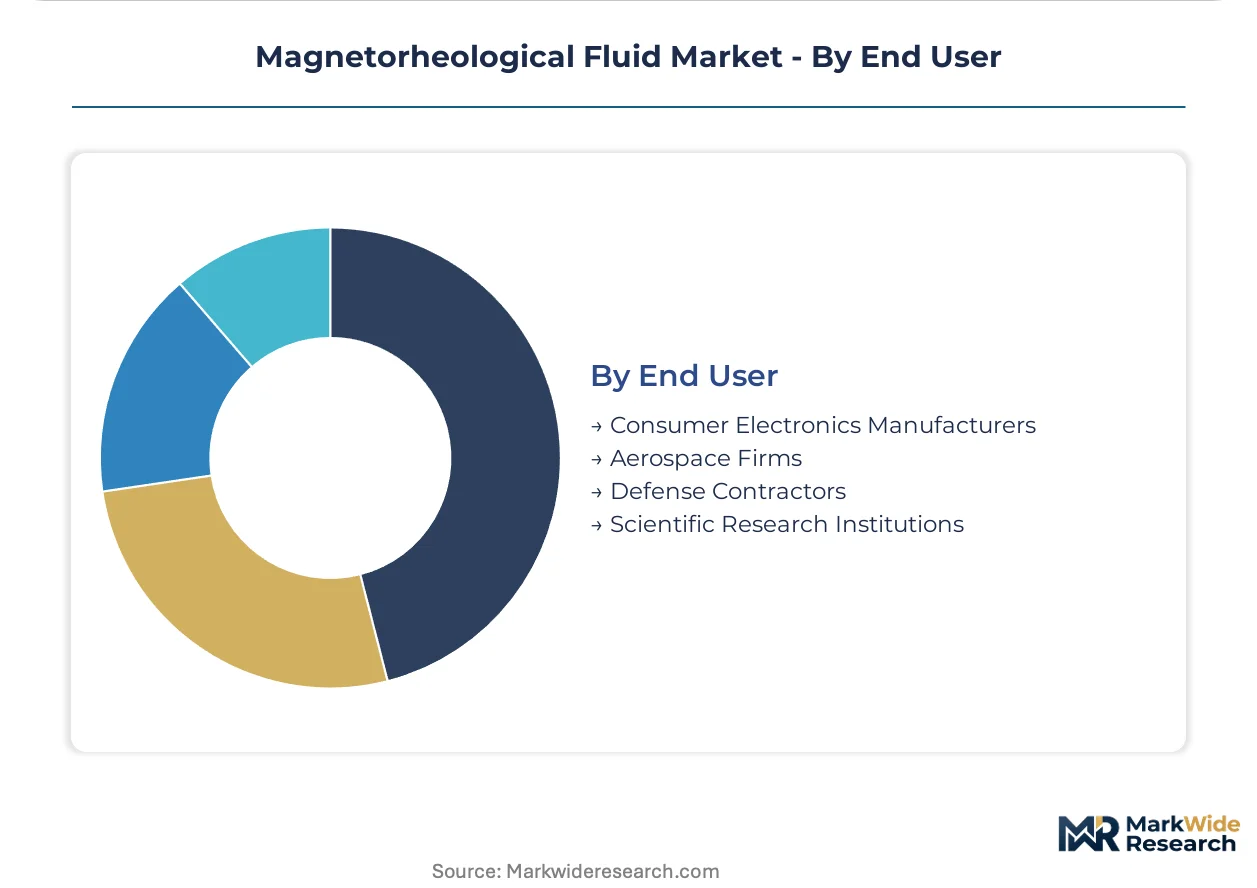
End User:
Procurement consolidation concentrates leverage among aerospace primes and defense contractors.
- Aerospace Firms:Boeing and Airbus platform specifications for semi-active landing gear and flight control surfaces drive high-temperature fluid qualification. Long-term supply agreements with Parker Hannifin and specialized formulators lock in approved supplier lists.
- Defense Contractors:Mission-critical damping for armored vehicles and naval platforms demands hardened electromagnetic architectures. Procurement consolidation among primes is narrowing vendor pools to three approved suppliers per region.
- Consumer Electronics Manufacturers:Haptic feedback systems and camera stabilization modules utilize miniature MR dampers in smartphone and wearable production.
- Scientific Research Institutions:National laboratories and university engineering centers purchase small-batch custom formulations for prototype validation and published performance studies.
Aerospace Firms concentrate procurement value; Defense Contractors are expanding fastest on platform modernization cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace procurement consolidation and automotive precision engineering clusters are concentrating MR fluid demand across three continents. Formulators must navigate distinct regulatory pathways and qualification timelines in each concentration zone.
Germany
Automotive tier-one suppliers and precision engineering clusters anchor European demand for standard and high-temperature formulations. REACH registration obligations constrain carrier oil chemistry flexibility for suppliers serving EMA-regulated medical device markets. Stuttgart and Munich engineering corridors host concentrated damper manufacturing operations with embedded technical service requirements.
United States
Boeing platform specifications for semi-active landing gear systems pull high-temperature fluid volumes through FAA-recognized qualification pipelines. EPA and OSHA standards govern carbonyl iron particle handling exposure limits during manufacturing operations. Parker Hannifin leverages channel control across aerospace distribution networks to sustain long-term supply agreements with defense contractors.
Japan
Powered exoskeleton developers in robotics corridors drive biocompatible fluid demand with METI-mandated performance certification for seismic protection systems. METI-recognized testing protocols extend commercialization timelines for prosthetics applications versus industrial grades. Osaka and Nagoya precision manufacturing clusters specify electromagnetic architectures for real-time damping adjustment in vibration control systems.
China
Carbonyl iron precursor production concentration exposes formulators to freight cost volatility and geopolitical supply interruption risks. MIIT industrial standards and dual carbon goals are reshaping domestic manufacturing compliance requirements for smart fluid formulations. Yangtze River Delta automotive component clusters are evaluating localized MR damper production under import substitution programs.
India
Automotive component localization incentives under the Production Linked Incentive scheme are drawing joint venture proposals for domestic MR damper manufacturing. BIS certification requirements and CDSCO medical device pathways create dual-track regulatory navigation for formulators. Maharashtra and Tamil Nadu automotive corridors represent the primary addressable manufacturing base for tier-one supplier consolidation.
Magnetorheological Fluid Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue biocompatible and marine-grade specialization. The vendor base stratifies across three capability tiers: integrated formulators with captive particle supply, regional damper specialists with formulation partnerships, and research-stage entrants targeting medical robotics validation. Strategic differentiation concentrates on REACH-compliant bio-based carriers, high-temperature synthetic ester chemistry, and embedded predictive viscosity monitoring. Competitive moves center on long-term supply agreements with technical service bundling and backward integration into magnetic particle precursor production.
Among Asia-Pacific-based specialists, CK Materials Lab Co., Ltd. and Akebono Brake Industry Co., Ltd. occupy positions within automotive tier-one supply chains, while Ferrotec Corporation exemplifies the integrated archetype through in-house production capabilities. These anchors represent distinct strategic postures: formulation customization with regional technical service, damper system integration with fluid specification influence, and upstream control over feedstock vulnerability.
| Leading Market Players |
|---|
| ARUS MR TECH |
| CK Materials Lab Co., Ltd. |
| Parker Hannifin Corp |
| Akebono Brake Industry Co., Ltd. |
| Ferrotec Corporation |
| QED Technologies |
| KURIMOTO, LTD. |
| ABM Nano LLC. |
| Liquids Research Ltd. |
| Others |
Cost & Logistics Intelligence
EU Green Deal material mandates gate qualified supply for REACH-registered bio-based carrier oils, restricting premium-tier pricing access to formulators with compliant chemistry portfolios and locking out hydrocarbon-dependent competitors from European automotive procurement.
Pricing Analysis
Volume concentrates in standard fluid tiers where automotive damper manufacturers negotiate multi-year supply agreements, while margin pools accrue to high-temperature and biocompatible grades with aerospace and medical qualification barriers. Price differentiation hinges on thermal tolerance certification and embedded technical service bundling. Cost compression in standard tiers intensifies as silicone oil substitutes capture sub-150°C industrial applications. Tier-one automotive suppliers exhibit lowest price sensitivity due to yield-critical damping performance, whereas industrial machinery buyers prioritize unit economics over formulation customization.
Supply Chain Analysis
Freight cost volatility from carbonyl iron precursor production clusters in China and Germany exposes formulators to margin erosion during geopolitical supply interruptions. The supply chain draws from carbonyl iron microparticles, synthetic ester carrier oils, and surfactant stabilizers. Single-source vulnerability concentrates in magnetic particle precursor production, with limited qualified alternative suppliers. Distribution runs through aerospace prime contractor approved vendor lists and automotive tier-one technical service partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer consolidation among aerospace primes and REACH compliance cost escalation are forcing sub-scale formulators toward exit or acquisition, rewarding players with captive particle supply and multi-regional certification portfolios.
For Market Incumbents: Extend long-term supply agreements with embedded predictive viscosity monitoring to lock out electrorheological fluid substitutes in precision manufacturing clusters. Deepen upstream control over carbonyl iron precursor production to insulate against China-Germany supply concentration risks. Prioritize EMA MDR pathway investment for biocompatible grades before regulatory timelines extend further. For New Entrants and Emerging Players: Damper system integrators represent the most accessible channel partners for bypassing established approved vendor lists in India's PLI-driven automotive corridors. Target marine-grade formulation white space in North Sea offshore wind installations where salt corrosion resistance requirements exceed incumbent capabilities. Pursue joint venture structures with regional automotive component manufacturers to satisfy localization mandates without full qualification burden. For Investors and Strategic Acquirers: Boeing and Airbus platform specification wins for semi-active landing gear are the leading indicator that high-temperature fluid qualification pipelines will consolidate around three approved suppliers per region. The five-to-ten year viability window favors formulators with backward integration into magnetic particle production and dual REACH-FDA certification capabilities. Monitor EMA MDR approval timelines for prosthetics applications as inflection signals for biocompatible tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbonyl Iron Production | Captive particle supply eliminates feedstock vulnerability to China-Germany freight volatility. |
| REACH-Compliant Bio-Based Carrier Development | EU Green Deal alignment unlocks premium positioning in European automotive procurement. |
| Long-Term Supply Agreement with Technical Service Bundling | Parker Hannifin's aerospace channel control demonstrates vendor list consolidation power. |
| Joint Venture for India PLI Localization | Maharashtra and Tamil Nadu automotive corridors require domestic manufacturing presence. |
| EMA MDR Biocompatibility Pathway Investment | Prosthetics robotics integration in Germany and Japan rewards first-mover regulatory clearance. |
Research Approach
Document review covered trade customs data, SEC filings from damper system manufacturers, and REACH registration databases, complemented by interviews with formulation chemists, aerospace procurement directors, and automotive tier-one supply chain managers. Secondary validation drew from FAA qualification pipeline disclosures, EMA MDR submission tracking, and carbonyl iron production capacity reports. Bottom-up fluid volume estimates triangulated against top-down aerospace and automotive platform forecasts.
Segment-level value outputs derived from product type, application, and end-user dimensions across the projection horizon, with thermal tolerance tiers and biocompatibility grades as industry-specific stratifiers. CAGRs emerged from fitted growth curves calibrated to platform specification timelines and regulatory approval velocity. Forecast inputs incorporated Boeing and Airbus landing gear deployment schedules, METI seismic protection mandates, and India PLI scheme localization incentives.
Caveats apply where EMA MDR timeline extensions, carbonyl iron supply interruptions, or electrorheological fluid response-time improvements could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Ferromanganese Market
Magnetic Materials
Magnet Wire Market
Magnetic Materials
Flux Field Directional Material Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Carbonyl Iron Powder Market
Magnetic Materials
Global Soft Magnetic Alloys Market
Magnetic Materials
Global Permanent Magnet Market
Magnetic Materials
Asia-Pacific Magnet Wire Market
Magnetic Materials
Gadolinium Market
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
Global Soft Magnetic Materials Market
Magnetic Materials
High Purity Carbonyl Iron Powder (CIP) Market
Magnetic Materials
Global Electrical Steel Sheet Market