
 Rapid Liquid Printing Market | 2026-2036
Rapid Liquid Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Liquid Printing Market Outlook
Direct-to-manufacturer equipment distribution is narrowing as OEMs seek tighter control over installation, calibration, and post-sale polymer supply contracts. Stratasys leverages its established service bureau network to sustain recurring material revenue streams alongside hardware placements. HP Inc. competes through integrated software-to-print workflows that anchor industrial customers in closed-loop production ecosystems. Steelcase differentiates by occupying the office furniture segment with rapid liquid printing systems configured for large-format soft material deposition.
Rapid liquid printing deposits viscous materials—thermosets, elastomers, and composite slurries—through precision nozzles into a supportive gel matrix, enabling geometric freedom beyond conventional layer-by-layer constraints with print volumes exceeding one cubic meter. The process serves industries requiring functional prototypes, custom orthopedic implants, and aerostructures where isotropic material properties prove critical. Inkjet printing technology leads current installations due to mature piezoelectric head reliability and established polymer ink formulations. Continuous flow systems represent the fastest-expanding category as throughput rates approach injection-molding economics for short-run production. Medical devices application commands premium margin pools where patient-specific geometries justify extended processing times and specialized silicone certifications.
EPA guidelines on volatile organic compound emissions from photocurable resins shape formulation chemistry and ventilation infrastructure requirements for US-based installation sites. FDA quality system regulation and ISO 13485 standards govern medical device applications, creating compliance barriers that filter non-specialized equipment vendors from healthcare procurement channels. The EU REACH framework restricts certain photoinitiator chemistries, redirecting European R&D toward bio-based gel support materials. Stakeholders must monitor evolving chemical safety thresholds and certification reciprocity agreements to anticipate which material platforms will retain cross-border market access.
Market Dynamics
Continuous flow deposition technology is compressing throughput gaps with injection molding, forcing equipment vendors to restructure from prototype-centric sales toward production-scale service contracts with polymer lock-in provisions.
Growth Catalysts
- Automotive Interior Customization:German and Japanese manufacturers are deploying rapid liquid printing for bespoke cabin components, eliminating tooling lead times that previously constrained low-volume personalization.
- FDA Quality System Regulation Pathways:Medical device prototyping hubs in Boston are leveraging patient-specific silicone certifications to command premium positioning in orthopedic implant workflows.
- REACH-Driven Bio-Based Reformulation:ECHA restrictions on photoinitiator chemistries are redirecting European R&D investment toward gel support materials derived from renewable feedstocks.
Market Restraints
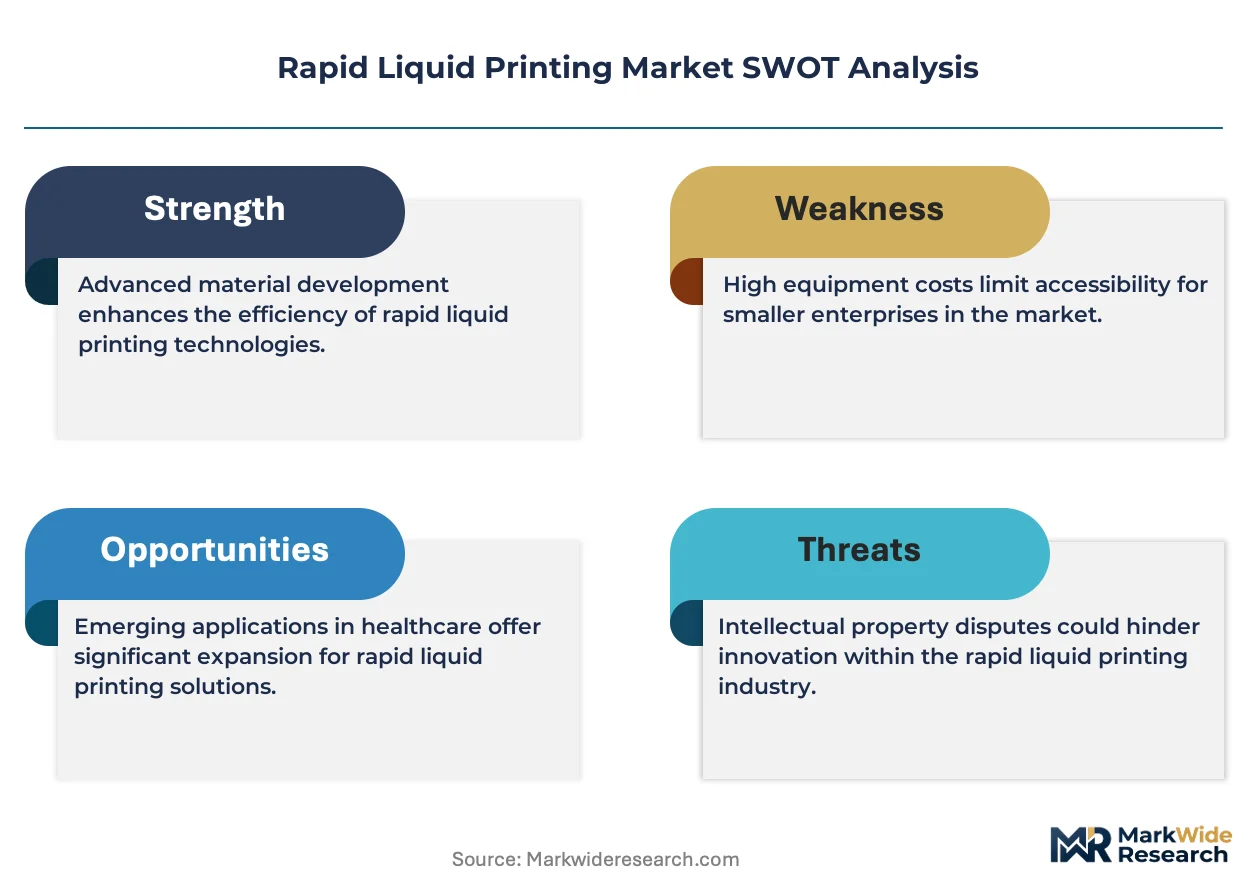
- Photocurable Resin Input Volatility:EPA volatile organic compound guidelines are elevating ventilation infrastructure costs for US installation sites, compressing margin structures for mid-scale service bureaus.
- Piezoelectric Head Supply Concentration:Mature inkjet printing architectures depend on concentrated Asian component sourcing, exposing lead time risks for Western equipment assemblers.
- Isotropic Property Verification Limitations:Layer-resolution constraints in legacy continuous flow systems create certification bottlenecks for aerostructure applications requiring full mechanical traceability.
Strategic Opportunities
- Soft Material Office Furniture:Large-format deposition systems configured for elastomeric seating components represent underexploited white space beyond automotive and medical verticals.
- Detroit Design Cluster Proximity:Geographic concentration of automotive OEM engineering centers in Michigan creates localized demand density for embedded rapid liquid printing service operations.
- ISO 13485 Reciprocity Expansion:Emerging mutual recognition agreements between FDA and European notified bodies are streamlining cross-border medical device qualification timelines.
Industry Challenges
- Gel Matrix Formulation Expertise Gap:Specialized polymer chemistry knowledge required for thermoset and composite slurry optimization remains scarce outside established materials science hubs.
- Closed-Loop Production Integration Complexity:HP Inc. and Stratasys ecosystem architectures demand significant legacy CAD-to-print workflow reconfiguration for industrial customers with entrenched software stacks.
- Post-Sale Polymer Contract Enforcement:OEMs tightening control over material supply chains face customer resistance to captive sourcing arrangements in price-sensitive prototype segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Liquid Printing Market |
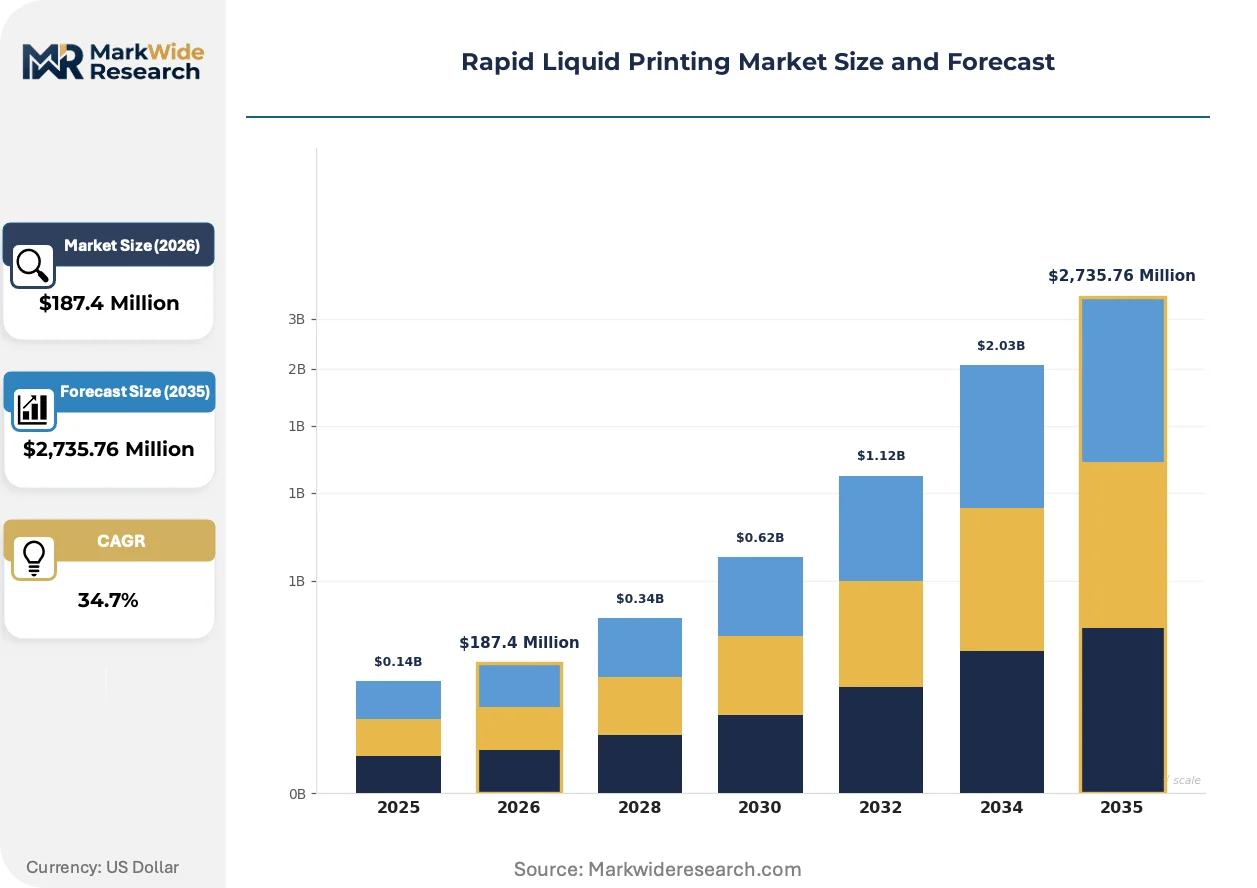
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,735.76 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Inkjet Printing, Continuous Flow, Digital Light Processing, Stereo Lithography Application: Prototyping, Custom Manufacturing, Medical Devices, Aerospace Components End User: Consumer Electronics, Healthcare, Automotive, Industrial Equipment Material Type: Polymers, Ceramics, Metals, Composite Materials |
| Companies Covered | Stratasys, 3D Systems, Materialise, EOS GmbH, HP Inc., ExOne, Steelcase, Dassault Systèmes, Autodesk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Liquid Printing Market Strategic Shifts
Digital manufacturing architectures are collapsing the boundary between design iteration and final part production, with software-to-print workflow integration emerging as the primary axis of vendor differentiation.
Continuous flow deposition systems are virtualizing the traditional tooling phase for short-run thermoset production. Tier-one automotive suppliers in Stuttgart and Nagoya are adopting these platforms for interior trim validation cycles measured in days rather than weeks. The technology is virtualizing capital allocation patterns by converting fixed mold investments into variable per-part polymer consumption.
REACH framework amendments are forcing reformulation of photoinitiator chemistries across European installation bases. ECHA restrictions on specific aromatic compounds are redirecting R&D expenditure toward bio-derived gel support matrices with equivalent mechanical properties. Medical device manufacturers in Ireland and Switzerland are accelerating ISO 13485 certification timelines to maintain market access ahead of anticipated substance ban enforcement.
Buyer concentration among Detroit automotive clusters and Boston medical device hubs is compressing vendor sales cycles toward direct OEM engagement. Equipment distributors are losing share to manufacturer-direct installation and calibration teams that anchor polymer supply contracts. This pattern is most pronounced in the United States, where NHTSA design validation requirements and FDA quality system regulations create procurement friction that favors established vendor relationships over speculative technology trials.
Rapid Liquid Printing Market Segmentation
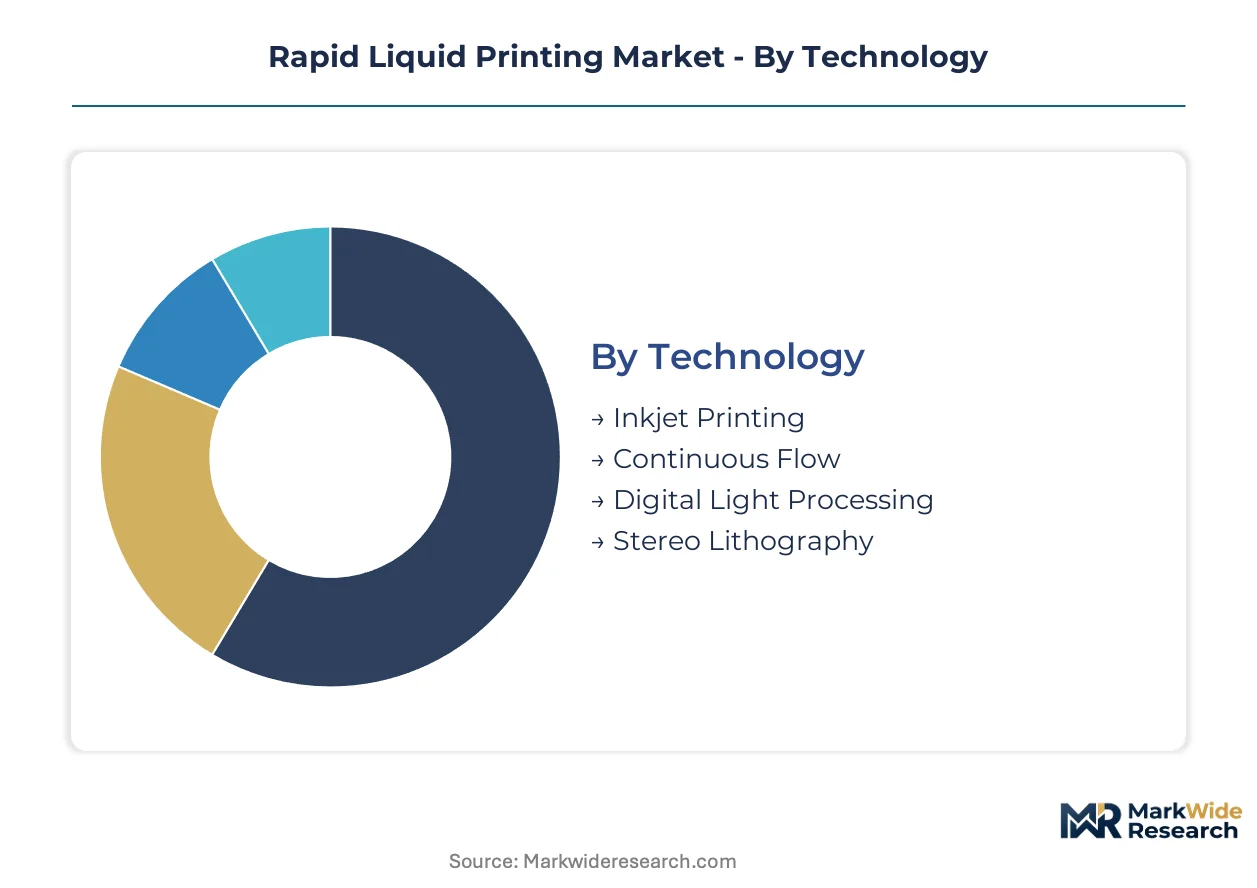
Segmentation in rapid liquid printing reveals divergent service intensity requirements across technology platforms and end-use verticals. Equipment vendors calibrate aftermarket revenue models—polymer supply contracts, calibration services, and gel matrix replenishment—based on which segments dominate customer portfolios.
Technology:
After-sales-service intensity varies sharply across technology categories, with continuous flow systems demanding embedded field engineering support while inkjet platforms rely on remote diagnostics and consumable replenishment.
- Inkjet Printing:Piezoelectric deposition heads deposit photocurable polymers through precision nozzles into gel matrices with mature reliability profiles. Demand concentrates in Boston medical device prototyping hubs where FDA quality system regulation compliance requires validated process documentation.
- Continuous Flow:Uninterrupted material streams enable deposition rates approaching injection molding throughput for thermoset and elastomer formulations. German automotive manufacturers in Stuttgart deploy these systems for interior trim validation cycles measured in days rather than weeks.
- Digital Light Processing:Projected light patterns cure entire layers simultaneously through vat photopolymerization.
- Stereo Lithography:Laser-directed point-by-point curing remains prevalent in legacy installations.
Inkjet printing holds the largest share; momentum sits with continuous flow.
Application:
Cost tier differentiation separates premium-certified medical workflows from price-sensitive prototype segments, with reimbursement pathways and tooling amortization schedules driving margin dispersion.
- Medical Devices:Patient-specific silicone implants and orthopedic geometries require ISO 13485-certified production environments with full mechanical traceability. Boston-area manufacturers command premium positioning through specialized biocompatible material certifications.
- Prototyping:Functional validation cycles for automotive and industrial equipment demand rapid geometric iteration without hard tooling investment. Detroit design clusters consume high volumes of gel matrix materials for iterative cabin component development.
- Custom Manufacturing:Low-volume production runs leverage geometric freedom for bespoke geometries.
- Aerospace Components:Isotropic property requirements create certification bottlenecks for aerostructure applications.
Medical devices command premium margins; custom manufacturing is climbing the fastest.
End User:
Customer type determines procurement channel structure, with automotive OEMs favoring direct manufacturer engagement while healthcare institutions route through specialized distributors.
- Automotive:Interior customization programs in Germany and Japan eliminate tooling lead times for bespoke cabin components. Tier-one suppliers in Nagoya adopt continuous flow platforms for soft material seating and trim validation.
- Healthcare:Hospital systems and device manufacturers require validated sterile production workflows with regulatory documentation packages. FDA quality system regulation pathways filter non-specialized vendors from procurement channels.
- Consumer Electronics:Rapid enclosure iteration cycles serve product development teams.
- Industrial Equipment:Functional prototypes for machinery components utilize large-format deposition volumes.
Automotive holds the largest share; healthcare shows steepest expansion trajectory.
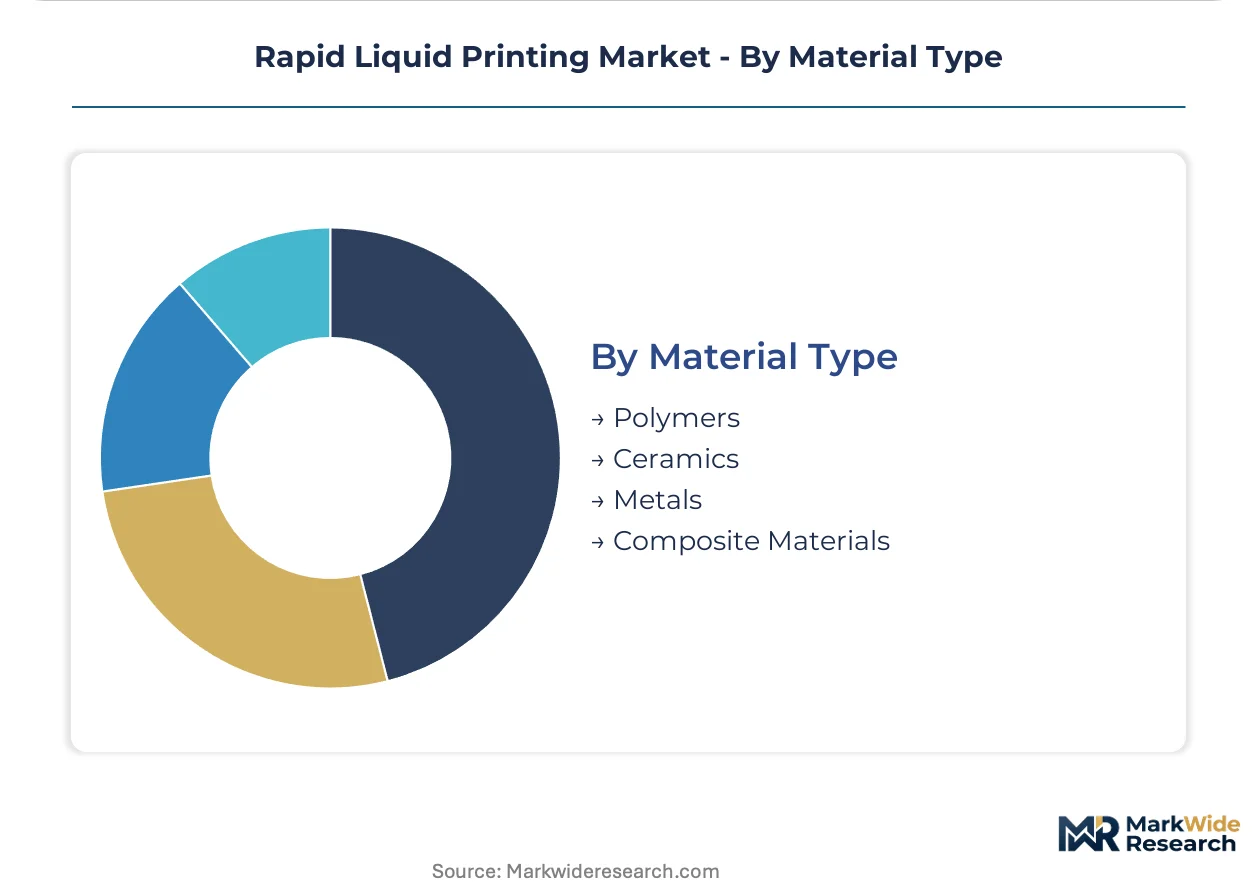
Material Type:
Supply concentration for specialized thermosets and composite slurries shapes regional vendor positioning, with gel matrix chemistry expertise scarce outside established materials science hubs.
- Polymers:Viscous thermoset and elastomer formulations dominate current installations, with EPA volatile organic compound guidelines elevating ventilation infrastructure costs for US-based photocurable resin processing.
- Composite Materials:Reinforced slurries combining polymers with ceramic or metallic fillers enable functional load-bearing geometries. ECHA REACH restrictions on photoinitiator chemistries redirect European R&D toward bio-based gel support matrices.
- Ceramics:High-temperature capable formulations serve specialized industrial applications.
- Metals:Metallic slurry deposition remains experimental with limited commercial deployment.
Polymers hold the largest share; composite materials are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput anchors Germany's position as a European hub for industrial equipment import and polymer supply chain consolidation. Japan's Shinkansen freight corridors enable just-in-time gel matrix delivery between Nagoya automotive clusters and Yokohama material processing facilities. Detroit's Ambassador Bridge crossing facilitates cross-border component validation cycles between Michigan design studios and Ontario manufacturing plants.
United States
Detroit's automotive engineering density drives concentrated demand for large-format soft material deposition systems. EPA volatile organic compound guidelines elevate ventilation infrastructure costs for photocurable resin processing sites. Boston's medical device prototyping corridor consumes specialized silicone certifications for patient-specific orthopedic implant workflows.
Germany
Stuttgart's tier-one supplier ecosystem deploys continuous flow platforms for interior trim validation cycles compressed from weeks to days. ECHA REACH restrictions on aromatic photoinitiator chemistries redirect R&D toward bio-based gel support matrices. Bavarian materials science hubs concentrate scarce polymer chemistry expertise for thermoset optimization.
Japan
Nagoya automotive manufacturers adopt rapid liquid printing for bespoke cabin component personalization programs. METI industrial technology roadmaps prioritize additive manufacturing throughput parity with injection molding economics. Tokyo-Yokohama corridor houses concentrated piezoelectric deposition head sourcing relationships.
United Kingdom
Midlands aerospace clusters face certification bottlenecks for isotropic property verification in legacy continuous flow systems. HSE workplace exposure limits for photocurable resins shape regional installation site requirements. London medical device consultancies leverage FDA quality system regulation pathway familiarity for cross-border qualification support.
Switzerland
Swiss orthopedic implant manufacturers command premium positioning through ISO 13485-certified production environments with full mechanical traceability. Swissmedic medical device regulations align with emerging FDA mutual recognition agreements. Basel's pharmaceutical-industrial corridor attracts specialized biocompatible material certification expertise.
Rapid Liquid Printing Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in piezoelectric deposition heads and gel matrix chemistry. The vendor base stratifies between closed-loop production ecosystem architects and open-architecture equipment distributors. Three archetypes dominate: industrial conglomerates with software-to-print workflow integration, specialized furniture manufacturers occupying large-format soft material niches, and service bureau operators sustaining recurring polymer revenue streams. Competitive moves center on direct-to-manufacturer distribution channel capture and post-sale material supply contract enforcement.
Among diversified technology conglomerates, HP Inc. and Stratasys occupy positions anchoring closed-loop production ecosystems through integrated software-to-print workflows and established service bureau networks respectively. Steelcase exemplifies the vertical specialization archetype, occupying large-format soft material deposition configurations for office furniture applications outside automotive and medical mainstream demand.
| Leading Market Players |
|---|
| Stratasys |
| 3D Systems |
| Materialise |
| EOS GmbH |
| HP Inc. |
| ExOne |
| Steelcase |
| Dassault Systèmes |
| Autodesk |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Asian piezoelectric deposition head suppliers compresses both pricing tier spreads and supply chain resilience, forcing Western equipment assemblers to absorb tariff exposure or pass through cost premiums to medical device and automotive buyers.
Pricing Analysis
Volume-discount tiering structures stratify across three levels: premium ISO 13485-certified medical workflows, standard automotive prototyping contracts, and economy service bureau rentals. Price differentiation hinges on certification grade and after-sales polymer bundling. Pricing pressure stems from EPA ventilation infrastructure mandates elevating fixed costs for US photocurable resin processors. Service bureaus exhibit highest price sensitivity due to thin margin structures, while orthopedic implant manufacturers tolerate premiums for patient-specific silicone certifications.
Supply Chain Analysis
Export-control regimes on precision deposition technology limit component flows from Japan and Taiwan to Western equipment assemblers. Piezoelectric head fabrication concentrates in the Tokyo-Yokohama corridor, with gel matrix chemistry expertise anchored in Bavarian materials science hubs. Raw material dependencies span photoinitiator chemistries, bio-based support matrices, and specialized thermoset formulations. Single-source vulnerability in piezoelectric component sourcing creates lead time risks. Distribution runs through direct manufacturer engagement with automotive OEMs and medical device manufacturers, bypassing traditional equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable barriers: FDA quality system regulation pathways and ISO 13485 certifications filter non-specialized vendors from healthcare procurement channels.
For Market Incumbents: Entrench polymer supply contract enforcement as the primary defensive mechanism against emerging open-architecture competitors. Deepen backward integration into gel matrix chemistry to capture margin pools currently flowing to Bavarian materials specialists. Secure embedded field engineering teams within Detroit and Boston demand clusters to anchor calibration service revenue and block challenger access. For New Entrants and Emerging Players: Establish a beachhead in large-format soft material office furniture applications, the segment Steelcase occupies with limited direct competition from automotive-focused incumbents. Target European markets where ECHA REACH restrictions on photoinitiator chemistries create reformulation demand that established vendors must address. Pursue partnership-based go-to-market models with regional materials science hubs lacking in-house equipment platforms. For Investors and Strategic Acquirers: The market sits at a technology-validation phase that favors specialized component suppliers over integrated platform vendors. Long-term viability centers on gel matrix chemistry expertise and regulatory certification infrastructure rather than hardware scale. Monitor FDA-European notified body mutual recognition agreement progress as the signal for cross-border medical device qualification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Gel Matrix Chemistry Acquisition | Captures scarce polymer formulation expertise concentrated in Bavarian and Boston hubs. |
| ISO 13485 Certification Investment | Unlocks premium-margin orthopedic implant workflows requiring full mechanical traceability. |
| Direct OEM Service Deployment | Anchors polymer supply contracts within Detroit automotive and Boston medical clusters. |
| Continuous Flow Platform Launch | Displaces legacy inkjet installations as throughput approaches injection molding economics. |
| Bio-Based Material Partnership | Aligns with ECHA REACH restrictions redirecting European R&D toward renewable feedstocks. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC equipment vendor filings, EPA regulatory guidance documents, FDA quality system regulation interpretations, and ECHA REACH substance restriction updates. Interviews with biomedical engineers at Boston medical device prototyping hubs, Tier 1 automotive procurement leads in Stuttgart and Nagoya, gel matrix chemistry specialists at Bavarian materials science institutes, and service bureau operators in Detroit validated demand assumptions. Bottom-up equipment shipment estimates triangulated against top-down polymer consumption data from customs records.
Forecast inputs span technology platform adoption curves, regulatory certification timeline assumptions, and end-use vertical penetration rates across the projection horizon. Segmentation dimensions modeled include deposition technology type, application tier by certification requirement, end-user procurement channel structure, and material chemistry platform. CAGRs derive from installed base expansion trajectories and consumable revenue per unit economics. Industry-specific inputs incorporate EPA ventilation infrastructure cost pass-through assumptions and ECHA substance ban enforcement schedules.
Stress conditions across piezoelectric component supply disruption, REACH regulatory acceleration, and automotive OEM personalization program cancellation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory reciprocity timeline progression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Printing Plate Market
Printing Inks
Printing Inks Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Global Chemical Indicator Inks Market
Printing Inks
UV Fluorescing Ink Market
Printing Inks
United States Printing Inks Market
Printing Inks
Specialty Ink Market
Printing Inks
Returnable Glass Bottle Ink Market
Printing Inks
Inkjet Colorants Market
Printing Inks
Brazil Commercial Printing Market
Printing Inks
Roll-To-Roll Type UV Imprinting Machines Market
Printing Inks
Squid Ink Market
Printing Inks
Global Decorative Print Market
Printing Inks
Thermochromic Ink Printing Market
Printing Inks
Flexo-Ink Market
Printing Inks
Offset Ink Market