
 North America Precision Fermentation Market | 2026-2036
North America Precision Fermentation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Precision Fermentation Market Insights
Capital-intensity divergence between contract manufacturers and in-house bioreactor operators is reorganizing competitive dynamics across the North American precision fermentation landscape. Perfect Day sustains vertical integration from strain engineering to dairy protein finishing, while Ginkgo Bioworks leverages its foundry model to serve multiple product categories without owning downstream assets. Amyris anchors its position through captive supply of fermentation-derived ingredients for cosmetics and flavors, competing against specialized players with narrower scope.
Precision fermentation deploys genetically modified microorganisms in controlled bioreactor environments to produce specific proteins, enzymes, and functional metabolites with exact molecular fidelity to conventional animal or plant sources. The process typically operates at pH ranges of 5.0 to 7.5 with dissolved oxygen monitoring and real-time metabolite sensing to optimize titers and reduce batch-to-batch variation. Microbial proteins command the largest revenue share among product types due to direct substitution potential in meat and dairy analogs, while enzymes generate premium margins from pharmaceutical and food processing contracts. Continuous fermentation technology attracts capital for its higher volumetric productivity, though batch systems dominate current installed capacity across North American facilities.
The FDA oversees GRAS self-determination and food additive petitions for precision fermentation outputs, while the USDA regulates labeling and inspection protocols for cell-cultured and bioengineered meat alternatives, creating a dual-track compliance burden for cross-category producers. Health Canada and PMRA coordinate novel food assessments for Canadian market entry, with divergent timelines from U.S. procedures complicating unified North American launch strategies. Stakeholders must monitor how FDA guidance on bioengineered food disclosure intersects with state-level labeling initiatives to anticipate channel access constraints.
Market Dynamics
The FDA's evolving GRAS determination framework is compressing approval timelines for novel fermentation-derived proteins while simultaneously fragmenting compliance pathways across state-level bioengineered food disclosure laws.
Growth Catalysts
- Midwest manufacturing cluster expansion:Illinois and Minnesota bioreactor facilities are scaling capacity for microbial protein production, drawing contract manufacturing demand from plant-based meat formulators seeking domestic supply security.
- USDA inspection protocol harmonization:Streamlined labeling requirements for cell-cultured meat alternatives are reducing market entry friction for cross-category precision fermentation producers operating under dual FDA-USDA jurisdiction.
- Continuous fermentation technology maturation:Real-time metabolite sensing and automated pH control systems are improving volumetric productivity in California biotech corridor facilities, lowering unit economics for enzyme production contracts.
Market Restraints
- Input cost volatility:Pharmaceutical-grade glucose and nitrogen source prices fluctuate with agricultural commodity markets, squeezing margin structures for high-titer microbial protein operations.
- Bioreactor fabrication bottleneck:Stainless steel vessel lead times from specialized fabricators concentrate supply risk, delaying capacity expansion timelines for in-house operators across the Great Lakes region.
- GRAS self-determination uncertainty:FDA notification review inconsistencies create regulatory friction, forcing conservative market entry strategies for novel enzyme categories without established safety precedents.
Strategic Opportunities
- Canadian novel food pathway optimization:Health Canada coordinated assessments with PMRA offer streamlined market entry for fermentation-derived ingredients, enabling unified North American launch strategies from Toronto-area R&D facilities.
- Pet food protein substitution:Underpenetrated animal nutrition applications present white space for microbial protein suppliers, bypassing stringent human food regulatory requirements while building production scale.
- IRA clean manufacturing incentives:Bioprocessing facility tax credits under US climate legislation are accelerating capital deployment toward low-carbon fermentation infrastructure in Texas and Colorado.
Industry Challenges
- Strain engineering talent scarcity:Computational biology and metabolic pathway optimization expertise concentrates in Boston and San Francisco, forcing Midwest manufacturers into costly relocation packages or remote team fragmentation.
- Downstream processing capex intensity:Chromatography and membrane filtration equipment for protein purification demands substantial capital commitment, favoring contract manufacturers with amortized infrastructure over greenfield entrants.
- Dual-track compliance complexity:Simultaneous FDA food additive petitions and USDA inspection scheduling create timeline coordination burdens, stretching regulatory affairs staffing for emerging product categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Precision Fermentation Market |
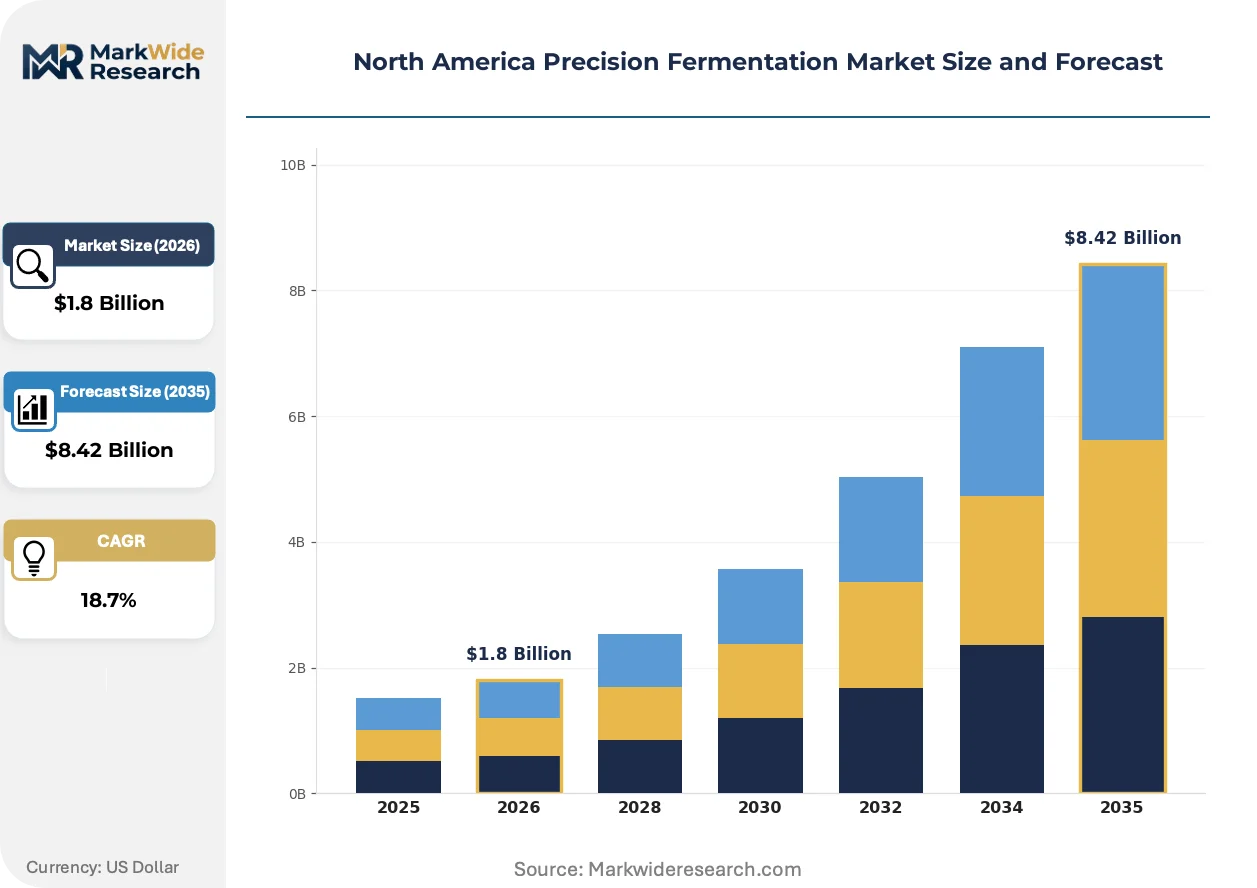
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Proteins, Enzymes, Additives, Probiotics End User: Food Manufacturers, Beverage Companies, Pharmaceutical Firms, Nutraceutical Providers Application: Animal Feed, Plant-Based Products, Dietary Supplements, Functional Foods Technology: Batch Fermentation, Continuous Fermentation, Fed-Batch Fermentation, Solid-State Fermentation |
| Companies Covered | The Every Company, MycoTechnology, Perfect Day, Ginkgo Bioworks, Change Foods, Impossible Foods, Motif FoodWorks, Amyris, Geltor, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Precision Fermentation Market Trends and Innovations
Bioprocess control architectures are converging with pharmaceutical-grade quality systems, elevating precision fermentation from commodity protein production toward high-value functional ingredient manufacturing with exact molecular specifications.
Continuous fermentation technology is decomposing the traditional batch production paradigm in North American facilities. Dairy protein manufacturers in California are adopting perfusion systems with real-time biomass monitoring, achieving steady-state operation that compresses capital requirements per kilogram of output. This operational shift is decomposing the historical advantage of incumbent batch operators with sunk capacity investments.
The FDA's 2023 guidance on bioengineered food disclosure is reshaping labeling obligations for precision fermentation outputs. Food manufacturers must now navigate intersecting federal disclosure requirements and state-level initiative compliance, particularly in Vermont and Colorado where supplemental labeling mandates apply. Enzyme producers supplying multiple end-use categories face the most complex compliance mapping, diverting technical resources toward regulatory documentation.
Ingredient procurement from contract fermentation operators is consolidating among multi-category food manufacturers seeking supply security. Large meat alternative brands are bypassing spot market purchasing, instead negotiating multi-year offtake agreements with dedicated microbial protein facilities. This pattern is most visible in the Midwest, where Cargill and ADM adjacent bioreactor clusters offer integrated feedstock and processing logistics.
North America Precision Fermentation Market Segmentation
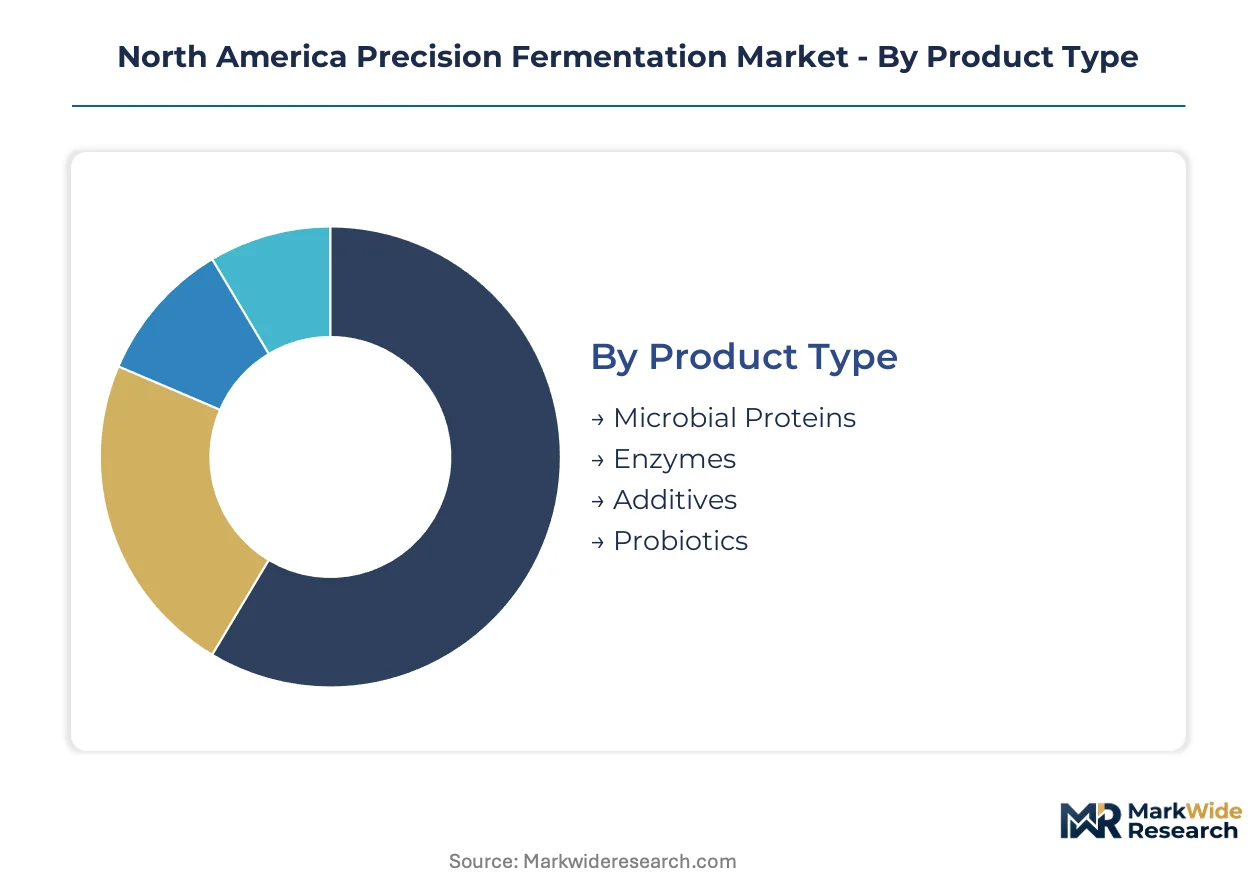
Channel access patterns vary sharply across precision fermentation outputs, with microbial proteins flowing through CPG procurement desks while enzymes reach pharmaceutical formulators via specialized distribution. Understanding these pathway structures clarifies where margin capture concentrates and which segments justify dedicated bioreactor investments.
Product Type:
Microbial proteins and enzymes dominate facility output allocations, with contract manufacturers structuring dedicated production lines around protein titer specifications versus enzyme activity assays.
- Microbial Proteins:Genetically optimized single-cell proteins achieve amino acid profiles matching conventional dairy and egg whites. California biotech corridor facilities supply plant-based meat formulators in Los Angeles and San Francisco with mycoprotein and yeast-derived isolates, though FDA GRAS notification backlogs constrain novel strain introductions.
- Enzymes:Catalytic proteins manufactured at pharmaceutical-grade titers serve food processing and therapeutic applications. Midwest fermentation clusters near Chicago produce proteases and lipases for dairy alternative texture modification, with premium pricing sustained by batch consistency requirements from multinational food processors.
- Additives:Flavor precursors and texturants from controlled microbial cultures.
- Probiotics:Live microbial strains requiring cryopreservation and specialized handling protocols.
By volume, microbial proteins lead. By growth pace, enzymes are climbing the fastest.
End User:
Customer scale determines fermentation run economics, with multinational food manufacturers commanding dedicated bioreactor capacity while nutraceutical providers purchase through toll manufacturing arrangements.
- Food Manufacturers:Plant-based meat and dairy alternative producers constitute the dominant demand source, with Cargill-adjacent Midwest facilities processing bulk mycoprotein for burger and sausage applications. These customers negotiate multi-year offtake agreements that amortize capital costs across predictable volume commitments.
- Pharmaceutical Firms:Therapeutic enzyme and recombinant protein producers impose the most stringent quality standards, requiring GMP-compliant facilities with validated chromatography suites. Boston-area biotech companies source fermentation capacity from specialized CDMOs rather than commodity protein operators.
- Beverage Companies:Precision fermentation-derived flavor modifiers and clarifying enzymes.
- Nutraceutical Providers:Dietary supplement brands procuring probiotic cultures and bioactive peptides.
Food manufacturers absorb the highest absolute volumes. Pharmaceutical firms generate the steepest margin premiums per kilogram.
Application:
Regulatory pathway complexity fragments application-level demand, with human food categories facing dual FDA-USDA oversight while animal feed operates under streamlined EPA and state agriculture department protocols.
- Plant-Based Products:Meat and dairy analogs represent the most visible commercial deployment, with Impossible Foods and Beyond Meat adjacent suppliers scaling whey and casein replicas in California facilities. Consumer packaged goods brands in Texas and Colorado are expanding refrigerated distribution for precision fermentation-derived cheese alternatives.
- Animal Feed:Pet food and livestock nutrition applications bypass stringent human food safety requirements, enabling faster market entry for novel microbial protein suppliers. Canadian facilities near Toronto serve North American pet food manufacturers with single-cell protein meal, building production scale ahead of human food regulatory approvals.
- Dietary Supplements:Fermentation-derived vitamins, amino acids, and bioactive compounds.
- Functional Foods:Probiotic-enhanced and protein-fortified consumer products.
Plant-based products command the highest unit values. Animal feed is expanding most quickly as a production scaling strategy.
Technology:
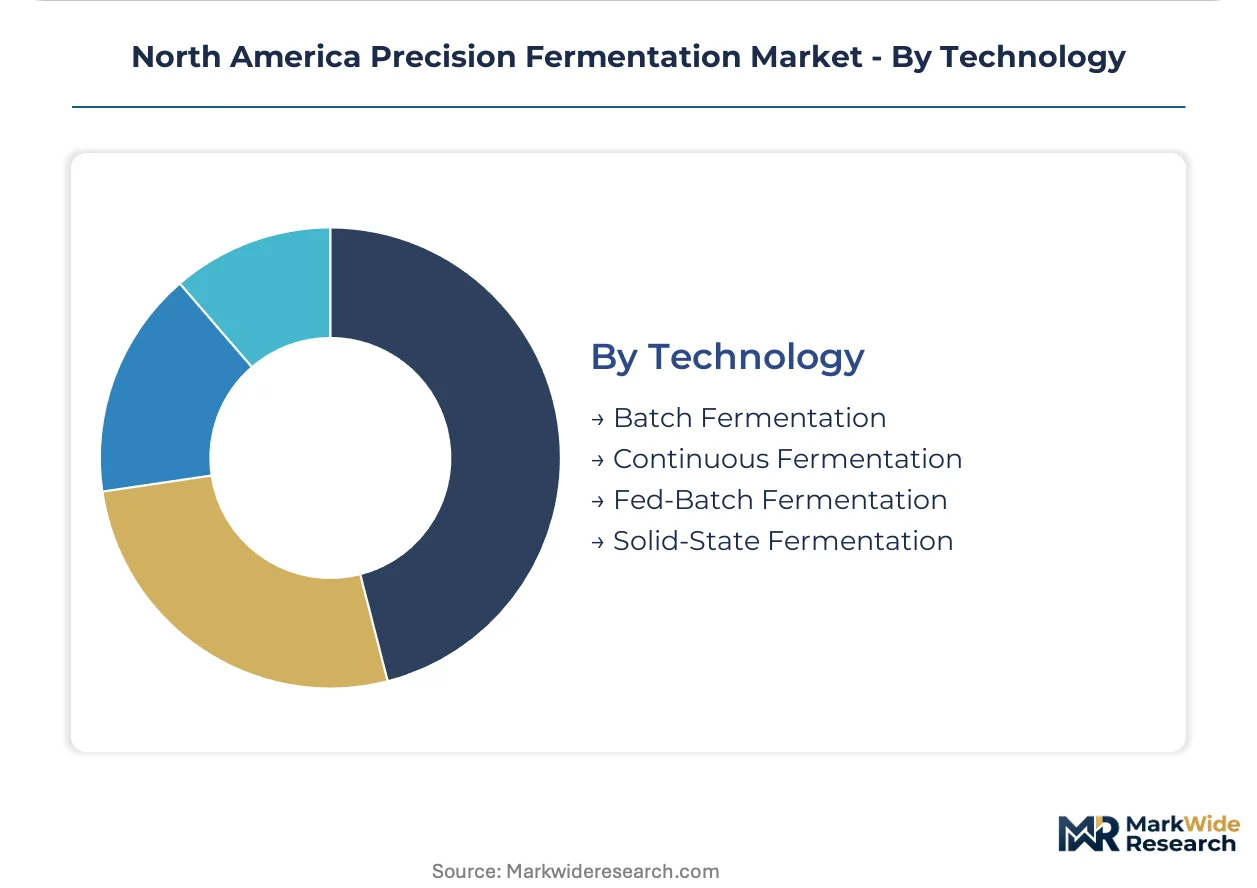
Capital deployment patterns separate incumbent batch operators from continuous fermentation adopters, with technology choice locking in operating cost structures for decade-long facility lifecycles.
- Continuous Fermentation:Perfusion systems with real-time biomass monitoring achieve steady-state operation that compresses capital requirements per kilogram of dairy protein output. California facilities are retrofitting existing stainless steel infrastructure with automated pH control and metabolite sensing to capture these productivity gains without greenfield construction.
- Batch Fermentation:Traditional stirred-tank systems dominate installed North American capacity, with Midwest facilities operating validated platforms for enzyme production under long-term pharmaceutical contracts. Sunk capital investments and regulatory filing histories protect incumbent operators despite higher per-unit operating costs.
- Fed-Batch Fermentation:Hybrid approaches with controlled nutrient addition.
- Solid-State Fermentation:Low-moisture cultivation systems for specialized enzyme categories.
Batch fermentation retains volume leadership. Continuous systems are gaining share fastest among new capacity investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California's biotech corridor while cost-sensitive capacity expansion accelerates across the Midwest, creating a structural asymmetry that reshapes procurement geography for precision fermentation outputs.
United States
Food manufacturers in Illinois and Minnesota are commissioning dedicated bioreactor capacity for microbial protein production. The FDA's evolving GRAS determination framework compresses approval timelines for novel fermentation-derived proteins. Chicago-area facilities now supply plant-based meat formulators with validated enzyme production under long-term pharmaceutical contracts.
Canada
Health Canada coordinates novel food assessments with PMRA to streamline market entry for fermentation-derived ingredients. Toronto-area R&D facilities enable unified North American launch strategies from Canadian soil. Single-cell protein meal from Ontario facilities serves pet food manufacturers building production scale ahead of human food approvals.
California
Dairy protein manufacturers in the San Francisco Bay Area deploy perfusion systems with real-time biomass monitoring to achieve steady-state operation. Continuous fermentation technology adoption here compresses capital requirements per kilogram of output. Berkeley and South San Francisco host strain engineering operations that feed downstream bioreactor clusters in the Central Valley.
Midwest Manufacturing Belt
Illinois and Minnesota bioreactor facilities scale capacity for microbial protein production, drawing contract manufacturing demand from plant-based meat formulators. The IRA's clean manufacturing tax credits accelerate capital deployment toward low-carbon fermentation infrastructure. Cargill-adjacent bioreactor clusters offer integrated feedstock and processing logistics for multi-year offtake agreements.
Texas and Colorado
Climate legislation bioprocessing facility tax credits are accelerating capital deployment toward low-carbon fermentation infrastructure in these states. Denver and Austin host emerging precision fermentation operations targeting enzyme production for food processing applications. These facilities benefit from lower energy costs and proximity to agricultural feedstock supply chains.
North America Precision Fermentation Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American precision fermentation landscape. The market structure consolidates around three strategic tiers: vertically integrated operators controlling strain-to-finished-protein pipelines, foundry-model platforms serving multiple product categories without downstream assets, and specialized contract manufacturers amortizing purification infrastructure across client portfolios. Dominant competitive moves include multi-year offtake agreements that lock in capacity commitments and backward integration into captive strain engineering capabilities.
Within the vertically integrated tier, Perfect Day exemplifies control over the full production pipeline from microbial strain development to dairy protein finishing. Ginkgo Bioworks occupies a distinct position as a foundry-model platform enabling multiple product categories through shared infrastructure. Amyris anchors the specialty ingredient segment through in-house production of fermentation-derived outputs for adjacent sectors.
| Leading Market Players |
|---|
| The Every Company |
| MycoTechnology |
| Perfect Day |
| Ginkgo Bioworks |
| Change Foods |
| Impossible Foods |
| Motif FoodWorks |
| Amyris |
| Geltor |
| Others |
Pricing and Supply Chain Analysis
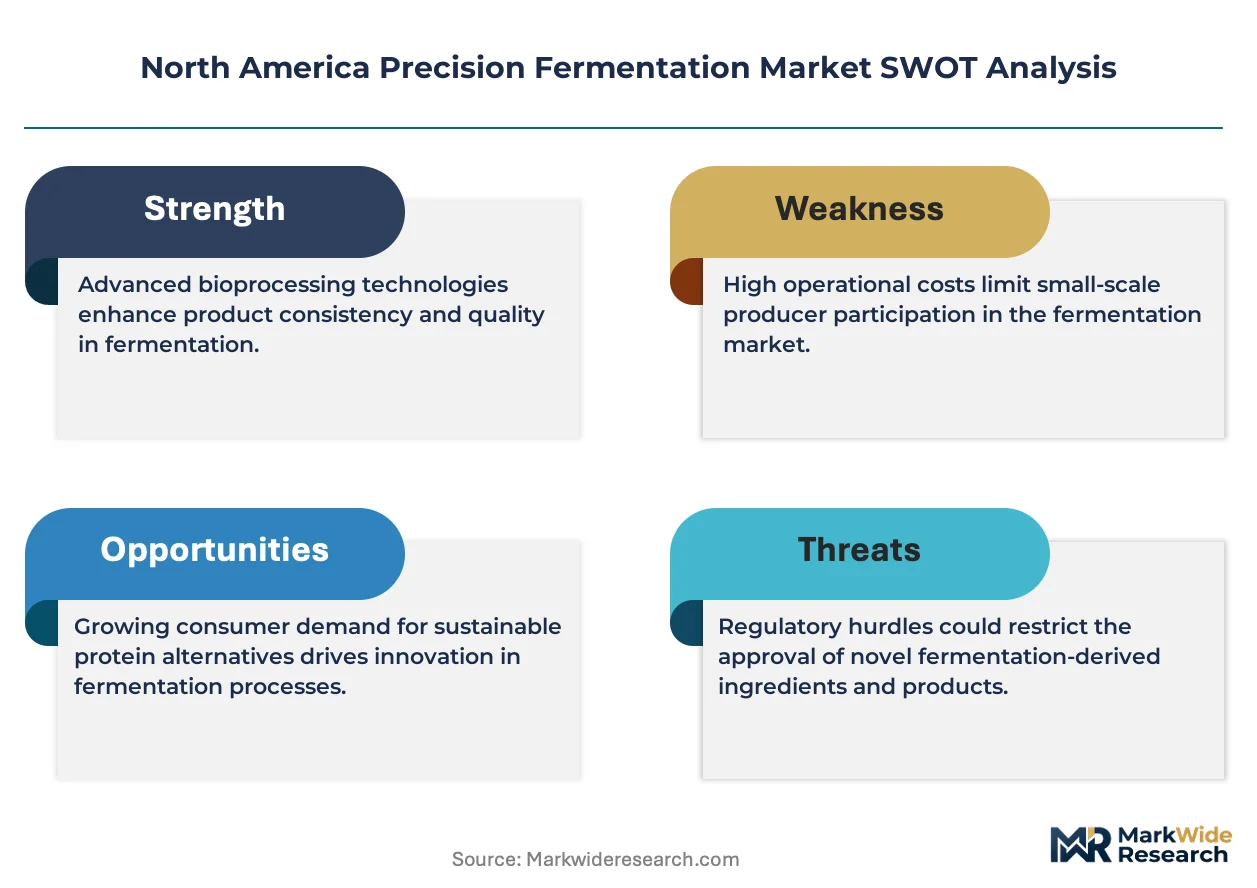
FDA GRAS notification requirements simultaneously gate supplier qualification and stratify price tiers across the North American precision fermentation landscape. Pharmaceutical-grade certification commands substantial premiums over food-grade outputs, while dual-track FDA-USDA compliance burdens compress margins for cross-category producers.
Pricing Analysis
The customization-premium spread separates contract manufacturers offering configured-to-order strain engineering from standard microbial protein suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification status, with pharmaceutical enzyme contracts generating the steepest margins. Cost compression in commodity protein tiers is intensifying because Midwest capacity expansion outpaces differentiated product development. Food manufacturers absorb the highest absolute volumes with greatest price sensitivity; pharmaceutical formulators exhibit lowest sensitivity due to batch consistency requirements.
Supply Chain Analysis
Bioreactor vessel inventory lead times from specialized stainless steel fabricators now stretch eighteen to twenty-four months, constraining capacity expansion timelines. Supply concentrates in the United States, Canada, and select European fabrication hubs for critical fermentation infrastructure. Pharmaceutical-grade glucose and nitrogen sources draw from agricultural commodity markets, creating input cost volatility. Single-source vulnerability pervades specialized chromatography equipment for downstream protein purification. Distribution runs through contract manufacturing organizations with amortized purification infrastructure serving multi-client portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multinational food manufacturers negotiating multi-year offtake agreements, fragmenting pricing leverage for uncommitted suppliers. This consolidation among plant-based meat and dairy alternative producers restructures procurement economics across the value chain.
For Market Incumbents: Secure captive strain engineering capabilities to defend against foundry-model platform disintermediation. Perfect Day's vertical integration from microbial engineering to dairy protein finishing exemplifies this defensive posture. Add dedicated bioreactor capacity in the Midwest manufacturing belt to anchor multi-year supply agreements with Cargill-adjacent procurement desks. FDA GRAS determination backlogs threaten first-mover advantage for novel enzyme categories.
For New Entrants and Emerging Players: Health Canada's coordinated novel food assessment pathway offers streamlined market entry relative to FDA notification procedures. Pet food protein substitution presents underpenetrated white space with reduced regulatory friction compared to human food categories. Animal feed applications enable production scale building ahead of human food approvals. Target toll manufacturing arrangements with existing bioreactor operators rather than greenfield capacity investments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous fermentation technology adopters as perfusion systems compress capital requirements per kilogram of output. Long-term viability favors operators with backward integration into strain engineering rather than pure-play contract manufacturers. Acquisition targets should demonstrate validated GMP facilities with pharmaceutical contract histories. Monitor FDA guidance publication timing as inflection indicator for novel protein category expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| GRAS Self-Determination Investment | FDA notification capabilities accelerate market entry timelines for novel protein categories. |
| Continuous Fermentation Retrofit | Perfusion system adoption reduces capital intensity for California dairy protein manufacturers. |
| Midwest Capacity Expansion | Illinois and Minnesota facilities capture Cargill-adjacent procurement demand from meat alternative formulators. |
| Canadian Regulatory Pathway Utilization | Health Canada coordinated assessments enable unified North American launch strategies from Toronto R&D. |
| Pet Food Segment Entry | Animal nutrition applications bypass stringent human food requirements while building production scale. |
Research Methodology
Cross-validation between primary interviews with fermentation facility operators and secondary regulatory filing analysis anchors the qualitative findings. Strain engineering directors, contract manufacturing executives, regulatory affairs leads at novel food companies, and procurement managers at plant-based meat formulators provided operational perspectives. FDA GRAS notifications, USDA inspection protocols, Health Canada novel food assessments, and SEC filings from publicly traded biotech platforms supplied secondary validation. Bottom-up capacity assessments triangulate against top-down demand modeling from end-use consumption patterns.
Sensitivity analysis around input cost volatility and regulatory timeline variations frames the projection horizon. The analytical framework segments by product type, end user scale, application category, and technology platform across the modeling period. CAGRs derive from fitted growth curves calibrated to capacity expansion announcements and offtake agreement disclosures. Modeled inputs include pharmaceutical-grade feedstock pricing indices and bioreactor fabrication lead time assumptions.
Decision-makers should treat outputs as directional under sustained FDA GRAS notification throughput and stable agricultural commodity pricing; material deviation would warrant model refresh. Specific risk factors include state-level bioengineered food disclosure law fragmentation and strain engineering talent scarcity concentration in Boston and San Francisco. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
North America Edible Insects Market
Alternative Food Sources
Insect-Based Pet Food Market
Alternative Food Sources
Black Soldier Fly (BSF) Market
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
Food Cultures Market
Alternative Food Sources
Soy Leghemoglobin Market
Alternative Food Sources
Plant-Based Squalene Market
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
Mushroom Protein Market
Alternative Food Sources
Corn-Based Protein Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
North America Fat Replacers Market
Alternative Food Sources
Carragean Alternatives Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
Global Algae Market
Alternative Food Sources
Europe Upcycled Food Products Market