
 Global Algae Market | 2026-2036
Global Algae Market Size, Share, and Industry Trends Forecast 2026-2036
Global Algae Market Analysis
Pharmaceutical-grade certification is rotating toward the center of supplier strategy. DSM-Firmenich leverages its integrated astaxanthin production network to sustain premium positioning across nutraceutical channels. Cargill Incorporated anchors North American supply through controlled pond cultivation systems. Corbion competes on fermentation-derived algae lipids for infant formula applications.
Algae constitute photosynthetic organisms ranging from unicellular microalgae to multicellular macroalgae, typically cultivated in open ponds, photobioreactors, or raceway systems with controlled light, temperature, and nutrient parameters; their commercial utility spans protein, lipid, pigment, and bioactive compound extraction for human and animal consumption. Spirulina dominates volume throughput due to established extraction infrastructure and lower cultivation complexity, while chlorella commands margin premiums through broken-cell processing for bioavailability. Biofuels application remains structurally constrained by cost parity with petroleum diesel, though nutraceuticals concentrate value capture through high-purity EPA and DHA concentrates.
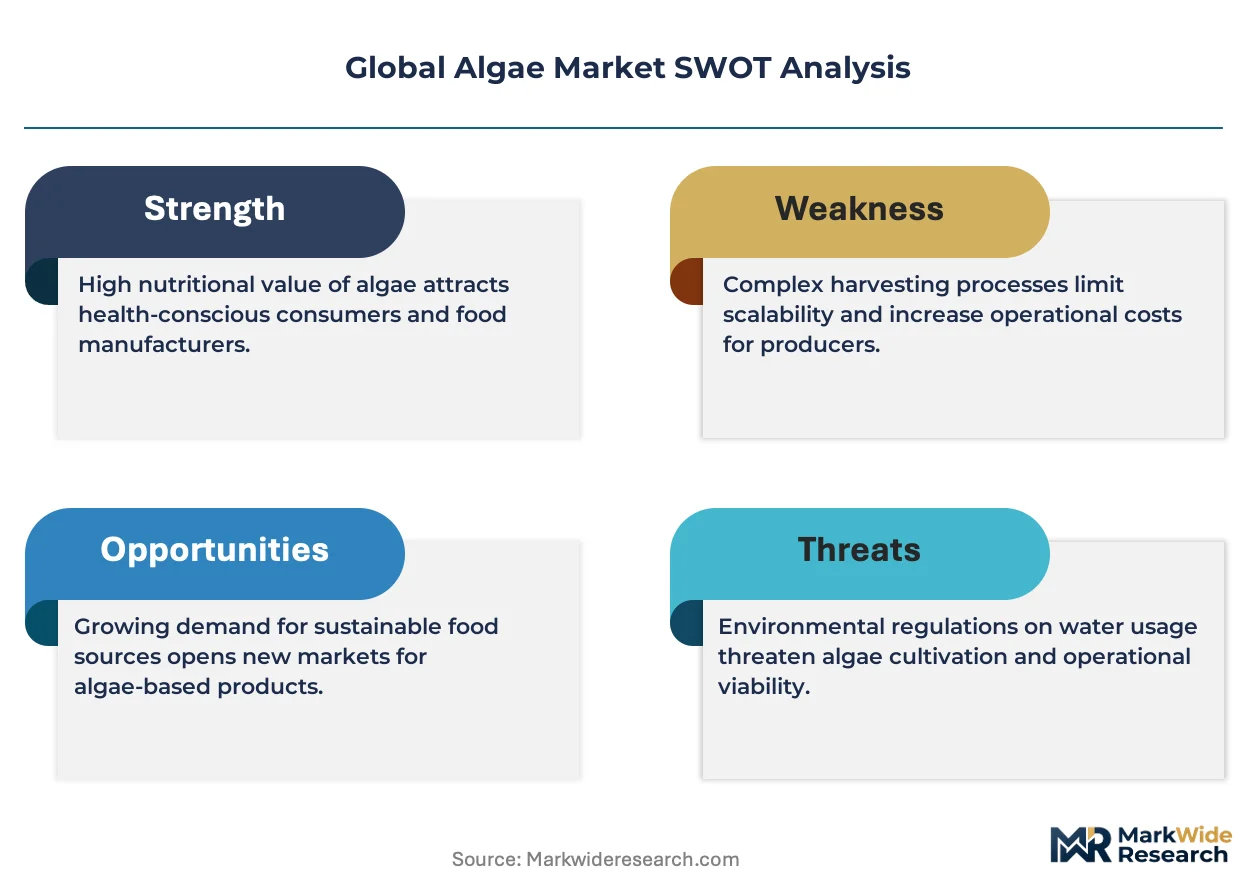
FDA GRAS determinations and EFSA Novel Food authorizations shape ingredient market access timelines for new algae strains entering food and supplement channels. EPA effluent guidelines and EU F-Gas Regulation compliance costs influence open-pond versus closed-system investment decisions across production geographies. Stakeholders must monitor regulatory divergence between jurisdictions as classification of algae-derived ingredients as food, feed, or novel food determines commercialization pathways and capital allocation priorities.
Market Dynamics
Pharmaceutical-grade certification requirements are compressing supplier margins while concentrating procurement authority among nutraceutical formulators with validated extraction protocols. This structural force is accelerating capital deployment toward closed-system photobioreactors and integrated quality assurance infrastructure.
Growth Catalysts
- EU Novel Food traceability mandates:EFSA authorization pathways for algae-derived ingredients are tightening documentation standards, advantaging suppliers with established supply chain provenance systems.
- Infant formula lipid fortification:Fermentation-derived DHA concentrates are securing preferred supplier status with pediatric nutrition manufacturers seeking consistent fatty acid profiles.
- Controlled pond cultivation scaling:The United States is expanding open-pond spirulina capacity to meet pharmaceutical extraction feedstock demand.
Market Restraints
- Petroleum diesel cost parity:Algal biofuel production remains structurally uncompetitive against fossil-derived transport fuels without subsidy support.
- CO2 feedstock price volatility:Carbon source costs for photobioreactor operations fluctuate with industrial emissions credit markets.
- Broken-cell processing bottlenecks:Chlorella bioavailability enhancement requires specialized milling equipment concentrated among limited equipment vendors.
Strategic Opportunities
- Japan's functional food regulatory pathway:PMDA consultation procedures for algae-derived FOSHU claims offer faster market entry than EU Novel Food routes.
- Precision fermentation convergence:Synthetic biology platforms are integrating with heterotrophic algae cultivation to produce customized lipid profiles.
- Direct-to-practitioner supplement channels:Clinician-dispensed omega-3 formulations are bypassing retail markup structures for high-purity astaxanthin complexes.
Industry Challenges
- Phycocyanin extraction technician scarcity:Specialized downstream processing expertise for pigment recovery remains concentrated among legacy spirulina producers.
- GRAS determination timeline variability:FDA notification review periods for new algae strains create revenue recognition uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Algae Market |
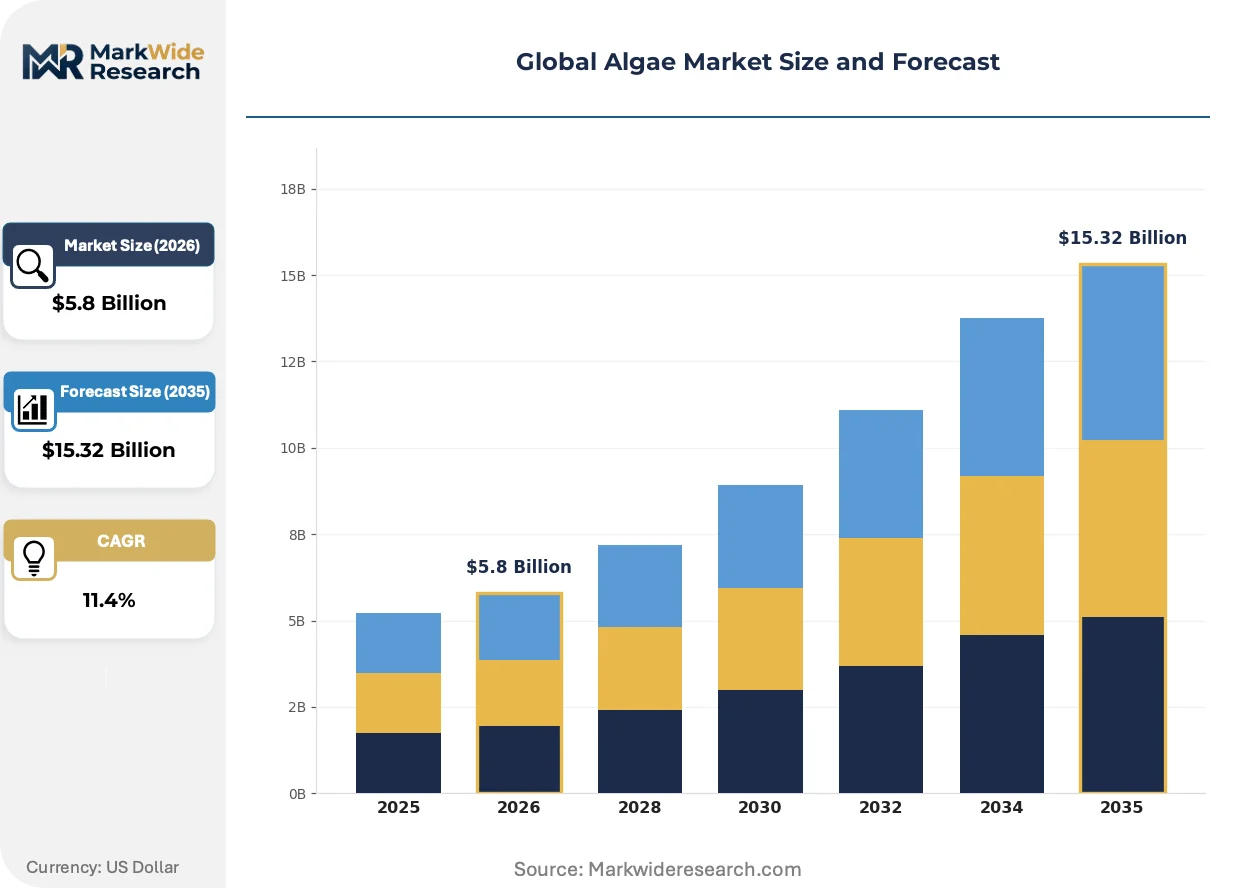
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $15.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirulina, Chlorella, Dunaliela, Others Application: Food & Beverage, Cosmetics, Nutraceuticals, Biofuels End User: Food Industry, Pharmaceutical Sector, Personal Care, Agriculture Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | DSM-Firmenich, BASF SE, Cargill Incorporated, Cyanotech Corporation, Corbion, Archer-Daniels-Midland Company, Euglena Co., Ltd., Cellana Inc., Algatechnologies Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Algae Market Emerging Trajectories
Bioprocess intensification and regulatory data harmonization are compressing development cycles for novel algae ingredients. These forces are reconfiguring competitive advantage toward integrated biomanufacturing platforms.
Photobioreactor-based heterotrophic cultivation is supplanting open-pond systems for high-value EPA and DHA production. Nutraceutical formulators in Germany and Switzerland are accelerating adoption to secure pharmaceutical-grade certification. This technology is supplanting traditional autotrophic methods by eliminating climate dependency and enabling year-round production consistency.
EFSA's tightened Novel Food authorization requirements are extending safety evaluation timelines for new microalgae strains. European ingredient suppliers are consolidating pre-submission toxicology data packages to accelerate regulatory clearance. Infant formula applications face the most stringent scrutiny, driving backward integration into captive toxicology testing infrastructure.
Long-term offtake contracting is displacing spot market purchasing for pharmaceutical-grade spirulina. North American supplement manufacturers are locking in multi-year supply agreements with validated producers. This pattern is most visible in the United States, where FDA inspection history and GRAS status have become non-negotiable procurement criteria.
Global Algae Market Segmentation
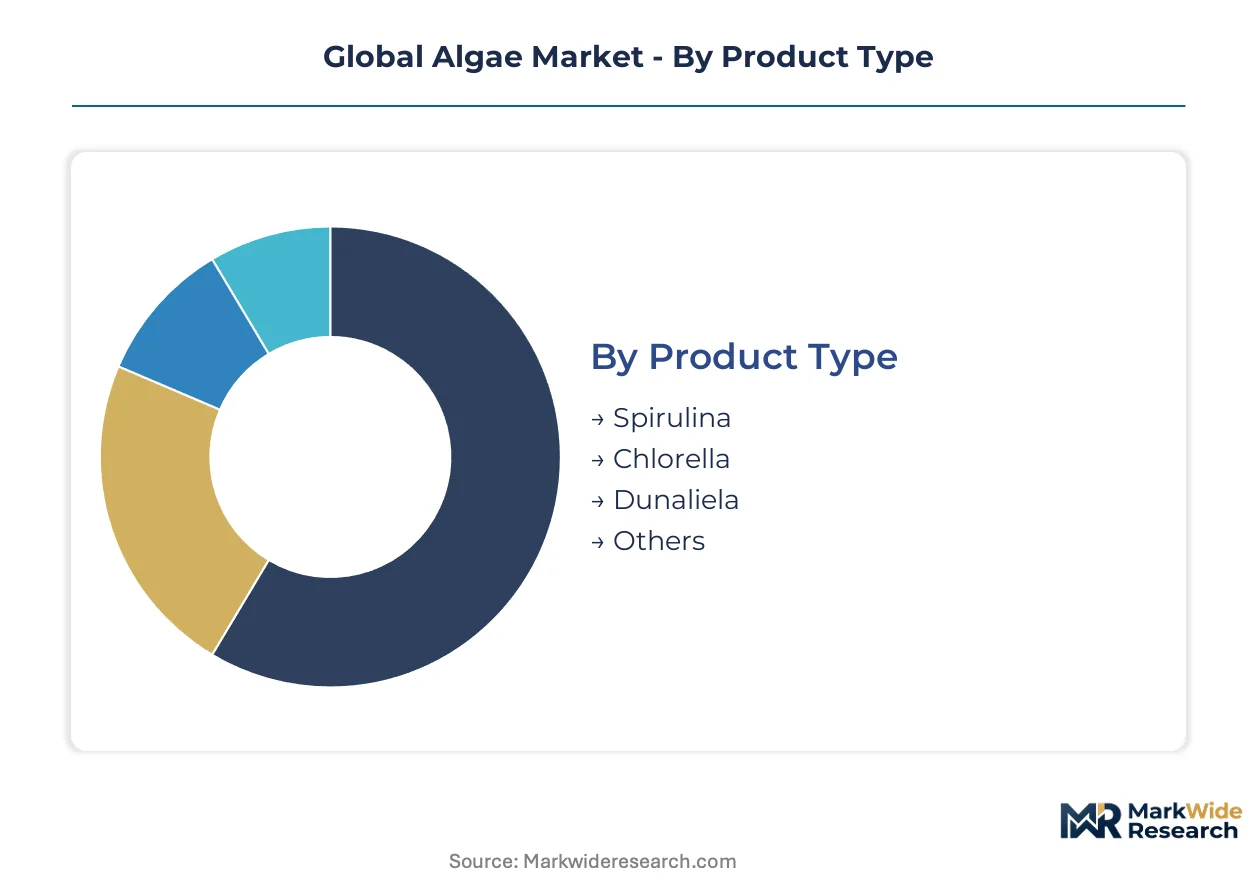
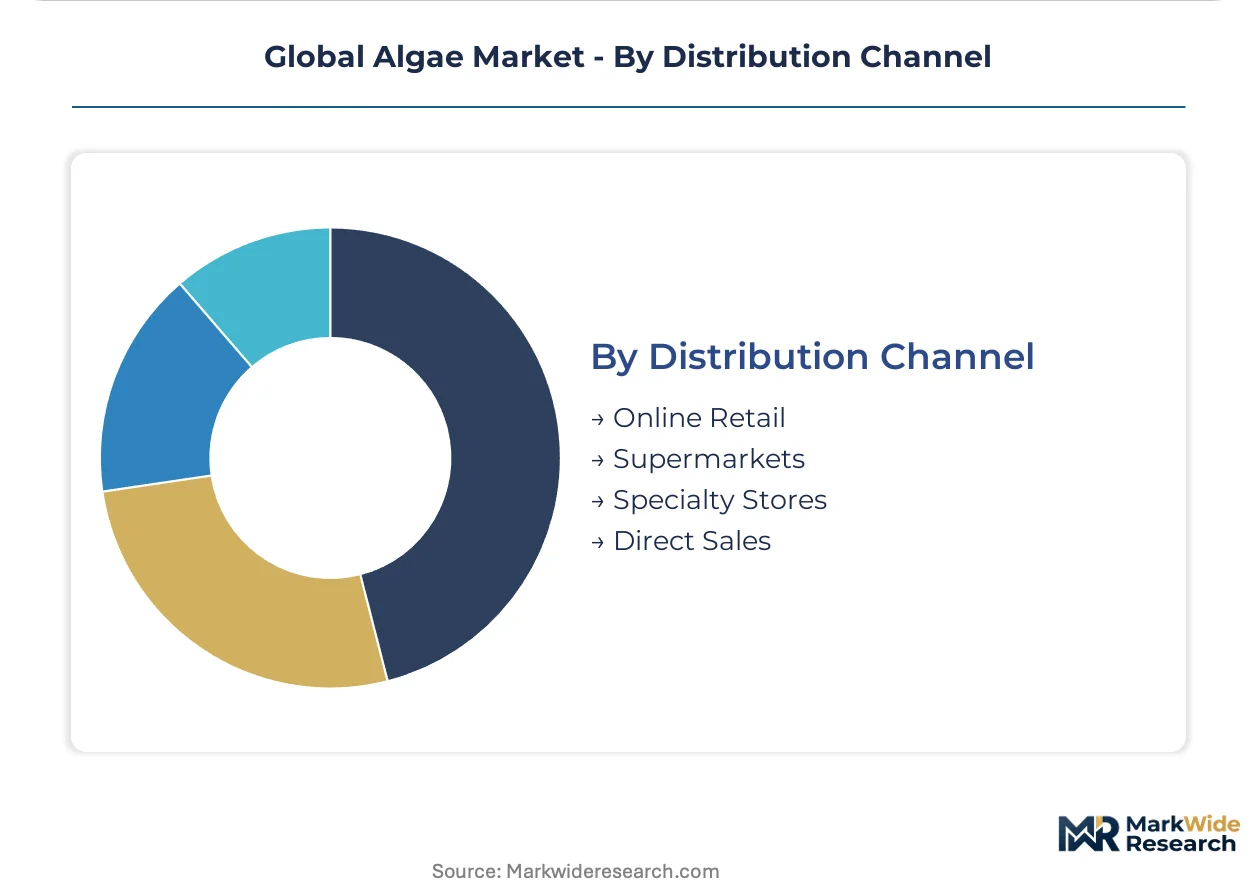
Algae market segmentation reveals distinct channel economics and margin structures across product categories. Each dimension carries specific regulatory and technical requirements that determine supplier positioning and capital allocation priorities.
Product Type:
Channel flow varies sharply by species—spirulina and chlorella dominate mass-market nutraceutical channels, while dunaliella concentrates in premium pigment applications.
- Spirulina:Cyanobacterium with 60-70% protein content and established GRAS status. United States pharmaceutical extraction facilities are scaling open-pond capacity to secure feedstock for clinician-dispensed supplement formulations. FDA inspection history has become a non-negotiable procurement filter.
- Chlorella:Single-celled green algae requiring broken-cell processing for bioavailability. Germany and Switzerland nutraceutical formulators pay margin premiums for pharmaceutical-grade certification, driving backward integration into specialized milling equipment.
- Dunaliella:Halotolerant microalgae prized for beta-carotene and glycerol accumulation. Israel and Australia cultivation sites supply cosmetic pigment houses.
- Others:Haematococcus pluvialis for astaxanthin, Schizochytrium for DHA fermentation, and emerging strains awaiting EFSA Novel Food authorization.
By volume, spirulina leads. By growth pace, chlorella is climbing the fastest.
Application:
Cost tier stratification separates commodity biofuel feedstock from premium nutraceutical concentrates, with regulatory burden increasing at each price level.
- Food & Beverage:Algae protein isolates and natural colorants for plant-based formulations. EU F-Gas Regulation compliance costs favor suppliers with closed-system cultivation.
- Cosmetics:Astaxanthin and phycocyanin for anti-aging and UV-protection claims. Swiss and French formulators demand ISO 16128 natural origin certification.
- Nutraceuticals:EPA and DHA concentrates for cardiovascular and cognitive health positioning. Japan's PMDA FOSHU pathway offers faster entry than EU Novel Food routes.
- Biofuels:Lipid extraction for renewable diesel remains structurally constrained by petroleum cost parity without subsidy support.
By revenue concentration, nutraceuticals dominate. By margin expansion, cosmetics is gaining share fastest.
End User:
Customer type determines specification intensity—pharmaceutical buyers impose validated extraction protocols that commodity food processors bypass.
- Food Industry:Plant-based meat and dairy alternatives seeking complete protein profiles. North American manufacturers prioritize long-term offtake contracts with validated producers.
- Pharmaceutical Sector:Pediatric nutrition and clinician-dispensed omega-3 formulations. Infant formula applications face the most stringent EFSA toxicology scrutiny.
- Personal Care:Clean beauty brands sourcing natural pigments with supply chain provenance documentation.
- Agriculture:Animal feed and biofertilizer applications with lower purity thresholds.
By procurement scale, food industry leads. By specification intensity, pharmaceutical sector sets the standard.
Distribution Channel:
Maturity gradient separates established retail infrastructure from emerging direct channels, with regulatory data requirements shaping channel access.
- Online Retail:Direct-to-consumer spirulina powders and chlorella tablets. Amazon and specialized supplement platforms require COA documentation for listing approval.
- Supermarkets:Mass-market algae protein products in natural foods sections. Whole Foods and Sprouts demand third-party organic certification.
- Specialty Stores:High-astaxanthin complexes and practitioner-exclusive formulations. Clinician-dispensed channels bypass retail markup structures.
- Direct Sales:Fermentation-derived DHA concentrates for infant formula manufacturers through negotiated supply agreements.
By transaction volume, supermarkets lead. By margin retention, direct sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spirulina extraction capacity clusters in the United States, Germany, and Japan, with each geography deploying distinct regulatory frameworks and cultivation architectures to secure pharmaceutical-grade certification.
United States
FDA GRAS determinations for new algae strains drive investment timelines. EPA effluent guidelines shape open-pond versus photobioreactor decisions in California and Hawaii. Arizona and New Mexico host expanding controlled pond systems supplying clinician-dispensed supplement channels.
Germany
EFSA Novel Food authorization requirements concentrate toxicology testing infrastructure in Frankfurt and Munich corridors. Broken-cell chlorella processing commands margin premiums from Swiss and German formulators. Bavaria anchors fermentation-derived lipid capacity for infant formula applications.
Japan
PMDA FOSHU consultation procedures offer faster regulatory pathways than EU routes for functional food positioning. Euglena Co., Ltd. exemplifies domestic cultivation scale in Yokohama and Kagoshima prefectures. Tokyo-based nutraceutical formulators secure supply agreements with validated extraction facilities.
Israel
Dunaliella beta-carotene production concentrates in Negev Desert cultivation sites with superior solar irradiance profiles. The national pharmaceutical regulator enforces ISO 16128 natural origin certification for cosmetic pigment exports. Rehovot and Beer Sheva host downstream processing clusters serving European cosmetic houses.
China
Spirulina volume throughput dominates global supply through Inner Mongolia and Yunnan open-pond operations. SAMR food safety standards tighten documentation requirements for export-oriented producers. Qingdao and Dalian concentrate photobioreactor manufacturing equipment fabrication.
Global Algae Market Vendor Landscape
Concentration sits with integrated nutrition and chemical conglomerates possessing validated extraction protocols and multi-jurisdictional regulatory dossiers. The supplier base stratifies across pharmaceutical-grade specialists, fermentation technology platforms, and agricultural-commodity diversifiers. DSM-Firmenich and Cargill Incorporated anchor premium positioning through captive cultivation infrastructure. Competitive dynamics center on backward integration into toxicology testing capabilities and long-term offtake contracting with infant formula manufacturers.
Within the integrated conglomerate tier, DSM-Firmenich and BASF SE exemplify multi-regional regulatory navigation capacity. Cargill Incorporated occupies a position linking agricultural commodity systems to pharmaceutical-grade certification pathways. Corbion represents the fermentation-derived lipid specialization archetype. These three anchors demonstrate how scale and regulatory dossier depth determine procurement authority in clinician-dispensed and pediatric nutrition channels.
| Leading Market Players |
|---|
| DSM-Firmenich |
| BASF SE |
| Cargill Incorporated |
| Cyanotech Corporation |
| Corbion |
| Archer-Daniels-Midland Company |
| Euglena Co., Ltd. |
| Cellana Inc. |
| Algatechnologies Ltd. |
| Others |
Supply Flow & Price Mechanics
Fermentation-derived DHA concentrates displacing open-pond lipid extraction are redrawing supply geography toward Bavaria and Yokohama while compressing margins for legacy autotrophic producers. This substitution dynamic simultaneously elevates pharmaceutical-grade certification premiums and depresses commodity spirulina spot pricing.
Pricing Analysis
EFSA Novel Food authorization dictates the pricing tier structure across European nutraceutical channels. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels separates DSM-Firmenich's astaxanthin complexes from commodity spirulina powders. Cost compression in pharmaceutical-grade tiers is intensifying because toxicology testing infrastructure scarcity concentrates among legacy producers. Infant formula manufacturers exhibit least price sensitivity while animal feed processors drive hardest bargain negotiations.
Supply Chain Analysis
Inventory lead times for broken-cell chlorella milling equipment stretch 14-20 weeks due to vendor concentration in Germany and Switzerland. Geographic supply concentration centers on the United States, China, and Israel for spirulina, chlorella, and dunaliella respectively. Raw material dependencies draw from industrial CO2 feedstock markets, specialized nutrient media formulations, and pharmaceutical-grade solvent supplies. Single-source vulnerability in phycocyanin extraction technician pools threatens downstream pigment recovery. Distribution runs through long-term offtake contracts with infant formula manufacturers and clinician-dispensed supplement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as EU Novel Food traceability mandates splinter procurement authority among validated suppliers with pre-submission toxicology dossiers. Clinician-dispensed omega-3 formulations and Japan's FOSHU pathway create addressable niches outside consolidated retail channels.
For Market Incumbents: Shield pharmaceutical-grade positioning by deepening backward integration into captive toxicology testing infrastructure in Frankfurt and Munich corridors. DSM-Firmenich and Cargill Incorporated should lock multi-year offtake contracts with pediatric nutrition manufacturers before fermentation-derived lipid platforms achieve cost parity. Priority lever sits with securing GRAS determination pipeline for novel algae strains entering food and supplement channels. For New Entrants and Emerging Players: Japan's PMDA FOSHU consultation procedures offer fastest regulatory pathway for functional food positioning among OECD markets. Target direct-to-practitioner supplement channels for high-purity astaxanthin complexes where retail markup bypasses create margin headroom. Precision fermentation convergence with heterotrophic algae cultivation represents most penetrable white-space for synthetic biology platforms seeking customized lipid profiles. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors fermentation-technology platforms with multi-jurisdictional regulatory dossiers. Long-term viability across the 5-10 year window hinges on backward integration into quality assurance infrastructure rather than commodity cultivation scale. Signal to watch is EFSA authorization timeline compression for infant formula applications as toxicology data package standardization accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | EFSA Novel Food authorization timelines compress competitive set to validated producers with toxicology infrastructure. |
| Precision Fermentation Platform Integration | Synthetic biology convergence with heterotrophic cultivation enables year-round EPA and DHA production consistency. |
| Long-Term Offtake Contracting | Multi-year supply agreements with infant formula manufacturers lock feedstock demand and secure revenue recognition. |
| Backward Integration into Toxicology Testing | Captive safety evaluation infrastructure accelerates regulatory clearance for new microalgae strains entering European channels. |
| Direct-to-Practitioner Channel Expansion | Clinician-dispensed supplement formulations bypass retail markup structures for high-purity astaxanthin complexes. |
Methodological Framework
Operator-level perspectives from cultivation facility managers, downstream nutraceutical formulators, regulatory affairs specialists at EFSA and FDA, and infant formula procurement directors anchored the qualitative base. Primary interview data combined with secondary validation from EFSA Novel Food authorization databases, FDA GRAS notification filings, EPA effluent guideline records, and customs trade flows for algae-derived ingredient imports. Bottom-up facility capacity assessments and top-down demand modeling from pediatric nutrition and cardiovascular supplement channels enabled triangulation.
Sensitivity analysis tested forecast robustness against CO2 feedstock price volatility, EFSA authorization timeline variability, and petroleum diesel cost parity assumptions. Segmentation dimensions modeled include species type, application tier, cultivation architecture, and geographic regulatory cluster. CAGRs derived from installed capacity trajectories, offtake contract visibility, and substitution elasticity between fermentation-derived and autotrophic lipid sources. Forecast inputs incorporated photobioreactor capital cost curves and pharmaceutical-grade certification penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained EU Novel Food traceability enforcement or accelerated precision fermentation cost reduction would require recalibration. Forecasts reflect documented assumptions regarding regulatory divergence persistence and carbon credit market stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Single Cell Protein Market
Alternative Food Sources
Middle East and Africa Meal Replacement Products Market
Alternative Food Sources
Global Meal Replacement Market
Alternative Food Sources
Fishless Fillets Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Spirulina Market
Alternative Food Sources
Vegetable Proteins Market
Alternative Food Sources
Soy Leghemoglobin Market
Alternative Food Sources
Synthetic Food Market
Alternative Food Sources
Low Carbs Vegan Food Market
Alternative Food Sources
Europe Upcycled Food Products Market
Alternative Food Sources
Edible Insects Market
Alternative Food Sources
Bioengineered Food Market
Alternative Food Sources
Plant-Based Squalene Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market