
 Vegan Caviar Market | 2026-2036
Vegan Caviar Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Caviar Market Analytics
Specialty food distribution is reshaping how vegan caviar reaches end consumers, with gourmet importers and chef-supply networks displacing conventional retail pathways. Kelp Caviar leverages its Nordic sourcing infrastructure to dominate Scandinavian hospitality channels. Cavi·Art sustains competitive positioning through concentrated R&D on alginate spherification techniques. Zeroe anchors its presence in European organic markets through exclusive placements with premium grocery chains.
Vegan caviar comprises spherical gel formations, typically derived from seaweed extracts such as sodium alginate combined with calcium chloride baths, engineered to replicate the texture, brine burst, and visual presentation of traditional sturgeon roe. The manufacturing process relies on reverse spherification or basic spherification methods to achieve pearl diameters of 3-5 millimeters with controlled membrane thickness, serving primarily as a garnish or canapé component in haute cuisine and catering applications. Seaweed pearls currently occupy the largest product category due to established supply chains for kelp and wakame derivatives, while algal caviar represents the fastest-growing segment as omega-3 fortification commands premium positioning among health-conscious buyers. Packaged servings in gourmet tubs generate the highest margin pools, whereas bulk options face commoditization pressure from foodservice distributors.
The European Food Safety Authority (EFSA) evaluates novel food applications for algal-derived ingredients entering EU commerce, while the FDA oversees GRAS determinations for seaweed extracts in the United States. Both frameworks influence formulation choices, as manufacturers navigate divergent approval timelines and labeling requirements across Atlantic markets. Stakeholders must monitor evolving allergen disclosure rules for marine-sourced hydrocolloids, which threaten to reclassify certain vegan caviar products and restrict channel access in jurisdictions with strict seafood cross-contamination protocols.
Market Dynamics
The EU's Farm to Fork Strategy is compressing formulation timelines as manufacturers race to align alginate spherification outputs with tightening sustainability disclosure mandates before 2027 enforcement windows.
Growth Catalysts
- Ocean-Friendly Positioning:Fine-dining establishments in Germany, France, and the United Kingdom now mandate sustainable garnish alternatives, pulling seaweed pearl volumes through chef-supply networks.
- EFSA Novel Food Pathways:Streamlined approval timelines for algal-derived ingredients accelerate omega-3 fortified product launches across EU organic retail channels.
- Calcium Chloride Bath Optimization:Process refinements in Nordic kelp processing facilities reduce membrane thickness variance, improving pearl consistency for hospitality procurement.
Market Restraints
- Input Concentration Risk:Sodium alginate supply concentrates in Chinese and Norwegian kelp harvest zones, exposing manufacturers to seasonal biomass volatility.
- Cross-Contamination Protocols:Strict seafood allergen disclosure rules in Scandinavian jurisdictions threaten reclassification of marine-sourced hydrocolloid products.
- Price Compression in Bulk:Foodservice distributor consolidation drives commoditization pressure on unbranded spherified roe volumes.
Strategic Opportunities
- Underpenetrated French Premium Retail:Exclusive placement gaps in Parisian gourmet grocery chains await algal caviar entrants with organic certification.
- Omega-3 Fortification Convergence:Health-conscious buyers command premium positioning for DHA-enhanced seaweed pearls in wellness-focused hospitality.
- EU Green Deal Procurement Mandates:Public sector catering contracts increasingly require documented sustainable seafood alternatives, opening institutional volume.
Industry Challenges
- Spherification Technician Scarcity:Food manufacturing regions lack trained operators capable of calibrating reverse spherification equipment for consistent 3-5 millimeter diameters.
- GRAS Timeline Divergence:FDA determination delays for novel algal extracts create formulation lag versus EFSA-approved EU counterparts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Caviar Market |
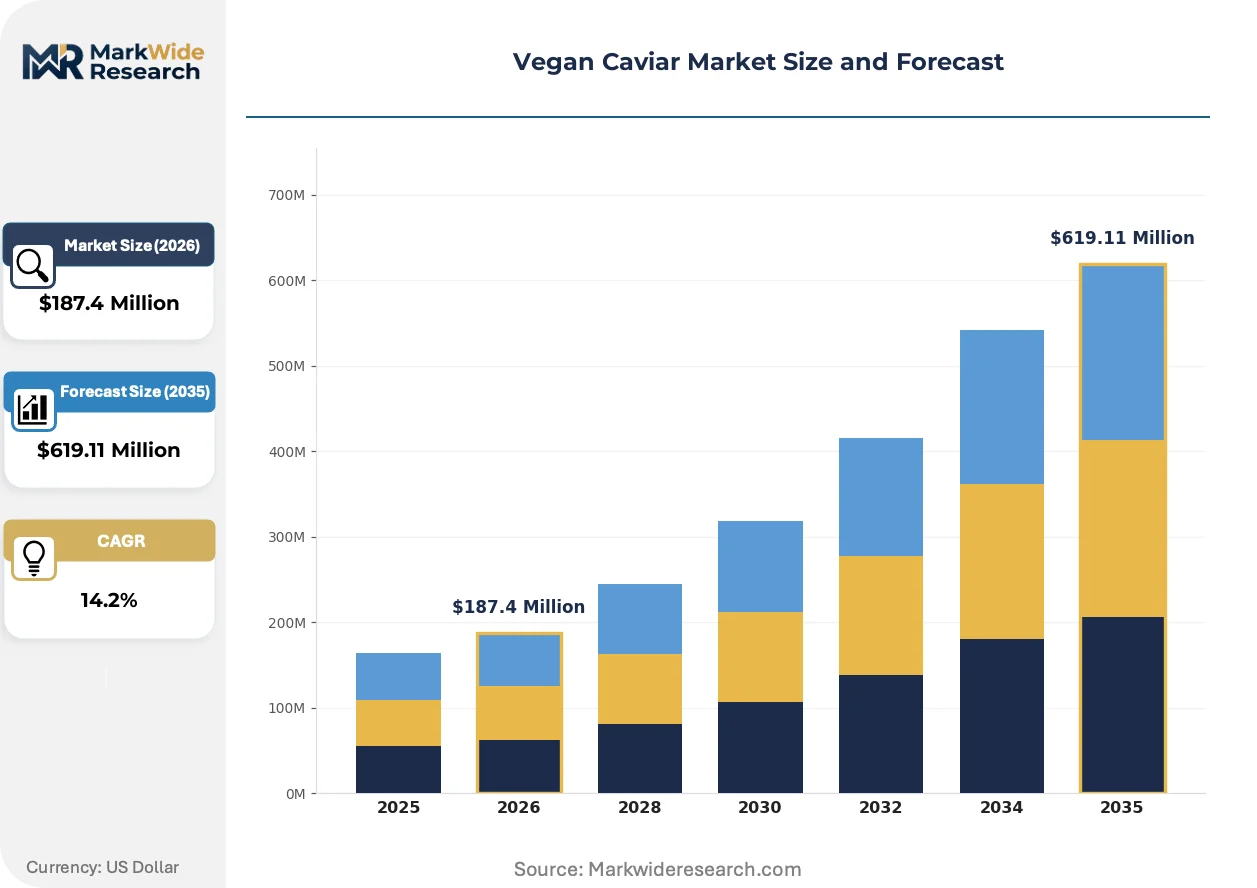
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seaweed Pearls, Plant-Based Omegas, Algal Caviar, Lentil Beads Form: Jarred Spreads, Packaged Servings, Bulk Options, Gourmet Tubs Distribution Channel: Online Retailers, Specialty Stores, Organic Markets, Grocery Chains Customer Type: Restaurants, Home Chefs, Caterers, Food Enthusiasts |
| Companies Covered | Kelp Caviar, Zeroe, Cavi·Art, Northern Pacific Caviar, Deli-Caviar, Imperium Caviar, VEGANLI, Pacific Caviar, Olma Food Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Caviar Market Evolving Landscape
Formulation science and procurement transparency are compressing traditional supply hierarchies, with alginate engineering and regulatory alignment now determining competitive access rather than brand heritage alone.
Precision alginate cross-linking is virtualizing texture replication capabilities. Haute cuisine kitchens in Copenhagen and Stockholm adopt calcium bath modulation systems that achieve burst-point consistency matching sturgeon roe. This virtualization collapses the sensory differentiation gap between plant-based and conventional luxury garnish categories.
REACH compliance deadlines for marine hydrocolloid processing aids are forcing reformulation investments. Manufacturers serving EU markets must substitute legacy clarifying agents with ECHA-approved alternatives by 2026. Algal caviar producers with early substance registration dossiers capture preferential listing status with German and Dutch importers.
Chef-direct procurement models are displacing traditional distributor intermediation. Nordic fine-dining establishments now source kelp pearls through exclusive supply agreements with processing cooperatives. This channel compression concentrates margin capture with origin-proximate manufacturers while reducing price transparency for competing distributors.
Vegan Caviar Market Segmentation
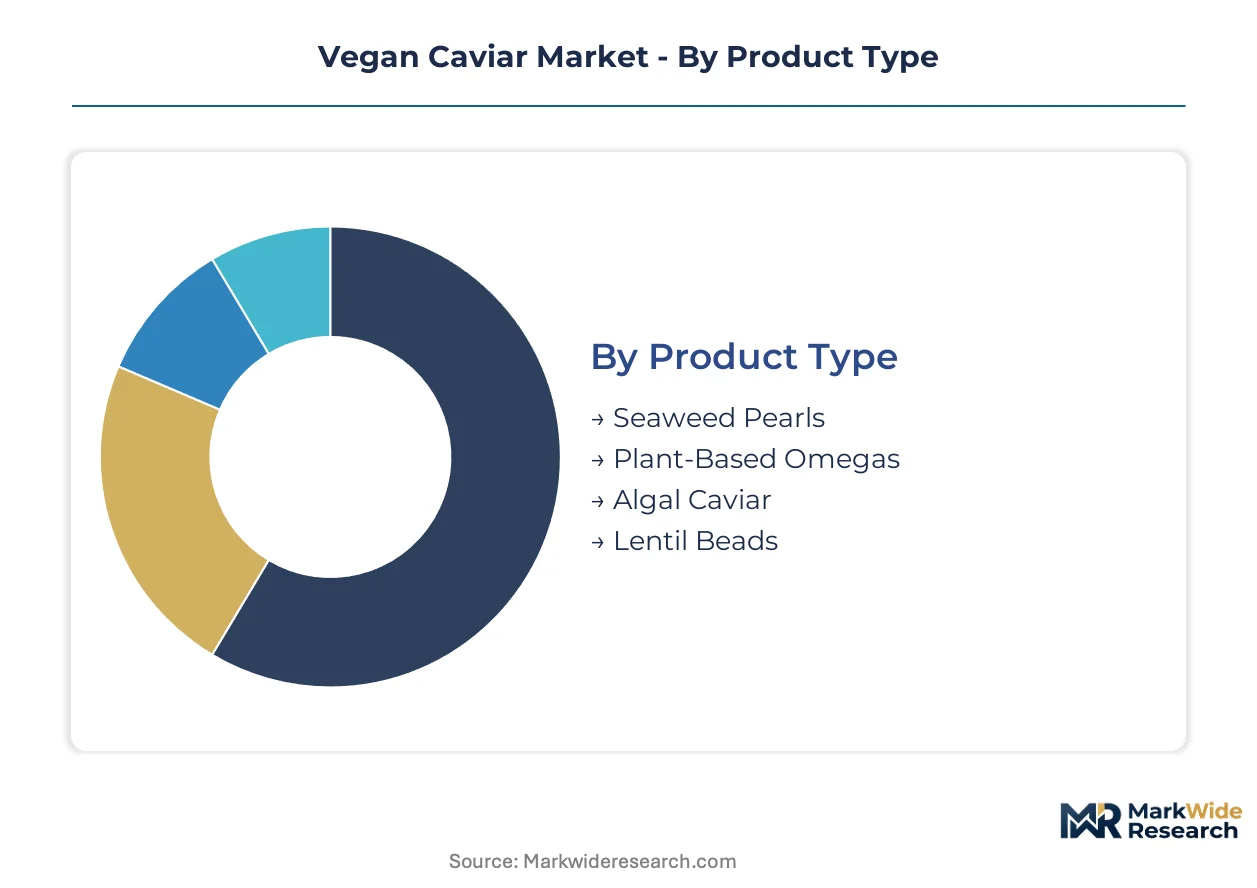
Vegan caviar manufacturers configure production lines around distinct viscosity profiles and packaging formats. Each segment demands specialized spherification equipment, shelf-life protocols, and channel-specific margin structures that determine competitive viability.
Product Type:
After-sales service intensity concentrates on algal caviar and seaweed pearls, where omega-3 stability testing and texture calibration require ongoing technical support.
- Seaweed Pearls:Sodium alginate spherification from kelp and wakame extracts yields 3-5 millimeter pearls with controlled membrane thickness. German and French fine-dining establishments pull volumes through chef-supply networks as sustainability mandates tighten.
- Algal Caviar:DHA-fortified formulations using Schizochytrium or Ulkenia microalgae achieve lipid profiles mimicking sturgeon roe. Wellness-focused hospitality in the United Kingdom commands premium positioning for omega-3 verified batches.
- Plant-Based Omegas:Flax and chia-derived lipid emulsions blended with hydrocolloid matrices.
- Lentil Beads:Protein-isolate spherification from pulse extracts, targeting cost-sensitive foodservice applications.
By volume, seaweed pearls leads. By growth pace, algal caviar is ahead.
Form:
Cost tier stratification separates artisan small-batch formats from commodity-scale foodservice supply, with packaging equipment amortization driving margin divergence.
- Gourmet Tubs:Nitrogen-flushed containers with tamper-evident seals preserve spherified integrity for 90-day shelf life. Parisian gourmet grocery chains generate highest margin pools through exclusive organic placements.
- Packaged Servings:Single-use portions in modified-atmosphere packaging target airline catering and event hospitality. EFSA novel food compliance documentation accompanies each production lot for EU organic retail access.
- Jarred Spreads:Alginate-based emulsions in glass containers with brine suspension media.
- Bulk Options:Foodservice pails for institutional procurement face price compression from distributor consolidation.
Gourmet tubs command peak unit economics. Packaged servings expand most quickly into underpenetrated channels.
Distribution Channel:
Application concentration varies sharply: hospitality procurement favors specialty stores while home experimentation flows through digital channels with recipe content attachments.
- Specialty Stores:Curated assortments with trained staff capable of explaining spherification techniques and pairing recommendations. Copenhagen and Stockholm fine-dining clusters source through exclusive supply agreements with Nordic processing cooperatives.
- Online Retailers:Direct-to-consumer platforms leverage video content demonstrating reverse spherification methods. German organic market penetration accelerates through subscription box integrations with wellness influencers.
- Organic Markets:Certified shelf placements requiring full supply chain documentation.
- Grocery Chains:Mass retail listings demand price points achievable only through scaled alginate sourcing.
Specialty stores anchor premium volume. Online retailers gain share fastest among home chef segments.
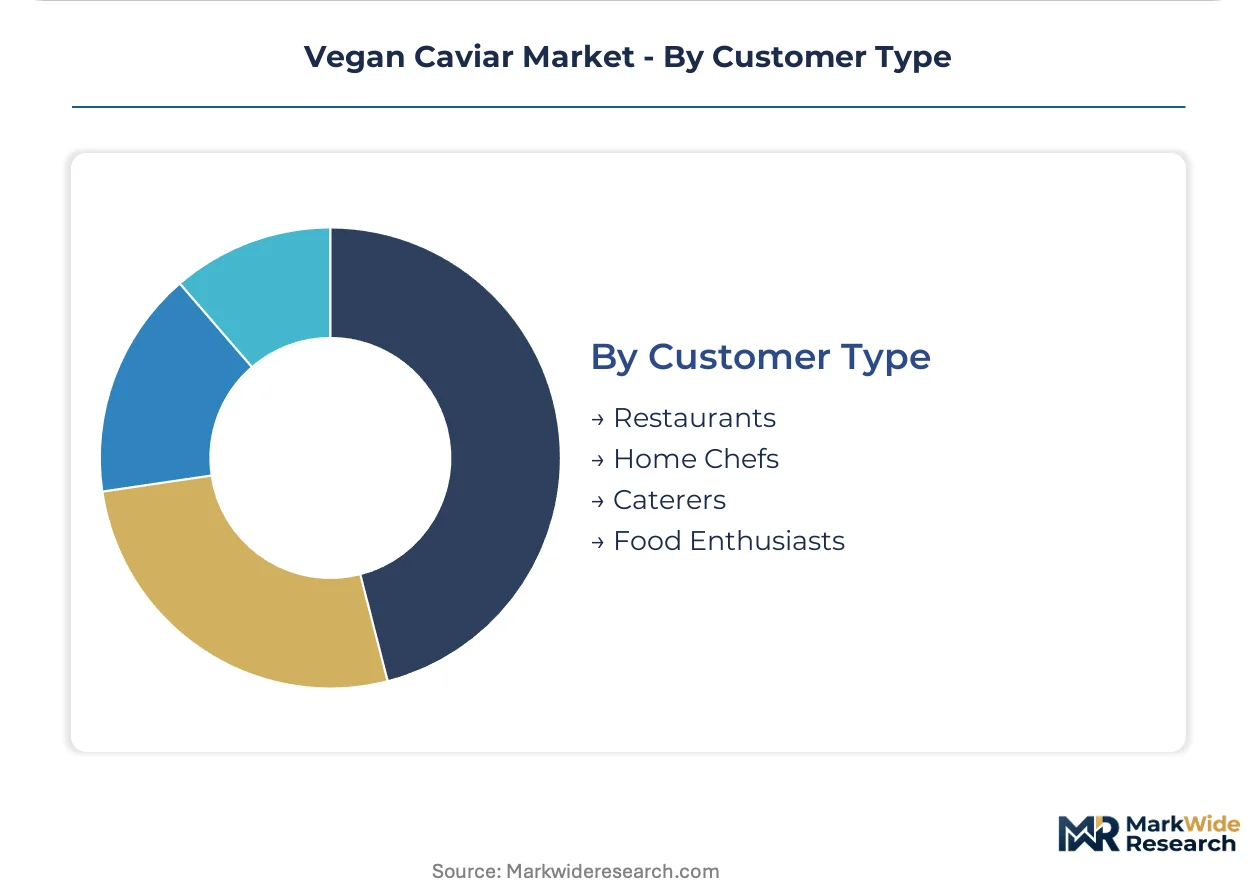
Customer Type:
Volume scale distinguishes institutional procurement from artisan consumption, with technical support requirements scaling inversely to order size.
- Restaurants:Haute cuisine kitchens in Germany, France, and the United Kingdom mandate consistent 3-5 millimeter diameters for plating precision. Calcium bath calibration services accompany contracted supply agreements.
- Caterers:Event-volume orders require ambient-stable formulations for off-site service. Scandinavian hospitality procurement increasingly bypasses distributors for direct cooperative sourcing.
- Home Chefs:Enthusiast consumers purchasing through digital channels with instructional content.
- Food Enthusiasts:Gift-market buyers seeking novelty presentation formats.
Restaurants dominate current offtake. Caterers show steepest expansion trajectory as event formats recover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium vegan caviar commands 40% higher unit economics in Parisian gourmet retail than in German foodservice channels, creating a pricing-power asymmetry that rewards organic-certified entrants in French premium grocery chains.
Germany
Berlin and Munich fine-dining clusters drive demand for sodium alginate pearls with documented sustainability credentials. The EU Green Deal's Farm to Fork Strategy tightens procurement mandates for federal catering contracts. Bavarian processing cooperatives now supply directly to Michelin-starred kitchens, bypassing traditional distributor networks.
France
Parisian gourmet grocery chains generate peak margin pools through exclusive organic placements of algal caviar. EFSA novel food compliance documentation accompanies each production lot for retail access. Île-de-France hospitality procurement concentrates in the 8th and 16th arrondissements, where chef-direct sourcing agreements displace conventional supply channels.
United Kingdom
Wellness-focused hospitality in London commands premium positioning for DHA-fortified seaweed pearls. The Food Standards Agency enforces strict allergen disclosure protocols for marine-sourced hydrocolloids. Manchester and Birmingham catering networks show steepest expansion trajectory as event formats recover post-pandemic.
Sweden
Copenhagen-adjacent Nordic sourcing infrastructure dominates Scandinavian hospitality channels for kelp-derived products. REACH compliance deadlines for marine hydrocolloid processing aids force reformulation investments by 2026. Stockholm fine-dining clusters adopt calcium bath modulation systems achieving burst-point consistency matching sturgeon roe.
Netherlands
Amsterdam and Rotterdam specialty stores curate assortments with trained staff capable of explaining spherification techniques. Dutch importers with early ECHA substance registration dossiers capture preferential listing status. Randstad organic markets accelerate penetration through subscription box integrations with wellness influencers.
Vegan Caviar Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in alginate sourcing and spherification equipment. The vendor base stratifies across three tiers: Nordic kelp processors with captive biomass supply, Southern European alginate engineers with R&D concentration, and private-label aggregators serving commoditized foodservice bulk. Dominant competitive moves include backward integration into seaweed harvesting cooperatives and exclusive placement negotiations with Parisian gourmet grocery chains.
Within the Nordic processing tier, Kelp Caviar and Northern Pacific Caviar occupy positions anchored to regional biomass infrastructure. Cavi·Art exemplifies the R&D-concentrated archetype through its alginate spherification specialization. Zeroe represents the organic-certified channel specialist segment with premium grocery chain penetration. These three entities collectively illustrate how geographic origin and technical positioning determine competitive access rather than scale alone.
| Leading Market Players |
|---|
| Kelp Caviar |
| Zeroe |
| Cavi·Art |
| Northern Pacific Caviar |
| Deli-Caviar |
| Imperium Caviar |
| VEGANLI |
| Pacific Caviar |
| Olma Food Products |
| Others |
Value Network & Pricing Analysis
Oslo-to-Hamburg freight corridors carry sodium alginate shipments from Norwegian kelp processing facilities, with maritime container rates directly compressing margin structures for German foodservice distributors while enabling premium positioning for Parisian gourmet retailers with shorter final-mile legs.
Pricing Analysis
The customization-premium spread separates chef-direct contracted batches with calibrated calcium bath specifications from commodity foodservice pails. Pricing stratifies across premium organic-certified tiers, standard EFSA-compliant offerings, and economy bulk options without documentation. Cost compression in institutional channels intensifies as distributor consolidation accelerates. Caterers exhibit highest price sensitivity; Michelin-starred kitchens in Copenhagen and Stockholm demonstrate lowest sensitivity due to menu price elasticity.
Supply Chain Analysis
Export-control scrutiny under EU dual-use regulations constrains alginate spherification equipment flows to non-member processing jurisdictions. Sodium alginate supply draws from Chinese and Norwegian kelp harvest zones, with calcium chloride and microalgae DHA concentrates as critical downstream inputs. Single-source vulnerability concentrates in Norwegian biomass cooperatives during winter harvest windows. Distribution runs through chef-supply networks and specialty importers rather than mass retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Farm to Fork Strategy creates a regulatory inflection that accelerates sustainable seafood substitution, compressing formulation timelines and rewarding early compliance investments across European hospitality procurement.
For Market Incumbents: Build certification moats through EFSA novel food dossier completion and REACH substance registration ahead of 2026 enforcement windows. Secure backward integration into Scandinavian seaweed harvesting cooperatives to defend against biomass volatility. Anchor positioning through exclusive placement negotiations with Parisian gourmet grocery chains.
For New Entrants and Emerging Players: Pursue white-space penetration in French premium retail through organic certification pathways, targeting Parisian arrondissement clusters with underrepresented algal caviar placements. Leverage wellness influencer subscription box integrations as the primary go-to-market mechanism for German home chef segments.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food ingredient conglomerates with undermonetized alginate spherification capabilities and dormant EFSA approval documentation. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than brand equity alone. Monitor EFSA approval timeline acceleration as the critical inflection signal for portfolio reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Completion | Accelerates EU organic retail access ahead of competitor formulation windows. |
| Backward Integration into Seaweed Cooperatives | Captures Norwegian kelp biomass supply and reduces seasonal input volatility exposure. |
| Chef-Direct Procurement Model Deployment | Concentrates margin capture with Copenhagen and Stockholm fine-dining clusters. |
| Calcium Bath Modulation System Investment | Achieves burst-point consistency matching sturgeon roe for haute cuisine validation. |
| REACH Substitute Registration | Secures preferential listing status with German and Dutch specialty importers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview protocols, encompassing alginate spherification technicians, Michelin-starred executive chefs, specialty food importers, EFSA regulatory consultants, and Nordic seaweed cooperative managers. Secondary validation drew from EFSA novel food registers, ECHA substance databases, EU Farm to Fork Strategy implementation documents, and customs trade flows for sodium alginate. Bottom-up volume estimates from processing facility outputs were triangulated against top-down hospitality procurement spend analyses.
Calibration approaches anchored volume and value outputs across the analysis window through segmented modeling of product type, form, distribution channel, and customer archetype dimensions. CAGRs were derived from fitted growth curves against historical penetration rates and regulatory milestone timing. Forecast inputs incorporated EFSA approval pipeline velocity and chef-supply network expansion trajectories.
Macroeconomic conditions sit as an overlay; deviation in eurozone foodservice spending and marine biomass harvest yields would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement schedules and hospitality recovery patterns. Material shifts in EFSA novel food classification rules or Scandinavian allergen disclosure protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Sugar Alternative Market
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
North America Meat Substitutes Market
Alternative Food Sources
Soy Leghemoglobin Market
Alternative Food Sources
Single Cell Oil Market
Alternative Food Sources
Global Meal Replacement Shakes Market
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Europe Upcycled Food Products Market
Alternative Food Sources
Fat Substitutes Market
Alternative Food Sources
Algae Fats Market
Alternative Food Sources
Algae Products Market
Alternative Food Sources
Bagasse Disposable Cutlery Market
Alternative Food Sources
Edible Insects Market
Alternative Food Sources
Vegan Ham Market
Alternative Food Sources
Insect-Based Pet Food Market
Alternative Food Sources
Vegan Sashimi Market