
 Plant-Based Squalene Market | 2026-2036
Plant-Based Squalene Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Squalene Market Insights
Spain is rewriting capacity dynamics for plant-derived squalene as Andalusian olive processors expand molecular distillation capabilities. Amyris leverages precision fermentation infrastructure in Brazil to supply sugarcane-derived squalene at industrial scale. Sophim anchors Mediterranean supply chains through olive-origin extraction in France, while Croda International Plc competes across both oleochemical and biotechnology routes.
Plant-based squalene denotes a triterpene hydrocarbon extracted or biosynthesized from renewable botanical sources, typically comprising C30H50 with a melting point near -75°C and exceptional oxidative stability for lipid-based formulations. Cosmetics applications command the dominant value pool given squalene's skin-identical sebum mimicry and emollient performance, while nutraceuticals represent the fastest-growing segment as functional food brands seek lipid-soluble antioxidant carriers. Sugarcane fermentation yields the highest purity grades for pharmaceutical specifications, whereas olive-derived material occupies mid-tier skincare positioning through established Mediterranean supply chains.
EMA stability guidelines and REACH substance registration shape pharmaceutical-grade purity thresholds across Europe, while FDA cosmetic ingredient oversight and EPA bio-based product certification influence North American market access pathways. The EU F-Gas Regulation indirectly advantages plant-derived alternatives by restricting petrochemical process inputs. Stakeholders must weigh biotechnology scale-up timelines against agricultural yield volatility when committing capital to specific feedstock platforms.
Market Dynamics
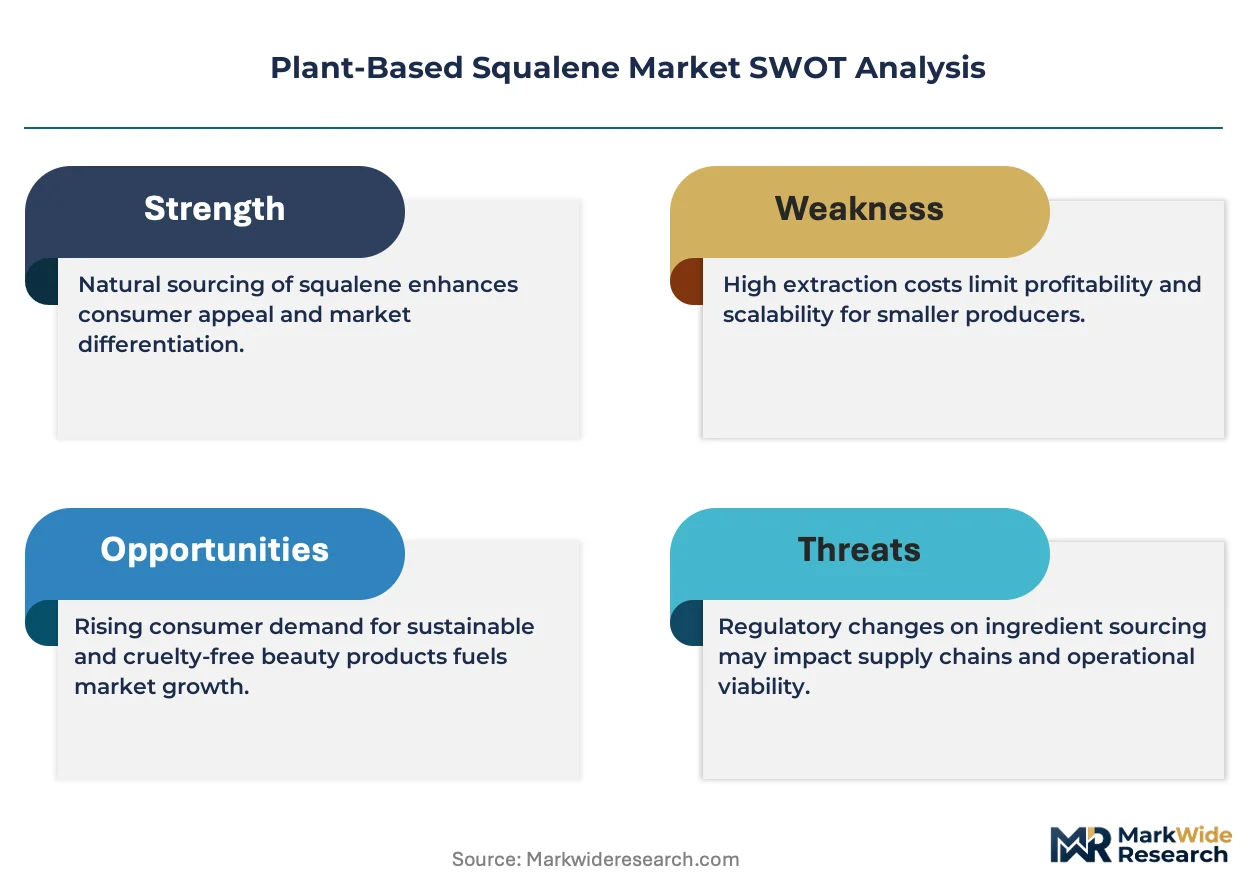
REACH substance registration and the EU Green Deal are compressing petrochemical squalane volumes while precision fermentation infrastructure scales in Brazil and sugarcane biorefineries consolidate supply-side control over high-purity pharmaceutical grades.
Growth Catalysts
- Clean-label cosmetics mandates:Formulators in France and South Korea are reformulating sebum-mimicry products around botanical-origin emollients as retailer sustainability scorecards harden.
- EMA stability guidelines:Pharmaceutical-grade purity thresholds for lipid-based drug delivery systems now favor sugarcane-derived squalene over olive-origin material for oxidation-sensitive formulations.
- Olive crushing infrastructure:Andalusian processors in Spain are retrofitting molecular distillation units to capture squalene from deodorizer distillate streams previously discarded.
Market Restraints
- Olive oil price volatility:Squalene extraction economics remain tethered to edible oil commodity cycles, squeezing refinery margins when harvests disappoint in Mediterranean growing regions.
- Fermentation capex concentration:Industrial-scale bioreactor networks for sugarcane-derived squalene concentrate in Brazilian industrial corridors, creating single-geography supply risk.
- Petrochemical substitution inertia:Shark liver oil and synthetic squalane retain cost advantages in mass-market personal care, delaying feedstock transitions.
Strategic Opportunities
- Pharmaceutical lipid excipients:mRNA vaccine stabilization protocols are opening specification windows for high-purity plant-derived squalene as a non-animal adjuvant carrier.
- EU F-Gas Regulation:Restrictions on fluorinated process gases indirectly advantage bio-based emollient routes by raising synthetic production costs.
- Direct-to-brand supply contracts:Bypassing traditional oleochemical distributors allows olive-origin extractors to capture premium positioning through chain-of-custody verification.
Industry Challenges
- Bioprocess engineering talent scarcity:Precision fermentation scale-up requires hybrid skill sets spanning metabolic pathway optimization and industrial bioreactor operation that outpace academic pipeline output.
- REACH dossier compilation timelines:Full substance registration for novel sugarcane-derived grades demands 18-24 month toxicological study completion before market access.
- Olive-origin standardization gaps:Variable triterpene concentration across cultivar and harvest conditions complicates batch-to-batch consistency for cosmetic formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Squalene Market |
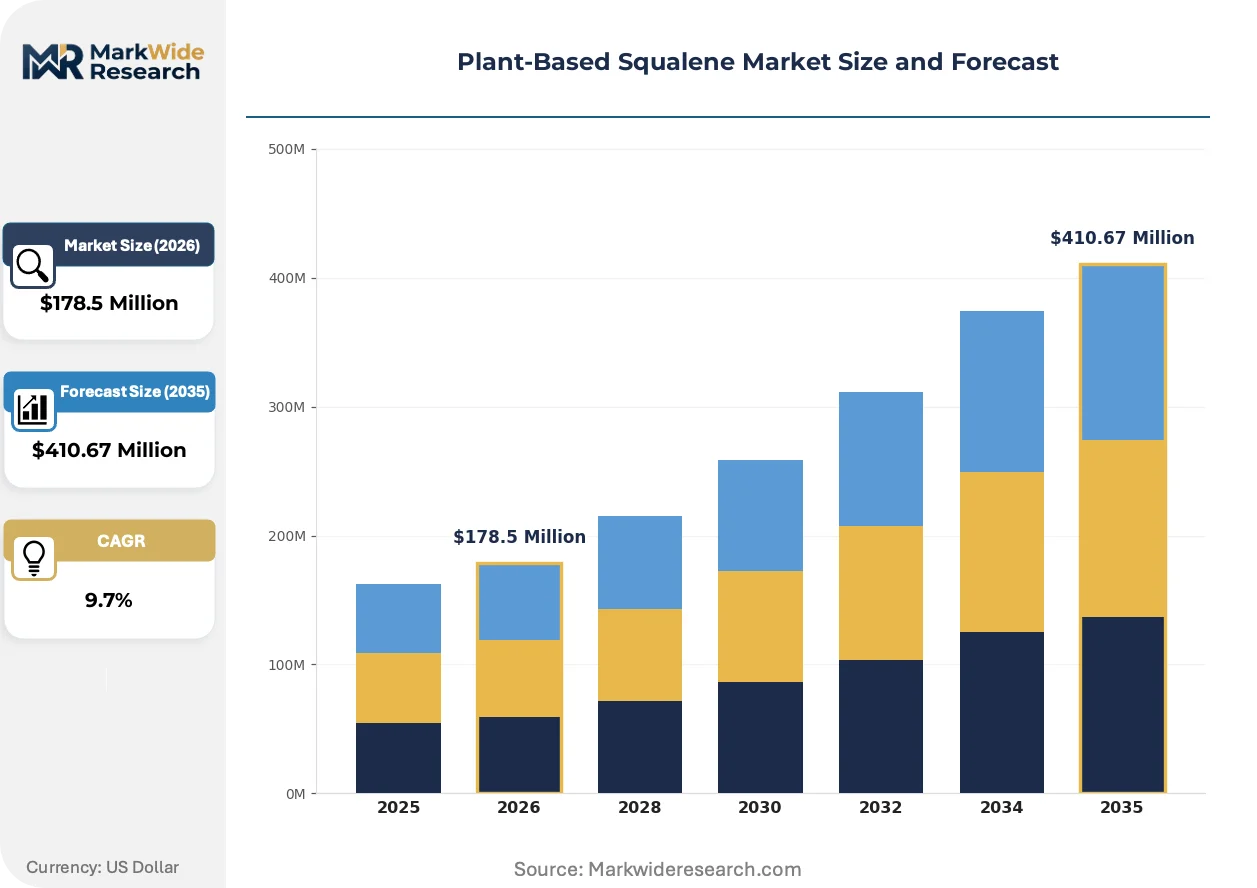
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $410.67 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Pharmaceuticals, Supplements, Food Additives Source: Olive Oil, Sugarcane, Amaranth, Others Application: Skincare, Haircare, Functional Foods, Nutraceuticals End User: Retail Consumers, Manufacturers, Healthcare Providers, Beauty Industry |
| Companies Covered | Amyris, Sophim, Croda International Plc, Evonik, Clariant, Nucelis, Jedwards International, EPF Biotek, Henry Lamotte Oils GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Squalene Market Trends and Innovations
Digital supply chain verification and biotechnology scale-up are converging to restructure how plant-derived squalene is sourced, certified, and priced across pharmaceutical and cosmetic value chains.
Precision fermentation using engineered yeast strains is virtualizing the traditional agricultural dependency of squalene production. Pharmaceutical excipient manufacturers are adopting sugarcane-derived material at accelerated qualification timelines. This biotechnology pathway is virtualizing geographic concentration risk by decoupling output from Mediterranean olive harvest variability.
The EU F-Gas Regulation and REACH authorization requirements are tightening process input restrictions for petrochemical squalane manufacturers. Synthetic routes face elevated compliance burdens as fluorinated solvents and high-pressure hydrogenation fall under substance scrutiny. European cosmetic formulators are responding by dual-sourcing olive and fermentation-origin material to hedge regulatory exposure.
Clean-label procurement mandates from prestige beauty retailers are compressing supplier qualification cycles. Brand sustainability teams now require mass-balance certification and carbon intensity scoring before contract execution. This behavioral shift is most visible in French and South Korean markets where retailer-led ingredient blacklists are reshaping refinery customer portfolios.
Plant-Based Squalene Market Segmentation
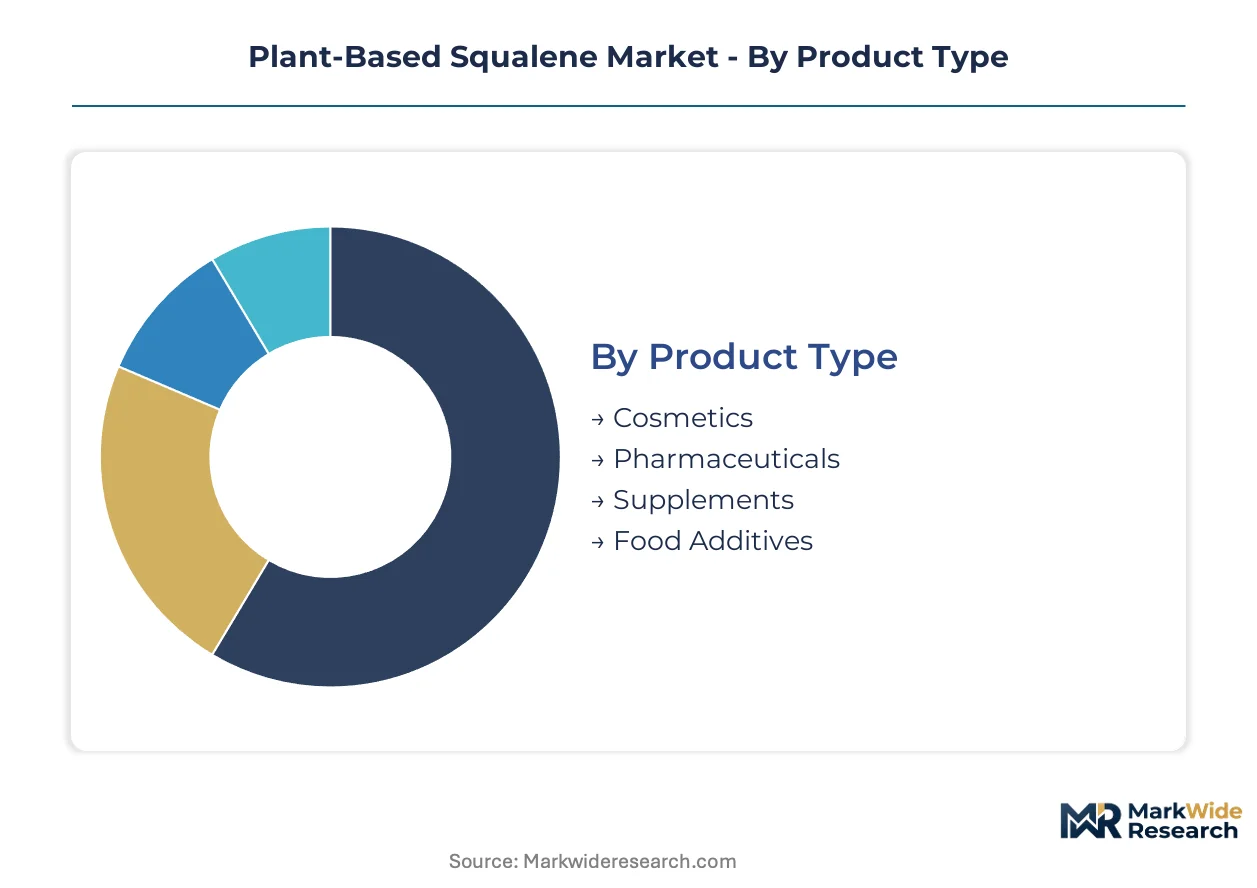
Plant-based squalene procurement patterns diverge sharply across end-use specifications, with pharmaceutical-grade purity commanding fundamentally different sourcing protocols than cosmetic formulations. Segmentation discipline reveals where margin pools concentrate and which feedstock-platform investments align with specific customer qualification requirements.
Product Type:
After-sales technical service intensity escalates from cosmetic emollient supply toward pharmaceutical excipient partnerships, with documentation burdens and stability-testing support defining supplier stickiness.
- Cosmetics:Sebum-mimicry formulations for prestige skincare drive specification diversity, with French and South Korean formulators demanding chain-of-custody verification and carbon intensity scoring. REACH-compliant documentation and retailer sustainability scorecards now gate market access for olive-origin material in European clean-label product lines.
- Pharmaceuticals:Lipid-based drug delivery systems and mRNA vaccine adjuvant carriers require sugarcane-derived grades meeting EMA stability guidelines, with oxidation-sensitive formulations rejecting olive-origin variability. Amyris precision fermentation infrastructure supplies this specification tier from Brazilian biorefineries.
- Supplements:Functional food brands seek lipid-soluble antioxidant carriers for softgel encapsulation, with purity thresholds sitting between cosmetic and pharmaceutical grades.
- Food Additives:Limited regulatory approval pathways restrict penetration, with EFSA novel food dossiers demanding extensive toxicological study completion.
Cosmetics holds the largest share; momentum sits with Pharmaceuticals.
Source:
Cost tier differentiation separates fermentation-derived purity premiums from agricultural extraction economics, with capital intensity and geographic risk exposure diverging across feedstock platforms.
- Olive Oil:Mediterranean crushing infrastructure in Spain and Italy feeds specialized refinery networks capturing squalene from deodorizer distillate streams. Sophim anchors French supply chains through molecular distillation capabilities, though batch-to-batch triterpene concentration variability complicates cosmetic formulator consistency requirements.
- Sugarcane:Engineered yeast strain fermentation in Brazilian industrial corridors yields pharmaceutical-grade purity with virtualized geographic concentration risk, decoupling output from harvest variability. Croda International Plc competes across this biotechnology route with industrial-scale bioreactor networks.
- Amaranth:Niche positioning for allergen-free cosmetic claims, with limited crushing infrastructure constraining volume scalability.
- Others:Wheat germ and rice bran origins occupy specialty positioning without meaningful scale.
Olive Oil holds the largest share; Sugarcane gains share fastest.
Application:
Volume concentration patterns favor topical delivery formats over ingestible categories, with formulation technology maturity and consumer acceptance timelines shaping adoption curves.
- Skincare:Emollient and antioxidant functionality in facial serums and moisturizers commands the dominant value pool, with sebum-mimicry properties driving replacement of petrochemical squalane in prestige and mass-market personal care.
- Haircare:Conditioning agent applications in premium shampoos and treatments leverage oxidative stability for shelf-life extension, with South Korean beauty manufacturers scaling botanical-origin purchases.
- Functional Foods:Lipid carrier applications for fat-soluble vitamins remain underdeveloped, with regulatory pathway complexity delaying market development.
- Nutraceuticals:Antioxidant supplementation positioning climbs fastest as wellness brands seek differentiation through clean-label lipid ingredients.
Skincare holds the largest share; Nutraceuticals climbs the fastest.
End User:
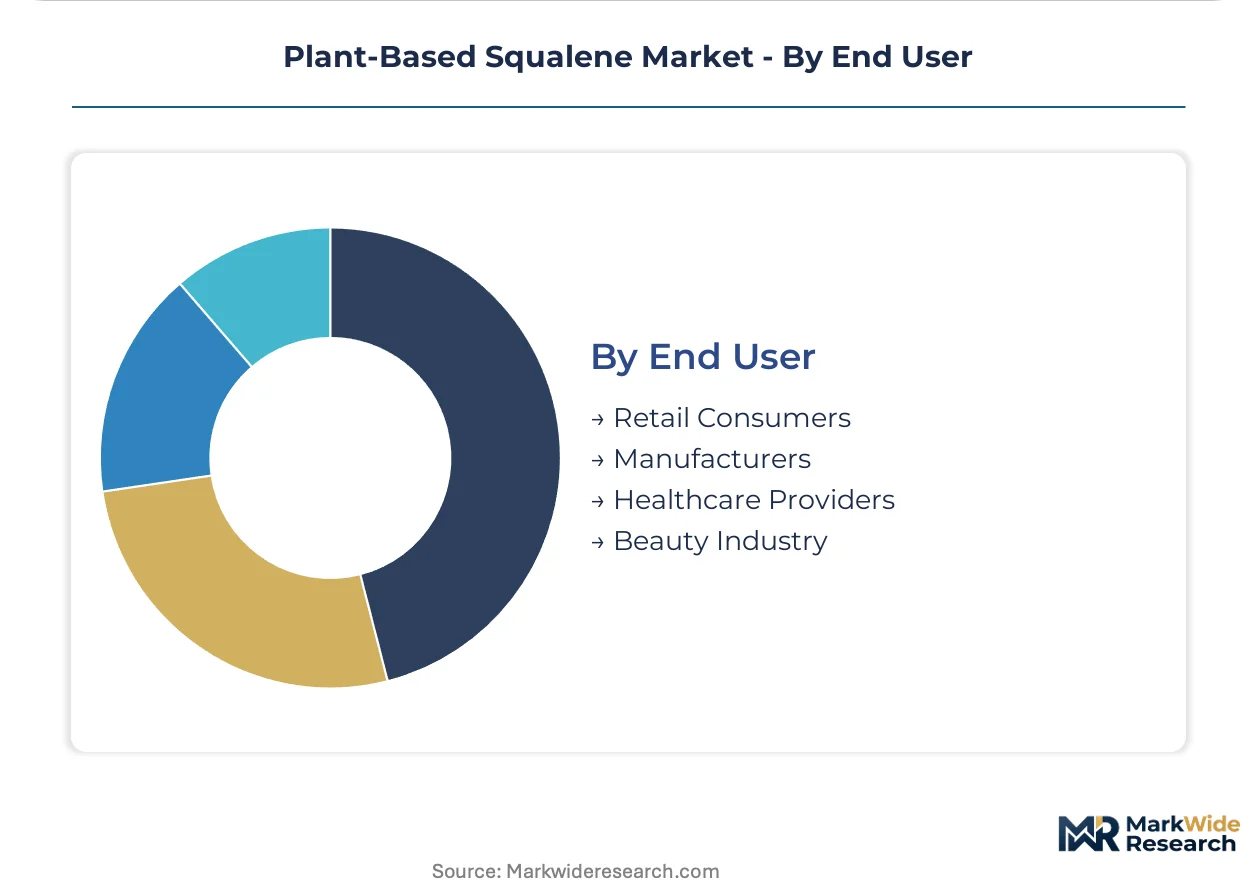
Customer type segmentation separates specification-heavy B2B relationships from brand-driven retail procurement, with contract structures and technical service demands diverging accordingly.
- Retail Consumers:Clean-label purchasing decisions increasingly filter through retailer sustainability scorecards and ingredient blacklists, with French and South Korean markets showing highest sensitivity to botanical-origin verification.
- Manufacturers:Cosmetic and pharmaceutical formulators drive procurement volume, with dual-sourcing strategies hedging regulatory exposure across olive and fermentation-origin material.
- Healthcare Providers:Limited direct engagement, with vaccine manufacturers and compounding pharmacies representing indirect demand channels.
- Beauty Industry:Prestige brand sustainability mandates compress supplier qualification cycles, with mass-balance certification now standard for contract execution.
Manufacturers holds the largest share; Retail Consumers gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Molecular distillation capacity clusters around Mediterranean olive processors and Brazilian fermentation corridors, with regulatory pressure in Europe and Asia-Pacific redirecting procurement toward verified botanical origins. Demand formation follows clean-label mandates from prestige beauty retailers and pharmaceutical excipient specifications.
France
Paris-based formulators drive sebum-mimicry reformulation as retailer sustainability scorecards harden. REACH substance registration and the EU Green Deal compress petrochemical alternatives. Sophim anchors supply chains through molecular distillation in southeastern refining clusters.
South Korea
Seoul beauty manufacturers scale botanical-origin purchases for K-beauty export positioning. MFDS cosmetic ingredient oversight tightens documentation requirements. Busan-Ulsan industrial corridors host specialized emollient distributors hedging across olive and fermentation sources.
Spain
Andalusian olive processors retrofit deodorizer distillate capture units as crushing volumes expand. EU F-Gas Regulation indirectly advantages bio-based routes. Jaén and Córdoba refining networks feed specialized cosmetic ingredient channels.
Brazil
São Paulo industrial corridors concentrate precision fermentation infrastructure for sugarcane-derived grades. ANVISA pharmaceutical excipient pathways open for high-purity adjuvant carriers. Campinas biorefinery clusters virtualize geographic concentration risk through engineered yeast strain production.
United States
FDA cosmetic ingredient oversight and EPA bio-based product certification shape market access for olive-origin imports. California clean beauty formulators demand chain-of-custody verification. New Jersey pharmaceutical corridors qualify sugarcane-derived material for lipid-based drug delivery systems.
Plant-Based Squalene Market Competitive Landscape
Biotechnology specialists and Mediterranean oleochemical refiners split the market along purity-grade fault lines, with fermentation-derived pharmaceutical tiers commanding premium positioning against olive-origin cosmetic supply. Consolidation concentrates around industrial-scale bioreactor networks and molecular distillation retrofit investments. Strategic archetypes separate precision fermentation platform operators from agricultural extraction specialists. Competitive moves center on dual-sourcing partnerships and direct-to-brand contract structures bypassing traditional distributors.
Within the biotechnology tier, Amyris exemplifies engineered yeast strain production at Brazilian industrial scale, while Croda International Plc occupies a position spanning both fermentation and oleochemical routes. Among Mediterranean specialists, Sophim anchors French supply chains through olive-origin molecular distillation. These three entities represent the dominant strategic configurations: captive biorefinery platforms, hybrid technology portfolios, and regional agricultural extraction networks.
| Leading Market Players |
|---|
| Amyris |
| Sophim |
| Croda International Plc |
| Evonik |
| Clariant |
| Nucelis |
| Jedwards International |
| EPF Biotek |
| Henry Lamotte Oils GmbH |
| Others |
Pricing and Supply Chain Analysis
Barcelona-Valencia freight corridors transmit cost volatility from Mediterranean olive crushing clusters to downstream cosmetic formulators, compressing margins at deodorizer distillate refineries while amplifying price spreads between pharmaceutical-grade fermentation output and mid-tier botanical grades.
Pricing Analysis
REACH substance registration dictates the pricing tier structure for plant-derived squalene across European markets. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades separates sugarcane-derived excipient purity from olive-origin emollient consistency. Cost compression in mid-tier cosmetic supply is intensifying because olive oil commodity cycles squeeze refinery margins during poor harvests. Mass-market personal care manufacturers exhibit highest price sensitivity, while pharmaceutical lipid excipient buyers prioritize oxidation stability over unit economics.
Supply Chain Analysis
Tariff exposure between Brazil and European Union markets dominates supply chain risk calculus for fermentation-derived grades. Production gravity centers on Brazilian industrial corridors for sugarcane biorefineries and Mediterranean Spain-Italy networks for olive-origin extraction. Engineered yeast strains, deodorizer distillate feedstock, and molecular distillation equipment anchor raw material dependencies. Distribution runs through specialized oleochemical distributors and direct-to-brand contracts bypassing traditional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against petrochemical squalane substitution as REACH compliance costs erode synthetic route competitiveness. Shark liver oil and synthetic alternatives retain cost advantages that delay feedstock transitions in mass-market segments.
For Market Incumbents: Build regulatory moats through REACH dossier completion for novel sugarcane-derived grades before competitor submission windows close. Amyris precision fermentation infrastructure demonstrates how captive biorefinery platforms neutralize olive harvest volatility. Dual-sourcing partnerships across Brazilian fermentation and Mediterranean extraction hedge geographic concentration risk. Certification investment in mass-balance documentation captures premium positioning from French and South Korean retailer sustainability mandates. For New Entrants and Emerging Players: Mid-market cosmetic formulators in Southeast Asia represent the most penetrable entry point for olive-origin material seeking alternative supply sources. Amaranth-derived allergen-free positioning offers white-space differentiation without competing against established Mediterranean crushing infrastructure. Direct-to-brand supply contracts bypassing traditional oleochemical distributors enable margin capture through chain-of-custody verification. Technical service bundling with stability-testing support builds supplier stickiness against incumbent technical documentation advantages. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized molecular distillation capacity in olive-growing regions. Long-term viability hinges on biotechnology scale-up timelines versus agricultural yield volatility across the projection horizon. Precision fermentation platform operators with engineered yeast strain IP command premium multiples against commodity extraction plays. Watch EMA stability guideline revisions for pharmaceutical-grade specifications as inflection indicators for feedstock platform winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive sugarcane biorefinery or olive crushing control secures margin capture against commodity volatility. |
| Pharmaceutical Excipient Qualification | EMA stability guideline compliance opens mRNA vaccine adjuvant carrier specifications for fermentation-derived grades. |
| Direct-to-Brand Contract Structures | Mass-balance certification and carbon intensity scoring enable premium positioning with French clean-label formulators. |
| Precision Fermentation Scale-Up | Engineered yeast strain production in Brazilian industrial corridors virtualizes geographic concentration risk from Mediterranean harvests. |
| REACH Dossier Completion | Full substance registration for novel botanical grades demands toxicological study investment before market access. |
Research Methodology
A spread of perspectives from cosmetic formulation chemists, pharmaceutical excipient procurement managers, olive refinery operations directors, and biotechnology process engineers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs trade data, ECHA substance registration databases, SEC filings from listed chemical conglomerates, and ANVISA pharmaceutical excipient pathway documentation. Bottom-up volume modeling across feedstock platforms triangulated against top-down market sizing from end-use consumption patterns.
Demand-supply balance dynamics anchored the analytical framework across the analysis window. Segmentation dimensions modeled include purity grade tier, end-use application, feedstock origin, and regional regulatory cluster. CAGRs derived from trajectory analysis of historical feedstock price elasticities and qualification timeline compressions. Industry-specific forecast inputs incorporated olive oil commodity cycle patterns and precision fermentation batch yield improvement curves.
Practitioners should monitor EMA guideline revisions, EU F-Gas Regulation enforcement intensity, and Brazilian real currency volatility for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Black Soldier Fly (BSF) Market
Alternative Food Sources
Egg Replacers Market
Alternative Food Sources
Upcycled Food Products Market
Alternative Food Sources
Vegetable Proteins Market
Alternative Food Sources
North America Fat Replacers Market
Alternative Food Sources
Insect Snacks Market
Alternative Food Sources
North America Insect Protein Market
Alternative Food Sources
Flour Substitutes Market
Alternative Food Sources
Algae Oil Market
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
Insect-Based Pet Food Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
Middle East and Africa Edible Insects Market
Alternative Food Sources
Quinoa Protein Market
Alternative Food Sources
Vegan Eggs Market
Alternative Food Sources
Bioengineered Food Market