
 Precision Fermentation Market | 2026-2036
Precision Fermentation Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Fermentation Market Outlook
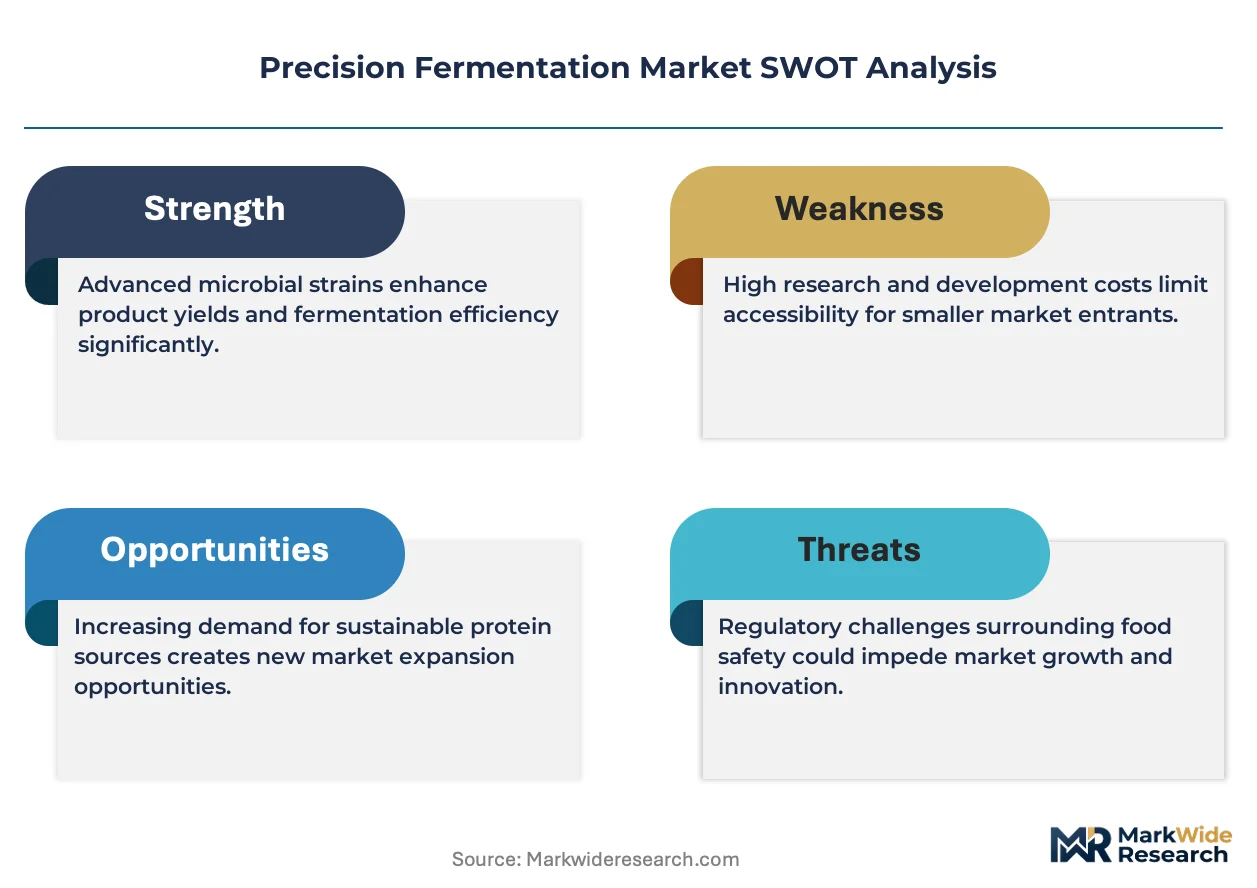
Modular bioreactor configurations is realigning how food manufacturers evaluate capital deployment, shifting procurement from monolithic stainless-steel installations toward skid-mounted, expandable fermentation trains. Perfect Day, Inc. leverages its integrated strain development and downstream processing infrastructure to control quality across whey protein production. Geltor anchors its position through specialized collagen protein platforms targeting cosmetic and nutraceutical offtake. Impossible Foods sustains competitive intensity by operating precision fermentation capacity in parallel with its broader protein texturization operations.
Precision fermentation deploys genetically optimized microbial hosts in controlled bioreactor environments to synthesize target proteins, lipids, or bioactive compounds, with titers, yield coefficients, and downstream recovery rates serving as core performance parameters; the process displaces conventional agricultural extraction for high-value ingredients in food, pharmaceutical, and materials applications. Enzyme production dominates current revenue pools due to established unit economics and broad industrial offtake, while biomass applications for alternative proteins represent the fastest-expanding segment as food manufacturers reformulate toward animal-free supply chains. Fermentation systems capture the largest share of technology spending, though downstream processing is emerging as the critical bottleneck where margin compression concentrates.
The U.S. FDA's Generally Recognized as Safe notification pathway and the EU's Novel Food Regulation frame market access requirements, with EFSA scientific opinions determining approval timelines for precision-fermented ingredients entering European food supply chains. The USDA oversees labeling standards that influence how finished products communicate fermentation-derived status to consumers, shaping brand positioning and retail acceptance. Stakeholders must monitor regulatory divergence between jurisdictions as a primary determinant of geographic rollout sequencing and partnership structures.
Market Dynamics
Modular bioreactor configurations are forcing food manufacturers to abandon monolithic stainless-steel installations in favor of skid-mounted, expandable fermentation trains that reduce capital lock-in and accelerate scale-up timelines.
Growth Catalysts
- EU Novel Food Regulation:The EFSA scientific opinion framework provides a structured pathway for precision-fermented ingredients to enter European food supply chains, accelerating commercial rollout timelines for compliant producers.
- Dairy alternatives sector:Consumer preferences shifting toward animal-free nutrition are pulling food manufacturers toward reformulation with precision-fermented proteins as core functional ingredients.
- Venture-backed biotech clusters:Concentrated capital deployment in California and New York is compressing the timeline between strain development and commercial-scale protein production.
Market Restraints
- Downstream processing bottlenecks:Recovery rate limitations in membrane filtration and chromatography steps concentrate margin compression at the purification stage, constraining unit economics.
- Input cost volatility:Fluctuations in pharmaceutical-grade glucose and nitrogen source pricing directly impact fermentation media costs, destabilizing production forecasts.
- Regulatory divergence:Misalignment between FDA's GRAS notification pathway and EFSA's pre-market authorization requirements forces parallel compliance investments, extending geographic rollout sequencing.
Strategic Opportunities
- Cosmetic and nutraceutical offtake:Collagen protein platforms targeting non-food applications unlock premium pricing outside commodity food ingredient markets.
- Biomass fermentation for alternative proteins:Whole-cell biomass applications remain underpenetrated relative to purified protein isolates, offering whitespace for mycoprotein and single-cell protein expansion.
- USDA labeling standards evolution:Emerging clarity on how fermentation-derived status must be communicated to consumers creates first-mover advantage in brand positioning and retail acceptance.
Industry Challenges
- Strain engineering talent scarcity:Competition for microbial geneticists and metabolic pathway designers with synthetic biology expertise outpaces academic pipeline output.
- Capex intensity for GMP infrastructure:Commercial-scale bioreactor installations with integrated clean-in-place systems demand substantial upfront investment before revenue generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Fermentation Market |
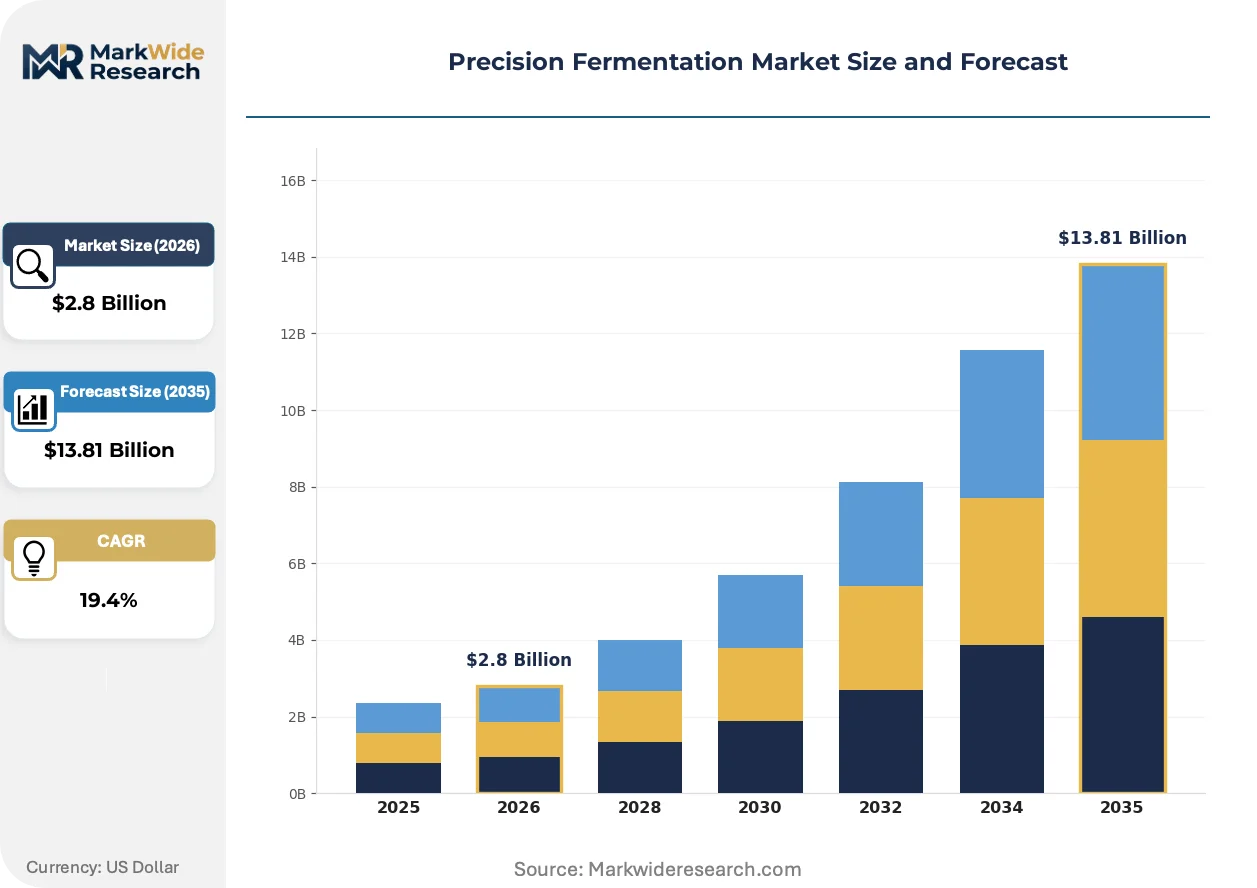
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13.81 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Strains, Enzymes, Biomass, Intermediate Products Application: Food & Beverages, Nutraceuticals, Animal Feed, Bioplastics Technology: Fermentation Systems, Downstream Processing, Bioinformatics, Starter Cultures End User: Food Manufacturers, Pharmaceutical Companies, Research Institutions, Chemical Producers |
| Companies Covered | Perfect Day, Inc., Geltor, Impossible Foods, Imagindairy, Change Foods, Remilk, The Every Company, Formo, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Fermentation Market Strategic Shifts
Continuous processing architectures and AI-driven bioprocess optimization are compressing development cycles and enabling real-time quality control across precision fermentation operations.
Single-use bioreactor systems with integrated sensors and automated feedback loops are electrifying how manufacturers approach batch-to-batch consistency. Mid-scale food ingredient producers are adopting these platforms at accelerating pace to reduce cross-contamination risk between product changeovers. The technology is electrifying competitive positioning by lowering the capital threshold for market entry and enabling faster strain-to-product transitions.
The EU's F-Gas Regulation is restricting hydrofluorocarbon use in industrial cooling systems, forcing fermentation facility operators to retrofit or specify low-global-warming-potential refrigeration alternatives. This industrial consequence elevates capital planning complexity for new biomanufacturing sites across member states. Cold-chain-dependent precision fermentation operations in Germany and the Netherlands are responding by front-loading heat recovery and alternative cooling infrastructure into facility designs.
Direct procurement relationships between food manufacturers and strain developers are displacing traditional ingredient distributor intermediaries, compressing margin extraction layers in the supply chain. Large CPG buyers are establishing captive supply agreements with biotech platforms to secure volume allocations and co-development rights. This pattern is most visible in the United States, where venture-backed precision fermentation startups are structuring multi-year offtake contracts with national dairy alternative brands.
Precision Fermentation Market Segmentation
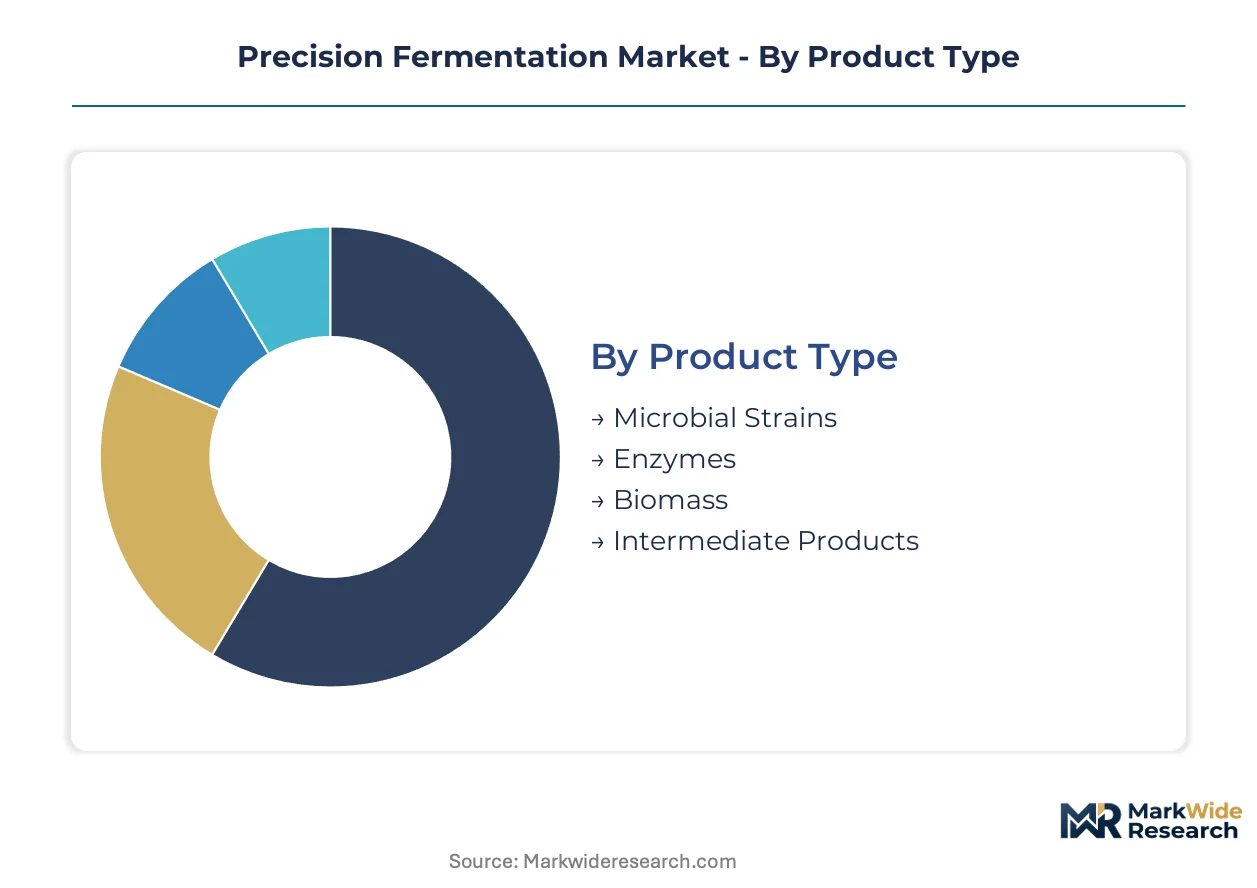
Precision fermentation markets fragment across four critical dimensions that determine procurement patterns, technology deployment, and margin capture. Buyers prioritize different performance specifications depending on whether they seek purified isolates, whole-cell ingredients, or process intermediates.
Product Type:
Cost tiers separate commodity biomass from high-purity enzymes and specialized microbial strains.
- Enzymes:These catalytic proteins command premium pricing due to established unit economics and broad industrial offtake across food processing and textile applications. Dairy alternative manufacturers in the United States source precision-fermented proteases and lipases to achieve functional parity with animal-derived ingredients.
- Biomass:Whole-cell microbial protein delivers lower per-kilogram costs but requires downstream formulation expertise to achieve consumer-acceptable texture and flavor profiles. Mycoprotein producers in Germany and the Netherlands are scaling biomass fermentation to supply European meat alternative brands seeking clean-label positioning.
- Microbial Strains:Genetically optimized host organisms with engineered metabolic pathways for target molecule production.
- Intermediate Products:Partially purified fermentation outputs requiring further processing before commercial application.
Volume sits with biomass applications; growth tilts toward enzymes as food manufacturers reformulate toward animal-free supply chains.
Application:
End-use specifications vary dramatically between ingestible products and industrial material inputs.
- Food & Beverages:Whey and casein protein alternatives dominate procurement volumes, with Perfect Day's precision-fermented dairy proteins supplying ice cream and cheese analog manufacturers. FDA GRAS notifications and EFSA Novel Food approvals frame geographic rollout sequencing for ingredient suppliers.
- Nutraceuticals:Collagen and bioactive peptide platforms target premium pricing outside commodity markets, with Geltor's marine collagen alternatives supplying cosmetic and supplement brands.
- Animal Feed:Single-cell protein applications for aquaculture and livestock nutrition remain underpenetrated relative to food-grade alternatives.
- Bioplastics:Fermentation-derived PHA and PLA precursors serve packaging manufacturers seeking petroleum-free feedstocks.
Maturity concentrates in food and beverages; nutraceuticals are climbing the fastest as cosmetic brands diversify protein sourcing.
Technology:
Capital deployment intensity separates hardware infrastructure from software and biological inputs.
- Fermentation Systems:Bioreactor hardware captures the largest share of technology spending, with modular skid-mounted configurations displacing monolithic stainless-steel installations. California and New York venture-backed clusters are driving commercial scale-up of microbial protein production capacity.
- Downstream Processing:Membrane filtration and chromatography steps concentrate margin compression, with recovery rate limitations constraining unit economics for purified protein isolates.
- Bioinformatics:AI-driven strain optimization platforms compress development cycles and enable real-time quality control across operations.
- Starter Cultures:Proprietary microbial inoculants with optimized growth characteristics for specific target molecules.
Hardware investment dominates current procurement; downstream processing represents the steepest expansion trajectory as purification bottlenecks constrain margin capture.
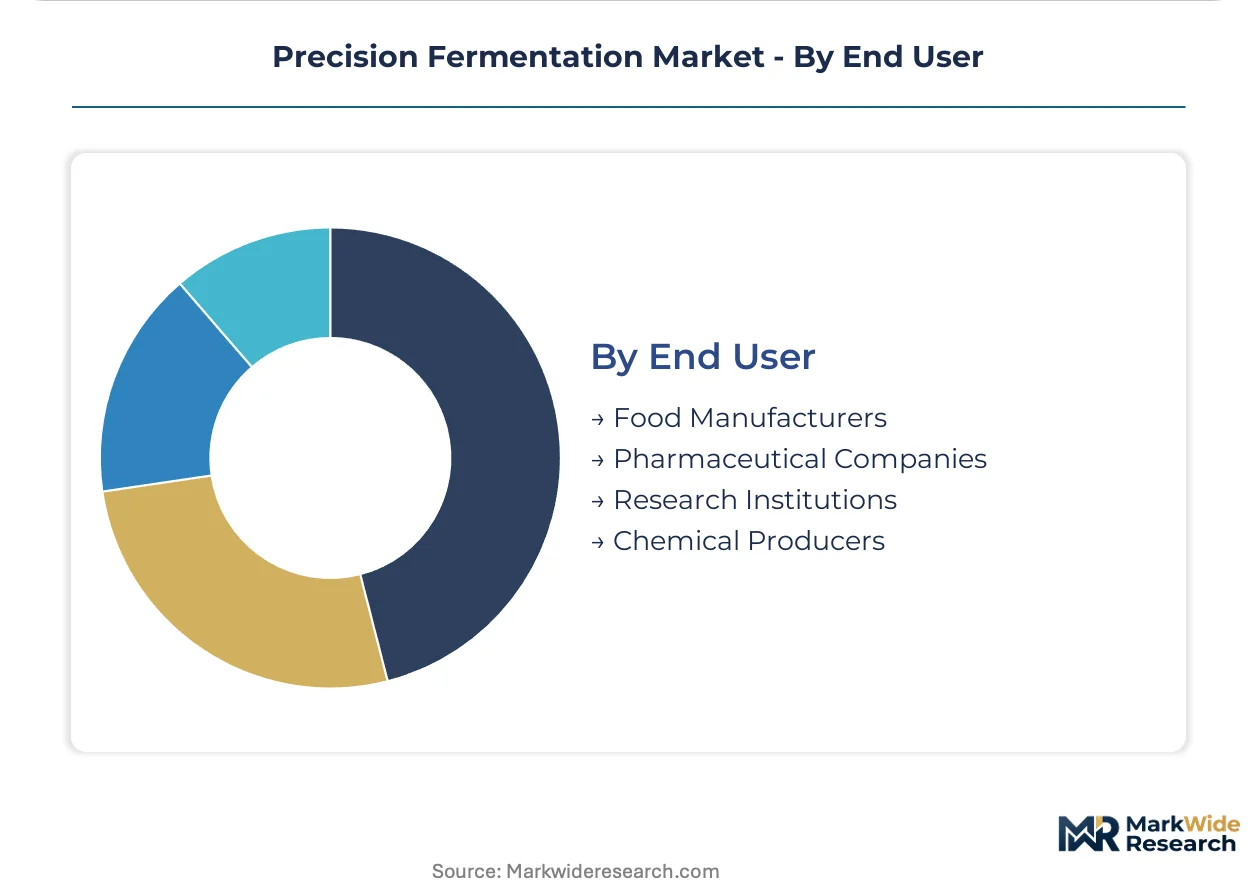
End User:
Regulatory sophistication and volume scale distinguish mass-market food producers from specialized chemical and pharmaceutical buyers.
- Food Manufacturers:Large CPG buyers establish captive supply agreements with biotech platforms to secure volume allocations and co-development rights. Direct procurement relationships are displacing traditional ingredient distributor intermediaries in the United States.
- Pharmaceutical Companies:GMP-compliant fermentation capacity serves therapeutic protein and vaccine adjuvant production, with capex intensity for clean-in-place systems demanding substantial upfront investment.
- Research Institutions:Academic and government laboratories license strain development platforms for foundational metabolic engineering research.
- Chemical Producers:Industrial biotechnology applications leverage fermentation for specialty chemical precursors and polymer building blocks.
Procurement volume clusters with food manufacturers; pharmaceutical engagement is gaining share fastest as GMP infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in venture-backed biotech clusters while consumption spreads across food manufacturing centers. The United States generates the largest procurement volumes for precision-fermented dairy alternatives. European regulatory frameworks shape approval sequencing for novel ingredients entering commercial supply chains.
United States
Venture capital deployment in California and New York accelerates strain-to-commercial timelines for microbial protein production. The FDA's Generally Recognized as Safe notification pathway provides a structured compliance framework for novel food ingredients. San Francisco Bay Area biotech clusters host integrated strain development and downstream processing infrastructure serving national dairy alternative brands.
Germany
Food manufacturers reformulate toward animal-free nutrition, pulling demand for precision-fermented functional ingredients. The EU's F-Gas Regulation restricts hydrofluorocarbon use in industrial cooling systems, forcing fermentation facility retrofits. Cold-chain-dependent operations in North Rhine-Westphalia front-load heat recovery infrastructure into new biomanufacturing site designs.
Netherlands
Mycoprotein producers scale biomass fermentation to supply European meat alternative brands seeking clean-label positioning. EFSA scientific opinions determine approval timelines for precision-fermented ingredients entering food supply chains. Rotterdam-area fermentation facilities respond to F-Gas restrictions by specifying low-global-warming-potential refrigeration alternatives in capital planning.
United Kingdom
Large CPG buyers establish captive supply agreements with biotech platforms to secure volume allocations and co-development rights. The Food Standards Agency implements the retained EU Novel Food Regulation framework post-Brexit, maintaining parallel compliance requirements. Greater London serves as a procurement hub for direct relationships between food manufacturers and strain developers displacing traditional distributors.
Israel
Specialized collagen protein platforms target premium pricing in cosmetic and nutraceutical applications outside commodity food markets. The Ministry of Health's novel food safety assessments align with EFSA scientific opinion structures for export-oriented producers. Tel Aviv-area biotech startups structure multi-year offtake contracts with international nutraceutical brands seeking fermentation-derived bioactive peptides.
Precision Fermentation Market Competitive Environment
The competitive structure tilts toward technology-integrated platforms with captive strain development capabilities. Player concentration splits between venture-backed specialists controlling proprietary microbial hosts and diversified ingredient suppliers extending into fermentation-derived inputs. Two strategic archetypes dominate: integrated biotech platforms managing end-to-end production, and ingredient distributors securing volume allocations through partnership structures. Capacity expansion and direct procurement relationships constitute the dominant competitive moves as margin compression in downstream processing intensifies.
Within the integrated platform tier, Perfect Day, Inc. and Geltor exemplify archetypes of strain-development-to-product companies. Impossible Foods occupies a position spanning precision fermentation capacity and broader protein texturization operations. These three entities represent distinct positioning vectors: dairy protein alternatives, specialized collagen platforms, and parallel fermentation-texturization integration.
| Leading Market Players |
|---|
| Perfect Day, Inc. |
| Geltor |
| Impossible Foods |
| Imagindairy |
| Change Foods |
| Remilk |
| The Every Company |
| Formo |
| Cargill |
| Others |
Value Chain & Pricing Dynamics
Large CPG buyers consolidating procurement around direct strain-developer relationships are forcing ingredient distributors to compress margin extraction layers, elevating pricing power for integrated biotech platforms with captive production capacity.
Pricing Analysis
Margin tightening in purified protein isolates reflects recovery rate limitations in downstream membrane filtration and chromatography steps. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified pharmaceutical-grade outputs from food-grade ingredients and commodity biomass applications. Cost-down pressure on food-grade whey and casein alternatives accelerates because dairy alternative manufacturers prioritize functional parity over purity premiums. Pharmaceutical buyers exhibit lowest price sensitivity due to regulatory compliance requirements, while animal feed formulators drive hardest bargain negotiations on per-kilogram biomass contracts.
Supply Chain Analysis
Pharmaceutical-grade glucose and nitrogen source supply rests on German and Dutch specialty chemical producers, with fermentation media formulation expertise concentrating in California and New York venture-backed clusters. Critical inputs include genetically optimized microbial host strains, single-use bioreactor consumables, and chromatography resins for downstream purification. Single-source vulnerability in strain development talent pools threatens production timelines as competition for microbial geneticists outpaces academic pipeline output. Distribution runs through direct captive supply agreements between food manufacturers and biotech platforms, displacing traditional ingredient distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation stands at a technology-transition inflection where AI-driven bioprocess optimization and continuous processing architectures are displacing legacy batch fermentation systems.
For Market Incumbents: Extend strain development capabilities through backward integration into proprietary microbial host platforms before emerging biotech startups lock up CRISPR-edited chassis organisms. Defend margin position by adding GMP-compliant capacity in the United States ahead of FDA enforcement trends on novel food ingredients. Secure captive supply agreements with national dairy alternative brands to preempt distributor displacement. For New Entrants and Emerging Players: Digital-channel direct procurement platforms offer route to bypass established ingredient distributor networks and capture margin extraction layers. Biomass fermentation for aquaculture feed applications represents most penetrable whitespace relative to saturated food-grade protein markets. Lead with sustainability positioning and clean-label credentials to differentiate against incumbent commodity suppliers. For Investors and Strategic Acquirers: The window for entry favors integrated platforms with end-to-end strain-to-product capabilities rather than pure-play downstream processors. Long-term viability hinges on securing proprietary microbial hosts and GMP infrastructure before regulatory compliance costs escalate. Watch EFSA scientific opinion timelines as inflection indicator for European market access sequencing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | Captive microbial host platforms reduce licensing costs and accelerate product pipelines for dairy protein alternatives. |
| GMP Infrastructure Expansion | FDA-compliant clean-in-place systems unlock pharmaceutical-grade pricing tiers and therapeutic protein adjacencies. |
| Direct Procurement Platform Launch | Bypassing distributor intermediaries captures margin extraction layers and deepens buyer relationships for volume allocation. |
| Continuous Processing Architecture Deployment | Real-time quality control and AI-driven bioprocess optimization compress development cycles against batch fermentation incumbents. |
| Multi-year Offtake Contract Structuring | Captive supply agreements with national CPG brands secure revenue visibility and co-development rights for novel ingredients. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across strain development executives, fermentation facility operators, CPG procurement directors, and downstream processing engineers. FDA GRAS notifications, EFSA scientific opinions, and USDA labeling guidance provided regulatory trajectory validation. Bottom-up capacity modeling across California and New York biotech clusters triangulated against top-down ingredient demand projections from dairy alternative manufacturers.
Granularity-level modeling operated at product type, application, technology, and end-user dimensions, with additional segmentation by regulatory jurisdiction given divergence between FDA and EFSA pathways. CAGRs derived from volume-demand elasticity analysis against capacity expansion timelines across the analysis window. Strain engineering productivity curves and downstream recovery rate assumptions shaped purified isolate pricing trajectories.
The model holds under stable regulatory approval timelines and continued venture capital deployment; deviation in EFSA scientific opinion delays or glucose feedstock price spikes would shift capacity expansion sequencing. Forecasts reflect documented assumptions on titer improvement rates and consumer acceptance curves for fermentation-derived labels. A small set of named triggers—regulatory divergence intensity, strain engineering talent availability, and F-Gas refrigeration retrofit costs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Meat Analogue Market
Alternative Food Sources
Konjac Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Algae Oil Market
Alternative Food Sources
Single Cell Oil Market
Alternative Food Sources
Algal Protein Market
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
North America Fat Replacers Market
Alternative Food Sources
Vegetable Proteins Market
Alternative Food Sources
Carragean Alternatives Market
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
Feather Meal Market
Alternative Food Sources
Low Carbs Vegan Food Market
Alternative Food Sources
Spirulina Market
Alternative Food Sources
Artificial Meat Market
Alternative Food Sources
Mock Meat Market