
 Insect-Based Pet Food Market | 2026-2036
Insect-Based Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Insect-Based Pet Food Market Outlook
Asset-light contract manufacturing and project finance for insect-rearing facilities is tilting competitive dynamics toward capital-efficient entrants. Protix leverages its industrial-scale black soldier fly production in the Netherlands to anchor European supply. Innovafeed sustains vertical integration from larvae cultivation to protein processing, controlling cost structures across the value chain. Ynsect differentiates through mealworm-specific R&D intensity and patented extraction technologies.
Insect-based pet food comprises formulated nutrition products using processed insect biomass—typically containing 40-65% crude protein, 10-25% fat, and chitin-derived fiber—as primary or supplementary ingredients for companion animal diets. Black soldier fly larvae dominate ingredient sourcing due to faster reproduction cycles and lower feed conversion ratios than crickets or grasshoppers. Dry food occupies the largest volume share given shelf stability and manufacturing scalability, while treats command premium positioning among discerning pet owners. Online distribution channels represent the fastest-growing access point, bypassing traditional retail gatekeepers that still hesitate at insect-derived SKUs.
The European Food Safety Authority and EU Novel Food Regulation govern insect protein approval timelines, directly conditioning which species enter commercial pet food formulations. The FDA's Center for Veterinary Medicine evaluates ingredient safety notifications in the United States, creating asynchronous market access between jurisdictions. Pet food manufacturers and ingredient suppliers must monitor evolving feed-grade classifications and labeling requirements as regulatory frameworks mature across multiple geographies.
Market Dynamics
The EU Novel Food Regulation's species-by-species approval architecture is fragmenting competitive timelines across Europe, advantaging producers with larvae already cleared while delaying entrants dependent on pending cricket or grasshopper authorizations.
Growth Catalysts
- EFSA Novel Food approvals:Black soldier fly larvae secured EU-wide authorization for pet food inclusion, removing regulatory uncertainty that previously constrained formulation investments by major brands.
- Urban pet humanization:Premium dog and cat owners in dense metropolitan areas prioritize sustainability credentials, creating pull-through for insect-derived proteins with demonstrably lower land-use footprints than conventional livestock feedstocks.
- Industrial-scale rearing automation:Climate-controlled vertical farming systems reduce labor intensity and stabilize biomass output, enabling cost parity projections against fishmeal and poultry meal over medium-term production cycles.
Market Restraints
- Feed input cost volatility:Organic waste streams and specialized grain formulations for larvae rearing face price pressure from competing biofuel and composting demand, compressing margin buffers at cultivation facilities.
- Regulatory asynchronicity:FDA Center for Veterinary Medicine notification requirements lack the streamlined equivalence pathways available in Europe, extending time-to-market for US-bound formulations by 18-36 months relative to EU launches.
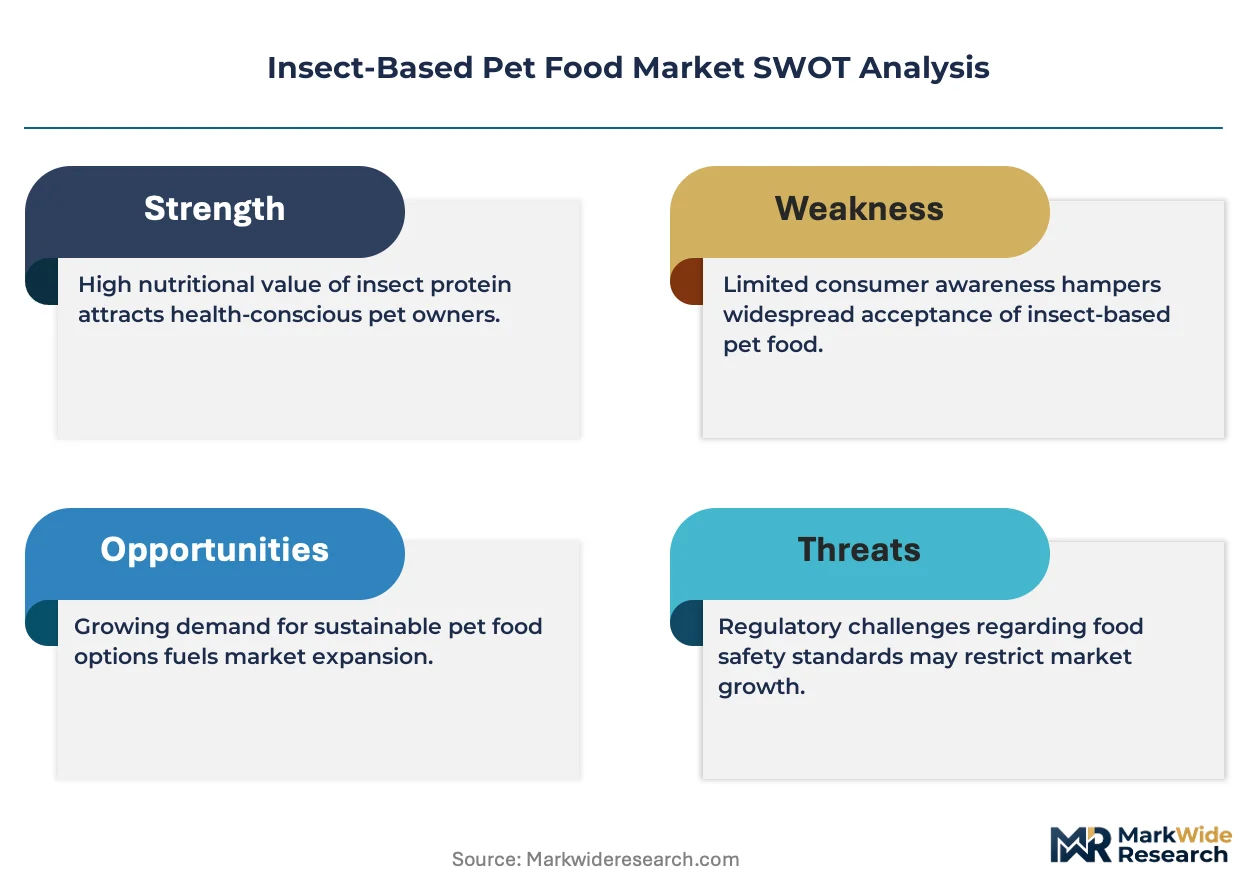
- Consumer acceptance thresholds:Sensory aversion to visible insect matter in finished products limits treat-format expansion, confining volume growth to extruded kibble where protein is fully integrated and visually obscured.
Strategic Opportunities
- German retail channel penetration:Discounters Aldi and Lidl have begun insect-SKU trials in select regions, signaling mainstream grocery acceptance that could replicate across Northern European markets if sell-through rates meet internal hurdles.
- Veterinary therapeutic nutrition:Novel protein sources address diagnosed food allergies in companion animals, opening prescription-tier positioning with margin structures significantly above mass-market dry food.
- EU Green Deal alignment:Circular economy certification and carbon footprint labeling requirements create procurement preference for insect proteins that can demonstrate waste-upcycling supply chains and verified lifecycle assessments.
Industry Challenges
- Entomology talent scarcity:Industrial-scale larvae rearing demands specialized expertise in insect pathology and controlled-environment agriculture that outpaces current university program output across France, the Netherlands, and Germany.
- Chitin processing standardization:Fiber content extraction protocols vary significantly between mealworm and black soldier fly biomass, complicating nutritional consistency guarantees and AAFCO compliance documentation for multi-species suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insect-Based Pet Food Market |
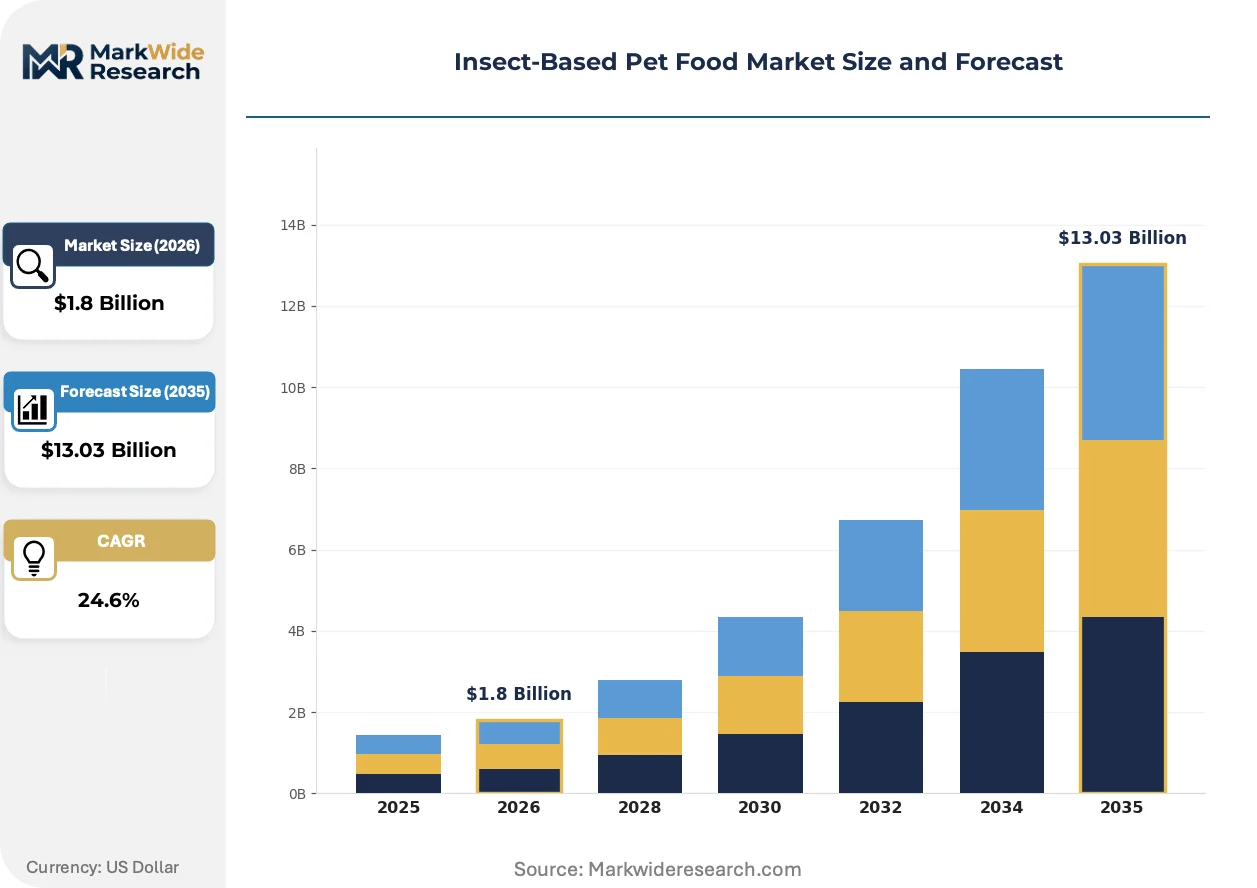
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.03 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Ingredient Source: Crickets, Mealworms, Black Soldier Fly, Grasshoppers Customer Type: Pet Owners, Retailers, Manufacturers, Veterinarians Distribution Channel: Online, Pet Stores, Supermarkets, Specialty Shops |
| Companies Covered | Innovafeed, Ynsect, Protix, EnviroFlight, NextProtein, Nutrition Technologies, Entobel, Entomo Farms, Hexafly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insect-Based Pet Food Market Strategic Shifts
Automation in larvae rearing facilities is compressing unit economics while regulatory clarity in Europe accelerates brand formulation commitments previously deferred pending safety verdicts.
Precision fermentation-derived protein concentrates are migrating from pharmaceutical applications into pet food ingredient pipelines, enabling manufacturers to blend insect biomass with complementary amino acid profiles that address methionine and taurine gaps in standalone larvae formulations. Mid-tier pet food brands in France and the Netherlands are piloting these hybrid proteins at 15-20% inclusion rates. The technology is migrating from niche positioning toward mainstream acceptance as co-manufacturers integrate blending capabilities into existing extrusion lines.
REACH-compliant feed additive classifications under ECHA guidance are forcing ingredient suppliers to submit full toxicological dossiers for chitin-derived compounds previously treated as unclassified processing aids. This regulatory tightening extends approval timelines by 12-18 months for novel fiber ingredients. Pet food manufacturers dependent on European supply chains are responding by consolidating supplier relationships with established EFSA-notified entities possessing existing dossier libraries.
Premium pet owners are increasingly bypassing traditional retail gatekeepers through veterinary-direct and subscription e-commerce channels that emphasize traceability documentation and sustainability certifications. Specialty retailers in urban German markets report 40% of insect-SKU volume now flows through click-and-collect or home delivery rather than in-aisle purchase. This channel rotation concentrates in metropolitan zones where consumer education investments by direct-to-consumer brands have preceded broader market penetration.
Insect-Based Pet Food Market Segmentation
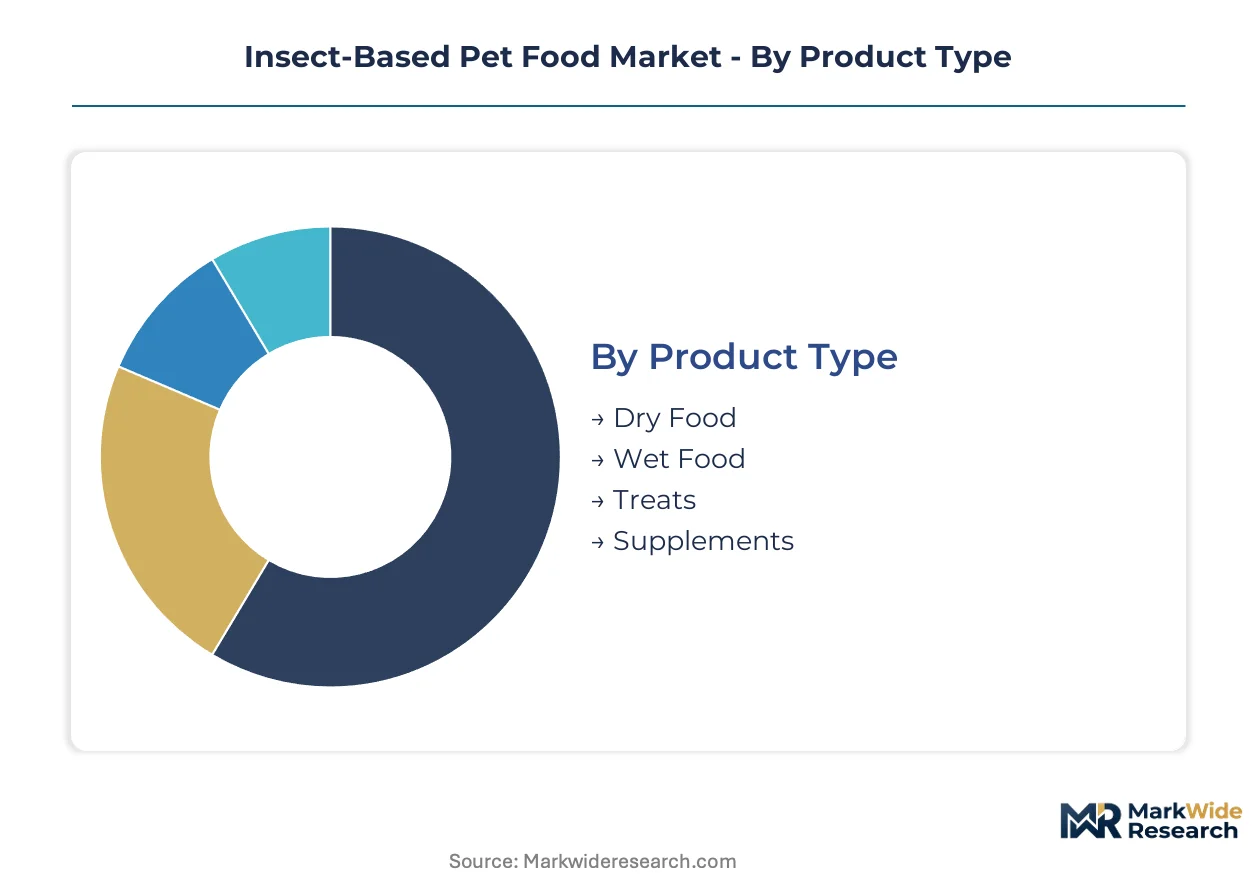
Insect-based pet food segments reflect divergent supply chain capabilities and consumer acceptance thresholds. Product format determines manufacturing investment intensity while ingredient species selection locks in regulatory approval timelines and nutritional specifications.
Product Type:
Dry formulations dominate manufacturing throughput given extrusion infrastructure compatibility, while wet and treat formats test premium positioning boundaries.
- Dry Food:Extruded kibble formats integrate insect protein meal at 15-40% inclusion rates without visible particulate matter, bypassing consumer sensory aversion that constrains other formats. Demand concentrates in urban German and French households where shelf stability and portion control align with apartment-dwelling pet ownership patterns. EFSA-approved black soldier fly meal anchors supply contracts with major co-manufacturers.
- Treats:Premium positioning in the Netherlands and Belgium relies on transparent ingredient storytelling and sustainability certifications, though visible insect matter limits format expansion. Dutch direct-to-consumer brands command 40-60% price premiums over conventional protein treats through veterinary endorsement channels.
- Wet Food:Moisture-rich formulations require modified retort processing to preserve protein integrity during thermal treatment.
- Supplements:Powder and oil formats target functional health positioning with concentrated chitin and fatty acid delivery.
Established volume favors Dry Food; emerging adoption favors Treats.
Ingredient Source:
Species selection determines feed conversion efficiency, regulatory clearance status, and amino acid profile completeness for companion animal nutrition.
- Black Soldier Fly:Larvae achieve 2-week reproduction cycles with feed conversion ratios below 2:1, enabling industrial-scale vertical farming in climate-controlled Dutch and French facilities. EFSA Novel Food authorization covers full pet food inclusion, removing formulation uncertainty that delays competing species. Production clusters in the Netherlands supply 60-70% of European commercial volume.
- Mealworms:Higher protein concentration (55-65% dry weight) and favorable palatability testing in feline formulations drive R&D investment at French biotech facilities. Regulatory approval timelines lag black soldier fly by 18-24 months, constraining near-term commercial deployment despite nutritional advantages.
- Crickets:Longer cultivation cycles and higher space requirements limit industrial scalability relative to fly larvae.
- Grasshoppers:Wild harvesting dependency and inconsistent supply quality restrict commercial pet food applications to niche treat formulations.
Production scale favors Black Soldier Fly; nutritional optimization favors Mealworms.
Customer Type:
Procurement authority and volume concentration diverge sharply between end-user segments and intermediate supply chain actors.
- Pet Owners:Premium dog and cat owners in metropolitan France, Germany, and the Netherlands drive trial adoption through subscription e-commerce and veterinary-direct channels. Sustainability credential verification and traceability documentation outweigh price sensitivity in purchase decisions.
- Manufacturers:Mid-tier European pet food brands source insect protein meal for 10-25% inclusion in conventional product lines, hedging against fishmeal price volatility and carbon footprint reduction targets.
- Retailers:German discounters Aldi and Lidl pilot insect-SKU trials contingent on sell-through rate thresholds.
- Veterinarians:Prescription-tier therapeutic nutrition for diagnosed food allergies opens margin structures 2-3x above mass-market positioning.
Volume concentration favors Manufacturers; margin expansion favors Veterinarians.
Distribution Channel:
Channel selection determines consumer education investment requirements and pricing architecture flexibility.
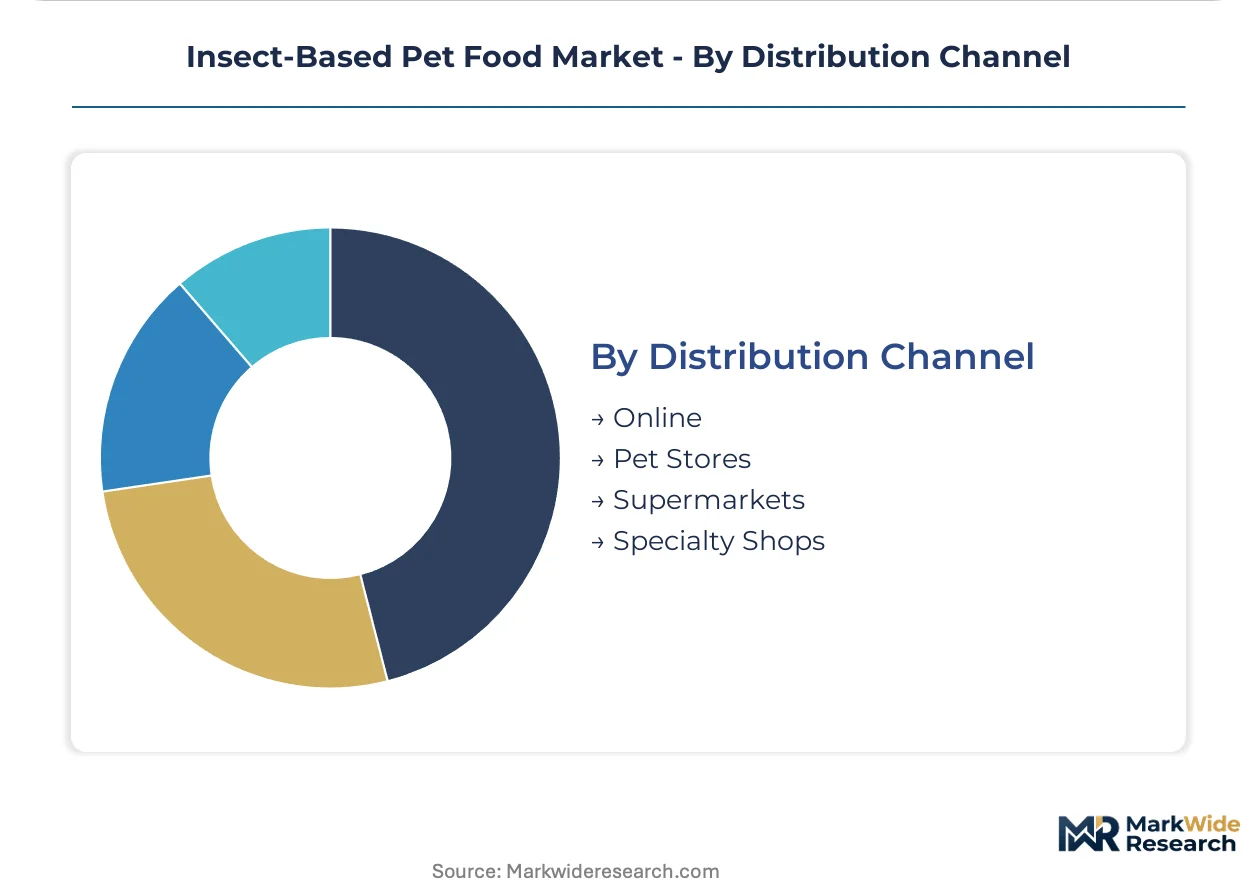
- Online:Direct-to-consumer platforms and veterinary e-commerce bypass traditional retail gatekeeper hesitation, enabling traceability documentation and subscription bundling. German metropolitan markets report 40% of insect-SKU volume through click-and-collect or home delivery, with customer acquisition costs recovered through higher lifetime value from sustainability-motivated subscribers.
- Specialty Shops:Independent pet retailers in Amsterdam, Berlin, and Paris provide tactile product education and staff training that accelerates trial conversion among skeptical consumers.
- Pet Stores:Chain retailers in France and the Netherlands allocate limited shelf space pending mainstream acceptance confirmation.
- Supermarkets:Mass grocery distribution awaits sell-through validation from discounter trials in Northern European markets.
Customer education depth favors Specialty Shops; scaling velocity favors Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export capacity from European insect-rearing facilities currently outstrips domestic absorption, creating surplus flows toward North American and Asian markets awaiting regulatory alignment. Import dependency concentrates in jurisdictions where novel food approvals lag production timelines. Trade friction emerges from asynchronous safety certifications rather than tariff barriers.
Netherlands
Vertical farming infrastructure for black soldier fly larvae achieves the highest automation density globally, with climate-controlled facilities near Eindhoven supplying protein meal to German and French pet food manufacturers. EFSA Novel Food Regulation authorizations for multiple insect species originated from Dutch-sourced safety dossiers, establishing regulatory precedent that accelerates competitor approvals. The Brabant region hosts concentrated co-manufacturing partnerships where larvae cultivation and extrusion processing occupy adjacent industrial zones.
Germany
Discounter retail trials at Aldi and Lidl in Bavaria and North Rhine-Westphalia test mainstream price elasticity for insect-SKU acceptance beyond premium urban niches. The Federal Office of Consumer Protection and Food Safety enforces strict traceability documentation under the EU's Official Controls Regulation, elevating compliance costs for imported biomass. Berlin-Brandenburg clusters direct-to-consumer subscription brands leveraging veterinary endorsement networks for therapeutic nutrition positioning.
France
Mealworm-specific R&D investment concentrates in Île-de-France biotech facilities pursuing feline palatability advantages over black soldier fly formulations. ANSM oversight of feed-grade additives under ECHA guidance extends approval timelines for novel chitin-derived ingredients. The Hauts-de-France region anchors industrial-scale larvae rearing with waste-upcycling supply chains certified under EU Green Deal circular economy frameworks.
United States
Import demand for EU-origin insect protein meal outpaces domestic production as FDA Center for Veterinary Medicine notification requirements delay facility commissioning by 18-36 months. State-level feed control officials in California and Texas apply asynchronous enforcement interpretations of AAFCO guidelines for insect ingredient labeling. Pacific Northwest metropolitan markets demonstrate highest trial adoption rates among sustainability-motivated premium pet owners bypassing traditional retail through veterinary-direct channels.
United Kingdom
Post-Brexit regulatory divergence from EFSA approval pathways forces redundant safety assessments by the Food Standards Agency, compressing margin structures for cross-channel suppliers. London and Southeast England concentrate specialty retail distribution where independent pet shops provide tactile product education accelerating skeptical consumer conversion. Midlands-based co-manufacturers pilot hybrid protein formulations blending insect biomass with precision fermentation concentrates at sub-scale volumes pending regulatory clarity.
Insect-Based Pet Food Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical moats. Market structure tilts toward consolidated larvae production with fragmented downstream formulation, creating margin capture asymmetries between biomass cultivators and finished goods brands. Two strategic archetypes dominate: vertically integrated rearing-to-protein processors controlling cost structures, and asset-light brand marketers outsourcing manufacturing to certified co-packers. Competitive dynamics center on capacity expansion in climate-controlled facilities and strategic partnerships securing waste-stream feedstock contracts.
Among French biotech specialists, Innovafeed and Ynsect exemplify divergent species-level bets within the same regulatory jurisdiction, while Dutch-originated Protix anchors the black soldier fly production archetype. These three entities occupy positions spanning the value chain from larvae cultivation through extraction processing, representing alternative vertical integration models against which asset-light entrants benchmark capital efficiency. Their geographic clustering in the Netherlands and France reflects regulatory approval sequencing rather than feedstock availability, positioning each as archetype anchors for competitor strategic planning.
| Leading Market Players |
|---|
| Innovafeed |
| Ynsect |
| Protix |
| EnviroFlight |
| NextProtein |
| Nutrition Technologies |
| Entobel |
| Entomo Farms |
| Hexafly |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Dutch black soldier fly larvae facilities is compressing supplier margins while amplifying pricing power for EFSA-certified biomass holders serving German and French pet food manufacturers. This utilization imbalance forces asset-light brands toward long-term offtake contracts that lock in volume commitments at premium rates.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing, with premium-mid-economy pricing differentiation separating EFSA-notified suppliers from pending-approval competitors. Price differentiation rests on certification tier and vertical integration depth. Cost compression in standard-grade meal is intensifying because organic waste feedstock competition from biofuel processors is elevating input expenses. Mid-tier pet food manufacturers exhibit highest price sensitivity, while veterinary-direct therapeutic nutrition channels remain least sensitive.
Supply Chain Analysis
Tariff exposure between the Netherlands and post-Brexit United Kingdom dominates supply chain risk planning for cross-channel biomass flows. Geographic supply concentrates in the Netherlands, France, and Germany. Raw material dependencies draw from organic waste streams, specialized grain formulations, and climate-controlled facility energy inputs. Single-source vulnerability emerges from concentrated larvae rearing automation expertise. Distribution runs through co-manufacturing partnerships adjacent to cultivation clusters, with finished goods reaching retail via veterinary-direct and subscription e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as pet humanization splits demand across therapeutic, premium sustainability, and mass-market convenience segments that no single supplier configuration optimally serves.
For Market Incumbents: Insulate margin structures by securing exclusive waste-stream feedstock contracts with municipal organic waste processors in the Netherlands and France. Expand climate-controlled capacity in Brabant-region clusters before regulatory approval waves flood competing biomass supply. Certification investment in EFSA Novel Food dossier libraries for secondary species creates switching costs against pending entrants. For New Entrants and Emerging Players: Mid-market wet food formulations for feline therapeutic nutrition in German metropolitan markets represent the most penetrable entry point, as black soldier fly palatability gaps in cat diets create formulation white space. Precision fermentation hybrid protein blending capabilities at sub-scale volumes offer technical differentiation without capital-intensive larvae rearing infrastructure. Veterinary endorsement networks in Berlin-Brandenburg provide credible go-to-market acceleration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light brand marketers outsourcing to certified co-packers, compressing returns for vertical integration strategies. Long-term viability favors platform integrators controlling larvae-to-protein processing with established EFSA dossiers. Acquisition target archetype: Dutch or French biotech specialists with mealworm-specific R&D pipelines and pending regulatory approvals. Signal to watch: Aldi and Lidl sell-through rate disclosures from Bavaria and North Rhine-Westphalia trials.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Expansion | Species-by-species authorization accelerates competitor approval timelines and locks in formulation partnerships. |
| Climate-Controlled Capacity Buildout | Vertical farming automation in Brabant-region clusters stabilizes biomass output against organic waste price volatility. |
| Veterinary-Direct Channel Penetration | Berlin-Brandenburg subscription brands leverage therapeutic nutrition positioning to bypass retail gatekeeper hesitation. |
| Precision Fermentation Hybrid Integration | French and Dutch mid-tier brands blend insect biomass with complementary amino acid profiles addressing methionine gaps. |
| Waste-Stream Feedstock Securement | Exclusive municipal organic waste contracts in Hauts-de-France anchor circular economy certification under EU Green Deal frameworks. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with insect-rearing facility operators, pet food formulation scientists, veterinary nutrition specialists, and German discounter category buyers; and secondary validation against EFSA Novel Food Regulation filings, EU customs trade data for insect protein meal, ANSM feed additive classifications, and SEC disclosures from publicly traded pet food manufacturers. Bottom-up volume modeling triangulated against top-down market sizing from production capacity assessments.
Forecast inputs span product format segmentation, ingredient species regulatory status, customer type procurement authority, and distribution channel penetration velocity across the analysis window. Modeled dimensions include dry-treat-wet-supplement formats, black soldier fly versus mealworm versus cricket sourcing, pet owner versus manufacturer versus veterinarian customer archetypes, and online versus specialty retail versus mass grocery channels. CAGRs derive from capacity expansion timelines, regulatory approval sequencing, and retail trial conversion assumptions. Industry-specific inputs incorporate EFSA Novel Food species authorization schedules and Aldi-Lidl sell-through rate thresholds.
Macroeconomic conditions sit as an overlay; deviation in organic waste feedstock pricing, energy costs for climate-controlled facilities, or EU Green Deal subsidy disbursement timing would shift the trajectory. Forecasts reflect documented assumptions subject to revision from regulatory asynchronicity between EFSA and FDA approval pathways. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Gluten Substitute Market
Alternative Food Sources
Corn-Based Protein Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Vegan Sashimi Market
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
United States Hemp Protein Market
Alternative Food Sources
Gluten-Free Meat Substitutes Market
Alternative Food Sources
Europe Duckweed Protein Market
Alternative Food Sources
Europe Algae Protein Market
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
Food Cultures Market
Alternative Food Sources
Synthetic Food Market
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
Fishless Fillets Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
Africa Protein Market