
 Mushroom Protein Market | 2026-2036
Mushroom Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Mushroom Protein Market Analysis
Market Context
Fermentation technologist shortages across Europe and North America is reorganizing production timelines for mycoprotein manufacturers, forcing contract partnerships over captive facilities. ENOUGH leverages its proprietary biomass fermentation platform to anchor supply agreements with major food processors. Nature's Fynd specializes in extremophile fungal strains that sustain protein yields under non-sterile conditions, lowering capex barriers. DSM-Firmenich competes through its ingredient formulation expertise, extending mushroom protein into blended meat analog applications where texture and amino acid completeness matter.
Technical Definition and Segment Structure
Mushroom protein denotes protein concentrates, isolates, or whole biomass derived from filamentous fungi or fruiting bodies, typically containing 40-80% protein by dry weight with balanced essential amino acid profiles and functional beta-glucan fractions. Its primary commercial purpose centers on replacing animal and soy proteins in formulated foods where allergen reduction, umami flavor contribution, or sustainability credentials drive formulation decisions. Powdered protein dominates current manufacturing throughput due to shelf stability and ease of incorporation into dry blends, while supplement bars capture expanding margin pools as branded finished goods command price premiums over commodity powders. The sport nutrition end-user segment leads volume growth, though food industry applications in meat alternatives and bakery represent the largest absolute demand base with mature but still expanding offtake.
Regulatory Environment
The European Food Safety Authority evaluates novel food dossiers for mycoprotein ingredients under centralized EU procedures, while the FDA exercises enforcement discretion over GRAS self-affirmations in the United States, creating divergent market access timelines that favor early movers in either jurisdiction. REACH compliance for processing aids and the EU Green Deal's protein diversification targets are reshaping investment incentives toward domestic fermentation capacity. Stakeholders must monitor how novel food harmonization progresses across member states and whether FDA guidance on fermented proteins hardens into formal rulemaking that alters competitive positioning for entrants without established GRAS portfolios.
Market Dynamics
Fermentation capacity scarcity across Europe and North America is compressing production timelines for mycoprotein manufacturers, forcing contract partnerships over captive facilities and reshaping competitive positioning toward asset-light scale-up models.
Growth Catalysts
- EU Green Deal protein diversification targets:Domestic fermentation incentives in Germany and the Netherlands are accelerating capital deployment toward alternative protein infrastructure.
- Sport nutrition formulation demand:Recovery product brands are integrating mushroom protein into plant-based portfolios to capture shifting athlete preferences.
- Biomass fermentation yield improvements:Continuous processing advances are lowering unit economics for filamentous fungi protein production.
Market Restraints
- Glucose feedstock price volatility:Corn and wheat-derived sugar costs fluctuate with agricultural commodity cycles, squeezing mycoprotein margins.
- EFSA novel food approval timelines:Centralized EU safety evaluations extend market entry horizons for new fungal strains by 18-24 months.
- Soy protein isolate substitution threat:Established supply chains and lower per-kilogram costs maintain soy's dominance in mass-market meat alternatives.
Strategic Opportunities
- Underpenetrated US sports nutrition channel:Specialty retailers and direct-to-consumer platforms remain lightly served by branded mushroom protein finished goods.
- Precision fermentation hybridization:Combining biomass and precision approaches enables tailored protein functionality for bakery applications.
- Clean label bakery reformulation:Egg replacement demand in European artisan bread sectors creates formulation partnership openings.
Industry Challenges
- Fermentation technologist scarcity:Specialized bioprocess engineering talent pools in Denmark and Germany cannot match facility expansion rates.
- GRAS dossier compilation complexity:FDA self-affirmation requirements demand extensive toxicology data that strains early-stage capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mushroom Protein Market |
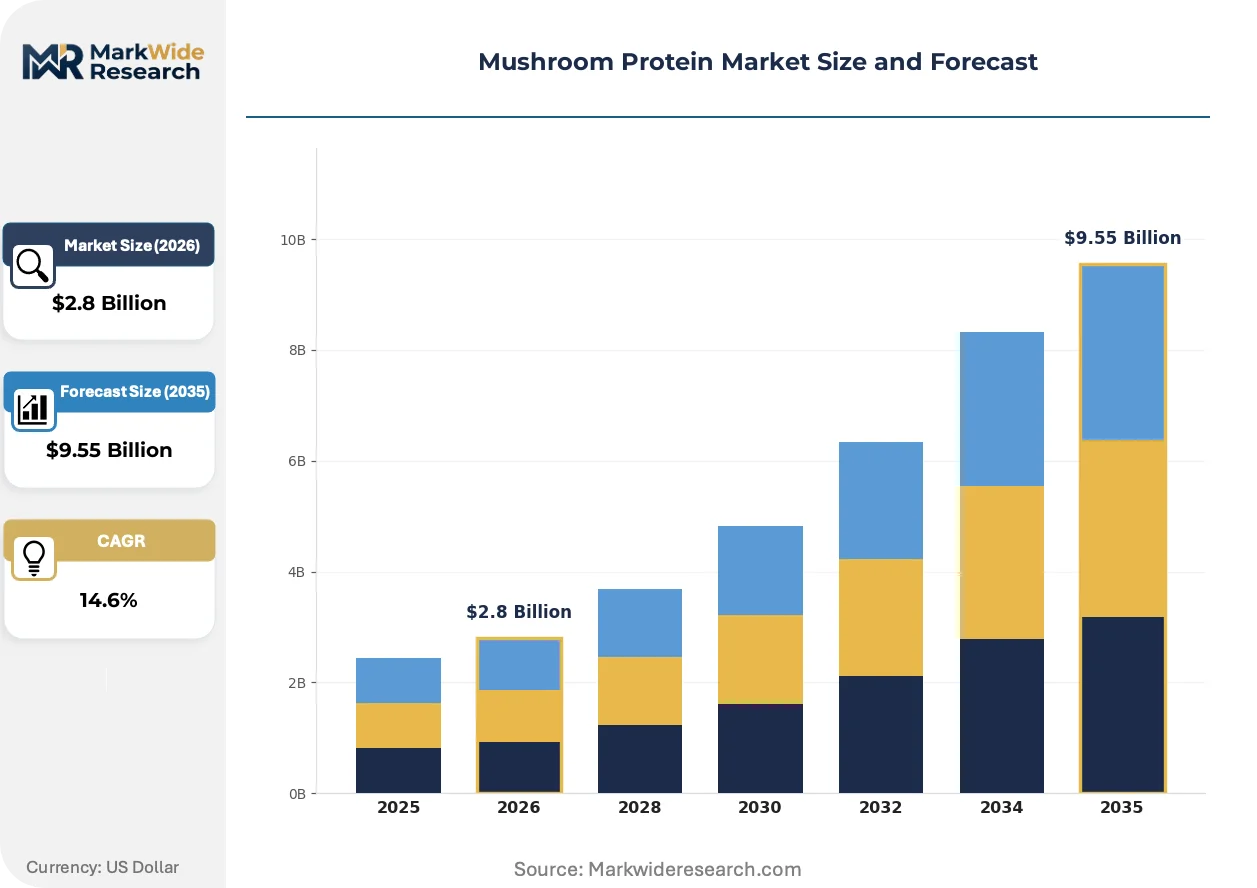
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Mushrooms, Dried Mushrooms, Powdered Protein, Supplement Bars End User: Food Industry, Nutraceuticals, Sport Nutrition, Dietary Supplements Nature: Organic, Non-Organic, Gluten-Free, Non-GMO Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | Angel Yeast Co., Ltd., ENOUGH, Monde Nissin Corporation, M2 Ingredients, Nammex, Cargill, Incorporated, Nature's Fynd, Maia Farms, DSM-Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mushroom Protein Market Emerging Trajectories
Active differentiation in production architecture and end-use targeting is fragmenting competitive strategies across the mushroom protein value chain, with technology choices increasingly determining addressable market scope.
Biomass fermentation platforms are bifurcating between high-throughput aerobic systems optimized for commodity protein powder and flexible smaller-scale configurations serving premium supplement bar manufacturers. Sport nutrition brands are adopting the latter for shorter production runs with rapid flavor rotation. This technology split is compressing mid-scale competitors lacking capital to operate across both modalities.
REACH compliance for processing aids and extraction solvents is tightening documentation requirements for European mycoprotein facilities. Manufacturers are reformulating downstream protocols to reduce chemical inputs. German and Dutch production sites are most affected, with several operators accelerating green chemistry certification timelines.
Direct procurement from fermentation operators is displacing traditional ingredient distributor relationships among large meat alternative processors. Cargill and ADM are building captive sourcing desks for alternative proteins. This channel shift is most visible in North American plant-based burger manufacturing, where volume commitments now precede facility construction.
Mushroom Protein Market Segmentation
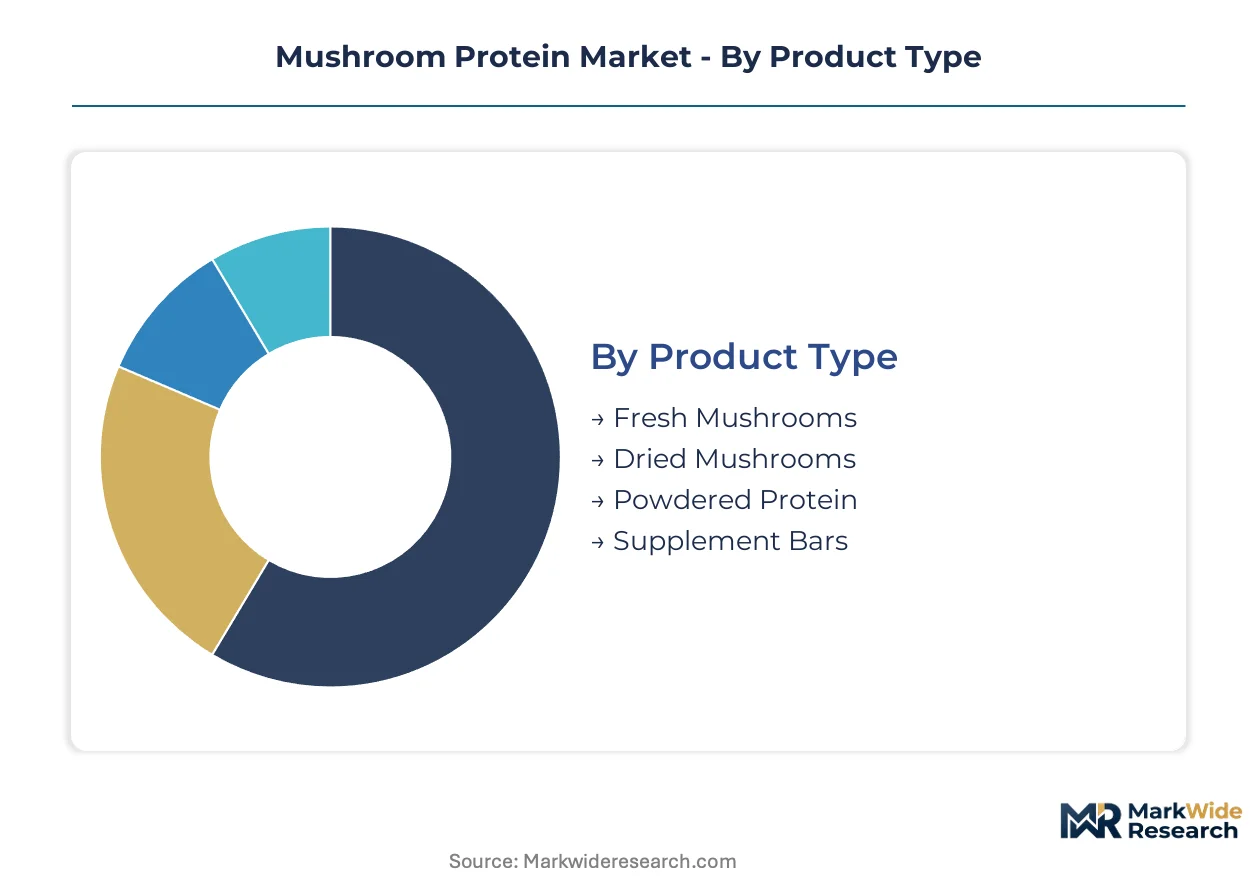
Mushroom protein segmentation reveals how formulation choices cascade through channel economics. Product format determines shelf stability requirements, while end-use concentration shapes margin capture and regulatory exposure across the value chain.
Product Type:
Powdered protein and supplement bars flow through divergent channel architectures. Bulk powder moves through ingredient distributors and direct B2B contracts with food processors, while finished bars reach consumers through branded retail and subscription platforms.
- Fresh Mushrooms:Whole fruiting bodies deliver 20-30% protein by wet weight with intact beta-glucan matrices. Food service operators in Germany and the Netherlands specify fresh biomass for premium meat alternative applications where texture authenticity commands formulation premiums.
- Powdered Protein:Spray-dried concentrates achieve 60-80% protein density with extended shelf stability. Dry blend manufacturers in the US sports nutrition channel are consolidating procurement around multi-year supply agreements to lock in fermentation capacity.
- Dried Mushrooms:Dehydrated whole or sliced fruiting bodies retain functional polysaccharides for traditional medicine applications.
- Supplement Bars:Finished consumer goods integrate mushroom protein with binding systems and flavor masking technologies.
Powdered protein dominates installed base. Supplement bars are where expansion concentrates.
End User:
Customer type stratification separates commodity volume buyers from premium formulation partners. Food industry procurement emphasizes cost-per-protein-unit, while sports nutrition brands prioritize amino acid completeness claims and clean label positioning.
- Food Industry:Meat alternative processors and bakery formulators consume mycoprotein biomass for texture and emulsification. German plant-based burger manufacturers are scaling filamentous fungi inclusion rates to reduce soy dependence.
- Sport Nutrition:Recovery product brands specify fungal protein for leucine content and digestibility scores. US specialty retailers are expanding shelf space for plant-based recovery formulations.
- Nutraceuticals:Immune support and cognitive health applications leverage beta-glucan bioactivity.
- Dietary Supplements:Capsule and tablet formats target wellness consumers seeking adaptogenic benefits.
Food industry commands absolute volume. Sport nutrition is climbing the fastest.
Nature:
Certification tiering creates price stratification that mirrors input cost structures. Organic cultivation requires substrate traceability and absence of synthetic pesticides, while conventional fermentation optimizes yield per glucose input.
- Organic:Certified substrate sourcing and processing without synthetic inputs. European artisan bakeries and premium supplement brands specify organic mycoprotein to satisfy clean label requirements.
- Non-GMO:Genetic non-modification verification addresses consumer skepticism toward biotechnology. US mass-market meat alternative processors are adopting non-GMO claims as a defensive positioning against precision fermentation competitors.
- Non-Organic:Standard cultivation without certification overhead.
- Gluten-Free:Allergen control certification for celiac-sensitive applications.
Non-Organic dominates installed base. Organic is where expansion concentrates.
Distribution Channel:
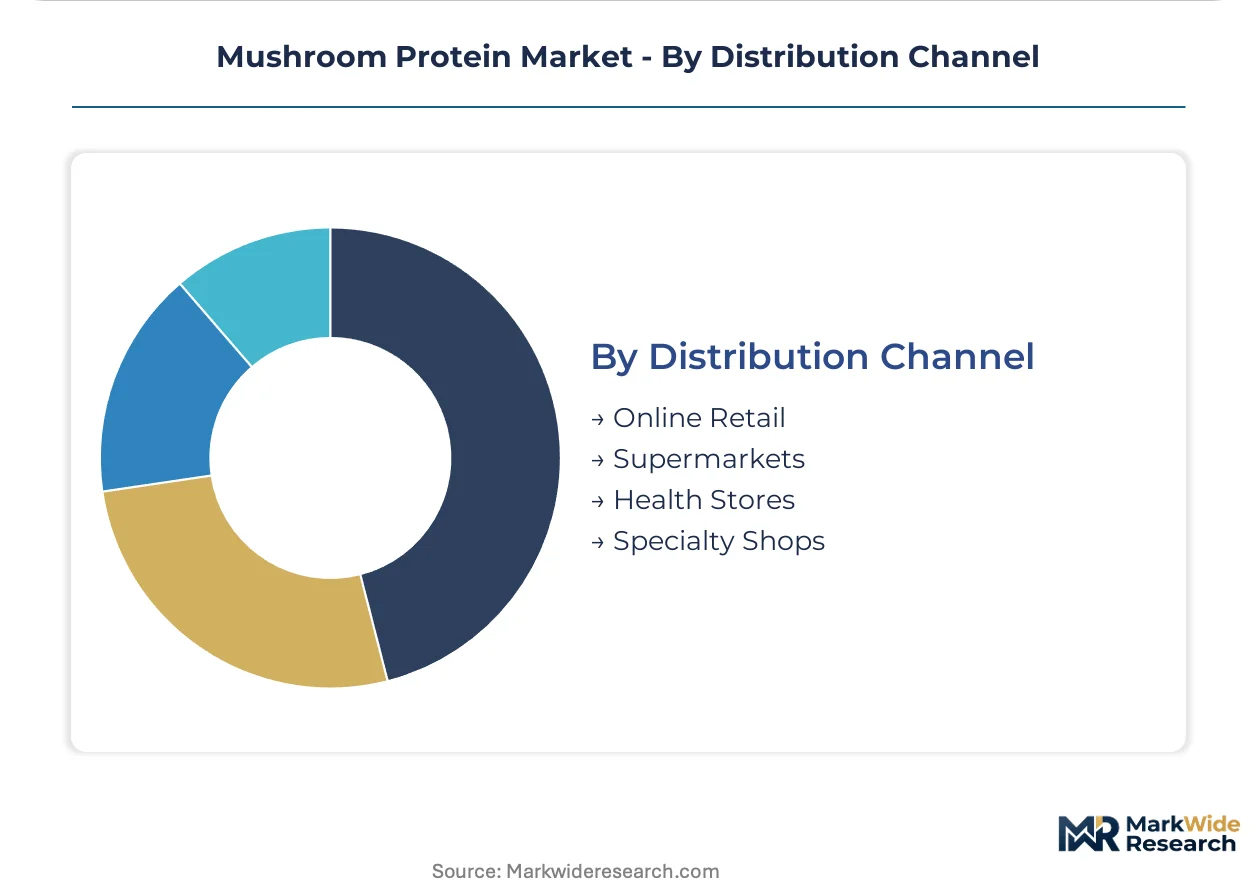
Channel mix is displacing traditional ingredient distributor relationships. Direct procurement from fermentation operators is compressing margin capture for intermediaries, particularly in North American plant-based manufacturing.
- Online Retail:Direct-to-consumer platforms and subscription services for finished goods. US sports nutrition startups are bypassing brick-and-mortar to capture recurring revenue with flavor-customized protein subscriptions.
- Supermarkets:Mass retail placement for branded supplement bars and powdered protein. German grocery chains are expanding alternative protein assortments in response to EU Green Deal protein diversification targets.
- Health Stores:Specialty retail with trained staff for product education.
- Specialty Shops:Boutique fitness and wellness retail with curated assortments.
Supermarkets dominate installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA's centralized novel food evaluation procedures anchor European market access timelines, while the FDA's GRAS self-affirmation pathway enables faster US entry for established fermentation operators. Divergent regulatory architectures are fragmenting competitive positioning across Atlantic markets.
Germany
Sport nutrition brands and plant-based meat processors drive mycoprotein procurement, with domestic fermentation infrastructure expanding around Hamburg and Berlin-Brandenburg clusters. The EU Green Deal's protein diversification targets accelerate capital deployment toward alternative protein scale-up. ENOUGH anchors supply agreements with major food processors from its biomass fermentation platform.
United States
Sports nutrition channel underpenetration creates whitespace for branded finished goods, while direct-to-consumer subscription platforms bypass traditional retail. FDA enforcement discretion over GRAS self-affirmations favors early movers with established dossiers. DSM-Firmenich extends mushroom protein into blended meat analog applications through ingredient formulation expertise.
Netherlands
Food-tech investment concentration in the Randstad region supports fermentation facility expansion for export-oriented mycoprotein production. REACH compliance for processing aids tightens documentation requirements at Dutch production sites. Nature's Fynd specializes in extremophile fungal strains that sustain protein yields under non-sterile conditions.
China
Domestic yeast and fermentation ingredient manufacturers leverage established bioprocess infrastructure for mycoprotein biomass production. SAMR's novel food registration requirements extend market entry timelines for imported fungal strains. Angel Yeast Co., Ltd. represents integrated fermentation ingredient supply capability.
Mushroom Protein Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the mushroom protein value chain. The vendor base fragments between biomass fermentation specialists, precision fermentation hybridizers, and ingredient formulation conglomerates. Three strategic archetypes dominate: asset-light technology licensors, vertically integrated biomass operators, and diversified ingredient houses. Competitive moves concentrate on capacity expansion through contract manufacturing partnerships and technology licensing for geographic market access.
Among fermentation technology specialists, ENOUGH and Nature's Fynd occupy distinct positioning vectors—ENOUGH exemplifying biomass platform scale-up and Nature's Fynd representing extremophile strain specialization. DSM-Firmenich anchors the diversified ingredient formulation tier, extending mushroom protein into downstream food applications through blended product architectures. These three companies collectively illustrate how technology choice determines addressable market scope.
| Leading Market Players |
|---|
| Angel Yeast Co., Ltd. |
| ENOUGH |
| Monde Nissin Corporation |
| M2 Ingredients |
| Nammex |
| Cargill, Incorporated |
| Nature's Fynd |
| Maia Farms |
| DSM-Firmenich |
| Others |
Supply Flow & Price Mechanics
Ninety-day fermentation batch cycles compress inventory turnover and tether pricing power to glucose feedstock hedging positions across German and Dutch production clusters. Supply concentration in these regions amplifies margin sensitivity to agricultural commodity swings while contract manufacturing partnerships dilute captive cost control.
Pricing Analysis
European organic mycoprotein commands a 40-50% premium over conventional North American supply, reflecting REACH compliance costs and EFSA novel food certification overhead. Three-tier pricing structure across premium, standard, and economy levels segments by organic certification, beta-glucan concentration, and direct-contract versus spot-market procurement. Cost compression in the standard tier is intensifying because soy protein isolate maintains a per-kilogram cost advantage in mass-market meat alternatives. Food industry processors exhibit the highest price sensitivity due to cost-per-protein-unit procurement metrics, while sports nutrition brands absorb premiums for leucine-content claims and clean-label positioning.
Supply Chain Analysis
Forty-five to sixty-day safety stock buffers at Dutch and German fermentation facilities reflect glucose supply volatility and EFSA approval timeline uncertainty. Production gravity centers on Germany, the Netherlands, and Denmark, where food-tech investment clusters anchor biomass fermentation scale-up. Downstream processing draws from corn-derived glucose, wheat-based substrates, and specialty nitrogen sources for fungal cultivation. Single-source vulnerability concentrates in glucose feedstock contracts tied to agricultural commodity cycles. Distribution runs through direct B2B procurement agreements that displace traditional ingredient distributors, particularly in North American plant-based burger manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mushroom protein platforms are approaching an interoperability inflection where fermentation capacity scarcity forces API-standardization for biomass-to-protein conversion metrics, enabling cross-manufacturer formulation substitution.
For Market Incumbents: Fortify supply security through backward integration into glucose feedstock processing or long-term agricultural partnerships, while accelerating green chemistry certification to preempt REACH enforcement tightening. DSM-Firmenich and ENOUGH face margin compression from precision fermentation entrants with lower capex requirements; defensive patenting around filamentous fungi strain libraries preserves formulation exclusivity in meat analog applications. For New Entrants and Emerging Players: Lead with extremophile strain specialization targeting non-sterile production conditions, capturing cost advantages in regions lacking Denmark-grade bioprocess engineering talent pools. The US sports nutrition channel remains the most penetrable whitespace, particularly direct-to-consumer subscription platforms bypassing brick-and-margin retail. Go-to-market execution should anchor on leucine-content certification and rapid flavor-rotation capabilities that biomass fermentation flexibility enables. For Investors and Strategic Acquirers: Long-term, this sits as a platform-commoditization play because fermentation technology licensing will displace captive manufacturing as the dominant value-capture mechanism. Acquisition targets should display hybrid biomass-precision fermentation capabilities with established GRAS dossiers or EFSA novel food approvals. The signal to watch is FDA guidance hardening into formal rulemaking on fermented proteins, which would revalue established regulatory dossiers against late entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Contract manufacturing partnerships in Germany and the Netherlands alleviate technologist scarcity constraints. |
| GRAS Dossier Compilation | FDA self-affirmation completion accelerates US market entry timelines for biomass fermentation operators. |
| Direct Procurement Desks | Cargill and ADM captive sourcing agreements reshape channel economics for mycoprotein volume buyers. |
| Extremophile Strain Licensing | Non-sterile production technology lowers capex barriers for geographic market access expansion. |
| Green Chemistry Certification | REACH compliance for processing aids protects European production site operating continuity. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EFSA novel food dossiers, FDA GRAS notifications, EU Green Deal implementation reports, and fermentation technology patent filings. Primary interviews engaged fermentation technologists, bioprocess engineering directors at mycoprotein manufacturers, sports nutrition brand formulators, and meat alternative procurement leads. Secondary validation drew from trade customs data, SEC filings of diversified ingredient houses, and REACH compliance documentation. Bottom-up capacity modeling triangulated against top-down protein diversification target allocations.
Segmentation dimensions modeled include product format hierarchy, end-user procurement behavior, certification tier stratification, and regional regulatory cluster divergence across the analysis window. CAGRs emerged from biomass fermentation yield improvement curves, glucose feedstock price trajectory assumptions, and channel shift velocity toward direct procurement. Industry-specific forecast inputs incorporated EU Green Deal protein diversification incentive deployment rates and FDA guidance evolution on fermented protein safety evaluation.
The analysis sits within stated boundaries; outcomes outside EFSA approval timeline stability, glucose commodity price bands, or fermentation technologist supply expansion would require recalibration. Forecasts reflect documented assumptions about regulatory harmonization progress and biomass yield improvement trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Vegan Tuna Market
Alternative Food Sources
Egg Replacers Market
Alternative Food Sources
Single Cell Oil Market
Alternative Food Sources
Flour Substitutes Market
Alternative Food Sources
Gluten Replacer Market
Alternative Food Sources
Precision Fermentation Market
Alternative Food Sources
Konjac Market
Alternative Food Sources
Asia-Pacific Algae Protein Market
Alternative Food Sources
South America Fat Replacers Market
Alternative Food Sources
Europe Emergency Food Market
Alternative Food Sources
Bagasse Disposable Cutlery Market
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
Teff Products Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
Global Meal Replacement Market
Alternative Food Sources
Edible Insects Market