
 South American Algae Protein Market | 2026-2036
South American Algae Protein Market Size, Share, and Industry Trends Forecast 2026-2036
South American Algae Protein Market Analytics
Buyer concentration among food manufacturers is broadening as mid-sized Brazilian and Argentine processors enter the algae protein supply base alongside established multinationals. Corbion leverages its fermentation infrastructure to secure bulk supply contracts with South American ingredient distributors. Roquette Frères anchors its regional position through specialized protein extrusion capabilities tailored to local formulation requirements. Cyanotech Corporation competes on astaxanthin-enriched spirulina strains that command premium positioning in nutraceutical channels.
Algae protein denotes protein biomass extracted from cultivated microalgae species, typically comprising 50-70% crude protein by dry weight with complete essential amino acid profiles comparable to soy or egg protein. Industrial applications exploit its emulsification stability and neutral flavor potential to fortify meat analogues, dairy alternatives, and sports nutrition products. Spirulina dominates current volume flows due to established cultivation infrastructure and lower downstream processing costs, while chlorella captures accelerating interest from nutraceutical formulators seeking detoxification-positioned ingredients. The animal feed application segment sustains above-average growth as Brazilian poultry and aquaculture operations trial algae meal to reduce fishmeal dependency in formulated diets.
ANVISA governs novel food ingredient approvals and safety assessments for algae-derived proteins entering Brazilian commerce, while Argentina's national food regulator enforces parallel sanitation standards that influence cross-border trade flows. The Mercosur technical regulation harmonization process is reducing duplicate certification burdens for suppliers operating across member states. Stakeholders must monitor pending updates to novel food frameworks and calibrate compliance investments against the pace of regulatory convergence.
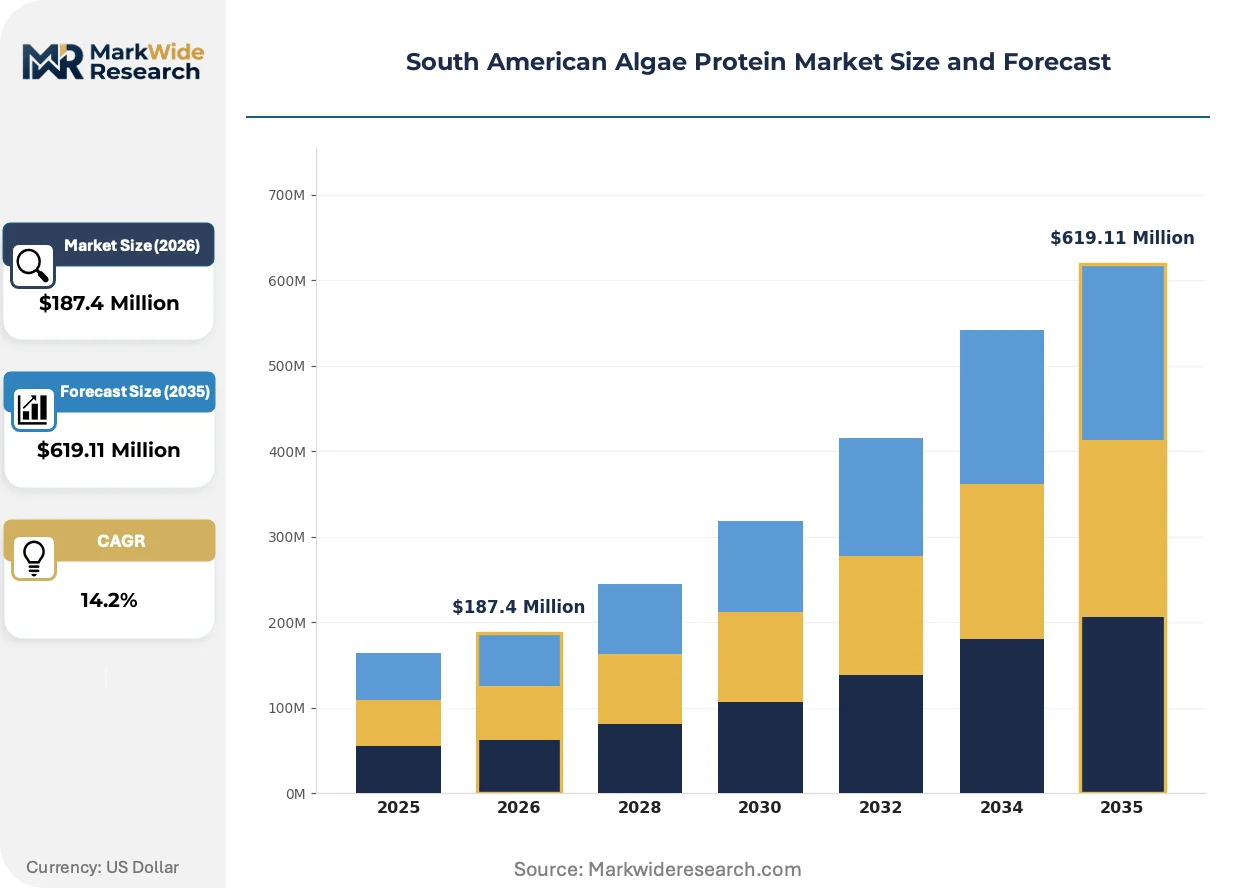
Market Dynamics
ANVISA's novel food framework is compressing approval timelines for algae-derived ingredients, accelerating Brazilian food manufacturer adoption while Mercosur harmonization reduces cross-border certification duplication.
Growth Catalysts
- ANVISA Streamlined Pathways:Brazil's health regulator has consolidated safety assessment protocols for microalgae biomass, cutting novel food approval cycles. Argentine processors leverage this precedent to fast-track chlorella imports.
- Poultry Feed Substitution:Brazilian integrators are trialing spirulina meal to displace fishmeal in broiler diets, driven by marine ingredient price volatility and sustainability mandates from export buyers.
- São Paulo-Minas Corridor Concentration:Food manufacturing clusters in southeastern Brazil generate economies of scale for algae protein toll processing, attracting specialized extrusion infrastructure investment.
Market Restraints
- Photobioreactor Capex Intensity:Closed-system cultivation requires substantial upfront capital for temperature and contamination control, limiting domestic production scale-up beyond pilot volumes.
- Argentine Import Friction:National sanitation standards enforced by Argentina's food regulator create documentation bottlenecks for Brazilian-sourced algae ingredients, fragmenting supply security.
- Soy Protein Substitution Threat:Established crushing infrastructure and farmer financing networks for Brazilian soy maintain cost advantages in mass-market meat analogue formulations.
Strategic Opportunities
- Colombian Market Entry:Underdeveloped local production and rising functional food demand in Bogotá and Medellín create first-mover positioning for Brazilian suppliers with Mercosur trade credentials.
- Nutraceutical Channel Expansion:Astaxanthin-enriched strains command premium positioning in pharmacy and direct-to-consumer wellness segments underserved by commodity spirulina.
- Fermentation Infrastructure Repurposing:Existing ethanol and yeast facilities in Brazil's sugarcane belt offer retrofit potential for heterotrophic algae cultivation, collapsing cultivation cost curves.
Industry Challenges
- Phycocyanin Extraction Talent Gap:Specialized downstream processing expertise for pigment recovery and protein isolation remains concentrated in European and North American technical institutes, constraining local value capture.
- Organic Certification Timelines:Brazilian certifiers lack established protocols for algae cultivation inputs, delaying premium positioning for export-oriented suppliers targeting EU organic standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South American Algae Protein Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirulina, Chlorella, Dunaliella, Others Application: Food & Beverages, Nutraceuticals, Animal Feed, Pharmaceuticals Distribution Channel: Online, Supermarkets, Health Stores, Direct Sales End User: Health-Conscious Consumers, Fitness Enthusiasts, Pet Owners, Food Manufacturers |
| Companies Covered | Corbion, Cyanotech Corporation, Roquette Frères, Far East Bio-Tec, Parry Nutraceuticals, Allmicroalgae, Taiwan Chlorella Manufacturing Company, Earthrise Nutritionals, DIC Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South American Algae Protein Market Evolving Landscape
Processing technology convergence and regulatory alignment are compressing the gap between laboratory strain development and industrial-scale protein output across the continent.
Heterotrophic fermentation is unifying upstream cultivation with downstream protein concentration in single-unit operations. Brazilian ethanol producers are retrofitting anaerobic digesters for glucose-fed chlorella production, collapsing the traditional separation between biomass generation and extraction. This integration is enabling toll manufacturers to offer integrated protein-isolate services rather than raw biomass trading.
Mercosur technical regulation harmonization is reducing duplicate safety dossier submissions for algae ingredients crossing Brazilian-Argentine borders. The mutual recognition framework allows ANVISA-approved strains to enter Argentine commerce with abbreviated local review, accelerating regional supply chain consolidation. Nutraceutical distributors are restructuring warehousing to exploit this friction reduction.
Sports nutrition brands are consolidating procurement around single-source spirulina contracts with embedded quality certification, displacing spot-market purchasing from multiple traders. This concentration is compressing supplier margins while rewarding integrated producers with captive cultivation and in-house analytical capabilities. The shift is most visible in São Paulo's contract manufacturing sector serving premium whey-alternative formulations.
South American Algae Protein Market Segmentation
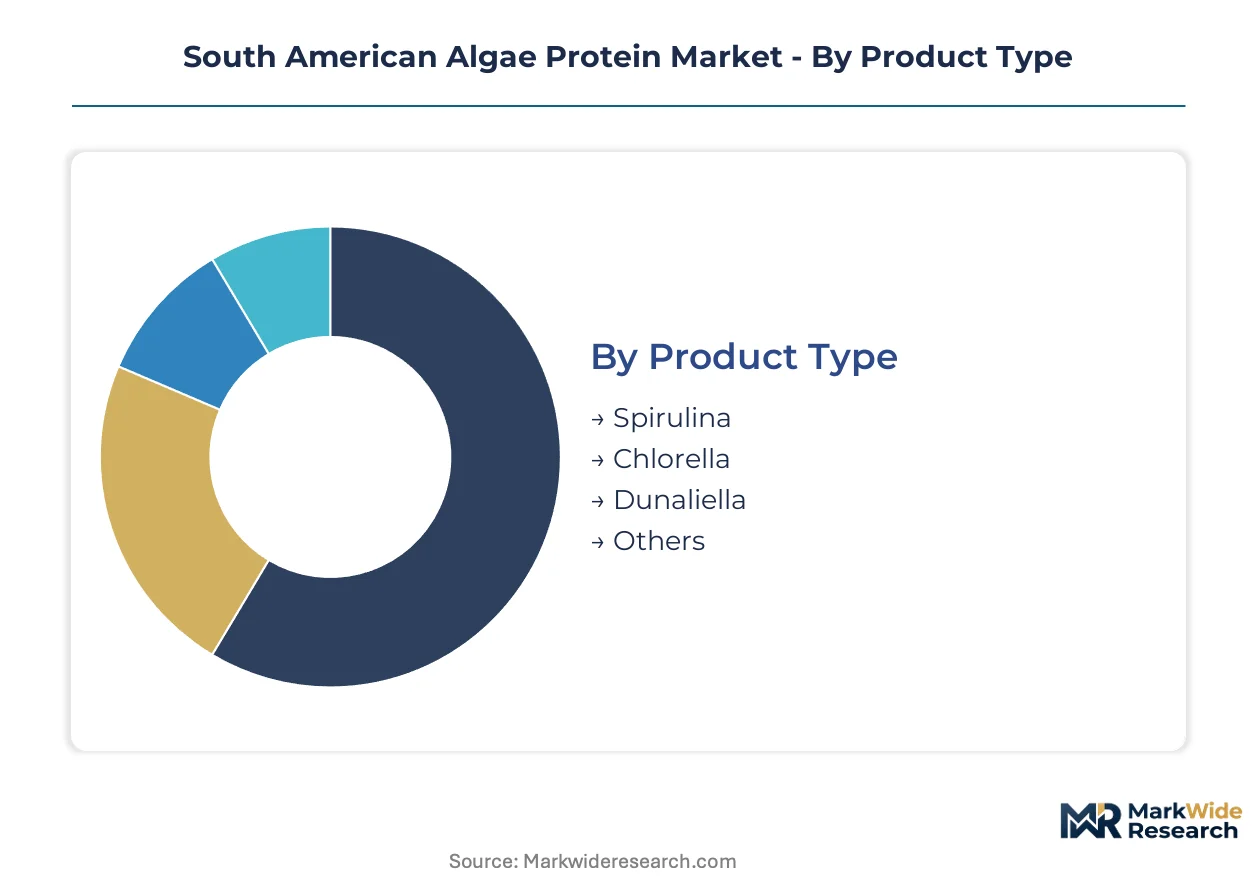
Algae protein segmentation in South America tracks distinct upgrade cycles across cultivation technologies, formulation requirements, and channel maturities. Manufacturers navigate divergent cost structures and regulatory pathways when targeting food-grade versus feed-grade outputs.
Product Type:
Upgrade cycles in cultivation infrastructure favor strains with established downstream processing ecosystems, while novel species face capital intensity barriers.
- Spirulina:Arthrospira platensis biomass delivers 60-70% crude protein with established open-pond cultivation infrastructure across Brazil's Northeast. São Paulo extrusion facilities source spirulina concentrates for meat analogue formulations, though photobioreactor contamination risks constrain premium-grade supply security.
- Chlorella:Broken-cell processing requirements for digestibility add 15-20% to downstream costs versus spirulina. Argentine nutraceutical formulators import chlorella for detoxification-positioned supplements, leveraging ANVISA's streamlined novel food precedents to accelerate local registration.
- Dunaliella:Beta-carotene enriched strains command specialty positioning in cosmetic and premium feed applications.
- Others:Haematococcus and Schizochytrium strains target astaxanthin and DHA extraction respectively, with minimal South American cultivation scale.
Volume placements concentrate in Spirulina; the faster expansion belongs to Chlorella.
Application:
Cost tier differentiation separates commodity feed applications from premium nutraceutical positioning, with food-grade formulations occupying a contested middle band.
- Food & Beverages:Emulsification-stable protein isolates fortify dairy alternatives and baked goods in Brazil's southeastern manufacturing corridor. ANVISA's consolidated safety protocols enable faster formulation trials, though soy protein cost advantages limit mass-market penetration.
- Nutraceuticals:Astaxanthin-enriched spirulina and broken-cell chlorella dominate pharmacy and direct-to-consumer channels. Colombian distributors are restructuring warehousing to capture Bogotá and Medellín demand with Mercosur-harmonized import documentation.
- Animal Feed:Brazilian poultry integrators trial spirulina meal to displace fishmeal in broiler diets, responding to marine ingredient price volatility and export buyer sustainability mandates.
- Pharmaceuticals:Clinical-grade protein isolates remain import-dependent due to domestic GMP fermentation capacity constraints.
Feed applications absorb the highest tonnage; nutraceutical channels are climbing the fastest.
Distribution Channel:
Customer type concentration drives channel selection, with institutional procurement favoring direct relationships and consumer segments fragmenting across digital and physical touchpoints.
- Online:Direct-to-consumer spirulina powders and capsules dominate Argentine and Colombian e-commerce, bypassing traditional pharmacy markups.
- Supermarkets:Mass-market spirulina tablets and fortified beverages concentrate in São Paulo and Rio de Janeiro retail chains.
- Health Stores:Specialty retailers in Buenos Aires and Santiago curate premium chlorella and astaxanthin-enriched formulations.
- Direct Sales:Bulk protein isolate contracts with Brazilian food manufacturers run through specialized ingredient distributors with embedded quality certification.
Direct sales capture the largest contract values; online channels are gaining share fastest.
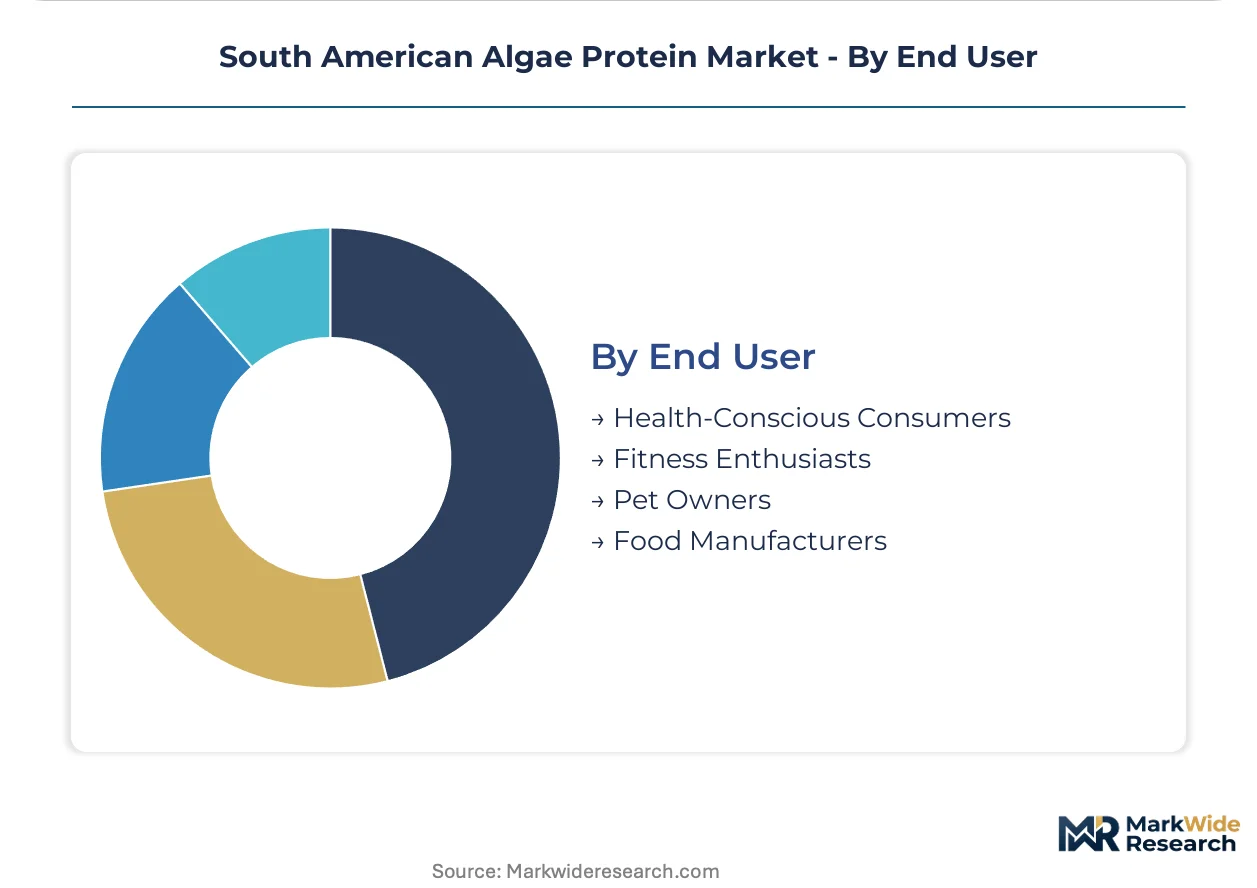
End User:
Margin structures diver sharply between price-sensitive feed buyers and premium-positioned wellness consumers, with fitness and pet segments emerging as intermediate tiers.
- Health-Conscious Consumers:Middle-income urban households in São Paulo and Buenos Aires drive spirulina tablet and powder demand, with organic certification premiums constrained by Brazilian certifier protocol gaps.
- Fitness Enthusiasts:Sports nutrition brands in southeastern Brazil consolidate procurement around single-source contracts with embedded analytical capabilities, displacing spot-market purchasing.
- Pet Owners:Premium companion animal formulations in Colombia and Chile incorporate algae protein for coat health positioning.
- Food Manufacturers:Brazilian meat analogue and dairy alternative processors represent the most concentrated demand bloc, with toll extrusion infrastructure investment following their procurement patterns.
Food manufacturers command the steepest volume; fitness enthusiasts show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Brazil's southeastern industrial corridor, where São Paulo and Minas Gerais states anchor formulation-scale procurement for meat analogues and dairy alternatives.
Brazil
Food manufacturers in the São Paulo-Minas corridor drive continent-leading volume procurement for algae protein isolates. ANVISA's consolidated novel food protocols compress approval timelines for microalgae biomass, enabling faster formulation trials. Toll extrusion infrastructure investment follows procurement patterns from Brazilian meat analogue processors seeking emulsification-stable protein fortification.
Argentina
Argentine nutraceutical formulators import broken-cell chlorella for detoxification-positioned supplements targeting pharmacy channels. The national food regulator enforces sanitation standards that create documentation friction for Brazilian-sourced ingredients. Buenos Aires health stores curate premium astaxanthin-enriched formulations alongside direct-to-consumer e-commerce distribution.
Colombia
Bogotá and Medellín generate rising functional food demand from underdeveloped local production capacity. Colombian distributors restructure warehousing to capture Mercosur-harmonized import documentation benefits. Pharmacy and wellness channels in these metropolitan centers absorb premium-positioned spirulina and chlorella supply.
Chile
Santiago-based specialty retailers concentrate premium algae protein distribution for nutraceutical and companion animal formulations. The country's technical regulator aligns with Mercosur harmonization frameworks to reduce cross-border certification duplication. Pet food manufacturers incorporate algae protein for coat health positioning in premium companion animal diets.
South American Algae Protein Market Competitive Landscape
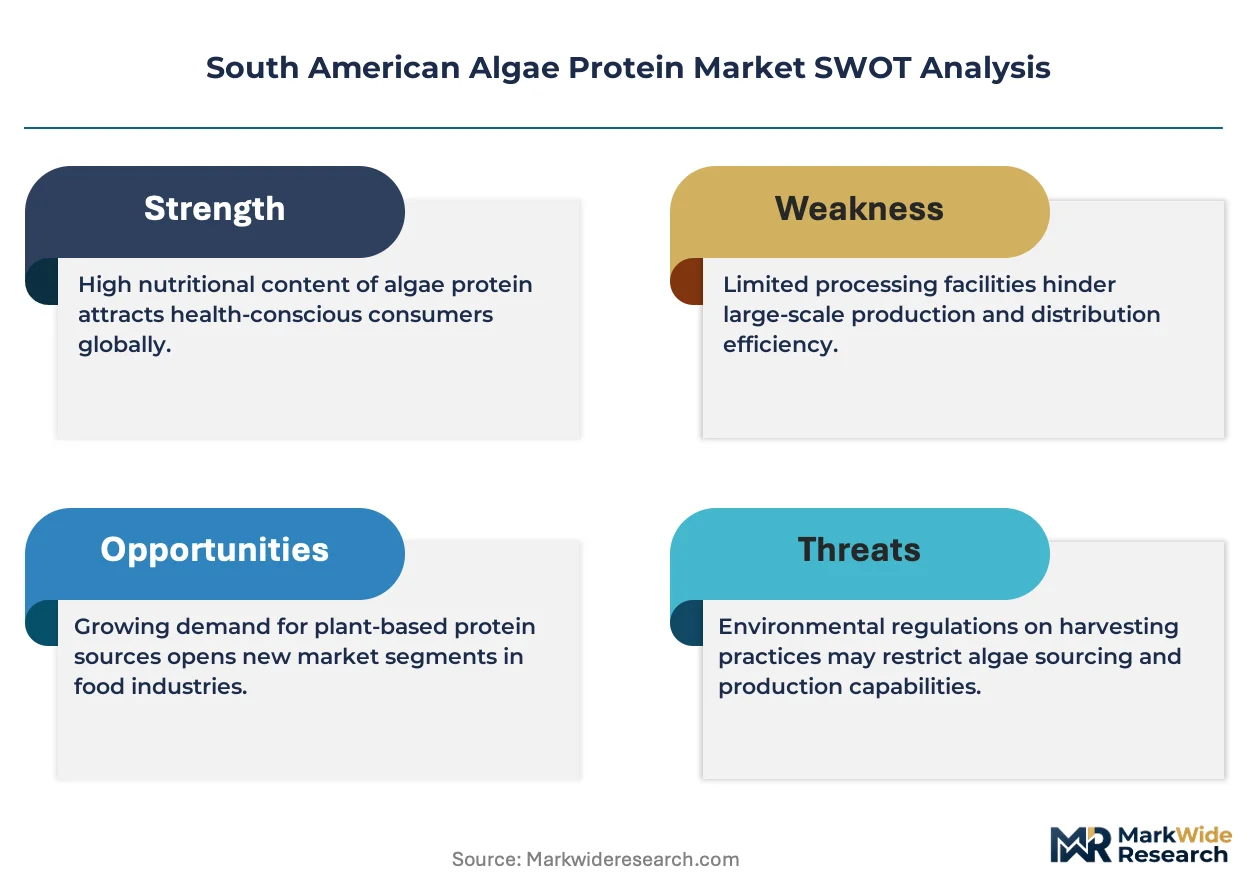
Established producers occupy the standard tier; emerging entrants pursue heterotrophic fermentation retrofit opportunities in Brazil's sugarcane belt. The vendor base stratifies between integrated cultivators with captive biomass supply and toll processors offering protein isolation services. Three archetypes dominate: multinational ingredient distributors with regional warehousing, fermentation specialists leveraging existing ethanol infrastructure, and nutraceutical-focused strain developers commanding premium positioning. Capacity expansion and strategic partnerships with food manufacturers represent the dominant competitive vectors.
Among fermentation-anchored suppliers, Corbion leverages its existing infrastructure to secure bulk supply contracts with South American ingredient distributors. Roquette Frères exemplifies the specialized processing tier through protein extrusion capabilities tailored to local formulation requirements. Cyanotech Corporation occupies the premium nutraceutical position, competing on astaxanthin-enriched strains that command elevated pricing in pharmacy and direct-to-consumer wellness channels.
| Leading Market Players |
|---|
| Corbion |
| Cyanotech Corporation |
| Roquette Frères |
| Far East Bio-Tec |
| Parry Nutraceuticals |
| Allmicroalgae |
| Taiwan Chlorella Manufacturing Company |
| Earthrise Nutritionals |
| DIC Corporation |
| Others |
Value Network & Pricing Analysis
Photobioreactor capex intensity cascades through South American algae protein markets, concentrating premium-grade biomass pricing power among Brazilian cultivators with closed-system infrastructure while Argentine importers absorb elevated landed costs for broken-cell chlorella.
Pricing Analysis
Volume placements in commodity spirulina biomass compress margins to single-digit returns, while astaxanthin-enriched strains and pharmaceutical-grade isolates sustain premium-mid-economy pricing differentiation. Certification tier—ANVISA novel food approval versus organic EU equivalence—drives price spreads exceeding 40% at wholesale. Pricing pressure stems from soy protein substitution in Brazilian meat analogue formulations, forcing algae suppliers to bundle technical formulation support. Food manufacturers exhibit highest price sensitivity; nutraceutical distributors accept premium positioning for pigment-enriched strains.
Supply Chain Analysis
Mercosur local-content harmonization is reshaping sourcing patterns, accelerating Brazilian biomass preference over Asian imports in Argentine commerce. Upstream cultivation concentrates in Brazil's northeastern open-pond corridor and São Paulo's emerging photobioreactor clusters; downstream isolation capacity clusters in Minas Gerais toll processors. Raw material dependencies include glucose feedstock from Brazil's sugarcane belt, specialized filtration membranes from European suppliers, and analytical reference standards for phycocyanin quantification. Single-source vulnerability pervades broken-cell processing equipment, where German and Japanese OEMs dominate. Distribution runs through specialized ingredient distributors with embedded quality certification rather than commodity traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American algae protein markets are consolidating around captive cultivation and in-house extraction capabilities, with backward integration into photobioreactor infrastructure emerging as the decisive competitive lever.
For Market Incumbents: Hedge spirulina commoditization by securing exclusive strain development partnerships with Brazilian agricultural research institutes. Lock in toll extrusion capacity in the São Paulo-Minas corridor before fermentation retrofit competitors capture shelf space. ANVISA's accelerating approval timelines for novel strains threaten first-mover advantages; patent-protected astaxanthin-enriched varieties offer defensive moats against generic spirulina traders. For New Entrants and Emerging Players: Nutraceutical distributors in Bogotá and Medellín present the most penetrable channel, with Colombian warehousing restructuring creating first-mover windows for Mercosur-credentialed suppliers. Target broken-cell chlorella for detoxification-positioned supplements, where Argentine pharmacy channels show supply gaps. Accelerate market entry through white-label manufacturing partnerships with São Paulo contract manufacturers rather than greenfield cultivation investment. For Investors and Strategic Acquirers: ANVISA's consolidation of microalgae safety assessment protocols is the leading indicator that regulatory arbitrage opportunities are closing, compressing valuation windows for pre-revenue strain developers. Prioritize acquisition targets with heterotrophic fermentation retrofit capabilities in Brazil's sugarcane belt, where ethanol infrastructure repurposing collapses cultivation cost curves. Watch for spirulina meal adoption rates in Brazilian poultry integrators as the inflection signal for feed-grade volume scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Heterotrophic Fermentation Retrofit | Repurposing Brazil's ethanol infrastructure collapses algae cultivation cost structures versus photobioreactor greenfields. |
| ANVISA Novel Food Pre-Registration | Early dossier submission accelerates Brazilian market access before Mercosur harmonization fully matures. |
| Single-Source Sports Nutrition Contracts | Embedded quality certification displaces spot-market purchasing in São Paulo's contract manufacturing sector. |
| Colombian Distribution Partnership | Bogotá and Medellín warehousing restructuring captures rising functional food demand with trade-credential advantages. |
| Phycocyanin Extraction Capability Buildout | Local downstream processing expertise reduces European technical institute dependency for pigment recovery. |
Research Methodology
Independent corroboration across ANVISA regulatory filings, Mercosur technical harmonization documentation, and Brazilian customs trade data underwrites the qualitative findings in this study. Primary interviews with algae cultivation facility managers, ingredient distributor procurement leads, food manufacturer R&D directors, and ANVISA regulatory affairs specialists were cross-referenced against secondary sources including ANVISA novel food registers, Brazilian Institute of Geography and Statistics agricultural production data, and SEC filings of listed suppliers. Bottom-up volume estimates from identified cultivation facilities were reconciled with top-down demand projections from end-use sector consumption patterns.
Rate-of-change decomposition across the analysis window isolates volume drivers from price effects in value projections. Segmentation modeling incorporates cultivation technology type, product grade tier, application channel, and regional regulatory cluster dimensions. CAGRs were derived from fitted trend extrapolation adjusted for identified inflection signals including ANVISA approval velocity and poultry feed substitution trial outcomes. Forecast inputs include strain-specific biomass productivity rates, extraction yield coefficients, and ANVISA novel food approval pipeline status.
Several conditions sit outside the modeled scope, including potential discontinuities in Mercosur political integration, abrupt shifts in Brazilian ethanol policy affecting feedstock availability, and breakthroughs in cell-cultured protein competitive substitution. Forecasts reflect documented assumptions regarding regulatory convergence pace and cultivation technology cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Precision Fermentation Market
Alternative Food Sources
United States Hemp Protein Market
Alternative Food Sources
Global Konjac Glucomannan Market
Alternative Food Sources
Global Algal Oil Market
Alternative Food Sources
Meat Analogue Market
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
Europe Emergency Food Market
Alternative Food Sources
Algae Oil Market
Alternative Food Sources
Feather Meal Market
Alternative Food Sources
Middle East and Africa Meal Replacement Products Market
Alternative Food Sources
Bagasse Disposable Cutlery Market
Alternative Food Sources
Upcycled Food Products Market
Alternative Food Sources
Spirulina Market
Alternative Food Sources
Plant-Based Compound Feed Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Global Algae Market