
 Black Soldier Fly (BSF) Market | 2026-2036
Black Soldier Fly (BSF) Market Size, Share, and Industry Trends Forecast 2026-2036
Black Soldier Fly (BSF) Market Insights
Modular larvae-processing configurations is rebalancing procurement decisions across the value chain. Nutrition Technologies Group leverages integrated breeding-to-drying operations across Southeast Asian facilities. Protix B.V. anchors European supply with industrial-scale bioconversion plants in the Netherlands. InnovaFeed SAS specializes in pharmaceutical-grade insect protein streams alongside commodity feed outputs.
The Black Soldier Fly (Hermetia illucens) is a dipteran insect whose larvae contain 40-45% crude protein and 30-35% lipid by dry weight, cultivated through controlled bioconversion of organic waste streams. Larvae production serves as a feedstock for animal nutrition, organic fertilizer, and biochemical extraction. Larvae product type dominates current volume due to established inclusion rates in aquaculture and poultry diets. Protein supplement application captures expanding margin pools as pet food brands reformulate with insect-derived alternatives. Bioconversion technology leads capital deployment, though anaerobic digestion co-location is gaining traction for integrated waste-to-protein facilities.
EU F-Gas Regulation and Novel Food frameworks under EFSA jurisdiction determine which life stages and end-uses gain market authorization. REACH compliance and CE marking requirements shape equipment import and facility design across European production sites. US FDA enforcement discretion letters and pending AAFCO ingredient definitions influence timing of American pet food and poultry feed adoption. Stakeholders must track regulatory divergence between jurisdictions to optimize facility location and product registration sequencing.
Market Dynamics
EU authorization of insect protein under revised F-Gas Regulation and Novel Food frameworks is compressing facility location decisions and product registration sequencing across the value chain. This regulatory momentum is pulling capital toward jurisdictions with clearer approval pathways while stranding pre-compliant capacity elsewhere.
Growth Catalysts
- Regulatory authorization:EFSA jurisdiction over insect life stages under EU Novel Food frameworks is unlocking poultry and pig feed applications previously restricted to aquaculture.
- Pet food reformulation:North American and European pet food manufacturers are scaling BSF protein meal purchases as a sustainable alternative to fishmeal and soy protein concentrates.
- Waste stream valorization:Anaerobic digestion co-location is gaining traction for integrated waste-to-protein facilities, reducing input cost volatility and disposal liabilities.
Market Restraints
- Input cost volatility:Organic waste substrate quality and availability fluctuates seasonally, compressing larval yield consistency and protein content stability.
- Supply concentration risk:Industrial-scale bioconversion capacity clusters in the Netherlands, creating single-point vulnerability for European compound feed supply security.
- Regulatory friction:Pending AAFCO ingredient definitions in the United States delay American pet food and poultry feed adoption timelines relative to European counterparts.
Strategic Opportunities
- Underpenetrated Southeast Asian production:Integrated breeding-to-drying operations in Malaysia and Vietnam offer lower-cost expansion paths outside EU regulatory complexity.
- Pharmaceutical-grade protein streams:High-purity insect protein for biomedical and cosmetic applications commands margin premiums above commodity feed outputs.
- EU Green Deal alignment:Circular economy mandates and carbon accounting frameworks incentivize bioconversion investments that monetize waste diversion credits.
Industry Challenges
- Entomology talent scarcity:Controlled-environment rearing of Hermetia illucens requires specialized expertise in insect physiology and microbiome management that outpaces academic program output.
- CE marking complexity:Equipment import and facility design across European production sites faces REACH compliance verification delays and divergent national implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Black Soldier Fly (BSF) Market |
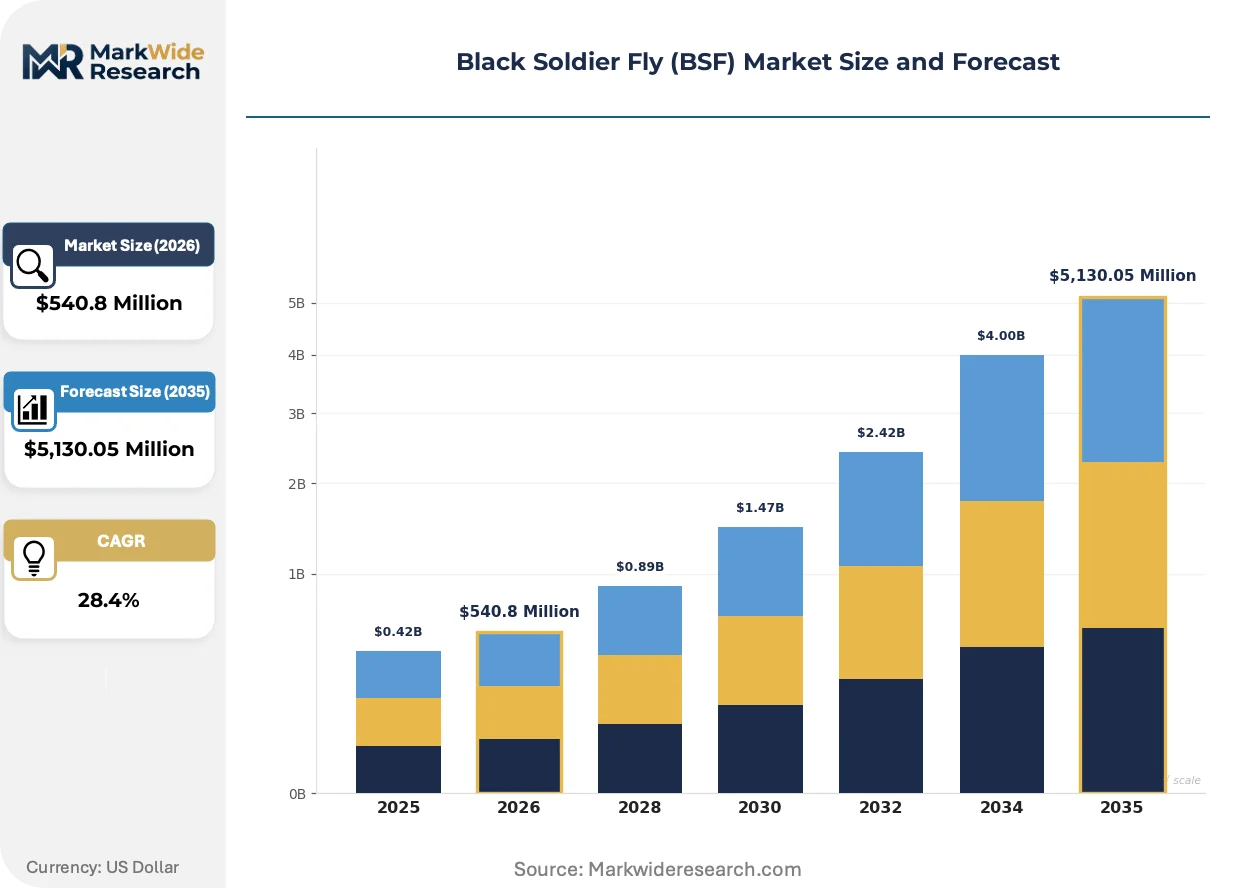
| Market Size in 2026 | $540.8 Million |
| Market Size in 2035 | $5,130.05 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Flies, Larvae, Dried Flies, Frass End User: Agriculture, Pet Food, Feed Industry, Waste Management Technology: Fermentation, Anaerobic Digestion, Composting, Bioconversion Application: Organic Fertilizer, Protein Supplement, Biopesticide, Nutraceuticals |
| Companies Covered | Nutrition Technologies Group, Entobel Holdings Pte. Ltd., Protix B.V., SFly Comgraf SAS, Entofood Sdn Bhd, InnovaFeed SAS, Bioflytech S.L., Hexafly, EnviroFlight, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Black Soldier Fly (BSF) Market Trends and Innovations
Modular larvae-processing configurations are rebalancing procurement decisions across the BSF value chain. Technology convergence, regulatory clarity, and buyer behavior shifts are compressing traditional supply relationships while opening new margin pools.
Automated climate-controlled rearing systems is electrifying the economics of industrial-scale bioconversion. Aquaculture feed compounders in Denmark and Norway are adopting these systems at pilot-to-commercial pace. This technology is compressing labor intensity and enabling 24-hour larval density optimization previously unattainable in manual operations.
REACH compliance and CE marking requirements are reshaping equipment import and facility design across European production sites. Manufacturers must now pre-certify bioreactor and drying equipment before installation, extending project timelines. Larvae product type facilities in Germany and France are responding by sourcing from EU-based equipment fabricators to bypass third-country verification bottlenecks.
Compound feed mills are consolidating supplier relationships around vertically integrated BSF processors capable of certifiable protein consistency. Long-term offtake agreements are displacing spot-market purchasing in aquaculture and poultry verticals. This concentration is most visible in the Netherlands, where Protix B.V. and InnovaFeed SAS have secured multi-year contracts with major feed groups.
Black Soldier Fly (BSF) Market Segmentation
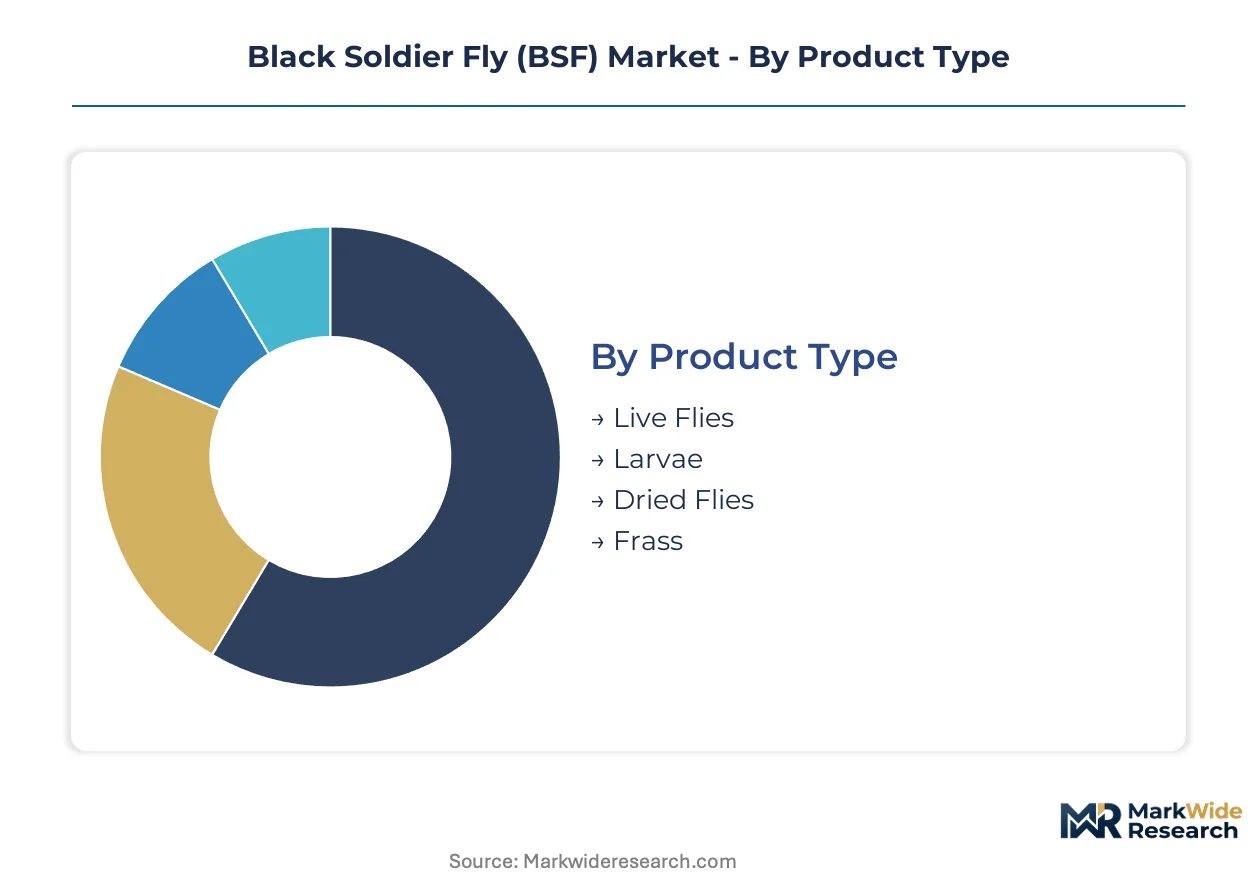
BSF market segmentation reveals how substrate handling capabilities, regulatory authorization boundaries, and buyer protein specifications determine facility configuration and margin capture. Each category isolates distinct procurement behaviors and technology deployment patterns across the value chain.
Product Type:
Buyers differentiate by shelf-life requirements, handling infrastructure, and downstream processing burden.
- Larvae:Fresh larvae contain 40-45% crude protein and 30-35% lipid by dry weight, serving as the primary feedstock for aquaculture and poultry diets. Demand concentrates in the Netherlands, where compound feed mills require consistent larval biomass for protein meal production, constrained by perishability logistics and cold-chain availability.
- Frass:Larval excrement functions as organic fertilizer with nitrogen-phosphorus-potassium profiles competitive with conventional amendments. Agricultural distributors in Germany and France are scaling frass procurement for organic farming operations, driven by EU Green Deal circular economy mandates and carbon accounting frameworks.
- Live Flies:Breeding stock for colony establishment and genetic refreshment in closed-loop facilities.
- Dried Flies:Long-shelf-life format for specialized research and niche feed applications.
Larvae leads volumes today; frass is gaining share fastest.
End User:
Procurement scale and certification requirements separate institutional buyers from specialty formulators.
- Feed Industry:Compound feed mills demand certifiable protein consistency with batch-level amino acid profiling. Aquaculture feed compounders in Denmark and Norway are consolidating supplier relationships around vertically integrated processors capable of multi-year offtake agreements.
- Pet Food:Manufacturers across North America and Europe reformulate with insect-derived alternatives to fishmeal and soy protein concentrates, requiring novel food registration and clean-label positioning.
- Agriculture:Crop producers source frass for soil amendment and larval biomass for direct animal feeding in non-regulated jurisdictions.
- Waste Management:Municipal and industrial waste operators deploy BSF bioconversion for organic diversion compliance and tip fee reduction.
Feed Industry anchors procurement volumes; Pet Food climbs the fastest.
Technology:
Capital intensity and substrate flexibility determine facility economics and geographic deployment.
- Bioconversion:Controlled-environment rearing of Hermetia illucens on organic waste streams, capturing 40-45% protein conversion efficiency. Industrial-scale plants in the Netherlands deploy automated climate-controlled systems that compress labor intensity and enable 24-hour larval density optimization.
- Anaerobic Digestion:Co-location with waste-to-energy infrastructure reduces input cost volatility and disposal liabilities. Integrated facilities in Belgium and Germany monetize biogas alongside protein output.
- Fermentation:Pre-treatment of substrates to enhance larval digestibility and accelerate biomass accumulation.
- Composting:Low-capital alternative for small-scale operations with limited protein purity requirements.
Bioconversion dominates capital deployment; anaerobic digestion co-location expands most quickly.
Application:
Margin structure and regulatory pathway complexity separate commodity outputs from premium streams.
- Protein Supplement:Defatted larval meal replaces fishmeal and soy in aquaculture, poultry, and pet food formulations. EFSA authorization under EU Novel Food frameworks is unlocking poultry and pig feed applications previously restricted to aquaculture.
- Organic Fertilizer:Frass sales to organic farming operations benefit from EU Green Deal alignment and waste diversion credit monetization.
- Biopesticide:Chitin-derived crop protection products with antimicrobial and antifungal properties.
- Nutraceuticals:Pharmaceutical-grade protein and lipid fractions for biomedical and cosmetic applications commanding margin premiums above commodity feed outputs.
Protein Supplement leads revenue today; Nutraceuticals shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands pioneered industrial-scale Black Soldier Fly bioconversion, establishing the regulatory and operational template that competitors now replicate across three continents. Facility investments have since diffused to Southeast Asian integrated operations and North American pet food supply chains. Each geography now cultivates distinct competitive advantages shaped by substrate access, regulatory authorization timelines, and downstream buyer concentration.
Netherlands
Dutch compound feed mills drive larval biomass procurement for protein meal production, with demand anchored by aquaculture and poultry formulators seeking fishmeal alternatives. EFSA jurisdiction under EU Novel Food frameworks authorized insect protein in pig and poultry feed, compressing product registration timelines relative to neighboring jurisdictions. Protix B.V. and InnovaFeed SAS operate industrial-scale bioconversion plants in the southern Netherlands, serving multi-year offtake contracts with major feed groups.
Malaysia
Integrated breeding-to-drying operations exploit lower-cost organic waste substrates and reduced regulatory complexity for export-oriented protein production. The country's national food safety regulator maintains alignment with Codex standards while permitting faster facility commissioning than EU jurisdictions. Nutrition Technologies Group anchors Southeast Asian supply from Malaysian facilities, leveraging integrated operations that span larval rearing through defatted meal output.
United States
Pet food manufacturers across the Midwest and Pacific Coast reformulate with BSF-derived alternatives to fishmeal and soy protein concentrates, awaiting definitive AAFCO ingredient definitions. FDA enforcement discretion letters provide interim market access, though pending regulatory clarity delays poultry feed adoption relative to European timelines. EnviroFlight, LLC represents early-mover positioning in the North American supply chain, with production geography reflecting proximity to organic waste streams and pet food formulator clusters.
France
Agricultural distributors scale frass procurement for organic farming operations, driven by EU Green Deal circular economy mandates and carbon accounting frameworks. REACH compliance and CE marking requirements shape equipment import decisions, with French facilities increasingly sourcing bioreactor systems from EU-based fabricators to bypass verification delays. InnovaFeed SAS maintains pharmaceutical-grade protein specialization alongside commodity feed outputs from its northern French operations.
Vietnam
Waste management operators deploy bioconversion for organic diversion compliance and tip fee reduction, with larval output supplying regional aquaculture feed compounders. The Ministry of Agriculture and Rural Development maintains permissive regulatory stance on insect protein in animal feed, enabling faster pilot-to-commercial scaling than jurisdictions with novel food authorization requirements. Entobel Holdings Pte. Ltd. and Entofood Sdn Bhd anchor Mekong Delta production clusters serving domestic aquaculture and export markets.
Black Soldier Fly (BSF) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification grade and downstream application complexity. The vendor base organizes into three tiers: pharmaceutical-grade protein specialists, vertically integrated feed-grade processors, and equipment-technology licensors. Market structure reflects early-stage consolidation around multi-year offtake agreements, with spot-market purchasing retreating to smaller agricultural and research applications. Dominant competitive moves include capacity expansion in underpenetrated geographies and strategic partnerships between bioconversion operators and compound feed mills.
Among European bioconversion specialists, Protix B.V., InnovaFeed SAS, and Bioflytech S.L. occupy positions across the premium-to-commodity margin spectrum. Protix B.V. exemplifies the vertically integrated archetype with captive breeding-through-processing operations. InnovaFeed SAS represents dual-stream positioning spanning pharmaceutical-grade and commodity feed outputs. Bioflytech S.L. anchors Spanish production capacity with regional substrate access advantages. Southeast Asian competition clusters around Nutrition Technologies Group and Entobel Holdings Pte. Ltd., reflecting integrated breeding-to-drying configurations optimized for export protein supply. North American participation centers on EnviroFlight, LLC, representing early-mover positioning pending regulatory authorization expansion.
| Leading Market Players |
|---|
| Nutrition Technologies Group |
| Entobel Holdings Pte. Ltd. |
| Protix B.V. |
| SFly Comgraf SAS |
| Entofood Sdn Bhd |
| InnovaFeed SAS |
| Bioflytech S.L. |
| Hexafly |
| EnviroFlight, LLC |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical-grade protein certification creates a three-tier pricing structure across premium, standard, and economy levels that compresses procurement decisions at compound feed mills while pulling equipment sourcing toward EU-based fabricators in the Netherlands and France. This certification ladder shapes both margin capture for bioconversion operators and geographic deployment of breeding-to-drying capacity.
Pricing Analysis
Contract-based long-term offtake agreements dominate volume procurement, with price differentiation resting on EFSA Novel Food authorization tier and batch-level amino acid profiling precision. Cost compression in commodity feed-grade streams intensifies as Malaysian and Vietnamese facilities exploit lower organic waste substrate costs. Pet food manufacturers in North America show highest price sensitivity due to pending AAFCO ingredient definitions, while pharmaceutical-grade buyers in France accept premium positioning for biomedical applications.
Supply Chain Analysis
Regional distribution centers in the Netherlands, Malaysia, and Vietnam anchor hub-and-spoke patterns serving compound feed mills and pet food formulators. Raw material dependencies center on organic waste substrate quality, automated climate-controlled rearing systems, and defatted meal processing equipment. Single-source vulnerability concentrates in Dutch industrial-scale bioconversion capacity. Distribution runs through vertically integrated processors capable of certifiable protein consistency rather than spot-market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Black Soldier Fly bioconversion hinges on automated climate-controlled rearing systems that compress labor intensity while unlocking pharmaceutical-grade certification premiums.
For Market Incumbents: Anchor multi-year offtake relationships with aquaculture feed compounders in Denmark and Norway through guaranteed batch-level amino acid profiling. Deepen upstream control over organic waste substrate streams in the Netherlands to mitigate seasonal quality volatility. Invest in EFSA Novel Food authorization maintenance as regulatory friction in the United States delays competitive entry. For New Entrants and Emerging Players: Enter via underpenetrated Southeast Asian production clusters in Vietnam's Mekong Delta, where the Ministry of Agriculture maintains permissive regulatory stance on insect protein. Target waste management operators seeking organic diversion compliance and tip fee reduction as anchor customers. Pursue integrated breeding-to-drying configurations optimized for export protein supply rather than domestic spot sales. For Investors and Strategic Acquirers: Consolidation pressure builds where entomology talent scarcity outpaces academic program output and automated rearing technology gaps separate scaled operators from pilot-stage competitors. Long-term viability favors vertically integrated processors with captive breeding-through-processing operations and multi-jurisdiction regulatory approvals. Watch for EFSA authorization expansion into additional livestock categories as inflection indicator for European capacity valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Climate-Controlled Rearing Scale-Up | Compresses labor intensity and enables 24-hour larval density optimization previously unattainable in manual Dutch operations. |
| EFSA Novel Food Authorization Expansion | Unlocks poultry and pig feed applications beyond aquaculture, reshaping procurement at compound feed mills. |
| Anaerobic Digestion Co-Location | Reduces input cost volatility and monetizes biogas alongside protein output in Belgian and German integrated facilities. |
| Pharmaceutical-Grade Protein Stream Development | Commands margin premiums above commodity feed outputs through biomedical and cosmetic application certification. |
| EU-Based Equipment Fabricator Partnerships | Bypasses REACH compliance verification delays and CE marking bottlenecks for French and German facility commissioning. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with bioconversion facility operators, compound feed mill procurement directors, pet food formulator R&D heads, and EFSA regulatory affairs specialists with secondary validation. Bottom-up larval production capacity estimates triangulated against top-down protein meal demand projections from customs records, EU feed industry association reports, and aquaculture feed compounder procurement disclosures.
Segment-weighting approaches modeled bioconversion technology deployment, anaerobic digestion co-location adoption, and pharmaceutical-grade certification penetration across the projection horizon. CAGRs derived from facility commissioning timelines, regulatory authorization trajectories, and buyer reformulation pace in pet food and aquaculture verticals. Forecast inputs incorporated organic waste substrate availability seasonality and entomology talent pipeline constraints.
Inputs from facility operators and feed mill procurement directors were available through the study window; gaps in pre-commercial pharmaceutical-grade production data introduce uncertainty bands around nutraceutical application forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Insect-Based Pet Food Market
Alternative Food Sources
Algae Products Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Organic Gluten Substitutes Market
Alternative Food Sources
Edible Packaging Market
Alternative Food Sources
Europe Upcycled Food Products Market
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
Plant-Based Compound Feed Market
Alternative Food Sources
Flour Substitutes Market
Alternative Food Sources
Fungal Protein Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Bagasse Disposable Cutlery Market
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Upcycled Food Products Market