
 Soy Leghemoglobin Market | 2026-2036
Soy Leghemoglobin Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Leghemoglobin Market Analytics
GRAS self-affirmation and FDA consultation pathways is reorganizing competitive access in the soy leghemoglobin space, determining which suppliers can serve U.S. food manufacturers. Impossible Foods Inc. leverages captive biomanufacturing infrastructure to secure consistent heme protein output for its own product lines. Creative BioMart specializes in recombinant protein expression systems that third-party brands access for formulation development. Genscript Biotech Corporation anchors Asian supply chains through its mammalian and microbial production platforms.
Soy leghemoglobin is a heme-containing protein extracted from nitrogen-fixing root nodules of Glycine max or produced via precision fermentation of Pichia pastoris, delivering the color, aroma, and cooking chemistry of animal-derived myoglobin to plant-based formulations. The ingredient typically contains a protoporphyrin IX iron complex at its active center, enabling Maillard browning and metallic flavor release under thermal stress. Powder and liquid product types capture diverging margin pools, with powder commanding premium positioning in shelf-stable ingredient portfolios while liquid concentrates integrate directly into continuous manufacturing lines for meat alternatives. Application concentration in meat alternatives reflects both formulation complexity and the segment's volume pull from quick-service restaurant supply contracts.
FDA oversight of color additives and USDA-FSIS jurisdiction over meat alternative labeling create a dual-track compliance environment that shapes product positioning and marketing claims. REACH registration requirements in Europe and China's NMPA novel food ingredient rules add cross-border complexity for suppliers seeking multi-region distribution. Stakeholders must monitor how novel protein regulatory precedents in the United States and European Union diverge, as these frameworks will determine which production technologies achieve scalable market access without reformulation mandates.

Market Dynamics
Precision fermentation capacity expansion is fragmenting the soy leghemoglobin supplier base, as food-grade biomanufacturing infrastructure scales beyond pharmaceutical-grade origins and enables new entrants to bypass traditional extraction economics.
Growth Catalysts
- GRAS pathway maturation:FDA consultation frameworks for novel proteins are clarifying entry requirements, reducing regulatory uncertainty for fermentation-derived heme suppliers targeting U.S. food manufacturers.
- Quick-service restaurant procurement:Plant-based meat supply contracts with major QSR chains are creating volume anchors that justify dedicated bioreactor capacity investments.
- Pichia pastoris strain optimization:Advances in yeast expression systems are improving heme protein yields per fermentation run, compressing unit economics toward commodity protein parity.
Market Restraints
- Dual-jurisdiction compliance costs:FDA color additive petitions combined with USDA-FSIS labeling reviews create sequential approval timelines that extend time-to-revenue for new market entrants.
- Feedstock price volatility:Sugar and nitrogen source costs for precision fermentation fluctuate with agricultural commodity markets, squeezing margin stability at scale.
- Extracted heme substitution:Animal-free myoglobin from other plant sources and synthetic heme analogs threaten to commoditize the functional attribute that soy leghemoglobin currently commands premium positioning for.
Strategic Opportunities
- European novel food authorization:EFSA's evolving stance on precision fermentation proteins creates first-mover positioning for suppliers achieving regulatory clearance under EU novel food regulations.
- Clean-label convergence:Formulation demand for single-ingredient heme solutions without synthetic additives aligns with retailer and consumer preference shifts in premium meat alternative segments.
- Bioreactor-as-a-service models:Contract manufacturing organizations with spare pharmaceutical-grade capacity are repurposing assets for food-grade protein production, lowering capital barriers for brand entrants.
Industry Challenges
- Fermentation scale-up expertise scarcity:Food-grade bioprocess engineers with experience in 100,000+ liter runs remain concentrated in pharmaceutical and industrial enzyme sectors, creating recruitment bottlenecks.
- Downstream purification capex:Chromatography and filtration systems required for food-grade heme isolation demand capital commitments that strain mid-tier supplier balance sheets.
- Label claim substantiation timelines:Nutritional equivalence studies and sensory validation protocols required for "meaty" marketing claims extend product development cycles beyond typical CPG windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Leghemoglobin Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Dry, Liquid, Powder Application: Meat Alternatives, Sauces, Snacks, Ready-to-Eat Meals End User: Food Manufacturers, Restaurants, Retailers, Home Cooks Distribution Channel: Online, Supermarkets, Health Food Stores, Wholesale |
| Companies Covered | Impossible Foods Inc., Abcam plc, Creative BioMart, Promega Corporation, BioVision Inc., Enzo Life Sciences, Genscript Biotech Corporation, Novus Biologicals, Rockland Immunochemicals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Leghemoglobin Market Evolving Landscape
Biomanufacturing technology diffusion and regulatory pathway clarification are converging to reshape competitive entry economics. Three developments warrant particular attention for their structural implications.
Continuous fermentation systems are fragmenting the traditional batch-production paradigm that has dominated recombinant protein manufacturing. Mid-scale food ingredient suppliers are adopting perfusion bioreactor designs originally developed for biopharmaceuticals, enabling steady-state heme protein output with higher volumetric productivity. This technology shift is compressing the minimum efficient scale for viable entry, allowing regional suppliers to achieve cost competitiveness without billion-liter capacity commitments.
REACH registration requirements in Europe are forcing reformulation strategies for suppliers seeking multi-region distribution. ECHA's evolving guidance on enzyme and protein classifications is creating compliance precedents that affect labeling, safety data sheet formatting, and downstream user communication obligations. Suppliers with existing pharmaceutical regulatory experience are adapting documentation systems faster than pure-play food ingredient entrants, creating asymmetric compliance capabilities.
Direct supplier-brand relationships are displacing traditional ingredient distributor networks in heme protein procurement. Large meat alternative manufacturers are establishing captive supply agreements or equity partnerships with fermentation operators, bypassing broadline food ingredient distributors that lack technical service depth for novel proteins. This channel restructuring is most visible in North American food processing corridors where plant-based meat production clusters have matured.
Soy Leghemoglobin Market Segmentation

Soy leghemoglobin procurement patterns diverge sharply across product formats and end-use channels. Formulation requirements from plant-based meat manufacturers versus retail ingredient brands create distinct demand profiles that reshape supplier priorities.
Product Type:
Channel flow patterns separate commodity-scale liquid deliveries from premium powder allocations through ingredient distributors. Frozen and dry formats serve diverging supply chain temperature requirements.
- Liquid:Continuous manufacturing lines for meat alternatives integrate liquid soy leghemoglobin directly via tanker or tote delivery. Quick-service restaurant supply contracts in the United States drive volume concentration here, with fermentation operators investing in dedicated liquid filling infrastructure to capture food manufacturer procurement.
- Powder:Spray-dried heme protein isolates achieve extended shelf stability through moisture reduction below 5%. Premium positioning in North American health food retail and European specialty ingredient portfolios supports margin capture, though downstream reconstitution adds formulation complexity for smaller food manufacturers.
- Frozen:Blast-frozen concentrates preserve heme protein activity for regional meat processors lacking liquid handling infrastructure.
- Dry:Lyophilized formats serve research-scale formulation development and niche clean-label applications requiring minimal processing aids.
Liquid dominates installed base. Powder is where expansion concentrates.
Application:
Cost tiers separate high-volume meat alternative formulations from lower-unit-value sauce and snack integrations. Application complexity determines heme concentration requirements and corresponding supplier technical service intensity.
- Meat Alternatives:Plant-based burger, sausage, and ground meat formulations require heme concentrations of 0.5-2% by weight to achieve Maillard browning and metallic flavor release. FDA color additive petitions for heme protein in simulated meat products create regulatory entry barriers that concentrate demand among GRAS-affirmed suppliers with established U.S. market access.
- Sauces:Gravy, broth, and umami-enhancing sauce applications utilize lower heme loadings for color modulation rather than primary protein structure. Asian fermented sauce manufacturers in China and South Korea represent emerging demand centers as NMPA and MFDS novel food frameworks clarify.
- Snacks:Extruded and baked snack applications face thermal degradation challenges that limit heme protein functionality.
- Ready-to-Eat Meals:Refrigerated and frozen prepared meals incorporate heme for visual appeal in plant-based protein components.
Meat alternatives anchor supplier revenue. Sauces are climbing the fastest.
End User:
Customer type determines order minimums, technical service requirements, and regulatory documentation depth. Volume concentration versus margin capture tradeoffs shape supplier account prioritization.
- Food Manufacturers:Integrated plant-based meat companies and contract manufacturers drive bulk procurement through direct supplier relationships. These buyers demand batch consistency certificates, allergen management protocols, and USDA-FSIS label review support that strains mid-tier supplier quality systems.
- Restaurants:Quick-service chains and fast-casual operators source through approved ingredient distributors with food safety certification. Procurement concentrates among chains with dedicated plant-based menu lines where heme protein differentiation supports premium pricing.
- Retailers:Private label development teams at specialty grocers and conventional supermarkets seek turnkey ingredient solutions.
- Home Cooks:Direct-to-consumer heme protein remains negligible due to formulation complexity and dosage precision requirements.
Food manufacturers dominate installed base. Restaurants are where expansion concentrates.
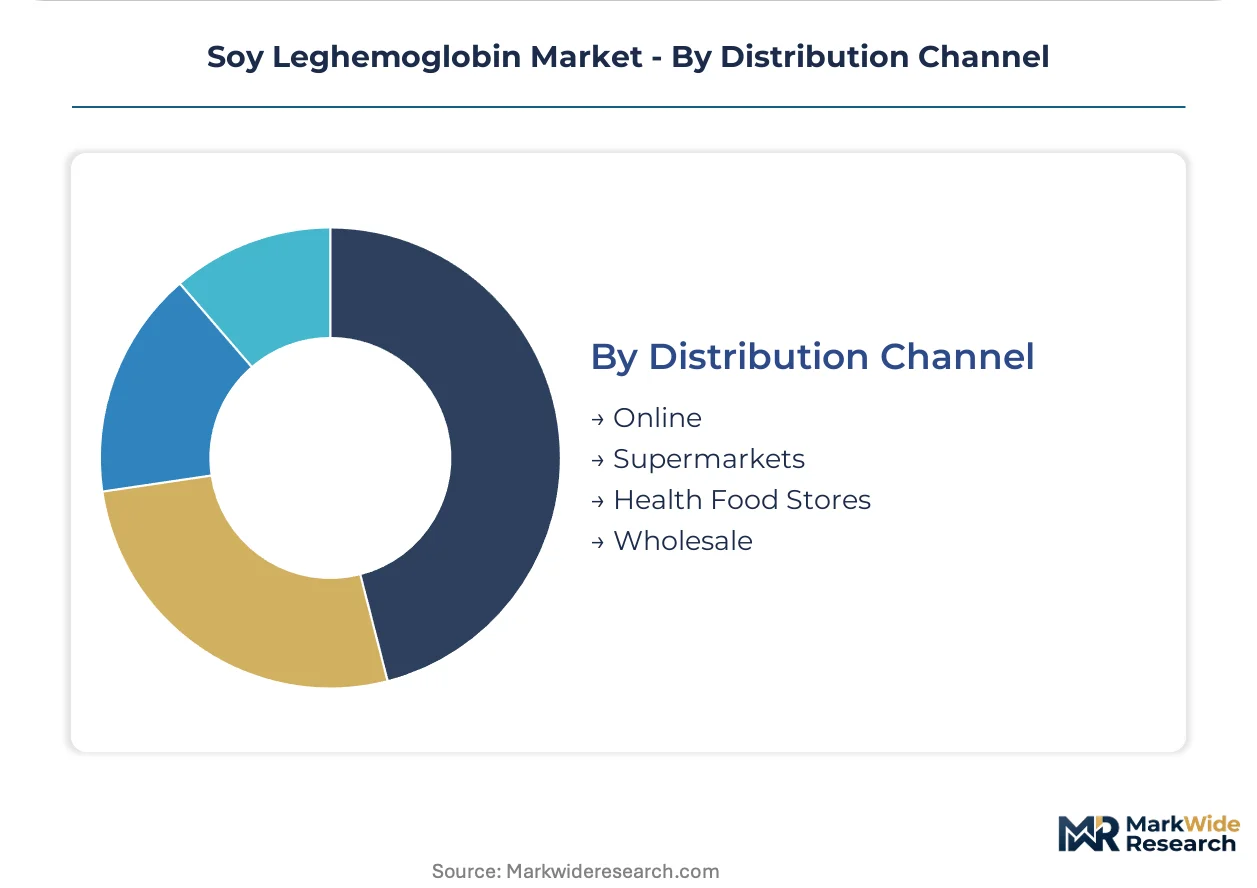
Distribution Channel:
Supply concentration varies by channel control—direct supplier relationships versus distributor intermediation reshape margin capture and technical service delivery.
- Wholesale:Broadline food ingredient distributors with temperature-controlled warehousing and technical sales teams capture meat alternative manufacturer procurement in clustered production regions. These channels consolidate smaller food manufacturer demand that lacks direct supplier minimums.
- Online:B2B ingredient marketplaces and supplier-direct portals serve formulation development samples and small-batch procurement. Research-scale buyers in university and corporate R&D settings favor online channels for rapid sourcing without distributor account establishment.
- Supermarkets:Retail ingredient aisles for consumer packaged heme protein remain underdeveloped.
- Health Food Stores:Specialty retail carries limited SKUs targeting clean-label home formulation enthusiasts.
Wholesale dominates installed base. Online is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA consultation pathways and USDA-FSIS labeling frameworks in the United States create regulatory precedents that shape multi-region market access strategies for precision fermentation suppliers.
United States
Quick-service restaurant supply contracts drive heme protein procurement volumes in clustered meat alternative production corridors. FDA color additive petitions for soy leghemoglobin in simulated meat products establish compliance benchmarks that fermentation operators must satisfy before commercial distribution. California and Illinois food processing hubs concentrate plant-based meat manufacturing capacity where direct supplier relationships displace traditional distributor networks.
Germany
EFSA novel food authorization processes determine which precision fermentation suppliers achieve European market entry for heme protein ingredients. REACH registration requirements for enzyme and protein classifications create documentation obligations that favor suppliers with pharmaceutical regulatory experience. Bavaria and North Rhine-Westphalia anchor German food ingredient distribution infrastructure where clean-label formulation demand supports premium positioning for spray-dried heme isolates.
China
NMPA novel food ingredient rules govern heme protein market access for fermentation-derived additives in domestic meat alternative formulations. Dual carbon policy targets accelerate investment in biomanufacturing capacity as lower-carbon protein production alternatives. Yangtze River Delta biotech clusters concentrate precision fermentation expertise where mammalian and microbial production platforms serve regional sauce and seasoning manufacturers.
South Korea
MFDS novel food frameworks clarify regulatory pathways for heme protein integration in fermented sauce and umami-enhancing applications. Government biotechnology investment programs support domestic fermentation capacity expansion for food-grade protein production. Seoul Capital Area food manufacturers drive formulation development demand where research-scale procurement concentrates among university and corporate R&D facilities.
Netherlands
ECHA guidance on protein classifications shapes safety data sheet and labeling compliance for heme protein suppliers seeking European distribution. Randstad logistics infrastructure enables temperature-controlled warehousing for liquid heme concentrates serving meat alternative manufacturers. Eindhoven Region bioprocess engineering expertise supports perfusion bioreactor adoption that compresses minimum efficient scale for regional fermentation operators.
Soy Leghemoglobin Market Competitive Landscape
Player mix skews toward integrated food manufacturers with captive biomanufacturing capacity alongside specialized recombinant protein suppliers serving third-party formulation development. Market structure concentrates among GRAS-affirmed operators with established FDA consultation histories and emerging fermentation entrants leveraging contract manufacturing partnerships. Two strategic archetypes dominate: vertically integrated plant-based meat companies controlling proprietary heme supply chains, and independent protein expression specialists licensing platform technologies to brand entrants. Capacity expansion and direct supplier-brand relationships constitute the primary competitive moves reshaping procurement channel structures.
Within the integrated manufacturer tier, Impossible Foods Inc. exemplifies captive biomanufacturing strategies that secure consistent heme protein output for proprietary product lines. Among independent expression specialists, Creative BioMart and Genscript Biotech Corporation occupy positions representing recombinant protein platform access for third-party brands seeking formulation development partnerships. These companies anchor competitive dynamics where technical service depth and regulatory documentation capabilities determine supplier selection criteria for meat alternative manufacturers.
| Leading Market Players |
|---|
| Impossible Foods Inc. |
| Abcam plc |
| Creative BioMart |
| Promega Corporation |
| BioVision Inc. |
| Enzo Life Sciences |
| Genscript Biotech Corporation |
| Novus Biologicals |
| Rockland Immunochemicals Inc. |
| Others |
Value Network & Pricing Analysis
Bioreactor scale economies at 100,000+ liter runs concentrate cost competitiveness among fermentation operators with dedicated food-grade infrastructure, compressing price floors for liquid heme concentrates while powder formats retain premium positioning through spray-drying capex barriers.
Pricing Analysis
Certification level (FDA GRAS-affirmed versus self-affirmed) creates the primary spread between heme protein tiers, with validated suppliers commanding 15-25% premia over emerging entrants lacking consultation history. Three-tier pricing structure across pharmaceutical-grade, food-grade certified, and research-grade heme isolates reflects downstream documentation depth and batch consistency protocols. Cost compression in standard-grade liquid concentrates is intensifying because contract manufacturing organizations are repurposing spare pharmaceutical bioreactor capacity for food protein production. Quick-service restaurant procurement teams demonstrate highest price sensitivity due to volume scale and menu cost engineering pressures, while specialty retail ingredient buyers accept premia for clean-label powder formats with minimal processing aid declarations.
Supply Chain Analysis
Inventory lead times for liquid heme concentrates extend 6-10 weeks due to cold-chain fermentation scheduling and downstream purification bottlenecks, whereas spray-dried powder stocks turn faster through ambient warehousing. Supply concentrates in United States biotech corridors, Chinese Yangtze River Delta biomanufacturing clusters, and Dutch Randstad logistics hubs where temperature-controlled infrastructure supports heme protein stability. Feedstock dependencies draw from agricultural sugar streams, nitrogen sources, and specialized yeast expression media that fluctuate with commodity markets. Single-source vulnerability persists for Pichia pastoris master cell banks held by limited expression platform licensors. Distribution runs through direct supplier-brand relationships displacing traditional broadline food ingredient distributors in North American meat alternative manufacturing corridors.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated plant-based meat manufacturers with captive heme supply agreements, fragmenting procurement leverage for smaller food brands dependent on spot market access.
For Market Incumbents: Secure captive biomanufacturing capacity or exclusive fermentation partnerships to defend against contract manufacturing organization entrants repurposing pharmaceutical assets for food-grade heme production. Deepen GRAS affirmation documentation and FDA consultation histories to maintain regulatory moats as novel protein frameworks mature. Prioritize backward integration into Pichia pastoris strain optimization and perfusion bioreactor technology to compress unit economics toward commodity protein parity. For New Entrants and Emerging Players: Lead with European novel food authorization pathways where EFSA clearance creates first-mover positioning before regulatory frameworks fully crystallize. Target sauce and seasoning manufacturers in South Korea and China as the most penetrable application segment, where lower heme loadings reduce formulation complexity and MFDS/NMPA novel food rules are clarifying fastest. Pursue bioreactor-as-a-service partnerships with pharmaceutical CMOs to bypass capital-intensive capacity buildouts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors recombinant protein expression specialists with platform licensing revenue streams rather than single-product fermentation operators. Five-to-ten year viability hinges on regulatory pathway diversification across FDA, EFSA, and NMPA jurisdictions to reduce single-market dependency. Signal to monitor: EFSA novel food authorization timelines for precision fermentation proteins as inflection indicator for European market access economics.| Strategic Initiative | Industry Significance |
|---|---|
| GRAS Self-Affirmation to FDA Consultation | Formal FDA engagement establishes compliance benchmarks that QSR procurement teams require for supplier qualification. |
| Perfusion Bioreactor Adoption | Continuous fermentation technology from Eindhoven Region engineering clusters compresses minimum efficient scale for regional entrants. |
| Direct Supplier-Brand Partnerships | Bypassing broadline distributors captures margin and enables technical service depth for meat alternative formulation support. |
| EFSA Novel Food Authorization | European regulatory clearance creates asymmetric access before competitors navigate REACH protein classification requirements. |
| Backward Integration into Strain Development | In-house Pichia pastoris optimization reduces licensing costs and accelerates yield improvement cycles. |
Research Methodology
Operator-level perspectives from fermentation facility managers, plant-based meat formulation scientists, regulatory affairs directors at novel protein suppliers, and quick-service restaurant procurement leads anchored the qualitative base. Primary interview insights combined with secondary validation from FDA color additive petitions, EFSA novel food submissions, NMPA ingredient registrations, USDA-FSIS label review databases, and precision fermentation capacity announcements. Bottom-up volume modeling from identified bioreactor installations and top-down demand triangulation from meat alternative production forecasts cross-checked segmentation outputs.
Sensitivity analysis around regulatory approval timelines, feedstock cost assumptions, and biomanufacturing scale-up success rates informed scenario ranges across the projection horizon. Segmentation dimensions modeled include product format (liquid, powder, frozen, dry), application category (meat alternatives, sauces, snacks, ready-to-eat meals), end-user archetype (food manufacturers, restaurants, retailers), and regional regulatory cluster (FDA-led, EFSA-led, NMPA-led, MFDS-led). CAGRs derived from fitted growth curves accounting for technology diffusion patterns and procurement contract visibility. Industry-specific inputs encompassed Pichia pastoris yield improvement trajectories and QSR supply contract renewal cycles.
The analysis sits within stated boundaries; outcomes outside GRAS affirmation success, EFSA authorization timelines, or sustained QSR volume commitments would require recalibration. Forecasts reflect documented assumptions about regulatory pathway maturation and biomanufacturing scale economics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Bagasse Disposable Cutlery Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
Food Cultures Market
Alternative Food Sources
Meal Replacement Products Market
Alternative Food Sources
Low Carbs Vegan Food Market
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
Global Algae Market
Alternative Food Sources
Plant-Based Compound Feed Market
Alternative Food Sources
Fat Replacers Market
Alternative Food Sources
Insect-Based Pet Food Market
Alternative Food Sources
Bioengineered Food Market
Alternative Food Sources
Sugar Alternative Market
Alternative Food Sources
Artificial Meat Market
Alternative Food Sources
Algae Fats Market
Alternative Food Sources
Middle East and Africa Meal Replacement Products Market
Alternative Food Sources
Meal Replacement Bars Market