
 Food Cultures Market | 2026-2036
Food Cultures Market Size, Share, and Industry Trends Forecast 2026-2036
Food Cultures Market Intelligence
The capability gap between freeze-dried and liquid concentrate infrastructure is unwinding competitive dynamics among established suppliers. Chr. Hansen Holding A/S leverages its Danish R&D base to dominate dairy fermentation strain development. Kerry Group PLC anchors its position through backward integration into spray-dried culture production for bakery enhancement applications. DSM-Firmenich differentiates via aromatic culture portfolios targeting plant-based alternatives.
Food cultures comprise defined microbial strains—bacteria, yeasts, or molds—cultivated under controlled fermentation conditions, typically specified at 10^9 to 10^12 CFU per gram for commercial viability, and deployed to catalyze biochemical transformations in food matrices. Their primary commercial purpose centers on acidification, flavor biogenesis, texture modification, and shelf-life extension across processed food systems. Starter cultures command the largest revenue pool given their indispensability in cheese and yogurt manufacturing, while protective cultures represent the fastest-expanding category as phosphate-replacement pressures intensify in meat processing. Powdered form factors capture disproportionate margin pools due to logistics efficiency and extended ambient stability.
FDA oversight of GRAS self-affirmations and USDA FSIS labeling requirements shape culture deployment in U.S. meat and dairy channels, while EFSA novel food assessments and EU MDR-adjacent quality standards govern strain introductions in Europe. The EU F-Gas Regulation directly constrains lyophilization energy profiles, pushing producers toward renewable-powered freeze-drying or alternative stabilization chemistries. Stakeholders must monitor evolving strain-level intellectual property regimes and carbon-border adjustment mechanisms to preserve market access and cost competitiveness.
Market Dynamics
The EU F-Gas Regulation is forcing freeze-dried culture producers to abandon conventional lyophilization energy profiles, triggering a wholesale migration toward renewable-powered stabilization technologies and alternative chemistries that redefine production economics across European manufacturing clusters.
Growth Catalysts
- Clean-label dairy mandates:Food manufacturers across Germany, France, and the Netherlands are eliminating synthetic preservatives, creating sustained pull for phosphate-replacement protective cultures in processed cheese and yogurt systems.
- EU Green Deal decarbonization targets:Carbon-border adjustment mechanisms are accelerating capital deployment into renewable-powered fermentation infrastructure, favoring early movers with captive renewable energy supply.
- Artisanal cheese cluster densification:Protected designation of origin (PDO) expansion in Italy and Spain is multiplying small-batch culture demand for heritage strain preservation and controlled acidification protocols.
Market Restraints
- Lyophilization energy cost volatility:Natural gas price swings in European Union member states directly compress margins for freeze-dried powder producers dependent on thermal stabilization cycles.
- Strain IP concentration:Patent thickets around thermophilic starter cultures restrict new entrants from competing in high-volume mozzarella and Swiss-type cheese fermentation.
- Regulatory fragmentation:Divergent GRAS self-affirmation timelines between FDA and EFSA novel food pathways delay multi-territory product launches by 18-36 months.
Strategic Opportunities
- Plant-based dairy alternatives:Aromatic culture portfolios targeting oat, almond, and coconut fermentation matrices remain underdeveloped relative to animal-derived applications, opening formulation partnerships with alt-protein brands.
- Direct-to-artisan distribution platforms:E-procurement channels connecting small culture suppliers with farmhouse cheese producers in Denmark and Ireland are compressing traditional distributor markups.
- Carbon-negative fermentation:Anaerobic digestion integration with culture production facilities in the Netherlands qualifies producers for EU Innovation Fund subsidies while reducing scope 1-2 emissions.
Industry Challenges
- Phage resistance breeding timelines:Developing rotation-compatible starter culture strains requires 4-7 year R&D cycles that strain mid-tier R&D budgets and strain banking capabilities.
- Legacy dairy equipment retrofit costs:Installing precision fermentation controls in 1980s-era cheese vats across Italian cooperatives demands capital outlays that exceed available EU rural development grants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Cultures Market |
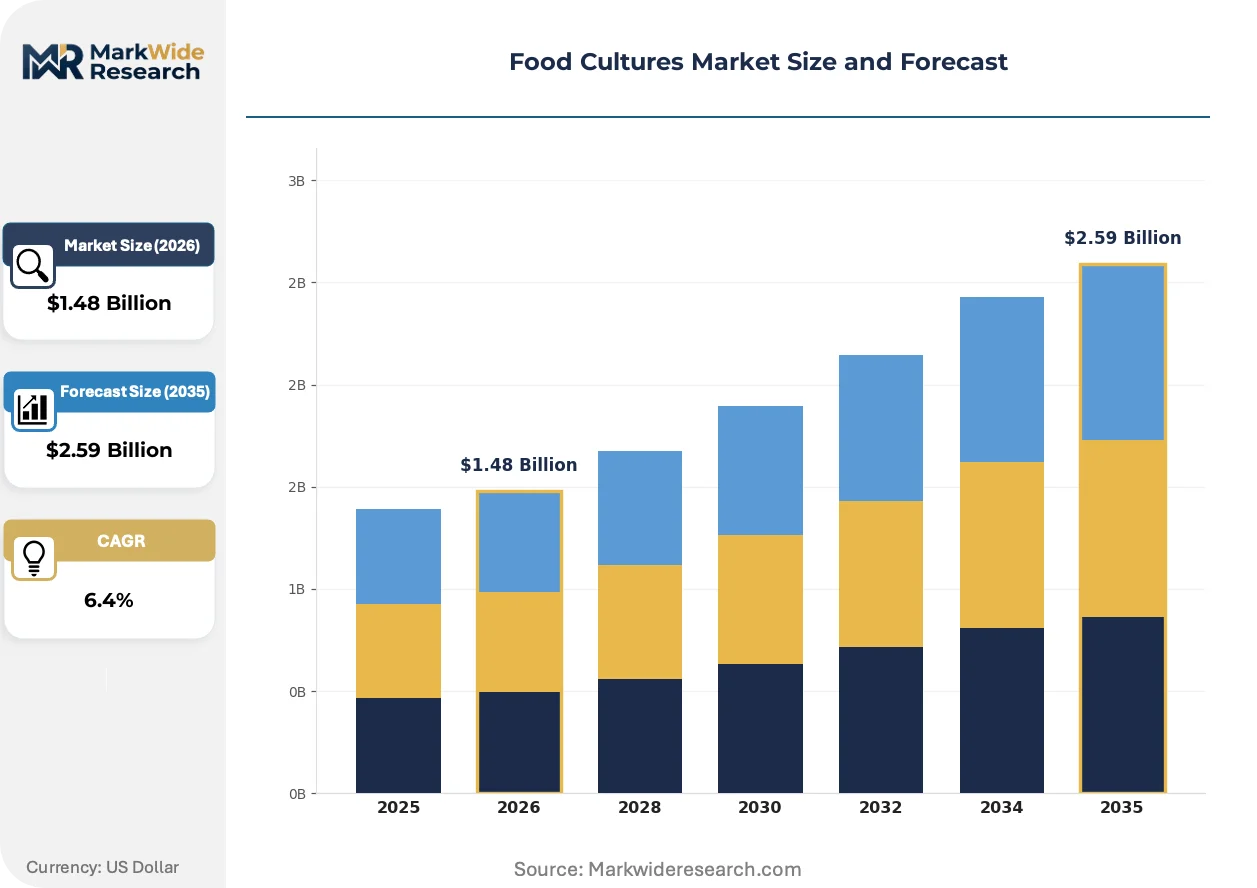
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $2.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotic Cultures, Starter Cultures, Adjunct Cultures, Protective Cultures, Aromatic Cultures Application: Dairy Fermentation, Meat Processing, Beverage Production, Bakery Enhancement, Plant-based Alternatives Form: Freeze Dried, Frozen, Liquid Concentrate, Spray Dried, Powdered End User: Food Manufacturers, Nutraceutical Companies, Research Institutions, Flavor Houses |
| Companies Covered | Corbion NV, Angel Yeast Co. Ltd., Chr. Hansen Holding A/S, CSK Food Enrichment B.V., Associated British Foods PLC, International Flavours & Fragrances Inc., DSM-Firmenich, Kerry Group PLC, Lallemand Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Cultures Market Strategic Shifts & Innovations
Bioprocess intensification and regulatory chemistry shifts are compressing traditional stabilization timelines while opening new formulation spaces for culture suppliers willing to reengineer their manufacturing footprints.
Single-use bioreactor systems equipped with online biomass sensors are displacing stainless steel batch fermentation in pilot-scale culture production. Specialty cheese manufacturers in the Netherlands and Denmark are adopting these modular platforms to shorten strain optimization cycles from months to weeks. This hardware transition is displacing centralized production economics, enabling distributed manufacturing closer to artisanal demand clusters.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is compelling freeze-drying operators to install mechanical vapor recompression or solid-state cooling alternatives. Industrial culture producers in Germany and France face 2027 compliance deadlines that require capital commitments exceeding EUR 5 million per lyophilization line. Powdered culture supply chains are responding by diversifying stabilization chemistries toward spray-dried and fluidized-bed alternatives with reduced cold-chain dependency.
Consolidated meat processors are unbundling protective culture procurement from phosphate ingredient bundles, creating direct supplier relationships that bypass traditional compound additive distributors. This disintermediation is most advanced in German and Polish sausage manufacturing, where private-label brands now specify strain-level performance guarantees rather than accepting generic "clean-label" claims. The shift compresses supplier margins while rewarding culture houses with documented antilisterial efficacy data and rapid custom formulation turnaround.
Food Cultures Market Segmentation
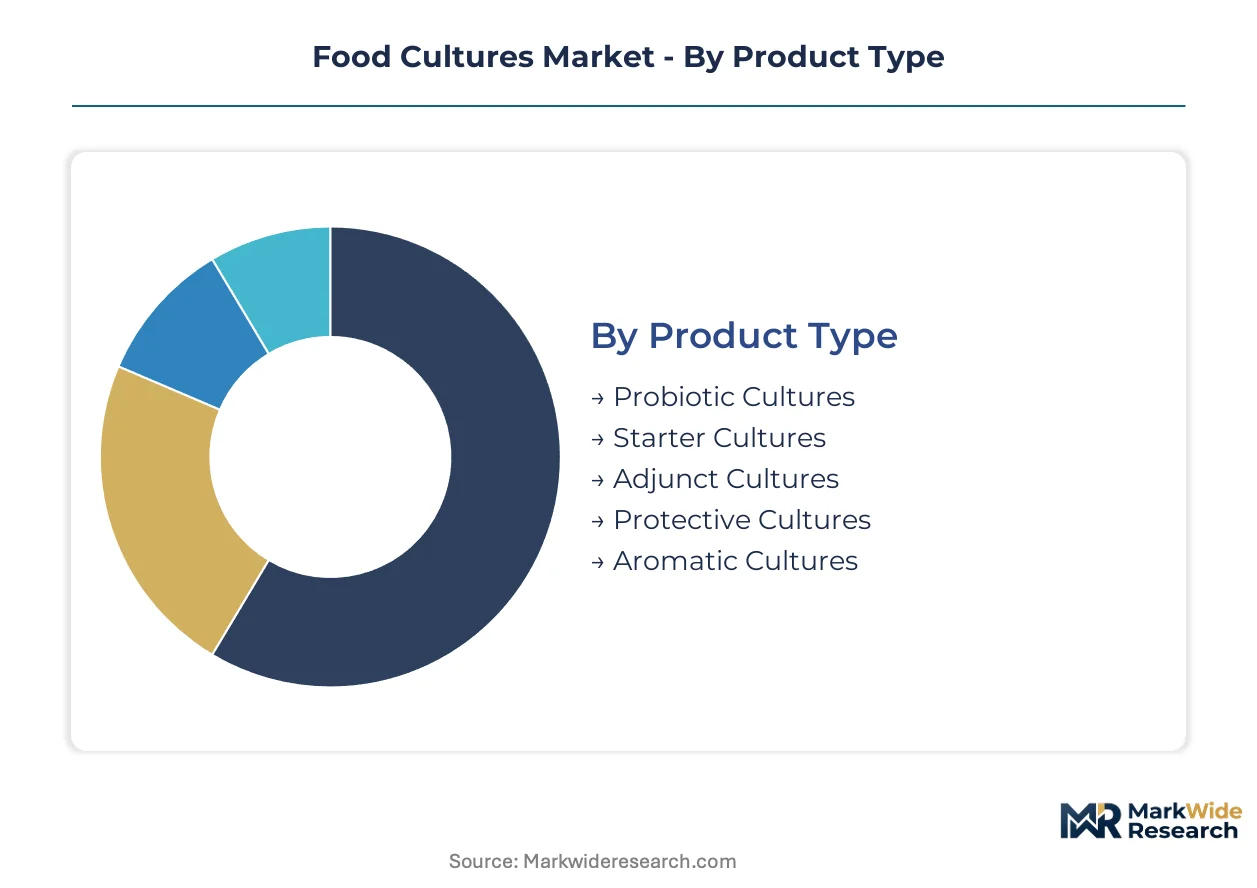
Segmentation in food cultures reveals how strain specialization, stabilization chemistry, and end-use certification requirements fragment procurement patterns across artisanal and industrial channels. Suppliers configure R&D pipelines and distribution networks around these divides rather than treating cultures as interchangeable commodities.
Product Type:
Geographic demand spread varies sharply across product types, with starter and protective cultures anchored in European dairy clusters while aromatic and probiotic strains serve export-led nutraceutical channels.
- Starter Cultures:Defined microbial consortia of thermophilic or mesophilic bacteria, typically Lactococcus, Streptococcus, or Lactobacillus species, specified at 10^9 to 10^12 CFU per gram for cheese and yogurt acidification. Demand concentrates in Germany, France, and the Netherlands where PDO cheese production requires heritage strain preservation and controlled fermentation protocols. Patent thickets around thermophilic strains restrict supplier competition in high-volume mozzarella manufacturing.
- Protective Cultures:Bacteriocin-producing strains such as Lactobacillus sakei or Pediococcus acidilactici deployed to inhibit Listeria and spoilage organisms in processed meats and dairy. German and Polish sausage manufacturers now specify strain-level antilisterial efficacy guarantees rather than accepting generic clean-label claims, compressing margins while rewarding documented performance.
- Probiotic Cultures:Clinically validated strains meeting EFSA health claim substantiation or FDA GRAS self-affirmation thresholds for gut health positioning. Regulatory divergence between FDA and EFSA novel food pathways delays multi-territory launches.
- Adjunct Cultures:Secondary fermentation strains added for flavor complexity acceleration or texture refinement in aged cheese systems. Italian cooperatives deploy these for Parmigiano-Reggiano and Grana Padano maturation.
- Aromatic Cultures:Yeast and mold strains selected for volatile compound biogenesis in specialty cheese and emerging plant-based dairy alternatives. Formulation partnerships with oat and almond milk processors remain underdeveloped relative to animal-derived applications.
Starter cultures hold the largest share; protective cultures are gaining share fastest as phosphate-replacement pressures intensify.
Application:
Cost tier differentiation separates commodity dairy fermentation from premium plant-based and nutraceutical applications requiring strain-level IP and clinical validation.
- Dairy Fermentation:Acidification and flavor biogenesis in cheese, yogurt, and fermented milk production. Clean-label mandates across German and French manufacturers are eliminating synthetic preservatives, pulling demand for phosphate-replacement protective cultures in processed cheese systems.
- Meat Processing:Biopreservation in fermented sausages, cooked ham, and ready-to-eat poultry. Carbon-border adjustment mechanisms are accelerating capital deployment into renewable-powered fermentation infrastructure for culture suppliers serving this channel.
- Beverage Production:Controlled fermentation in kombucha, kefir, and functional drink matrices. E-procurement channels connecting small suppliers with farmhouse producers are compressing traditional distributor markups.
- Bakery Enhancement:Sourdough starter propagation and shelf-life extension in artisanal and industrial bread systems. Backward integration into spray-dried culture production anchors supplier positioning here.
- Plant-based Alternatives:Aromatic culture portfolios targeting oat, almond, and coconut fermentation matrices for flavor masking and texture development. This segment climbs the fastest as alt-protein brands seek formulation partnerships.
Dairy fermentation commands the largest share; plant-based alternatives show the steepest expansion trajectory.
Form:
Volume concentration favors powdered and freeze-dried formats for logistics efficiency, while liquid concentrates serve regional artisanal clusters requiring rapid strain rotation.
- Freeze Dried:Lyophilized cultures with extended ambient stability and precise rehydration protocols. EU F-Gas Regulation compliance deadlines in Germany and France require capital commitments exceeding EUR 5 million per lyophilization line, reshaping supplier economics.
- Powdered:Spray-dried or fluidized-bed alternatives with reduced cold-chain dependency and disproportionate margin capture. Diversification toward these chemistries is accelerating as freeze-drying energy costs escalate.
- Liquid Concentrate:High-viability suspensions for direct vat inoculation in large-scale dairy operations. Capability gaps between freeze-dried and liquid infrastructure are unwinding competitive dynamics among established suppliers.
- Spray Dried:Rapid stabilization via atomization and hot-air drying, sacrificing some viability for cost efficiency in commodity applications. This format is displacing centralized production economics in pilot-scale operations.
- Frozen:Cryopreserved cultures for strain banking and specialized industrial applications requiring genetic stability. Distribution constraints limit this format to captive supply arrangements with major dairy cooperatives.
Powdered forms capture the largest share; spray-dried alternatives are expanding most quickly as producers abandon conventional lyophilization.
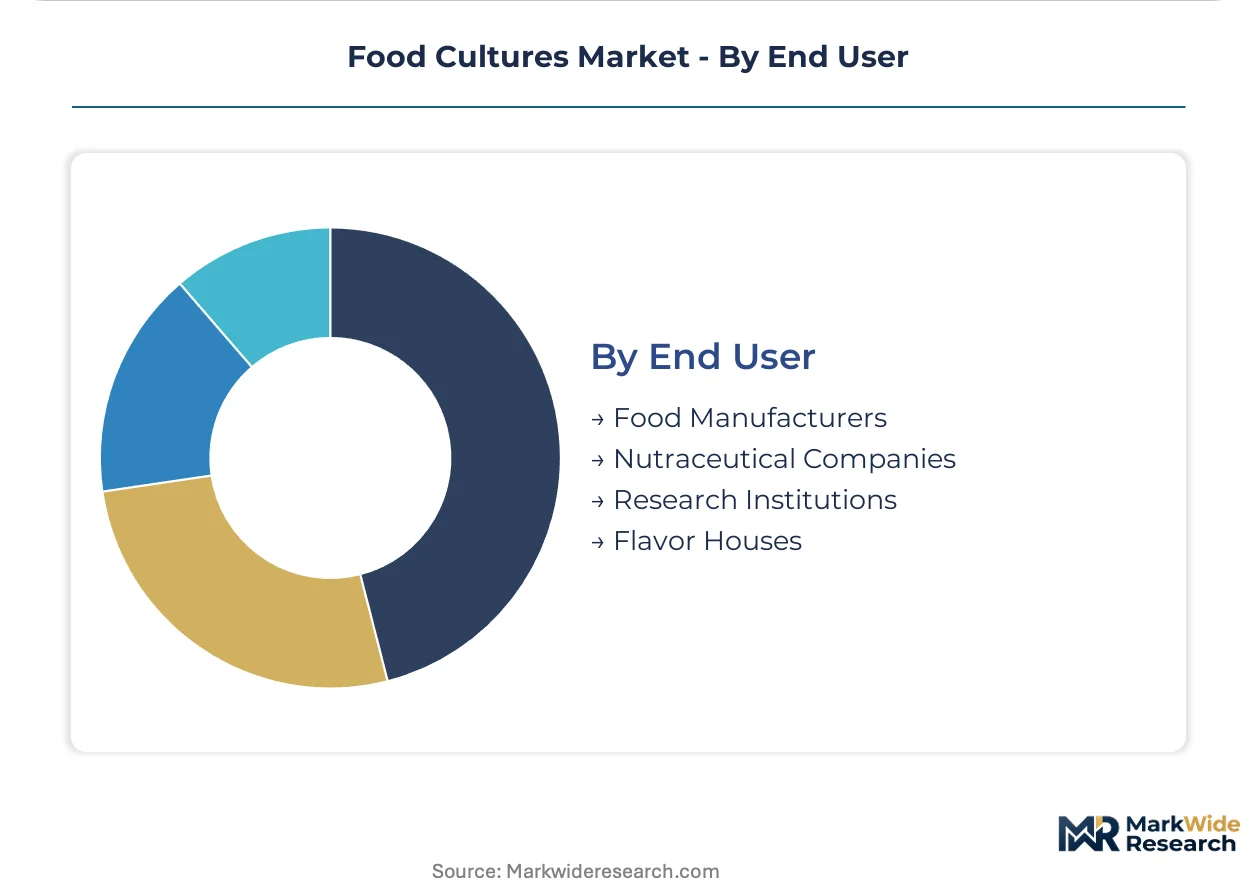
End User:
Customer type fragmentation separates price-sensitive commodity procurement from premium specification relationships requiring custom formulation turnaround and documented efficacy data.
- Food Manufacturers:Industrial dairy, meat, and bakery processors specifying strain performance guarantees and regulatory compliance documentation. Consolidated meat processors are unbundling protective culture procurement from phosphate ingredient bundles, creating direct supplier relationships.
- Nutraceutical Companies:Dietary supplement and functional food brands requiring clinically validated probiotic strains with EFSA or FDA substantiation. Novel food assessment timelines delay product launches.
- Flavor Houses:Aromatic culture sourcing for compounded flavor systems and clean-label taste modulation. These intermediaries face margin compression as end-users specify direct strain procurement.
- Research Institutions:Strain development, phage resistance breeding, and fermentation optimization programs. Four-to-seven-year R&D cycles for rotation-compatible starter strains strain mid-tier R&D budgets.
Food manufacturers hold the largest share; nutraceutical companies are gaining share fastest as clinical validation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for food cultures varies sharply across procurement tiers. Artisanal cheese producers in Denmark and Ireland absorb premium pricing for heritage strain preservation, while commodity dairy processors in Poland and Spain drive hard volume negotiations on standard starter cultures.
Germany
Sausage manufacturers in Lower Saxony and Bavaria now specify strain-level antilisterial efficacy guarantees for protective cultures, unbundling procurement from phosphate additive bundles. The EU F-Gas Regulation compels freeze-drying operators to install mechanical vapor recompression systems by 2027. Industrial culture production clusters around Frankfurt-Rhine-Main face capital commitments exceeding EUR 5 million per lyophilization line.
France
PDO expansion in Auvergne-Rhône-Alpes and Normandy multiplies small-batch demand for controlled acidification protocols in Comté and Camembert systems. EFSA novel food assessments govern probiotic strain introductions, delaying multi-territory launches against FDA timelines. Paris Basin dairy cooperatives retrofit 1980s-era cheese vats with precision fermentation controls.
Netherlands
Carbon-border adjustment mechanisms accelerate capital deployment into renewable-powered fermentation infrastructure. Anaerobic digestion integration with culture production facilities in Gelderland qualifies producers for EU Innovation Fund subsidies. Single-use bioreactor adoption concentrates in Noord-Brabant specialty cheese operations, shortening strain optimization cycles.
Italy
Emilia-Romagna cooperatives deploy adjunct cultures for Parmigiano-Reggiano and Grana Padano maturation acceleration. Rural development grants prove insufficient for legacy equipment retrofit costs across Lombardy and Piedmont artisanal clusters. Rome-based regulators enforce MDR-adjacent quality standards on strain banking documentation.
United States
Consolidated meat processors in Wisconsin and California establish direct supplier relationships for protective cultures, bypassing traditional compound additive distributors. FDA GRAS self-affirmations and USDA FSIS labeling requirements shape deployment in dairy and meat channels. Greater Boston nutraceutical companies demand clinically validated probiotic strains with substantiated health claims.
Food Cultures Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with Danish and Irish biotechnology groups commanding proprietary strain development pipelines while regional fermentation houses compete on custom formulation turnaround. The vendor base fragments across three strategic archetypes: heritage culture banks with deep strain libraries, dairy-integrated suppliers with captive demand, and plant-based formulation specialists. Consolidation pressures intensify as phosphate-replacement mandates force meat processors toward direct supplier relationships, while carbon-border mechanisms favor early movers with renewable energy supply.
Within the integrated biotechnology tier, Chr. Hansen Holding A/S and DSM-Firmenich exemplify archetypes built on aromatic culture portfolios and dairy fermentation strain dominance. Kerry Group PLC anchors a second archetype of backward-integrated ingredient houses with spray-dried production capabilities. These three occupy positions where regulatory chemistry shifts and F-Gas compliance deadlines reshape competitive economics, particularly for European manufacturing footprints facing 2027 stabilization technology transitions.
| Leading Market Players |
|---|
| Corbion NV |
| Angel Yeast Co. Ltd. |
| Chr. Hansen Holding A/S |
| CSK Food Enrichment B.V. |
| Associated British Foods PLC |
| International Flavours & Fragrances Inc. |
| DSM-Firmenich |
| Kerry Group PLC |
| Lallemand Inc. |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between freeze-dried culture suppliers and German sausage manufacturers lock in multi-year supply access while capping price volatility exposure against natural gas-driven lyophilization cost swings. These arrangements bundle strain performance guarantees with volume commitments, embedding EU F-Gas Regulation compliance costs into negotiated base rates rather than spot-market premiums.
Pricing Analysis
After-sales technical service and strain rotation advisory contracts generate disproportionate lifetime value relative to initial culture shipments. Three-tier pricing structure across premium, standard, and economy levels separates heritage PDO-certified strains from commodity thermophilic starters and generic protective blends. Pricing pressure stems from consolidated meat processors unbundling phosphate-replacement bundles and demanding direct supplier relationships. Artisanal cheese cooperatives in Denmark and Ireland exhibit lowest price sensitivity, while Polish commodity dairy processors drive hardest volume negotiations on standard starter cultures.
Supply Chain Analysis
Inbound logistics costs from Danish R&D centers to German manufacturing clusters hinge on cold-chain integrity across North Sea shipping lanes and Rhine-Ruhr distribution networks. Supply concentrates in Denmark, Germany, and the Netherlands for strain development and fermentation infrastructure, with raw material dependencies on specialized growth media, cryoprotectant chemistries, and sterile packaging formats. Single-source vulnerability around thermophilic starter strain IP creates supply concentration risk for high-volume mozzarella producers. Distribution runs through compound additive distributors in traditional channels, though direct-to-artisan e-procurement platforms are compressing intermediary margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strain-level intellectual property and phage resistance breeding capabilities constitute scarce assets that fragment competitive positioning between integrated biotechnology houses and mid-tier fermentation specialists. The gap between freeze-dried and liquid concentrate infrastructure widens as EU F-Gas deadlines force capital commitments exceeding mid-tier R&D budgets.
For Market Incumbents: Secure renewable-powered lyophilization capacity ahead of 2027 EU F-Gas compliance deadlines in Germany and France, locking in cost advantages against gas-dependent competitors. Deepen backward integration into spray-dried culture production to defend margin position as freeze-drying energy costs escalate. Patent thickets around thermophilic starter strains remain the priority defensive moat against emerging plant-based formulation specialists. For New Entrants and Emerging Players: Direct-to-artisan distribution platforms where incumbent culture houses under-serve small-batch farmhouse cheese producers in Ireland and Denmark offer the most penetrable white-space target. Formulation partnerships with oat and almond milk processors remain underdeveloped relative to animal-derived applications, opening rapid custom turnaround angles. Carbon-negative fermentation integration with anaerobic digestion qualifies for EU Innovation Fund subsidies while differentiating against legacy suppliers. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors early movers with captive renewable energy supply and compliant stabilization technology. Long-term viability over the coming decade hinges on strain banking depth and phage resistance R&D pipelines rather than commodity fermentation scale. Acquisition target archetype: mid-tier culture houses with documented antilisterial efficacy data and established artisanal relationships. Watch EU carbon-border adjustment mechanism implementation as the inflection signal for renewable infrastructure valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable-Powered Lyophilization Transition | EU F-Gas Regulation compliance secures market access against gas-dependent competitors in Germany and France. |
| Direct-to-Artisan Distribution Platform | E-procurement channels compress traditional distributor markups while capturing heritage strain demand in Denmark and Ireland. |
| Plant-Based Formulation Partnership | Aromatic culture portfolios for oat and almond fermentation open underdeveloped segments relative to dairy applications. |
| Phage Resistance Strain Banking | Rotation-compatible starter development requires 4-7 year R&D cycles that strain mid-tier competitor budgets. |
| Anaerobic Digestion Integration | Carbon-negative fermentation qualifies Dutch producers for EU Innovation Fund subsidies while reducing scope 1-2 emissions. |
Research Approach
Initial hypotheses were tested against primary input from culture production managers, dairy cooperative procurement leads, meat processor R&D directors, and regulatory affairs specialists at biotechnology houses, then refined against secondary validation. Data synthesis combined EFSA novel food assessment filings, EU F-Gas Regulation implementation guidance, customs trade records for fermentation equipment, and SEC filings from listed ingredient suppliers. Bottom-up strain demand modeling and top-down fermentation capacity assessments were triangulated to constrain forecast variance.
Variance decomposition across the projection horizon isolates volume drivers by product type, application end-use, stabilization chemistry, and customer tier segmentation dimensions. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs include PDO cheese production cluster densification in Italy and Spain, phosphate-replacement regulatory pressure in German and Polish meat processing, and renewable energy infrastructure deployment timelines in the Netherlands and Denmark.
Underlying assumptions cover sustained EU Green Deal decarbonization enforcement, stable GRAS self-affirmation and EFSA novel food pathway divergence, and continued artisanal cheese demand elasticity in heritage strain preservation markets, with deviation risk concentrated in natural gas price volatility for lyophilization energy inputs and phage outbreak frequency affecting starter culture rotation protocols. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Konjac Market
Alternative Food Sources
Vegetable Proteins Market
Alternative Food Sources
Gluten-Free Meat Substitutes Market
Alternative Food Sources
Flour Substitutes Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
Quinoa Protein Market
Alternative Food Sources
Meal Replacement Products Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
Single Cell Oil Market
Alternative Food Sources
Artificial Meat Market
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
Synthetic Food Market
Alternative Food Sources
Global Algae Market
Alternative Food Sources
Global Algae Protein Market
Alternative Food Sources
Mycoprotein Market