
 North America Potato Protein Market | 2026-2036
North America Potato Protein Market Size, Share, and Industry Trends Forecast 2026-2036
North America Potato Protein Market Analytics
Plant-based meat formulators is bifurcating demand away from legacy dairy protein buyers as clean-label formulation priorities shift across North American CPG kitchens. Royal Avebe anchors its position through backward integration into starch co-product streams in the Red River Valley. Kerry Group differentiates via flavor-masked isolate systems that reduce off-taste in high-inclusion meat analogues. Roquette Frères competes on pharmaceutical-grade hydrolysate capacity serving nutritional supplement contract manufacturers.
Potato protein comprises the albumin and globulin fractions extracted from potato juice, a co-product of starch manufacture, typically yielding 75-90% protein content in isolate form depending on precipitation method and dialfiltration steps. Its primary commercial purpose centers on emulsification, gelation, and foaming in food systems where allergen-free status and neutral flavor prove critical against soy and dairy alternatives. Isolate commands the dominant margin pool given its functional superiority in meat analogue extrusion, while concentrate sustains volume leadership in feed and lower-inclusion bakery applications. Powder form dominates logistics and shelf stability, though liquid hydrolysates are gaining traction in ready-to-drink nutritional formulations.
The FDA governs GRAS self-determination and food additive petitions for novel potato protein isolates entering the U.S. supply chain, while Health Canada and PMRA coordinate cross-border allergen threshold harmonization through the Canada-U.S. Regulatory Cooperation Council. USDA biobased procurement preferences and the FDA's draft guidance on fermented and cell-cultured protein labeling collectively steer investment toward transparent, domestically traceable supply streams. Stakeholders must monitor how state-level clean-label legislation in California and New York propagates ingredient disclosure burdens before committing to long-term isolate capacity expansions.
Market Dynamics
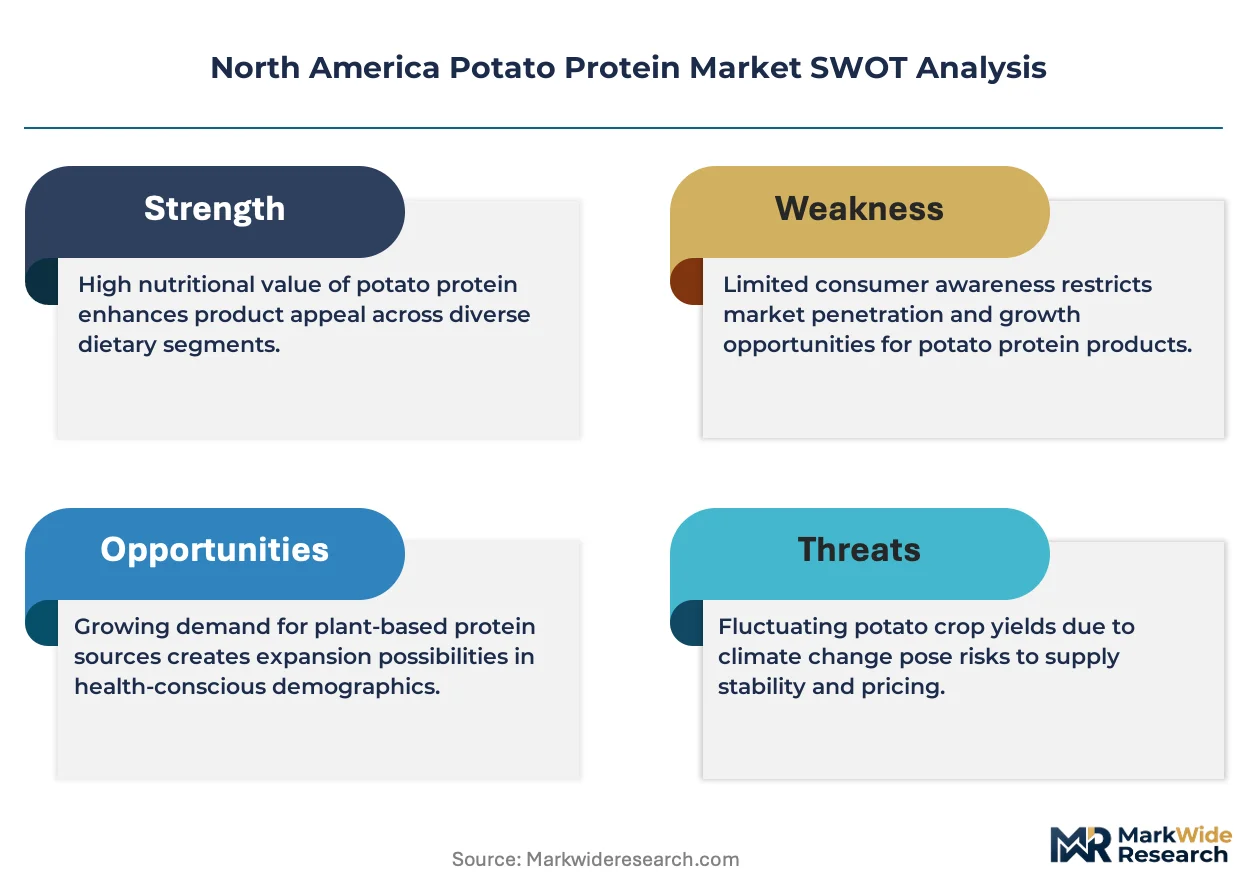
Plant-based meat formulators are accelerating clean-label reformulations, displacing soy and dairy isolates with allergen-free alternatives across North American CPG kitchens. This demand rotation concentrates procurement power in the hands of extrusion specialists and contract manufacturers serving retail private-label programs.
Growth Catalysts
- USDA biobased procurement preferences:Federal purchasing mandates favor domestically traceable protein streams, directing institutional foodservice contracts toward Red River Valley processors with verified supply chain documentation.
- Clean-label meat analogue extrusion:High-inclusion potato protein isolates enable superior gelation and bite texture in plant-based burgers and sausages, accelerating adoption by formulators seeking neutral-flavor alternatives to pea and soy.
- Upper Midwest processing corridor concentration:Minnesota, Wisconsin, and North Dakota host integrated starch-protein facilities that reduce logistics costs and enable just-in-time isolate delivery to meat alternative manufacturers.
Market Restraints
- Potato crop input volatility:Weather-driven yield fluctuations in North Dakota and Idaho directly constrain juice availability for protein extraction, creating margin pressure during drought cycles.
- Single-region supply concentration:Overreliance on Red River Valley processing infrastructure creates vulnerability to localized flooding, rail bottlenecks, and energy price spikes affecting spray-drying operations.
- FDA GRAS self-determination complexity:Novel isolate variants require extensive toxicological documentation, extending time-to-market for functional improvements and deterring mid-cap entrants.
Strategic Opportunities
- California state-level clean-label legislation:Proposed ingredient disclosure mandates in Sacramento and Albany create first-mover advantage for transparent, single-source potato protein suppliers with blockchain traceability systems.
- Ready-to-drink nutritional hydrolysates:Liquid protein formats targeting sports nutrition and clinical nutrition segments remain underdeveloped relative to powder concentrates, offering margin expansion potential.
- Health Canada-PMRA allergen threshold harmonization:Cross-border regulatory alignment through the Canada-U.S. Regulatory Cooperation Council simplifies export qualification for isolates meeting dual jurisdiction standards.
Industry Challenges
- Specialized extrusion technologist scarcity:High-inclusion meat analogue formulation requires rare expertise in twin-screw parameter optimization, constraining co-manufacturer capacity expansion.
- Flavor-masked isolate R&D capex intensity:Developing off-taste suppression systems demands sustained investment in sensory science infrastructure beyond reach of most mid-tier processors.
- FDA fermented protein labeling uncertainty:Draft guidance ambiguity creates compliance timeline risk for hybrid products combining potato isolate with precision fermentation inputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Potato Protein Market |
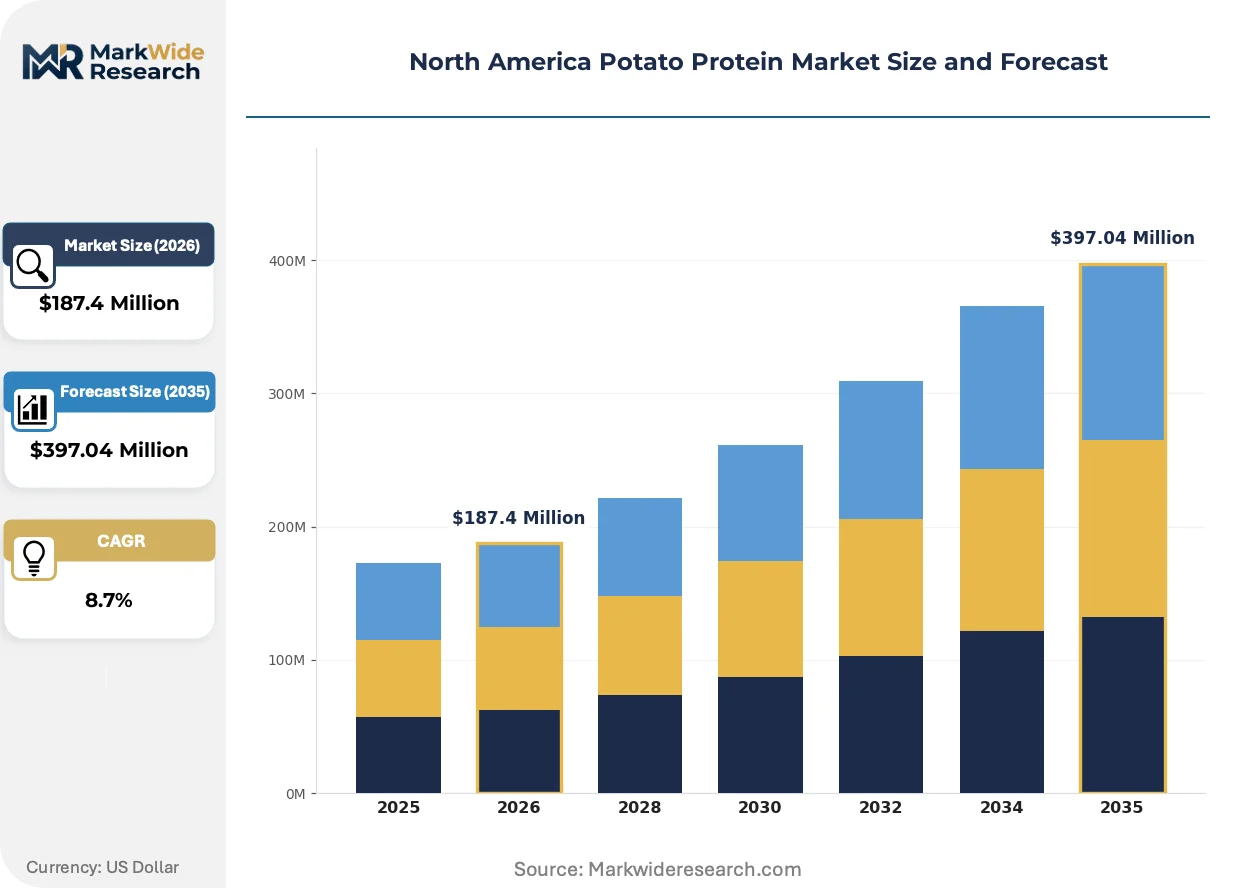
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Textured, Hydrolyzed End Use Industry: Food & Beverage, Nutritional Supplements, Feed, Bakery Form: Powder, Liquid, Granule, Flake Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Royal Avebe, Kerry Group, Tereos Group, Roquette Frères, AGRANA Beteiligungs-AG, Emsland Group, KMC Ingredients, Meelunie B.V., Kemin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Potato Protein Market Evolving Landscape
Membrane filtration and enzymatic hydrolysis advances are compressing extraction costs while expanding functional property customization. These process innovations enable protein fractionation tailored to specific food system applications.
Membrane-based protein recovery is miniaturizing pilot-scale isolation workflows, allowing regional processors to validate custom isolate specifications without capital-intensive central facilities. Mid-sized CPG manufacturers in Chicago and Toronto are adopting these modular systems for rapid prototype iteration. The technology is compressing minimum viable scale thresholds, fragmenting production geography beyond legacy Red River Valley dominance.
The FDA's draft guidance on fermented and cell-cultured protein labeling is forcing disclosure granularity for hybrid formulations containing both plant and biotech-derived proteins. Meat analogue manufacturers must now segregate ingredient streams for distinct regulatory treatment. Plant-based burger brands with complex supply chains face reformulation pressure to simplify label declarations and avoid consumer confusion.
Direct procurement contracts between protein isolate suppliers and retail private-label programs are displacing traditional ingredient distributor intermediaries. Costco and Kroger are negotiating multi-year supply agreements with processors for exclusive clean-label product lines. This channel consolidation concentrates volume commitments in fewer relationships, privileging processors with certified organic and non-GMO verification stacks.
North America Potato Protein Market Segmentation
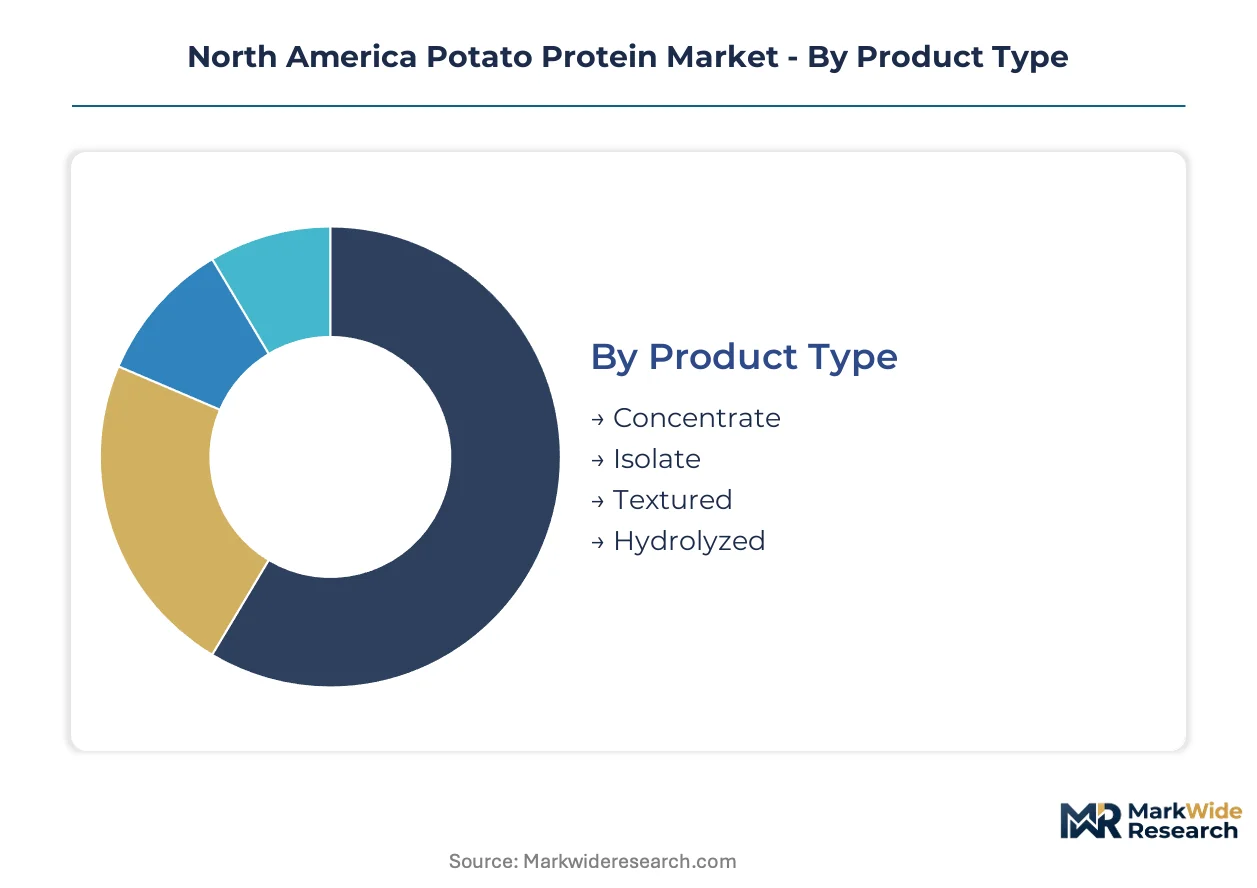
Potato protein segmentation reveals how functional specifications and channel economics fragment addressable markets across North American food manufacturing. Substitution dynamics vary sharply by product tier and end-use application maturity.
Product Type:
Isolate and concentrate segments face divergent substitution pressures from pea and rice protein alternatives, with textured formats increasingly vulnerable to emerging fungal mycelium ingredients.
- Concentrate:Contains 60-75% protein content with retained potato starch fractions, serving feed compounders and cost-sensitive bakery applications. Demand concentrates in Upper Midwest livestock operations where dairy ration reformulation drives inclusion rates.
- Isolate:Achieves 85-90% protein purity through isoelectric precipitation and ultrafiltration, commanding premium positioning in plant-based meat extrusion. Procurement from Minnesota and North Dakota processors accelerates as clean-label formulators displace soy isolates in high-inclusion analogue systems.
- Textured:Extruded fibrous structures for meat extenders and analogues; fungal protein alternatives are compressing growth in legacy applications.
- Hydrolyzed:Enzymatically cleaved peptides for rapid absorption in clinical nutrition; sports nutrition contract manufacturers in Toronto and Chicago represent emerging demand nodes.
Concentrate retains volume leadership; isolate holds the steepest expansion curve.
End Use Industry:
Application maturity determines margin capture, with established food manufacturing segments trading volume against emerging nutritional formats trading growth against regulatory uncertainty.
- Food & Beverage:Encompasses plant-based meat, dairy alternatives, and processed foods where emulsification and gelation properties prove critical. Meat analogue extrusion specialists in Wisconsin and Illinois dominate procurement volumes.
- Nutritional Supplements:Ready-to-drink formulations and powder blends targeting sports and clinical nutrition segments; FDA GRAS documentation requirements constrain new entrant participation.
- Feed:Poultry and swine ration inclusion driven by amino acid profile optimization; Red River Valley compounders source directly from integrated starch processors.
- Bakery:Gluten-free bread and snack applications leveraging potato protein's water-binding capacity; lower-inclusion rates limit absolute volume contribution.
Feed sustains the broadest geographic footprint; nutritional supplements are climbing fastest despite regulatory headwinds.
Form:
Logistics economics and shelf stability requirements partition the market between bulk powder dominance and liquid format experimentation in specialized nutritional channels.
- Powder:Spray-dried isolates and concentrates dominate commercial flows, enabling extended storage and flexible reconstitution. Rail-served Red River Valley processors supply bulk quantities to Chicago and Toronto manufacturing clusters.
- Liquid:Hydrolysate suspensions for ready-to-drink applications; cold-chain requirements restrict distribution radius and concentrate demand near processing facilities.
- Granule:Agglomerated particles for improved dispersibility in instant beverage applications.
- Flake:Thin-dried sheets for specialty bakery and snack coating operations with limited commercial scale.
Powder commands procurement scale; liquid formats are expanding most quickly in sports nutrition channels.
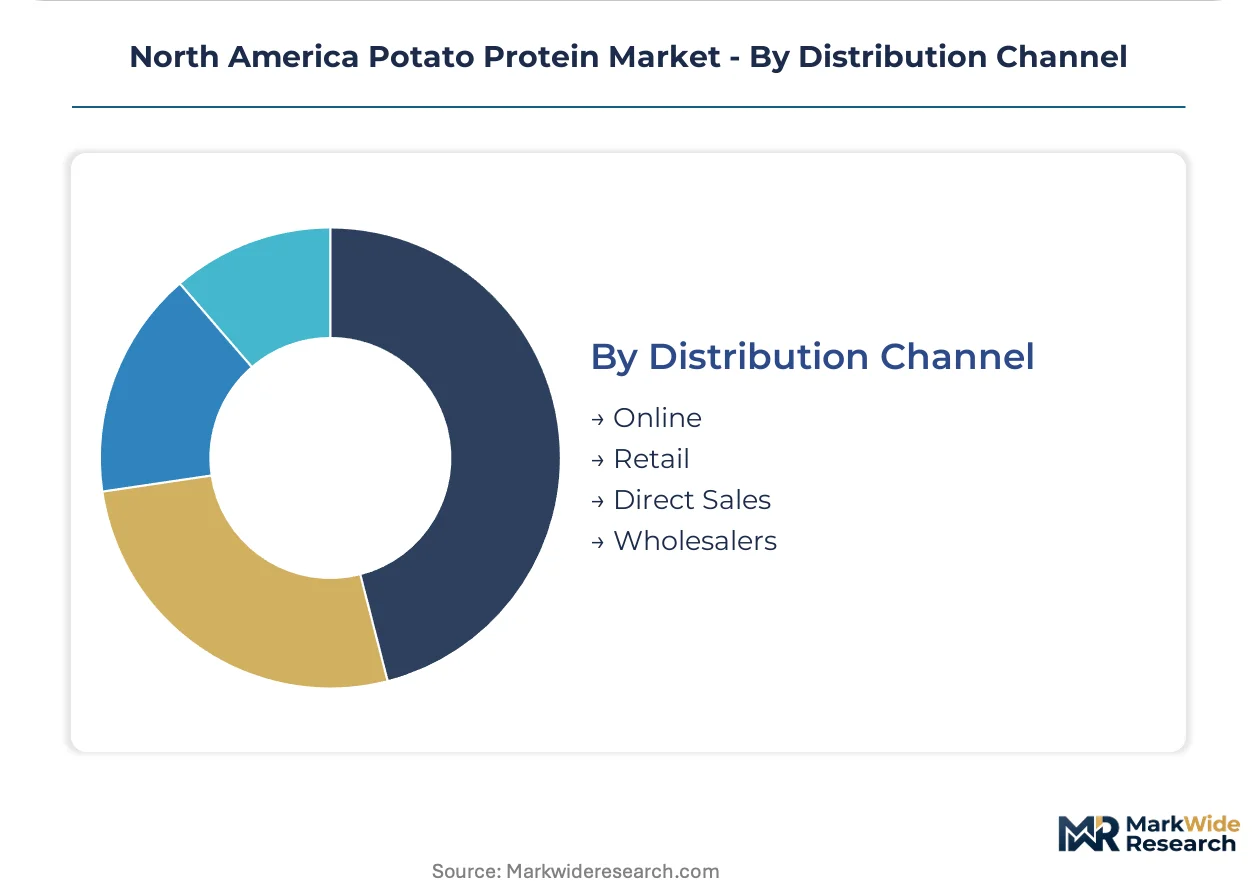
Distribution Channel:
Channel consolidation reflects procurement power concentration among large CPG and retail private-label programs, squeezing traditional distributor intermediaries.
- Direct Sales:Multi-year supply agreements between processors and meat analogue manufacturers or retail private-label programs. Costco and Kroger negotiate exclusive clean-label lines directly with Red River Valley suppliers.
- Wholesalers:Legacy ingredient distributors serving mid-tier bakery and feed compounders; margin compression from direct procurement trends threatens viability.
- Online:E-commerce platforms for small-scale nutritional supplement manufacturers and research institutions; limited volume contribution.
- Retail:Limited consumer-facing packaged protein sales; primarily specialty health food channels.
Direct sales captures the largest contract values; online channels are gaining traction fastest among emerging supplement brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports potato protein isolates to U.S. meat analogue manufacturers clustered in the Upper Midwest, while Mexico serves as an emerging destination for hydrolysates targeting sports nutrition brands in Mexico City.
United States
Plant-based meat formulators in Wisconsin and Illinois drive isolate procurement for extruded analogue systems. FDA GRAS self-determination requirements govern novel protein variants entering interstate commerce. The Red River Valley processing corridor spanning Minnesota and North Dakota hosts integrated starch-protein facilities supplying bulk isolates to Chicago manufacturing clusters.
Canada
Health Canada coordinates allergen threshold harmonization with U.S. regulators through the Canada-U.S. Regulatory Cooperation Council. PMRA oversight of processing aids affects extraction chemistry approvals for cross-border shipments. Manitoba and Alberta potato processors supply concentrate to Ontario poultry compounders and export isolates to U.S. CPG manufacturers.
Mexico
Sports nutrition brands in Mexico City and Guadalajara import hydrolysates for ready-to-drink formulations targeting clinical and athletic segments. COFEPRIS registration requirements for novel food ingredients create documentation burdens for isolate suppliers. Northern border states concentrate feed-grade concentrate demand from livestock operations supplying U.S. protein markets.
North America Potato Protein Market Competitive Landscape
Player mix skews toward integrated starch processors and specialty ingredient formulators with flavor-masking capabilities. Market structure concentrates around processors with captive potato juice supply and spray-drying infrastructure. Two strategic archetypes dominate: Red River Valley integrated processors with backward control over co-product streams, and European multinationals with pharmaceutical-grade hydrolysate capacity. Competitive moves center on direct procurement contracts with retail private-label programs and membrane filtration technology licensing to regional processors.
Within the integrated processor tier, Royal Avebe exemplifies backward integration into starch co-product streams, while Kerry Group represents flavor-masked isolate system development. Roquette Frères occupies a position emphasizing pharmaceutical-grade hydrolysate capacity for nutritional supplement contract manufacturers. These three anchors illustrate how geographic proximity to raw material supply, sensory science infrastructure, and regulatory documentation depth stratify competitive positioning across isolate, concentrate, and hydrolyzed product tiers.
| Leading Market Players |
|---|
| Royal Avebe |
| Kerry Group |
| Tereos Group |
| Roquette Frères |
| AGRANA Beteiligungs-AG |
| Emsland Group |
| KMC Ingredients |
| Meelunie B.V. |
| Kemin Industries |
| Others |
Value Network & Pricing Analysis
FDA GRAS self-determination requirements for novel potato protein isolates simultaneously gate supply qualification and stratify price tiers across North American procurement channels. Certification documentation depth separates premium pharmaceutical-grade hydrolysate suppliers from commodity concentrate processors, embedding compliance costs directly into contract pricing structures for meat analogue manufacturers and nutritional supplement brands.
Pricing Analysis
Membrane filtration technology-generation pricing gaps separate established spray-dried isolate systems from emerging enzymatic hydrolysis platforms. Three-tier pricing structure across premium, standard, and economy levels tracks protein purity grades and organic certification status, with isolate commanding substantial premiums over concentrate for extrusion applications. Cost compression in feed-grade concentrate is intensifying because dairy ration reformulators negotiate volume offtakes with Red River Valley processors. Contract manufacturers serving retail private-label programs exhibit lowest price sensitivity, while mid-tier bakery compounders drive aggressive spot-market negotiations.
Supply Chain Analysis
Inventory lead times for spray-dried isolates extend during Red River Valley harvest windows as starch processing prioritizes juice availability for protein extraction. Supply concentrates in the United States, Canada, and limited Mexican border states, with Minnesota and North Dakota hosting integrated facilities that source from captive potato co-product streams. Raw material dependencies hinge on Red River Valley tuber supply, rail-served energy infrastructure for drying operations, and specialized membrane filtration equipment. Single-region concentration creates vulnerability to localized flooding and rail bottlenecks. Distribution runs through direct procurement contracts with meat analogue manufacturers and retail private-label programs, displacing traditional ingredient distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label meat analogue formulation platforms are consolidating procurement power around extrusion specialists with verified supply chain documentation, creating ecosystem-level interoperability requirements for isolate suppliers seeking retail shelf placement.
For Market Incumbents: Consolidate backward integration into Red River Valley starch co-product streams to secure captive juice supply against emerging fungal protein substitutes. Deepen FDA GRAS documentation libraries for novel isolate variants to extend time-to-market barriers protecting premium positioning. Prioritize direct procurement contract renewal with Costco and Kroger private-label programs before state-level clean-label legislation in California and New York proliferates disclosure requirements. For New Entrants and Emerging Players: Flavor-masked isolate system development represents the most penetrable service layer where Kerry Group's sensory science infrastructure leaves mid-tier coverage gaps. Target ready-to-drink nutritional hydrolysate segments in Toronto and Chicago sports nutrition channels, where liquid format cold-chain requirements deter established powder-focused processors. Pursue membrane filtration technology licensing to regional processors as a capital-light go-to-market pathway. For Investors and Strategic Acquirers: FDA fermented protein labeling guidance reshapes the acquisition landscape by elevating regulatory documentation depth above scale economics in valuation frameworks. Long-term viability favors processors with dual jurisdiction Health Canada-PMRA qualification stacks enabling cross-border arbitrage. The signal to watch is California state-level clean-label legislation progression, which would accelerate consolidation toward transparent, blockchain-traceable supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Starch Co-Product Streams | Royal Avebe's Red River Valley positioning secures captive potato juice supply against harvest volatility. |
| Flavor-Masked Isolate System Development | Kerry Group's sensory science infrastructure reduces off-taste in high-inclusion meat analogues for CPG formulators. |
| Pharmaceutical-Grade Hydrolysate Capacity Expansion | Roquette Frères serves Toronto and Chicago sports nutrition contract manufacturers with rapid-absorption peptides. |
| Direct Procurement Contract Negotiation | Costco and Kroger multi-year supply agreements displace traditional ingredient distributor intermediaries. |
| Membrane Filtration Technology Licensing | Regional processors in Wisconsin and Illinois adopt modular systems for rapid prototype iteration. |
Research Methodology
A standing panel of plant-based meat formulation technologists, starch processing plant managers, retail private-label category buyers, and FDA regulatory affairs consultants provided ongoing calibration across the research cycle. Primary interviews with extrusion specialists in Wisconsin and Illinois, Red River Valley procurement leads, and nutritional supplement contract manufacturers in Toronto and Chicago were cross-validated against secondary sources including FDA GRAS notification filings, Health Canada novel food approvals, USDA biobased procurement records, and SEC 10-K disclosures from listed ingredient suppliers. Bottom-up volume modeling from isolate, concentrate, and hydrolysate production capacities was triangulated against top-down demand estimates from meat analogue manufacturer procurement data.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions including product type tiers, end-use industry maturity, powder versus liquid form logistics economics, and direct versus wholesale distribution channel consolidation. CAGRs were derived from fitted growth curves calibrated to procurement volume trajectories and capacity expansion announcements. Industry-specific forecast inputs incorporated potato crop yield projections from North Dakota and Idaho agricultural surveys, and clean-label reformulation timelines from CPG manufacturer R&D pipeline disclosures.
Underlying assumptions cover sustained plant-based meat analogue adoption rates, FDA labeling guidance finalization timelines, and Red River Valley processing infrastructure stability, with deviation risk concentrated in potato crop input volatility and state-level clean-label legislation propagation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Soy Protein Concentrate Market
Ingredients
Native Whey Protein Ingredients Market
Ingredients
Europe Agar Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
Specialty Yeast Market
Ingredients
Cooking Oil Market
Ingredients
Soy Peptones Market
Ingredients
Oat Ingredients Market
Ingredients
Protein Extracts from Single Cell Protein and Other Conventional Sources Market
Ingredients
Cocoa Beans Market
Ingredients
Pea Peptones Market
Ingredients
Soy Lecithin Market
Ingredients
Europe Whey Protein Ingredients Market
Ingredients
Specialty Fats and Oils Market
Ingredients
Alcohol Ingredients Market
Ingredients
Pomace Olive Oil Market