
 Africa Potato Protein Market | 2026-2036
Africa Potato Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Potato Protein Market Outlook
Contract-based technical support and formulation advisory is hardening as a distinct revenue layer alongside bulk isolate and concentrate sales. Roquette Freres anchors its African presence through specialized nutrition application labs that customize potato protein functionality for regional bakery processors. Meelunie B.V. competes by leveraging its Rotterdam-to-Lagos supply chain to reduce lead times for Nigerian food manufacturers. Kemin Industries, Inc. differentiates through its technical service model, embedding food scientists with industrial buyers to optimize protein incorporation into meat alternatives.
Potato protein denotes the concentrated protein fraction extracted from potato tubers, typically containing 75-90% protein by dry weight depending on whether isolate or concentrate grades are produced, with primary commercial purpose as a functional emulsifier and nutritional fortifier in processed foods. Isolate-grade material commands premium positioning due to superior amino-acid completeness and lower starch carryover, making it the preferred input for nutritional beverages and meat-alternative formulations across African processing hubs. Concentrate and flour segments occupy volume-driven roles in animal feed and lower-cost bakery fortification, where functional requirements remain less stringent and price sensitivity dominates procurement decisions.
South Africa's Department of Health enforces food fortification standards that mandate accurate protein-content labeling on packaged goods, directly shaping product formulation requirements for manufacturers sourcing potato protein. The country's National Regulator for Compulsory Specifications and Nigeria's National Agency for Food and Drug Administration and Control both maintain import-registration protocols that condition market access on compositional testing and certificate-of-analysis documentation. Stakeholders must monitor how these dual regulatory frameworks evolve around novel protein claims and allergen-labeling expansions, as compliance complexity will increasingly determine which suppliers can sustain commercial relationships with major African food processors.
Market Dynamics
Contract-based technical support is hardening as a distinct revenue layer alongside bulk isolate and concentrate sales, as South African and Nigerian food manufacturers demand embedded formulation advisory to meet tightening protein-labeling standards.
Growth Catalysts
- South Africa's food fortification regulations:The Department of Health's tightening protein-labeling standards for processed foods mandate accurate content declarations, forcing manufacturers to source verified isolate-grade material with complete amino-acid profiles and documented compositional analysis.
- Plant-based meat alternatives:Nigeria's expanding snack-food manufacturing corridor around Lagos is absorbing increasing volumes of isolate-grade potato protein as meat-alternative processors seek functional emulsifiers with superior gelling and water-binding capacity.
- Specialized nutrition application labs:Regional bakery processors now require customized potato protein functionality for specific dough systems and shelf-life extension, creating pull-through demand for technical service capabilities alongside commodity supply.
Market Restraints
- Import-registration protocols:Nigeria's National Agency for Food and Drug Administration and Control maintains certificate-of-analysis documentation requirements that extend lead times and create compliance friction for new supplier entrants.
- Starch carryover in concentrate grades:Technical limitations in regional extraction infrastructure produce higher starch contamination in concentrate material, restricting its use to animal feed and lower-cost bakery applications where functional requirements remain less stringent.
- Soy protein substitution threat:Established soy isolate supply chains from South American origins offer price-competitive alternatives for cost-sensitive Nigerian food manufacturers prioritizing margin over amino-acid completeness.
Strategic Opportunities
- Underpenetrated East African markets:Kenya and Ethiopia's nascent processed food sectors present white-space opportunity for isolate-grade material as urbanization accelerates demand for fortified packaged goods and nutritional beverages.
- Technical service embedding:Food scientists placed directly with industrial buyers to optimize protein incorporation into meat alternatives represent an emerging service revenue stream distinct from commodity margin capture.
- Rotterdam-to-Lagos supply chain optimization:Direct maritime routing with reduced transshipment points can compress lead times for Nigerian manufacturers currently sourcing through multi-port distribution networks.
Industry Challenges
- Food formulation chemistry expertise:Regional processors lack technical staff capable of optimizing potato protein incorporation across varying pH and thermal processing conditions, creating adoption friction even where regulatory pull exists.
- Dual regulatory compliance complexity:South Africa's National Regulator for Compulsory Specifications and Nigeria's NAFDAC operate non-harmonized testing protocols, forcing suppliers to maintain parallel certification documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Potato Protein Market |
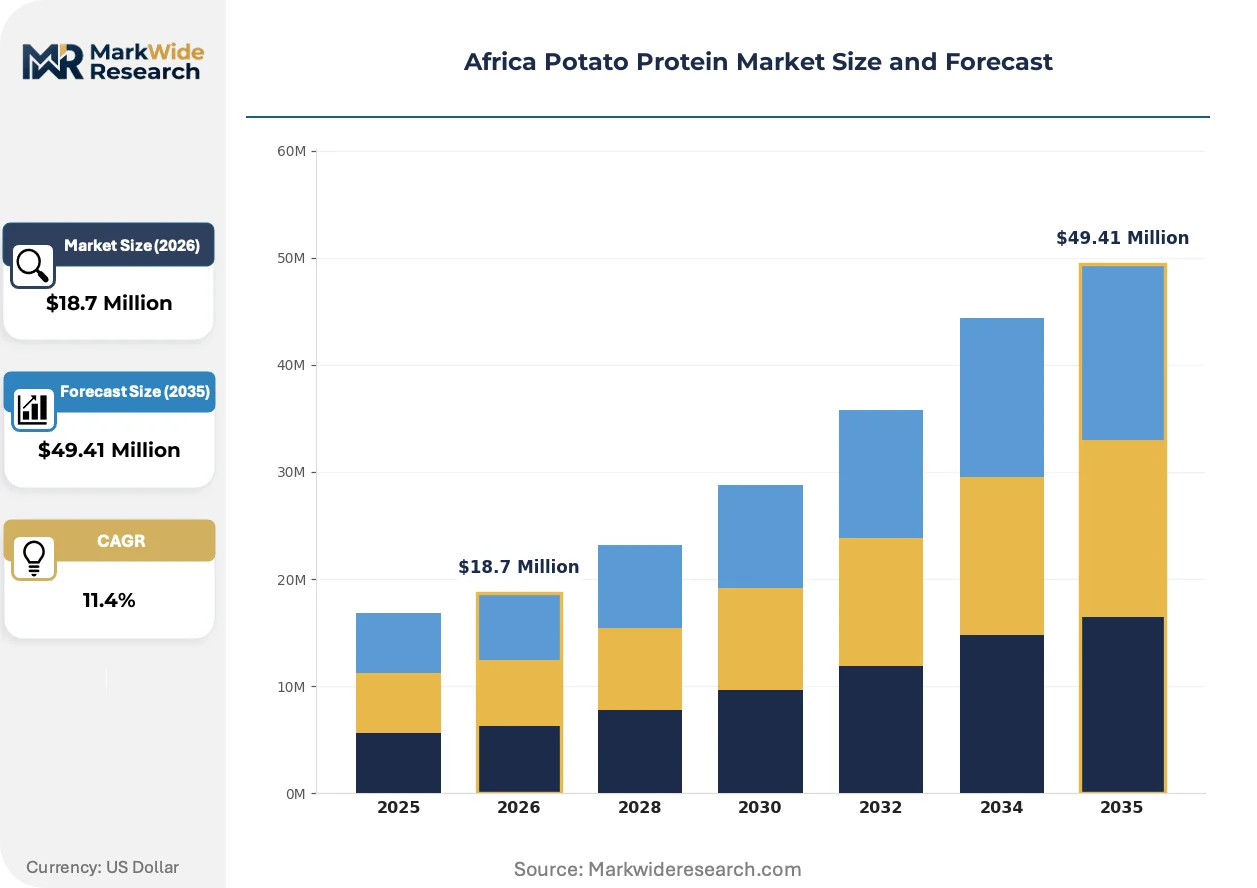
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $49.41 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Flour, Granules End User: Food & Beverages, Animal Feed, Supplements, Bakery Products Form: Powder, Liquid, Solid, Bar Application: Meat Alternatives, Protein Fortification, Nutritional Beverages, Snack Foods |
| Companies Covered | Cooperatie Avebe U.A., Roquette Freres, Meelunie B.V., Kemin Industries, Inc., KMC Ingredients, Tereos Group, AGRANA Beteiligungs-AG, Emsland Group, AKV Langholt, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Potato Protein Market Strategic Shifts
Membrane filtration and enzymatic extraction technologies are reshaping competitive positioning by enabling higher-purity isolate production at reduced starch carryover, while embedded technical service models separate premium suppliers from commodity traders.
Advanced membrane filtration systems incorporating ceramic microfiltration and ultrafiltration cascades are automating the separation of protein fractions from potato fruit juice with precision previously requiring manual process intervention. South African isolate producers are adopting these systems at accelerating pace as export-grade certification demands intensify. This automation is compressing the quality variance between production batches and reducing reliance on skilled operator judgment for fractionation timing.
South Africa's Department of Health enforcement of food fortification standards is mandating accurate protein-content labeling on packaged goods with compositional testing documentation. Manufacturers must reformulate using verified isolate inputs with certificate-of-analysis backing to maintain retail distribution access. Bakery and meat-alternative processors in Johannesburg and Cape Town industrial zones are responding by qualifying suppliers with in-house analytical capabilities rather than accepting trader-mediated material.
Direct technical embedding with industrial buyers is displacing traditional distributor-mediated sales relationships across Nigerian food manufacturing. Lagos-based snack processors now require supplier food scientists on-site for formulation optimization during product development cycles. This pattern concentrates procurement authority with technical-capable suppliers and marginalizes pure trading intermediaries lacking application expertise.
Africa Potato Protein Market Segmentation
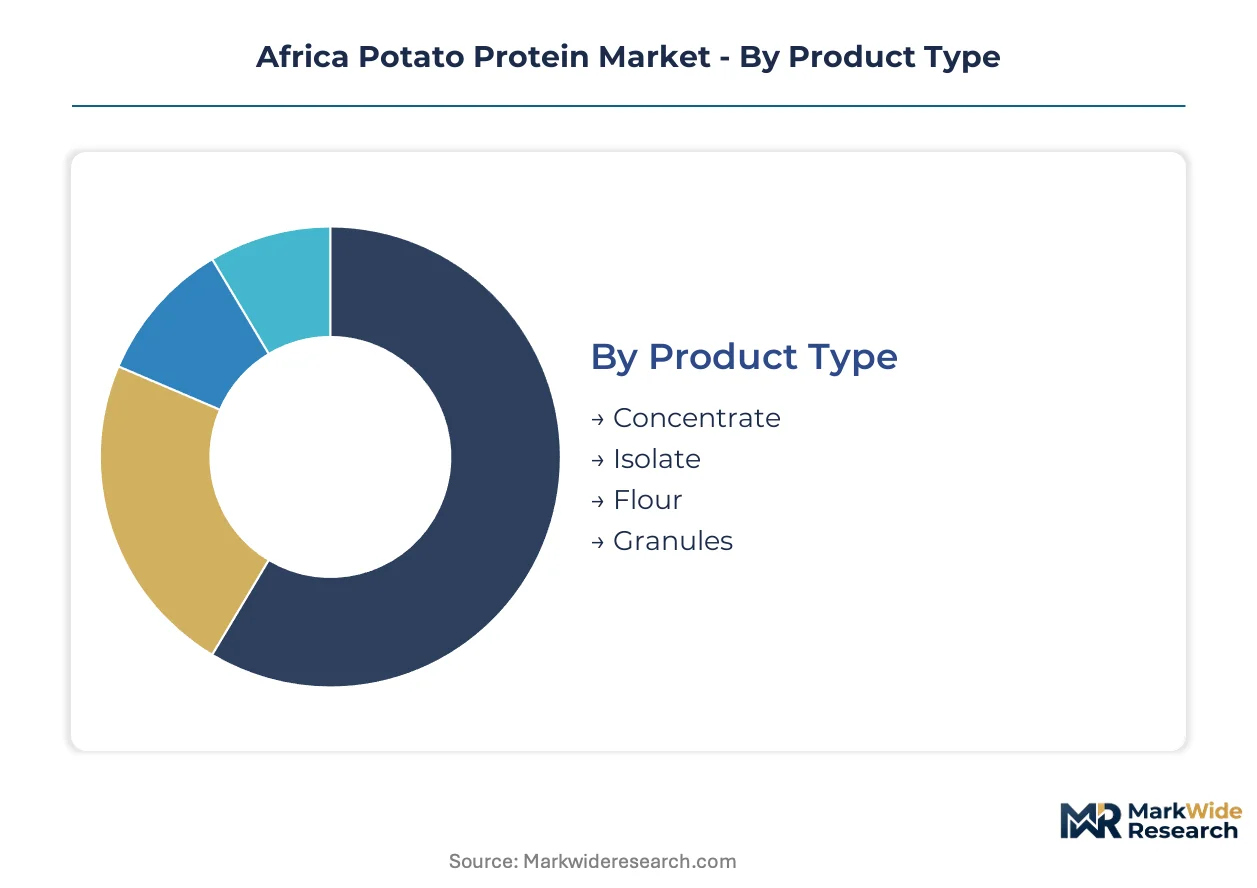
Potato protein procurement in Africa splits sharply between premium isolate grades demanded by regulated food manufacturers and volume-driven concentrates serving cost-sensitive feed and bakery sectors. Understanding these segment boundaries clarifies where technical service investments yield returns versus where commodity logistics dominate supplier selection.
Product Type:
Volume concentrates anchor procurement tonnage while isolate commands pricing premiums across African processing hubs.
- Isolate:Contains 75-90% protein by dry weight with minimal starch carryover, qualifying for South Africa's Department of Health protein-labeling compliance in meat alternatives and nutritional beverages. Lagos-based snack processors absorb growing volumes as NAFDAC registration requirements harden documentation standards for isolate-grade imports.
- Concentrate:Carries higher starch fractions and commands lower unit economics, restricting deployment to animal feed compounding and lower-tier bakery fortification where functional requirements remain less stringent. Nigerian feed millers around Kano represent the primary demand concentration for this grade.
- Flour:Ground whole-potato material with protein content typically below 10%, serving regional livestock operations seeking bulk caloric density rather than amino-acid optimization.
- Granules:Intermediate moisture format finding niche adoption in wet-feed processing systems at South African poultry operations.
Today's leader: Isolate. Tomorrow's challenger: Concentrate (if starch separation technology improves regionally).
End User:
Regulatory pressure intensity varies dramatically across buyer categories, reshaping supplier qualification requirements.
- Food & Beverages:South African beverage manufacturers and Nigerian dairy alternatives processors drive isolate demand as fortified product labeling rules tighten compositional verification standards.
- Animal Feed:Concentrate-grade absorption concentrates in Nigerian poultry and aquaculture operations seeking cost-efficient protein supplementation amid soy price volatility.
- Supplements:Sports nutrition formulators in Johannesburg and Cape Town represent emerging isolate demand as gym culture expands among urban middle-class consumers.
- Bakery Products:Bread fortification programs in Ethiopia and Kenya absorb flour-grade material, though technical staff shortages limit adoption velocity.
Food & Beverages captures current procurement value. Supplements exhibit the steepest expansion trajectory as distribution infrastructure matures.
Form:
Handling economics and shelf stability requirements dictate format selection across climatic and logistical conditions.
- Powder:Dominates isolate shipments to Lagos and Durban ports due to superior storage stability in high-humidity environments and compatibility with automated dosing equipment at scale processors.
- Liquid:Concentrated protein suspensions serve wet pet food manufacturers in South Africa's Western Cape, though cold-chain requirements limit Nigerian penetration.
- Solid:Compressed blocks find limited traction in artisanal feed mixing operations lacking precision weighing capacity.
- Bar:Ready-to-eat formats remain negligible in African markets, constrained by consumer price sensitivity and underdeveloped sports-nutrition retail channels.
Powder maintains logistics supremacy. Liquid gains share where cold-chain infrastructure receives capital injection.
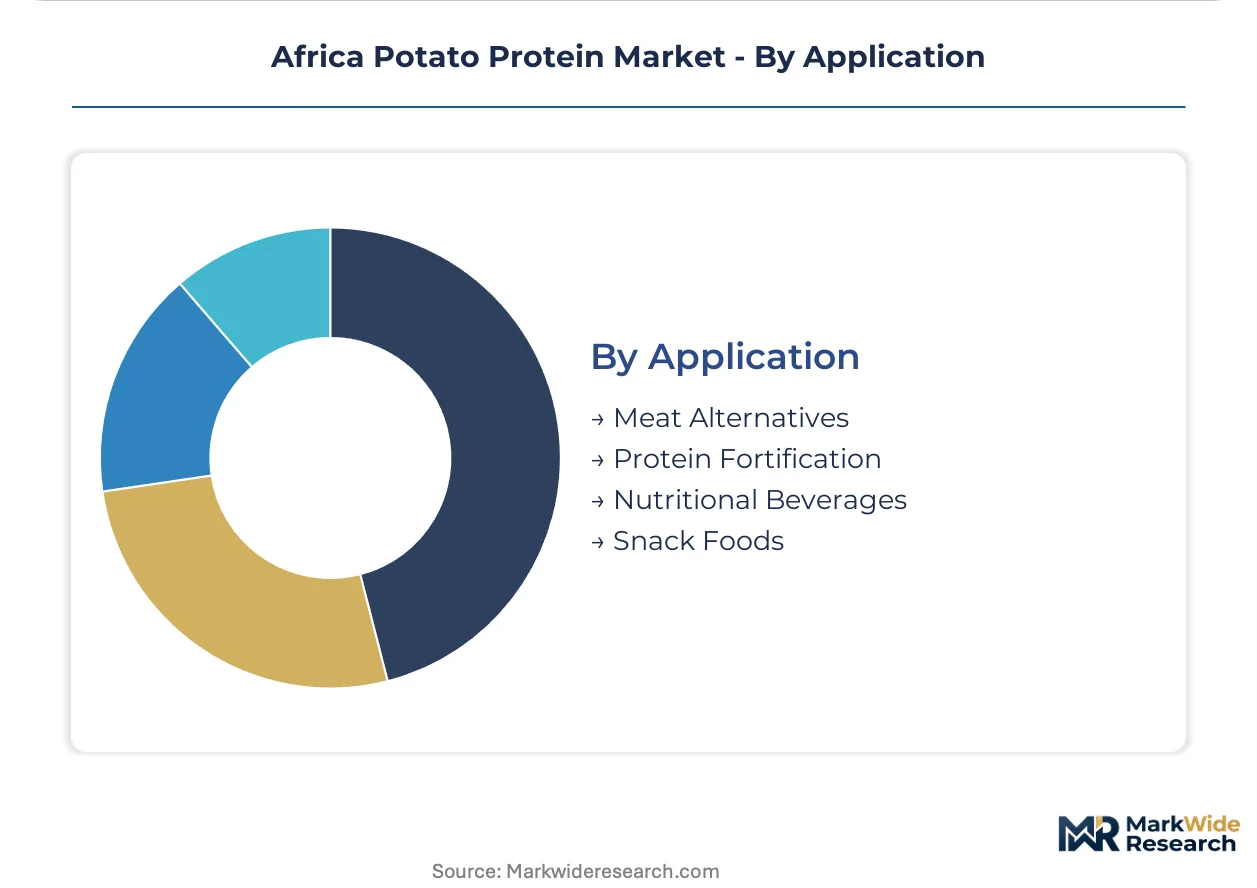
Application:
Functional performance requirements separate premium-grade from commodity-grade procurement decisions.
- Meat Alternatives:South African plant-based burger and sausage processors require isolate-grade gelling and water-binding functionality to replicate muscle protein texture, with formulation advisory now standard in supplier contracts.
- Protein Fortification:Government-mandated flour fortification in Nigeria and voluntary packaged goods enrichment in South Africa drive concentrate and isolate demand depending on target population and cost constraints.
- Nutritional Beverages:Ready-to-drink protein products targeting Ethiopian and Kenyan urban consumers represent emerging powder-format demand, though flavor masking challenges slow adoption.
- Snack Foods:Lagos corridor extruded snack manufacturers absorb isolate for protein claim differentiation in competitive retail environments.
Meat Alternatives commands technical service investment. Snack Foods offers volume scaling potential as Nigerian retail modernizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa commands premium isolate procurement through regulatory enforcement, while Nigeria absorbs volume concentrates amid infrastructure constraints. Kenya and Ethiopia represent emerging demand frontiers as urbanization accelerates processed food consumption. Egypt's strategic position offers transshipment potential for Mediterranean-facing suppliers.
South Africa
The Department of Health's protein-labeling standards drive isolate-grade absorption by Johannesburg and Cape Town meat-alternative processors. The National Regulator for Compulsory Specifications mandates certificate-of-analysis documentation for all imported protein inputs. Western Cape beverage manufacturers and Eastern Cape bakery clusters now require embedded technical service from suppliers to maintain compliance.
Nigeria
Lagos corridor snack-food manufacturers absorb expanding isolate volumes for protein-fortified extruded products. The National Agency for Food and Drug Administration and Control maintains rigorous import-registration protocols that extend supplier qualification timelines. Kano feed millers concentrate demand for concentrate-grade material in poultry and aquaculture operations seeking soy alternatives.
Kenya
Nairobi-based dairy alternatives processors represent nascent isolate demand as gym culture spreads among urban middle-class consumers. The country's national food regulator enforces packaged goods labeling standards that increasingly reference protein content claims. Mombasa port infrastructure improvements are compressing lead times for isolate shipments from European origins.
Ethiopia
Addis Ababa bakery fortification programs absorb flour-grade potato protein amid government nutrition intervention initiatives. The country's food safety authority maintains evolving standards for imported nutritional inputs that condition market access. Industrial zones around the capital are attracting regional snack-food manufacturers seeking cost-efficient protein supplementation.
Egypt
Alexandria and Damietta ports offer Mediterranean transshipment nodes for suppliers targeting North African markets with reduced Suez Canal routing. The country's food and drug administration maintains import protocols that parallel Egyptian standards harmonization efforts. Cairo-based trading houses are consolidating procurement authority for redistribute into Sub-Saharan corridors.
Africa Potato Protein Market Competitive Environment
Top-tier vendors anchor technical service capabilities, while commodity traders compete on logistics optimization and price positioning. The market structures around three archetypes: integrated nutrition specialists with application laboratories, regional distributors with port-adjacent warehousing, and agricultural cooperatives with captive raw material access. Dominant competitive moves include embedded formulation advisory contracts and direct maritime routing investments to compress Nigerian lead times.
Within the integrated specialist tier, Roquette Freres and Kemin Industries, Inc. exemplify technical service differentiation through nutrition application support. Meelunie B.V. occupies a position among logistics-optimized distributors leveraging Rotterdam-origin supply chains. Cooperatie Avebe U.A. represents the agricultural cooperative archetype with upstream raw material integration.
| Leading Market Players |
|---|
| Cooperatie Avebe U.A. |
| Roquette Freres |
| Meelunie B.V. |
| Kemin Industries, Inc. |
| KMC Ingredients |
| Tereos Group |
| AGRANA Beteiligungs-AG |
| Emsland Group |
| AKV Langholt |
| Others |
Value Chain & Pricing Dynamics
Potato starch futures on the European Commodity Exchange anchor input cost baselines for African processors, with Rotterdam-origin isolate commanding premium spreads over Black Sea alternatives as South African fortification rules harden amino-acid verification requirements.
Pricing Analysis
Capacity additions in the Netherlands and Germany are reshaping price floors for isolate-grade material entering Lagos and Durban ports. Three-tier pricing structure across pharmaceutical-grade isolate, food-grade isolate, and feed-grade concentrate segments reflects starch carryover variance and documentation depth. Pricing pressure stems from soy protein substitution in Nigerian snack manufacturing where cost-sensitive formulators prioritize margin over completeness. Feed-grade concentrate buyers exhibit highest price sensitivity, while Johannesburg meat-alternative processors absorb premium isolate spreads for NAFDAC-compliant certificate-of-analysis backing.
Supply Chain Analysis
South Africa's local-content procurement guidelines for nutritional inputs are reshaping sourcing patterns for state-supported bakery fortification programs. European extraction facilities in the Netherlands, Germany, and France anchor upstream supply, with potato fruit juice feedstock drawing from Benelux and northern French starch processing cooperatives. Single-source vulnerability concentrates in Rotterdam-port transshipment nodes where Nigerian manufacturers face extended lead times. Distribution runs through port-adjacent warehousing at Lagos Apapa, Durban Container Terminal, and Mombasa Kilindini with last-mile feed miller and beverage processor direct delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on membrane filtration automation compressing starch separation costs and isolate-grade absorption accelerating among Lagos corridor snack processors willing to pay documentation premiums.
For Market Incumbents: Extend technical service embedding contracts from advisory-only to full formulation partnership models, locking in Johannesburg meat-alternative processors before soy protein traders develop comparable application support. Deepen backward integration into potato starch cooperative supply agreements to secure fruit juice feedstock priority allocation amid European bioethanol policy competition. For New Entrants and Emerging Players: South Africa's Department of Health protein-labeling enforcement opens a window for analytical-service-first market entry, positioning certificate-of-analysis capabilities as the primary qualification wedge rather than commodity trading relationships. Target Nairobi dairy alternatives processors and Addis Ababa bakery clusters where technical staff shortages create advisory dependency and incumbent presence remains thin. For Investors and Strategic Acquirers: Asymmetric upside sits with membrane filtration technology licensors possessing African installation partnerships and existing NAFDAC registration dossiers. Five-to-ten year viability favors specialists with captive European feedstock access rather than pure trading intermediaries. Monitor Rotterdam-to-Lagos direct maritime routing announcements as inflection signal for Nigerian procurement authority consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Licensing | Enables South African isolate producers to meet export-grade certification with reduced operator judgment dependency. |
| Embedded Technical Service Expansion | Positions suppliers as formulation partners rather than commodity vendors for Lagos snack-food manufacturers. |
| Rotterdam-to-Lagos Direct Maritime Routing | Compresses lead times for Nigerian processors currently dependent on multi-port distribution networks. |
| Certificate-of-Analysis Infrastructure Investment | Qualifies suppliers for South Africa's National Regulator for Compulsory Specifications import protocols. |
| East African Distribution Partnership | Establishes presence in Kenya and Ethiopia before fortification regulation maturity accelerates incumbent lock-in. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with potato protein extraction plant managers, Lagos-based food manufacturing procurement leads, South African bakery processor technical directors, and Nigerian feed miller operations heads with secondary validation through EU starch industry association reports, Rotterdam port customs data, NAFDAC import registration filings, and South African National Regulator for Compulsory Specifications documentation requirements. Bottom-up isolate and concentrate volume estimates triangulated against top-down processed food sector protein demand projections.
Historical reference periods spanning pre-regulatory enforcement and post-fortification mandate implementation anchored the forecast window's growth trajectory calibration. Segmentation dimensions modeled include product grade tier, end-use application, geographic regulatory cluster, and buyer technical capability level. CAGRs derived from slope analysis of documented procurement volume shifts across enforcement milestone dates, with membrane filtration adoption curves and soy protein price volatility incorporated as scenario-weighting inputs.
Revisions become necessary when South Africa or Nigeria announce novel protein claim regulations, when Rotterdam port congestion triggers alternative routing structural shifts, or when European bioethanol policy redirects potato fruit juice feedstock availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Microalgae Based Products Market
Alternative Food Sources
Insect-Based Pet Food Market
Alternative Food Sources
Bagasse Disposable Cutlery Market
Alternative Food Sources
Global Algal Oil Market
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Carragean Alternatives Market
Alternative Food Sources
Edible Insects Market
Alternative Food Sources
Soy Leghemoglobin Market
Alternative Food Sources
Vegetable Proteins Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Single Cell Oil Market
Alternative Food Sources
Fungal Protein Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Plant-Based Compound Feed Market
Alternative Food Sources
Spirulina Market