
 Protein Extracts from Single Cell Protein and Other Conventional Sources Market | 2026-2036
Protein Extracts from Single Cell Protein and Other Conventional Sources Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Extracts from Single Cell Protein and Other Conventional Sources Market Analytics
Ingredient licensing revenue is reshaping competitive economics in protein extraction, as technology holders capture value upstream of commodity manufacturing. Cargill Incorporated leverages its global oilseed processing footprint to backward integrate into yeast protein fermentation. Koninklijke DSM N.V. anchors European supply through precision fermentation platforms for single cell proteins. Kerry Group plc differentiates via application-specific protein blends targeting savory taste modulation.
Protein extracts from single cell protein and other conventional sources comprise concentrated amino acid fractions recovered via enzymatic hydrolysis, mechanical disruption, or solvent extraction from microbial biomass, oilseeds, legumes, and cereal streams, typically achieving protein contents between 50% and 90% dry weight depending on source and purification grade. These inputs serve as functional replacements for animal-derived proteins in formulated foods, feed rations, and fermentation media. Yeast extracts dominate current volume owing to established supply chains from beverage fermentation coproducts, while algal protein commands premium positioning in nutritional supplements where allergen-free claims and omega-3 cofractionation justify higher unit economics. Plant protein from soy and pea sources sustains the largest installed extraction capacity globally, though bacterial protein from methanotrophic fermentation is gaining traction in aquaculture feed applications.
EFSA novel food authorizations govern European market entry for single cell protein ingredients, with safety dossiers requiring extensive toxicological and compositional data that extend development timelines. FDA GRAS self-determination pathways in the United States offer faster commercialization for established microbial chassis, though enforcement discretion on fermentation-derived proteins is tightening. China's NMPA and SAMR jointly regulate new food ingredient registrations, with GB standards specifying heavy metal and microbiological limits that shape extraction process design. Stakeholders must monitor divergence in protein labeling standards between jurisdictions, as classification disputes between food, feed, and supplement categories determine applicable compliance burdens and accessible customer segments.
Market Dynamics
Ingredient licensing revenue is restructuring competitive economics in protein extraction, as technology holders capture value upstream of commodity manufacturing and fermentation capacity constraints concentrate supply leverage.
Growth Catalysts
- EFSA Novel Food Pathways:Accelerated safety validation timelines under EU regulations are compressing development cycles for yeast and algal protein isolates entering food processing applications.
- Methanotrophic Fermentation:Bacterial protein production from methane feedstock is displacing fishmeal in aquaculture feed rations, driven by supply security concerns in Norway and Chile.
- Germany's Biotech Clusters:Concentrated fermentation capacity and precision fermentation R&D infrastructure in Baden-Württemberg and Bavaria are anchoring scaled extraction operations for European supply.
Market Restraints
- Input Cost Volatility:Natural gas and agricultural substrate prices directly impact methanotrophic and yeast fermentation economics, squeezing margin structures for volume producers.
- EFSA Dossier Requirements:Extensive toxicological and compositional data demands for novel food authorizations extend development timelines and capital lockup periods.
- Plant Protein Substitution:Established soy and pea protein isolates with depreciated extraction assets compete on price in functional food applications.
Strategic Opportunities
- China's NMPA Registrations:GB standards for heavy metal and microbiological limits create compliance barriers that favor early movers with validated extraction processes.
- Omega-3 Cofractionation:Algal protein positioning in nutritional supplements leverages allergen-free claims and lipid coproduct value capture in premium segments.
- Direct-to-Manufacturer Channels:Bypassing traditional ingredient distributors through embedded technical service teams is compressing customer acquisition costs in savory taste modulation applications.
Industry Challenges
- Fermentation Scale-Up Talent:Shortages of process engineers with hybrid biology-chemical engineering expertise constrain facility commissioning timelines.
- Downstream Purification Capex:Chromatography and membrane filtration systems for 90% protein grades require capital commitments that strain mid-cap balance sheets.
- Cross-Jurisdictional Labeling:Divergent classification disputes between food, feed, and supplement categories across FDA, EFSA, and NMPA regimes multiply compliance burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Extracts from Single Cell Protein and Other Conventional Sources Market |
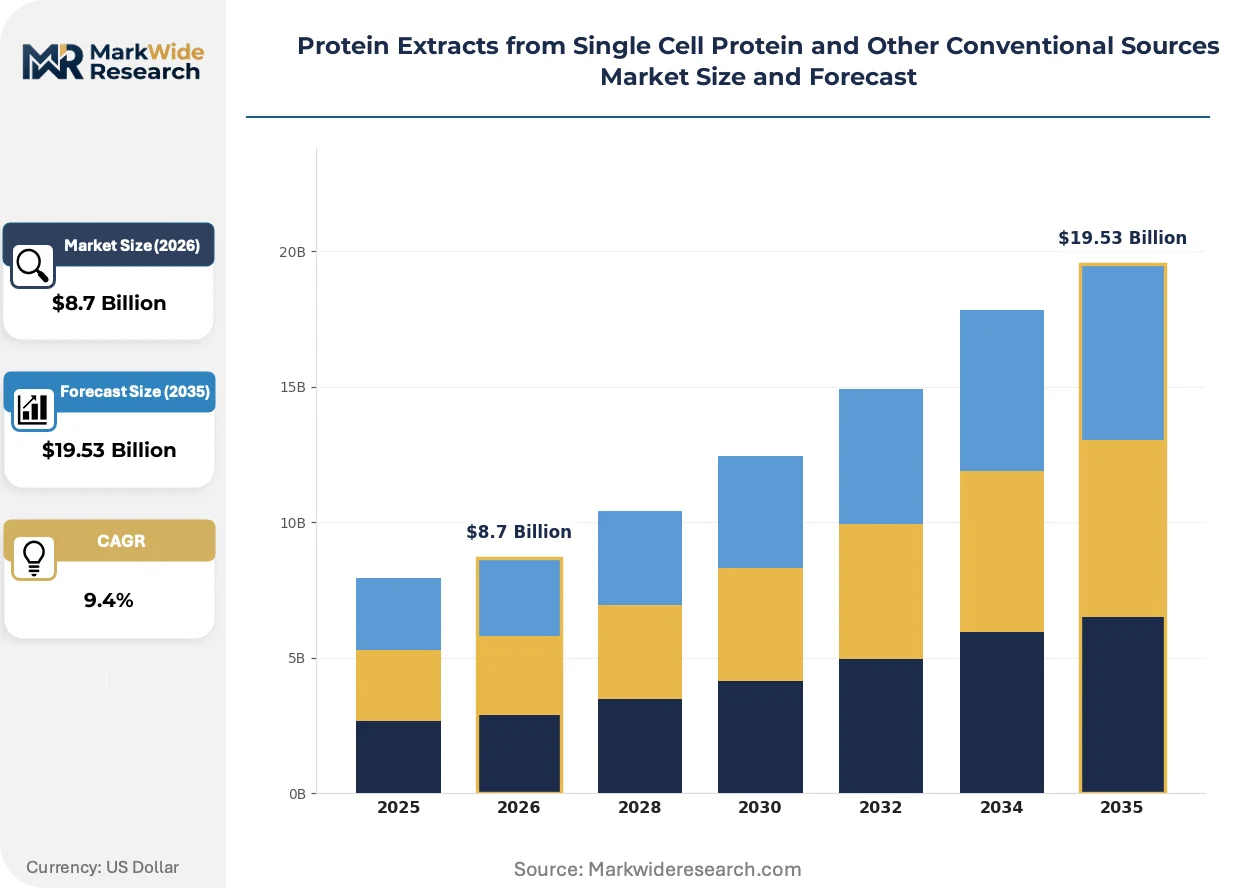
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yeast Extracts, Algal Protein, Bacterial Protein, Plant Protein Form: Powder, Liquid, Granules, Paste Application: Nutritional Supplements, Animal Feed, Food Processing, Biofuel End User: Food Industry, Agriculture, Pharmaceuticals, Nutraceuticals |
| Companies Covered | Cargill Incorporated, The Archer-Daniels-Midland Company, DuPont de Nemours Inc., Koninklijke DSM N.V., Ajinomoto Co. Inc., Kerry Group plc, Ingredion Inc., Unilever, Lallemand Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Extracts from Single Cell Protein and Other Conventional Sources Market Evolving Landscape
Continuous processing architectures and regulatory data science are compressing development timelines while procurement models shift toward embedded technical partnerships rather than spot market transactions.
Precision fermentation platforms utilizing methanotrophic and hydrogen-oxidizing bacteria are collapsing the cost structure for single cell protein production. Aquaculture feed formulators in Norway and Southeast Asia are adopting these inputs at pilot scale, enabling volume displacement of fishmeal and soy protein concentrate in salmon and shrimp diets. The structural consequence is collapsing capital intensity requirements per ton of protein output as continuous culture systems replace batch fermentation.
EFSA's implementation of the Transparency Regulation for novel food applications is tightening data requirements for single cell protein safety dossiers. Industrial consequence includes extended review timelines and higher toxicological study costs for entrants without existing microbial chassis approvals. Yeast-based ingredients with beverage fermentation heritage face lower regulatory friction than bacterial proteins from non-traditional chassis, concentrating development investment in Saccharomyces platforms.
Formulation partnerships are replacing transactional ingredient purchasing in savory taste modulation applications. Major food manufacturers are embedding protein supplier technical teams within product development workflows, compressing iteration cycles for clean-label reformulations. This pattern is most visible in Germany and the Netherlands, where fermentation-derived yeast extracts compete directly with hydrolyzed vegetable proteins for umami functionality in processed meat alternatives.
Protein Extracts from Single Cell Protein and Other Conventional Sources Market Segmentation
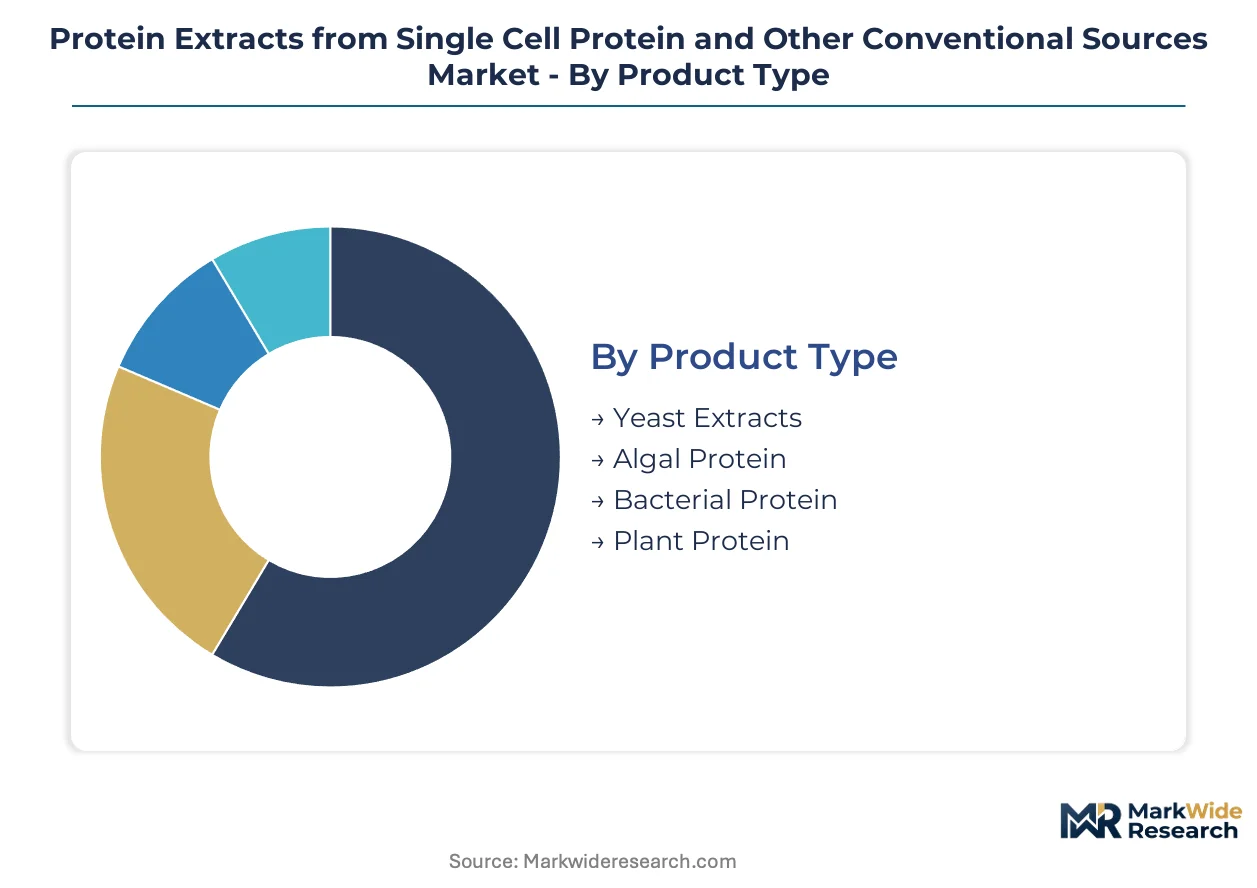
Segmentation in protein extracts reveals divergent margin structures and regulatory pathways across source materials and delivery formats. Product type determines extraction complexity and novel food authorization burden, while application dictates price realization and customer concentration.
Product Type:
Mature extraction infrastructure anchors established categories, while emerging fermentation platforms reshape cost curves for novel chassis.
- Yeast Extracts:Recovered from Saccharomyces biomass via autolysis or enzymatic hydrolysis, typically achieving 50-70% protein content with complete amino acid profiles. Beverage fermentation coproduct supply chains in Germany and the Netherlands concentrate volume leadership, though EFSA transparency regulations are extending safety dossier timelines for new entrants.
- Algal Protein:Recovered from Chlorella or Spirulina biomass through mechanical disruption and aqueous extraction, achieving 60-80% protein with omega-3 lipid cofractionation potential. Nutritional supplement applications in Germany absorb premium volumes, where allergen-free positioning justifies unit economics above plant protein alternatives.
- Bacterial Protein:Methanotrophic fermentation from methane feedstock yields 70-90% protein content with favorable amino acid scoring for aquaculture.
- Plant Protein:Soy and pea isolates from established oilseed processing sustain the largest installed extraction capacity globally.
Yeast extracts retain volume leadership; bacterial protein holds the steepest expansion curve.
Form:
Physical state determines handling economics, shelf stability requirements, and integration complexity across downstream manufacturing processes.
- Powder:Spray-dried or roller-dried particulates with moisture content below 5%, enabling extended ambient storage and bulk logistics. Nutritional supplement manufacturers in Germany prefer powder formats for encapsulation and tablet compression workflows.
- Liquid:Concentrated protein suspensions or hydrolysates with 20-40% solids content, requiring refrigerated distribution chains. Food processing applications favor liquid delivery for direct incorporation into savory taste modulation systems without rehydration steps.
- Granules:Agglomerated particles with controlled dissolution properties, targeting feed milling operations where dust generation creates handling hazards.
- Paste:Semi-solid concentrates with high water activity, common in yeast extract derivatives for umami flavor bases.
Powder commands the broadest addressable market; liquid is climbing fastest in food processing integration.
Application:
End-use differentiation separates commodity feed rations from premium nutritional positioning, with regulatory classification determining accessible market segments.
- Nutritional Supplements:Protein isolates and hydrolysates formulated for sports nutrition, clinical nutrition, and wellness positioning. Algal and yeast proteins in Germany concentrate demand here, where EFSA novel food authorizations enable premium pricing against commodity alternatives.
- Animal Feed:Bacterial protein from methanotrophic fermentation displaces fishmeal in Norwegian and Chilean salmon aquaculture, driven by supply security mandates and marine ingredient cost volatility.
- Food Processing:Yeast extracts and hydrolyzed proteins for umami functionality in processed meat alternatives and savory formulations.
- Biofuel:Protein coproduct recovery from algae cultivation systems originally installed for lipid extraction toward renewable diesel.
Animal feed retains volume leadership; nutritional supplements hold the steepest expansion curve.
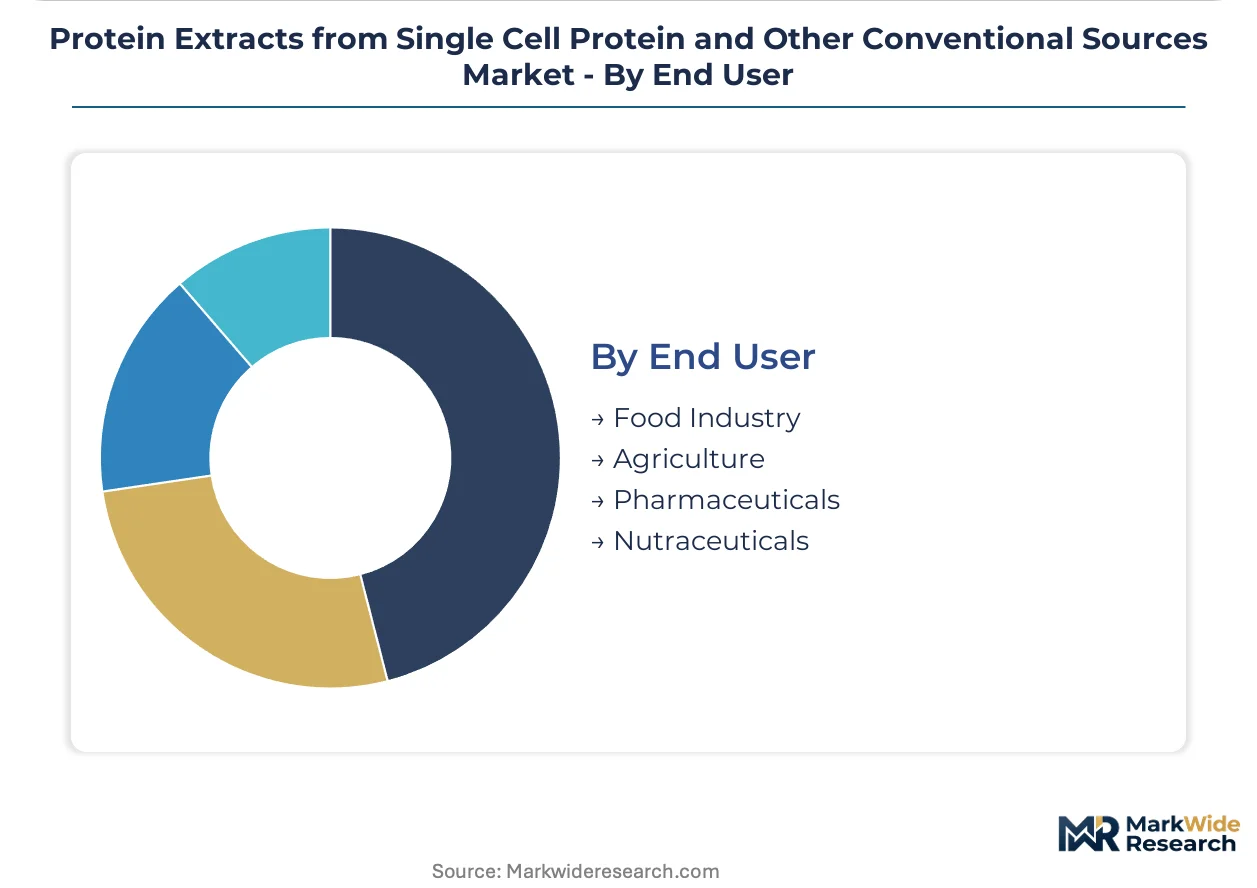
End User:
Customer type determines technical service intensity, contract structure, and regulatory compliance burden across divergent procurement workflows.
- Food Industry:Large-scale manufacturers of processed foods, meat alternatives, and savory seasonings requiring consistent functional performance. Formulation partnerships in Germany and the Netherlands are embedding supplier technical teams within customer R&D workflows.
- Agriculture:Feed compounders and integrated aquaculture operations sourcing protein inputs for ration optimization. Norwegian salmon producers are piloting bacterial protein inclusion rates above 20% in grower diets.
- Pharmaceuticals:Fermentation media suppliers and excipient manufacturers requiring low-endotoxin protein fractions for biologic production.
- Nutraceuticals:Branded supplement marketers targeting clean-label positioning and allergen-free claims in direct-to-consumer channels.
Food industry retains volume leadership; nutraceuticals hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany absorbs premium volumes of algal protein for nutritional supplements, while the United States and China prioritize bacterial protein for aquaculture feed rations, creating divergent consumption patterns across major demand centers.
Germany
EFSA novel food authorizations accelerate yeast and algal protein commercialization for clean-label applications. The Transparency Regulation tightens safety dossier requirements, extending review timelines for new microbial chassis. Baden-Württemberg and Bavaria host concentrated precision fermentation R&D clusters that anchor scaled extraction operations for European supply.
United States
FDA GRAS self-determination pathways enable faster market entry for established Saccharomyces platforms in savory taste modulation. Enforcement discretion on fermentation-derived proteins is tightening, prompting proactive engagement with the agency. Midwest oilseed processing corridors in Illinois and Iowa sustain depreciated plant protein extraction assets that compete on price.
China
NMPA and SAMR jointly regulate new food ingredient registrations under GB standards specifying heavy metal and microbiological limits. Yangtze River Delta biotech parks in Shanghai and Jiangsu province concentrate methanotrophic fermentation pilot facilities for aquaculture feed applications. Early movers with validated extraction processes capture compliance barriers as competitive moats.
Norway
Marine ingredient cost volatility and supply security mandates drive bacterial protein adoption in salmon aquaculture above 20% inclusion rates in grower diets. The Norwegian Food Safety Authority monitors feed safety alongside EU regulatory alignment. Bergen and Trondheim host integrated aquaculture operations piloting methane-derived protein at commercial scale.
Netherlands
Formulation partnerships embed supplier technical teams within food manufacturer R&D workflows for umami functionality in processed meat alternatives. The Dutch Food and Consumer Product Safety Authority enforces EU novel food regulations with national implementation specificity. Eindhoven and Wageningen fermentation corridors concentrate yeast extract production for savory applications.
Protein Extracts from Single Cell Protein and Other Conventional Sources Market Competitive Landscape
Capability concentration sits with precision fermentation specialists; scale advantage sits with diversified agribusiness conglomerates. The market structures around three tiers: global oilseed processors with backward integration into microbial biomass, European biotechnology platforms with novel food authorization expertise, and regional yeast extract specialists serving beverage fermentation coproduct streams. Dominant competitive moves include strategic partnerships for formulation embedding and capacity expansion in methanotrophic fermentation.
Within the diversified agribusiness tier, Cargill Incorporated and The Archer-Daniels-Midland Company occupy positions anchored by global oilseed processing footprints. Koninklijke DSM N.V. exemplifies the European biotechnology platform archetype, representing precision fermentation capability concentration. Kerry Group plc sits within the specialty ingredient formulation tier, exemplifying application-specific technical service integration. These three anchors illustrate divergent paths to value capture upstream of commodity manufacturing.
| Leading Market Players |
|---|
| Cargill Incorporated |
| The Archer-Daniels-Midland Company |
| DuPont de Nemours Inc. |
| Koninklijke DSM N.V. |
| Ajinomoto Co. Inc. |
| Kerry Group plc |
| Ingredion Inc. |
| Unilever |
| Lallemand Inc. |
| Others |
Value Network & Pricing Analysis
Baden-Württemberg's precision fermentation capacity concentration anchors European supply leverage, translating upstream biotech infrastructure into pricing power for yeast and algal protein isolates. Contract structures in this cluster reward long-term offtake commitments with volume discounts that spot buyers forfeit.
Pricing Analysis
Long-term offtake agreements dominate procurement for methanotrophic bacterial protein in Norwegian aquaculture, while spot transactions persist for yeast extract derivatives in savory applications. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-authorized novel food ingredients from feed-grade bacterial protein and commodity plant isolates. Cost compression in standard-grade yeast extracts is intensifying because depreciated beverage fermentation coproduct streams flood European supply. Feed compounders in aquaculture exhibit highest price sensitivity; nutraceutical brands purchasing allergen-free algal protein show lowest.
Supply Chain Analysis
Methane feedstock availability in Norway, natural gas pricing in Germany, and agricultural substrate costs in the United States anchor upstream cost structures for single cell protein production. Downstream purification draws from chromatography resin suppliers, membrane filtration OEMs, and spray-drying equipment manufacturers concentrated in Germany and the Netherlands. Single-source vulnerability runs through Chinese fermentation equipment fabrication for methanotrophic bioreactor installations. Distribution runs through embedded technical service teams for food processing customers, bulk logistics for feed compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation platform economics are collapsing protein production cost curves, creating interoperability between microbial chassis libraries and downstream extraction infrastructure that favors ecosystem orchestrators over point-product suppliers.
For Market Incumbents: Entrench formulation partnerships with major food manufacturers by embedding technical teams within customer R&D workflows, compressing iteration cycles for clean-label reformulations. Deepen backward integration into captive yeast fermentation capacity in Baden-Württemberg to defend margin position against depreciated beverage coproduct streams. Prioritize EFSA novel food authorization maintenance for Saccharomyces platforms as bacterial chassis face extended dossier timelines under Transparency Regulation. For New Entrants and Emerging Players: Pursue white-space positioning in methanotrophic bacterial protein for aquaculture feed, where Norwegian inclusion rate pilots above 20% signal demand elasticity. Target China's NMPA registration pathway for new food ingredients, where GB standard compliance creates moats against late movers. Anchor go-to-market through direct technical service embedding with feed formulators rather than distributor intermediation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation platform specialists with validated extraction processes and regulatory dossier libraries over commodity plant protein processors with depreciated assets. Long-term viability across the analysis window rests on novel food authorization velocity and fermentation scale-up talent retention. The signal to watch is EFSA transparency regulation implementation timelines as inflection indicator for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Authorization | Accelerates commercialization timelines for yeast and algal protein isolates in EU food applications. |
| Methanotrophic Fermentation Scale-Up | Collapses unit economics for bacterial protein in Norwegian salmon aquaculture feed rations. |
| Backward Integration into Yeast Fermentation | Captures upstream margin from beverage coproduct streams for Cargill and ADM oilseed processors. |
| Formulation Partnership Embedding | Compresses customer acquisition costs for Kerry Group in savory taste modulation applications. |
| China NMPA Registration | Creates compliance moats under GB standards for heavy metal and microbiological limits. |
Research Methodology
The analysis maps yeast extract derivatives, algal protein isolates, methanotrophic bacterial protein, and plant protein concentrates, each validated through fermentation process engineers, novel food regulatory consultants, feed formulation scientists, and savory applications R&D directors. Primary interviews with DSM technical service teams, Cargill procurement leads, and Norwegian aquaculture nutritionists combined with secondary validation from EFSA transparency regulation filings, NMPA registration databases, and SEC 10-K disclosures for diversified agribusiness conglomerates. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Assumptions held EFSA review timelines and natural gas feedstock pricing as fixed parameters while varying methanotrophic fermentation yield improvements and aquaculture inclusion rate adoption curves across the projection horizon. Segmentation dimensions modeled include protein source taxonomy, physical form factor, application end-use, and customer procurement archetype. CAGRs derived from installed fermentation capacity expansion schedules and substitution elasticity estimates for fishmeal displacement in salmon diets.
Macroeconomic conditions sit as an overlay; deviation in European natural gas pricing or Chinese regulatory enforcement intensity would shift the trajectory for bacterial protein cost competitiveness. Forecasts reflect assumptions about fermentation scale-up talent availability and EFSA dossier approval velocity. Cross-checking against aquaculture feed formulation substitution rates reported by Norwegian Food Safety Authority monitoring is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Custom Dry Ingredients Blends Market
Ingredients
US Ingredients Market
Ingredients
China Beer Adjuncts Market
Ingredients
Specialty Yeast Market
Ingredients
Commercial Amino Acids Market
Ingredients
Fish Peptones Market
Ingredients
Europe Edible Oil Market
Ingredients
Protein Ingredients Market
Ingredients
Chickpea Fiber Market
Ingredients
Indonesia Edible Oil Market
Ingredients
Stabilized Starch Market
Ingredients
Anti-Aging Ingredients Market
Ingredients
Global Cocoa Products Market
Ingredients
Smoked Yeast Market
Ingredients
Industrial and Bar-B-Que Charcoal Market
Ingredients
High Oleic Oil Market