
 Europe Agar Market | 2026-2036
Europe Agar Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Agar Market Foresight
Portugal's seaweed processing corridor is narrowing the supply gap between Atlantic harvesting capacity and Central European laboratory demand. Hispanagar S.A. anchors its extraction operations near coastal Galicia, leveraging proximity to raw red algae beds. Iberagar competes through specialized hydrocolloid refining for pharmaceutical-grade batches. Sobigel SAS dominates food-service distribution channels across France and Belgium.
Agar denotes a gelatinous polysaccharide extracted primarily from red algae of the Rhodophyta phylum, composed of repeating agarose and agaropectin units that form thermoreversible gels at concentrations as low as one percent. It functions as a vegetarian gelling agent, culture medium solidifier, and stabilizer across food science and microbiology. Powder formulations lead pharmaceutical procurement due to precise dissolution control and batch consistency. Biotechnology applications in culture media represent the fastest-expanding segment as cell-line research intensifies. Food & Beverage demand sustains volume throughput through confectionery and dairy stabilization requirements.
EFSA purity standards govern food-grade agar specifications across EU member states, while REACH registration mandates trace heavy-metal thresholds in imported seaweed biomass. EMA guidelines for culture media components shape pharmaceutical-grade certification pathways. Stakeholders must monitor evolving EU Green Deal sourcing rules on marine biomass traceability and decide between Atlantic coastal partnerships versus Pacific supply diversification before regulatory deadlines tighten.
Market Dynamics
EFSA clean-label mandates and REACH chemical safety protocols are tightening extraction standards across European agar supply chains, forcing processors to reconfigure coastal harvesting partnerships and laboratory-grade certification pathways.
Growth Catalysts
- Pharmaceutical corridor concentration:France's Lyon-Rhône-Alpes cluster anchors cell-line research demand for culture media solidifiers. Biotechnology laboratories prioritize batch-consistent powder formulations.
- Plant-based formulation expansion:Iberian food manufacturers accelerate vegetarian gelling agent substitution in confectionery and dairy stabilization.
- EU Green Deal traceability rules:Marine biomass sourcing documentation requirements favor Atlantic coastal partnerships over Pacific supply diversification.
Market Restraints
- Red algae supply concentration:Galician and Portuguese Atlantic harvesting beds dominate raw material access, creating geographic single-point vulnerability.
- Heavy-metal threshold compliance:REACH registration mandates for imported seaweed biomass impose costly pre-processing and testing burdens on smaller extractors.
- Carrageenan substitution pressure:Alternative hydrocolloids compete in food-service applications where thermoreversible gel precision is less critical.
Strategic Opportunities
- Central European laboratory demand:Germany's pharmaceutical research hubs remain underpenetrated relative to Atlantic supply capacity.
- Specialized hydrocolloid refining:Pharmaceutical-grade batch certification creates margin expansion beyond commodity food-service distribution.
- CSRD sustainability disclosure:Corporate reporting mandates reward transparent marine biomass chain-of-custody documentation.
Industry Challenges
- Pharmaceutical-grade certification timelines:EMA culture media component approval pathways extend 18-24 months, freezing working capital.
- Extraction technician scarcity:Specialized red algae processing expertise concentrates in coastal Galicia and northern Portugal, limiting continental European facility expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Agar Market |
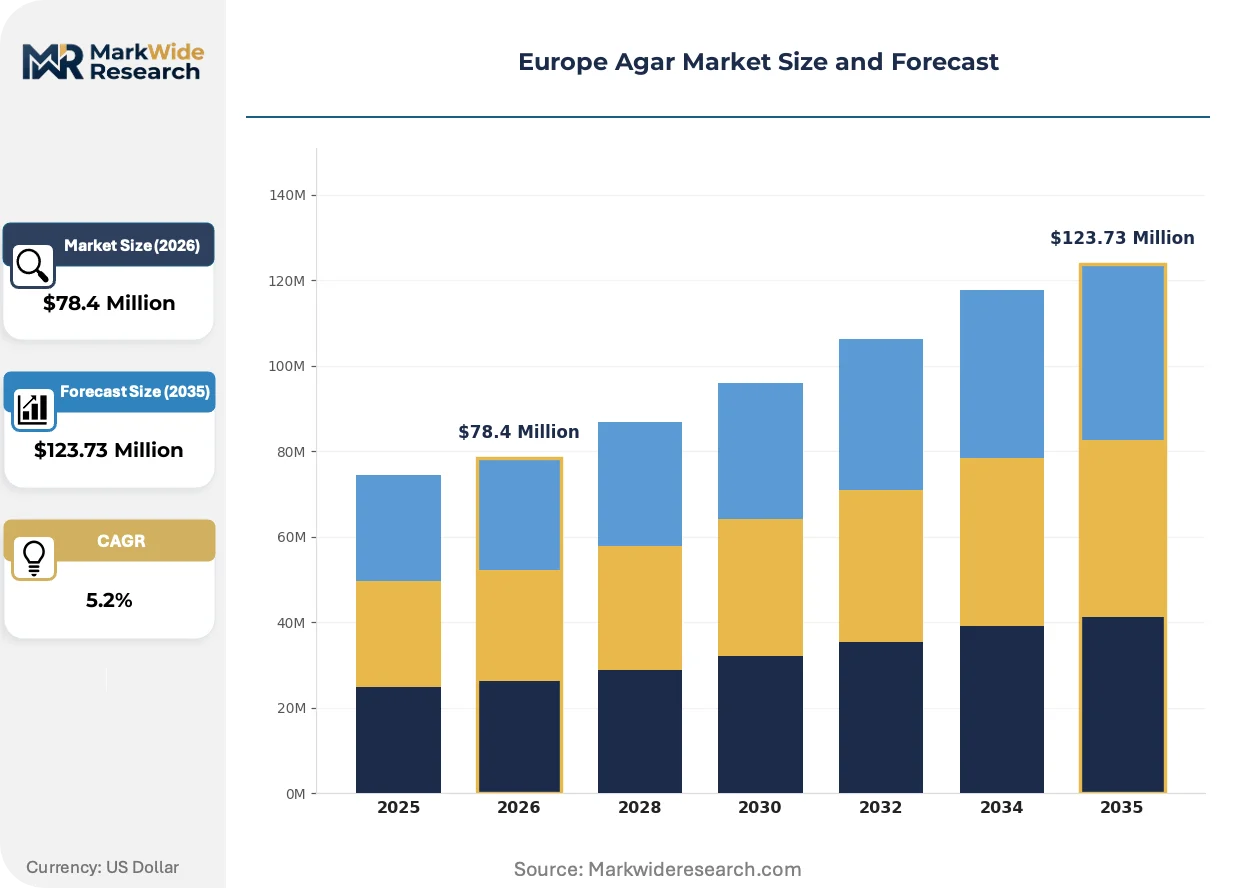
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $123.73 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Flakes, Bars, Sheets Application: Food & Beverage, Pharmaceuticals, Biotechnology, Personal Care End User: Food Manufacturers, Research Institutions, Cosmetic Companies, Healthcare Providers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Hispanagar S.A., Industrial Roko SA, Setexam, Sobigel SAS, B&V Agar s.r.l., Iberagar - Indústria de Extractos Algícolas, S.A., ROKO GmbH, TIC Gums, Inc., CP Kelco, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Agar Market Shifts & Advancements
Clean-label certification and precision dissolution control are reshaping competitive differentiation between food-grade commodity supply and pharmaceutical-grade specialty batches.
Enzymatic pre-treatment of red algae biomass is collapsing traditional multi-day alkali extraction cycles into single-shift operations. Spanish processors deploy cellulase and protease cocktails to accelerate agarose chain liberation. Pharmaceutical laboratories gain faster batch turnaround without thermochemical degradation of gel strength.
REACH Annex XVII restrictions on heavy-metal content in imported seaweed are tightening testing protocols for Asian biomass suppliers. ECHA guidance documents now specify atomic absorption spectroscopy thresholds for arsenic and lead. French extractors pivot toward verified Atlantic sourcing to preempt documentation gaps.
Belgian and Dutch distributors consolidate food-service procurement into direct mill relationships, bypassing layered importer networks. Confectionery manufacturers negotiate volume commitments against locked purity specifications. Channel compression is most visible in Benelux dairy stabilization supply.
Europe Agar Market Segmentation
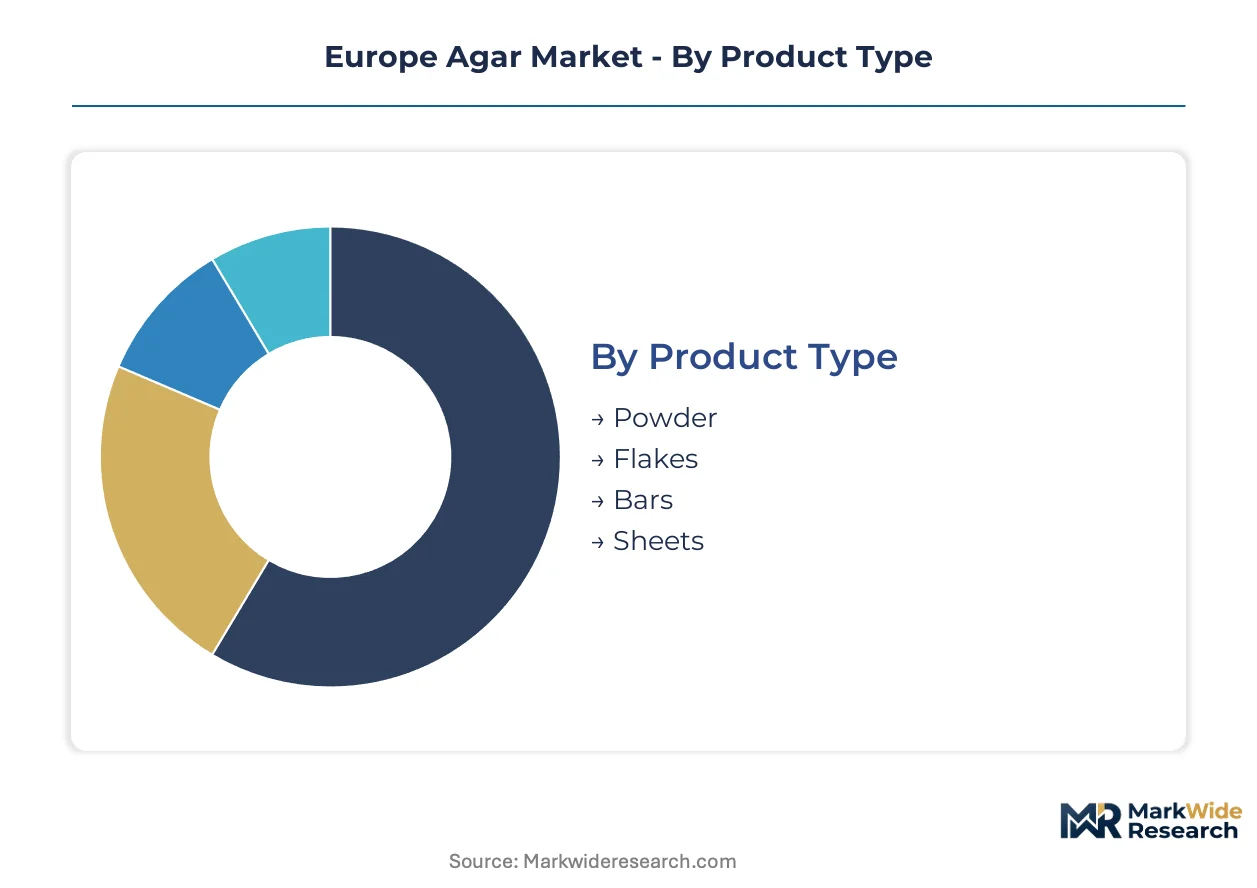
Agar procurement patterns diverge sharply between precision-driven laboratory applications and cost-sensitive food-service volumes. EFSA purity tiers and REACH traceability mandates create distinct certification pathways that reshape how processors configure product formats and channel strategies.
Product Type:
Use-case spectrum spans thermochemical stability requirements in cell culture against dissolution speed demands in industrial kitchens.
- Powder:Micronized agarose particles enable precise concentration control in pharmaceutical-grade batches. France's Lyon-Rhône-Alpes biotechnology corridor drives procurement for culture media solidifiers where batch consistency governs cell-line viability.
- Flakes:Intermediate surface-area-to-volume ratio suits mid-scale confectionery operations requiring gradual hydration. Iberian dairy stabilization facilities favor flake formulations for thermoreversible gel production in plant-based desserts.
- Bars:Traditional format retains artisan food-service preference in Mediterranean confectionery traditions. Coastal Portuguese processors supply bars to heritage sweet manufacturers.
- Sheets:Uniform thickness enables standardized portioning in commercial bakery applications. Belgian distributors stock sheets for Benelux channel consolidation.
Established volume favors powder; emerging adoption favors flakes.
Application:
Margin concentration tracks regulatory burden intensity across end-use categories.
- Food & Beverage:Thermoreversible gel functionality stabilizes confectionery, dairy alternatives, and canned meat suspensions. Spain and Portugal dominate formulation demand as EFSA clean-label guidelines accelerate vegetarian gelling agent substitution.
- Pharmaceuticals:EMA culture media component certification requires heavy-metal documentation below REACH Annex XVII thresholds. German research hubs remain underpenetrated relative to Atlantic supply capacity.
- Biotechnology:Cell-line research intensity in French pharmaceutical corridors drives powder procurement for precise dissolution protocols.
- Personal Care:Hydrocolloid film-forming properties serve cosmetic emulsion stabilization. Cosmetic companies in Italy and France source pharmaceutical-grade residuals.
Food & Beverage sustains volume throughput; biotechnology climbs the fastest on cell-culture research expansion.
End User:
Customer-type fragmentation reflects divergent specification stringency between industrial procurement and laboratory procurement.
- Food Manufacturers:Volume commitments lock purity specifications against direct mill relationships. Benelux dairy stabilization supply concentrates procurement power.
- Research Institutions:Batch-consistent powder formulations command premium pricing for cell-line reproducibility. Central European laboratory demand outpaces Atlantic supply penetration.
- Cosmetic Companies:Film-forming and emulsion stabilization requirements drive hydrocolloid refining specialization.
- Healthcare Providers:Culture media preparation for diagnostic microbiology sustains steady pharmaceutical-grade consumption.
Food manufacturers anchor volume scale; research institutions command margin expansion.
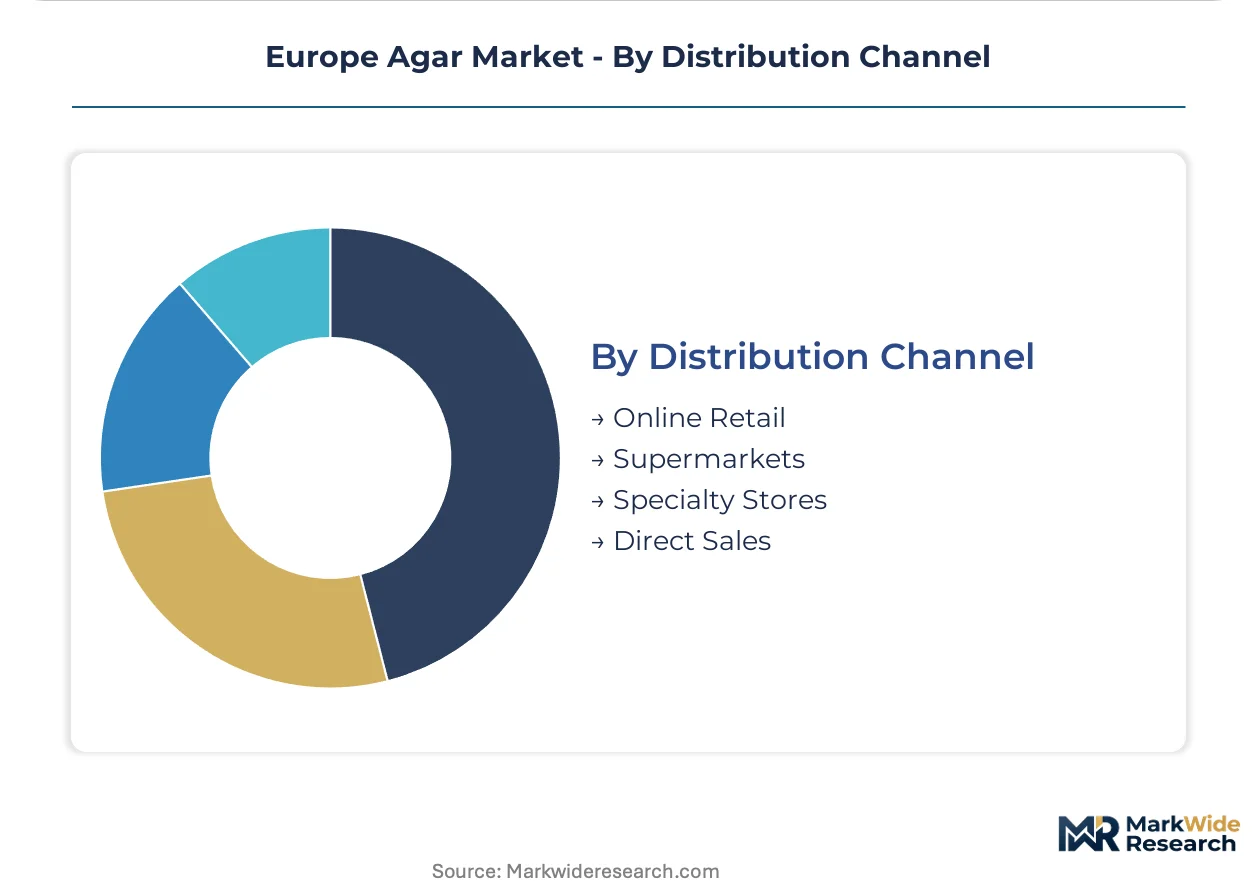
Distribution Channel:
Channel compression dynamics reshape margin capture between extractors and end-users.
- Online Retail:Small-batch laboratory procurement and artisan food-service sourcing converge on digital platforms. Specialized hydrocolloid distributors deploy e-commerce for Central European reach.
- Supermarkets:Consumer-packaged agar for home confectionery remains marginal against commercial volumes.
- Specialty Stores:Heritage bakery supply and molecular gastronomy ingredient retail sustain niche positioning in Mediterranean urban centers.
- Direct Sales:Belgian and Dutch distributors consolidate food-service procurement into direct mill relationships, bypassing layered importer networks for locked purity specifications.
Direct sales capture volume concentration; online retail gains share fastest on laboratory procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA clean-label mandates and REACH chemical safety protocols anchor regulatory gravity across Western European agar supply chains, with extraction capacity concentrating along Atlantic coastal zones and pharmaceutical demand clustering in continental research corridors.
Spain
Galicia's red algae harvesting beds supply raw biomass to coastal extraction facilities, while Madrid-based food manufacturers accelerate plant-based gel substitution under EFSA purity guidelines. The Lyon-Rhône-Alpes pharmaceutical corridor across the border draws refined powder shipments for culture media applications.
France
Biotechnology laboratories in Lyon and the Rhône-Alpes cluster drive pharmaceutical-grade powder procurement for cell-line research, with CSRD sustainability disclosure requirements rewarding transparent marine biomass documentation. REACH Annex XVII heavy-metal thresholds shape importer testing protocols at Atlantic ports.
Germany
Pharmaceutical research hubs in Baden-Württemberg and Bavaria remain underpenetrated relative to Atlantic supply capacity, creating procurement gaps for batch-consistent culture media components. EMA certification timelines extend working capital cycles for extractors seeking laboratory-grade entry.
Portugal
The seaweed processing corridor narrows supply gaps between Atlantic harvesting capacity and Central European demand, with enzymatic pre-treatment innovations collapsing traditional extraction cycles. Northern Portuguese facilities specialize in hydrocolloid refining for pharmaceutical-grade certification pathways.
Belgium and Netherlands
Benelux distributors consolidate food-service procurement into direct mill relationships, bypassing layered importer networks for locked purity specifications in dairy stabilization applications. Channel compression concentrates volume commitments against EFSA-compliant documentation standards.
Europe Agar Market Competitive Landscape
Coastal extractors and continental distributors split the market along raw material access versus channel control vectors. Vendor concentration remains moderate, with Iberian processors commanding upstream biomass proximity and French-Belgian intermediaries dominating downstream logistics. Two strategic archetypes predominate: Atlantic-integrated harvester-extractors with captive red algae supply, and Central European laboratory specialists with pharmaceutical-grade certification capabilities. Competitive moves center on enzymatic extraction technology licensing and direct mill relationship consolidation bypassing traditional importer tiers.
Among Iberian harvester-extractors, Hispanagar S.A. and Iberagar occupy positions exemplifying coastal integration archetypes, with geographic nomenclature indicating Spanish and Portuguese origins respectively. Sobigel SAS represents the distribution-focused tier, anchoring food-service channel control across France and Belgium. These three entities illustrate the structural divide between raw material proximity and market access specialization that defines competitive positioning in European agar supply.
| Leading Market Players |
|---|
| Hispanagar S.A. |
| Industrial Roko SA |
| Setexam |
| Sobigel SAS |
| B&V Agar s.r.l. |
| Iberagar - Indústria de Extractos Algícolas, S.A. |
| ROKO GmbH |
| TIC Gums, Inc. |
| CP Kelco |
| Others |
Supply & Pricing Matrix
Atlantic freight corridors from Galician ports to Central European laboratory hubs carry extraction-derived agar at rates that compress margins for pharmaceutical-grade batches while widening spreads between food-service commodity tiers and certified culture media components. EFSA purity documentation costs and REACH heavy-metal testing burdens accumulate through each logistics node, forcing processors to pass compliance expenditures downstream or absorb them against locked long-term contracts.
Pricing Analysis
Geographic price spreads between Iberian coastal extraction sites and German pharmaceutical research hubs exceed those within food-service channels by substantial margins. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels reflects EMA certification timelines and batch-traceability documentation depth. Pricing pressure stems from enzymatic extraction technology licensing costs spreading across smaller processors. Food manufacturers exhibit highest price sensitivity due to carrageenan substitution availability, while biotechnology laboratories accept premium positioning for cell-line reproducibility guarantees.
Supply Chain Analysis
Export-control scrutiny under REACH Annex XVII restrictions on heavy-metal content limits Asian seaweed biomass flows into European processing facilities. Raw material access concentrates in Spain, Portugal, and Morocco's Atlantic harvesting beds, with red algae biomass, cellulase enzyme cocktails, and laboratory certification services forming critical input dependencies. Single-source vulnerability runs through Galician coastal harvesting corridors where climate fluctuation threatens seasonal yield consistency. Distribution runs through direct mill relationships consolidating Benelux food-service procurement alongside specialized hydrocolloid distributors serving Central European research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's agar market sustains defensive moats through regulatory entrenchment, where EMA culture media certification and REACH traceability documentation create switching costs that lock laboratory procurement relationships across multi-year validation cycles.
For Market Incumbents: Pre-empt carrageenan substitution pressure in food-service channels by accelerating enzymatic extraction technology deployment to collapse production cycle times. Secure backward integration into Atlantic coastal harvesting partnerships before EU Green Deal traceability deadlines tighten, anchoring biomass chain-of-custody documentation that smaller extractors cannot replicate.
For New Entrants and Emerging Players: Pursue underpenetrated German pharmaceutical research hubs in Baden-Württemberg and Bavaria where Atlantic supply capacity has not established direct laboratory relationships. Target biotechnology applications with specialized hydrocolloid refining capabilities, entering through e-commerce procurement platforms that bypass entrenched distributor networks.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with agar extraction divisions lacking pharmaceutical-grade certification focus. Long-term viability hinges on regulatory compliance infrastructure rather than commodity volume scale. Watch EMA approval pathway acceleration signals as inflection indicators for working capital efficiency improvements.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Technology Licensing | Spanish processors deploying cellulase-protease cocktails collapse multi-day alkali cycles into single-shift operations. |
| Atlantic Coastal Harvesting Partnership Consolidation | Galician and Portuguese biomass access secures EU Green Deal traceability compliance ahead of regulatory deadlines. |
| Pharmaceutical-Grade Certification Investment | EMA culture media component approval pathways extend 18-24 months, freezing competitors without capital reserves. |
| Direct Mill Relationship Expansion | Belgian and Dutch distributors bypass layered importer networks for locked purity specifications in dairy stabilization. |
| Central European Laboratory Channel Development | German biotechnology hubs remain underpenetrated relative to Atlantic supply capacity, creating procurement gaps. |
Research Methodology
A standing panel of red algae extraction facility managers, pharmaceutical procurement officers at biotechnology laboratories, EFSA regulatory compliance consultants, and Benelux dairy stabilization supply planners provided ongoing calibration against secondary validation from ECHA guidance documents, EMA submission databases, EU customs trade statistics, and CSRD sustainability disclosure filings. Bottom-up volume modeling across extraction facility capacity and top-down demand triangulation from end-use consumption patterns converged on segment-level estimates.
Scenario-bracketing around regulatory implementation timelines and enzymatic technology adoption curves anchored projections across the analysis window. Segmentation dimensions spanned product format, application category, end-user type, and distribution channel, with CAGRs derived from regression analysis of historical volume trajectories against pharmaceutical research expenditure growth and plant-based formulation substitution rates.
Sensitivities concentrate around EMA certification timeline extensions, Atlantic harvesting yield volatility, and REACH heavy-metal threshold adjustments. Material shifts in EU Green Deal marine biomass traceability requirements or enzymatic extraction technology licensing cost structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Wheat Starch Market
Ingredients
Soluble Fibers Market
Ingredients
Hydrolysed Vegetable Protein (HVP) Market
Ingredients
APAC Savoury Ingredients Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
Tapioca Market
Ingredients
Rennet Market
Ingredients
Hexane-Free Protein Market
Ingredients
Soy Protein Concentrate Market
Ingredients
North America Soy Protein Concentrate Market
Ingredients
Middle East and Africa Fermented Ingredients Market
Ingredients
North America Dairy Protein Ingredients Market
Ingredients
Marine Protein Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Flaxseed Derivatives Market
Ingredients
Soy Peptones Market