
 Oat Ingredients Market | 2026-2036
Oat Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Oat Ingredients Market Analytics
EU Green Deal compliance is broadening the cost-of-entry calculus for oat ingredient suppliers entering European markets. Cargill, Incorporated leverages its integrated grain handling infrastructure to manage origin-traceability costs. Lantmännen sustains competitive positioning through cooperative-owned milling assets across Nordic supply zones. Grain Millers, Inc. anchors North American supply with specialty oat processing capabilities.
Oat ingredients comprise milled oat fractions—whole oats, flour, bran, and extracted milk bases—containing beta-glucan levels typically ranging from 3% to 5% by weight and serving as functional fiber sources in formulated foods. Bakery applications dominate volume throughput, while oat milk commands the fastest value expansion as dairy alternatives reshape beverage formulation. Food manufacturers represent the most concentrated end-user segment, with procurement patterns favoring suppliers offering dual-certified organic and gluten-free oat streams.
EFSA guidelines on beta-glucan health claims and FDA standards for gluten-free labeling shape product specification thresholds and market access requirements across major demand zones. USDA organic certification and EU REACH chemical compliance add further compliance layers for multinational suppliers. Stakeholders must monitor evolving clean-label thresholds and carbon-accounting rules that will redefine supplier qualification criteria.
Market Dynamics
Plant-based beverage manufacturers are accelerating oat milk procurement at industrial scale, compressing legacy dairy supply chains and forcing ingredient processors to reconfigure milling capacity toward beta-glucan extraction protocols.
Growth Catalysts
- EU Green Deal sustainable sourcing mandates:The EU Green Deal is tightening traceability requirements for agricultural inputs entering European food systems. Oat ingredient suppliers with certified carbon-accounting systems gain preferential access to German and Dutch procurement channels.
- Bakery sector functional fiber substitution:Food manufacturers are reformulating baked goods to replace wheat bran with oat-derived beta-glucan fractions. This technical substitution is accelerating as clean-label thresholds harden across retail private-label specifications.
- Nordic cooperative processing infrastructure:Lantmännen's cooperative-owned milling assets across Sweden and Finland have expanded specialty oat fractionation capacity. This supply concentration is pulling additional Nordic acreage into certified organic oat production.
Market Restraints
- Gluten-free certification cost structure:Achieving FDA gluten-free labeling standards requires dedicated facility segregation and testing protocols. Small-scale oat processors face capital barriers to dual-certified organic and gluten-free production streams.
- Raw oat price volatility:Weather-driven yield fluctuations in Canadian prairie provinces and Ukrainian black-soil regions create input cost instability. Maltsters and millers lack long-term hedging instruments for specialty oat grades.
- Pea protein substitution threat:Plant-based beverage formulators are actively testing pea-protein milk bases as oat milk alternatives. Pea protein's amino acid completeness and lower water footprint are displacing oat in certain nutrition-positioned SKUs.
Strategic Opportunities
- Underpenetrated Brazilian foodservice channel:Brazilian quick-service chains and café operators have minimal oat milk penetration compared to North American benchmarks. Local dairy distributors represent untapped partnership pathways for ingredient suppliers.
- EFSA beta-glucan health claim expansion:EFSA guidelines currently permit cholesterol-reduction claims at specific beta-glucan thresholds. Broadening approved health indications would unlock pharmaceutical and clinical nutrition applications beyond conventional food uses.
- Precision fermentation convergence:Biotech startups are integrating precision fermentation with oat base substrates to produce hybrid dairy alternatives. This technology pairing could create novel ingredient categories with superior functional properties.
Industry Challenges
- Organic certification timeline compression:USDA organic certification requires three-year transition periods for conventional oat acreage. Supply shortages of certified organic oats are forcing manufacturers to accept split-crop sourcing with traceability complications.
- Legacy ERP integration with carbon-accounting platforms:Mid-size oat processors are struggling to retrofit existing inventory management systems with EU REACH chemical compliance and carbon-footprint tracking modules. Implementation costs are diverting capital from fractionation equipment upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oat Ingredients Market |
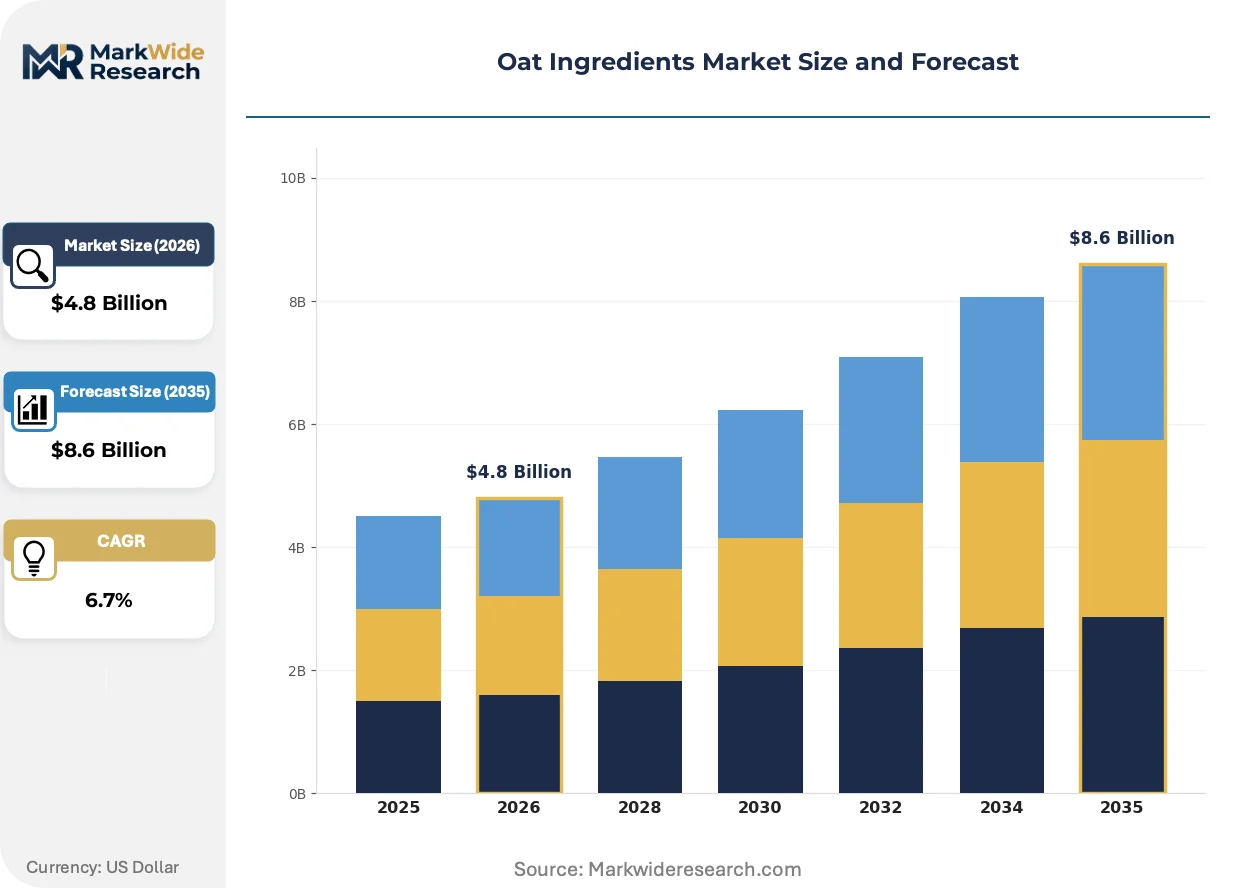
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Oats, Oat Flour, Oat Bran, Oat Milk Application: Bakery, Snacks, Beverages, Breakfast Cereals End User: Food Manufacturers, Retail Consumers, Food Service, Health Institutions Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales |
| Companies Covered | Avena Foods Ltd, Cargill, Incorporated, Lantmännen, Blue Lake Milling, General Mills Inc., Grain Millers, Inc., PepsiCo, Inc., Nestlé SA, Richardson International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oat Ingredients Market Evolving Landscape
Enzymatic processing technologies are restructuring how beta-glucan is extracted and stabilized, enabling ingredient suppliers to command premium positioning in functional food formulations previously dominated by synthetic hydrocolloids.
Hydrolyzed oat protein isolates are overtaking commodity oat flour in high-protein beverage applications. Sports nutrition brands and ready-to-drink meal replacement manufacturers are adopting these isolates for superior dispersibility and mouthfeel. This displacement is compressing margins for conventional milling operations while rewarding suppliers with enzymatic fractionation capabilities.
REACH chemical compliance requirements are forcing reformulation of cleaning and processing aids used in oat ingredient facilities. ECHA restrictions on specific sanitizers are driving adoption of enzymatic cleaning protocols. German and Dutch processing plants are absorbing the highest compliance costs, accelerating consolidation among smaller Nordic operators.
Direct contracting between oat ingredient suppliers and plant-based beverage brands is replacing spot-market purchasing. Large-format retailers are insisting on origin-traceable oat streams with batch-level documentation. This channel restructuring is most visible in German retail, where discounters now require supplier-specific sustainability scorecards as procurement gatekeepers.
Oat Ingredients Market Segmentation
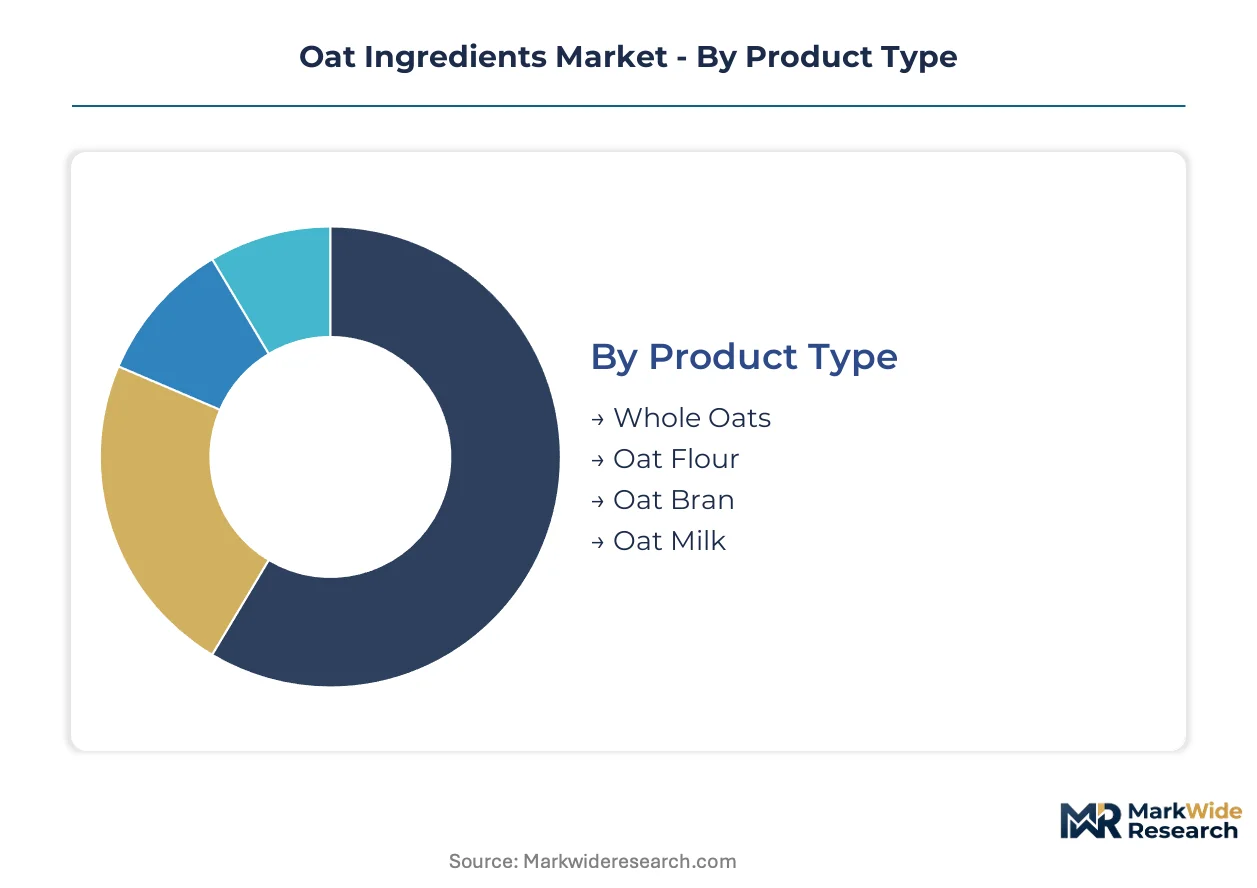
Oat ingredient procurement patterns diverge sharply across product formats and end-use channels. Suppliers configure milling assets and certification protocols around specific segment requirements rather than serving homogeneous demand pools.
Product Type:
Supply concentration varies dramatically by processing complexity and beta-glucan extraction yield.
- Oat Milk:Hydrolyzed oat bases with 3-5% beta-glucan content require enzymatic fractionation and aseptic stabilization. German beverage manufacturers and Dutch plant-based dairy specialists are pulling capacity expansion toward this segment as dairy alternatives reshape procurement specifications.
- Oat Bran:Concentrated beta-glucan fractions (8-12% by weight) serve functional food formulators replacing synthetic hydrocolloids. Health claim eligibility under EFSA guidelines drives premium positioning in cholesterol-management applications.
- Oat Flour:Standardized particle-size distributions support bakery sector reformulation for clean-label fiber enrichment. Milling operations in Nordic cooperative networks dominate supply.
- Whole Oats:Unfractionated grain streams supply conventional breakfast cereal manufacturers and animal feed compounders with minimal processing overhead.
Today's leader: Oat Milk. Tomorrow's challenger: Oat Bran.
Application:
End-use specifications determine certification requirements and margin structures across downstream channels.
- Beverages:Plant-based milk alternatives command the steepest expansion trajectory as retail discounters in Germany mandate origin-traceable oat streams with batch-level sustainability documentation.
- Bakery:Functional fiber substitution in wheat-based formulations concentrates demand in industrial-scale bread and pastry manufacturers seeking dual-certified organic and gluten-free inputs.
- Breakfast Cereals:Conventional milling-grade oats serve established brands with stable volume requirements but compressed pricing power.
- Snacks:Extruded and puffed oat applications in granola bars and savory crisps favor textural specifications over beta-glucan concentration.
Volume dominance sits with Bakery. Value capture is climbing fastest in Beverages.
End User:
Procurement scale and technical specification intensity separate customer tiers.
- Food Manufacturers:Industrial formulators of baked goods, beverages, and cereals drive consolidated demand with strict organic and gluten-free certification requirements. Direct contracting is replacing spot-market purchasing.
- Food Service:Café chains and quick-service operators in underpenetrated markets like Brazil represent partnership opportunities for suppliers with regional distribution infrastructure.
- Health Institutions:Clinical nutrition and hospital feeding programs seek EFSA-compliant beta-glucan levels for cholesterol-reduction positioning.
- Retail Consumers:Packaged oat ingredients for home baking constitute a fragmented, price-sensitive channel with minimal loyalty.
Contract security favors Food Manufacturers. Growth optionality favors Food Service.
Distribution Channel:
Channel selection determines traceability documentation requirements and working capital intensity.
- Direct Sales:Large-format beverage brands and cereal manufacturers source through supplier-specific agreements with sustainability scorecards as procurement gatekeepers.
- Supermarkets:Private-label oat milk and flour SKUs require dual-certified supply streams with carbon-accounting documentation under EU Green Deal compliance.
- Health Food Stores:Specialty retailers concentrate organic and gluten-free certified products with premium positioning and smaller lot sizes.
- Online Retail:E-commerce channels serve dispersed retail consumers with higher logistics costs and limited cold-chain capabilities for fresh oat milk.
Scale efficiency concentrates in Direct Sales. Margin premiums persist in Health Food Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oat ingredient processing originated in Nordic cooperative milling networks during the early twentieth century, then expanded through German industrial baking clusters and North American prairie grain handling infrastructure. Contemporary demand concentrates in beverage manufacturing hubs and functional food formulation centers.
Germany
Plant-based beverage manufacturers in Hamburg and Berlin are scaling oat milk production to serve retail discounters demanding origin-traceable supply streams. EU Green Deal carbon-accounting requirements are tightening procurement specifications for agricultural inputs entering German food systems. Bavarian milling clusters are absorbing compliance costs through facility consolidation and enzymatic fractionation upgrades.
United States
Specialty oat processors in Minnesota and North Dakota are expanding beta-glucan extraction capacity to serve sports nutrition and ready-to-drink meal replacement brands. FDA gluten-free labeling standards require dedicated facility segregation that favors larger operators with capital for dual-certified production streams. Pacific Northwest organic oat acreage is transitioning under three-year USDA certification timelines.
Sweden
Lantmännen's cooperative-owned milling assets across Skåne and Västra Götaland have concentrated Nordic supply for organic oat fractionation. EFSA beta-glucan health claim eligibility drives premium positioning in cholesterol-management applications. Stockholm-area food tech startups are testing precision fermentation integration with oat base substrates.
Canada
Richardson International and Prairie oat handlers are navigating weather-driven yield volatility in Manitoba and Saskatchewan production zones. Health Canada regulations on plant-based dairy alternatives are shaping beverage formulation standards. Calgary and Winnipeg grain terminals are developing specialty oat grading protocols for export markets.
Brazil
São Paulo quick-service chains and café operators present underpenetrated demand for oat milk compared to North American benchmarks. ANVISA food safety frameworks are evolving to accommodate novel plant-based ingredient categories. Southern Brazilian dairy distributors represent partnership pathways for suppliers establishing regional distribution infrastructure.
Oat Ingredients Market Competitive Landscape
The competitive structure tilts toward integrated grain handlers with captive milling assets and cooperative-owned processing networks with regional supply concentration. Tiered capability gaps separate enzymatic fractionation specialists from conventional flour millers. Three archetypes dominate: multinational agribusiness conglomerates with traceability infrastructure, Nordic cooperative processors with organic certification density, and North American specialty millers with gluten-free segregation capacity. Dominant competitive moves include backward integration into certified organic acreage contracting and technology licensing for beta-glucan stabilization protocols.
Among integrated agribusiness operators, Cargill, Incorporated and General Mills Inc. occupy positions anchored by grain handling infrastructure spanning multiple continents. Lantmännen exemplifies the cooperative archetype with Nordic supply zone concentration. Grain Millers, Inc. and Richardson International Limited represent North American specialty milling capabilities. Avena Foods Ltd and Blue Lake Milling sit within regional processing tiers focused on organic and gluten-free certification streams. Nestlé SA and PepsiCo, Inc. anchor end-user integration strategies through captive beverage brand portfolios.
| Leading Market Players |
|---|
| Avena Foods Ltd |
| Cargill, Incorporated |
| Lantmännen |
| Blue Lake Milling |
| General Mills Inc. |
| Grain Millers, Inc. |
| PepsiCo, Inc. |
| Nestlé SA |
| Richardson International Limited |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between dual-certified organic-gluten-free oat streams and commodity milling grades manifests in divergent margin structures and sourcing configurations. Premium-tier suppliers command pricing power through EFSA-compliant beta-glucan documentation and EU Green Deal carbon-accounting systems, while conventional processors absorb cost compression from weather-driven raw oat volatility in Canadian prairie provinces.
Pricing Analysis
Enzymatic fractionation services versus commodity flour milling define the core pricing split. Three-tier pricing structure across premium, standard, and economy levels tracks certification density, with dual-certified organic-gluten-free streams capturing maximum value from beverage manufacturers and clinical nutrition formulators. Cost compression in standard milling grades is intensifying because pea protein substitution threatens oat milk positioning in nutrition-positioned SKUs. Food manufacturers with direct contracting arrangements exhibit lowest price sensitivity; retail consumers in fragmented home-baking channels show highest elasticity.
Supply Chain Analysis
EU Green Deal local-content traceability mandates are reshaping sourcing toward German, Swedish, and Dutch processing clusters with verified carbon-accounting infrastructure. Raw oat dependencies draw from Canadian prairie provinces, Ukrainian black-soil regions, and Nordic cooperative acreage. Single-source vulnerability concentrates in enzymatic fractionation capacity for beta-glucan extraction. Distribution runs through direct supplier agreements with large-format beverage brands and retail discounters demanding batch-level sustainability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in oat ingredients rests on enzymatic processing adoption that compresses per-unit extraction costs while enabling premium positioning in functional food applications.
For Market Incumbents: Cement defensible positioning through backward integration into certified organic acreage contracting across Nordic and North American supply zones. Accelerate beta-glucan stabilization protocol licensing to lock in beverage manufacturer relationships before precision fermentation hybrids mature. Threat vector: biotech startups integrating precision fermentation with oat substrates. For New Entrants and Emerging Players: Launch via partnership pathways with southern Brazilian dairy distributors serving São Paulo quick-service chains and café operators where oat milk penetration lags North American benchmarks. Target underpenetrated foodservice channels with regional distribution infrastructure rather than competing for saturated German retail discounter slots. White-space opportunity: ANVISA-compliant ingredient categories in Brazilian clinical nutrition. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-size processors lack capital for dual-certified facility segregation and carbon-accounting ERP retrofits. Long-term viability favors integrated grain handlers with captive milling assets or enzymatic fractionation specialists with patented stabilization protocols. Acquisition target archetype: Nordic cooperative processors with organic certification density and stranded fractionation capacity. Signal to watch: EFSA beta-glucan health claim expansion beyond cholesterol reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Acreage | Cargill and Lantmännen secure origin-traceable supply streams under EU Green Deal compliance. |
| Enzymatic Fractionation Capacity Expansion | Specialty millers capture premium positioning in beta-glucan extraction for beverage applications. |
| Precision Fermentation Technology Licensing | Hybrid dairy alternatives with superior functional properties reshape ingredient category boundaries. |
| Direct Contracting with Sustainability Scorecards | German retail discounters mandate batch-level documentation as procurement gatekeepers. |
| Regional Distribution Infrastructure in Brazil | Suppliers establish partnership pathways with ANVISA-compliant foodservice channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with oat ingredient procurement managers at beverage manufacturers, bakery sector formulators, and cooperative milling executives alongside secondary validation. Secondary sources included EFSA guidance documents, USDA organic certification databases, EU REACH chemical compliance filings, and trade flow data from Nordic grain handling associations. Bottom-up volume modeling triangulated against top-down market sizing across enzymatic processing capacity and beta-glucan extraction yield estimates.
Comparable-period anchoring linked historical milling throughput and oat milk production volumes to forward projections across the analysis window. Segmentation dimensions spanned product type complexity, application channel certification requirements, end-user procurement scale, and regional regulatory cluster density. CAGRs derived from trend extrapolation of plant-based beverage procurement acceleration and bakery sector functional fiber substitution rates, with scenario weighting for pea protein substitution threat and precision fermentation convergence timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under weather-driven yield disruption in Canadian prairie provinces or EFSA health claim expansion beyond current cholesterol-reduction indications. Forecasts reflect documented assumptions on enzymatic processing adoption curves and EU Green Deal carbon-accounting implementation pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Aroma Ingredients Market
Ingredients
Europe Alcohol Ingredients Market
Ingredients
Pea Peptones Market
Ingredients
Egg Free Premix Market
Ingredients
Global Malt and Malt Extracts Market
Ingredients
North America Dairy Protein Market
Ingredients
Feed Premix Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
Global Amaranth Oil Market
Ingredients
Cholesterol API Market
Ingredients
Hops Derivative Market
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
Carotenes Market
Ingredients
Lime Seed Oils Market
Ingredients
South America Fermented Ingredients Market
Ingredients
Boysenberry Extract Market