
 Pomace Olive Oil Market | 2026-2036
Pomace Olive Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Pomace Olive Oil Market Insights
Blending-as-a-service is repositioning how pomace oil reaches food manufacturers, with processors now offering customized fatty acid profiles and stability packages rather than commodity grades. Sovena leverages backward integration into Spanish olive milling to secure consistent pomace supply across seasons. Deoleo anchors its competitive stance through brand strength in Mediterranean retail channels, while Borges International Group dominates industrial volume through direct sales to European food service providers.
Pomace olive oil is the refined edible oil extracted from olive pulp residue using food-grade solvents, typically containing 5-10% virgin olive oil when sold as blended product; its high smoke point and neutral flavor suit commercial frying, while cosmetic-grade fractions supply saponification feedstock. Refined pomace oil leads volume due to its cost advantage over extra virgin grades in heat-intensive food manufacturing, yet organic pomace oil captures expanding margin pools as personal care producers seek certified feedstock. The pharmaceutical raw material segment sustains premium pricing through strict acid value and peroxide specifications demanded by excipient makers.
EU REACH and F-Gas Regulation govern solvent recovery systems in European extraction facilities, while EFSA purity standards define acceptable fatty acid ester profiles for food-contact applications. India's FSSAI mandates quantitative virgin oil disclosure on blended labels, reshaping how exporters formulate pomace-virgin mixtures for that market. Stakeholders must monitor evolving biofuel qualification criteria in EU member states, where renewable energy firms test pomace oil as hydrotreated feedstock.
Market Dynamics
Refined pomace oil procurement is consolidating around solvent extraction clusters in Spain and Italy, where olive mill density enables cost-competitive bulk supply to food manufacturers facing tightened virgin oil labeling mandates.
Growth Catalysts
- India's FSSAI labeling mandate:Quantitative disclosure requirements on blended edible oils are redirecting formulation strategies toward certified pomace-virgin mixtures, expanding addressable volume for exporters.
- Cosmetic saponification demand:Personal care manufacturers are certifying organic pomace fractions for soap base feedstock, creating margin expansion beyond commodity food grades.
- Andalusian extraction infrastructure:Dense olive milling in southern Spain supports year-round solvent recovery operations with lower unit costs than dispersed Mediterranean competitors.
Market Restraints
- Hexane price volatility:Food-grade solvent costs fluctuate with petrochemical feedstock markets, compressing extraction margins during upstream price spikes.
- EU F-Gas Regulation compliance:Refrigerant-based solvent recovery systems face phase-down timelines, forcing capital reinvestment in European refining facilities.
- Extra virgin substitution threat:Price-sensitive food service buyers in Mediterranean retail channels trade down to lampante or refined virgin grades when pomace-virgin spreads narrow.
Strategic Opportunities
- Hydrotreated renewable diesel feedstock:EU member states are testing pomace oil qualification under biofuel mandates, opening energy-sector offtake agreements for refining byproducts.
- Blending-as-a-service models:Customized fatty acid profile formulation and stability packaging are displacing commodity grade procurement among industrial bakery and snack manufacturers.
- Organic certification arbitrage:Certified organic pomace oil commands premium positioning in North American natural cosmetics channels where conventional grades face commoditization.
Industry Challenges
- Peroxide value stabilization:Maintaining acid value and oxidation specifications for pharmaceutical excipient contracts requires accelerated testing protocols and inventory turnover discipline.
- Cross-border formulation complexity:Divergent purity standards between EFSA food-contact requirements and national cosmetic regulations in target export markets multiply compliance documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pomace Olive Oil Market |
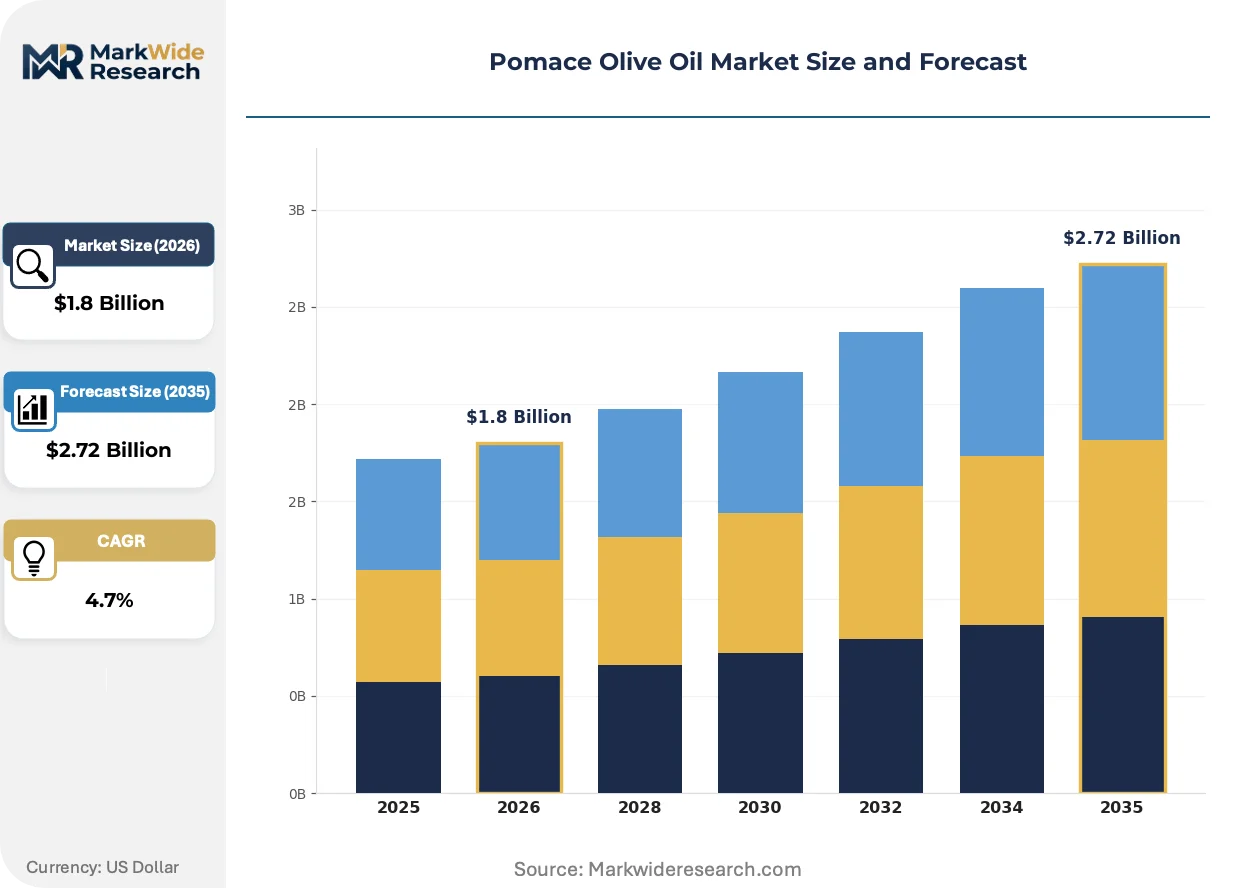
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Pomace Oil, Crude Pomace Oil, Blended Olive Oil, Organic Pomace Oil Application: Cooking Oil, Cosmetic Ingredient, Pharmaceutical Raw Material, Industrial Lubricant, Biofuel Distribution Channel: Supermarkets, E-Commerce, Specialty Stores, Direct Sales, Food Service Providers End User: Food Manufacturers, Personal Care Producers, Pharmaceutical Companies, Renewable Energy Firms |
| Companies Covered | Acesur, Sovena, Deoleo, Borges International Group, Ybarra Group, Modi Naturals, Basso Fedele & Figli, San Miguel Arcangel, Colavita, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pomace Olive Oil Market Trends and Innovations
Extraction technology and procurement logistics are converging to reshape how pomace oil reaches end-use markets, with solvent recovery efficiency and formulation customization emerging as primary competitive differentiators.
Supercritical CO2 extraction systems are modularizing downstream processing capabilities for mid-scale olive mill cooperatives. Spanish and Italian equipment suppliers are deploying skid-mounted units that bypass centralized refining infrastructure. This technology is modularizing supply chain geography, enabling pomace capture from seasonally dispersed milling operations without bulk transport to coastal refineries.
EU REACH registration requirements for solvent recovery byproducts are tightening documentation burdens on extraction facilities. Industrial consequence includes mandatory substance volume tracking and extended safety data sheet obligations for hexane-recovered fractions. Mediterranean bulk refiners are responding by consolidating registration compliance through trade association frameworks rather than individual facility filings.
Food manufacturers are unbundling virgin oil blending from commodity procurement contracts. Industrial bakery and frying operations now specify fatty acid profiles and smoke point minimums rather than purchasing standard pomace-virgin ratios. This specification-driven purchasing is most visible in India's processed food sector, where FSSAI disclosure rules have made blend transparency a procurement priority.
Pomace Olive Oil Market Segmentation
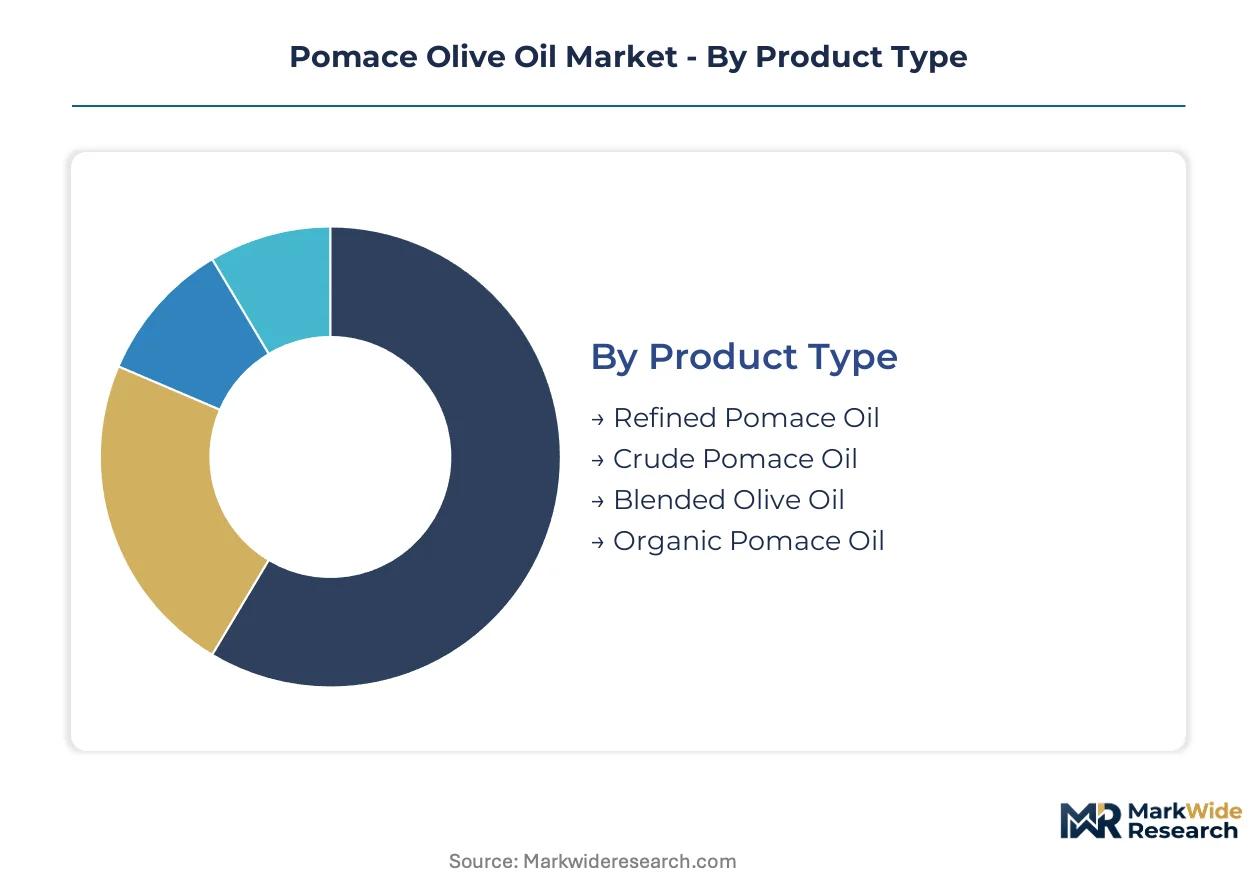
Pomace olive oil procurement decisions hinge on smoke point requirements, certification thresholds, and end-use regulatory exposure. Buyers segment supply by refining depth, application purity standards, and channel traceability obligations.
Product Type:
Cost tier determines procurement scale, with heat-intensive food manufacturing favoring lower-unit-cost refined grades while cosmetic and pharmaceutical buyers absorb organic premiums for certification compliance.
- Refined Pomace Oil:Solvent-extracted and deodorized to neutral flavor with smoke points exceeding 240°C. Food manufacturers across India and Spain concentrate procurement here for frying and baking applications where FSSAI and EFSA labeling mandates apply.
- Blended Olive Oil:Contains 5-10% virgin olive oil mixed with refined pomace base, offering modest sensory improvement at intermediate pricing. Mediterranean retail channels and Indian food service providers drive demand as virgin oil spreads fluctuate.
- Crude Pomace Oil:Unrefined extraction output with elevated free fatty acid content requiring downstream processing.
- Organic Pomace Oil:Certified feedstock commanding premium positioning in North American natural cosmetics and EU pharmaceutical excipient channels.
Volume sits with Refined Pomace Oil; growth tilts toward Organic Pomace Oil.
Application:
Application segmentation tracks thermal stress tolerance and regulatory stringency, with food-contact approvals separating commodity grades from pharmaceutical and cosmetic certifications.
- Cooking Oil:Commercial frying and industrial baking operations specify smoke point minimums and fatty acid profiles rather than standard pomace-virgin ratios. Indian processed food sector procurement prioritizes blend transparency under FSSAI disclosure rules.
- Cosmetic Ingredient:Saponification feedstock for soap base manufacturing demands organic certification and controlled peroxide values. Personal care producers in Mediterranean clusters certify pomace fractions to access North American natural product channels.
- Pharmaceutical Raw Material:Excipient-grade supply requires strict acid value and oxidation specifications with accelerated testing protocols.
- Industrial Lubricant:Niche metalworking fluid applications leveraging pomace oil's polar lipid content.
- Biofuel:Hydrotreated renewable diesel feedstock testing under EU member state biofuel qualification criteria.
Revenue concentrates in Cooking Oil; margin expansion is steepest in Pharmaceutical Raw Material.
Distribution Channel:
Channel selection reflects buyer scale and formulation complexity, with industrial volume migrating toward direct procurement while smaller food service operators rely on intermediaries.
- Direct Sales:Bulk supply agreements between Spanish extraction clusters and European food manufacturers enable customized fatty acid profile formulation. Blending-as-a-service models displace commodity grade procurement through specification-driven contracting.
- Food Service Providers:Institutional buyers in Mediterranean markets source standardized pomace-virgin blends for frying operations with price-sensitive substitution to lampante grades when spreads narrow.
- Supermarkets:Retail shelf presence for consumer-facing blended olive oil products.
- E-Commerce:Direct-to-consumer organic pomace oil for small-batch cosmetic producers.
- Specialty Stores:Premium positioning for certified organic grades in natural product channels.
Procurement scale favors Direct Sales; channel diversification is expanding fastest through Food Service Providers.
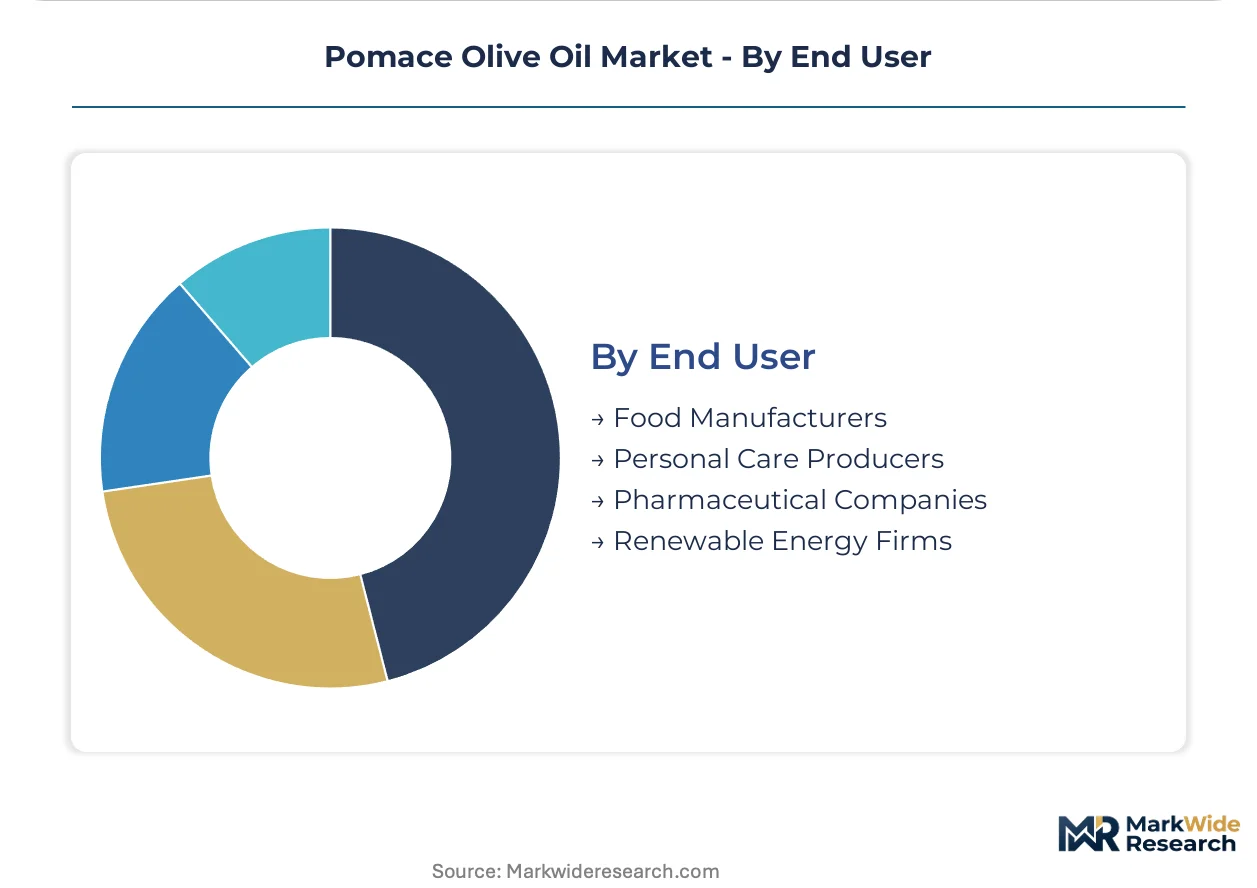
End User:
End user segmentation aligns with regulatory jurisdiction complexity, as food-contact, cosmetic, and pharmaceutical purity standards diverge across EFSA, national cosmetic regulations, and pharmacopeial requirements.
- Food Manufacturers:Industrial bakery and snack operations in India and Spain drive refined pomace oil volume with specification-driven purchasing replacing commodity contracts. FSSAI quantitative disclosure mandates reshape formulation strategies for exporters.
- Personal Care Producers:Soap base and cosmetic manufacturers certify organic pomace fractions to satisfy North American natural product channel requirements, capturing margin pools beyond commodity food grades.
- Pharmaceutical Companies:Excipient makers enforce strict peroxide value and acid value specifications with inventory turnover discipline.
- Renewable Energy Firms:EU-based hydrotreated renewable diesel producers testing pomace oil qualification under evolving biofuel mandates.
Demand scale rests with Food Manufacturers; certified supply premiums are climbing fastest among Personal Care Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain and Italy generate surplus pomace oil through dense olive milling clusters, while India and the United States absorb refined volumes under divergent regulatory frameworks. This production-consumption asymmetry shapes trade flows and extraction infrastructure investment.
Spain
Andalusian olive mill density enables year-round solvent extraction operations with lower unit costs than Mediterranean competitors. EFSA food-contact standards and EU F-Gas Regulation compliance requirements govern refining facility operations. Seville and Córdoba extraction clusters supply bulk refined pomace oil to European food manufacturers and Indian exporters.
Italy
Apulian and Calabrian milling cooperatives feed centralized refining infrastructure serving cosmetic and pharmaceutical channels. REACH registration requirements for solvent recovery byproducts tighten documentation burdens on extraction facilities. Bari-based refiners consolidate compliance through trade association frameworks rather than individual facility filings.
India
Processed food manufacturers in Maharashtra and Gujarat scale procurement of refined pomace oil for frying and baking applications. FSSAI mandates quantitative virgin oil disclosure on blended edible oil labels, redirecting formulation strategies toward certified pomace-virgin mixtures. Mumbai and Ahmedabad distribution hubs reshape how exporters structure blend transparency for this market.
United States
Personal care producers in California and New Jersey certify organic pomace fractions for soap base and natural cosmetics feedstock. FDA cosmetic ingredient regulations and state-level organic certification requirements create compliance layering. Los Angeles-area formulators source certified supply to access premium natural product channels.
Greece
Peloponnese olive mill clustering supports seasonal pomace capture for regional refining and export. National food safety authority alignment with EFSA standards enables cross-border formulation for EU pharmaceutical excipient contracts. Kalamata extraction cooperatives serve as secondary supply nodes when Spanish and Italian capacity tightens.
Pomace Olive Oil Market Competitive Landscape
Top-tier vendors anchor Mediterranean extraction and refining infrastructure, while mid-scale cooperatives and regional blenders occupy specialized certification niches. Market structure concentrates around solvent extraction clusters where olive mill density enables cost-competitive bulk supply. Two strategic archetypes dominate: backward-integrated mill-to-refinery operators and formulation specialists offering customized fatty acid profiles. Competitive moves center on blending-as-a-service capability expansion and organic certification arbitrage into North American cosmetics channels.
Among Spanish and Portuguese extraction specialists, Sovena and Acesur represent the integrated mill-to-refinery archetype with captive pomace supply across seasons. Deoleo occupies a position exemplifying brand-anchored retail channel dominance in Mediterranean markets. These three entities illustrate how geographic clustering, regulatory compliance depth, and channel specialization stratify competitive positioning.
| Leading Market Players |
|---|
| Acesur |
| Sovena |
| Deoleo |
| Borges International Group |
| Ybarra Group |
| Modi Naturals |
| Basso Fedele & Figli |
| San Miguel Arcangel |
| Colavita |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between organic pharmaceutical feedstock and commodity refined pomace oil manifests in parallel supply chain configurations, with EFSA-compliant extraction clusters in Spain and Italy commanding premium positioning while Indian bulk buyers optimize around FSSAI disclosure-compliant blending economics.
Pricing Analysis
Cost-down pressure on refined pomace oil accelerates because hexane solvent costs track volatile petrochemical feedstock markets, compressing extraction margins during upstream price spikes. Three-tier pricing structure across organic certified, food-grade refined, and crude unprocessed levels separates pharmaceutical excipient premiums from commodity frying oil contracts. Price differentiation hinges on acid value specifications and peroxide stability thresholds, with personal care producers absorbing organic certification premiums while Indian food manufacturers prioritize blend transparency over grade escalation. Food service providers in Mediterranean retail channels exhibit highest price sensitivity, trading down to lampante grades when pomace-virgin spreads narrow.
Supply Chain Analysis
Dual-sourcing requirements from Indian food manufacturers and EU pharmaceutical excipient makers mandate multi-supplier qualification across Spanish Andalusian clusters and Italian Apulian cooperatives. Raw material dependencies center on olive pulp residue feedstock, food-grade hexane solvent, and virgin olive oil blending components. Supply chain risk concentrates in single-source vulnerability to seasonal olive harvest concentration, with extraction capacity tightening during off-peak milling periods. Distribution runs through direct bulk supply agreements between Mediterranean refiners and industrial food manufacturers, supplemented by food service provider intermediaries for smaller-scale procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction technology is displacing legacy hexane-based solvent recovery systems, modularizing downstream processing capabilities for mid-scale olive mill cooperatives and reshaping competitive economics across extraction infrastructure investment decisions.
For Market Incumbents: Acquire organic certification capacity and captive pomace supply agreements to defend against supercritical CO2 entrants and biofuel offtake competition. Backward integration into Andalusian olive milling secures year-round feedstock access. Accelerated peroxide value testing protocols and inventory turnover discipline protect pharmaceutical excipient contract renewals against oxidation specification failures. For New Entrants and Emerging Players: Enter via certified organic pomace oil supply to North American natural cosmetics channels, where premium positioning escapes commodity food-grade pricing compression. White-space targets include hydrotreated renewable diesel feedstock qualification under evolving EU member state biofuel mandates and blending-as-a-service formulation for Indian processed food manufacturers navigating FSSAI disclosure requirements. Direct sales to personal care producers in California and New Jersey offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale extraction cooperatives deploying modular supercritical CO2 units given technology transition catalysts and REACH registration consolidation trends. Long-term viability over the next decade favors operators with dual food-contact and pharmaceutical certification depth rather than commodity refining scale alone. Acquisition target archetype: Apulian or Andalusian cooperatives with organic certification infrastructure and solvent recovery compliance frameworks. The signal to watch is EU F-Gas Regulation phase-down timelines forcing capital reinvestment in refrigerant-based recovery systems.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Deployment | Modular processing bypasses centralized refining infrastructure for seasonally dispersed milling operations. |
| Organic Certification Investment | EFSA and FDA cosmetic ingredient compliance unlocks premium North American personal care channel access. |
| Blending-as-a-Service Capability | Customized fatty acid profiles displace commodity procurement among Indian food manufacturers under FSSAI rules. |
| Biofuel Feedstock Qualification | Hydrotreated renewable diesel testing under EU mandates opens energy-sector offtake for refining byproducts. |
| REACH Registration Consolidation | Trade association frameworks reduce documentation burdens on Italian extraction facilities versus individual filings. |
Research Methodology
Document review covered EFSA food-contact standards documentation, FSSAI labeling mandate circulars, EU REACH registration filings, and olive oil trade flow databases, complemented by interviews with extraction facility operations managers, pharmaceutical excipient procurement leads, Indian food manufacturer R&D directors, and personal care formulator supply chain heads. Secondary validation drew from customs and trade data, SEC filings of listed edible oil processors, and industry association production statistics. Bottom-up volume modeling across product type and application segments triangulated against top-down market sizing from regional production cluster analysis.
Cross-referencing historical price spread data between pomace and virgin olive oil grades against panel input from procurement executives anchored volume and value projections across the analysis window. Segmentation dimensions modeled include refining depth, end-use regulatory exposure, distribution channel structure, and geographic certification requirements. CAGRs were derived from weighted average growth assumptions across cooking oil, cosmetic ingredient, and pharmaceutical raw material application clusters, with specific inputs from hexane price volatility indices and olive harvest yield forecasts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU F-Gas Regulation acceleration or Indian FSSAI enforcement intensity shifts. Projections reflect assumptions around solvent extraction cost structures, organic certification penetration rates, and biofuel mandate qualification timelines. Deviation in hexane petrochemical feedstock pricing or olive pulp residue supply seasonality would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Low Fat Oil Market
Ingredients
Pomegranate Peel Polyphenol Complex Market
Ingredients
Hexane-Free Protein Market
Ingredients
Middle East and Africa Dairy Ingredients Market
Ingredients
Waxy Maize Starch Market
Ingredients
Omega Ingredients Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Europe Corn Glucose Market
Ingredients
South America Fruit and Vegetable Ingredients Market
Ingredients
South America Phytosterols Market
Ingredients
Yeast and Yeast Extract Market
Ingredients
Asia-Pacific Yeast and Yeast Extract Market
Ingredients
Fermentation Ingredient Market
Ingredients
Cocoa Maker Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Egg White Powder Market