
 Cocoa Beans Market | 2026-2036
Cocoa Beans Market Size, Share, and Industry Trends Forecast 2026-2036
Cocoa Beans Market Analysis
Whole-bean cocoa butter is consolidating its position as the preferred lipid base in premium confectionery, displacing palm oil and shea fractions across European and North American formulations. Barry Callebaut AG leverages its integrated bean-to-bar infrastructure across multiple continents. Cargill, Incorporated anchors its procurement through direct farmer partnerships in West Africa. Olam International Limited differentiates via traceability platforms that map individual cooperative output.
Cocoa beans are the dried and fermented seeds of Theobroma cacao, typically containing 50-57% cocoa butter by dry weight, 12-18% protein, and 5-7% theobromine; processors roast, winnow, and grind them to produce chocolate liquor, the foundational intermediate for all chocolate products. The form dimension splits across cocoa butter, cocoa powder, chocolate liquor, and whole beans, with cocoa butter commanding the strongest margin pool due to its irreplaceable melting profile in confectionery applications. Fine flavor grades within the quality grade category attract the fastest-growing buyer interest from craft chocolatiers, while bulk cocoa still dominates total volume throughput.
The EU Deforestation Regulation and FDA food safety standards collectively reshape traceability mandates and pesticide residue thresholds for cocoa entering major consumer markets. EUDR due diligence requirements force exporters to geolocate every production plot, raising compliance costs for smallholder-dependent supply chains. Stakeholders must decide whether to absorb traceability investments or pass them downstream before the full enforcement framework activates.
Market Dynamics
The EU Deforestation Regulation mandates geolocation traceability for every cocoa plot entering European supply chains, forcing exporters to rebuild compliance infrastructure around farm-level digital mapping and due diligence documentation.
Growth Catalysts
- Bean-to-bar craft movement:Small-batch chocolatiers in North America and Western Europe source directly from origin cooperatives, bypassing commodity exchanges and capturing margin through origin storytelling.
- EUDR compliance deadlines:European importers accelerate supplier audits and satellite verification systems to meet traceability requirements before full enforcement activates.
- Fine flavor differentiation:Criollo and Trinitario varietals command price premiums as craft manufacturers emphasize terroir and fermentation protocols in marketing.
Market Restraints
- West African supply concentration:Côte d'Ivoire and Ghana together account for the majority of global bean output, exposing buyers to synchronized weather shocks and political instability.
- Fungal disease pressure:Black pod rot and witches' broom disease destroy harvests across Latin American and West African growing regions, with limited resistant cultivars available.
- Input cost volatility:Fertilizer prices fluctuate with natural gas markets, squeezing smallholder margins and reducing application rates below optimal agronomic thresholds.
Strategic Opportunities
- Latin American origin expansion:Ecuador, Peru, and Colombia develop fine flavor infrastructure to capture premium segments as West African compliance costs rise.
- Carbon credit monetization:Agroforestry cocoa systems qualify for voluntary carbon markets, creating supplementary revenue streams for certified farmers.
- Blockchain traceability platforms:Distributed ledger technology converges with mobile payment systems to deliver real-time provenance verification and instant farmer compensation.
Industry Challenges
- Digital literacy gaps:Smallholder cooperatives lack technical capacity to operate geolocation tools and submit EUDR-compliant documentation without external support.
- Certification timeline compression:Organic and Fairtrade audit backlogs delay market access for farmers seeking premium channel eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocoa Beans Market |
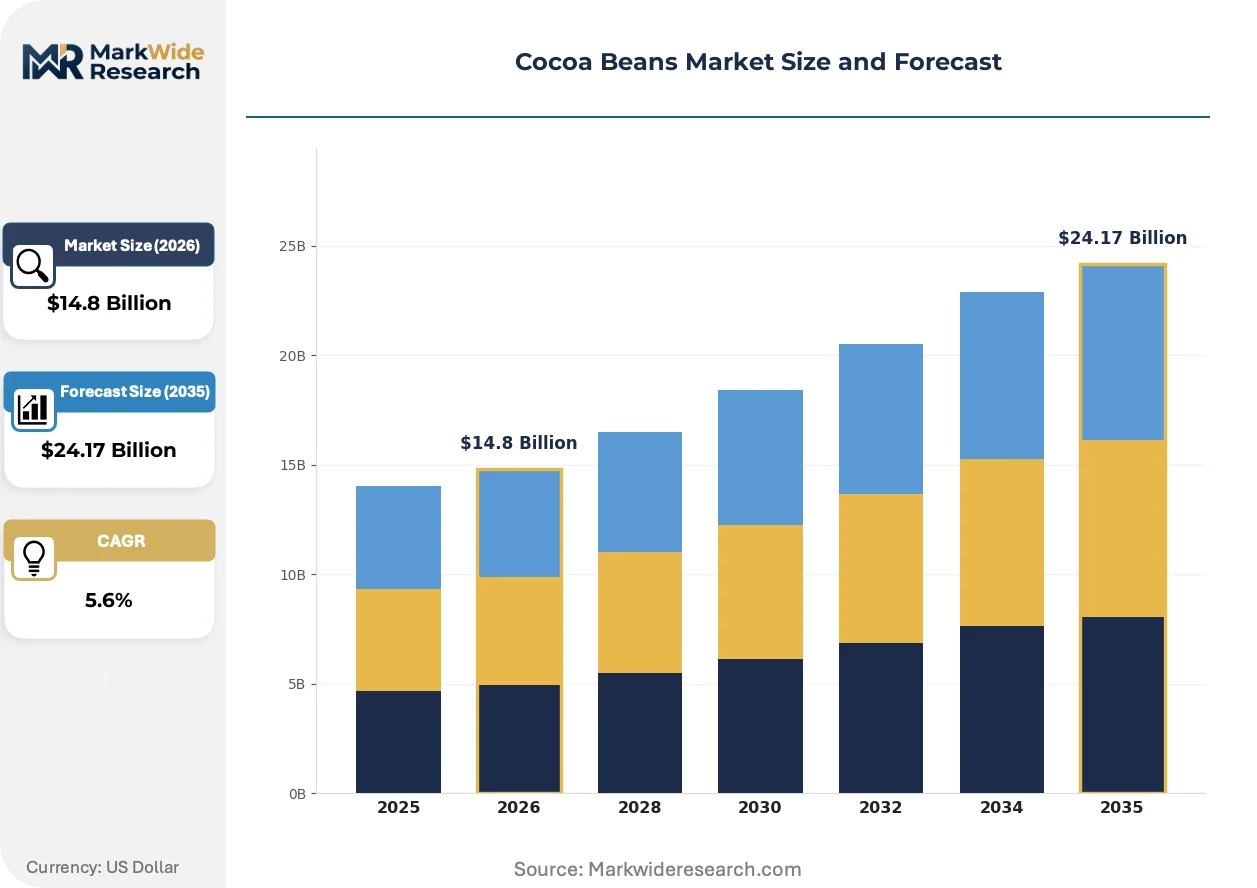
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryogenic, Fermented, Non-Fermented, Roasted Form: Cocoa Butter, Cocoa Powder, Chocolate Liquor, Whole Beans End Use: Beverages, Confectionery, Bakery, Cosmetics Quality Grade: Fine Flavor, Bulk Cocoa, Organic, Conventional |
| Companies Covered | Archer Daniels Midland Company, Touton S.A., Barry Callebaut AG, Guan Chong Berhad, Fuji Oil Holdings Inc., Cargill, Incorporated, ECOM Agroindustrial Corp Ltd, Cemoi SAS, Olam International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocoa Beans Market Emerging Trajectories
Processing technology and regulatory architecture are rewriting competitive rules across the cocoa value chain. Innovations concentrate in fermentation control, traceability infrastructure, and lipid extraction methods that reshape product economics.
Precision fermentation chambers equipped with sensor arrays and automated turning mechanisms are integrating into mid-sized processing facilities from Ecuador to Vietnam. Craft manufacturers in Belgium and Switzerland adopt these systems to standardize flavor profiles across harvest seasons. The technology is integrating quality control previously concentrated in industrial-scale operations, compressing the capability gap between artisan and commodity processors.
REACH chemical registration requirements in Europe tighten pesticide residue thresholds for cocoa butter imports, forcing exporters to substitute synthetic fungicides with biological controls. Processing facilities in Ghana and Nigeria reconfigure washing and drying protocols to meet descending maximum residue limits. Bulk cocoa shipments face extended port inspections, redirecting investment toward pre-export laboratory certification.
Direct trade purchasing contracts now replace spot market transactions for premium segments, with roasters locking multi-year volumes against fixed quality specifications. Specialty buyers in California and Tokyo bypass commodity exchanges entirely, establishing vertical relationships with specific cooperatives. This restructuring concentrates price risk with processors while transferring origin accountability upstream.
Cocoa Beans Market Segmentation
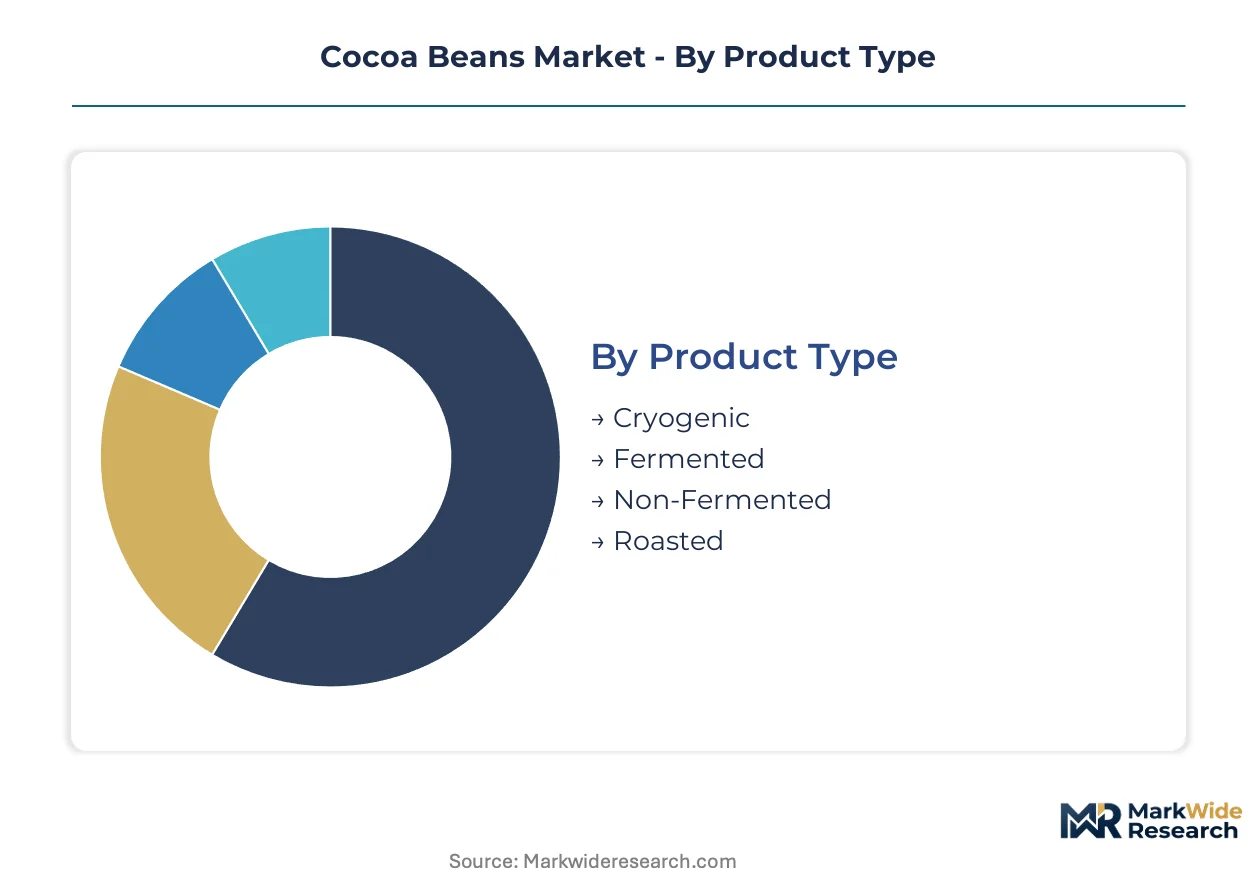
Cocoa bean segmentation separates commodity bulk flows from premium specialty channels, determining margin capture and compliance burden across the value chain. Product form and quality grade dictate processing investment requirements, while end-use application shapes origin sourcing patterns and certification priorities.
Product Type:
Fermented beans dominate export volume, yet cryogenic preservation is gaining traction among fine flavor specialists seeking extended shelf stability.
- Fermented:Standard processing involves heap or box fermentation lasting five to seven days, developing precursor compounds for chocolate flavor. Demand concentrates in Côte d'Ivoire and Ghana, where cooperative infrastructure supports mass-market supply to European processors facing EUDR traceability mandates.
- Cryogenic:Rapid freezing at harvest locks volatile aromatic compounds, preserving varietal character for premium craft applications. Specialty buyers in Switzerland and Japan source these beans for single-origin bars, absorbing higher logistics costs to secure fermentation-independent flavor consistency.
- Non-Fermented:Raw seeds dried without microbial transformation, retaining astringent polyphenol profiles suited for specific nutraceutical extraction processes.
- Roasted:Pre-roasted beans reduce processing steps for small confectioners lacking in-house roasting capacity, common in emerging market bakery supply chains.
Today's leader: Fermented. Tomorrow's challenger: Cryogenic.
Form:
Downstream processing economics favor butter extraction for margin, while whole bean trade persists where origin traceability commands premium pricing.
- Cocoa Butter:Extracted via hydraulic pressing or solvent methods, this lipid fraction provides the essential melting curve for confectionery tempering. North American premium chocolate manufacturers specify deodorized variants, displacing palm oil blends in clean-label formulations.
- Chocolate Liquor:Ground nib mass containing roughly equal butter and cocoa solids serves as the universal intermediate for all chocolate production. Industrial processors in Belgium and Germany standardize liquor specifications to reduce batch variability across seasonal harvests.
- Cocoa Powder:Press cake milling yields alkalized or natural powders for beverage and bakery applications, with fat content tiers determining price positioning.
- Whole Beans:Unprocessed seeds trade in specialty channels where bean-to-bar narratives support direct farmer relationships and cooperative branding.
Butter commands the steepest expansion trajectory as clean-label confectionery reformulates away from alternative fats.
End Use:
Confectionery absorbs the majority of bean throughput, though cosmetics-grade butter specifications are tightening purity thresholds.
- Confectionery:Chocolate bars, pralines, and couverture demand precise butter crystallization behavior, driving specification rigor from processors in France and Italy. Craft segment growth in California and Tokyo reshapes procurement toward direct trade contracts with named cooperatives.
- Beverages:Drinking chocolate and malted formulations utilize lower-fat powder grades, with instant beverage manufacturers in Brazil and Mexico sourcing bulk cocoa for cost-sensitive retail positioning.
- Bakery:Inclusion chocolate and cocoa dusting applications tolerate broader particle size distributions than confectionery, opening secondary processing outlets for off-spec liquor.
- Cosmetics:Pharmaceutical-grade butter requirements for dermal applications impose heavy metal and microbial limits beyond food standards, filtering supply toward certified processing facilities in Ecuador and Colombia.
Confectionery retains volume dominance. Cosmetics offers the sharpest margin expansion potential.
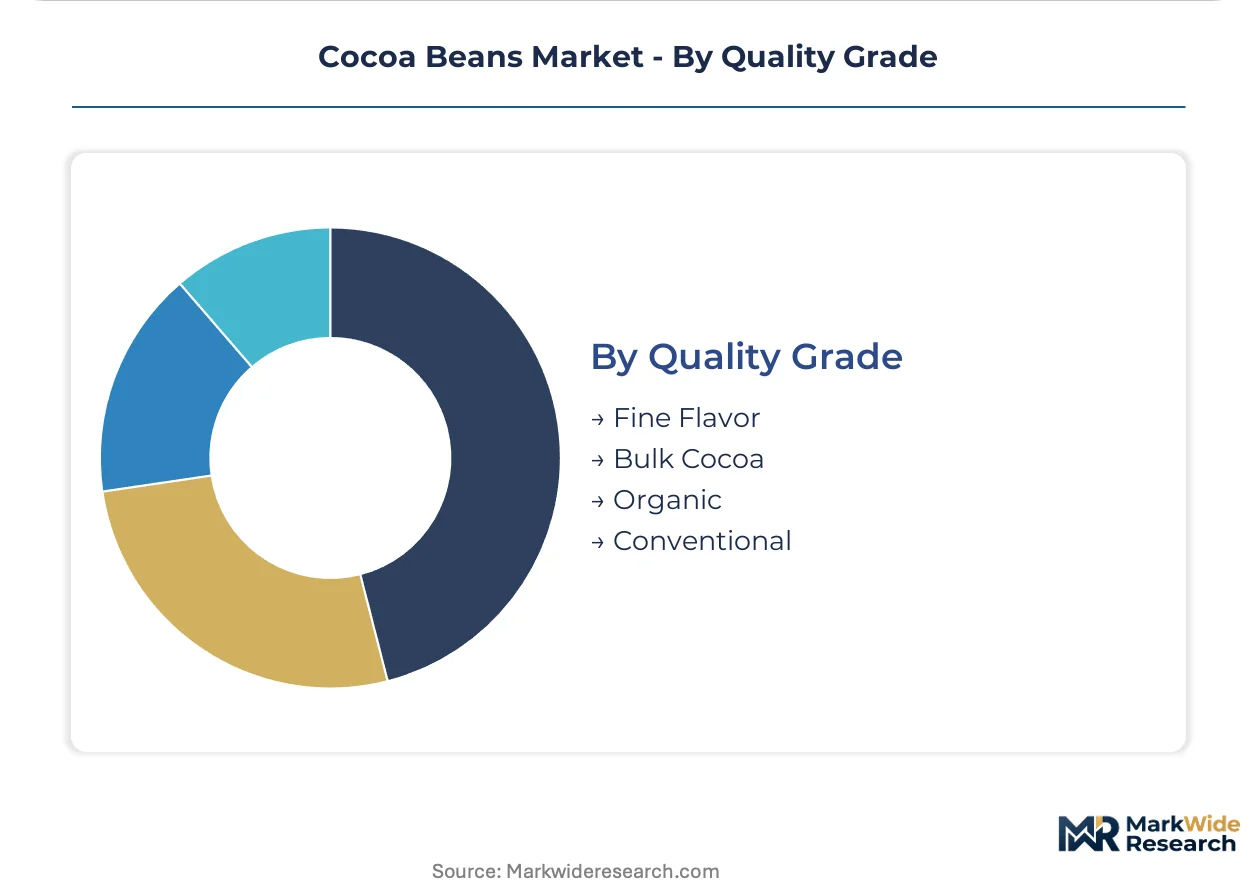
Quality Grade:
Bulk cocoa moves through commodity exchanges, while fine flavor grades bypass futures markets entirely for direct negotiated contracts.
- Fine Flavor:Criollo, Trinitario, and selected Forastero clones meet ICCO thresholds for aromatic intensity, commanding price multiples over bulk grades. Craft manufacturers in Brooklyn and Copenhagen build brand identity around specific estate or cooperative provenances.
- Organic:Certification prohibits synthetic pesticide and fertilizer use, requiring three-year conversion periods that strain smallholder cash flow in Ghana and Nigeria. European retailers increasingly mandate organic SKUs for private-label chocolate lines.
- Bulk Cocoa:Standard Forastero varieties from West Africa supply mass-market chocolate with neutral flavor profiles optimized for consistency and cost.
- Conventional:Non-certified production remains the default for emerging market confectionery and industrial food service applications where price sensitivity dominates procurement criteria.
Fine Flavor owns premium positioning. Organic certification is gaining share fastest as EUDR compliance overlaps with chemical input restrictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
West African supply chains anchor the Cocoa Beans Market, with European processing clusters driving compliance investment and Asian demand nodes expanding origin sourcing networks.
Côte d'Ivoire
Abidjan and San-Pédro port complexes process roughly two-fifths of global bean exports, with cooperative consolidation accelerating under EUDR geolocation mandates. The Conseil du Café-Cacao enforces farm-level digital mapping requirements for all export registrations. Yamoussoukro-based grinders expand butter extraction capacity to capture downstream margin from European confectionery reformulation.
Ghana
Tema port infrastructure supports the Ghana Cocoa Board's quality-controlled auction system, maintaining price premiums over Ivorian bulk grades. COCOBOD's input credit programs distribute fertilizer and seedlings through district-level cooperatives. Kumasi processing zones attract Asian joint venture investment for liquor and powder production targeting ASEAN beverage manufacturers.
Germany
Hamburg and Bremen harbor facilities constitute Europe's largest cocoa bean import gateway, with ECHA REACH compliance laboratories clustered along the Elbe. German confectionery manufacturers in Cologne and Munich drive specification rigor for deodorized butter grades. The country's federal food safety authority enforces pesticide residue thresholds that redirect West African shipments toward pre-export certification.
United States
Pennsylvania and New Jersey processing corridors supply North American chocolate manufacturers with standardized liquor specifications. FDA food safety modernization rules impose foreign supplier verification programs on direct trade importers. Brooklyn and San Francisco craft chocolatiers establish vertical relationships with Ecuadorian and Peruvian cooperatives, bypassing commodity exchanges entirely.
Switzerland
Zurich and Geneva trading houses coordinate fine flavor procurement from Latin American origins, with Swissmedic-grade butter specifications filtering supply toward pharmaceutical applications. The country's chocolate manufacturers in Vevey and Kilchberg specify Criollo and Trinitario varietals for premium positioning. Swiss private banks finance warehouse receipt systems for West African cooperative collateralization.
Cocoa Beans Market Vendor Landscape
Global majors compete with regional champions across integrated processing and origin sourcing dimensions. The vendor base clusters around three tiers: bean-to-bar integrated processors with multi-continent infrastructure, mid-scale regional grinders serving confectionery clusters, and specialty traders focusing on fine flavor direct trade. Strategic moves concentrate on backward integration into West African cooperative networks and fermentation technology licensing to secure EUDR-compliant supply.
Within the integrated processing tier, Barry Callebaut AG exemplifies multi-continent bean-to-bar infrastructure, while Cargill, Incorporated anchors procurement through direct farmer partnerships. Olam International Limited occupies a position in traceability platform development, mapping cooperative output for premium segment verification. These three entities represent distinct archetypes: European integrated processing, American agricultural commodity systems, and Singapore-based supply chain digitization.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Touton S.A. |
| Barry Callebaut AG |
| Guan Chong Berhad |
| Fuji Oil Holdings Inc. |
| Cargill, Incorporated |
| ECOM Agroindustrial Corp Ltd |
| Cemoi SAS |
| Olam International Limited |
| Others |
Supply Flow & Price Mechanics
Premium chocolate manufacturers in Belgium and Switzerland concentrate procurement power through direct cooperative contracts, anchoring a pricing model that stratifies across fine flavor, certified organic, and bulk commodity tiers. EUDR compliance costs and fermentation technology investments feed back into origin sourcing decisions, compressing margins for undifferentiated suppliers while amplifying premiums for traceable supply.
Pricing Analysis
Input-cost pass-through from fertilizer and labor inputs in West African origins shapes contract negotiations between cooperatives and European grinders. Three-tier pricing structure across premium, standard, and economy levels separates fine flavor Criollo-Trinitario lots from certified organic grades and conventional Forastero bulk. Price differentiation hinges on geolocation traceability and fermentation protocol documentation. Pricing pressure stems from EUDR infrastructure investments being pushed upstream to smallholder cooperatives with limited balance sheet capacity. Industrial confectioners in Germany and France exhibit highest price sensitivity, while Swiss pharmaceutical-grade butter buyers absorb premiums for heavy metal and microbial certification.
Supply Chain Analysis
Workforce availability constraints in Ghana and Côte d'Ivoire cooperative sectors limit EUDR geolocation data collection speed, creating bottlenecks at export registration points. Supply concentration in these two West African origins, plus emerging Ecuadorian fine flavor infrastructure, draws from seasonal labor pools with limited digital literacy. Raw material dependencies span fermentation boxes, hybrid seedling stock, and biological fungicide substitutes for synthetic pesticide phase-out. Single-source vulnerability runs through Abidjan and San-Pédro port complexes handling two-fifths of global exports. Distribution runs through Hamburg and Bremen harbor clusters for European processing, with Asian demand increasingly served by Tema port expansion and direct Latin American shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cocoa beans rests on capturing premium-tier shifts toward fine flavor and certified organic segments, while digital traceability infrastructure creates defensible cost positions against EUDR compliance burdens.
For Market Incumbents: Extend fermentation technology licensing programs to Latin American cooperatives in Ecuador and Peru, securing EUDR-compliant supply alternatives before West African compliance backlogs harden. Deepen backward integration into Ghanaian and Ivorian cooperative networks through input credit and seedling distribution programs, defending against Asian grinder joint ventures capturing ASEAN beverage demand. Prioritize blockchain traceability platform deployment to maintain premium channel access as European retailers mandate geolocation documentation. For New Entrants and Emerging Players: EUDR in Europe opens a window for Latin American origin specialists to capture premium segments as West African compliance costs rise and audit timelines extend. Target cryogenic preservation and single-origin direct trade channels in Switzerland and Japan, where buyers absorb higher logistics costs for fermentation-independent flavor consistency. Pursue carbon credit monetization through agroforestry cocoa systems, accessing voluntary carbon markets as supplementary revenue streams for certified farmers. For Investors and Strategic Acquirers: Integrated confectionery manufacturers are the most active acquirer in this space, seeking captive supply of EUDR-compliant beans and butter extraction capacity. Long-term viability favors targets with established cooperative relationships and digital traceability infrastructure already deployed. Acquisition focus should center on mid-scale regional grinders with Latin American fine flavor access and Swissmedic-grade butter certification. Monitor EUDR enforcement activation timelines and West African geolocation completion rates as inflection indicators for supply availability and price volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperative Networks | Cargill and Barry Callebaut anchor procurement through direct farmer partnerships in Ghana and Côte d'Ivoire. |
| Fermentation Technology Licensing | Precision fermentation chambers with sensor arrays standardize flavor profiles for Belgian craft manufacturers. |
| Blockchain Traceability Platform Deployment | Olam International maps cooperative output for real-time provenance verification and instant farmer compensation. |
| Carbon Credit Monetization Program | Agroforestry cocoa systems in Ecuador and Colombia qualify for voluntary carbon market revenue streams. |
| Pharmaceutical-Grade Butter Certification | Swissmedic specifications filter supply toward certified processing facilities for dermal applications. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cooperative managers, European grinder procurement leads, confectionery R&D directors, and sustainability certification officers with secondary validation. Secondary sources included ICCO production statistics, EU TRACES import documentation, Ghana Cocoa Board auction records, and Swissmedic pharmaceutical-grade specifications. Bottom-up cooperative yield estimates triangulated against top-down country-level export data.
Comparable-period anchoring linked projection assumptions to historical harvest cycles and price formation patterns across the modeling period. Segmentation dimensions spanned product form, quality grade, end-use application, and origin country regulatory cluster. CAGRs derived from weighted average growth across these segments, incorporating EUDR implementation pace, fine flavor demand elasticity, and butter extraction capacity expansion as industry-specific inputs.
Revisions become necessary when EUDR enforcement timelines shift, West African political stability deteriorates, or fungal disease outbreaks exceed historical incidence rates. Forecasts reflect assumptions about cooperative digital literacy improvement and satellite verification system deployment. Practitioners should monitor EUDR geolocation completion rates, black pod rot incidence in Latin America, and Asian grinder joint venture announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Malt Ingredient Market
Ingredients
Europe Protein Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
Smoke Ingredients for Food Market
Ingredients
Codonopsis Extract Market
Ingredients
Omega 3 Ingredients Market
Ingredients
Wheat Germ Oil Market
Ingredients
South America Plant Protein Ingredients Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Mediterranean Barley Beta-Glucan Ingredients Market
Ingredients
Food Minerals Market
Ingredients
North America Plant Protein Ingredients Market
Ingredients
North America Wheat Protein Ingredients Market
Ingredients
Oat Grass Powder Market
Ingredients
Europe Dairy Protein Market
Ingredients
Flaxseed Derivatives Market