
 Pea Peptones Market | 2026-2036
Pea Peptones Market Size, Share, and Industry Trends Forecast 2026-2036
Pea Peptones Market Analytics
Multi-source procurement for plant-derived hydrolysates is pivoting as pharmaceutical and biotech buyers reduce reliance on animal-based peptones. Organotechnie leverages its European fermentation supply base to serve cell culture customers seeking serum-free media components. Thermo Fisher Scientific anchors North American distribution through its life sciences catalog and direct sales to research institutions. Kerry Group competes on food-grade applications, extending its pea protein expertise into peptone formulations for nutritional markets.
Pea peptones are enzymatically hydrolyzed protein fractions derived from Pisum sativum, typically containing 70-85% protein with balanced amino acid profiles optimized for microbial fermentation and mammalian cell culture. Hydrolyzed pea proteins dominate pharmaceutical applications where endotoxin control and batch consistency determine supplier qualification. Nutritional supplements represent the fastest-expanding application segment as dietary supplement companies reformulate with plant-derived nitrogen sources to meet clean-label expectations. Food manufacturers occupy mature demand pools, utilizing peptones for flavor precursors and fermentation substrates in savory product development.
EMA guidelines on TSE/BSE risk materials and REACH chemical registration requirements shape European supplier qualification protocols for peptone imports. FDA quality standards for cell culture media components influence U.S. buyer specifications, while ISO 9001 certification operates as a baseline threshold for contract manufacturing organization vendor approval. Stakeholders must monitor evolving pharmacopeial monographs for plant-derived peptones and assess backward integration into pea protein isolate supply as a margin defense strategy.
Market Dynamics
Pharmaceutical manufacturers are abandoning animal-derived peptones en masse as TSE/BSE risk protocols tighten and serum-free media formulations achieve parity performance. This substitution cascade is compressing qualification timelines for plant-based hydrolysate suppliers while fragmenting procurement across dual-source validation requirements.
Growth Catalysts
- EMA TSE/BSE guidelines:European pharmaceutical regulators now mandate documented risk assessments for animal-origin materials in cell culture media. Pea peptones bypass these compliance burdens entirely.
- Fermentation-grade hydrolysate demand:Microbial expression systems for recombinant proteins require nitrogen sources with controlled molecular weight distributions. Pea-derived fractions meet these specifications at scale.
- Clean-label supplement reformulation:Dietary supplement brands are replacing soy and dairy peptones with pea alternatives to capture allergen-free positioning and plant-based narrative premiums.
Market Restraints
- Yellow pea protein concentrate volatility:Input costs fluctuate with Canadian and Ukrainian harvest cycles, squeezing hydrolysate processor margins during drought years.
- Enzymatic hydrolysis equipment concentration:Industrial-scale peptide fractionation capacity clusters in northern France and the Netherlands, creating geographic supply vulnerability.
- Endotoxin specification friction:Pharmaceutical-grade peptone production requires LAL-tested batches below 10 EU/g, a threshold many food-grade hydrolysate facilities cannot economically achieve.
Strategic Opportunities
- Precision fermentation feedstocks:Alternative protein startups require defined nitrogen sources for mycelial and microbial biomass production. Pea peptones offer batch-to-batch amino acid consistency that undefined yeast extracts cannot match.
- EU Green Deal bio-based procurement mandates:Public research funding now prioritizes renewable feedstocks in life sciences applications, steering institutional buyers toward plant-derived media components.
- Direct-to-biotech distribution platforms:E-commerce marketplaces for laboratory reagents are collapsing traditional distributor markups on peptone SKUs, enabling supplier margin capture.
Industry Challenges
- Pharmacopeial monograph latency:USP and EP standards for plant-derived peptones remain in draft status, forcing manufacturers to negotiate individual drug master file pathways with each customer.
- Pea protein isolate supply integration:Hydrolysate processors lack captive access to premium-grade isolate streams, exposing them to protein supplier pricing power and allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pea Peptones Market |
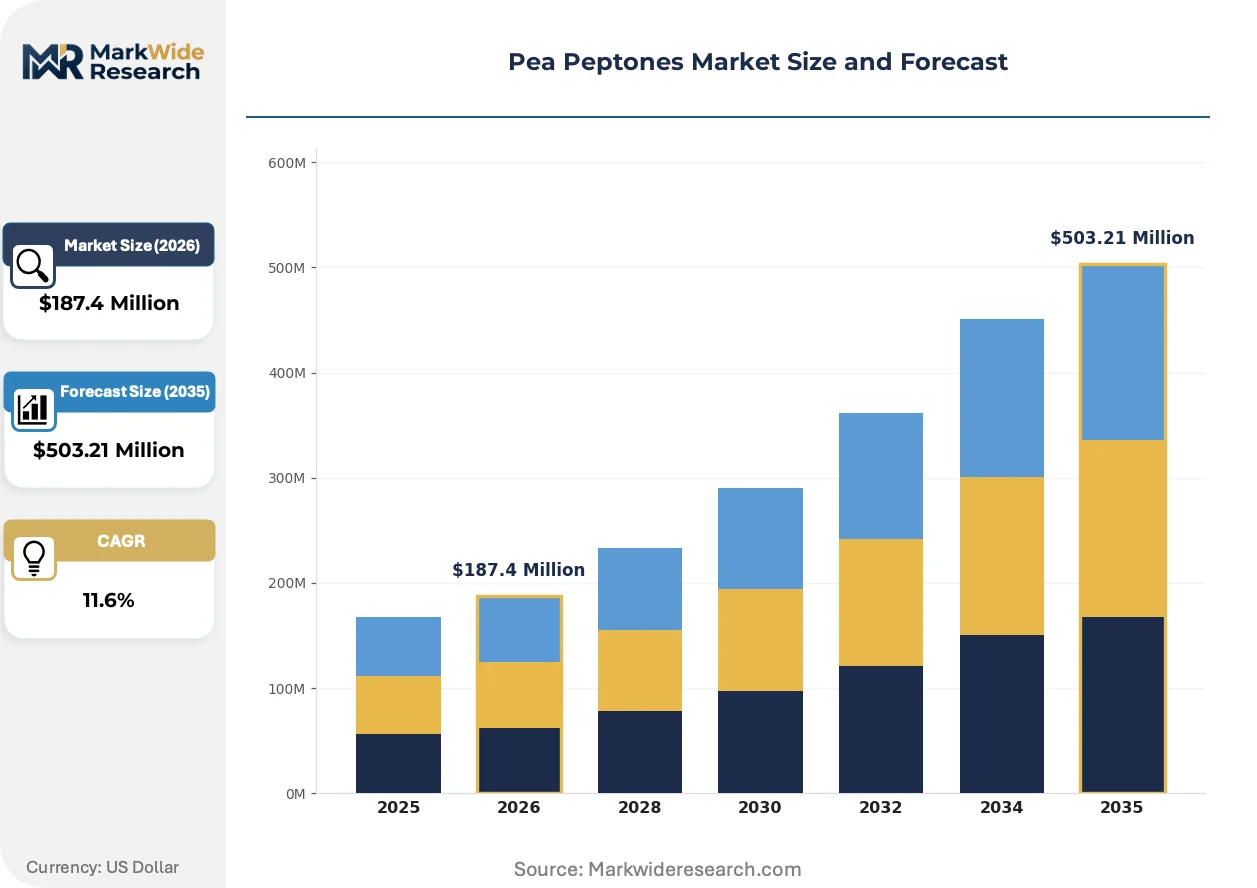
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Pea Proteins, Pea Protein Isolate, Pea Protein Concentrate, Pea Peptones Application: Animal Feed, Nutritional Supplements, Food & Beverages, Pharmaceuticals End User: Food Manufacturers, Dietary Supplement Companies, Research Institutions, Pet Food Producers Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Distributors |
| Companies Covered | Organotechnie, Solabia Group, Titan Biotech, Global BioIngredients, HiMedia Laboratories, Merck KGaA, Thermo Fisher Scientific, Kerry Group, Biotecnica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pea Peptones Market Evolving Landscape
Enzymatic process control and analytical characterization advances are transforming pea peptone from commodity hydrolysate into precision cell culture ingredient. Suppliers now compete on peptide mapping specificity rather than crude protein content alone.
Membrane filtration cascades with molecular weight cut-off tuning are integrating into production lines. Biopharmaceutical contract manufacturers specify 1-10 kDa peptide fractions for CHO cell culture applications. This granularity is compressing lot-to-lot variability and reducing validation burden for media formulators.
REACH registration deadlines for protein hydrolysate imports are forcing non-European suppliers to establish EU-based toll manufacturing partnerships. ECHA substance data requirements now cover enzymatic processing aids and residual protease activity. German and Dutch fermentation supply houses are capturing volume from Asian competitors unable to navigate registration complexity.
Biotech procurement teams are consolidating supplier panels and demanding multi-year peptide mapping certificates upfront. Large pharmaceutical buyers now audit hydrolysate facilities against ISO 13485 medical device quality standards. This elevation of vendor qualification requirements is squeezing smaller peptone producers without dedicated regulatory affairs functions.
Pea Peptones Market Segmentation
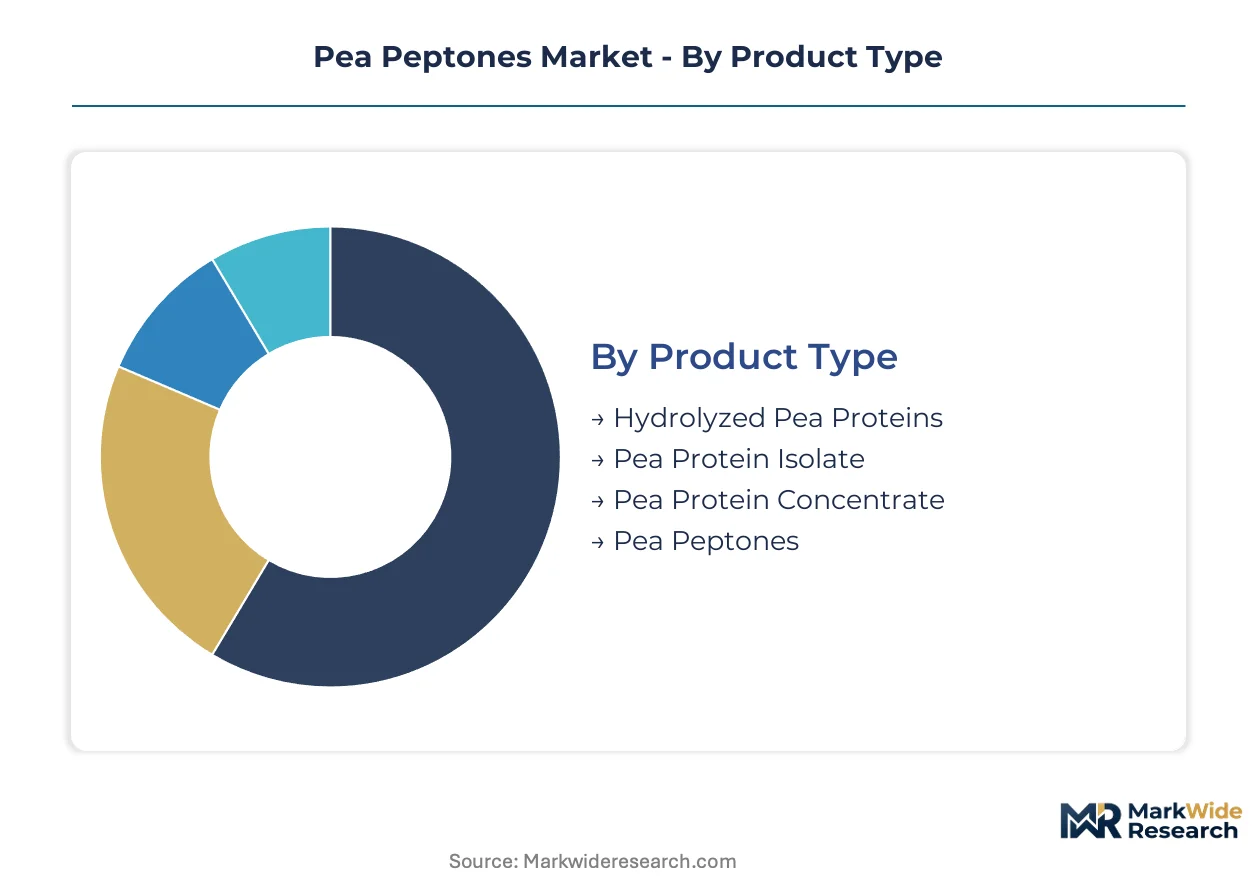
Pea peptone procurement patterns diverge sharply across product grades and end-use specifications. Pharmaceutical buyers enforce endotoxin thresholds below 10 EU/g, while food manufacturers prioritize cost-efficient hydrolysates for flavor development.
Product Type:
Standalone hydrolysates serve direct formulation needs, whereas protein isolates and concentrates function as upstream inputs requiring further enzymatic processing.
- Hydrolyzed Pea Proteins:Enzymatically cleaved peptide fractions with molecular weight distributions of 1-10 kDa dominate CHO cell culture applications. German and Dutch fermentation supply houses concentrate demand for these pharmaceutical-grade hydrolysates as EMA TSE/BSE guidelines tighten.
- Pea Protein Isolate:Refined protein streams with 85-90% purity serve as the premium feedstock for endotoxin-controlled peptone production. North American biotech clusters in Massachusetts and California drive qualification volumes for ultra-low endotoxin batches.
- Pea Protein Concentrate:Intermediate-grade inputs at 70-80% protein content supply nutritional supplement reformulation.
- Pea Peptones:Finished hydrolysate products with standardized amino acid profiles target microbial fermentation media.
Volume placements concentrate in Hydrolyzed Pea Proteins; the faster expansion belongs to Pea Protein Isolate.
Application:
Cost tiers separate commodity feed applications from premium cell culture media, with regulatory burden intensity determining margin structures.
- Animal Feed:Standardized hydrolysates with minimal processing overhead supply pet food protein fortification. Canadian harvest cycles dictate input cost volatility for this price-sensitive segment.
- Nutritional Supplements:Clean-label positioning drives reformulation from soy and dairy peptones toward allergen-free pea alternatives. Dietary supplement brands in the United States capture plant-based narrative premiums through this substitution.
- Food & Beverages:Umami precursor development and savory fermentation substrates utilize food-grade hydrolysates.
- Pharmaceuticals:Serum-free media components for recombinant protein production require peptide mapping certificates and ISO 13485 facility audits.
Pharmaceuticals command the steepest margin tier; Nutritional Supplements are climbing the fastest.
End User:
Customer sophistication spectra range from bulk commodity procurement to multi-year peptide mapping validation contracts.
- Food Manufacturers:Flavor house procurement teams source hydrolysates for savory product development at scale.
- Dietary Supplement Companies:Clean-label reformulation priorities steer nitrogen source selection toward allergen-free positioning.
- Research Institutions:Cell culture media preparation for academic laboratories requires consistent batch-to-batch amino acid profiles.
- Pet Food Producers:Protein fortification applications utilize standard-grade hydrolysates with lower specification thresholds.
Research Institutions anchor qualification-intensive volumes; Dietary Supplement Companies are expanding most quickly.
Distribution Channel:
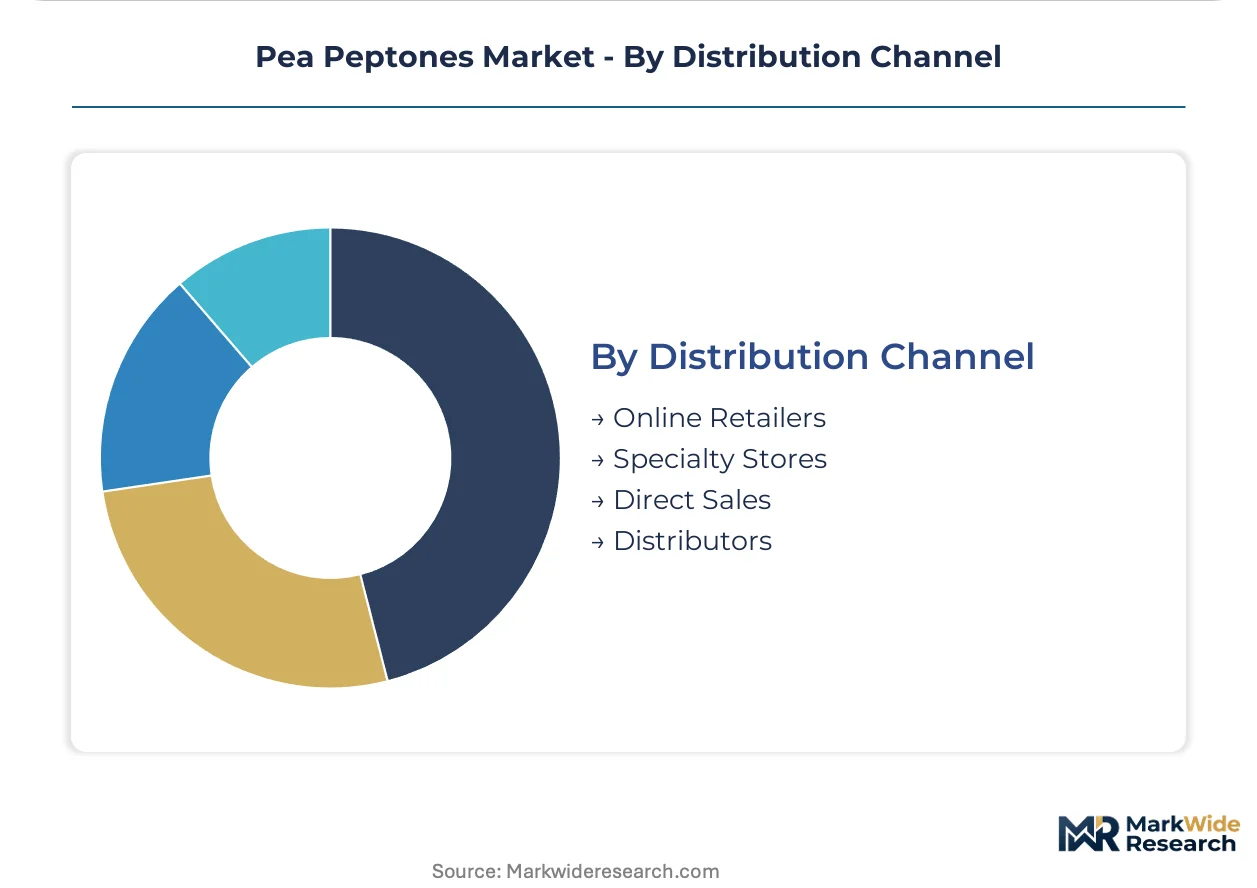
Channel selection reflects order size, technical support needs, and geographic proximity to fermentation supply clusters.
- Online Retailers:E-commerce marketplaces for laboratory reagents collapse traditional distributor markups on peptone SKUs.
- Specialty Stores:Regional life sciences distributors serve mid-tier research institutions with localized inventory.
- Direct Sales:Large pharmaceutical buyers negotiate multi-year peptide mapping certificates through supplier-direct relationships.
- Distributors:Thermo Fisher Scientific's North American catalog anchors broad-reach distribution to fragmented research customers.
Direct Sales concentrate contract value; Online Retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yellow pea harvests in Saskatchewan and Manitoba anchor raw material flows into North American hydrolysate processors. European fermentation supply houses in northern France and the Netherlands command premium-tier pharmaceutical qualification volumes. Asian contract manufacturers are expanding toll processing capacity to serve regional biotech clusters.
Germany
EMA TSE/BSE guideline enforcement drives pharmaceutical manufacturers toward documented animal-free peptone sourcing. REACH registration requirements for protein hydrolysate imports filter supplier panels toward EU-based toll manufacturers. The Cologne-Düsseldorf corridor concentrates fermentation-grade peptone distribution to contract manufacturing organizations.
United States
FDA quality standards for cell culture media components shape buyer specifications across Massachusetts and California biotech clusters. Serum-free media formulation adoption accelerates plant-derived hydrolysate procurement for recombinant protein production. The Greater Boston area anchors qualification-intensive volumes for ultra-low endotoxin batches.
France
EU Green Deal bio-based procurement mandates steer public research funding toward renewable feedstocks in life sciences applications. ANSM oversight of pharmaceutical raw materials reinforces supplier qualification protocols for peptone imports. The Lille-Roubaix fermentation supply base captures volume from Asian competitors facing ECHA registration complexity.
Netherlands
Precision fermentation feedstock demand from alternative protein startups creates defined nitrogen source requirements for mycelial biomass production. ECHA substance data requirements for enzymatic processing aids concentrate toll manufacturing partnerships in Rotterdam-Utrecht corridor. Wageningen University research clusters drive peptide mapping specificity standards for CHO cell culture applications.
India
CDSCO pharmaceutical manufacturing standards elevate vendor qualification requirements for contract research organizations serving export markets. Nutritional supplement reformulation toward clean-label positioning expands pea-derived nitrogen source adoption in dietary supplement production. Hyderabad and Bangalore biotech corridors develop in-house media preparation capabilities for biosimilar development programs.
Pea Peptones Market Competitive Landscape
Global majors compete with regional champions across distribution reach and regulatory navigation capabilities. The vendor base stratifies into three tiers: diversified life sciences conglomerates with catalog breadth, fermentation supply specialists with European regulatory expertise, and regional hydrolysate processors serving nutritional markets. Strategic moves concentrate on backward integration into pea protein isolate supply and multi-year peptide mapping certificate contracts with large pharmaceutical buyers.
Within the fermentation supply specialist tier, Organotechnie and Solabia Group exemplify European regulatory navigation capabilities. Thermo Fisher Scientific occupies a position as a diversified distributor anchoring North American research institution procurement. Kerry Group represents food-grade hydrolysate expertise extending into adjacent nutritional applications. These three anchors illustrate the competitive segmentation between pharmaceutical-grade qualification intensity and nutritional market scale efficiency.
| Leading Market Players |
|---|
| Organotechnie |
| Solabia Group |
| Titan Biotech |
| Global BioIngredients |
| HiMedia Laboratories |
| Merck KGaA |
| Thermo Fisher Scientific |
| Kerry Group |
| Biotecnica |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap hydrolysate processors in northern France and the Netherlands anchor supply discipline through multi-generational fermentation expertise, while private-equity-rolled-up protein specialists compress pricing power through volume aggregation contracts with North American biotech buyers.
Pricing Analysis
Service-bundling separates peptide mapping certificates and multi-year validation support from unbundled commodity hydrolysate transactions. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade levels stratifies by endotoxin thresholds and ISO certification intensity. Cost compression in food-grade tiers is intensifying because Canadian yellow pea protein concentrate volatility feeds directly into processor margins. Dietary supplement companies exhibit highest price sensitivity; large pharmaceutical buyers with direct sales relationships show lowest sensitivity due to qualification switching costs.
Supply Chain Analysis
Single-source vulnerability sits with enzymatic hydrolysis equipment concentration in northern France and the Netherlands, where industrial-scale peptide fractionation capacity clusters. Raw material flows draw from Canadian prairie harvests in Saskatchewan and Manitoba, Ukrainian pea protein streams, and Dutch toll-manufacturing partnerships. Regulatory restriction through REACH registration deadlines for protein hydrolysate imports creates supply chain risk for Asian competitors. Distribution runs through Thermo Fisher Scientific's North American catalog for fragmented research customers and direct sales channels for large pharmaceutical buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pea peptone supply is consolidating as EMA TSE/BSE guideline enforcement and REACH registration complexity force smaller hydrolysate processors without dedicated regulatory affairs functions toward exit or acquisition.
For Market Incumbents: Anchor qualification-intensive volumes through multi-year peptide mapping certificates with Massachusetts and California biotech clusters. Secure backward integration into premium-grade pea protein isolate supply to defend margins against Canadian harvest volatility. ISO 13485 facility audits and pharmacopeial monograph navigation capabilities serve as the primary defensive moat against emerging Asian toll manufacturers. For New Entrants and Emerging Players: Capture precision fermentation feedstock demand from alternative protein startups in the Netherlands requiring defined nitrogen sources for mycelial biomass production. Target dietary supplement reformulation white space in the United States where clean-label positioning commands narrative premiums. E-commerce marketplace distribution for laboratory reagents enables margin capture without traditional distributor markups. For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation supply specialists with European regulatory navigation capabilities in Germany and France. Long-term viability over the next decade hinges on captive access to pea protein isolate supply and peptide mapping specificity standards. Watch ECHA substance data requirement enforcement as the inflection indicator for Asian competitor displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Protein Isolate Supply | Captive feedstock access defends margins against Canadian harvest volatility and supplier pricing power. |
| ISO 13485 Facility Certification Investment | Medical device quality standards satisfy large pharmaceutical buyer audit requirements and compress competitor panels. |
| Multi-Year Peptide Mapping Certificate Contracts | Long-term validation support locks in biotech procurement teams and elevates switching costs for rival suppliers. |
| EU-Based Toll Manufacturing Partnerships | REACH registration compliance enables volume capture from Asian competitors facing ECHA complexity barriers. |
| E-Commerce Marketplace Distribution Launch | Direct-to-biotech platforms collapse traditional distributor markups and enable margin recovery on peptone SKUs. |
Research Methodology
Independent corroboration across fermentation supply house executives, pharmaceutical media formulators, and regulatory affairs specialists underwrites the qualitative findings. Primary interviews with Dutch toll manufacturing partners, German contract manufacturing organization procurement leads, and North American dietary supplement brand managers combined with secondary validation from ECHA substance registration databases, FDA quality guidance documents for cell culture media components, and ISO certification registries. Bottom-up volume triangulation against top-down market sizing anchored the segmentation outputs.
Rate-of-change decomposition across product grade tiers, application segments, and geographic regulatory clusters structured the analytical framework. Pharmaceutical-grade versus food-grade versus feed-grade stratification, endotoxin specification thresholds, and regional EMA versus FDA versus CDSCO compliance pathways formed the core segmentation dimensions. CAGRs derived from elasticity-adjusted demand curves and input cost pass-through modeling across the projection horizon. Pea protein isolate spot price volatility and enzymatic processing capacity utilization served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH registration deadline enforcement and pharmacopeial monograph finalization timelines. Forecasts reflect documented assumptions regarding EMA TSE/BSE guideline adherence and serum-free media formulation adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Pregelatinized Starch Market
Ingredients
South America Vegetable Oil Market
Ingredients
Mirepoix Market
Ingredients
Coconut Flour Market
Ingredients
Food Grade Linseed Oil Market
Ingredients
Native Starch Market
Ingredients
EPA and DHA Omega-3 Ingredient Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Malted Wheat Flour Market
Ingredients
Animal-Derived Ingredients Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
Edible Animal Fat Market
Ingredients
North America Fruit and Vegetable Ingredients Market
Ingredients
Africa Food Ingredients Market
Ingredients
Brazil Corn Syrup Market
Ingredients
Wheat Germ Oil Market