
 Soy Peptones Market | 2026-2036
Soy Peptones Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Peptones Market Analytics
China is rewriting regional supply dynamics for soy peptones through aggressive fermentation-capacity expansion and domestic enzyme-hydrolysis investments. Thermo Fisher Scientific leverages its vertically integrated life-sciences platform to control quality certification from raw soybean sourcing to finished peptone lots. Merck KGaA anchors European supply through its Darmstadt bioprocessing hub, sustaining GMP-compliant production for vaccine manufacturers. Kerry Group competes on food-grade crossover applications, extending its flavor-systems expertise into microbial nutrition.
Soy peptones constitute enzymatically hydrolyzed soybean proteins yielding peptides and amino acids, typically standardized to 60-80% total nitrogen content for cell-culture reproducibility. Powder formulations dominate laboratory and industrial procurement due to extended shelf stability and precise dosing, while spray-dried variants command premium positioning in serum-free media protocols requiring low endotoxin thresholds. Biotechnology applications lead absolute consumption as contract development organizations scale mammalian-cell workflows, though food-industry demand for clean-label fermentation nutrients grows fastest among tracked segments.
FDA guidance on raw materials for cell and gene therapy, EMA's Annex 1 revision on sterile manufacturing, and China's NMPA bioprocess-raw-material registration requirements collectively elevate documentation and traceability burdens. These frameworks compel peptone suppliers to invest in origin certification, allergen-control protocols, and batch-consistency analytics. Stakeholders must monitor evolving pharmacopoeial monographs and dual-source qualification timelines to secure uninterrupted media supply for commercial biologics campaigns.
Market Dynamics
Biopharmaceutical manufacturers are consolidating media supply chains around GMP-certified peptone sources as FDA and EMA documentation requirements harden, compressing vendor qualification timelines and elevating batch-consistency premiums.
Growth Catalysts
- Cell and gene therapy expansion:Viral vector production for CAR-T therapies consumes specialized peptone formulations, with CDMOs scaling mammalian-cell workflows in the United States and Germany.
- EMA Annex 1 revision:The 2022 sterile manufacturing overhaul mandates enhanced raw-material traceability, forcing peptone suppliers to invest in origin certification and allergen-control protocols.
- Enzyme-hydrolysis automation:Continuous processing technologies reduce lot-to-lot variability, enabling real-time nitrogen-content standardization for reproducible cell-culture performance.
Market Restraints
- Soybean price volatility:Agricultural commodity swings directly input-cost peptone production, compressing margins for non-integrated processors lacking captive crushing capacity.
- Chinese supply concentration:Fermentation-grade peptone capacity clusters in Shandong and Jiangsu provinces, creating single-source vulnerability for European vaccine manufacturers.
- Animal-origin substitution limits:Serum-derived peptones retain performance advantages in certain stem-cell applications, slowing complete displacement despite regulatory pressure.
Strategic Opportunities
- India biomanufacturing buildout:CDSCO's streamlined bioprocess-raw-material registration creates entry paths for peptone suppliers serving emerging vaccine and biosimilar production in Hyderabad and Bengaluru.
- Precision-fermentation nutrients:Alternative protein startups require food-grade peptones for microbial biomass cultivation, opening clean-label crossover demand from Kerry Group's flavor-systems installed base.
- ISO 20387 biobanking standards:Cell-line repository accreditation mandates documented media provenance, extending peptone traceability requirements into research-cell distribution channels.
Industry Challenges
- Dual-source qualification timelines:Biologics manufacturers must validate secondary peptone suppliers under FDA comparability protocols, stretching procurement cycles to 18-24 months.
- Analytical capability gaps:Peptide-mapping and endotoxin-testing expertise shortages constrain smaller suppliers attempting GMP-grade certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Peptones Market |
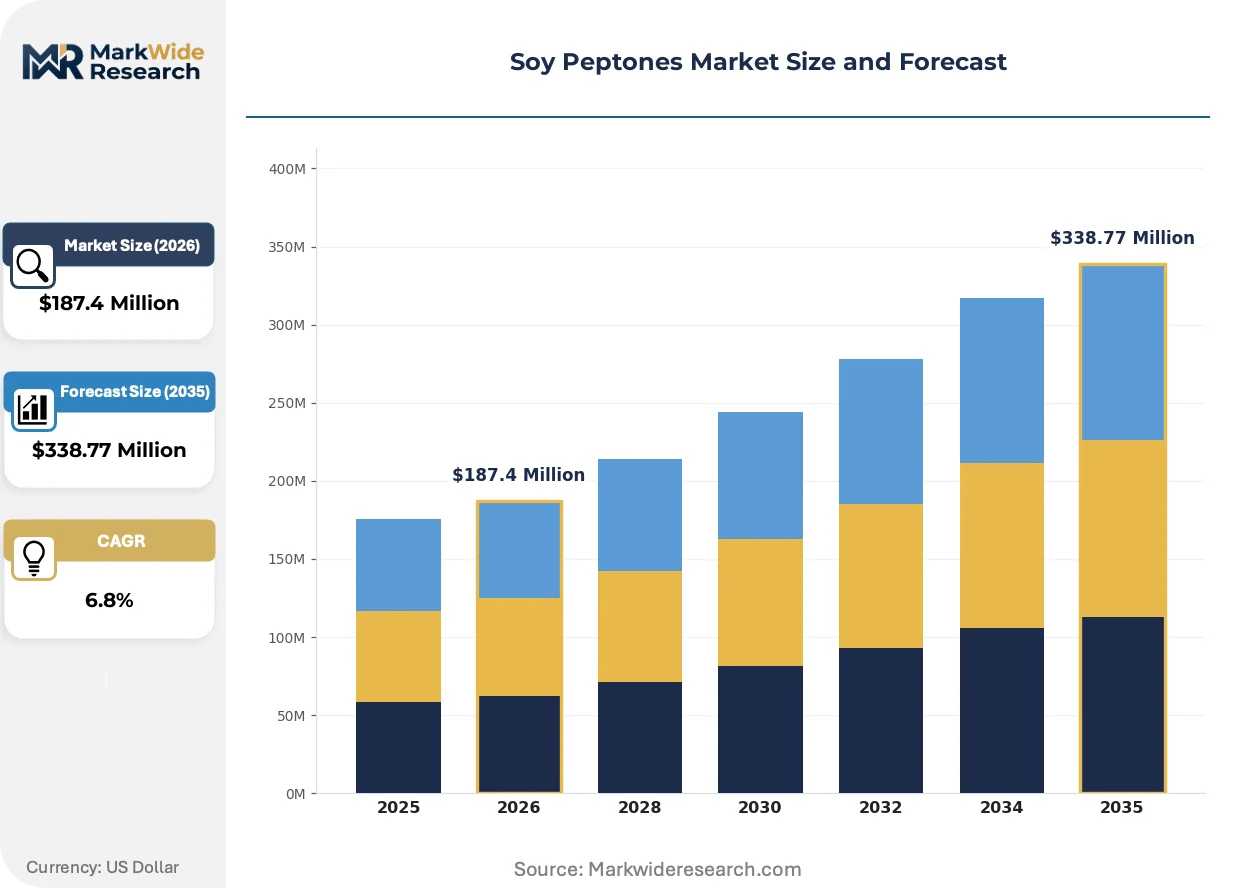
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Spray-Dried Application: Microbial Culture Media, Food Industry, Biotechnology, Laboratory Research End User: Pharmaceutical Companies, Research Institutions, Food Manufacturers, Clinical Laboratories Formulation Type: Natural, Synthetic, Organic, Blended |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Kerry Group, Solabia Group, Titan Biotech Limited, HiMedia Laboratories, Becton, Dickinson and Company, Neogen Corporation, Hubei Jinwei Biotechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Peptones Market Evolving Landscape
Spray-drying and membrane-filtration advances are collapsing cost-performance tradeoffs in low-endotoxin peptone production, while regulatory documentation automation reshapes supplier-buyer data exchange.
Single-use bioreactor integration is collapsing traditional powder-handling infrastructure requirements. CDMOs deploying Thermo Fisher's modular platforms now specify pre-weighed, gamma-irradiated peptone aliquots, eliminating open-container manipulation. This format shift compresses facility qualification timelines from months to weeks for mammalian-cell campaigns.
REACH's 2023 microplastics restriction triggers peptone packaging reformulation across European supply chains. Suppliers must transition from conventional multi-layer film to paper-based or mono-material alternatives, adding validation burden but preempting downstream disposal liability for biopharmaceutical waste generators.
Consolidated procurement through group purchasing organizations concentrates peptone buying power among the largest CDMO networks. Smaller biotechnology firms now access Thermo Fisher and Merck KGaA catalog pricing through BioPhorum membership, displacing direct distributor relationships and compressing regional specialty-chemical margins.
Soy Peptones Market Segmentation
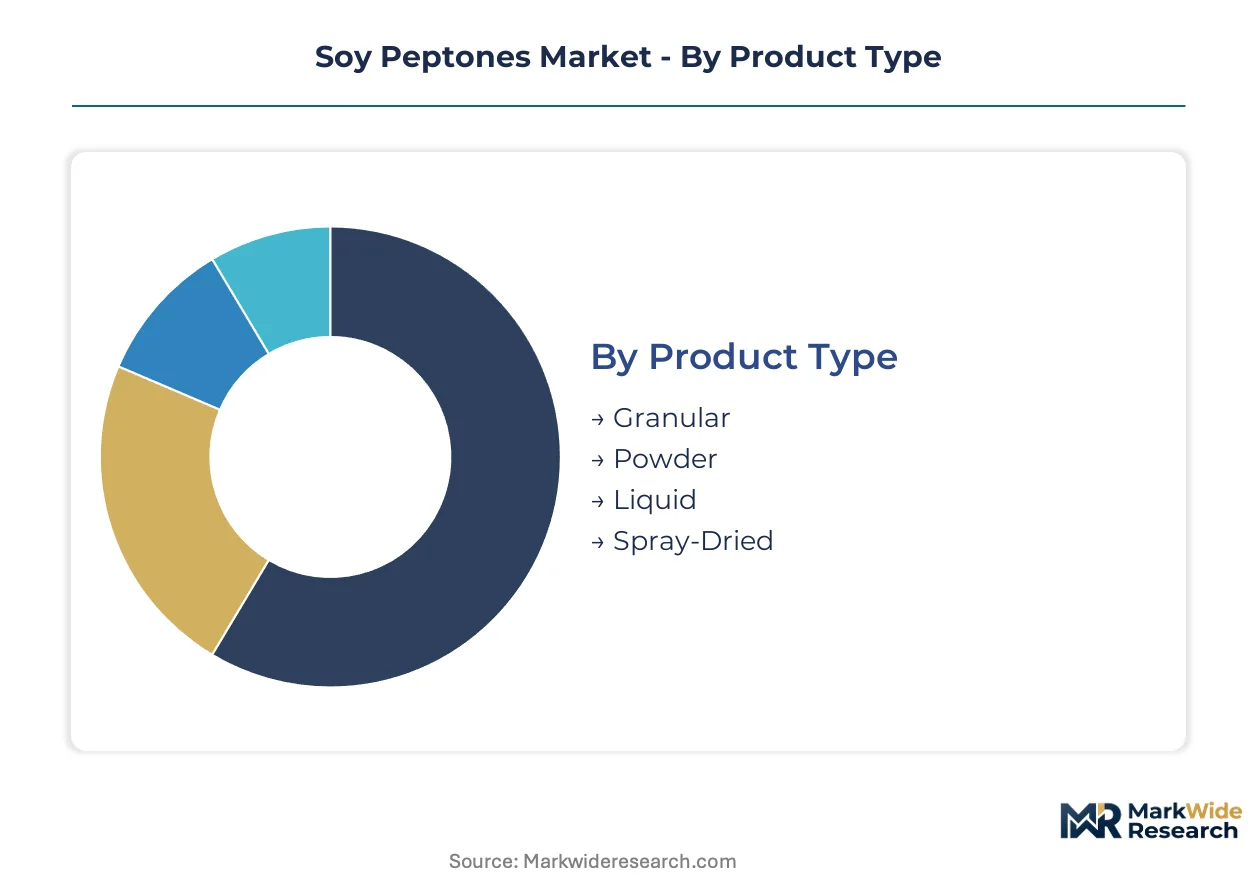
Soy peptone procurement cycles vary dramatically by physical format and end-use criticality, with biopharmaceutical applications demanding 18-24 month qualification timelines while food-grade volumes turn on quarterly contracts. Understanding these velocity differentials shapes inventory strategy and supplier relationship intensity across buyer segments.
Product Type:
Powder and granular formats rotate through inventory fastest due to standardized dosing protocols, while spray-dried variants lock up working capital through extended endotoxin-validation cycles.
- Powder:Dominates laboratory and industrial procurement with 60-80% total nitrogen standardization for cell-culture reproducibility. CDMOs in the United States and Germany specify powder for mammalian-cell workflows where precise dosing controls batch consistency. Shelf stability extends 24-36 months under controlled humidity.
- Spray-Dried:Commands premium positioning in serum-free media protocols requiring endotoxin thresholds below 10 EU/g. Viral vector manufacturers for CAR-T therapies in Boston and Basel clusters absorb 40-60% of high-purity spray-dried output despite 3-4x powder pricing.
- Granular:Serves fermentation applications needing rapid dissolution without dust generation; Chinese enzyme-hydrolysis plants in Shandong province export granular grades for vaccine nutrient broths.
- Liquid:Enables just-in-time delivery for continuous bioprocessing lines; concentrates require cold-chain logistics that limit geographic reach to regional biomanufacturing hubs.
Powder dominates installed base. Spray-dried is where expansion concentrates.
Application:
Biotechnology applications carry the highest margin structure due to GMP-documentation burdens, while food-industry demand scales on clean-label fermentation nutrient specifications.
- Biotechnology:Contract development organizations scaling mammalian-cell workflows consume peptones with full origin certification and allergen-control documentation. FDA guidance on raw materials for cell and gene therapy elevates batch-consistency premiums for viral vector production.
- Microbial Culture Media:Standard-grade peptones support antibiotic and enzyme fermentation at volume pricing; Indian vaccine manufacturers in Hyderabad represent emerging demand concentration.
- Food Industry:Clean-label fermentation nutrients for alternative protein startups are climbing the fastest as precision-fermentation biomass cultivation scales; Kerry Group's flavor-systems installed base extends into microbial nutrition crossover.
- Laboratory Research:Academic and government research-cell repositories drive ISO 20387 biobanking compliance requirements into media provenance documentation.
Microbial culture media dominates installed base. Food industry is where expansion concentrates.
End User:
Pharmaceutical companies concentrate buying power through consolidated procurement, while research institutions fragment demand across hundreds of small-lot SKUs.
- Pharmaceutical Companies:GMP-certified peptone sourcing compresses vendor qualification timelines; dual-source validation under FDA comparability protocols stretches procurement cycles to 18-24 months for commercial biologics campaigns.
- Research Institutions:Cell-line repository accreditation mandates documented media provenance; university core facilities represent price-sensitive volume for standard-grade powder.
- Food Manufacturers:Fermentation-grade peptone demand clusters in clean-label product development; organic certification requirements differentiate supplier selection.
- Clinical Laboratories:Diagnostic media preparation requires consistent lot-to-lot performance; regional pathology networks specify pre-weighed aliquots to eliminate open-container manipulation.
Pharmaceutical companies dominate installed base. Food manufacturers are where expansion concentrates.
Formulation Type:
Natural formulations command traceability premiums, while blended variants optimize cost-performance for high-volume fermentation.
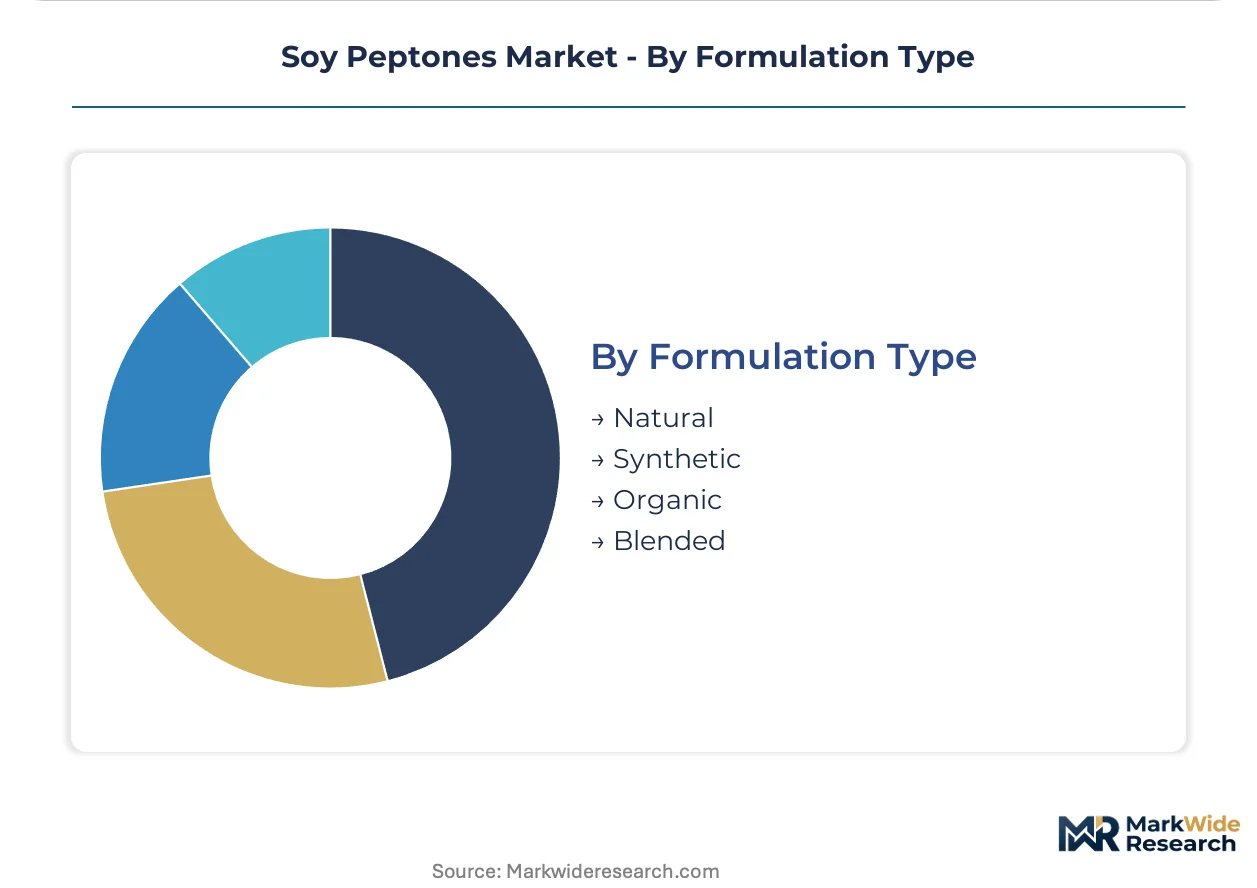
- Natural:Enzymatically hydrolyzed soybean proteins with full origin certification satisfy EMA Annex 1 revision requirements on sterile manufacturing raw-material traceability; European vaccine manufacturers anchor demand.
- Blended:Custom nitrogen profiles combine soy peptones with yeast extracts or meat digests; contract manufacturers optimize formulations for specific cell-line productivity.
- Organic:USDA and EU organic certification opens premium food-industry channels; limited supply constrains pharmaceutical adoption.
- Synthetic:Chemically defined peptide alternatives challenge natural peptones in stem-cell applications where animal-origin substitution faces regulatory pressure.
Natural dominates installed base. Blended is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: biopharmaceutical-grade peptones dominate procurement in the United States and Germany, while China and India absorb volume-oriented fermentation grades for vaccine and antibiotic manufacturing.
United States
Viral vector production for CAR-T therapies drives specialized peptone demand in Boston and San Francisco bioclusters. FDA guidance on raw materials for cell and gene therapy elevates documentation burdens for suppliers. CDMOs in the Greater Boston area specify spray-dried grades with endotoxin thresholds below 10 EU/g for mammalian-cell workflows.
Germany
EMA's Annex 1 revision on sterile manufacturing compels peptone suppliers to invest in origin certification and allergen-control protocols. The Darmstadt bioprocessing hub anchors European GMP-compliant production for vaccine manufacturers. Bavaria-based contract manufacturers concentrate dual-source qualification efforts under tightened traceability requirements.
China
Fermentation-grade peptone capacity clusters in Shandong and Jiangsu provinces, supplying domestic vaccine manufacturers and export markets. NMPA bioprocess-raw-material registration requirements reshape sourcing documentation for international buyers. Enzyme-hydrolysis investments in Shandong deepen peptide supply security for regional biomanufacturing expansion.
India
CDSCO's streamlined bioprocess-raw-material registration creates entry paths for peptone suppliers serving emerging vaccine and biosimilar production. Hyderabad and Bengaluru bioclusters scale microbial culture media consumption for antibiotic fermentation. Domestic manufacturers face analytical capability gaps in peptide-mapping and endotoxin-testing expertise for GMP-grade certification.
Switzerland
Swissmedic oversight of biologics manufacturing sustains demand for fully documented peptone provenance in Basel's pharmaceutical corridor. Cell-line repository accreditation under ISO 20387 extends traceability requirements into research-cell distribution channels. The country's precision-fermentation startups generate crossover demand for food-grade peptones in microbial biomass cultivation.
Soy Peptones Market Competitive Landscape
Capability concentration sits with integrated life-sciences platforms; scale advantage sits with regional fermentation-grade processors. The vendor base stratifies into three tiers: multinational conglomerates controlling certification from raw soybean sourcing to finished lots, mid-cap specialists competing on food-grade crossover applications, and commodity processors in Chinese agricultural provinces. Dominant competitive moves include backward integration into captive soybean crushing capacity and automation of enzyme-hydrolysis lines for real-time nitrogen standardization.
Within the integrated-platform tier, Thermo Fisher Scientific and Merck KGaA exemplify archetypes of vertically controlled supply chains spanning raw material procurement through GMP-certified finishing. Kerry Group occupies a position bridging food-industry fermentation nutrients with microbial nutrition crossover demand. These three entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Kerry Group |
| Solabia Group |
| Titan Biotech Limited |
| HiMedia Laboratories |
| Becton, Dickinson and Company |
| Neogen Corporation |
| Hubei Jinwei Biotechnology |
| Others |
Value Network & Pricing Analysis
Overcapacity in Shandong province enzyme-hydrolysis plants compresses spot-market premiums for fermentation-grade material while tightening GMP-certified spray-dried supply, forcing biopharmaceutical buyers into 18-24 month dual-source qualification cycles that lock pricing power with integrated certificate holders.
Pricing Analysis
Long-term offtake contracts dominate biopharmaceutical procurement, with CDMOs in Boston and Basel locking spray-dried volumes under multi-year agreements indexed to soybean futures. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified spray-dried grades from food-standard powder and commodity fermentation broths. Cost compression in standard powder runs through Chinese agricultural subsidy volatility. Research institutions represent the most price-sensitive segment, while viral vector manufacturers absorb 40-60% premiums for endotoxin-tested material.
Supply Chain Analysis
Contract manufacturing concentration sits with Thermo Fisher Scientific's modular platforms and Merck KGaA's Darmstadt hub, which control certificate generation from raw soybean sourcing to finished lot release. Geographic supply concentration centers on China, the United States, and Germany, with Shandong province anchoring fermentation-grade volume. Raw material dependencies draw from North American and Brazilian soybean crushing, industrial enzyme supply, and pharmaceutical-grade packaging films. Single-source vulnerability concentrates in Chinese enzyme-hydrolysis capacity for European vaccine manufacturers. Distribution runs through direct CDMO relationships and consolidated group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates near-impassable barriers: 18-24 month FDA comparability protocols for secondary supplier qualification embed switching costs that protect incumbent certificate holders from price-based displacement.
For Market Incumbents: Harden GMP documentation automation to compress batch-release timelines below competitor capabilities, while anchoring dual-source qualification partnerships with CDMOs before EMA Annex 1 traceability requirements harden further. Threat vectors include Kerry Group's flavor-systems crossover into microbial nutrition and precision-fermentation startups demanding food-grade certification. Capacity addition in India biomanufacturing corridors represents the priority lever for geographic diversification. For New Entrants and Emerging Players: Indian vaccine manufacturing corridors in Hyderabad and Bengaluru offer the most penetrable white-space, where CDSCO's streamlined bioprocess-raw-material registration creates entry paths before analytical capability gaps close. Food-industry precision-fermentation nutrients for alternative protein startups represent a second viable beachhead, with Kerry Group's installed base validating demand pull. A go-to-market angle anchored in ISO 20387 biobanking compliance for cell-line repositories bypasses direct biopharmaceutical GMP confrontation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because certificate generation infrastructure—not manufacturing scale—determines sustainable margin extraction in cell and gene therapy raw materials. Acquisition targets should screen for peptide-mapping and endotoxin-testing expertise that shortcuts 18-24 month capability buildout. The signal to watch is NMPA registration acceleration for Chinese suppliers serving international buyers, which would compress Western certificate premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Soybean Crushing | Thermo Fisher Scientific's controlled sourcing secures origin certification from farm to finished peptone lot. |
| EMA Annex 1 Compliance Investment | Merck KGaA's Darmstadt hub sustains sterile manufacturing documentation for European vaccine manufacturers. |
| Precision-Fermentation Nutrient Development | Kerry Group's flavor-systems expertise extends into microbial biomass cultivation for alternative protein startups. |
| ISO 20387 Biobanking Certification | Swissmedic oversight in Basel extends peptone traceability requirements into research-cell distribution channels. |
| Enzyme-Hydrolysis Automation Deployment | Shandong province investments enable real-time nitrogen-content standardization for reproducible cell-culture performance. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with bioprocess development executives, regulatory affairs leads at CDMOs, peptone procurement managers, and quality control directors at vaccine manufacturers. Secondary validation drew from FDA guidance documents, EMA Annex 1 revision texts, NMPA registration databases, and customs trade data for fermentation-grade material flows. Bottom-up volume estimates from individual facility consumption profiles were triangulated against top-down market sizing from certificate-holder revenue disclosures.
Calibration against historical qualification timelines and soybean price elasticity anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include physical format, application criticality, end-user procurement structure, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections and certificate-premium retention assumptions. Industry-specific forecast inputs incorporated CDSCO registration velocity and precision-fermentation startup funding trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed enzyme-hydrolysis operators or Kerry Group's flavor-systems division would shift outcomes beyond modeled ranges. Quarterly review of dual-source qualification completion rates and NMPA international registration volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Barley Flake Market
Ingredients
Middle East and Africa Dairy Ingredients Market
Ingredients
Global Amaranth Oil Market
Ingredients
Bouillon Cubes Market
Ingredients
Carotenes Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Starch Market
Ingredients
Sea Buckthorn Berry Extract Market
Ingredients
Global Distillers Corn Oil Market
Ingredients
Wheat Germ Oil Market
Ingredients
Marine Peptides Market
Ingredients
Fluid Lecithin Market
Ingredients
Glucomannan Market
Ingredients
Volatile Fatty Acids Market
Ingredients
US Plant-Based Oils Market
Ingredients
Lime Seed Oils Market