
 Europe Whey Protein Ingredients Market | 2026-2036
Europe Whey Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Whey Protein Ingredients Market Foresight
Modular portioning is pivoting how European buyers select whey protein formats, with single-serve sachets and stackable dosing systems replacing bulk canisters in direct-to-consumer channels. Arla Foods amba leverages its Danish dairy cooperative structure to sustain captive whey streams across Northern Europe. Glanbia plc anchors its ingredient dominance through specialized whey fractionation capabilities at Irish processing sites. Carbery Group competes on whey protein isolate purity grades tailored to sports nutrition contract manufacturers.
Europe whey protein ingredients comprise the refined protein fractions separated from liquid whey during cheese manufacturing, typically containing beta-lactoglobulin and alpha-lactalbumin fractions with protein concentrations ranging from 34% to 90% depending on processing intensity; these ingredients serve primarily as functional nutrition inputs where emulsification, gelation, and amino acid completeness determine formulation value. Whey protein isolate commands premium positioning due to higher purity thresholds and lower lactose residuals demanded by clinical nutrition and elite sports segments. Sports nutrition applications absorb the largest volume flows, while functional foods represent the fastest-expanding application as bakery and beverage manufacturers reformulate for protein fortification.
EFSA maintains strict health claim validation protocols that constrain how whey protein products communicate muscle maintenance and satiety benefits to European consumers. REACH chemical registration requirements and the EU Green Deal's emerging carbon border adjustments are reshaping sourcing compliance for imported whey derivatives. Stakeholders must monitor how ECHA's evolving microplastics restrictions intersect with whey protein packaging formats, particularly where single-use portion packs proliferate in German and Dutch retail channels.
Market Dynamics
Modular portioning is compressing traditional bulk purchasing patterns across European whey protein channels, as single-serve sachets and stackable dosing systems displace canisters in direct-to-consumer retail. This format shift is forcing processors to reconfigure filling lines and packaging specifications while simultaneously navigating tightening sustainability mandates under the EU Green Deal.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Sustainability criteria tightening for dairy-derived ingredients is accelerating investment in carbon-efficient whey processing infrastructure across Northern Europe.
- Sports nutrition contract manufacturing:Germany's functional food manufacturing corridor is absorbing expanded whey protein isolate volumes as brands localize production for reduced lead times.
- Protein fortification reformulation:Bakery and beverage manufacturers across France and the Netherlands are integrating whey concentrates into mainstream food applications beyond traditional sports nutrition.
Market Restraints
- Input cost volatility:Fresh milk supply fluctuations and energy price spikes at Irish and Danish processing sites are compressing margin structures for whey fractionation operations.
- Supply concentration risk:Captive whey streams controlled by cooperative dairy structures in Denmark and Ireland limit independent processor access to raw material.
- EFSA health claim validation:Strict protocols constraining muscle maintenance and satiety benefit communication are increasing marketing compliance costs and claim substantiation timelines.
Strategic Opportunities
- Clinical nutrition expansion:Germany's aging demographic and hospital nutrition protocols are creating demand for high-purity whey protein isolate in medical food formulations.
- Carbon border adjustment positioning:Early compliance with emerging EU carbon border mechanisms offers export advantage for European processors serving Asian markets.
- Plant-dairy hybrid formulations:Convergence of whey protein with pea and oat bases is opening clean-label positioning in Dutch and German premium retail channels.
Industry Challenges
- Fractionation specialist scarcity:Shortage of process engineers skilled in membrane filtration and chromatographic separation is constraining capacity expansion at Irish and French processing sites.
- REACH chemical registration timelines:Extended ECHA evaluation periods for novel whey derivatives are delaying product launches and reformulation cycles.
- Microplastics packaging compliance:Evolving ECHA restrictions on single-use portion packs are forcing rapid material transitions in German and Dutch retail formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Whey Protein Ingredients Market |
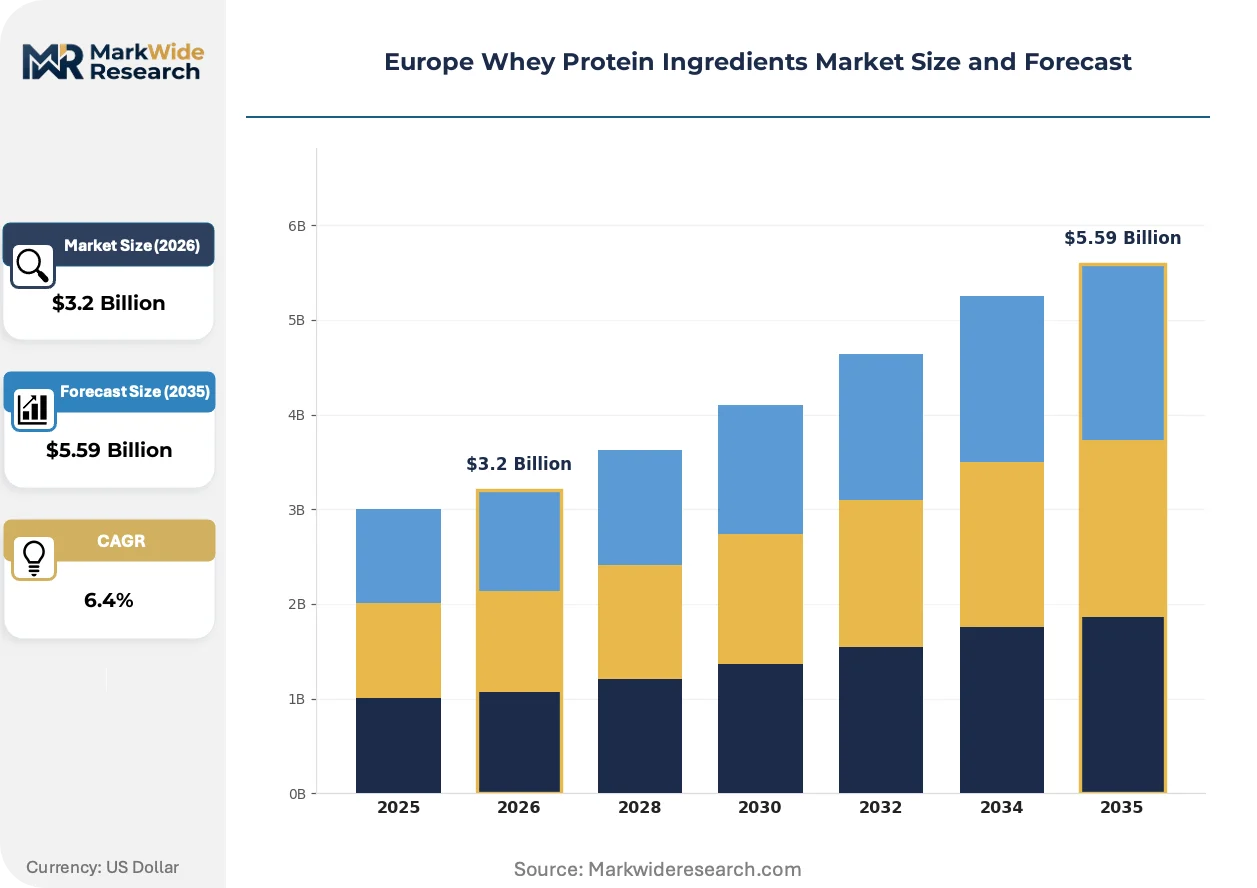
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein Concentrate, Whey Protein Isolate, Hydrolyzed Whey Protein, Native Whey Protein Application: Sports Nutrition, Functional Foods, Infant Nutrition, Bakery Products End User: Manufacturers, Fitness Centers, Health Stores, Hospitals Form: Powder, Liquid, Bar, Capsule |
| Companies Covered | Arla Foods amba, Glanbia plc, Carbery Group, Agrial S.A., Groupe Lactalis S.A., Koninklijke FrieslandCampina N.V., Lactoprot Deutschland GmbH, MEGGLE GmbH & Co. KG, Kerry Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Whey Protein Ingredients Market Shifts & Advancements
Processing intensification and sustainability verification are reshaping competitive positioning across European whey protein supply chains. Technology investments now prioritize carbon footprint reduction alongside purity metrics.
Membrane filtration advancements are electrifying whey protein isolate production economics. German and Irish processors are adopting ceramic microfiltration systems that reduce energy consumption per kilogram of protein recovered. Sports nutrition contract manufacturers are absorbing these premium isolates at accelerated contract renewal cycles, compressing commodity-grade concentrate margins across Northern Europe.
REACH chemical registration requirements are restructuring import compliance for whey derivatives entering European customs territory. Non-EU processors face expanded documentation burdens and extended evaluation timelines. Clinical nutrition and infant formula segments, where supply security demands are highest, are accelerating dual-sourcing strategies to mitigate border delay risks.
Direct-to-consumer subscription models are fragmenting traditional ingredient procurement relationships. Sports nutrition brands in Germany and the Netherlands are bypassing distributors to contract directly with Arla Foods amba and Glanbia plc for customized fractionation. This channel compression is most visible in Berlin and Amsterdam metropolitan markets, where same-day delivery expectations are forcing inventory positioning closer to end-consumers.
Europe Whey Protein Ingredients Market Segmentation
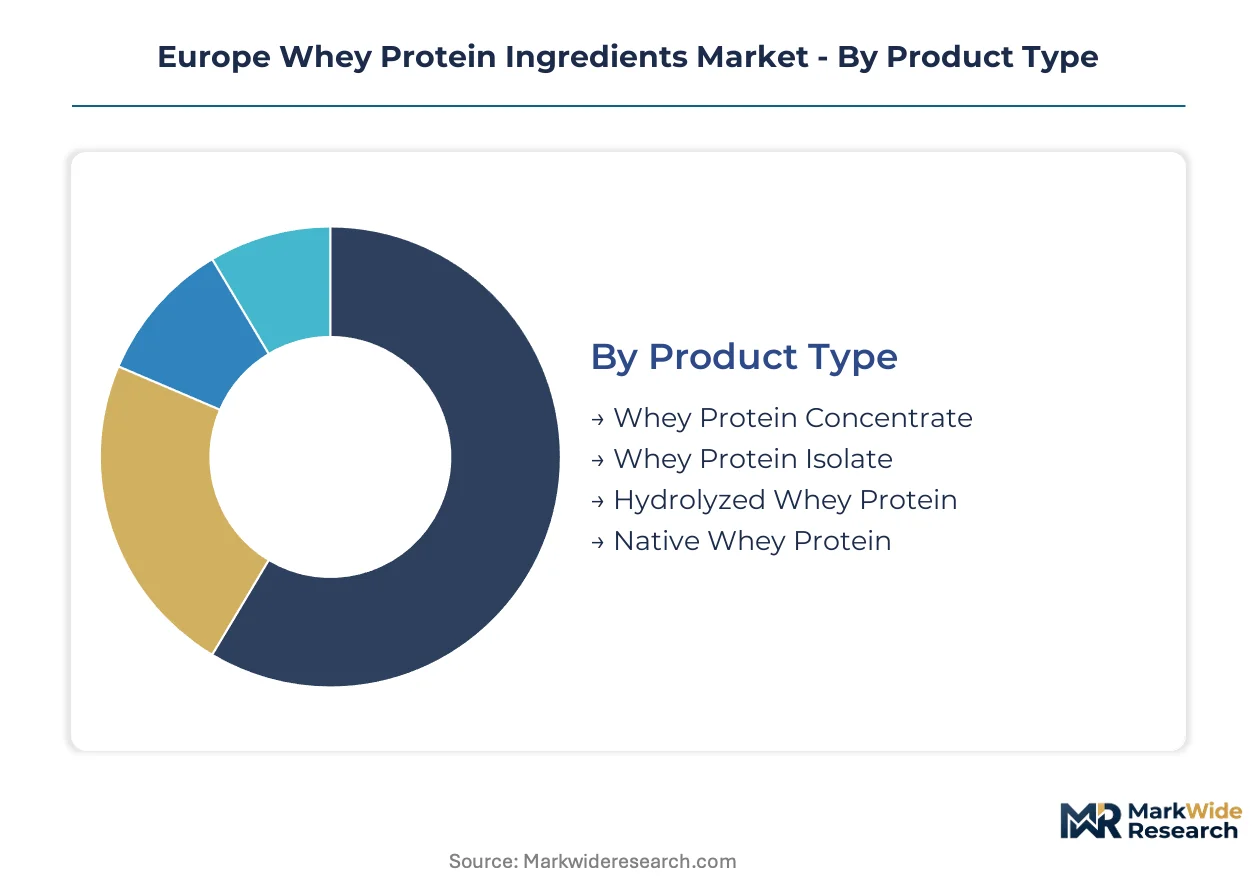
Segmentation in European whey protein ingredients reveals how processing intensity, application requirements, and delivery formats create distinct value tiers. Each dimension carries regulatory and supply chain implications that shape procurement strategies across Northern European manufacturing corridors.
Product Type:
Processing intensity and protein fractionation depth determine functional performance and pricing tiers across European dairy processing sites.
- Whey Protein Isolate:Contains 90%+ protein content with minimal lactose and fat residuals. German clinical nutrition manufacturers and Dutch sports nutrition brands absorb premium volumes where EFSA health claim substantiation demands purity thresholds. Membrane filtration investments at Irish processing sites are expanding isolate capacity to serve this specification tier.
- Whey Protein Concentrate:Ranges from 34% to 80% protein depending on ultrafiltration intensity. French bakery and beverage manufacturers integrate concentrate grades for cost-efficient protein fortification in mainstream retail products. Energy price volatility at Danish cooperative processing sites compresses margins on standard concentrate grades.
- Hydrolyzed Whey Protein:Pre-digested peptide fractions for rapid amino acid absorption. Infant formula manufacturers in Netherlands and Germany specify hydrolyzed grades for reduced allergenicity profiles.
- Native Whey Protein:Cold-filtered from skim milk rather than cheese whey, preserving undenatured protein structures. Premium positioning in German organic and clean-label sports nutrition channels.
Whey Protein Isolate leads on scale; Native Whey Protein leads on momentum.
Application:
End-use specifications create divergent purity, solubility, and documentation requirements across European formulation sectors.
- Sports Nutrition:Absorbs the largest volume flows across German and Dutch contract manufacturing networks. Protein fortification in ready-to-drink beverages and powder blends drives consistent demand for isolate and concentrate grades with rapid dispersibility characteristics.
- Functional Foods:Bakery and beverage reformulation across France and Netherlands is expanding whey protein incorporation beyond traditional sports channels. REACH registration compliance for novel food applications extends development timelines for ingredient suppliers.
- Infant Nutrition:Demands the highest purity certifications and batch traceability. Hydrolyzed whey fractions serve specialized hypoallergenic formula segments under strict EFSA safety protocols.
- Bakery Products:Protein enrichment in bread and pastry applications requires heat-stable whey concentrates that maintain functionality through baking temperatures.
Sports Nutrition leads on scale; Functional Foods leads on momentum.
End User:
Procurement sophistication and volume scale separate institutional buyers from fragmented retail channels across European markets.
- Manufacturers:Sports nutrition and functional food producers in Germany's manufacturing corridor negotiate direct contracts with Arla Foods amba and Glanbia plc for customized fractionation. Specifications cover protein content, microbiological standards, and carbon footprint documentation under EU Green Deal requirements.
- Fitness Centers:Smaller volume procurement through distributors, increasingly demanding single-serve portion formats and private-label branding options.
- Health Stores:Premium retail channels in Amsterdam and Berlin metropolitan areas stock organic and native whey variants with sustainability certifications.
- Hospitals:Clinical nutrition protocols in German healthcare systems specify high-purity isolates for medical food formulations serving aging demographics.
Manufacturers lead on scale; Hospitals lead on momentum.
Form:
Delivery format selection reflects consumption occasion, shelf stability requirements, and packaging sustainability pressures under evolving ECHA regulations.
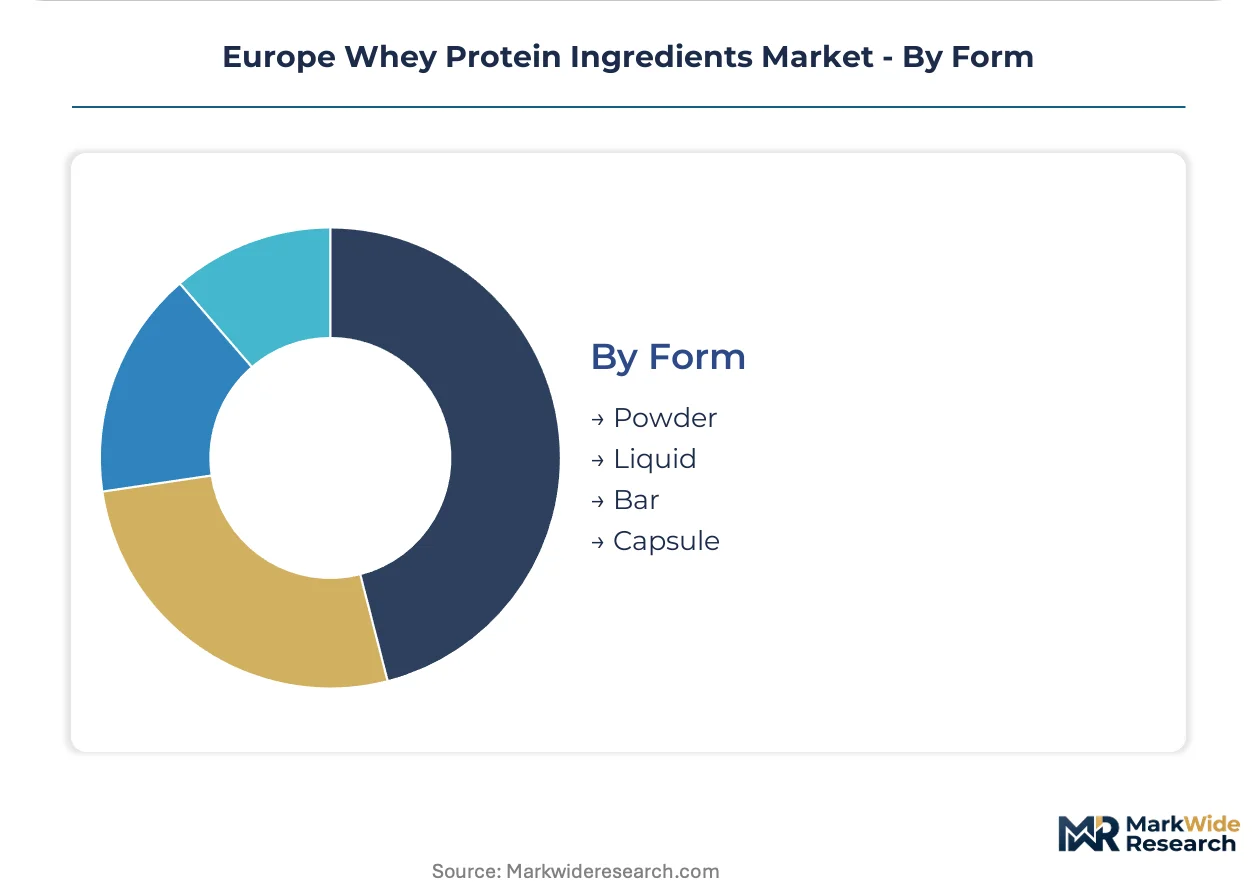
- Powder:Dominates bulk ingredient flows and direct-to-consumer canister formats. German and Dutch processors are reconfiguring filling lines for modular portion sachets alongside traditional bulk packaging.
- Liquid:Ready-to-drink applications in sports nutrition and clinical segments demand aseptic processing capabilities and extended shelf-life stabilization.
- Bar:Protein fortification in confectionery and snack formats requires whey fractions with controlled water activity and texture modification properties.
- Capsule:Encapsulated delivery for precise dosing in clinical and specialized nutrition applications, limited volume relative to other formats.
Powder leads on scale; Bar leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy cooperative structures established across Northern Europe during the post-war decades created the processing infrastructure that now supplies whey protein fractions to formulation industries. Germany's functional food manufacturing corridor and the Netherlands' ingredient trading hubs emerged as demand centers, while Irish and Danish sites specialized in fractionation technology.
Germany
Sports nutrition contract manufacturers and clinical nutrition formulators absorb premium whey protein isolate volumes. EFSA health claim validation protocols constrain marketing communications for muscle maintenance benefits. The manufacturing corridor spanning Bavaria and North Rhine-Westphalia hosts reformulation facilities serving bakery and beverage protein fortification.
Netherlands
Ingredient trading and distribution networks concentrate in Rotterdam and Amsterdam metropolitan areas. REACH chemical registration requirements reshape import compliance documentation for whey derivatives entering European customs territory. Dutch processors specialize in hydrolyzed whey fractions for infant formula applications.
Ireland
Membrane filtration investments at Irish processing sites expand whey protein isolate capacity for premium specification tiers. Energy price volatility compresses margins on standard concentrate grades. The southwest dairy processing cluster anchors specialized whey fractionation capabilities serving sports nutrition brands.
France
Bakery and beverage manufacturers integrate whey concentrates for cost-efficient protein fortification in mainstream retail products. The EU Green Deal's Farm to Fork Strategy tightens sustainability criteria for dairy-derived ingredients. The Brittany and Normandy dairy belts supply raw whey streams to fractionation facilities.
Denmark
Cooperative dairy structures sustain captive whey streams across Northern European supply networks. Carbon-efficient processing infrastructure investments accelerate under EU Green Deal mandates. Danish sites specialize in native whey protein cold-filtration for organic and clean-label sports nutrition channels.
Europe Whey Protein Ingredients Market Competitive Landscape
The competitive structure tilts toward cooperative-backed dairy processors with captive raw material access. Tiered concentration separates fractionation specialists from commodity whey traders, with membrane filtration capabilities determining premium positioning. Strategic archetypes include cooperative-integrated processors, independent fractionation specialists, and diversified nutrition ingredient platforms. Dominant competitive moves center on direct-to-consumer channel compression and sustainability certification investments.
Among cooperative-integrated processors, Arla Foods amba exemplifies the archetype leveraging Danish dairy cooperative structures to sustain captive whey streams. Glanbia plc occupies a position representing specialized whey fractionation capabilities at Irish processing sites. Carbery Group anchors the independent specialist tier, competing on whey protein isolate purity grades tailored to sports nutrition contract manufacturers.
| Leading Market Players |
|---|
| Arla Foods amba |
| Glanbia plc |
| Carbery Group |
| Agrial S.A. |
| Groupe Lactalis S.A. |
| Koninklijke FrieslandCampina N.V. |
| Lactoprot Deutschland GmbH |
| MEGGLE GmbH & Co. KG |
| Kerry Group |
| Others |
Supply & Pricing Matrix
Isolate-to-concentrate purity bifurcation separates German clinical nutrition buyers from French bakery reformulators, with membrane filtration intensity determining both unit economics and captive whey access across Irish and Danish processing clusters. This tier divergence concentrates pricing power with fractionation specialists while commodity concentrate margins compress under energy cost volatility.
Pricing Analysis
Three-tier pricing structure across premium isolate, standard concentrate, and economy-grade whey permeate levels governs European whey protein transactions. Protein purity thresholds and EFSA health claim substantiation status differentiate price bands, with clinical nutrition buyers showing lowest price sensitivity. Cost compression in standard concentrate tiers is intensifying because Danish cooperative processors face energy price spikes at membrane filtration sites. Sports nutrition contract manufacturers in Germany absorb premium isolate volumes with limited price resistance.
Supply Chain Analysis
Direct-to-manufacturer channels handle hyperscale demand from German functional food producers, bypassing traditional ingredient distributors. Supply concentrates in Ireland, Denmark, and Germany, with raw material flows drawing from Brittany and Normandy dairy belts. The supply chain rests on fresh milk availability, ceramic membrane filtration capacity, and REACH-registered hydrolyzed fractions. Single-source vulnerability emerges where Arla Foods amba and Glanbia plc control captive whey streams across Northern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe whey protein ingredients constitute a late-cycle quality story as clinical nutrition protocols and elite sports applications pivot demand toward EFSA-validated isolate specifications. Premium fractionation capabilities now determine sustainable margin capture.
For Market Incumbents: Anchor membrane filtration dominance through ceramic microfiltration capacity additions at Irish and Danish sites. Defend against emerging plant-dairy hybrid entrants by deepening carbon footprint documentation under EU Green Deal Farm to Fork mandates. Prioritize direct-to-consumer channel control in Berlin and Amsterdam metropolitan markets where same-day delivery expectations concentrate inventory positioning. For New Entrants and Emerging Players: Cold-filtration native whey technology offers entry leverage into German organic sports nutrition channels underserved by cheese-whey incumbents. Target white-space in Dutch hospital nutrition procurement where high-purity isolate specifications outstrip current fractionation capacity. Pursue go-to-market partnerships with Amsterdam health store chains demanding sustainability-certified native variants. For Investors and Strategic Acquirers: Consolidation pressure builds where independent fractionation specialists lack captive whey streams yet possess membrane filtration engineering depth. Frame long-term viability around clinical nutrition penetration rates as German aging demographics expand medical food volumes. Monitor EFSA health claim validation timelines as inflection signals for premium isolate demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Irish processing sites deploy ceramic systems to reduce energy consumption per kilogram of protein recovered. |
| Carbon Border Adjustment Compliance | Early documentation alignment positions European processors for export advantage into Asian clinical nutrition markets. |
| Direct-to-Consumer Channel Compression | Berlin and Amsterdam sports nutrition brands bypass distributors to contract directly with fractionation specialists. |
| Plant-Dairy Hybrid Formulation Development | Dutch premium retailers demand clean-label positioning combining whey with pea and oat protein bases. |
| EFSA Health Claim Validation Investment | Substantiation protocols for muscle maintenance benefits constrain marketing compliance costs for isolate marketers. |
Research Methodology
Coverage spans Northern European dairy processing corridors, with primary inputs from each major whey fractionation hub. The approach combines interviews with membrane filtration engineers, sports nutrition procurement directors, clinical nutrition formulators, and EFSA regulatory consultants with secondary validation from customs trade data, dairy cooperative processing reports, and REACH registration filings. Bottom-up volume triangulation across isolate, concentrate, and hydrolyzed grade tiers reconciles with top-down value estimates derived from contract manufacturing disclosures.
Rate-of-change decomposition separates volume drivers from price evolution across the projection horizon. Segmentation dimensions modeled include protein purity tier, application end-use, and delivery format, with cross-cutting analysis of EFSA health claim validation status. CAGRs emerge from historical processing capacity expansion patterns and documented contract renewal cycles at German sports nutrition manufacturers. Forecast inputs incorporate membrane filtration technology adoption curves and EU Green Deal carbon accounting implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to fresh milk supply fluctuations and ECHA microplastics packaging restrictions. Periodic stress-testing of base assumptions is recommended, particularly regarding energy price volatility at Irish and Danish processing sites and the pace of plant-protein substitution in Dutch retail channels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Egg White Powder Market
Ingredients
Oat Grass Powder Market
Ingredients
Asia-Pacific Agar Market
Ingredients
Arrowroot Starch Market
Ingredients
Algae-Based Ingredients Market
Ingredients
North America Feed Yeast Market
Ingredients
Europe Dairy Ingredients Market
Ingredients
Farnesene Market
Ingredients
Milk Ingredients Market
Ingredients
Fig Ingredient Market
Ingredients
Brazil Starch Derivatives Market
Ingredients
Virgin Coconut Oil Market
Ingredients
Sodium Caseinate Market
Ingredients
Tapioca Market
Ingredients
Plant Based Premix Market
Ingredients
Asia-Pacific Soy Protein Concentrate Market