
 North America Perfume Market | 2026-2036
North America Perfume Market Size, Share, and Industry Trends Forecast 2026-2036
North America Perfume Market Intelligence
Younger fragrance enthusiasts is collapsing the historical dominance of department-store-dependent mature buyers across North America. Coty Inc leverages social-native marketing and celebrity licensing partnerships to capture digitally native consumers. The Estee Lauder Companies anchors premium fragrance portfolios through heritage brand equity and selective retail distribution. Chanel sustains ultra-luxury positioning via controlled scarcity and exclusive boutique channels.
Perfume comprises concentrated aromatic compounds dissolved in ethanol or oil bases, typically containing 15-40% fragrance oil by volume, designed for personal scent application and identity expression. Eau de Parfum and Eau de Toilette lead volume sales due to accessible price-to-concentration ratios, while perfume oils represent the fastest-growing sub-segment driven by clean-beauty positioning and alcohol-free formulation preferences. Online Retail and Specialty Stores now command the most dynamic margin pools as direct-to-consumer brands bypass legacy wholesale markups.
The US FDA enforces cosmetic labeling standards including fragrance allergen disclosure, while Health Canada and PMRA oversee parallel safety requirements affecting cross-border product harmonization. California's Proposition 65 and Safer Consumer Products regulations impose additional chemical disclosure burdens that filter formulation choices for brands operating across North American jurisdictions. Stakeholders must monitor evolving state-level chemical restriction trajectories and their cascading effects on supply chain compliance costs.
Market Dynamics
Social commerce infrastructure is collapsing the historical department-store gatekeeper model for fragrance discovery across North America. TikTok and Instagram Shop algorithms now surface niche and celebrity-backed scents directly to Gen Z and millennial buyers, bypassing legacy wholesale relationships and reshaping brand launch economics.
Growth Catalysts
- Fair Packaging and Labeling Act amendments:FDA-mandated fragrance allergen disclosure is accelerating clean-formulation R&D investments. Brands reformulating for transparency capture premium shelf positioning.
- Alcohol-free perfume oils:Sensitive-skin consumers and wellness-oriented buyers drive double-digit volume expansion in oil-based formats. This chemistry shift opens formulation partnerships with skincare laboratories.
- Texas urban corridor:Dallas-Fort Worth and Houston beauty retail density now matches coastal incubation rates. Direct-to-consumer brands establish secondary headquarters to access lower operational costs and growing Hispanic consumer segments.
Market Restraints
- Ethanol supply concentration:US Gulf Coast biofuel policy fluctuations squeeze cosmetic-grade alcohol availability. Fragrance houses face input cost volatility from competing fuel mandates.
- California Proposition 65:Chemical disclosure burdens force reformulation of legacy scents containing flagged compounds. Compliance costs disproportionately burden small and mid-size brands.
- Synthetic musk substitution limits:Natural alternatives lack olfactory stability at commercial scale. Clean-beauty positioning conflicts with performance requirements in fine fragrance.
Strategic Opportunities
- Quebec and Ontario underserved premium segments:Health Canada regulatory alignment with FDA standards enables US brand expansion with minimal reformulation. Francophone marketing localization remains underexploited.
- AI-powered scent personalization:Machine learning models matching consumer preference data to molecular profiles enable mass-customization at scale. Subscription models lock in recurring revenue.
- Livestream commerce integration:Real-time influencer demonstrations with instant purchase functionality collapse the consideration-to-transaction funnel. Early adopters capture impulse-driven trial rates.
Industry Challenges
- Fragrance chemist talent scarcity:Specialized formulation expertise concentrates at legacy houses. New entrants compete for limited perfumery school graduates.
- Cross-border inventory harmonization:Divergent state-level chemical restrictions complicate unified North American supply chains. SKUs fragment by jurisdiction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Perfume Market |
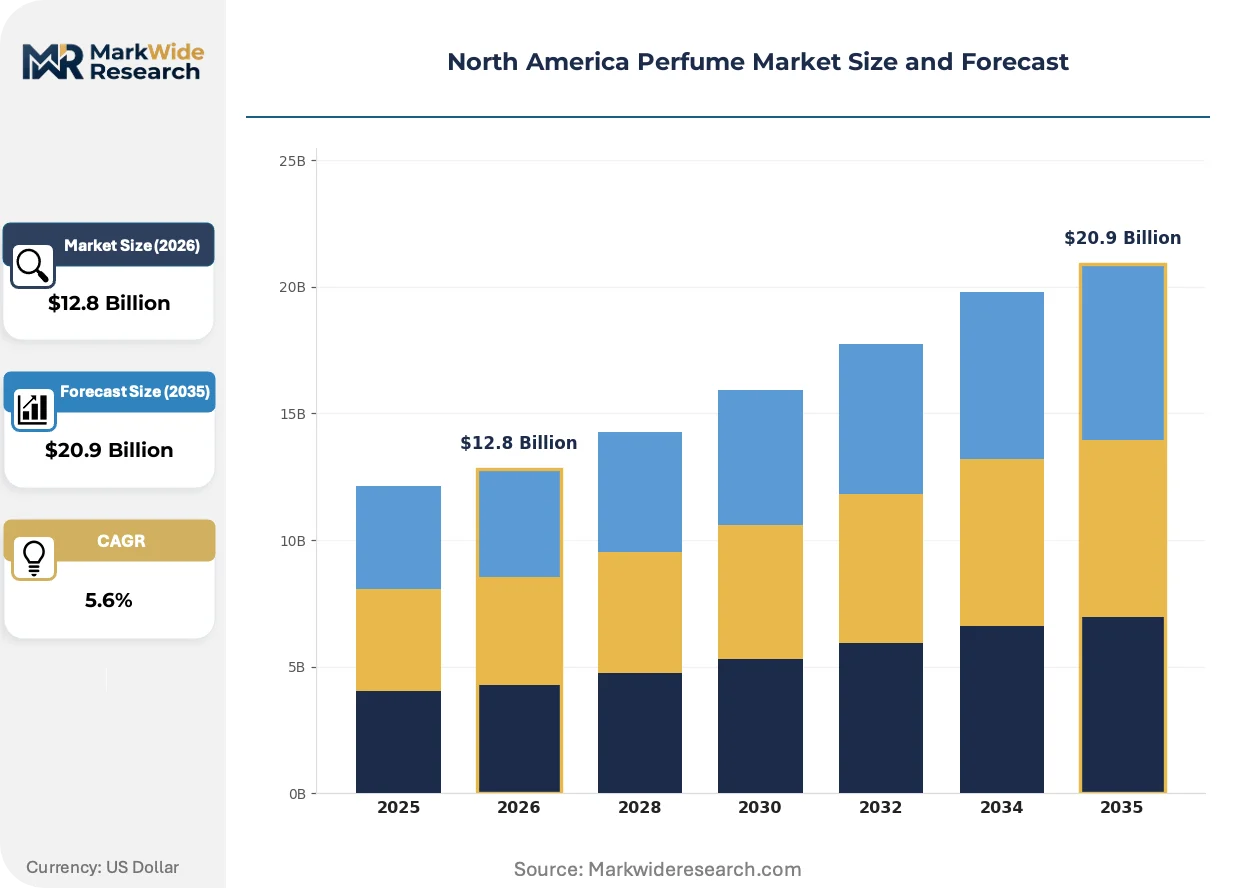
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $20.9 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eau de Parfum, Eau de Toilette, Eau de Cologne, Perfume Oils Fragrance Notes: Citrus, Floral, Woody, Spicy Packaging Type: Spray Bottles, Roll-ons, Gift Sets, Solid Perfumes Distribution Channel: Online Retail, Department Stores, Specialty Stores, Duty-free Shops |
| Companies Covered | LVMH, Revlon, The Estee Lauder Companies, Procter & Gamble, Elizabeth Arden, L'Oreal, Chanel, Shiseido Company, Coty Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Perfume Market Strategic Shifts & Innovations
Biotechnology-derived fragrance molecules and algorithmic consumer targeting are converging to compress traditional development cycles. This shift enables rapid-response launches tied to viral social moments rather than seasonal calendar planning.
Precision fermentation for rare natural isolates is displacing plantation-sourced ingredients in prestige formulations. Niche fragrance houses adopt lab-grown oud and sandalwood to bypass sustainability scrutiny and supply inconsistency. This biotechnology pivot is displacing traditional raw material procurement relationships that dominated fine fragrance for decades.
Health Canada's alignment with FDA allergen disclosure timelines is forcing simultaneous reformulation across North American product lines. Brands must consolidate ingredient lists to satisfy both jurisdictions without maintaining separate SKUs. California's Safer Consumer Products program adds a third compliance layer, pushing multinationals toward preemptive global formula simplification.
Discovery-driven purchasing via short-form video platforms is fragmenting brand loyalty structures. Consumers sample multiple scents monthly through decant subscriptions and travel sizes before committing to full bottles. This behavior concentrates in California and New York, where algorithmic content density and same-day delivery infrastructure enable impulse replenishment cycles.
North America Perfume Market Segmentation
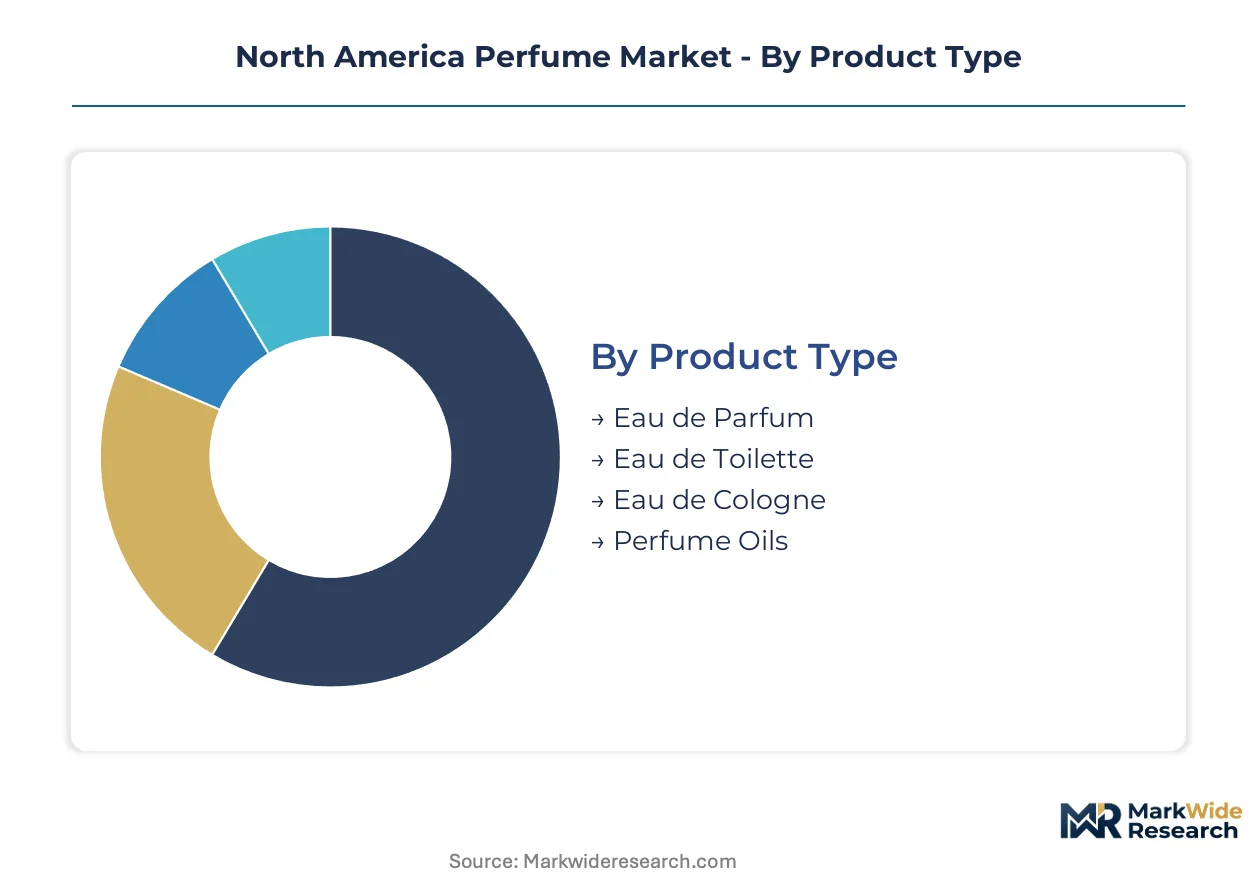
Perfume segmentation in North America tracks divergent consumer rituals across California's influencer-driven discovery corridors and Texas's expanding Hispanic retail corridors. Each dimension reveals distinct margin architectures and regulatory exposure profiles that shape brand portfolio construction.
Product Type:
Domestic consumption concentrates in alcohol-based formats, while perfume oils gain traction through cross-border wellness commerce from Canadian clean-beauty incubators.
- Eau de Parfum:These formulations carry 15-20% fragrance oil concentration in ethanol bases, balancing longevity with wearability. California and New York buyers drive volume through Sephora and Ulta flagship locations, though FDA allergen labeling requirements now force reformulation of legacy compounds.
- Perfume Oils:Alcohol-free formulations with 20-30% pure fragrance concentration appeal to sensitive-skin demographics. Texas and Florida consumers expand this segment fastest through direct-to-subscription models that bypass traditional retail markups entirely.
- Eau de Toilette:Lighter 5-15% concentration formats dominate mass-market shelf space at Walmart and Target.
- Eau de Cologne:Traditional 2-5% concentration citrus-forward compositions retain loyalty among older male demographics in the US Northeast.
Eau de Parfum commands the established base. The steepest expansion runs through Perfume Oils.
Fragrance Notes:
Cost tier stratification separates premium niche positioning from mass-market accessibility, with raw material sourcing geography determining margin pressure.
- Floral:Rose, jasmine, and peony accords rely on plantation-sourced absolutes and increasingly on biotechnology-derived equivalents. California's clean-beauty retailers favor lab-grown alternatives to bypass sustainability scrutiny.
- Woody:Sandalwood, cedar, and oud bases face supply volatility from Indian and Southeast Asian export restrictions. Texas and Arizona consumers show highest willingness-to-pay for precision-fermented sandalwood substitutes.
- Citrus:Bergamot, lemon, and grapefruit top notes dominate summer seasonal launches.
- Spicy:Cinnamon, cardamom, and pepper heart notes anchor fall and holiday collections.
Floral notes anchor mass-market revenue. Woody compositions climb the fastest as biotechnology displaces traditional extraction.
Packaging Type:
Application context dictates format selection, with portability requirements fragmenting design specifications across commuter corridors and travel retail.
- Spray Bottles:Standard atomizer formats with 30-100ml capacity dominate full-bottle purchases. New York and Los Angeles urban density supports premium glass packaging with refill programs that reduce per-unit material costs.
- Gift Sets:Curated multi-piece collections with travel sizes and body products capture holiday purchasing concentrated in US Midwest department stores.
- Roll-ons:10ml rollerball formats suit handbag portability and trial conversion.
- Solid Perfumes:Wax-based alcohol-free formats appeal to TSA-conscious business travelers.
Spray bottles command the established base. Gift sets gain share fastest through seasonal bundling strategies.
Distribution Channel:
Customer acquisition cost structures separate high-touch experiential retail from algorithmic discovery platforms, with margin retention varying dramatically by channel control.
- Online Retail:Direct-to-consumer platforms and marketplace listings capture full margin without wholesale dilution. TikTok Shop and Instagram Checkout enable same-day fulfillment in California, New York, and Texas metro corridors.
- Specialty Stores:Sephora, Ulta, and independent perfumeries provide sampling infrastructure and education. These locations concentrate in urban beauty retail clusters where consumer lifetime value justifies rent premiums.
- Department Stores:Macy's and Nordstrom fragrance halls retain older demographic loyalty through counter service.
- Duty-free Shops:Airport retail captures impulse purchasing from international travelers at JFK, LAX, and Toronto Pearson.
Department stores command the established base. Online retail expands most quickly through social commerce integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian fragrance exports flow primarily into United States retail corridors, while Mexican manufacturing clusters supply glass packaging and alcohol bases northward. This tri-national trade pattern concentrates value capture in coastal metropolitan zones.
United States
California and New York drive premium fragrance velocity through Sephora and Ulta flagship density. FDA allergen disclosure mandates under the Fair Packaging and Labeling Act force simultaneous reformulation across domestic product lines. Los Angeles and Manhattan incubate direct-to-consumer brands that bypass wholesale markups through TikTok Shop integration.
Canada
Quebec and Ontario present underserved premium segments where Health Canada regulatory alignment enables US brand expansion with minimal adaptation. Toronto's Queen Street West corridor hosts emerging clean-beauty incubators specializing in alcohol-free perfume oils. Vancouver's Asian diaspora communities accelerate demand for niche Eastern fragrance profiles.
Mexico
Mexico City and Monterrey anchor glass bottle manufacturing and cosmetic-grade ethanol distillation serving US brand supply chains. The country's national consumer protection regulator enforces labeling standards that converge with FDA frameworks. Guadalajara's industrial corridor expands fragrance compound blending capacity for North American contract manufacturing.
North America Perfume Market Key Industry Players
Player mix skews toward diversified beauty conglomerates with fragrance as a portfolio pillar rather than pure-play specialists. Market structure exhibits tiered concentration: three holding companies control heritage luxury houses, while independent niche labels fragment the premium tier. Strategic archetypes include celebrity-licensing operators, biotechnology-forward clean formulators, and controlled-distribution ultra-luxury guardians. Competitive moves center on social-native acquisition channels and precision-fermentation supply partnerships.
Within the diversified conglomerate tier, LVMH and The Estee Lauder Companies exemplify scale-driven portfolio breadth across price segments. Coty Inc occupies a position as the archetypal celebrity-licensing specialist with social-commerce-native marketing infrastructure. Chanel represents controlled-scarcity ultra-luxury positioning through exclusive boutique channel discipline.
| Leading Market Players |
|---|
| LVMH |
| Revlon |
| The Estee Lauder Companies |
| Procter & Gamble |
| Elizabeth Arden |
| L'Oreal |
| Chanel |
| Shiseido Company |
| Coty Inc |
| Others |
Cost & Logistics Intelligence
FDA allergen disclosure mandates under the Fair Packaging and Labeling Act simultaneously gate supply qualification for fragrance houses and enable price differentiation through clean-formulation certification. This regulatory convergence concentrates margin capture among brands that absorb reformulation costs while fragmenting price tiers across compliance-capable and legacy-dependent competitors.
Pricing Analysis
Concentration-tier pricing gaps separate legacy alcohol-based formulations from emerging alcohol-free perfume oils and precision-fermented biotechnology alternatives. Three-tier pricing structure across prestige niche, accessible premium, and mass-market economy levels tracks raw material sourcing geography and certification status. Price differentiation hinges on biotechnology-derived ingredient premiums and California Proposition 65 compliance costs. Pricing pressure stems from ethanol supply volatility tied to US Gulf Coast biofuel policy fluctuations. Mass-market buyers at Walmart and Target exhibit highest price sensitivity, while prestige consumers in Sephora flagship corridors absorb biotechnology premiums with minimal elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate fragrance house operations for volatile natural absolutes, while strategic stockpiling of synthetic musk alternatives buffers against clean-beauty substitution limits. Supply concentrates in France for heritage fragrance compounds, India for jasmine and rose absolutes, and the United States for cosmetic-grade ethanol distillation. Raw material dependencies span plantation-sourced sandalwood, precision-fermented oud substitutes, and petroleum-derived aroma chemicals. Single-source vulnerability runs through Indian and Southeast Asian export restrictions on endangered wood species. Distribution runs through direct-to-consumer platforms bypassing wholesale markups, with secondary fulfillment nodes in Texas reducing last-mile costs for Hispanic consumer corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized fragrance chemist expertise concentrates at legacy houses, creating acquisition premiums for formulation talent and constraining rapid scale-up for clean-beauty positioning. This capability scarcity rewards early investment in biotechnology partnerships and perfumery school pipeline development.
For Market Incumbents: Shield heritage portfolio margins by accelerating backward integration into precision-fermentation supply partnerships before biotechnology feedstock costs escalate. Consolidate position through selective acquisition of niche clean-beauty labels that have already absorbed California Proposition 65 reformulation costs. Channel control through exclusive Sephora and Ulta flagship positioning remains critical as TikTok Shop democratizes discovery.
For New Entrants and Emerging Players: Anchor in Quebec and Ontario's underserved premium segments where Health Canada regulatory alignment minimizes adaptation costs for US-formulated products. Francophone marketing localization represents underexploited white space against English-dominant incumbent campaigns. Direct-to-subscription models targeting Texas and Florida's Hispanic wellness consumers bypass retail markup structures entirely.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified beauty conglomerates seeking to divest non-core fragrance assets amid portfolio rationalization pressures. Long-term viability favors brands with captive biotechnology supply agreements and social-native customer acquisition infrastructure. The signal to watch is FDA enforcement intensity on allergen disclosure timelines, which will accelerate consolidation among reformulation-lagged mid-tier players.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Supply Partnership | Precision-fermentation agreements with Ginkgo Bioworks or Amyris displace plantation-sourced oud and sandalwood. |
| Direct-to-Consumer Platform Launch | TikTok Shop integration captures Gen Z discovery moments without Sephora wholesale margin dilution. |
| Clean-Beauty Certification Investment | California Safer Consumer Products pre-compliance opens premium shelf positioning before mandatory deadlines. |
| Francophone Marketing Localization | Quebec-targeted campaigns exploit underpenetrated premium segments against English-default competitors. |
| Alcohol-Free Formulation R&D | Perfume oil development targets sensitive-skin demographics and wellness-oriented subscription buyers. |
Research Approach
Desk research of customs trade databases, FDA cosmetic registration filings, and Health Canada product notification records preceded structured interviews with fragrance house R&D directors, Sephora category buyers, biotechnology supply specialists, and direct-to-consumer brand founders. Primary fieldwork across California, New York, and Texas beauty retail corridors validated algorithmic consumer targeting claims and social commerce infrastructure maturity. Secondary sources included Circana retail audit data, state-level chemical restriction filings, and perfumery school graduate placement records. Bottom-up volume modeling triangulated against top-down category spend estimates from beauty conglomerate segment disclosures.
Variance decomposition across product type, fragrance note category, packaging format, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators and demographic cohort expansion patterns. Biotechnology adoption curves and social commerce penetration rates served as industry-specific forecast inputs alongside regulatory compliance cost trajectories.
Material uncertainties — FDA enforcement timing on allergen disclosure, US Gulf Coast biofuel policy shifts, and Indian sandalwood export restriction escalations — sit outside the modeled envelope. Forecasts reflect assumptions on consumer willingness-to-pay for clean-beauty certification and biotechnology ingredient premiums. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
GCC Perfume Market
Fragrances & Perfumes
Middle East Fragrances Market
Fragrances & Perfumes
Digital Perfume Market
Fragrances & Perfumes
Wax Melts Market
Fragrances & Perfumes
Mini Refillable Perfume Bottles Market
Fragrances & Perfumes
Saudi Arabia Perfume Market
Fragrances & Perfumes
Perfume Vials Market
Fragrances & Perfumes
Home Fragrance Diffusers Market
Fragrances & Perfumes
Digital Fragrance Market
Fragrances & Perfumes
Global Fragrances and Perfumes Market
Fragrances & Perfumes
Natural Fragrance Market
Fragrances & Perfumes
Cosmetic and Fragrance Retail Chain Market
Fragrances & Perfumes
Clean Perfume Market
Fragrances & Perfumes
Global Scented Candle Market
Fragrances & Perfumes
Fragrance Oil Market
Fragrances & Perfumes
Fragrance Emulsion Market