
 Floral Water Spray Market | 2026-2036
Floral Water Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Floral Water Spray Market Foresight
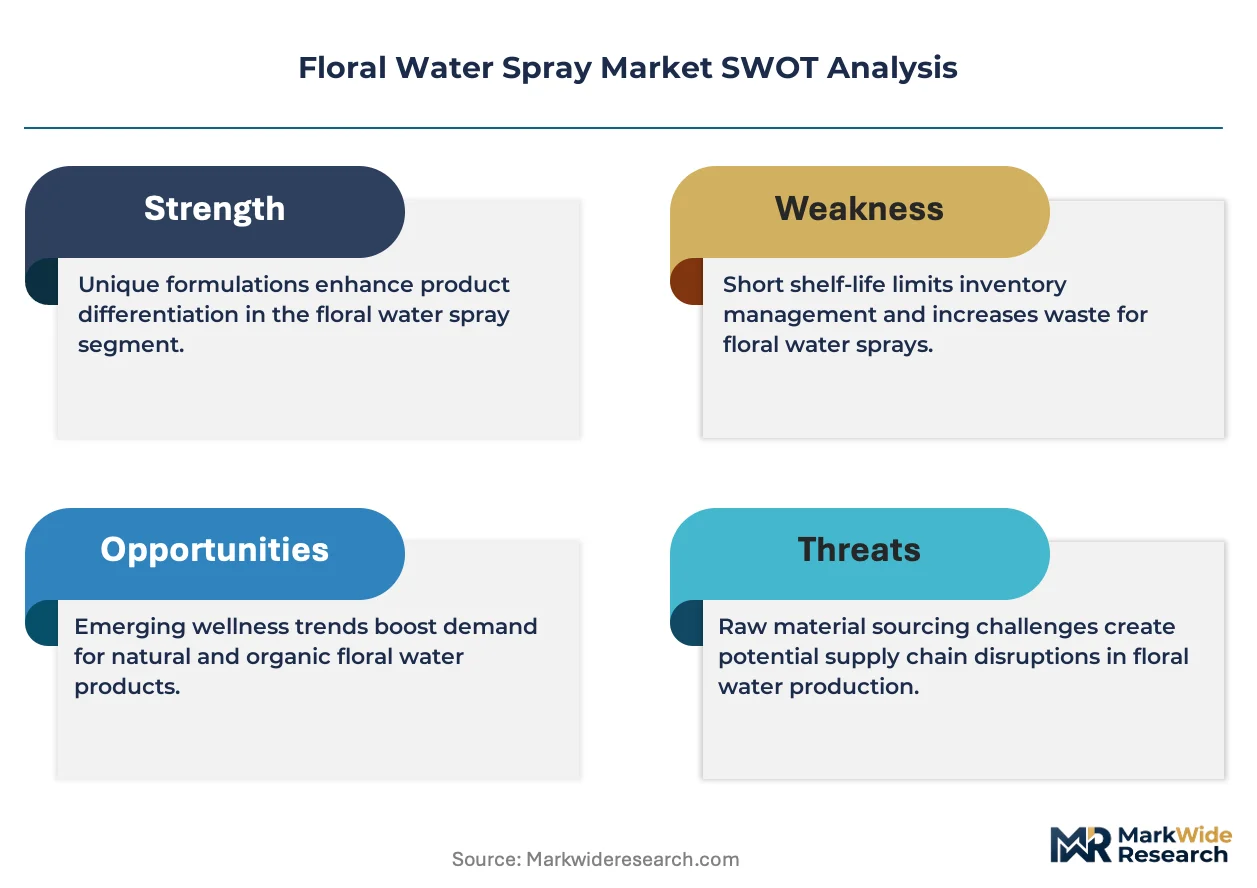
REACH is repositioning the cost-of-entry calculus for European floral water suppliers by mandating full substance registration and safety documentation for hydrosol imports. Melvita leverages its Provence-based distillation heritage to sustain premium positioning in certified organic segments. LiuShen anchors its competitive stance through deep control of herbal extraction supply chains in eastern China. RunBen competes aggressively on price in mass-market baby care applications where mild formulation claims drive purchase decisions.
Floral water spray denotes aqueous distillates produced through steam distillation of fresh flowers, typically containing 0.02-0.05% essential oil microdroplets and organic acids in solution, serving primarily as functional ingredients in cosmetic formulations and therapeutic topical applications. Rose water dominates volume throughput due to its ubiquity in Middle Eastern and South Asian cosmetic traditions, while lavender water captures accelerating demand from aromatherapy practitioners seeking standardized linalool content. Skincare applications command the deepest margin pools as dermatology clinics and prestige beauty brands specify pharmaceutical-grade hydrosol purity.
FDA oversight of cosmetic labeling in the United States and ECHA enforcement of REACH substance restrictions in Europe collectively elevate compliance burdens for cross-border hydrosol trade. China's SAMR implements national food-grade and cosmetic-grade standards that bifurcate domestic production into separate quality tiers with divergent pricing. Stakeholders must monitor regulatory divergence between cosmetic and therapeutic classification regimes to anticipate which distribution channels face expanded documentation requirements.
Market Dynamics
REACH substance registration requirements are restructuring European hydrosol trade economics, forcing importers to absorb full safety documentation costs or exit the market entirely. Cold-press distillation capacity expansion in eastern China is simultaneously compressing global pricing benchmarks for rose and lavender water grades.
Growth Catalysts
- Pharmaceutical-grade purity specifications:Dermatology clinics in Germany and France now mandate certified organic hydrosol chains for topical therapeutic formulations, pulling supply toward GMP-compliant distillers.
- India:Ayurvedic cosmetic manufacturers are integrating traditional floral waters into export-oriented skincare lines, creating certified organic demand corridors into Middle Eastern retail channels.
- SAMR cosmetic-grade standards:China's bifurcated quality tiers are professionalizing domestic production, enabling premium hydrosol brands to command price separation from food-grade alternatives.
Market Restraints
- Input cost volatility:Damask rose harvest yields in Bulgaria and Turkey fluctuate with frost patterns, destabilizing raw material pricing for distillers dependent on specific cultivar sourcing.
- Supply concentration risk:Provence-based organic distillers control limited certified lavender water volumes, creating bottleneck vulnerability for brands requiring French origin claims.
- Substitution threat:Synthetic fragrance compounds and deionized water with added essential oils undercut authentic hydrosol positioning in mass-market personal care formulations.
Strategic Opportunities
- Brazil:ANVISA's expanding natural cosmetic registration pathways create regulatory tailwinds for hydrosol-based therapeutic claims in Latin America's largest beauty market.
- Direct-to-practitioner channels:Aromatherapy certification programs in Australia and Canada are building institutional procurement relationships that bypass traditional cosmetic distribution markups.
- Convergence of blockchain traceability and organic certification:Distillers implementing batch-level provenance tracking capture premium positioning with sustainability-verified buyers in Nordic markets.
Industry Challenges
- REACH compliance timeline compression:Hydrosol importers face accelerated substance registration deadlines without grandfathering provisions for existing botanical distillate portfolios.
- Cross-functional formulation expertise:Cosmetic brands require staff conversant in both traditional distillation chemistry and modern clean-label marketing claims, creating talent scarcity in product development roles.
- Cold-chain integrity:Temperature-sensitive hydrosol shipments demand refrigerated logistics investment that smaller regional distillers struggle to finance for intercontinental routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floral Water Spray Market |
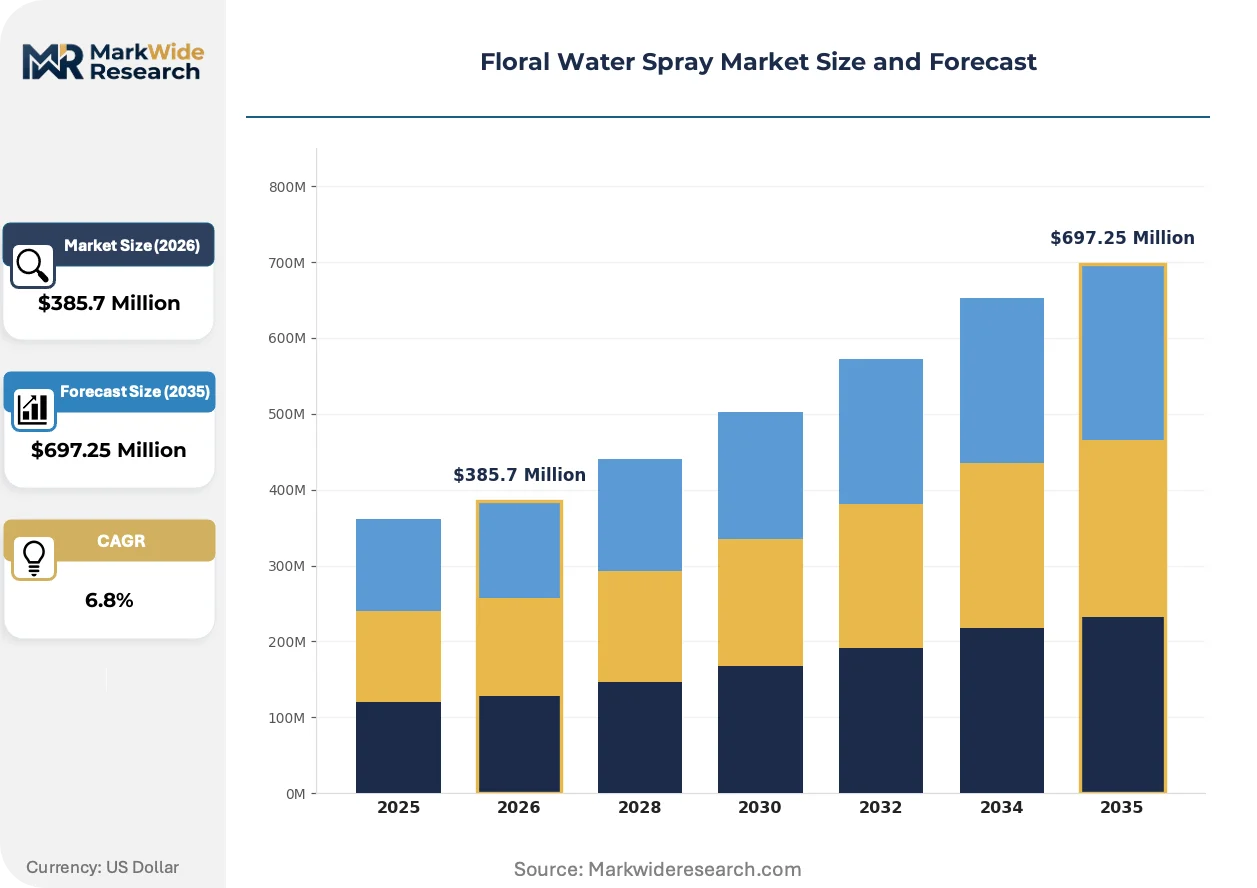
| Market Size in 2026 | $385.7 Million |
| Market Size in 2035 | $697.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rose Water, Lavender Water, Jasmine Water, Orange Blossom Water, Chamomile Water Application: Skincare, Haircare, Aromatherapy, Cosmetic Formulation, Therapeutic Treatments End User: Beauty Salons, Spas, Dermatology Clinics, Personal Consumers, Wellness Centers Distribution Channel: Online Stores, Specialty Retailers, Pharmacies, Supermarkets, Direct Sales |
| Companies Covered | OFF, YuMeiJing, Melvita, LongHu, Elsker, LiuShen, BaoBaoJinShu, RunBen, LongLiQi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floral Water Spray Market Shifts & Advancements
Steam distillation is yielding to advanced extraction methods that preserve volatile aromatic compounds previously lost to thermal degradation. Formulators and procurement teams are recalibrating supplier qualification criteria around these technical capabilities.
Supercritical CO2 extraction paired with membrane filtration is electrifying premium hydrosol production by capturing heat-sensitive floral compounds that conventional steam methods destroy. Prestige skincare brands in South Korea and Japan are adopting these systems to differentiate sensorial profiles. The technology is compressing acceptable purity thresholds across pharmaceutical-grade supply tiers.
REACH Annex XVII restrictions on allergen labeling are forcing reformulation of lavender water products destined for European sensitive-skin segments. ECHA enforcement is tightening documentation requirements for linalool content declarations in cosmetic applications. German and French brands are responding by specifying distilled rather than reconstituted hydrosol grades to satisfy safety assessor scrutiny.
Certification-driven purchasing is fragmenting procurement authority within cosmetic houses, with sustainability officers now vetoing suppliers lacking organic or fair-trade credentials. Traditional fragrance buyers are losing sole control over hydrosol sourcing decisions. This behavioral shift is most pronounced in Nordic markets where retailer sustainability scorecards determine shelf placement eligibility.
Floral Water Spray Market Segmentation
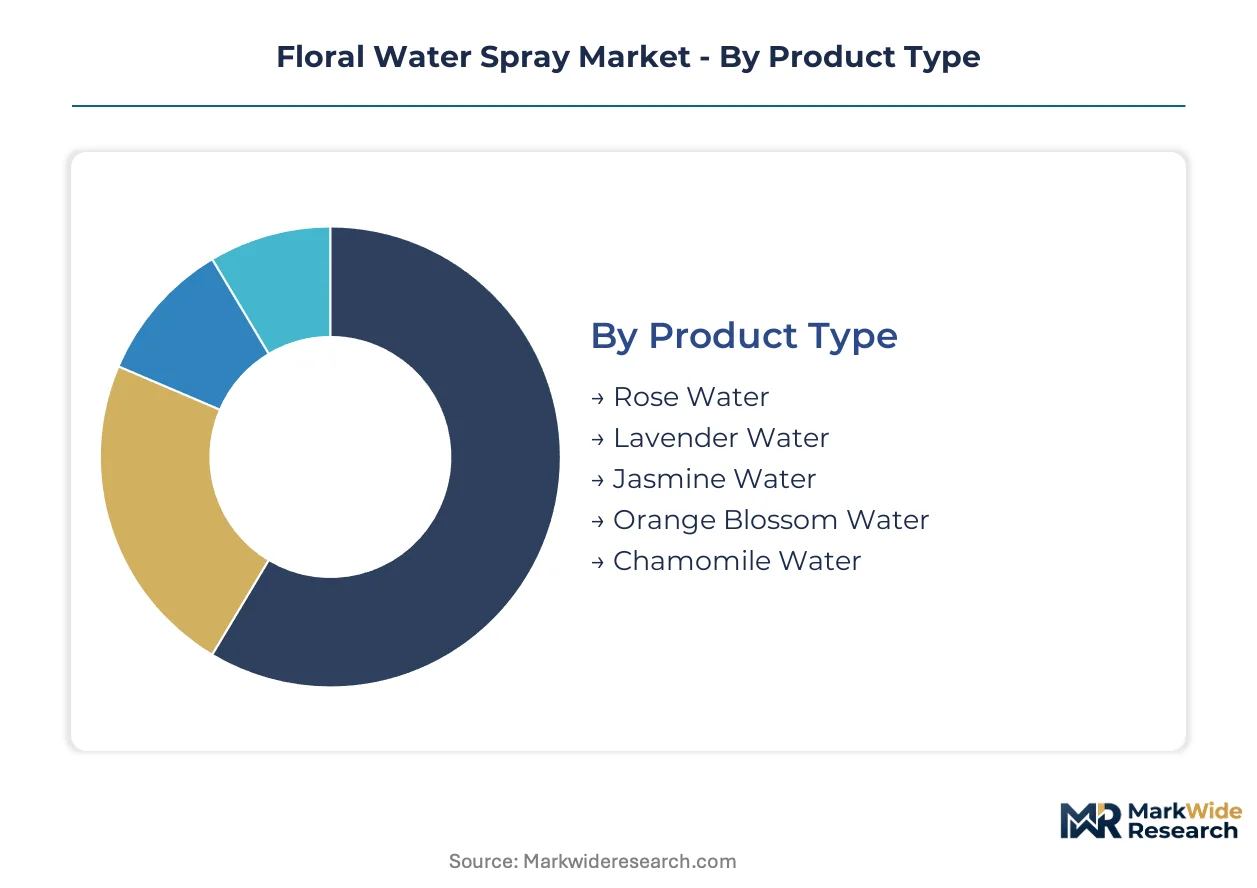
Floral water spray procurement decisions pivot on certification grade, extraction method, and end-use regulatory classification. Distillers and formulators calibrate supply strategies across four intersecting dimensions that determine pricing power and channel access.
Product Type:
Steam distillation yields and volatile compound retention define the technical hierarchy across botanical sources.
- Rose Water:Aqueous distillate of Rosa damascena containing 0.02-0.05% essential oil microdroplets and phenylethyl alcohol. Bulgarian and Turkish harvest volumes command pricing leverage in Middle Eastern cosmetic formulations where traditional preparation methods retain cultural authority.
- Lavender Water:Hydrosol standardized for linalool content between 0.1-0.3% by weight. German and French aromatherapy practitioners specify Provence-origin certification for therapeutic-grade procurement, creating supply bottlenecks during seasonal harvest windows.
- Jasmine Water:Night-blooming Jasminum sambac distillate requiring solvent-free extraction protocols. Indian Ayurvedic exporters integrate the hydrosol into certified organic skincare lines targeting Gulf retail channels.
- Orange Blossom Water:Citrus aurantium amara distillate with neroli trace compounds. North African producers dominate food-grade supply tiers while cosmetic-grade batches command triple pricing in French fragrance houses.
- Chamomile Water:Matricaria recutita hydrosol valued for bisabolol content in sensitive-skin segments. German dermatology clinics specify organic-certified chains for topical therapeutic applications.
Rose water leads on scale; lavender water leads on momentum.
Application:
Regulatory classification boundaries separate cosmetic, therapeutic, and food-grade demand pools with divergent documentation burdens.
- Skincare:Pharmaceutical-grade hydrosol purity specifications now mandatory for German and French dermatology clinic procurement. Prestige beauty brands specify GMP-compliant distillation chains, compressing supplier qualification timelines.
- Cosmetic Formulation:Clean-label marketing claims drive hydrosol substitution for synthetic fragrance compounds. South Korean formulators adopt supercritical CO2 extraction outputs to differentiate sensorial profiles in premium tiers.
- Aromatherapy:Standardized linalool and linalyl acetate content declarations required under REACH Annex XVII. Australian and Canadian certification programs build institutional procurement relationships bypassing traditional distribution markups.
- Haircare:Mild formulation claims in mass-market baby care segments where RunBen competes aggressively on price. pH-balanced hydrosol blends replace synthetic conditioners in professional salon applications.
- Therapeutic Treatments:Topical wound care and anti-inflammatory protocols in European spa medicine. ANVISA's expanding natural cosmetic registration pathways in Brazil create regulatory tailwinds for hydrosol-based therapeutic claims.
Skincare commands margin concentration; cosmetic formulation is climbing the fastest.
End User:
Institutional procurement volumes contrast with fragmented personal consumer demand across certification-sensitivity tiers.
- Dermatology Clinics:German and French facilities mandate certified organic hydrosol chains with full substance registration documentation. GMP compliance filters out regional distillers lacking quality management infrastructure.
- Beauty Salons:Professional-grade bulk procurement concentrates in Middle Eastern and South Asian metropolitan markets. Traditional preparation methods influence supplier selection in heritage-conscious segments.
- Spas:Wellness tourism destinations in Thailand and Indonesia specify traceable provenance for sustainability marketing. Blockchain batch-level tracking captures premium positioning with Nordic sustainability-verified buyers.
- Wellness Centers:Ayurvedic and traditional Chinese medicine integration drives hydrosol demand in India and China. SAMR cosmetic-grade standards professionalize domestic production quality tiers.
- Personal Consumers:E-commerce direct-to-consumer channels fragment across price-sensitive and certification-driven segments. Social media education elevates organic and fair-trade credential awareness in urban demographics.
Dermatology clinics lead on specification rigor; spas lead on sourcing innovation.
Distribution Channel:
Cold-chain integrity requirements and regulatory documentation burdens stratify channel economics.
- Specialty Retailers:Curated organic and natural beauty assortments in France, Germany, and Nordic markets. Retailer sustainability scorecards determine shelf placement eligibility for hydrosol brands.
- Pharmacies:OTC therapeutic positioning requires national pharmaceutical regulator approval in each jurisdiction. Documentation burdens favor established distillers with regulatory affairs capacity.
- Online Stores:Direct-to-consumer growth concentrates in urban China and Southeast Asian markets. Temperature-controlled logistics investment separates scalable operators from regional players.
- Supermarkets:Mass-market personal care formulations where synthetic fragrance compounds undercut authentic hydrosol positioning. Price competition compresses margins for commodity-grade distillates.
- Direct Sales:Aromatherapy practitioner networks in Australia and Canada build institutional procurement relationships. Certification program affiliations validate product quality claims without third-party retail markup.
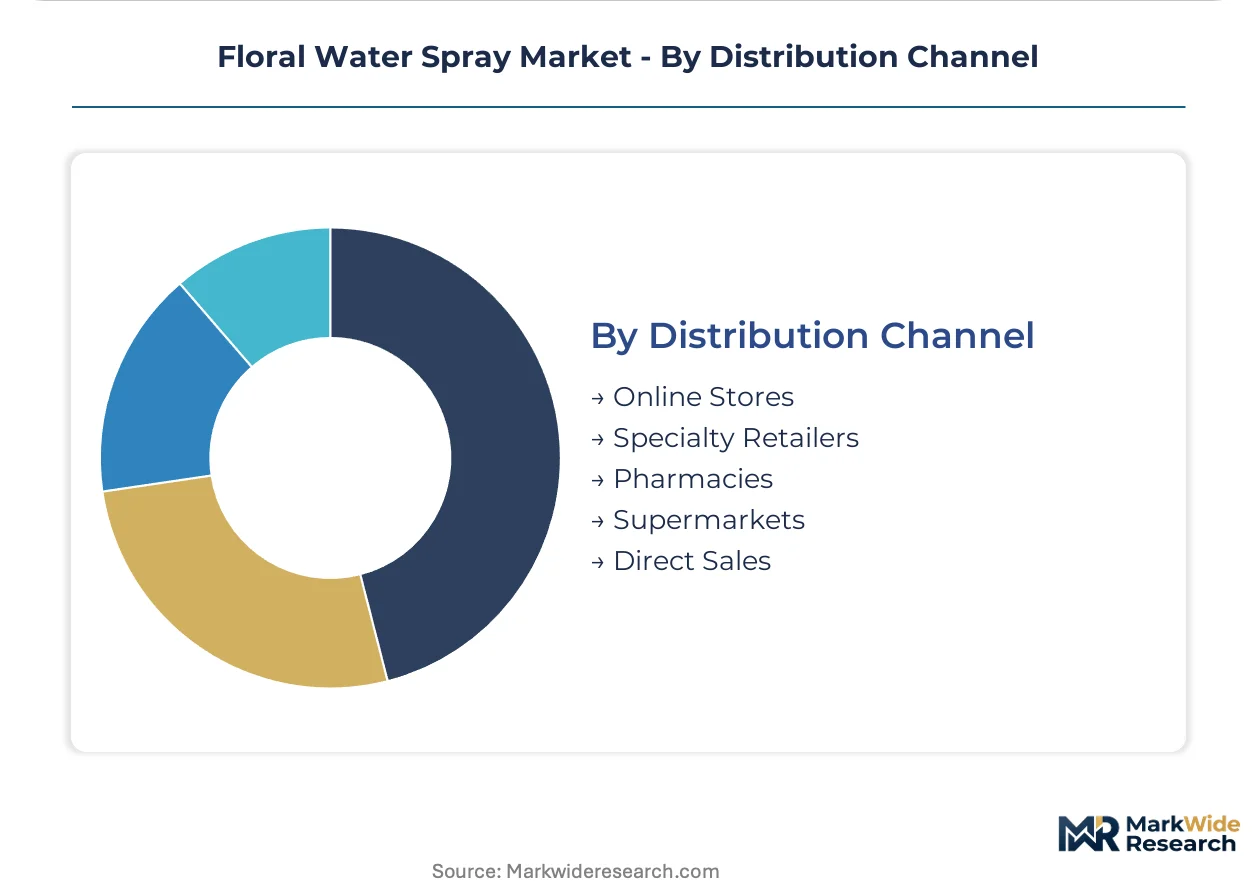
Specialty retailers lead on premium positioning; direct sales leads on margin preservation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provence-trained distillers and Bulgarian rose harvest specialists anchor the geographic distribution of hydrosol expertise. Certification requirements and cold-press capacity expansion are redrawing procurement maps across three continents.
China
Cold-press distillation capacity in eastern provinces is compressing global pricing benchmarks for rose and lavender water grades. SAMR cosmetic-grade standards bifurcate domestic production into separate quality tiers with divergent pricing. Zhejiang and Jiangsu clusters scale pharmaceutical-grade hydrosol output for skincare formulators.
France
Provence-based organic distillers control limited certified lavender water volumes, creating supply bottlenecks for brands requiring French origin claims. ECHA enforcement of REACH Annex XVII restrictions elevates documentation burdens for linalool content declarations. Grasse fragrance houses specify distilled rather than reconstituted hydrosol grades to satisfy safety assessor scrutiny.
Germany
Dermatology clinics in Bavaria and North Rhine-Westphalia mandate certified organic hydrosol chains with full substance registration documentation. REACH substance registration requirements are restructuring European hydrosol trade economics. Hamburg-based importers absorb full safety documentation costs or exit the market entirely.
India
Ayurvedic cosmetic manufacturers in Uttar Pradesh and Karnataka integrate traditional floral waters into export-oriented skincare lines. FSSAI and CDSCO oversight creates dual compliance pathways for cosmetic versus therapeutic classifications. Kannauj distillers leverage heritage rose cultivation corridors into Middle Eastern retail channels.
Brazil
ANVISA's expanding natural cosmetic registration pathways create regulatory tailwinds for hydrosol-based therapeutic claims. São Paulo and Rio de Janeiro wellness centers drive institutional procurement of aromatherapy-grade hydrosols. Domestic formulators bypass European cold-chain logistics through regional distillation partnerships.
Floral Water Spray Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-grade tiers. The vendor base stratifies between heritage distillers with Provence or Kannauj lineage and industrial-scale operators in eastern China. Three archetypes dominate: certified organic heritage brands, mass-market price competitors, and pharmaceutical-grade GMP specialists. Capacity expansion in cold-press distillation and backward integration into captive rose cultivation represent the dominant competitive moves.
Within the heritage organic tier, Melvita leverages its French S.A. structure to sustain premium positioning in certified segments. LiuShen anchors the Chinese specialist archetype through deep control of herbal extraction supply chains. RunBen occupies the mass-market vector, competing aggressively on price in baby care applications where mild formulation claims drive purchase decisions.
| Leading Market Players |
|---|
| OFF |
| YuMeiJing |
| Melvita |
| LongHu |
| Elsker |
| LiuShen |
| BaoBaoJinShu |
| RunBen |
| LongLiQi |
| Others |
Supply & Pricing Matrix
Damask rose harvest yields in Bulgaria and Turkey transmit directly through pharmaceutical-grade hydrosol pricing tiers, with frost-damaged vintages compressing margins for distillers locked into long-term cosmetic house contracts. Cold-press distillation capacity expansion in Zhejiang and Jiangsu provinces is simultaneously eroding premium positioning for European heritage brands unable to match unit economics.
Pricing Analysis
Unbundled hydrosol shipments command premium positioning against contract-bundled volumes that absorb documentation and certification costs into headline rates. Pharmaceutical-grade certification under REACH and SAMR standards separates pricing into three tiers: premium organic chains, standard cosmetic-grade batches, and economy food-grade alternatives. Pricing pressure intensifies in mass-market personal care as synthetic fragrance compounds undercut authentic distillate positioning. Baby care formulators exhibit highest price sensitivity; dermatology clinics demonstrate lowest elasticity due to therapeutic protocol requirements.
Supply Chain Analysis
Seasonal workforce availability in Bulgarian rose cultivation zones and Provence lavender harvest windows constrains annual distillation throughput regardless of installed equipment capacity. Supply concentrates in Bulgaria, Turkey, and eastern China for raw botanical inputs; France and Germany dominate GMP-certified finishing capacity. Rose otto and lavender essential oil co-production economics hinge on volatile aromatic compound recovery rates. Single-source vulnerability runs through Provence-origin certification requirements for French fragrance house procurement. Distribution runs through temperature-controlled logistics networks serving specialty retailers and direct-to-practitioner channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where dermatology clinic procurement shifts toward pharmaceutical-grade hydrosol specifications are filtering backward through cosmetic formulation tiers.
For Market Incumbents: To counter synthetic fragrance substitution in mass-market personal care, heritage distillers should deepen backward integration into captive rose cultivation in Bulgaria and Turkey while accelerating REACH substance registration completion for existing botanical portfolios. Certification investment in blockchain batch-level provenance tracking captures premium positioning with Nordic sustainability-verified buyers. For New Entrants and Emerging Players: Supercritical CO2 extraction technology offers entry wedge into South Korean and Japanese prestige skincare supply chains where sensorial differentiation commands price separation. White-space targets include ANVISA-registered therapeutic positioning in Brazil and direct-to-practitioner aromatherapy channels in Australia bypassing traditional retail markups. For Investors and Strategic Acquirers: Consolidation pressure builds where cold-press capacity scale in China meets European regulatory documentation barriers that smaller regional distillers cannot finance. Long-term viability favors GMP-compliant operators with in-house quality management infrastructure. Signal to watch: REACH registration deadline compliance rates among mid-tier importers as inflection indicator for supply rationalization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Distillation Scale-Up | Zhejiang and Jiangsu clusters compress global pricing benchmarks for rose and lavender water grades. |
| Backward Integration into Cultivation | Bulgarian and Turkish rose corridor control insulates harvest yield volatility for GMP-certified distillers. |
| Blockchain Provenance Implementation | Batch-level tracking satisfies Nordic retailer sustainability scorecards determining shelf placement eligibility. |
| REACH Substance Registration Completion | Full safety documentation preserves European market access as accelerated deadlines eliminate grandfathering. |
| ANVISA Therapeutic Registration Pathway | Natural cosmetic claims expansion in Brazil creates regulatory tailwinds for hydrosol-based spa medicine protocols. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hydrosol distillation executives, cosmetic formulation directors, dermatology clinic procurement managers, and aromatherapy certification program administrators with secondary validation against REACH Annex XVII filings, SAMR cosmetic-grade standards documentation, customs trade data for botanical distillate flows, and ECHA substance registration databases. Bottom-up volume modeling and top-down value triangulation anchored segment-level outputs.
Comparable-period anchoring tied projection assumptions to historical reference windows across the analysis window, with segmentation modeling spanning product type, extraction method, certification grade, end-use regulatory classification, and geographic demand cluster. CAGRs were derived from fitted growth curves incorporating pharmaceutical-grade purity specification adoption rates, cold-press capacity expansion trajectories, and regulatory compliance cost absorption patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH enforcement intensity, frost pattern disruption in Bulgarian rose cultivation zones, and synthetic fragrance compound cost compression. Forecasts reflect documented assumptions about regulatory timeline adherence and harvest yield stability. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Clean Perfume Market
Fragrances & Perfumes
Global Perfume Market
Fragrances & Perfumes
Kuwait Perfume Market
Fragrances & Perfumes
Global Fragrances and Perfumes Market
Fragrances & Perfumes
UAE Perfume Market
Fragrances & Perfumes
Gulf Cooperation Council Fragrance and Perfumes Market
Fragrances & Perfumes
Cosmetic and Fragrance Retail Chain Market
Fragrances & Perfumes
Fragrance Diffuser Market
Fragrances & Perfumes
Saudi Arabia E-Commerce Cosmetics and Fragrances Market
Fragrances & Perfumes
Evaporative Diffusers Market
Fragrances & Perfumes
Smart Fragrance Box Market
Fragrances & Perfumes
GCC Perfume and Fragrance Market
Fragrances & Perfumes
Digital Scent Market
Fragrances & Perfumes
Gourmand Fragrance Market
Fragrances & Perfumes
Reed Diffusers Market
Fragrances & Perfumes
Saudi Arabia Perfume Market