
 Digital Fragrance Market | 2026-2036
Digital Fragrance Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Fragrance Market Insights
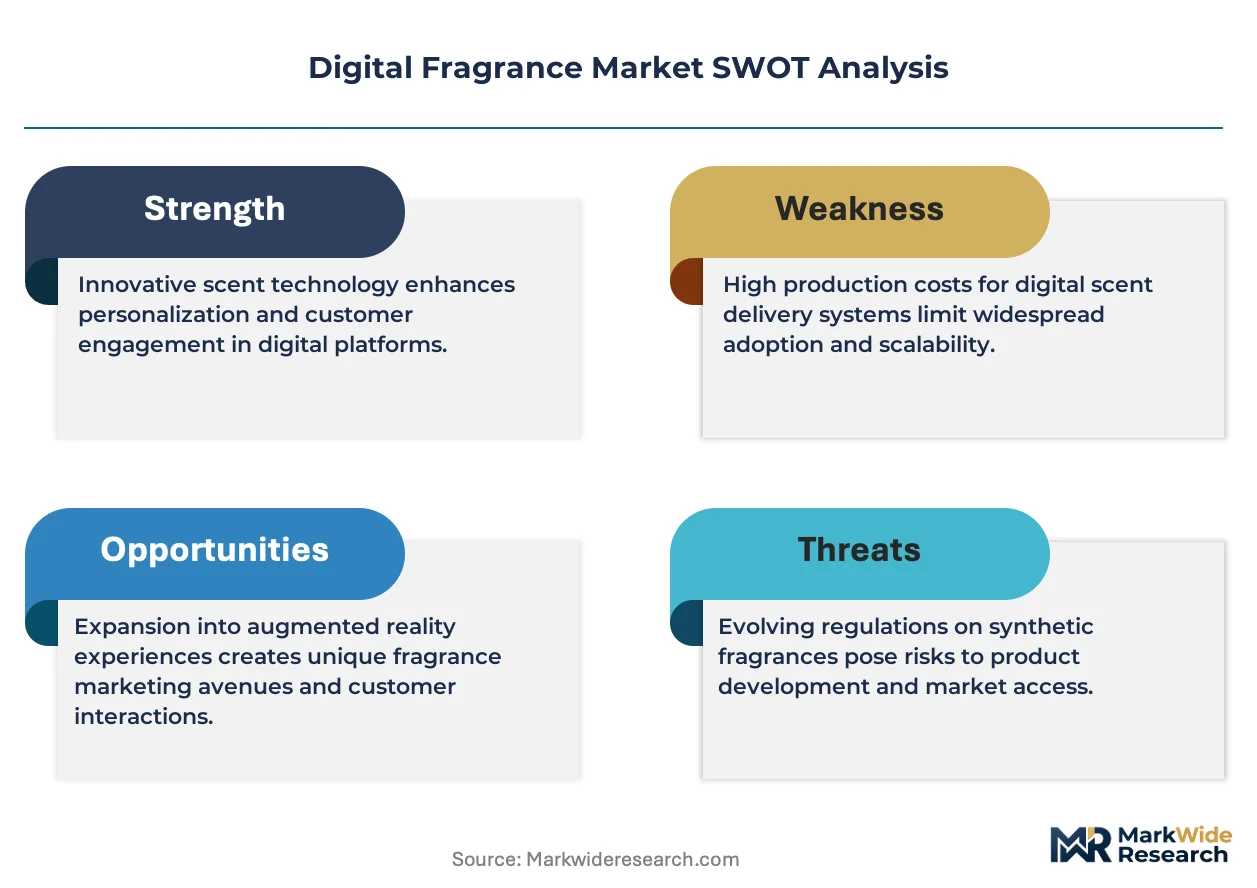
ISO 17025 laboratory accreditation is bifurcating the competitive landscape for digital fragrance hardware. Aryballe Technologies SA leverages silicon photonics expertise to sustain leadership in compact odor-sensing modules. Airsense Analytics GmbH anchors European demand through industrial-grade electronic nose systems for environmental monitoring.
Digital fragrance denotes the emission, synthesis, or transmission of scent through software-controlled hardware, typically employing piezoelectric atomizers, thermal evaporation chambers, or solid-state fragrance cartridges with programmable release profiles. The technology serves commercial and consumer applications ranging from immersive retail environments to personalized therapeutic interventions. Smart Devices and IoT Diffusers occupy the dominant margin pools as recurring consumable revenue attaches to hardware platforms. Wearable Technology competes for fastest-growing status as miniaturized scent-emitting modules integrate with personal electronics and fitness bands.
FDA oversight of therapeutic scent claims, EPA registration requirements for pesticidal odor-masking applications, and FCC certification for wireless-connected diffusers collectively raise compliance costs for new entrants. The EU REACH framework further constrains volatile organic compound formulations in networked emission devices. Stakeholders must monitor evolving chemical disclosure mandates and interoperability standards before committing capital to platform ecosystems.
Market Dynamics
Silicon photonics miniaturization is collapsing the cost curve for odor-sensing modules, enabling mass-market deployment of connected scent hardware that was previously confined to industrial laboratories and luxury retail installations.
Growth Catalysts
- EU Green Deal chemical provisions:The framework's volatile organic compound disclosure mandates are accelerating replacement of solvent-based fragrance cartridges with solid-state programmable formulations in networked emission devices.
- China IoT hardware clusters:Concentrated manufacturing ecosystems in Shenzhen and Dongguan compress prototyping cycles from months to weeks for scent-emitting wearables.
- Immersive retail environments:Flagship stores in hospitality and automotive showrooms deploy programmable scent zones to extend dwell time and reinforce brand identity.
Market Restraints
- Piezoelectric atomizer supply concentration:Precision microfluidic nozzle fabrication depends on a handful of German and Japanese specialty ceramics suppliers, creating single-source vulnerability.
- EPA pesticidal registration pathways:Odor-masking devices claiming air quality benefits face monthslayered review timelines that freeze product launches.
- Thermal evaporation energy density limits:Battery-powered portable units sacrifice fragrance payload capacity for operational duration, constraining use cases.
Strategic Opportunities
- India wellness tourism corridors:Ayurvedic therapy centers in Kerala and Karnataka represent untapped demand for personalized therapeutic scent interventions.
- FCC certification reciprocity expansion:Streamlined wireless device approval across North American markets reduces compliance duplication for connected diffuser platforms.
- Synthetic biology convergence:Engineered yeast strains producing rare fragrance molecules at scale threaten to collapse raw material costs for cartridge formulations.
Industry Challenges
- ISO 17025 accreditation timelines:Laboratory certification for volatile organic compound testing stretches twelve to eighteen months, gating market entry for hardware startups.
- Legacy HVAC integration complexity:Building management system protocols vary across commercial real estate vintages, forcing costly custom engineering for centralized scent distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Fragrance Market |
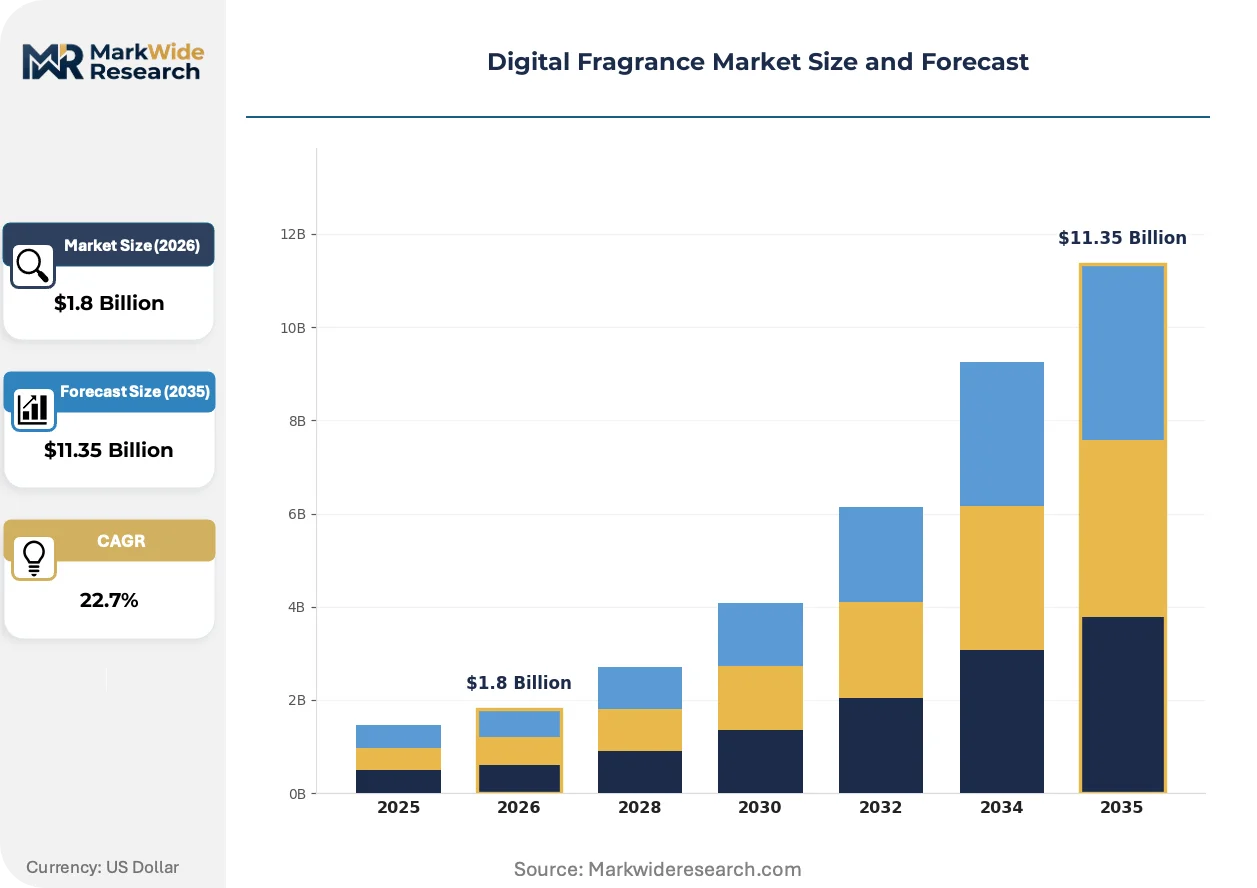
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Smart Devices, IoT Diffusers, Wearable Technology Target Audience: Consumers, Businesses, Healthcare Professionals, Educators Technology: Scent Emission, Virtual Reality, Augmented Reality, Digital Marketing Application: Entertainment, Home Decor, Therapeutic Uses, Retail Experiences |
| Companies Covered | Alpha MOS SA, Airsense Analytics GmbH, Aryballe Technologies SA, Electronic Sensor Technology, The eNose Company, Scentcom Ltd., Aromajoin Corporation, Odotech Inc., ScentSational Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Fragrance Market Trends and Innovations
Computational olfaction hardware is migrating from laboratory benchtops to consumer electronics form factors, compressing sensor size while expanding deployment contexts across automotive cabins, healthcare facilities, and domestic environments.
Solid-state fragrance cartridges with embedded microcontrollers are fragmenting the traditional liquid-refill model. Automotive OEMs in Stuttgart and Toyota City embed these units directly into climate control systems. The shift compresses aftermarket revenue pools while expanding captive consumable attachment rates.
REACH Annex XVII restrictions on synthetic musks are forcing reformulation of networked diffuser libraries. Fragrance houses in Grasse and Geneva accelerate biotech-derived replacements. Premium residential segments absorb compliance costs more readily than commercial hospitality deployments.
Subscription cartridge replenishment is displacing retail purchase for connected home diffusers. Direct-to-consumer channels in California and Seoul capture recurring revenue previously lost to mass-market retailers. The model concentrates customer data ownership with platform operators rather than fragrance houses.
Digital Fragrance Market Segmentation
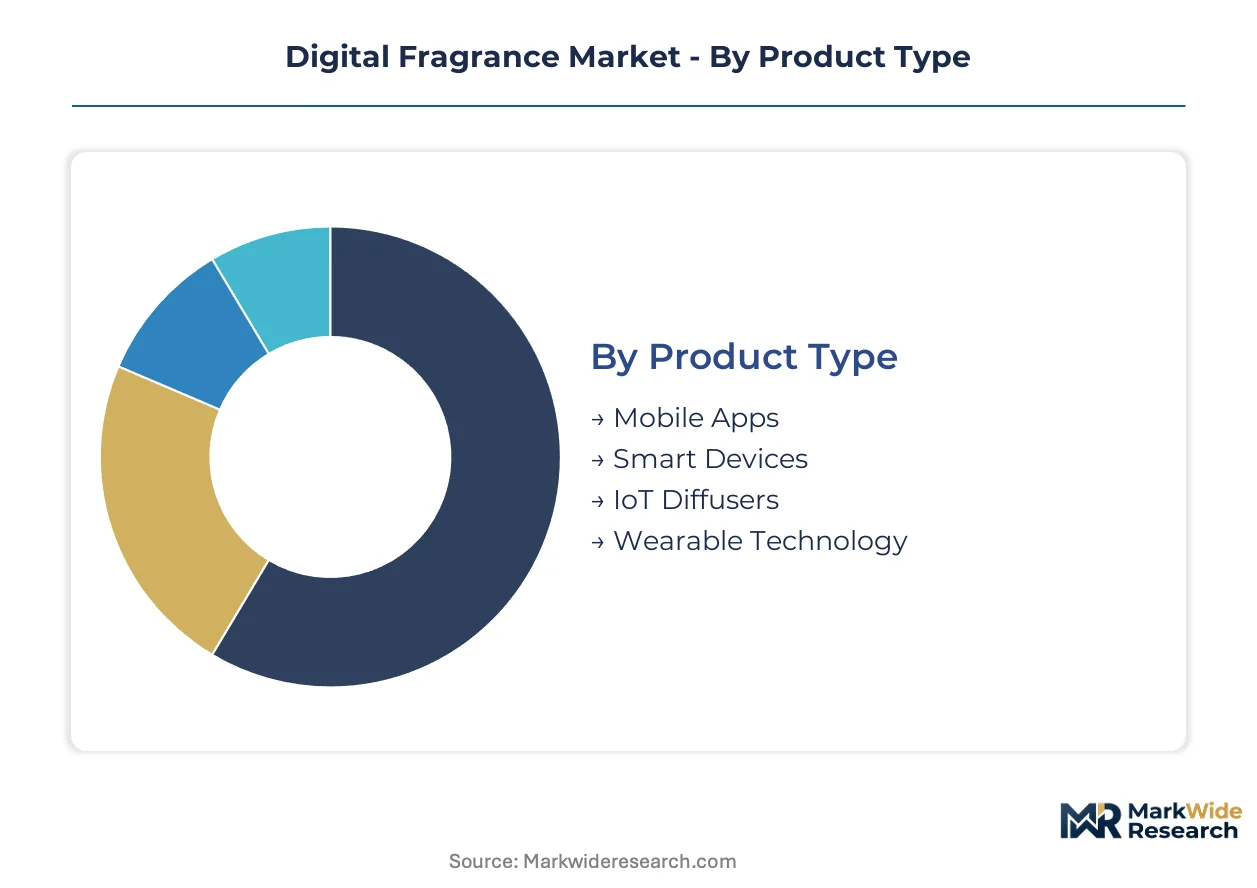
Digital fragrance hardware and software platforms serve fundamentally different margin economics. Recurring consumable revenue attaches to connected devices, while application-layer solutions capture value through licensing and content fees. Understanding where profit pools concentrate within each dimension shapes capital allocation decisions.
Product Type:
Margin pools concentrate in hardware platforms with recurring cartridge revenue, while software-only solutions compete on acquisition cost.
- Smart Devices:Dedicated scent-emitting hardware with embedded microcontrollers and programmable release profiles. Demand clusters in luxury residential installations across California and Seoul, driven by subscription replenishment models that displace retail cartridge purchases.
- IoT Diffusers:Network-connected emission systems integrating with smart home ecosystems via Wi-Fi or mesh protocols. Hospitality deployments in Dubai and Singapore absorb premium pricing for centralized management capabilities and brand-customizable scent libraries.
- Mobile Apps:Software platforms delivering scent-related content without dedicated hardware. Fragrance houses in Grasse license digital scent pairing algorithms to supplement physical product sales.
- Wearable Technology:Miniaturized emission modules integrated with personal electronics. Shenzhen manufacturing clusters compress prototyping cycles for fitness band attachments targeting wellness applications.
The dominant share belongs to IoT Diffusers, while Wearable Technology is closing the gap fastest.
Target Audience:
Volume concentrates in consumer-facing segments, though healthcare and commercial deployments command pricing premiums through regulatory compliance requirements.
- Consumers:Individual purchasers of residential scent systems and mobile applications. Direct-to-consumer channels in California and Seoul capture recurring revenue previously lost to mass-market retailers.
- Healthcare Professionals:Clinical practitioners deploying therapeutic scent interventions for anxiety management and sleep disorders. FDA oversight of therapeutic claims raises compliance costs for hardware startups entering this segment.
- Businesses:Corporate purchasers outfitting commercial spaces, automotive showrooms, and retail flagships. Immersive retail environments in Stuttgart and Toyota City deploy programmable scent zones to extend dwell time.
- Educators:Museums, science centers, and experiential learning facilities. Institutions in Geneva and Kyoto integrate scent emission with virtual reality installations for historical and cultural programming.
Businesses command the highest average contract values, though Healthcare Professionals show the steepest expansion trajectory as clinical validation accumulates.
Technology:
Cost tiers separate hardware-dependent emission systems from software-only virtual and augmented reality integrations.
- Scent Emission:Hardware systems employing piezoelectric atomizers, thermal evaporation chambers, or solid-state cartridges. Precision microfluidic nozzle fabrication depends on German and Japanese specialty ceramics suppliers, creating single-source vulnerability.
- Virtual Reality:Immersive digital environments with synchronized olfactory output. VR arcades in Tokyo and Los Angeles deploy multi-user scent systems for entertainment and training simulations.
- Augmented Reality:Overlay scent cues onto physical environments through mobile or wearable hardware. Retail applications in Paris and Milan trigger fragrance samples when consumers scan product packaging.
- Digital Marketing:Scent-triggered advertising content and brand experience platforms. Automotive OEMs embed these capabilities into online configurators for luxury vehicle previews.
Scent Emission retains the dominant installed base, while Augmented Reality is expanding most quickly through smartphone penetration.
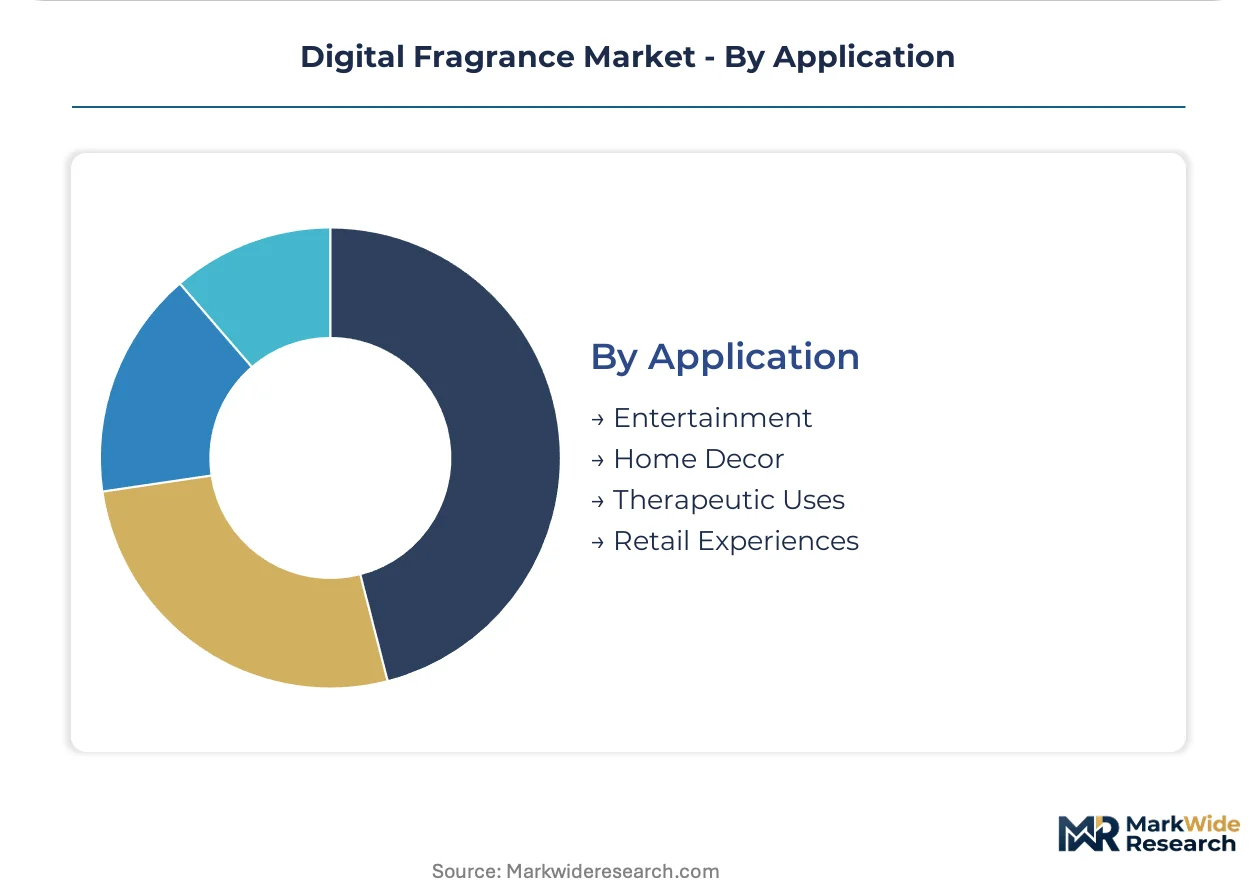
Application:
Customer type determines specification requirements, with therapeutic and retail deployments demanding precision unavailable in consumer home decor segments.
- Therapeutic Uses:Clinical and wellness applications targeting stress reduction, sleep enhancement, and cognitive performance. Ayurvedic therapy centers in Kerala and Karnataka represent emerging demand for personalized interventions.
- Retail Experiences:Programmable scent zones in flagship stores, showrooms, and hospitality venues. EU REACH Annex XVII restrictions on synthetic musks force reformulation of networked diffuser libraries for European deployments.
- Entertainment:Cinematic, gaming, and live event applications with synchronized olfactory output. Premium theaters in Seoul and Dubai install seat-level emission systems for immersive content.
- Home Decor:Residential aesthetic and ambient scent applications. Smart home integration accelerates adoption among residential consumers seeking automated climate and fragrance coordination.
Retail Experiences generate the highest revenue per installation, while Therapeutic Uses are gaining share fastest through regulatory pathway clarifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxury residential buyers in Seoul and California drive premium hardware adoption, while hospitality chains in Dubai and Singapore absorb enterprise-grade systems. Industrial odor-sensing demand concentrates in German environmental monitoring sectors.
United States
FDA oversight of therapeutic scent claims and EPA pesticidal registration requirements shape hardware deployment timelines. Direct-to-consumer channels in California capture recurring cartridge revenue through subscription replenishment models. Silicon Valley IoT startups compress prototyping cycles for smart home-integrated diffusers.
Germany
Industrial environmental monitoring applications sustain demand for laboratory-grade electronic nose systems. EU REACH Annex XVII restrictions on synthetic musks force fragrance house reformulations in Grasse and Geneva supply chains. Stuttgart automotive OEMs embed solid-state cartridges directly into climate control systems.
China
Domestic IoT hardware manufacturing clusters in Shenzhen and Dongguan enable rapid product iteration for scent-emitting wearables. MIIT certification pathways for wireless-connected devices streamline commercial deployment. Yangtze River Delta electronics assemblers achieve month-scale prototyping for fitness band attachments.
South Korea
Wellness-oriented consumers in Seoul adopt subscription-based home diffuser platforms at premium price points. MFDS regulatory clarity on therapeutic scent claims accelerates clinical hardware development. Seoul Capital Area electronics firms miniaturize emission modules for personal electronics integration.
United Arab Emirates
Hospitality deployments in Dubai absorb centralized scent management systems for programmable lobby and retail environments. MOHAP guidance on indoor air quality devices influences commercial specification requirements. Dubai Design District hosts experiential retail installations with brand-customizable scent libraries.
Digital Fragrance Market Competitive Landscape
Player mix skews toward specialized sensor technology developers and industrial environmental monitoring firms. Market structure exhibits moderate consolidation around ISO 17025-accredited laboratory networks. Two strategic archetypes dominate: silicon photonics miniaturization specialists and industrial-grade electronic nose system providers. Competitive moves concentrate on strategic partnerships for HVAC integration and portfolio diversification into therapeutic applications.
Among France-based technology developers, Aryballe Technologies SA and Alpha MOS SA exemplify the sensor miniaturization archetype, while Airsense Analytics GmbH anchors European industrial demand from its German base. These three occupy positions across the value chain from compact odor-sensing modules to environmental monitoring installations.
| Leading Market Players |
|---|
| Alpha MOS SA |
| Airsense Analytics GmbH |
| Aryballe Technologies SA |
| Electronic Sensor Technology |
| The eNose Company |
| Scentcom Ltd. |
| Aromajoin Corporation |
| Odotech Inc. |
| ScentSational Technologies LLC |
| Others |
Pricing and Supply Chain Analysis
Subscription cartridge replenishment contracts lock in recurring revenue visibility for platform operators while binding consumers to predictable per-month expenditure commitments across California and Seoul residential markets. These arrangements simultaneously secure offtake volumes for fragrance formulation houses and compress price transparency for competing hardware entrants.
Pricing Analysis
Cost-plus arrangements with raw material indexation dominate cartridge procurement between fragrance houses and hardware platforms. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-accredited therapeutic-grade systems from residential ambient devices and unconnected basic diffusers. Pricing pressure stems from Shenzhen manufacturing clusters compressing hardware margins for entry-tier connected devices. Healthcare deployments show least price sensitivity due to FDA compliance cost absorption, while mass-market residential segments in emerging economies resist subscription commitments.
Supply Chain Analysis
Precision microfluidic nozzle fabrication from German and Japanese specialty ceramics suppliers creates single-source vulnerability for piezoelectric atomizer assembly. Component sourcing draws from China for microcontroller boards, South Korea for miniaturized emission modules, and France for biotech-derived fragrance molecules. Tariff exposure on ceramic subcomponents threatens cost escalation for hardware platforms dependent on East Asian electronics integration. Distribution runs through direct-to-consumer channels capturing recurring revenue, supplemented by hospitality procurement through systems integrators in Dubai and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon photonics miniaturization represents a high-growth disruption reshaping competitive economics, with EU REACH Annex XVII restrictions on synthetic musks accelerating biotech-derived formulation investment. This regulatory-technological inflection compresses incumbent advantage windows while expanding accessible market segments.
For Market Incumbents: Compound certification moats by accelerating ISO 17025 laboratory accreditation for volatile organic compound testing ahead of hardware startup entrants. Deepen backward integration into solid-state cartridge manufacturing to capture consumable margin pools threatened by synthetic biology convergence. Prioritize HVAC integration partnerships with building management system providers to lock out challenger platforms from commercial real estate deployments. For New Entrants and Emerging Players: Differentiate on therapeutic claim validation by pursuing FDA oversight pathways for anxiety management and sleep disorder applications before clinical validation saturates. Target Ayurvedic therapy centers in Kerala and Karnataka as white-space demand with limited incumbent penetration. Pursue white-label manufacturing partnerships with Shenzhen clusters to compress time-to-market for fitness band scent attachments. For Investors and Strategic Acquirers: Sensor miniaturization specialists with silicon photonics expertise and existing automotive OEM relationships represent priority acquisition targets for platform consolidation plays. Long-term viability hinges on recurring revenue attachment rates exceeding hardware depreciation cycles. Watch for MFDS regulatory clarity on therapeutic scent claims as signal for clinical segment inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Cartridge Integration | Automotive OEMs in Stuttgart embed programmable units directly into climate control systems, compressing aftermarket revenue pools. |
| ISO 17025 Laboratory Accreditation | Certification for volatile organic compound testing gates market entry and concentrates competitive advantage among accredited networks. |
| Smart Home Platform Integration | Wi-Fi and mesh protocol connectivity with Alexa and Google Home ecosystems accelerates residential adoption in Seoul and California. |
| Synthetic Biology Partnership | Engineered yeast strain collaborations with Grasse fragrance houses threaten to collapse rare molecule raw material costs. |
| HVAC Systems Integration | Building management system partnerships enable centralized scent distribution across Dubai hospitality corridors and Singapore retail flagships. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with IoT hardware engineering leads, fragrance house formulation directors, hospitality procurement managers, and smart home platform integration specialists. Secondary validation drew from FCC certification filings, EU REACH Annex XVII regulatory updates, MIIT wireless device registrations, and customs trade data for piezoelectric component flows. Bottom-up hardware shipment estimates triangulated against top-down fragrance cartridge consumption models across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, target audience archetype, emission technology, and application context with regional regulatory cluster overlays. CAGRs were derived from installed base expansion rates and consumable attachment velocity assumptions. Industry-specific inputs included silicon photonics cost curve trajectories and synthetic biology-derived molecule commercialization timelines.
Material uncertainties — regulatory pathway delays for therapeutic claims, supply disruption in German-Japanese ceramic nozzle channels, and REACH Annex XVII expansion scope — sit outside the modeled envelope. Forecasts reflect assumptions about smart home penetration curves and hospitality capital expenditure cycles. Practitioners should keep alternative scenarios live as EU Green Deal chemical safety provisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
GCC Perfume Market
Fragrances & Perfumes
Mini Refillable Perfume Bottles Market
Fragrances & Perfumes
Digital Scent Market
Fragrances & Perfumes
Smart Fragrance Box Market
Fragrances & Perfumes
Natural Fragrance Market
Fragrances & Perfumes
Kuwait Perfume Market
Fragrances & Perfumes
Saudi Arabia Perfume Market
Fragrances & Perfumes
Organic Perfumes Market
Fragrances & Perfumes
Perfume Vials Market
Fragrances & Perfumes
North America Perfume Market
Fragrances & Perfumes
Middle East Fragrances Market
Fragrances & Perfumes
Fragrance Emulsion Market
Fragrances & Perfumes
Scented Oil Market
Fragrances & Perfumes
Clean Perfume Market
Fragrances & Perfumes
Fragrance Product Market
Fragrances & Perfumes
Global Luxury Perfumes Market