
 Natural Fragrance Market | 2026-2036
Natural Fragrance Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Fragrance Market Analysis
Market Context
Premium natural fragrance formulations is decoupling from commodity-grade essential oil markets as certification standards and extraction methods diverge sharply. Givaudan SA leverages captive botanical sourcing across Madagascar and Haiti to secure rare raw materials for high-margin perfumery. Symrise AG anchors its position through biotechnology-derived naturals that bypass agricultural yield constraints. Robertet SA dominates traditional extraction, sustaining heritage methods in Grasse while competing on traceability credentials.
Technical Definition and Segment Structure
Natural fragrance denotes aromatic compounds derived exclusively from botanical, animal, or mineral sources through distillation, expression, or solvent extraction, with ISO 9235 serving as the definitional standard for what qualifies as "natural" in commercial labeling. Essential oils and floral extracts command the deepest margin pools in personal care and fine fragrance applications, where brand equity ties directly to provenance claims. Aroma compounds from biotechnology fermentation represent the fastest-expanding product type, while herbal blends occupy mature demand in home care and aromatherapy channels. Specialty stores and online retail together capture the highest-value distribution for premium natural fragrance, though supermarkets move volume in mass-market personal care.
Regulatory Framework and Outlook
REACH in Europe, FDA labeling requirements in the United States, and ISO 9235 standards collectively define what constitutes "natural" on product labels, with each framework tightening analytical thresholds for synthetic adulteration. ECHA's expanding restriction candidate list and the EU Green Deal's chemical sustainability targets are forcing reformulation timelines across the supply chain. Stakeholders must monitor how regulatory divergence between Brussels and Washington reshapes ingredient qualification and cross-border market access.
Market Dynamics
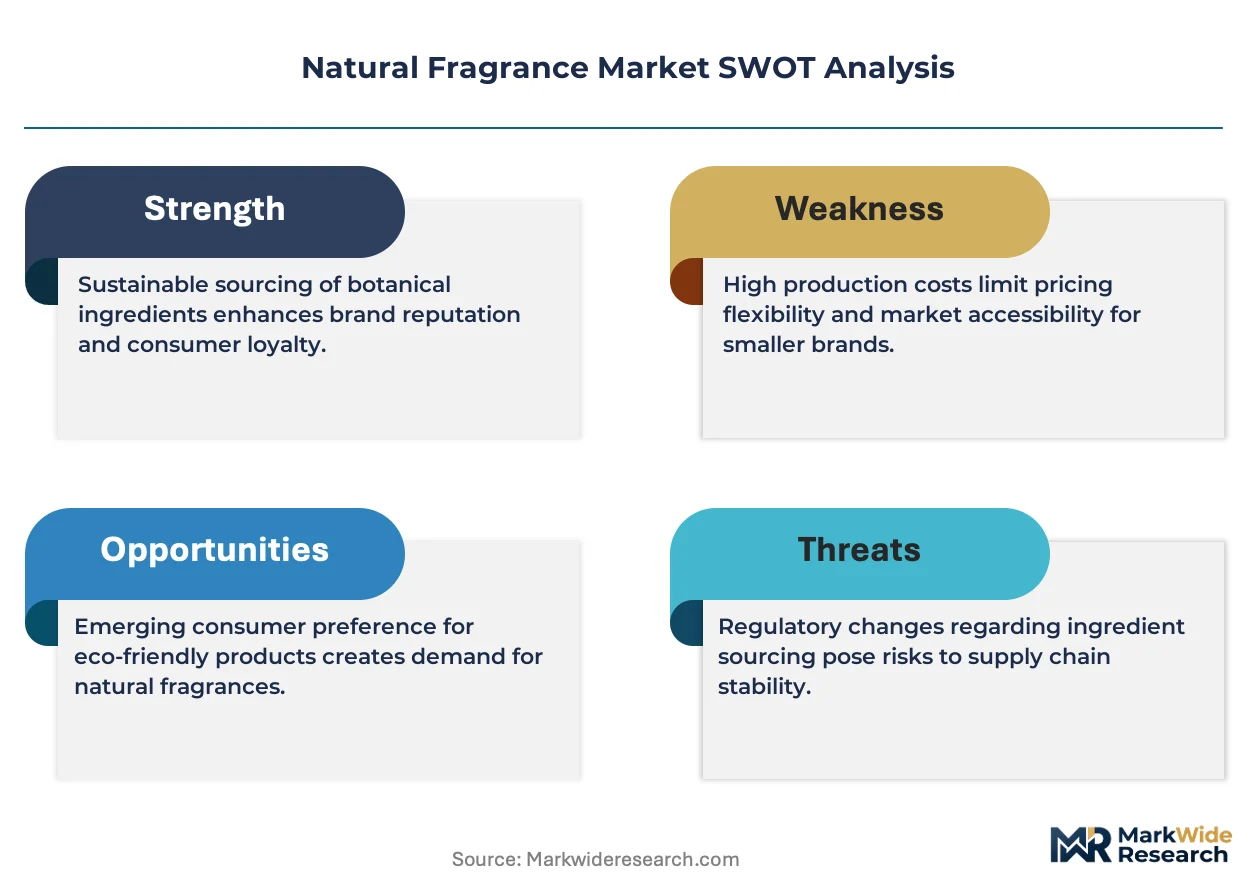
REACH and the EU Green Deal are compressing synthetic fragrance thresholds, forcing reformulation budgets toward botanical extraction and biotechnology-derived alternatives across personal care supply chains.
Growth Catalysts
- REACH mandates:Tightening permissible synthetic thresholds in Europe redirect procurement toward ISO 9235-certified botanical inputs, accelerating clean-label substitution cycles.
- Biotechnology fermentation:Microbial aroma production bypasses agricultural yield constraints and climate volatility, securing supply for rare compounds previously dependent on harvests.
- Grasse extraction cluster:France's concentration of heritage extraction houses and luxury perfumers anchors premium supply chains, concentrating traceability-driven demand.
Market Restraints
- Agricultural input volatility:Weather-driven crop failures and harvest variability destabilize essential oil pricing, compressing margin predictability for botanical-dependent formulators.
- Extraction capacity concentration:Traditional distillation and solvent extraction expertise clusters in Southern France and select tropical origins, creating bottleneck risk for scale-up.
- Biotechnology scale-up costs:Fermentation-derived naturals require capital-intensive bioreactor infrastructure and strain development, delaying cost parity with conventional extraction.
Strategic Opportunities
- Home care aromatherapy expansion:Herbal blend applications in ambient scenting and wellness products remain underpenetrated relative to personal care, offering volume diversification.
- Specialty retail channel development:Direct-to-consumer and boutique retail formats bypass mass-market margin compression, capturing premium pricing for provenance-verified formulations.
- EU Green Deal chemical sustainability targets:Mandated reduction in petrochemical-derived inputs creates procurement preference for biotech and botanical alternatives in European formulations.
Industry Challenges
- ISO 9235 analytical compliance:Certification timelines for natural labeling claims require extensive carbon-14 testing and documentation, delaying product launches.
- Traceability system integration:Blockchain and batch-tracking technologies must interface with legacy ERP systems across fragmented agricultural supply bases.
Report Scope
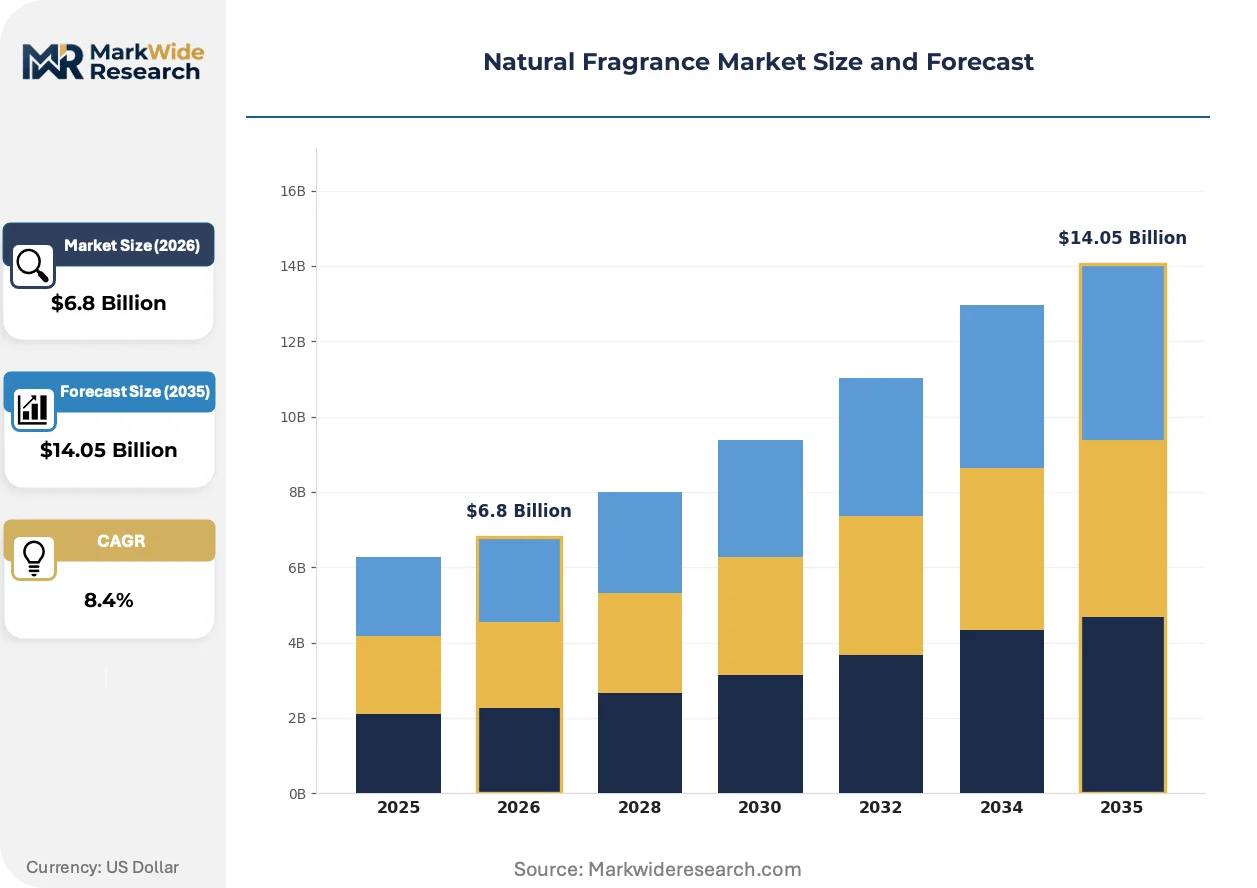
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Fragrance Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Floral Extracts, Herbal Blends, Aroma Compounds Application: Personal Care, Home Care, Food & Beverage, Aromatherapy End User: Manufacturers, Retail Brands, Home Users, Wellness Centers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Symrise AG, Robertet SA, International Flavors & Fragrances Inc., Mane SA, T. Hasegawa Co., Ltd., Givaudan SA, Sensient Technologies Corporation, CPL Aromas, Firmenich SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Fragrance Market Emerging Trajectories
Biotechnology-derived aroma compounds and precision extraction methods are compressing the cost-performance gap with synthetics while regulatory tightening redefines qualification standards for natural claims.
Precision fermentation of fragrance molecules is electrifying supply security for rare botanicals. Fine fragrance houses and niche perfumers are adopting biotech-derived sandalwood and musk alternatives at accelerating rates. This technology is electrifying margin structures by decoupling high-value compounds from agricultural land use and harvest cycles.
REACH authorization procedures and the EU Green Deal's chemical sustainability roadmap are forcing systematic ingredient reviews. ECHA's expanding restriction candidate list triggers preemptive reformulation across personal care portfolios. European fine fragrance and mass-market personal care segments are responding by accelerating biotechnology partnerships and captive botanical sourcing arrangements.
Clean-label preference is compressing synthetic fragrance tolerance thresholds among formulation buyers. Mass-market personal care brands are displacing conventional scent systems with certified natural alternatives, while specialty retailers capture premium positioning through provenance storytelling. France and adjacent European markets exhibit the most pronounced certification-driven procurement behavior, with Grasse-origin claims commanding measurable price premiums.
Natural Fragrance Market Segmentation
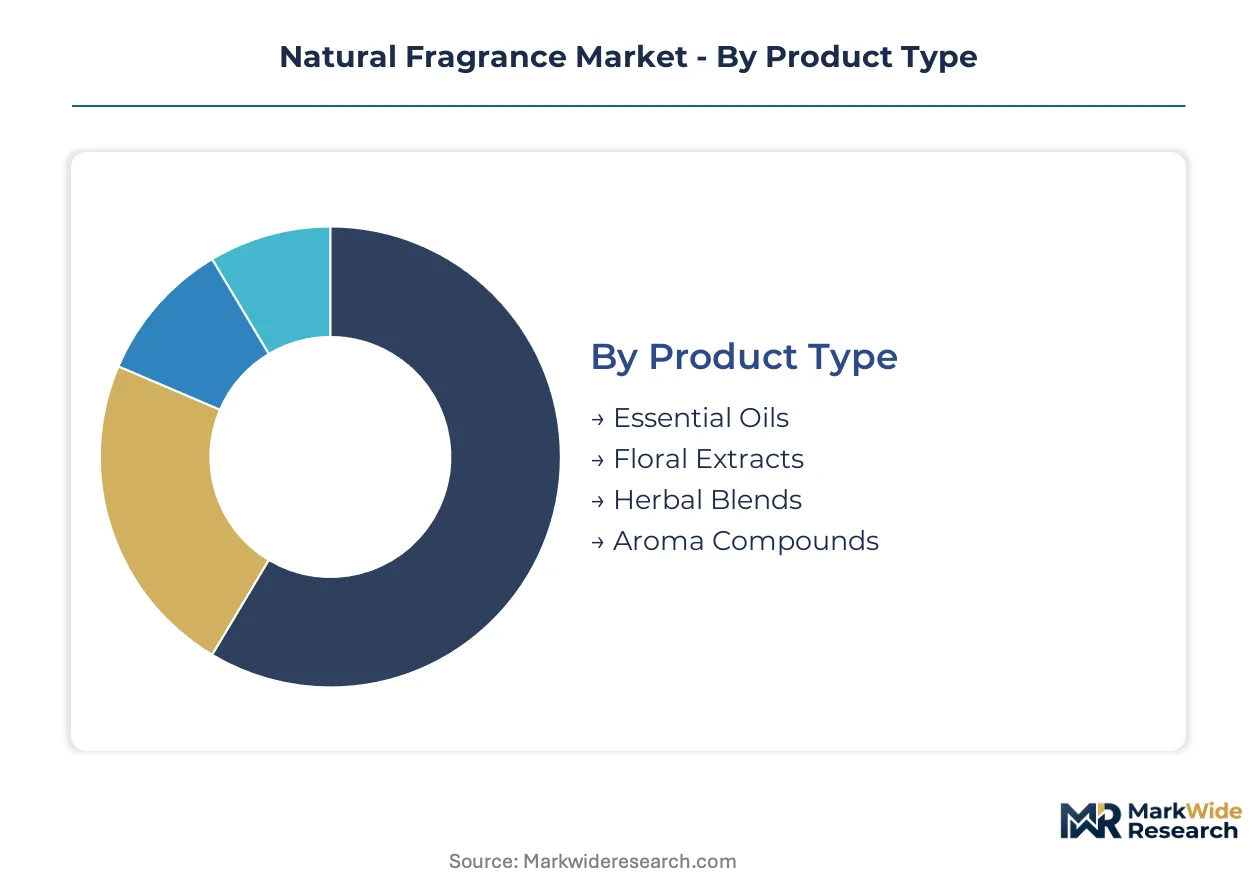
Segmentation in natural fragrances tracks how extraction methods, certification tiers, and end-use specifications diverge across supply chains. Buyers upgrade from commodity essential oils to ISO 9235-certified extracts as regulatory thresholds tighten and provenance claims harden into pricing power.
Product Type:
Upgrade cycles in natural fragrance procurement favor extracts with verified botanical provenance and carbon-14 compliance over undifferentiated commodity grades.
- Essential Oils:Distilled or cold-pressed volatile compounds from plant material, standardized by ISO 9235 for natural labeling eligibility. Personal care formulators in France concentrate procurement here, driven by REACH-mandated synthetic displacement timelines.
- Floral Extracts:Solvent-extracted or enfleurage-derived aromatic concentrates preserving delicate top notes. Fine fragrance houses anchor demand in Grasse, where extraction heritage commands measurable price premiums over industrial alternatives.
- Herbal Blends:Composite formulations targeting wellness and home care applications.
- Aroma Compounds:Biotechnology-fermented molecules bypassing agricultural yield constraints.
Essential oils sit at the top of the volume ranking, with aroma compounds climbing the fastest.
Application:
Cost tier stratification separates premium fine fragrance formulations from mass-market personal care and commodity home care applications.
- Personal Care:Skincare, haircare, and body wash formulations requiring ISO 9235-certified inputs for clean-label positioning. European brands accelerate reformulation here, compressing synthetic fragrance tolerance thresholds ahead of EU Green Deal chemical sustainability targets.
- Home Care:Detergents, surface cleaners, and ambient scenting products with lower certification requirements. Volume demand concentrates in supermarket channels, though margin compression limits botanical input penetration relative to personal care.
- Food & Beverage:Flavor-grade natural extracts meeting food safety standards.
- Aromatherapy:Wellness-oriented applications in therapeutic and spa contexts.
Personal care commands the deepest margin pools, with aromatherapy gaining share fastest in specialty retail channels.
End User:
Customer type determines whether procurement prioritizes traceability systems, formulation services, or direct consumer education.
- Manufacturers:Industrial formulators requiring batch consistency and regulatory documentation. These buyers drive demand for blockchain-enabled traceability as ECHA expands its restriction candidate list and reformulation timelines compress.
- Retail Brands:Consumer-facing companies sourcing finished fragrance compounds for private-label development. Clean-label positioning here depends on Grasse-origin claims and carbon-14 verification, particularly in French and adjacent European markets.
- Home Users:Direct purchasers through e-commerce and specialty retail.
- Wellness Centers:Service providers integrating natural fragrances into therapeutic protocols.
Manufacturers anchor procurement volume, with retail brands expanding most quickly as direct-to-consumer channels mature.
Distribution Channel:
Supply concentration in heritage extraction clusters shapes how channels capture value from provenance verification versus volume throughput.
- Online Retail:Direct-to-consumer platforms enabling provenance storytelling and subscription models. Niche perfumers and wellness brands leverage this channel to bypass mass-market margin compression, particularly for biotech-derived rare compounds.
- Specialty Stores:Boutique retail formats emphasizing traceability credentials and extraction heritage. Grasse-based houses concentrate here, capturing premium pricing through immersive origin narratives and limited-batch releases.
- Supermarkets:Mass-market volume channels for personal care and home care.
- Direct Sales:B2B procurement relationships with extraction houses and biotech suppliers.
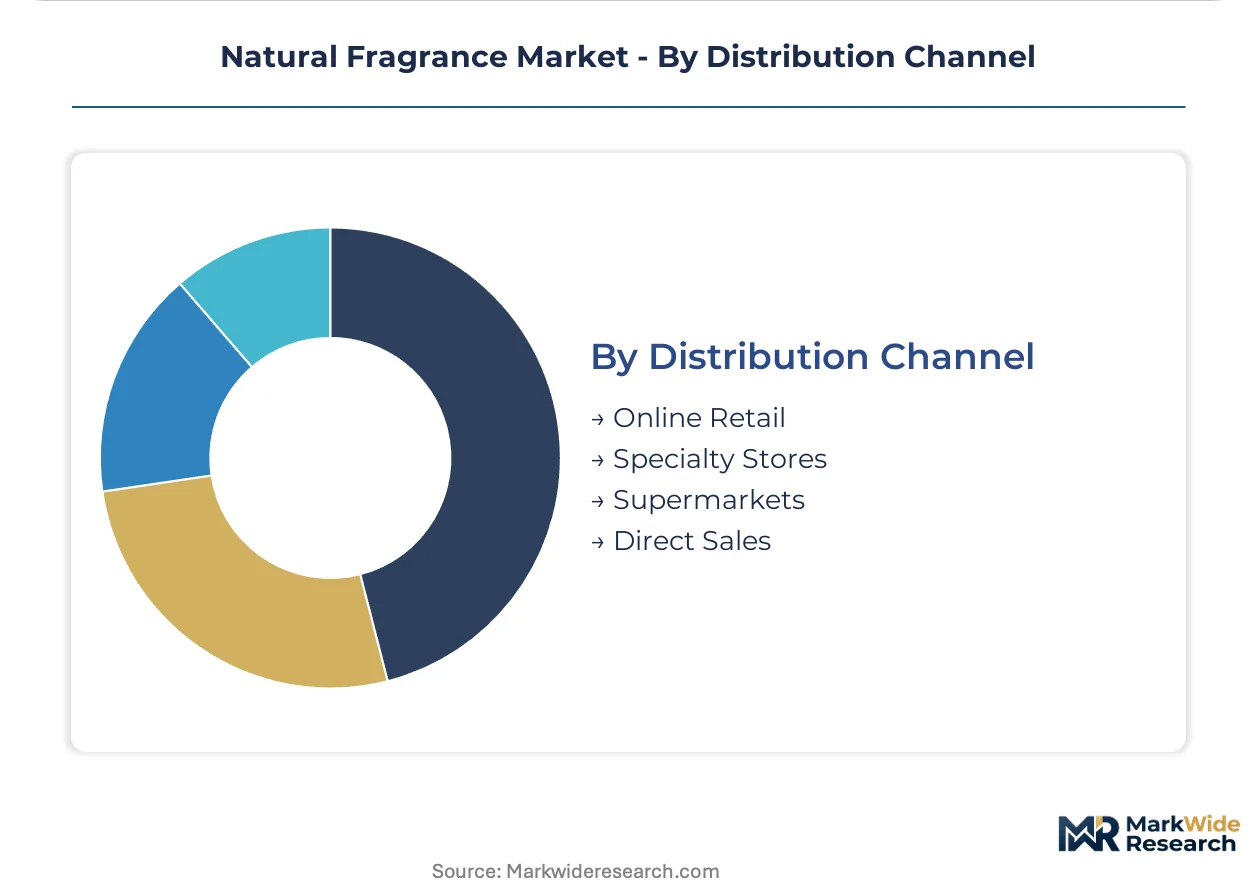
Supermarkets move the highest absolute volume, with online retail expanding most steeply as digital-native brands enter the segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grasse-trained perfumers and extraction specialists concentrate in Southern France, anchoring global supply of heritage-method botanicals. Biotechnology fermentation talent clusters in Basel and Boston, driving microbial aroma innovation. Regulatory chemists and compliance officers populate Brussels and Washington, shaping qualification standards.
France
Fine fragrance houses in Paris and Grasse drive ISO 9235-certified extract procurement for luxury positioning. REACH and EU Green Deal mandates compress synthetic thresholds, redirecting formulation budgets toward botanical inputs. The Grasse extraction cluster dominates traditional distillation and enfleurage methods, commanding traceability premiums.
Germany
Personal care manufacturers in Hamburg and Düsseldorf accelerate clean-label reformulation ahead of ECHA restriction list expansions. The country's national chemical regulator enforces stringent analytical thresholds for natural labeling claims. Bavaria-based biotechnology firms develop microbial aroma production platforms, bypassing agricultural yield constraints.
United States
Mass-market personal care brands in New York and California displace synthetic fragrance systems with certified natural alternatives. FDA labeling requirements define natural claim boundaries, though less prescriptively than European frameworks. The Pacific Northwest hosts emerging precision fermentation facilities for rare compound production.
Japan
Cosmetic formulators in Tokyo and Osaka prioritize carbon-14 verified extracts for premium skincare positioning. METI guidelines on sustainable chemical manufacturing nudge procurement toward plant-derived inputs. The Kansai region concentrates traditional extraction expertise for high-end fragrance applications.
India
Essential oil distillers in Uttar Pradesh and Karnataka supply commodity-grade botanicals for global personal care supply chains. BIS standards on natural product labeling gain enforcement traction, elevating documentation requirements. The Kannauj heritage cluster sustains traditional attar production methods for niche export markets.
Natural Fragrance Market Vendor Landscape
Top-tier vendors anchor premium extraction and biotechnology tiers, while mid-scale specialists occupy regional supply niches. The market exhibits consolidated leadership in heritage Grasse extraction and Swiss-German biotechnology, with fragmented competition in commodity essential oils. Three archetypes dominate: captive botanical sourcers with tropical origin control, precision fermentation platforms decoupling from agriculture, and heritage extraction houses leveraging traceability credentials. M&A activity concentrates on biotechnology capability acquisition, while capacity expansion focuses on fermentation infrastructure.
Among Swiss-French heritage houses, Givaudan SA and Firmenich SA exemplify the captive sourcing archetype through controlled botanical supply chains. Symrise AG occupies a position representing biotechnology-derived alternatives, anchoring microbial production platforms. Robertet SA exemplifies traditional extraction specialization, sustaining Grasse-method heritage while competing on batch-level traceability systems.
| Leading Market Players |
|---|
| Symrise AG |
| Robertet SA |
| International Flavors & Fragrances Inc. |
| Mane SA |
| T. Hasegawa Co., Ltd. |
| Givaudan SA |
| Sensient Technologies Corporation |
| CPL Aromas |
| Firmenich SA |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between ISO 9235-verified extracts and commodity essential oils manifests in both pricing power and supply chain sourcing patterns, with REACH-mandated synthetic displacement compressing tolerance for undifferentiated botanical inputs across European personal care formulators.
Pricing Analysis
Unbundled carbon-14 testing and traceability documentation now command separate fees from base extract pricing, while bundled heritage-method contracts from Grasse houses capture premium positioning through provenance storytelling. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with personal care manufacturers showing highest price sensitivity as reformulation timelines compress. Pricing pressure stems from biotechnology scale-up costs delaying cost parity with conventional extraction, though fine fragrance houses absorb premiums for batch-level origin verification.
Supply Chain Analysis
EU Green Deal domestic-content preferences and emerging BIS enforcement in India are reshaping sourcing patterns toward verifiable origin documentation. Supply concentrates in France for heritage extraction, Madagascar and Haiti for captive botanical sourcing, and Germany for fermentation platforms. Raw material dependencies include sandalwood biomass, jasmine harvests, and microbial feedstocks for precision fermentation. Single-source vulnerability runs through Grasse distillation expertise concentrated in fewer than a dozen heritage houses. Distribution runs through direct B2B procurement with extraction houses, bypassing commodity traders for certified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The natural fragrance market functions as a stable compounder, with regulatory tightening on synthetic thresholds generating predictable procurement shifts toward botanical and biotech alternatives across each reformulation cycle.
For Market Incumbents: Deepen captive botanical sourcing in tropical origins to secure rare raw material pipelines against climate-driven harvest volatility. Expand fermentation capacity in Basel-adjacent biotechnology clusters before scale-up costs erode first-mover margins. Biotechnology-derived alternatives threaten traditional extraction premiums, requiring incumbents to anchor heritage-method differentiation through immersive provenance narratives. For New Entrants and Emerging Players: Enter via home care aromatherapy applications, where herbal blend penetration lags personal care certification intensity. Target wellness-oriented direct-to-consumer channels with subscription-format ambient scenting products, bypassing mass-market margin compression. A go-to-market angle emphasizing carbon-14 verified transparency captures price-insensitive segments in specialty retail. For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation platforms lack downstream brand relationships to monetize microbial aroma production. Five-to-ten year viability favors biotech-naturals specialists with strain development moats and offtake agreements with fine fragrance houses. Acquisition targets include precision fermentation startups with validated sandalwood or musk alternatives. Watch for ECHA restriction list expansions triggering preemptive portfolio reformulation as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Botanical Sourcing Expansion | Secures Madagascar and Haiti supply corridors against harvest volatility for Givaudan-type positioning. |
| Precision Fermentation Scale-Up | Decouples rare compound production from agricultural land use, anchoring Symrise-type biotechnology margins. |
| Blockchain Traceability Integration | Enables batch-level origin verification demanded by REACH-compliant European retail brands. |
| Grasse Heritage Certification | Commands measurable price premiums through enfleurage-method provenance claims in fine fragrance. |
| Direct-to-Consumer Channel Development | Bypasses supermarket margin compression for niche perfumers with subscription wellness formats. |
Methodological Framework
Coverage spans France, Germany, the United States, Japan, and India, with primary inputs from each market's extraction houses, personal care formulators, and biotechnology developers. Primary interviews combined fragrance house procurement directors, Grasse extraction specialists, regulatory affairs leads at European personal care manufacturers, and precision fermentation R&D heads with secondary validation from ECHA restriction candidate lists, REACH authorization databases, BIS natural product standards, and customs trade data for essential oil flows. Bottom-up volume modeling and top-down value triangulation anchored segment-level outputs.
Rate-of-change decomposition across the analysis window isolated volume drivers from price effects, with CAGRs derived from segment-level trend extrapolation moderated by regulatory timeline assumptions. Segmentation dimensions modeled include extraction method, certification tier, end-use application, and buyer archetype. Industry-specific inputs incorporated ECHA restriction list expansion schedules, EU Green Deal chemical sustainability target trajectories, and biotechnology fermentation yield improvement curves.
Inputs from extraction house production records and personal care brand procurement disclosures were available through the study window; gaps in early-stage fermentation facility capacity data introduce uncertainty bands around biotechnology-derived supply forecasts. Forecasts reflect documented assumptions on regulatory enforcement intensity and reformulation timeline adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Wax Melts Market
Fragrances & Perfumes
Global Fragrance Market
Fragrances & Perfumes
GCC Perfume Market
Fragrances & Perfumes
Home Fragrance Market
Fragrances & Perfumes
Home Fragrance Diffusers Market
Fragrances & Perfumes
Clean Perfume Market
Fragrances & Perfumes
Global Luxury Perfumes Market
Fragrances & Perfumes
Floral Water Spray Market
Fragrances & Perfumes
Evaporative Diffusers Market
Fragrances & Perfumes
Digital Fragrance Market
Fragrances & Perfumes
Mini Refillable Perfume Bottles Market
Fragrances & Perfumes
Fragrance Oil Market
Fragrances & Perfumes
Middle East Fragrances Market
Fragrances & Perfumes
Gulf Cooperation Council Fragrance and Perfumes Market
Fragrances & Perfumes
Gourmand Fragrance Market
Fragrances & Perfumes
Reed Diffusers Market