
 Mini Refillable Perfume Bottles Market | 2026-2036
Mini Refillable Perfume Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Mini Refillable Perfume Bottles Market Foresight
Multi-source procurement for atomizer mechanisms is shifting toward vertically integrated European glassworks. Coty Inc. leverages captive mold-making facilities to compress prototyping cycles. Shiseido anchors its refillable line through dedicated travel-retail partnerships in Asia. Chanel differentiates via proprietary pump-engine designs that resist leakage under cabin pressure.
Mini refillable perfume bottles are portable fragrance vessels, typically 5–50 milliliters in capacity, engineered with borosilicate or soda-lime glass bodies and precision-molded polymer or metal closures to enable repeated decanting without degradation of volatile compounds. Their commercial purpose centers on brand extension, sample conversion, and circular economy compliance within prestige beauty. Glass dominates material value pools due to chemical inertness and premium tactile properties, while plastic variants capture volume in mass-market trial formats. Spray closures command the widest application breadth across gendered and unisex lines, though roll-on formats occupy growing niches in oil-based and alcohol-free fragrance segments.
REACH governs substance restrictions across EU-sold atomizer components, while FDA oversight applies to fragrance-contact materials in US distribution channels. France's national environmental agency enforces extended producer responsibility quotas that push brands toward refillable architectures. Stakeholders must track evolving substance bans and packaging recovery mandates to secure market access and avoid reformulation costs.
Market Dynamics
REACH substance restrictions are forcing glassworks and polymer suppliers to requalify atomizer materials, compressing supplier qualification timelines and reshaping procurement patterns across European manufacturing footprints.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility quotas in France and Germany are mandating refillable architectures, creating regulatory pull for circular bottle designs.
- Travel retail channel expansion:Airport duty-free operators are dedicating shelf space to refillable formats, converting transient travelers into repeat purchasers.
- Borosilicate glass thermal stability:Superior chemical inertness enables repeated alcohol exposure without degradation, supporting premium brand positioning.
Market Restraints
- Precision mold cost volatility:CNC-machined steel molds for atomizer mechanisms require specialized European tooling houses, creating input cost concentration.
- Substitution by solid fragrance formats:Alcohol-free balm and wax alternatives eliminate leakage risk entirely, capturing trial-oriented consumers.
- REACH substance restriction timelines:ECHA's evolving restricted substance lists force reformulation of polymer seals and metal springs mid-production cycle.
Strategic Opportunities
- Underpenetrated US prestige retail:Department store fragrance counters have minimal refillable inventory versus European equivalents, representing white space.
- Subscription fragrance services:Direct-to-consumer decanting platforms require bulk-compatible mini bottles, creating channel-specific demand.
- Dual carbon goals in China:NMPA-aligned sustainable packaging incentives are opening procurement pathways for compliant European glass suppliers.
Industry Challenges
- Atomizer engineer talent scarcity:Precision micro-pump design requires rare cross-disciplinary expertise spanning fluid dynamics and cosmetic chemistry.
- Multi-jurisdiction certification lag:Simultaneous FDA fragrance-contact approval and REACH substance compliance extends go-to-market timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini Refillable Perfume Bottles Market |
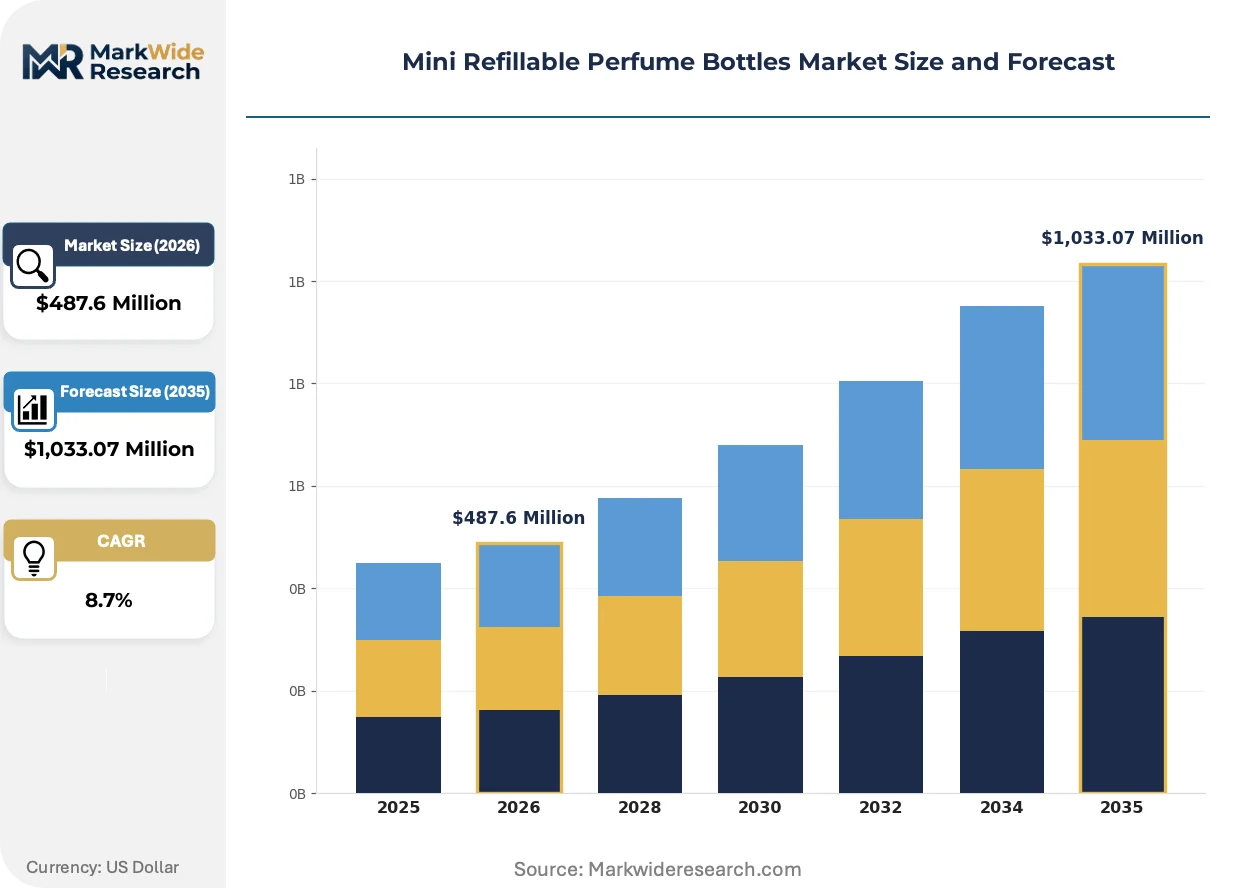
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Plastic, Metal, Crystal Size: 10ml, 20ml, 30ml, 50ml Closure Type: Screw Cap, Spray, Roll-On, Flip Top Target Audience: Women, Men, Unisex, Professionals |
| Companies Covered | Coty Inc., Shiseido, L'Oreal, Gucci, Revlon, Estée Lauder, Chanel, Avon Products, Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini Refillable Perfume Bottles Market Shifts & Advancements
Material science advances and regulatory pressure are converging to transform how refillable vessels are engineered, sourced, and brought to market across prestige and mass-tier segments.
Interchangeable pump-head architectures are modularizing the interface between glass body and atomizer mechanism. Travel retail operators are piloting these systems to reduce SKU complexity. This modularity is modularizing supply chains, allowing brands to source bodies and closures from separate qualified suppliers.
France's ANSM is tightening post-market surveillance of fragrance-contact materials, extending testing requirements to secondary packaging components. Manufacturers must now document migration profiles for polymer seals under accelerated aging protocols. Prestige houses with captive glassworks are absorbing these compliance costs more readily than contract-dependent competitors.
Corporate gifting procurement is consolidating toward certified sustainable packaging. Hospitality groups and airline amenity programs now specify refillable formats with documented circularity credentials. This specification shift is most visible in Dubai and Singapore, where luxury hotel chains are replacing disposable vials with branded refillable vessels.
Mini Refillable Perfume Bottles Market Segmentation
Segmentation in mini refillable perfume bottles reveals divergent margin structures across material tiers and closure technologies. Material selection governs regulatory compliance pathways, while closure type determines channel applicability from travel retail to subscription services.
Material:
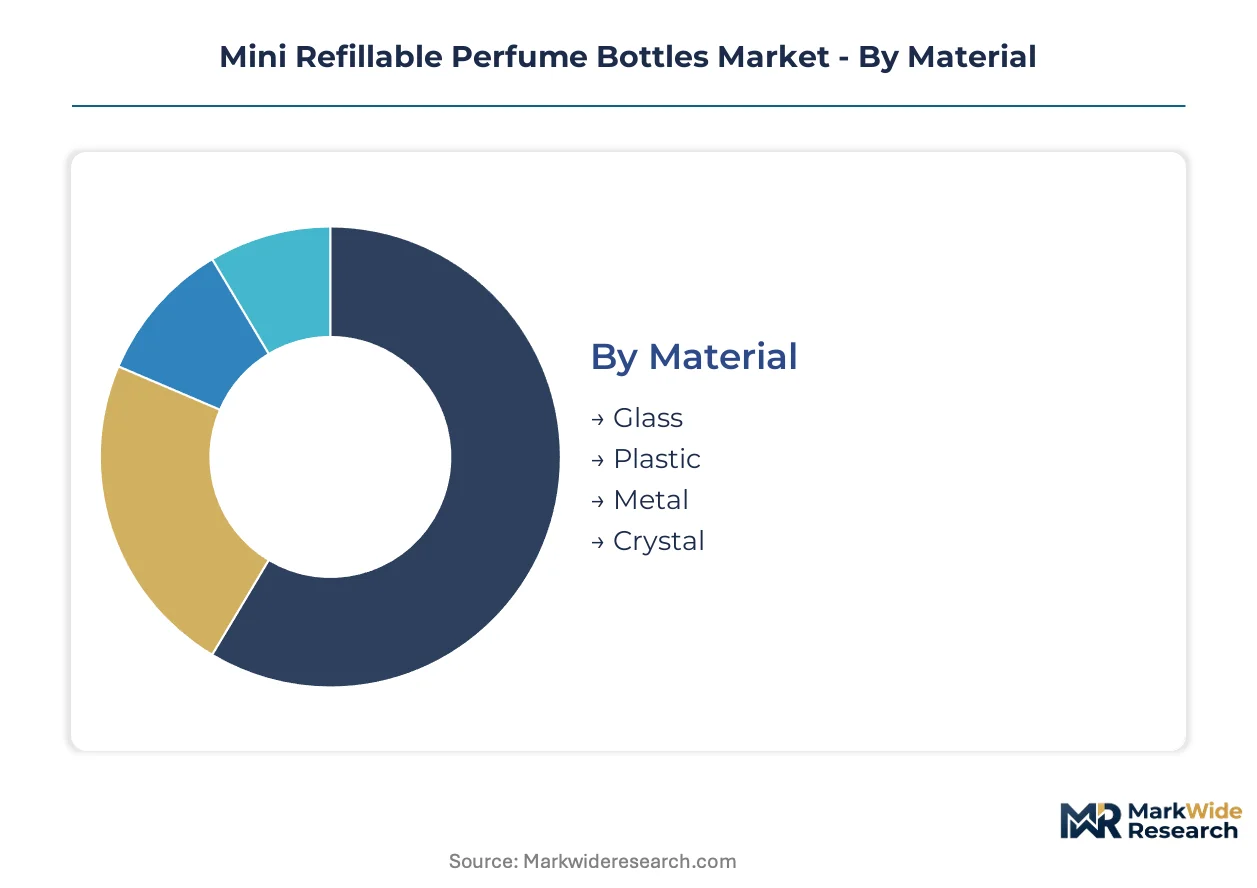
Glass commands premium positioning against plastic's mass-market volume dominance, with metal and crystal occupying specialized niches.
- Glass:Borosilicate and soda-lime formulations provide chemical inertness against alcohol-based fragrances. Heritage houses in France specify borosilicate for circular packaging programs requiring repeated thermal sterilization cycles.
- Plastic:PET and PP variants reduce unit costs for trial-format distribution. REACH substance restrictions on polymer seals are forcing requalification of plastic atomizer assemblies across European manufacturing footprints.
- Metal:Aluminum bodies serve luxury travel retail channels with lightweight durability. Cabin pressure compatibility requirements favor metal closures for airline amenity programs.
- Crystal:Lead-free crystal variants target corporate gifting procurement with documented sustainability credentials.
Mature deployment sits with Glass. Newer deployment is concentrated in Plastic.
Size:
Capacity selection maps directly to use-case economics, with smaller formats enabling trial conversion and larger vessels supporting subscription replenishment models.
- 10ml:Pocket-sized formats dominate airport duty-free impulse purchases. Shiseido's travel-retail partnerships in Asia anchor demand for this capacity tier.
- 20ml:The standard refillable format balances portability with sufficient volume for multi-week travel. Coty Inc. leverages captive mold-making to compress prototyping cycles for this mid-range segment.
- 30ml:Extended-stay formats capture business traveler segments in Dubai and Singapore luxury hotel chains.
- 50ml:Near-full-size refillables approach standard bottle economics while maintaining circular packaging compliance.
Volume concentration favors 20ml. Steepest expansion trajectory is visible in 10ml.
Closure Type:
Mechanism selection determines leakage risk profiles and regulatory testing burdens across fragrance-contact material approvals.
- Screw Cap:Simple threaded closures minimize mechanical failure points for oil-based fragrance lines. Roll-on format growth in alcohol-free segments is displacing screw cap share in niche applications.
- Spray:Precision pump mechanisms command widest application breadth across gendered and unisex lines. Chanel's proprietary pump-engine designs resist leakage under cabin pressure, differentiating this segment.
- Roll-On:Ball-bearing applicators serve oil-based and alcohol-free fragrance segments with reduced evaporation rates. ANSM's tightened post-market surveillance extends testing requirements to these secondary packaging components.
- Flip Top:Hinged closures target mass-market trial formats with single-hand operability.
Established architecture centers on Spray. Emerging adoption concentrates in Roll-On.
Target Audience:
Gendered positioning and professional segmentation dictate distribution channel selection and pricing architecture.
- Women:Heritage fragrance houses pilot circular packaging programs through female-skewed SKU lines. Extended producer responsibility quotas in France push refillable architectures most aggressively in this segment.
- Men:Solid fragrance substitution is capturing trial-oriented male consumers with alcohol-free balm alternatives.
- Unisex:Modular pump-head architectures reduce SKU complexity for travel retail operators serving diverse passenger demographics.
- Professionals:Corporate gifting procurement specifies refillable formats with documented circularity credentials for hospitality and airline amenity programs.
Current revenue weight rests with Women. Fastest share gain is occurring in Professionals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Borosilicate glass feedstock from German industrial zones anchors European manufacturing, while Asian polymer clusters supply precision-molded atomizer components to prestige houses worldwide.
France
Heritage fragrance houses pilot circular packaging programs through refillable architectures. ANSM enforces extended producer responsibility quotas that mandate reusable vessel designs. Paris and Grasse concentrate glassworks operations where captive mold-making facilities compress prototyping cycles for luxury brands.
Germany
REACH substance restrictions force glassworks and polymer suppliers to requalify atomizer materials mid-production. ECHA's evolving restricted substance lists govern fragrance-contact polymer seals. Bavaria's precision tooling houses supply CNC-machined steel molds for atomizer mechanisms, creating input cost concentration.
United States
Department store fragrance counters carry minimal refillable inventory versus European equivalents, representing white space for prestige retail expansion. FDA oversight applies to fragrance-contact materials in distribution channels. California's sustainability procurement mandates push hospitality groups toward certified refillable formats.
China
NMPA-aligned sustainable packaging incentives open procurement pathways for compliant European glass suppliers. Dual carbon goals accelerate domestic demand for circular bottle designs. Yangtze River Delta manufacturing clusters produce PET and PP variants for mass-market trial formats.
Japan
Shiseido anchors refillable lines through dedicated travel-retail partnerships across Asian airports. METI standards govern cosmetic packaging material specifications. Osaka-Kobe industrial zones concentrate precision pump-engine manufacturing for cabin-pressure-resistant atomizer designs.
Mini Refillable Perfume Bottles Market Competitive Landscape
Global majors compete with regional champions across material sourcing and atomizer engineering capabilities. The vendor base spans heritage fragrance houses with captive glassworks, contract manufacturers serving private-label programs, and specialized atomizer engineering firms. Three archetypes dominate: vertically integrated luxury houses controlling mold-to-shelf supply chains, Asian contract fabricators leveraging polymer cluster proximity, and European precision-engineering specialists. Competitive moves concentrate on backward integration into glassworks capacity and strategic partnerships with travel-retail operators.
Among heritage houses with captive manufacturing, Coty Inc., Shiseido, and Chanel occupy positions exemplifying distinct competitive vectors. Coty Inc. represents backward integration into mold-making infrastructure. Shiseido exemplifies geographic anchoring through Asia-Pacific travel-retail partnerships. Chanel occupies a position defined by proprietary engineering capabilities in pressure-resistant pump mechanisms.
| Leading Market Players |
|---|
| Coty Inc. |
| Shiseido |
| L'Oreal |
| Gucci |
| Revlon |
| Estée Lauder |
| Chanel |
| Avon Products |
| Procter & Gamble |
| Others |
Supply & Pricing Matrix
Modular pump-head architectures are reshaping cost economics by decoupling glass body sourcing from precision atomizer procurement, concentrating margin capture among European tooling houses while fragmenting supplier tiers across Germany, France, and China.
Pricing Analysis
Extended warranty coverage for cabin-pressure-resistant seals commands premium positioning in airline amenity programs, while unbundled after-sales support characterizes mass-market trial formats. Three-tier pricing structure across premium borosilicate, standard soda-lime, and economy PET tiers reflects certification grade and thermal sterilization compatibility. Cost compression in plastic atomizer assemblies is intensifying because REACH substance restrictions force mid-cycle polymer requalification. Mass-market retailers exhibit acute price sensitivity versus heritage houses absorbing compliance costs through captive glassworks.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore coordinate hub-and-spoke patterns for atomizer components, feeding assembly operations across European and Asian manufacturing footprints. German borosilicate feedstock, Japanese precision pump-engine manufacturing, and Chinese PET molding clusters anchor upstream capacity. Raw material dependencies encompass CNC-machined steel molds, fragrance-contact polymer seals, and aluminum closure alloys. Single-source vulnerability concentrates in Bavaria's specialized tooling houses for atomizer mechanisms. Distribution runs through travel-retail operators and direct-to-consumer decanting platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-side scarcity in precision micro-pump engineering sustains pricing power for incumbents controlling captive mold-making infrastructure, while atomizer talent shortages constrain capacity expansion across European manufacturing zones.
For Market Incumbents: Anchor market position through backward integration into borosilicate glassworks capacity in France and Germany, securing thermal sterilization cycle compliance for circular packaging mandates. Solid fragrance substitution threatens trial-format volumes; counter through proprietary pump-engine R&D resisting leakage under cabin pressure. Prioritize certification investment for REACH-aligned polymer seals ahead of ECHA restriction timelines. For New Entrants and Emerging Players: Travel-retail operators represent the most penetrable channel archetype for modular pump-head architectures, given SKU complexity reduction mandates across Dubai and Singapore airport duty-free networks. Target US department store fragrance counters with minimal refillable inventory versus European equivalents. Pursue direct-to-consumer decanting platform partnerships requiring bulk-compatible 10ml and 20ml formats. For Investors and Strategic Acquirers: Re-rating potential sits with European precision-engineering specialists possessing cross-disciplinary fluid dynamics and cosmetic chemistry expertise, given atomizer engineer talent scarcity and extended go-to-market timelines from multi-jurisdiction certification lag. Long-term viability hinges on 5-10 year regulatory compliance moats rather than volume scale. Monitor ANSM post-market surveillance enforcement intensity as inflection indicator for compliance cost absorption capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glassworks | Coty Inc.'s captive mold-making facilities compress prototyping cycles for 20ml formats. |
| Travel-Retail Partnership Expansion | Shiseido's Asia-Pacific airport anchoring converts transient travelers into repeat purchasers. |
| Proprietary Pump-Engine Development | Chanel's cabin-pressure-resistant designs differentiate against leakage risk in airline programs. |
| REACH Compliance Pre-Investment | Early polymer seal requalification ahead of ECHA timelines avoids mid-production reformulation costs. |
| Subscription Channel Alignment | Bulk-compatible mini bottle formats capture direct-to-consumer decanting platform demand. |
Research Methodology
Independent corroboration across fragrance house supply chain executives, precision tooling house technical directors, and travel-retail procurement managers underwrites the qualitative findings. Primary fieldwork encompassed glassworks operations managers, polymer seal compounders, and airline amenity program specifiers. Secondary validation drew from ECHA substance restriction databases, ANSM post-market surveillance filings, and EU Green Deal packaging mandate documentation. Bottom-up volume builds across material tiers and closure types triangulated against top-down market sizing from customs trade flows and prestige beauty sector reports.
Historical reference periods spanning pre-pandemic travel retail volumes through post-recovery duty-free expansion anchored the forecast window. The analytical framework modeled segmentation across material composition, capacity tier, closure mechanism, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume projections incorporating REACH compliance cost pass-through assumptions. Industry-specific inputs included atomizer engineer wage inflation indices and borosilicate glass feedstock price volatility from German industrial zone output data.
Caveats apply where ECHA substance ban acceleration or ANSM testing requirement extensions could materially shift the outlook. Forecasts reflect documented assumptions regarding travel retail channel recovery trajectory and circular packaging mandate enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Evaporative Diffusers Market
Fragrances & Perfumes
GCC Perfume Market
Fragrances & Perfumes
Organic Perfumes Market
Fragrances & Perfumes
Global Perfume Market
Fragrances & Perfumes
Clean Perfume Market
Fragrances & Perfumes
Global Luxury Perfumes Market
Fragrances & Perfumes
Home Fragrance Market
Fragrances & Perfumes
Reed Diffusers Market
Fragrances & Perfumes
Fragrance Emulsion Market
Fragrances & Perfumes
Scented Oil Market
Fragrances & Perfumes
Gulf Cooperation Council Fragrance and Perfumes Market
Fragrances & Perfumes
Fragrance Oil Market
Fragrances & Perfumes
Floral Water Spray Market
Fragrances & Perfumes
UAE Perfume Market
Fragrances & Perfumes
Fragrance Product Market
Fragrances & Perfumes
Digital Perfume Market