
 GCC Perfume Market | 2026-2036
GCC Perfume Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Perfume Market Intelligence
ESMA fragrance certification is unwinding competitive access across the GCC, forcing smaller houses to invest in compliant laboratories or exit. Rasasi Perfumes leverages vertical integration from raw oud sourcing to retail packaging, sustaining margin control through captive distillation in Dubai. Abdul Samad Al Qurashi anchors its position through generational brand equity in oud and musk traditions, while Ajmal Perfumes competes via aggressive geographic expansion into secondary Saudi cities. Arabian Oud Company dominates the gift-box segment through duty-free exclusivity agreements.
GCC perfume encompasses concentrated fragrance oils, alcohol-based eaux de parfum, and water-based mists formulated typically at 15-30% aromatic compound concentration for thermal stability in arid climates. The category serves personal adornment, social gifting rituals, and religious observance across Gulf societies. Oriental and woody fragrance types lead volume due to cultural affinity for oud, amber, and sandalwood accords, while unisex customer segments grow fastest as gender-fluid marketing gains traction in UAE and Kuwait. Luxury price ranges capture disproportionate margin pools, though mass-tier distribution through supermarket channels extends volume reach for multinational houses.
SFDA oversight of cosmetic safety assessments in Saudi Arabia, ESMA allergen disclosure mandates in the UAE, and GSO harmonization efforts across Gulf states collectively elevate compliance costs for new market entrants. These frameworks advantage established players with in-house regulatory affairs teams and certified testing partnerships. Stakeholders must monitor evolving halal certification standards for alcohol-free alternatives and assess whether local production incentives in Saudi Vision 2030 reshape supply chain geography.
Market Dynamics
ESMA's allergen disclosure mandates and SFDA cosmetic safety protocols are forcing GCC fragrance houses to rebuild formulation pipelines around certified testing infrastructure, compressing margins for non-compliant entrants while rewarding vertically integrated players with captive laboratory capacity.
Growth Catalysts
- Religious observance patterns:Ramadan and Eid gifting cycles sustain concentrated demand spikes for oud-based gift sets across Saudi Arabia and the UAE, with duty-free corridors capturing premium spend from returning pilgrims.
- SFDA cosmetic safety assessments:Saudi Arabia's tightened halal certification pathways for alcohol-free alternatives are accelerating reformulation investments by multinational houses seeking access to conservative consumer segments.
- Water-based mist technologies:Thermal-stable formulations at 15-30% aromatic concentration address arid climate performance gaps, expanding wearable fragrance occasions beyond traditional oil-based applications.
Market Restraints
- Agarwood supply concentration:Wild oud sourcing from Southeast Asian forests faces export quota restrictions and sustainability scrutiny, elevating raw material cost volatility for GCC distillers dependent on imported resin.
- Allergen labeling compliance:ESMA's expanded disclosure requirements for fragrance sensitizers impose fixed laboratory certification costs that disproportionately burden small-batch artisan houses lacking in-house testing partnerships.
- Synthetic oud substitution:Biotech-derived aroma molecules from European specialty chemical suppliers threaten premium positioning of natural oud extracts in mass-market price tiers.
Strategic Opportunities
- Kuwait's underserved mall networks:Secondary retail expansion beyond Dubai and Riyadh corridors offers first-mover positioning in high-disposable-income households with limited local fragrance brand penetration.
- Gender-fluid marketing convergence:Unisex fragrance positioning aligns with evolving social norms in UAE and Kuwait consumer segments, opening SKU rationalization and margin expansion pathways.
- Saudi Vision 2030 local production incentives:Domestic manufacturing subsidies and import substitution policies invite supply chain relocation from Dubai free zones to Jeddah industrial clusters.
Industry Challenges
- Regulatory affairs talent scarcity:GCC fragrance houses face acute shortages of professionals fluent in ESMA, SFDA, and GSO harmonization protocols, delaying product registration timelines by 8-14 months.
- Legacy distributor integration:Family-owned retail networks across the Gulf resist digital inventory management systems, complicating real-time demand forecasting for multinational brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Perfume Market |
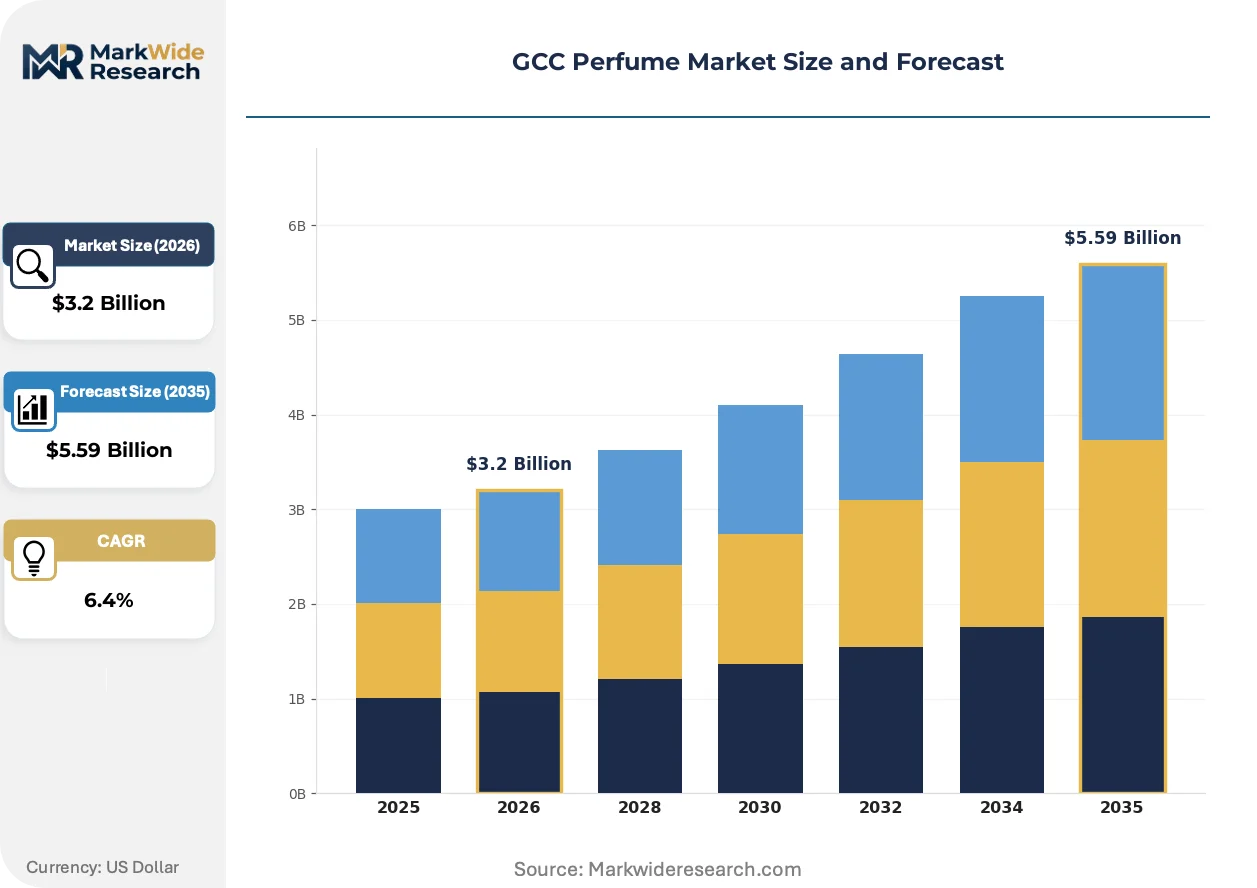
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fragrance Type: Floral, Woody, Oriental, Fresh Customer Type: Women, Men, Unisex, Children Price Range: Luxury, Premium, Mass, Economy Distribution Channel: Online, Specialty Stores, Department Stores, Supermarkets |
| Companies Covered | Rasasi Perfumes, Abdul Samad Al Qurashi, Procter & Gamble, Coty, Estee Lauder, L'Oreal, Arabian Oud Company, Firmenich, Ajmal Perfumes, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Perfume Market Strategic Shifts & Innovations
Formulation science and distribution architecture are diverging sharply across the GCC fragrance landscape, with technology investments clustering around climate adaptation and regulatory compliance rather than traditional scent innovation alone.
Encapsulated fragrance release systems using polymer microspheres are bifurcating the wearable perfume category. Luxury houses in Dubai are adopting these technologies for extended longevity in high-heat environments, while mass-market players lag on capex requirements. This capability gap is compressing mid-tier positioning and forcing private-label manufacturers toward commodity water-mist formulations.
ESMA's 2023 allergen disclosure expansion and parallel GSO harmonization efforts across Gulf states are mandating reformulation of legacy SKUs. Fragrance houses must now disclose 26 additional sensitizers on Arabic-English dual labels, triggering inventory write-downs of non-compliant stock. Saudi Arabia's SFDA is simultaneously requiring cosmetic safety assessments for all new fragrance introductions, extending time-to-market by four to six months for imported brands.
Direct-to-consumer sampling via social commerce platforms is displacing traditional mall-based discovery in UAE and Kuwait urban centers. Instagram and TikTok-native fragrance influencers now drive trial conversion for niche oud houses, bypassing department store concession fees. This channel shift is most visible among 25-34 year-old consumers in Dubai and Abu Dhabi, where unboxing content generates measurable foot traffic to physical flagships for full-bottle purchases.
GCC Perfume Market Segmentation
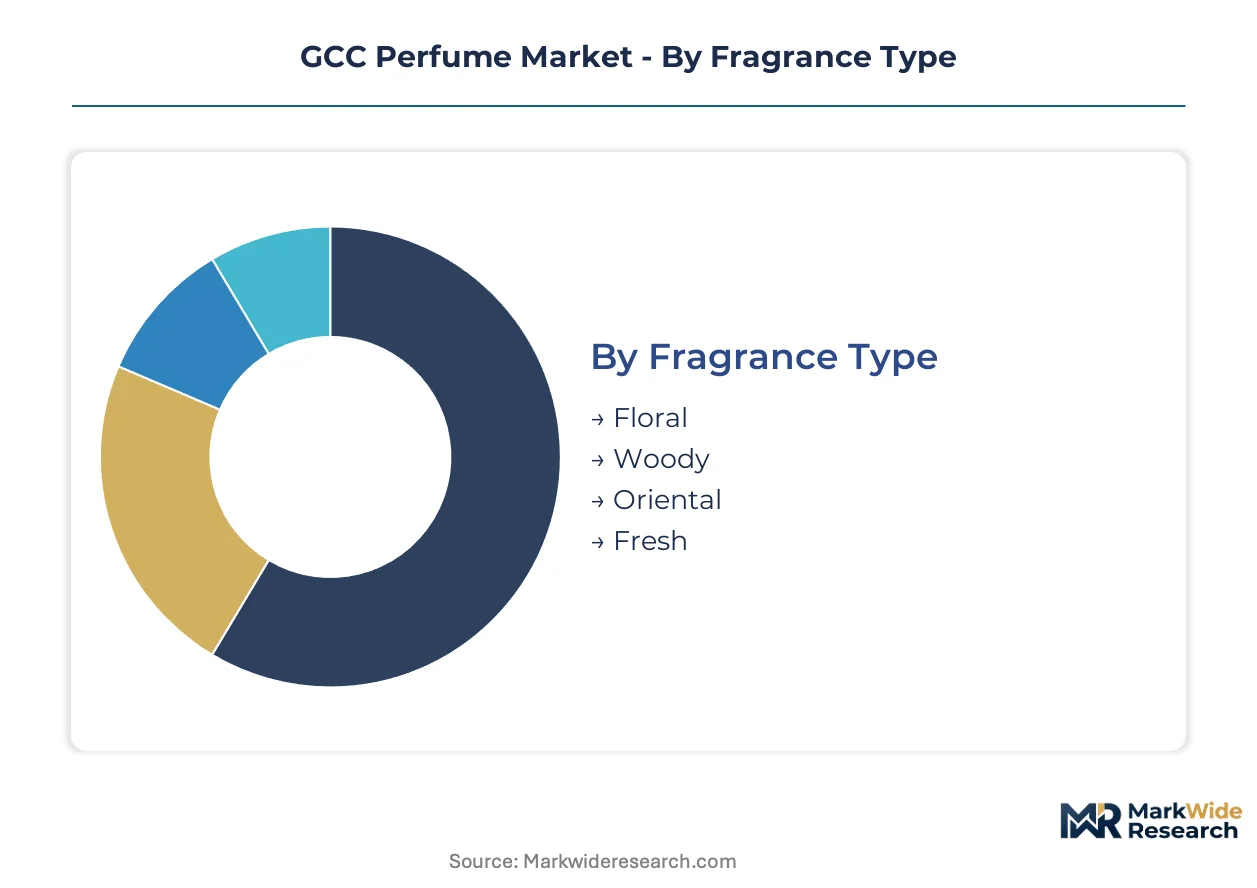
GCC perfume segmentation reveals how cultural preference, climate adaptation, and retail channel evolution create distinct margin pools. Each dimension carries unique substitution pressures from biotech alternatives, digital commerce, or regulatory compliance costs.
Fragrance Type:
Synthetic aroma molecules threaten natural extract segments unevenly, with woody and oriental categories facing the steepest biotech substitution pressure from European specialty chemical suppliers.
- Oriental:Heavy amber, musk, and spice accords formulated at 20-30% concentration dominate Saudi gifting rituals and Ramadan consumption cycles. ESMA allergen disclosure mandates are forcing reformulation of legacy ambergris and natural musk bases, compressing margins for houses lacking captive laboratory capacity.
- Woody:Oud, sandalwood, and cedar formulations anchor the premium positioning of GCC heritage houses, though wild agarwood supply quotas from Southeast Asian forests are elevating raw material cost volatility. Dubai duty-free corridors capture disproportionate revenue from oud-based gift sets purchased by returning pilgrims.
- Floral:Rose, jasmine, and white flower compositions serve daily wear occasions in UAE and Kuwait urban centers, competing against European designer imports through lighter concentration formats.
- Fresh:Citrus and aquatic notes formulated for thermal stability in arid climates represent the smallest volume pool, concentrated in water-based mist technologies for younger demographics.
Oriental anchors the volume base while unisex woody positioning gains share at the steepest rate.
Customer Type:
Gender-fluid marketing convergence is reshaping SKU economics, with unisex segments commanding premium shelf space as traditional gendered categories face rationalization pressure.
- Unisex:Gender-neutral oud and amber positioning aligns with evolving social norms in UAE and Kuwait, enabling fragrance houses to consolidate production runs and reduce inventory fragmentation. Instagram-native discovery channels drive trial conversion among 25-34 year-old consumers in Dubai and Abu Dhabi.
- Women:Floral-oriental hybrid formulations dominate personal purchase occasions across Saudi Arabia's upscale mall networks, though alcohol-free reformulations for conservative segments are extending development timelines.
- Men:Concentrated oud oils and woody eaux de parfum serve professional and social gifting contexts, with Rasasi and Abdul Samad Al Qurashi anching loyalty through generational brand equity.
- Children:Alcohol-free water-based mists at sub-15% concentration represent a nascent category, constrained by SFDA cosmetic safety assessment requirements for pediatric use claims.
Women's segments generate the largest absolute revenue while unisex positioning climbs the fastest.
Price Range:
Compliance cost concentration is compressing mid-tier positioning, as ESMA and SFDA fixed certification expenses disproportionately burden brands between mass scale and luxury margin structures.
- Luxury:Concentrated oud oils and bespoke formulations above 25% aromatic compound concentration command exclusivity through Dubai duty-free agreements and Riyadh flagship locations. Vertical integration from raw sourcing to retail packaging sustains margin control for heritage houses with captive distillation.
- Premium:Designer-branded eaux de parfum at 15-20% concentration compete through mall-based discovery in Abu Dhabi and Jeddah, facing margin pressure from social commerce displacement of department store traffic.
- Mass:Supermarket and hypermarket distribution extends volume reach for multinational houses, though synthetic oud substitution threatens differentiation in this tier.
- Economy:Private-label water-mist formulations serve price-sensitive segments in secondary Saudi cities, with minimal regulatory compliance burden due to simplified ingredient disclosure.
Luxury tiers capture disproportionate margin pools while premium positioning faces the steepest compression.
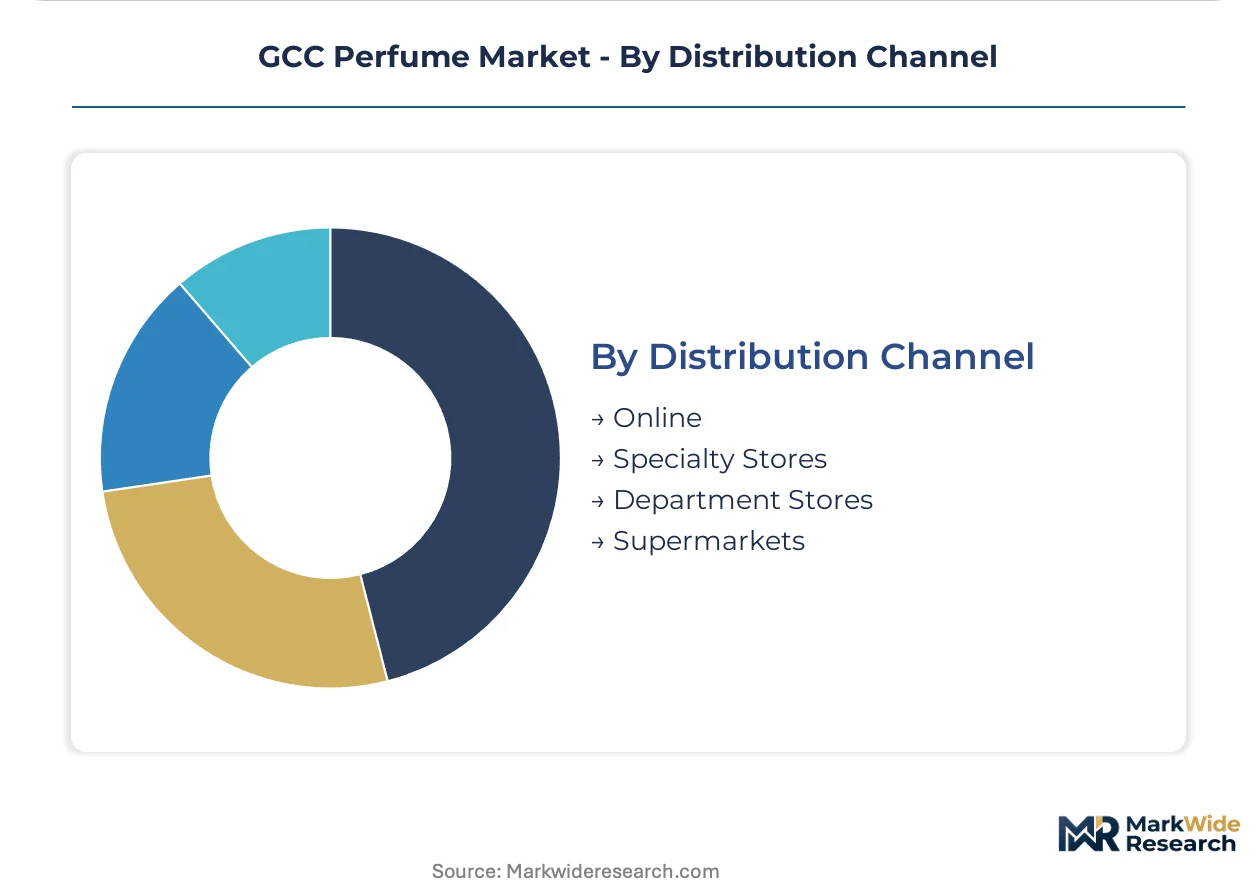
Distribution Channel:
Digital inventory management gaps in family-owned retail networks are creating fulfillment arbitrage opportunities for direct-to-native platforms.
- Specialty Stores:Dedicated fragrance boutiques in Dubai Mall and Riyadh's Kingdom Centre enable immersive oud sampling and gift-box customization, sustaining premium price realization through experiential service.
- Online:Social commerce platforms and brand-direct websites are displacing traditional discovery in UAE and Kuwait, with TikTok-native influencers driving measurable foot traffic to physical flagships for full-bottle conversion.
- Department Stores:Concession-based retail in Abu Dhabi's Yas Mall and Jeddah's Red Sea Mall faces traffic erosion from digital sampling, though remaining footfall concentrates in high-spending tourist demographics.
- Supermarkets:Mass-tier volume distribution through Carrefour and Lulu networks extends reach into Saudi secondary cities, constrained by limited shelf space for fragrance relative to personal care categories.
Specialty stores anchor premium volume while online channels expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Vision 2030 manufacturing incentives and UAE free zone infrastructure are redrawing supply chain geography across the Gulf fragrance corridor. Domestic production subsidies in Riyadh and Jeddah industrial clusters now compete with Dubai's established distillation and packaging ecosystems.
Saudi Arabia
Ramadan and Eid gifting cycles drive concentrated demand spikes for oud-based gift sets in Riyadh and Jeddah upscale mall networks. SFDA cosmetic safety assessments and tightened halal certification pathways for alcohol-free alternatives extend product registration timelines by four to six months for imported brands. The Jeddah industrial cluster attracts supply chain relocation from Dubai free zones through Vision 2030 local production incentives.
United Arab Emirates
Dubai duty-free corridors capture premium spend from returning pilgrims while Abu Dhabi and Dubai urban centers experiment with gender-fluid fragrance marketing among 25-34 year-old demographics. ESMA allergen disclosure mandates requiring Arabic-English dual labels for 26 additional sensitizers trigger inventory write-downs of non-compliant stock. Dubai Mall and Mall of the Emirates anchor specialty retail discovery through immersive oud sampling experiences.
Kuwait
Secondary retail expansion opportunities concentrate in high-disposable-income households with limited local fragrance brand penetration beyond Dubai and Riyadh corridors. MOHAP-equivalent cosmetic safety frameworks align with broader GSO harmonization efforts across Gulf states. Kuwait City mall networks remain underserved relative to UAE and Saudi retail density, offering first-mover positioning for heritage houses.
Qatar
Luxury tourism and diplomatic gift procurement sustain concentrated demand for concentrated oud oils above 25% aromatic compound concentration. National standardization bodies participate in GSO fragrance allergen harmonization initiatives. Doha retail clusters around Villaggio Mall and Pearl-Qatar marina districts emphasize experiential service for premium price realization.
Bahrain
Cross-border shopping flows from Eastern Province consumers supplement domestic demand for mid-tier eaux de parfum formulations. The national standards body implements GSO-aligned cosmetic safety protocols alongside ESMA and SFDA frameworks. Manama City Centre and Seef Mall anchor regional distribution for multinational houses targeting Saudi Arabia's secondary cities through proximity logistics.
GCC Perfume Market Key Industry Players
Listed multinational conglomerates compete with private Gulf heritage houses across formulation heritage and retail channel control. Market structure tilts toward consolidation at the luxury tier through vertical integration from raw oud sourcing to duty-free exclusivity, while mid-tier positioning fragments under compliance cost pressure. Three archetypes dominate: heritage houses with generational brand equity in oud traditions, multinational beauty conglomerates with mass-tier supermarket reach, and specialty chemical suppliers with biotech-derived aroma molecules. Competitive moves concentrate on captive laboratory certification capacity and social commerce influencer partnerships displacing department store discovery.
Among heritage specialists, Rasasi Perfumes and Abdul Samad Al Qurashi exemplify the vertically integrated archetype with backward integration into raw material sourcing and captive retail packaging operations. Ajmal Perfumes occupies a position representing geographic expansion strategies into secondary Saudi cities beyond Dubai-Riyadh corridor concentration. These private houses anchor competitive positioning through control of oud distillation supply chains rather than outsourced formulation.
| Leading Market Players |
|---|
| Rasasi Perfumes |
| Abdul Samad Al Qurashi |
| Procter & Gamble |
| Coty |
| Estee Lauder |
| L'Oreal |
| Arabian Oud Company |
| Firmenich |
| Ajmal Perfumes |
| Others |
Cost & Logistics Intelligence
Ninety-day aromatic compound inventory cycles at Dubai free-zone distillers concentrate pricing power among houses with captive agarwood reserves, while smaller blenders face margin compression from spot-market resin procurement. ESMA certification backlogs extending to fourteen months force non-compliant entrants to absorb rush-testing premiums or cede shelf space to vertically integrated competitors.
Pricing Analysis
Certification level (ESMA/SFDA-grade) creates the primary spread between luxury heritage houses and mass-market private labels. Three-tier pricing structure across premium, standard, and economy levels stratifies by aromatic concentration and halal compliance depth. Price differentiation stems from captive laboratory capacity versus outsourced testing partnerships. Cost compression in mid-tier eaux de parfum is intensifying because social commerce displaces department store concession traffic. Mass-market supermarket buyers exhibit highest price sensitivity; duty-free tourists purchasing oud gift sets show lowest.
Supply Chain Analysis
Strategic stockpiling of wild agarwood resin dominates inventory strategy among heritage houses, contrasting with just-in-time synthetic aroma molecule procurement by mass-market blenders. Raw material sourcing draws from Southeast Asian forests, European specialty chemical suppliers, and domestic Dubai distillation facilities. Agarwood supply rests on export quota restrictions from Indonesia, Malaysia, and Vietnam. Single-source vulnerability concentrates in wild oud resin channels facing sustainability scrutiny. Distribution runs through Dubai duty-free corridors, Riyadh upscale mall networks, and emerging social commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Social commerce platform economics are rewiring fragrance discovery in UAE and Kuwait, creating interoperability between TikTok-native influencer ecosystems and physical flagship conversion. This shift rewards houses that synchronize digital sampling with inventory positioning at Dubai Mall and Riyadh Kingdom Centre locations.
For Market Incumbents: Fortify captive laboratory certification capacity to compress ESMA registration timelines below competitor benchmarks. Deepen backward integration into agarwood distillation to insulate margin structures from Southeast Asian export quota volatility. Synthetic oud substitution from European biotech suppliers threatens premium positioning; counter with generational brand equity storytelling around wild resin provenance. For New Entrants and Emerging Players: Digital sampling infrastructure gaps in Kuwait's underserved mall networks offer first-mover positioning among high-disposable-income households. Secondary Saudi cities beyond Riyadh-Jeddah corridors present penetrable white space with limited heritage house presence. Pursue social commerce-native go-to-market angles leveraging unboxing content to drive measurable foot traffic to physical flagships for full-bottle conversion. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational beauty conglomerates seeking to divest non-core fragrance assets under compliance cost pressure. Long-term viability centers on houses with demonstrated ESMA/SFDA regulatory fluency and captive supply chain control. Watch for inflection when biotech-derived oud molecules achieve sensory parity with natural extracts at mass-market price points.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Laboratory Certification Investment | ESMA compliance capacity compresses rival registration timelines by 8-14 months. |
| Social Commerce Platform Integration | TikTok-native discovery channels displace department store concession economics in Dubai. |
| Backward Integration into Agarwood Sourcing | Wild resin stockpiling insulates margin structures from Southeast Asian quota volatility. |
| Unisex SKU Consolidation | Gender-fluid positioning reduces inventory fragmentation and extends production run economics. |
| Saudi Vision 2030 Manufacturing Relocation | Jeddah industrial cluster subsidies invite supply chain migration from Dubai free zones. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across fragrance house executives, regulatory affairs specialists at ESMA and SFDA, duty-free procurement managers, and social commerce platform operators. Secondary validation incorporated customs records from GCC trade authorities, GSO harmonization documentation, retail audit data from Dubai Mall and Riyadh Kingdom Centre, and SEC filings from listed multinational beauty conglomerates. Bottom-up volume modeling triangulated against top-down value estimates from aromatic compound consumption patterns.
Across the analysis window, forecasts segmented by fragrance type, customer demographic, price tier, and distribution channel. Projection mechanics combined historical consumption elasticity with regulatory event modeling around ESMA allergen disclosure expansions and SFDA halal certification pathway modifications. CAGRs derived from iterative convergence between primary interview demand indicators and secondary trade flow data.
Forecasts assume regulatory continuity in ESMA, SFDA, and GSO harmonization regimes; material policy shifts would require re-modeling around laboratory certification timelines or agarwood import restrictions. Revision becomes warranted when biotech-derived oud molecules achieve mass-market sensory parity or when Saudi Vision 2030 manufacturing subsidies materially alter supply chain geography.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Digital Scent Market
Fragrances & Perfumes
Fragrance Diffuser Market
Fragrances & Perfumes
Global Fragrance Market
Fragrances & Perfumes
Kuwait Perfume Market
Fragrances & Perfumes
Wax Melts Market
Fragrances & Perfumes
Evaporative Diffusers Market
Fragrances & Perfumes
Saudi Arabia E-Commerce Cosmetics and Fragrances Market
Fragrances & Perfumes
Scented Oil Market
Fragrances & Perfumes
Perfume Vials Market
Fragrances & Perfumes
Gulf Cooperation Council Fragrance and Perfumes Market
Fragrances & Perfumes
Global Fragrances and Perfumes Market
Fragrances & Perfumes
Natural Fragrance Market
Fragrances & Perfumes
Global Luxury Perfumes Market
Fragrances & Perfumes
Global Perfume Market
Fragrances & Perfumes
UAE Perfume Market
Fragrances & Perfumes
Mini Refillable Perfume Bottles Market