
 Clean Perfume Market | 2026-2036
Clean Perfume Market Size, Share, and Industry Trends Forecast 2026-2036
Clean Perfume Market Analysis
Biotechnology-driven ingredient synthesis is fragmenting traditional supply relationships between fragrance houses and raw material providers. Aesop leverages its vertically integrated botanical sourcing to control ingredient provenance across its retail network. Dedcool competes through water-free formulation chemistry that eliminates ethanol dependence in its product architecture. Henry Rose anchors its position with full ingredient transparency protocols that exceed prevailing disclosure norms.
Clean perfume denotes fragrance formulations excluding phthalates, parabens, synthetic musks, and formaldehyde-releasing preservatives, typically substituting these with steam-distilled essential oils, CO2 extracts, or fermented aroma molecules. These compositions serve consumers with contact dermatitis, multiple chemical sensitivities, or endocrine-disruptor concerns who retain willingness to pay premium price points. Eau de Parfum and solid perfume formats capture disproportionate margin pools as concentration and portability command pricing premiums over mass-market Eau de Toilette. Natural and organic ingredient sourcing segments attract supply-constrained premium positioning, while vegan certification creates differentiation friction against legacy houses reliant on animal-derived fixatives like ambergris or civet.
REACH in Europe mandates fragrance allergen disclosure thresholds that reshape formulation complexity and labeling costs for market entrants. The FDA in the United States maintains voluntary cosmetic ingredient review without pre-market approval, creating regulatory asymmetry that fragments compliance investment across export destinations. California's Proposition 65 warning requirements and the EU AI Act's emerging transparency obligations for algorithmic retail personalization add overlapping compliance layers. Stakeholders must monitor whether fragmented national chemical registries consolidate into mutual recognition frameworks or deepen formulation localization requirements.
Market Dynamics
Biotechnology-driven ingredient synthesis is collapsing the traditional supply chain hierarchy between fragrance houses and botanical raw material providers, forcing reformulation investments and captive sourcing decisions across the competitive landscape.
Growth Catalysts
- EU Green Deal chemical phase-outs:Mandates under REACH and the European Chemicals Strategy for Sustainability are accelerating R&D budgets toward plant-derived and biodegradable fragrance molecules, creating first-mover advantages for compliant formulators.
- Gen Z channel migration:Digital-native consumers aged 18-27 purchase clean perfume predominantly through direct-to-consumer platforms and specialty retail, compressing traditional wholesale margin structures and rewarding vertically integrated brands.
- Water-free formulation chemistry:Elimination of ethanol dependence through solid and oil-based delivery systems reduces flammability shipping classifications and opens air freight channels previously closed to liquid fragrance.
Market Restraints
- Natural ingredient supply concentration:Premium botanicals including sandalwood, rose otto, and frankincense concentrate cultivation in specific climate zones vulnerable to weather volatility and geopolitical export controls.
- Allergen disclosure cost inflation:REACH-mandated fragrance allergen labeling thresholds below 0.001% for rinse-off products multiply testing expenditures and reformulation cycles for market entrants.
- Performance-perception gap:Synthetic musk substitutes including ambrettolide and Habanolide demonstrate shorter scent longevity than nitro musks, constraining premium positioning for natural-only formulations.
Strategic Opportunities
- Fermented aroma molecule production:Precision fermentation platforms using engineered yeast strains enable biosynthesis of rare terpenes and sesquiterpenes without agricultural land use or harvest seasonality.
- South Korean regulatory alignment:MFDS cosmetic ingredient disclosure rules and K-beauty retail infrastructure create a testbed market for transparency protocols ahead of broader Asian expansion.
- California Proposition 65 warning thresholds:Preemptive compliance with the state's chemical warning requirements opens shelf placement in Sephora, Ulta, and clean beauty specialty chains that exclude non-compliant brands.
Industry Challenges
- Green chemistry talent scarcity:Formulation chemists with dual expertise in traditional perfumery and biotechnology-derived ingredient integration command premium compensation and limited availability.
- Multi-jurisdiction certification stacking:Simultaneous pursuit of COSMOS organic, Leaping Bunny vegan, and B Corp status requires parallel audit tracks with divergent documentation standards and timeline misalignment.
- Legacy fixative substitution:Replacement of animal-derived ambergris and civet with synthetic or plant-based alternatives demands extensive stability testing and consumer sensory validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean Perfume Market |
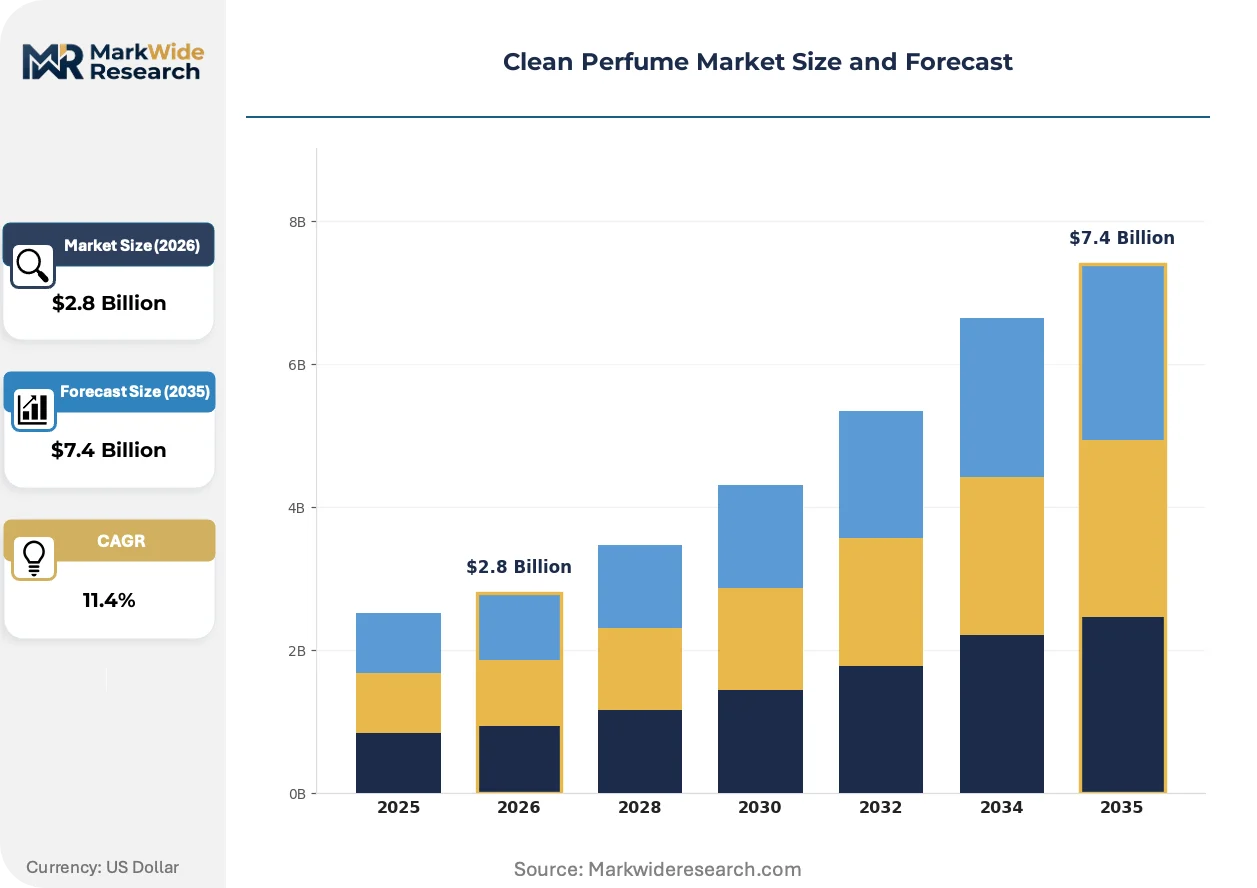
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eau de Toilette, Eau de Parfum, Solid Perfume, Roll-on Perfume Ingredient Source: Natural, Synthetic, Organic, Vegan Customer Type: Retail Consumers, Wholesale Buyers, B2B Clients, Online Shoppers Fragrance Family: Citrus, Floral, Woody, Green |
| Companies Covered | Aesop, Dedcool, Henry Rose, Vyrao, By Rosie Jane, Le Labo, Creed, Esas Organic, Chloé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean Perfume Market Emerging Trajectories
Clean perfume innovation clusters around three vectors: molecular biotechnology displacing agricultural extraction, regulatory transparency mandates reshaping competitive disclosure norms, and format innovation compressing logistics cost structures.
Precision fermentation platforms using engineered microbial strains are collapsing the cost curve for rare natural-identical molecules previously dependent on scarce botanical harvests. Niche and independent fragrance houses in France and the United States adopt these biosynthetic ingredients at accelerating pace, enabling scent profiles—sandalwood, oud, iris—that were supply-constrained and price-prohibitive under traditional cultivation. The technology is collapsing the historical distinction between "natural" and "synthetic" marketing categories, forcing brands to redefine clean credentials around carbon intensity and biodegradability rather than source origin.
REACH fragrance allergen disclosure mandates in Europe are restructuring formulation complexity and labeling obligations for all products sold in EU member states. The regulation requires identification of 82 fragrance allergens above specified thresholds, multiplying analytical testing costs and compressing permissible formulation palettes for mass-market launches. Eau de Parfum and solid perfume formats face disproportionate compliance burden due to higher concentration levels, driving some entrants to prioritize Eau de Toilette dilutions for initial European market entry.
Direct-to-consumer subscription models are displacing department store fragrance counters as the primary discovery channel for Millennial and Gen Z buyers. Clean perfume brands bypass wholesale margin structures through personalized sampling programs and algorithmic scent matching, capturing customer lifetime value data unavailable in retail environments. This channel migration is most visible in the United States, where digital-native brands leverage Instagram and TikTok for launch velocity without traditional retail gatekeeper dependence.
Clean Perfume Market Segmentation
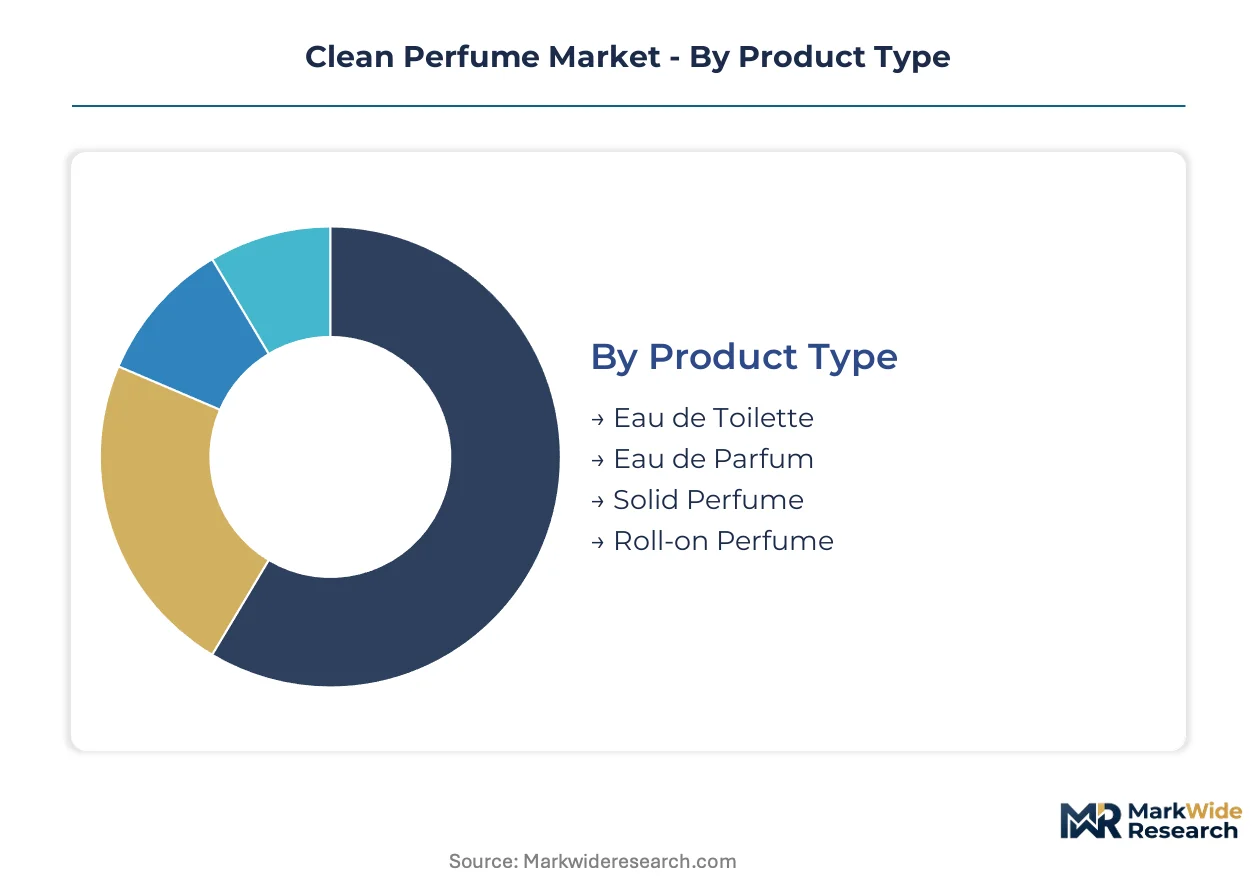
Clean perfume segmentation reveals how concentration levels, ingredient provenance, and purchase channels fragment pricing power and compliance burdens across the value chain. Understanding these divides exposes where margin pools concentrate and where regulatory costs bite deepest.
Product Type:
Mature formats dominate shelf presence while emerging delivery systems reshape logistics economics.
- Eau de Parfum:Higher fragrance oil concentration (15-20%) commands premium positioning in France and South Korea where consumers prioritize longevity. REACH allergen disclosure thresholds hit this segment hardest due to concentrated formulation complexity.
- Solid Perfume:Water-free wax or oil bases eliminate ethanol dependence, enabling air freight cost advantages and travel retail placement. Demand concentrates among Gen Z digital-native buyers seeking portability and TSA compliance.
- Eau de Toilette:Diluted formulations (5-15% oil) reduce compliance testing costs for EU market entry.
- Roll-on Perfume:Precision application format targets contact dermatitis-sensitive users with controlled dosage delivery.
Eau de Parfum handles the majority of throughput; Solid Perfume is the fastest mover on share.
Ingredient Source:
Cost tier stratification separates supply-constrained botanical positioning from scalable biotechnology alternatives.
- Natural:Steam-distilled essential oils and CO2 extracts from sandalwood, rose otto, and frankincense carry harvest volatility risk. Sourcing concentrates in India, Bulgaria, and Oman where climate vulnerability and export controls threaten consistency.
- Synthetic:Fermented aroma molecules and nature-identical compounds collapse cost curves for rare terpenes. Precision fermentation platforms using engineered yeast strains bypass agricultural land constraints entirely.
- Organic:COSMOS-certified cultivation requires multi-year farm conversion and parallel audit documentation.
- Vegan:Elimination of ambergris and civet fixatives demands extensive stability testing for synthetic substitutes.
Natural ingredients command the steepest price premiums; Synthetic biosynthesis is expanding most quickly as biotechnology matures.
Customer Type:
Channel migration patterns determine margin capture and data ownership across the purchase journey.
- Online Shoppers:Direct-to-consumer platforms enable algorithmic scent matching and subscription retention models. Gen Z and Millennial buyers in the United States drive discovery through Instagram and TikTok without retail gatekeeper dependence.
- Retail Consumers:Specialty clean beauty chains and Sephora shelf placement require California Proposition 65 compliance and full ingredient transparency protocols.
- Wholesale Buyers:Department store and duty-free channels compress margins through traditional markup structures.
- B2B Clients:Hospitality and corporate gifting segments demand bulk formulation stability and customized packaging.
Online Shoppers generate the highest customer lifetime value data; Retail Consumers remain the volume anchor for premium positioning.
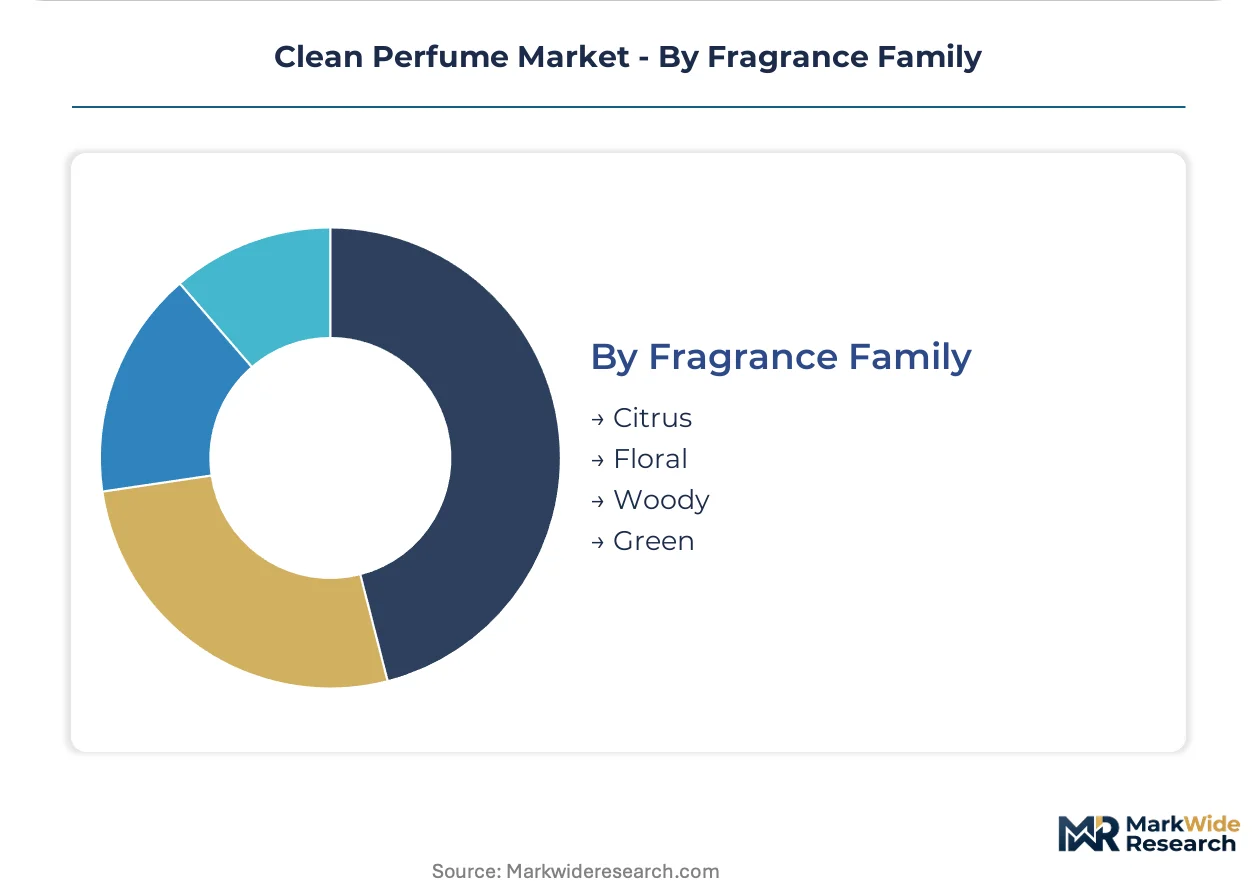
Fragrance Family:
Application context and demographic targeting fragment demand across olfactory preference clusters.
- Floral:Rose, jasmine, and neroli compositions dominate female-skewing markets in France and South Korea. Natural extraction costs for rose otto from Bulgaria concentrate supply risk.
- Woody:Sandalwood and oud profiles command masculine and unisex positioning with supply constrained to Indian and Southeast Asian cultivation zones.
- Citrus:Bergamot and grapefruit oils from Italian and Spanish groves face climate volatility.
- Green:Galbanum and violet leaf notes target niche consumers with multiple chemical sensitivities.
Floral maintains the broadest demographic reach; Woody is gaining share fastest as unisex positioning expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France, the United States, and South Korea dominate clean perfume trade flows, with formulation expertise concentrating in Paris and Grasse while California and Seoul drive retail channel innovation. Import dependency for rare botanicals creates supply vulnerability for European and Asian formulators sourcing from Indian and Middle Eastern cultivation zones.
France
Grasse-based fragrance houses and Parisian clean beauty retailers anchor European demand for Eau de Parfum concentrations. REACH fragrance allergen disclosure mandates from ECHA reshape formulation complexity for products entering EU member states. The Provence-Alpes-Côte d'Azur cluster hosts biotechnology startups developing fermented aroma molecules to bypass agricultural extraction constraints.
United States
California's clean beauty retail infrastructure and direct-to-consumer subscription models capture Millennial and Gen Z purchasing migration away from department stores. FDA maintains voluntary cosmetic ingredient review without pre-market approval, creating regulatory asymmetry with European export destinations. Los Angeles and New York Metro anchor specialty retail placement requiring Proposition 65 chemical warning compliance.
South Korea
Seoul Capital Area consumers drive K-beauty adoption of transparent ingredient protocols ahead of broader Asian market expansion. MFDS cosmetic disclosure rules create a testbed regulatory environment for clean perfume transparency standards. The Busan-Ulsan corridor supports contract manufacturing for brands targeting Asian duty-free and travel retail channels.
United Kingdom
London-based independent fragrance houses leverage Brexit-adjusted regulatory autonomy to experiment with disclosure protocols between EU REACH and US FDA frameworks. The Greater Southeast cluster concentrates specialty retail and e-commerce fulfillment infrastructure serving domestic and export demand. Manchester and Birmingham emerging as formulation R&D hubs as green chemistry talent concentrates in Northern England.
Germany
Bavaria and North Rhine-Westphalia host chemical and biotechnology firms supplying fermented aroma molecules to fragrance houses across Europe. The country's national chemical regulator enforces REACH implementation with stringent documentation requirements for market entrants. Berlin-Brandenburg attracts clean beauty startups leveraging proximity to EU regulatory expertise and Central European distribution networks.
Clean Perfume Market Vendor Landscape
On the supply side, the industry is bifurcating between legacy fragrance houses with captive raw material relationships and digitally native brands with vertically controlled botanical sourcing. Biotechnology platforms are collapsing traditional supply hierarchies, forcing established players into partnership or acquisition postures. Three strategic archetypes dominate: precision fermentation specialists, direct-to-consumer transparency brands, and heritage houses with reformulated clean portfolios. Competitive moves concentrate on captive ingredient sourcing and algorithmic retail personalization capabilities.
Within the transparency-first tier, Henry Rose exemplifies full ingredient disclosure protocols exceeding prevailing norms, while Aesop anchors vertically integrated botanical provenance control across retail networks. Dedcool occupies a position at the formulation innovation frontier with water-free chemistry eliminating ethanol dependence. These three companies represent divergent strategic bets on how clean credentials will evolve as biotechnology dissolves traditional natural-synthetic marketing boundaries.
| Leading Market Players |
|---|
| Aesop |
| Dedcool |
| Henry Rose |
| Vyrao |
| By Rosie Jane |
| Le Labo |
| Creed |
| Esas Organic |
| Chloé |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Paris air freight corridor compresses logistics economics for water-free solid perfume formats while amplifying price premiums for liquid Eau de Parfum bound for EU allergen disclosure compliance. This freight-cost asymmetry stratifies pricing power between ethanol-dependent and ethanol-free formulations, concentrating margin capture among brands with captive biotechnology sourcing.
Pricing Analysis
Retail consumers anchor a three-tier pricing structure across premium, standard, and economy levels in the clean perfume market. Price differentiation hinges on ingredient certification tier — COSMOS organic versus conventional natural — and concentration format, with solid perfumes commanding portability premiums. Pricing pressure stems from REACH-mandated allergen testing costs that compress margins for concentrated formulations. Digital-native Gen Z buyers exhibit lowest price sensitivity, while wholesale department store channels face acute margin compression.
Supply Chain Analysis
Upstream feedstock for rare botanicals draws from India, Bulgaria, and Oman, where sandalwood, rose otto, and frankincense cultivation faces climate volatility and export control exposure. Precision fermentation platforms in Germany and France now supply biosynthetic terpenes and sesquiterpenes, reducing agricultural dependency. Single-source vulnerability concentrates in Indian sandalwood harvests restricted by CITES quotas. Distribution runs through direct-to-consumer subscription channels and Sephora-led specialty retail, bypassing legacy wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The clean perfume market rewards formulators who command scarce biotechnology-chemistry hybrid expertise, while punishing brands dependent on volatile agricultural extraction without captive fermentation capacity.
For Market Incumbents: Pre-empt precision fermentation disruption by acquiring yeast-strain biotechnology platforms or exclusive licensing agreements with German and French biosynthesis specialists. Defend margin position through backward integration into sandalwood cultivation in Australia and Vanuatu, insulating against Indian supply restrictions. REACH disclosure cost inflation threatens mass-market Eau de Parfum lines; prioritize solid perfume capacity expansion to capture air freight economics and TSA-compliant travel retail placement. For New Entrants and Emerging Players: Establish a beachhead in South Korean K-beauty retail through MFDS-aligned transparency protocols, using Seoul as a testbed for Asian expansion ahead of broader regional compliance convergence. Target the roll-on precision application segment, where contact dermatitis-sensitive users accept premium pricing for controlled dosage formats. Bypass saturated US direct-to-consumer channels by partnering with clean beauty subscription boxes for algorithmic scent discovery without Instagram advertising dependency. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy fragrance houses with stranded natural-extraction assets and reformulation liabilities under EU Green Deal phase-outs. Long-term viability centers on biotechnology-derived ingredient pipelines and vertical retail data ownership. Watch for inflection when precision fermentation achieves cost parity with agricultural rose otto extraction, signaling margin structure inversion across floral fragrance families.| Strategic Initiative | Industry Significance |
|---|---|
| Fermented Aroma Molecule Production | Precision yeast platforms bypass Indian sandalwood CITES quotas and Bulgarian rose harvest volatility. |
| Water-Free Formulation Expansion | Solid and oil-based formats unlock air freight channels and TSA-compliant travel retail placement. |
| REACH Preemptive Compliance | Early 82-allergen disclosure investment secures Sephora EU shelf access ahead of enforcement waves. |
| Direct-to-Consumer Subscription Launch | Algorithmic scent matching captures Gen Z lifetime value data unavailable in wholesale channels. |
| South Korean Regulatory Alignment | MFDS transparency protocols position brands for K-beauty expansion across Asian duty-free corridors. |
Methodological Framework
Desk research of customs trade data, ECHA REACH guidance documents, and MFDS cosmetic disclosure regulations preceded structured interviews with fragrance house R&D directors, clean beauty brand founders, biotechnology platform chemists, and Sephora category buyers. Secondary validation drew from EU Green Deal policy briefs, fermentation technology patent filings, and South Korean retail audit data. Bottom-up volume modeling triangulated against top-down spending elasticity estimates across Millennial and Gen Z demographic cohorts.
Assumptions held fixed include current REACH allergen disclosure thresholds and existing CITES restrictions on Indian sandalwood exports, while variables included precision fermentation cost reduction trajectories and Gen Z channel migration velocity. The analytical framework segmented by product concentration format, ingredient provenance tier, and customer purchase channel across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves incorporating subscription retention rates and regulatory compliance cost pass-through coefficients.
Sensitivities concentrate around biotechnology scale-up timelines, EU chemical strategy acceleration, and climate volatility in Bulgarian rose otto harvest zones. Cross-checking against MFDS cosmetic registration databases and Sephora shelf-placement announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Saudi Arabia E-Commerce Cosmetics and Fragrances Market
Fragrances & Perfumes
Fragrance Oil Market
Fragrances & Perfumes
Digital Scent Market
Fragrances & Perfumes
Cosmetic and Fragrance Retail Chain Market
Fragrances & Perfumes
Evaporative Diffusers Market
Fragrances & Perfumes
Reed Diffusers Market
Fragrances & Perfumes
Fragrance Product Market
Fragrances & Perfumes
Global Fragrances and Perfumes Market
Fragrances & Perfumes
Mini Refillable Perfume Bottles Market
Fragrances & Perfumes
Saudi Arabia Perfume Market
Fragrances & Perfumes
Global Scented Candle Market
Fragrances & Perfumes
GCC Perfume and Fragrance Market
Fragrances & Perfumes
Natural Fragrance Market
Fragrances & Perfumes
Gulf Cooperation Council Fragrance and Perfumes Market
Fragrances & Perfumes
Perfume Vials Market
Fragrances & Perfumes
Home Fragrance Market