
 Global Scented Candle Market | 2026-2036
Global Scented Candle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Scented Candle Market Outlook
Single-wick unbundling from multi-candle gift sets is decoupling volume purchasing from seasonal gifting patterns. Yankee Candle Company leverages its manufacturing scale to dominate mass-market shelf space across North American retail channels. Bath & Body Works anchors its fragrance ecosystem by integrating candle releases with body care collections, sustaining repeat purchase frequency. Diptyque competes through artisan positioning and Parisian brand heritage, commanding premium price points in selective distribution.
Scented candles are fragranced solid fuel sources comprising wax substrates, aromatic compounds, and woven cotton wicks engineered for controlled combustion and olfactory diffusion; soy wax formulations typically incorporate hydrogenated soybean oil with melt points between 49°C and 82°C to optimize scent throw and burn duration. The luxury category captures disproportionate margin pools as consumers trade up for provenance narratives and limited editions, while soy wax leads material growth due to clean-label positioning displacing paraffin in health-conscious segments. Glass packaging dominates premium tiers, though metal vessels are gaining share in travel and outdoor sub-applications.
REACH in Europe and EPA indoor air quality protocols in the United States constrain volatile organic compound thresholds in fragrance loads, compelling reformulation investments and third-party certification. China's GB standards for combustion emissions and labeling requirements administered by SAMR shape market access for imported candle brands. Stakeholders must monitor evolving state-level fire safety codes and fragrance disclosure mandates to anticipate compliance cost trajectories and sourcing flexibility requirements.
Market Dynamics
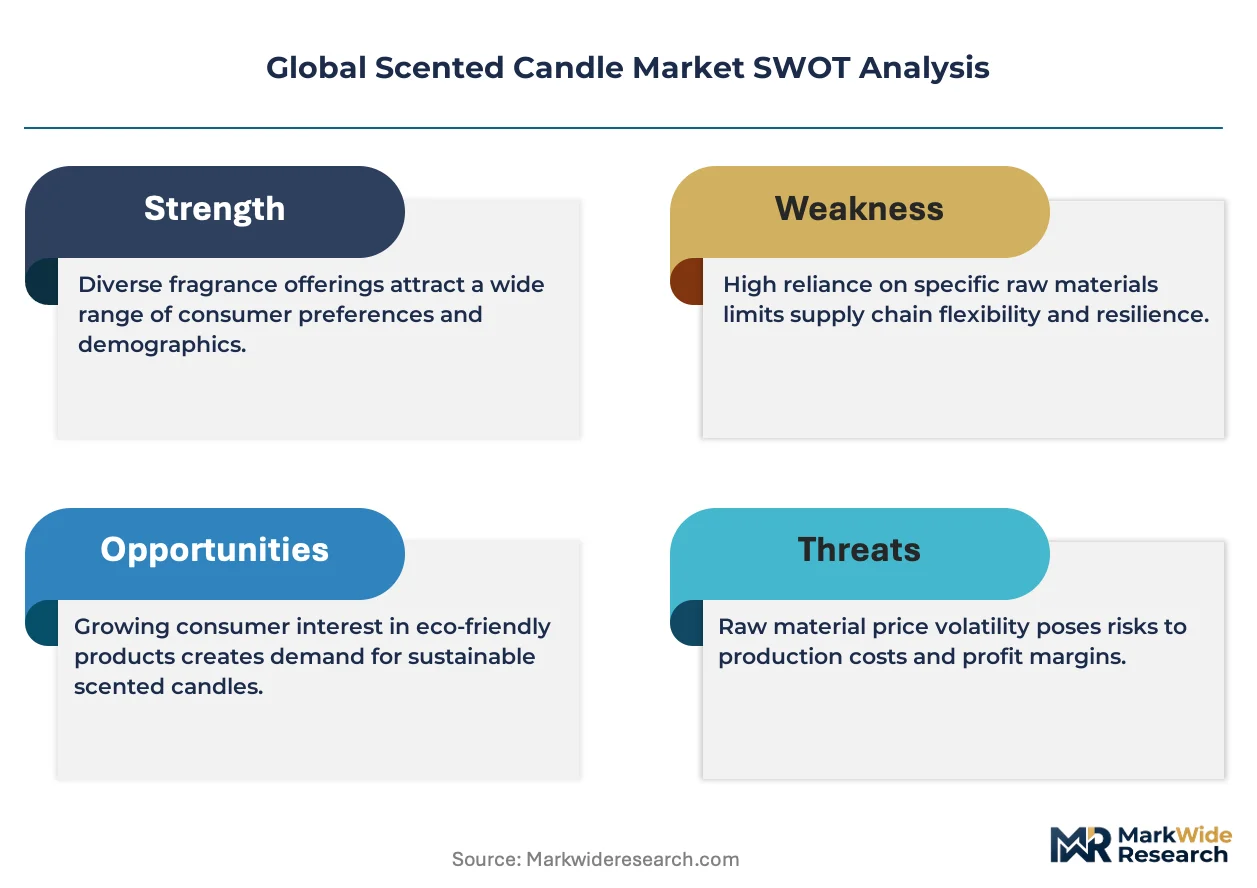
REACH compliance in Europe and EPA indoor air quality protocols are forcing simultaneous reformulation of wax substrates and fragrance loads, compressing margin structures while elevating certification costs across tier-one manufacturing bases.
Growth Catalysts
- Wellness hospitality integration:Hotels and spa operators in Shanghai, Dubai, and Milan are deploying signature scent programs as brand differentiation tools, creating institutional demand for custom-formulated candles with extended burn specifications.
- Soy wax hydrogenation advances:Refinements in hydrogenated soybean oil processing now deliver melt-point precision between 49°C and 82°C, enabling cleaner combustion profiles that satisfy health-conscious household segments.
- China's urban middle-class expansion:Tier-one city consumers in Beijing, Shenzhen, and Guangzhou are trading up to premium imported candles, accelerating demand for Parisian and Nordic heritage brands with provenance narratives.
Market Restraints
- Paraffin displacement cost penalty:Soy and beeswax formulations carry 15-30% raw material premiums versus petroleum-derived alternatives, squeezing mass-market price elasticity.
- Glass vessel supply concentration:Premium container manufacturing clusters in Italy and Portugal face energy cost volatility and kiln capacity constraints, creating packaging bottlenecks for limited-edition releases.
- VOC threshold compression:REACH and EPA protocols are lowering permissible volatile organic compound loads in fragrance oils, forcing costly third-party testing and reformulation cycles.
Strategic Opportunities
- India's underpenetrated household segment:Urban consumers in Mumbai, Bangalore, and Delhi display nascent appetite for Western home fragrance rituals, with domestic production scaling to meet price-point expectations.
- Travel-format metal vessels:Tin and aluminum containers are capturing outdoor and hospitality amenity applications, displacing fragile glass in airline, cruise, and boutique hotel channels.
- EU Green Deal circularity mandates:Packaging take-back schemes and recycled glass quotas are creating first-mover advantages for brands with closed-loop vessel programs.
Industry Challenges
- Fragrance chemist scarcity:Formulation expertise combining combustion stability with olfactory performance remains concentrated among legacy European and American compounders, constraining new entrant R&D velocity.
- Multi-jurisdiction certification lag:Simultaneous compliance with REACH, EPA guidance, and China's SAMR labeling requirements extends product launch timelines by 8-14 months.
- Wick-cotton supply reconfiguration:Egyptian and American long-staple cotton suppliers are prioritizing textile contracts, forcing candle manufacturers to qualify alternative woven wick sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Scented Candle Market |
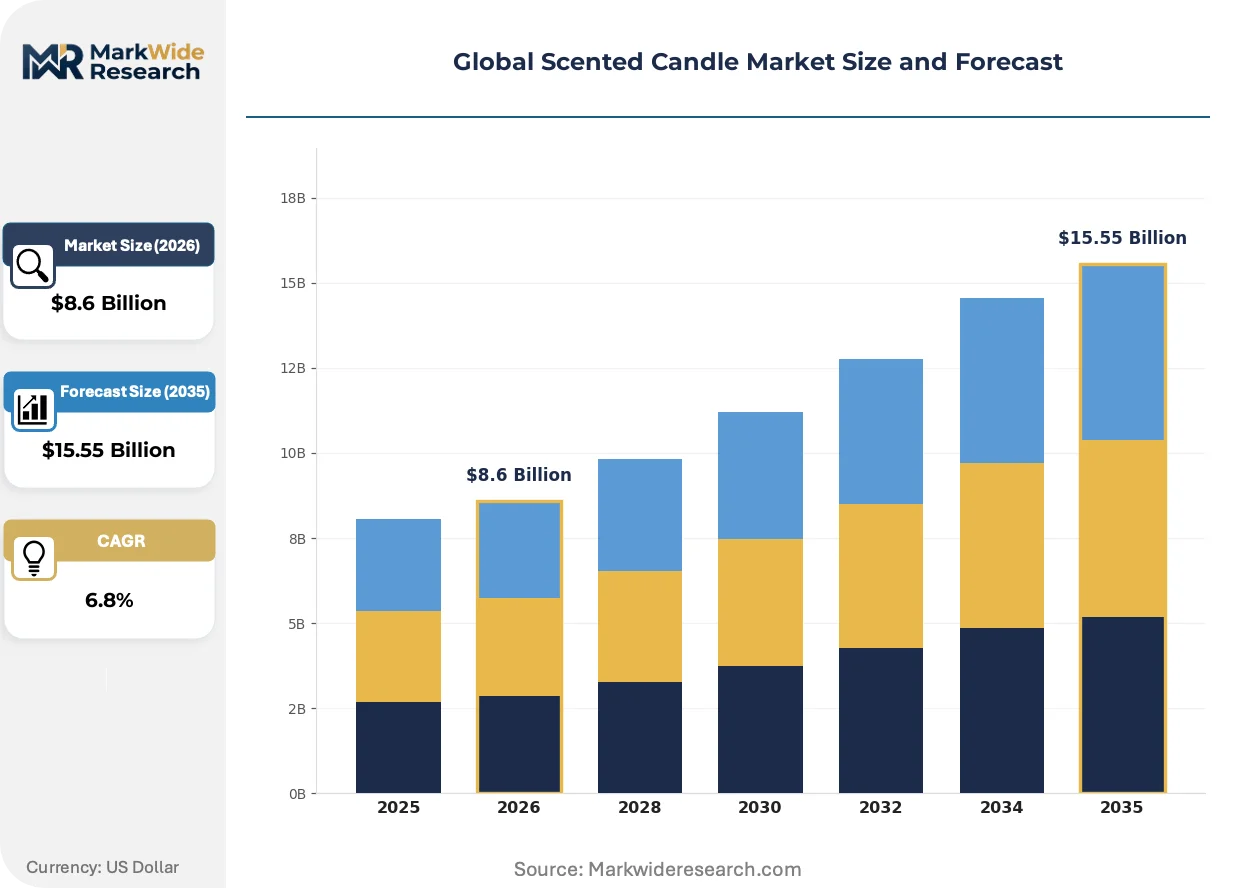
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $15.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Category: Luxury, Premium, Mid-Range, Budget Material: Paraffin Wax, Soy Wax, Beeswax, Palm Wax Fragrance Type: Floral, Fruity, Woody, Spicy Packaging Type: Glass, Metal, Plastic, Cardboard |
| Companies Covered | Yankee Candle Company, Bath & Body Works, Diptyque, NEST Fragrances, Voluspa, Jo Malone London, Chesapeake Bay Candle, Woodwick Candles, Village Candle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Scented Candle Market Strategic Shifts
Formulation chemistry, regulatory architecture, and consumption rituals are converging to reshape competitive positioning across mass and premium tiers.
Smart wick engineering is unifying combustion control with digital traceability. Embedded temperature sensors and QR-linked batch codes now enable real-time burn monitoring through mobile applications. Wellness-focused consumers in Germany and California are adopting these connected formats at accelerating rates. This convergence is compressing quality variance between artisan and industrial production by standardizing heat distribution curves.
ECHA's 2023 fragrance allergen disclosure expansion is mandating ingredient transparency down to 0.01% concentration thresholds. European manufacturers must now reformulate signature scents or redesign labels with expanded warning panels. The luxury segment, where proprietary blends constitute core brand equity, faces the steepest compliance costs and accelerated patent filing activity.
Subscription-based scent curation is displacing seasonal bulk purchasing in North American direct-to-consumer channels. Buyers receive monthly rotations matched to biometric or calendar data rather than accumulating holiday gift sets. This pattern is most visible among millennial households in Austin, Toronto, and Brooklyn, where cabinet clutter aversion intersects with discovery-oriented consumption.
Global Scented Candle Market Segmentation
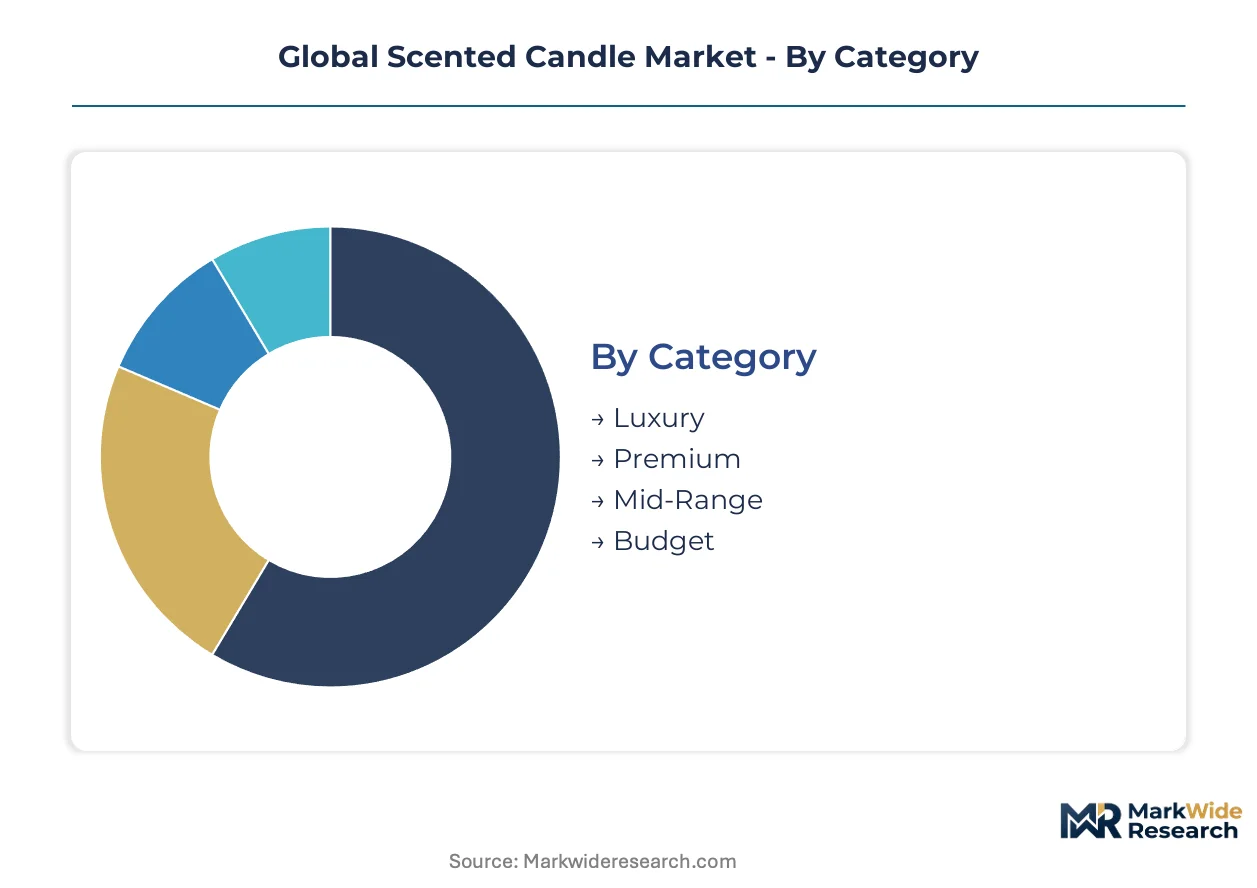
Price positioning determines formulation chemistry, vessel quality, and distribution channel access across the scented candle industry. Material selection and packaging architecture further stratify margins, while fragrance families align products with seasonal purchasing rituals and wellness-oriented consumption patterns.
Category:
Luxury buyers prioritize provenance narratives and limited-edition releases; budget purchasers optimize burn-hour economics and mass-retail accessibility.
- Luxury:Artisan production runs featuring hand-poured batches, heritage brand positioning, and selective distribution through department stores and flagship boutiques. Parisian and Nordic heritage houses command price premiums in Shanghai, Milan, and Dubai where hotel spa procurement teams specify custom-formulated signature scents.
- Premium:Bridge positioning between artisan credibility and retail scale, typically featuring soy or beeswax substrates with extended burn specifications. North American direct-to-consumer channels and wellness hospitality programs in Austin, Toronto, and Brooklyn concentrate demand through subscription-based scent curation models.
- Mid-Range:Mass-market retail presence with seasonal gifting orientation and multi-candle set configurations. Yankee Candle Company and Bath & Body Works anchor this tier through integrated fragrance ecosystems and body care collection tie-ins.
- Budget:Petroleum-derived paraffin formulations with standardized vessel designs and compressed fragrance loads. Price elasticity constraints dominate purchasing decisions in emerging household segments across India and Southeast Asia.
Mid-Range leads volumes today; Luxury is gaining share fastest.
Material:
Substrate chemistry dictates combustion profiles, scent throw characteristics, and regulatory compliance burdens across manufacturing bases.
- Soy Wax:Hydrogenated soybean oil formulations with melt-point precision between 49°C and 82°C enable cleaner combustion profiles. Health-conscious household segments in Germany and California drive displacement of petroleum alternatives, though raw material premiums compress mass-market price elasticity.
- Paraffin Wax:Petroleum-derived substrates with established supply chains and cost advantages. REACH and EPA volatile organic compound thresholds are forcing reformulation investments among legacy manufacturers.
- Beeswax:Natural wax with inherent honeyed aroma and extended burn duration. Premium positioning in artisan and wellness-oriented channels, constrained by apiary supply volatility.
- Palm Wax:Crystalline aesthetic properties with distinctive feathering patterns. Sustainability certification requirements and EU Green Deal circularity mandates shape sourcing decisions.
Paraffin Wax retains volume leadership; Soy Wax is expanding most quickly.
Fragrance Type:
Olfactory families align with seasonal purchasing cycles, biometric wellness trends, and hospitality brand differentiation strategies.
- Floral:Rose, lavender, and jasmine profiles dominating spring gifting and spa amenity applications. ECHA fragrance allergen disclosure expansion is mandating reformulation of signature blends down to 0.01% concentration thresholds.
- Woody:Sandalwood, cedar, and oud compositions capturing autumn and winter consumption rituals. Limited-edition releases in this category command disproportionate margin pools through provenance narratives.
- Fruity:Citrus and berry profiles with younger demographic appeal and summer seasonal concentration. Bath & Body Works integrates these releases with body care collection launches.
- Spicy:Cinnamon, clove, and ginger formulations tied to holiday gifting patterns. Smart wick engineering with embedded temperature sensors is standardizing heat distribution for these dense fragrance loads.
Floral leads current volumes; Woody shows the steepest expansion trajectory.
Packaging Type:
Vessel architecture determines shipping economics, shelf presence, and circularity compliance across distribution channels.
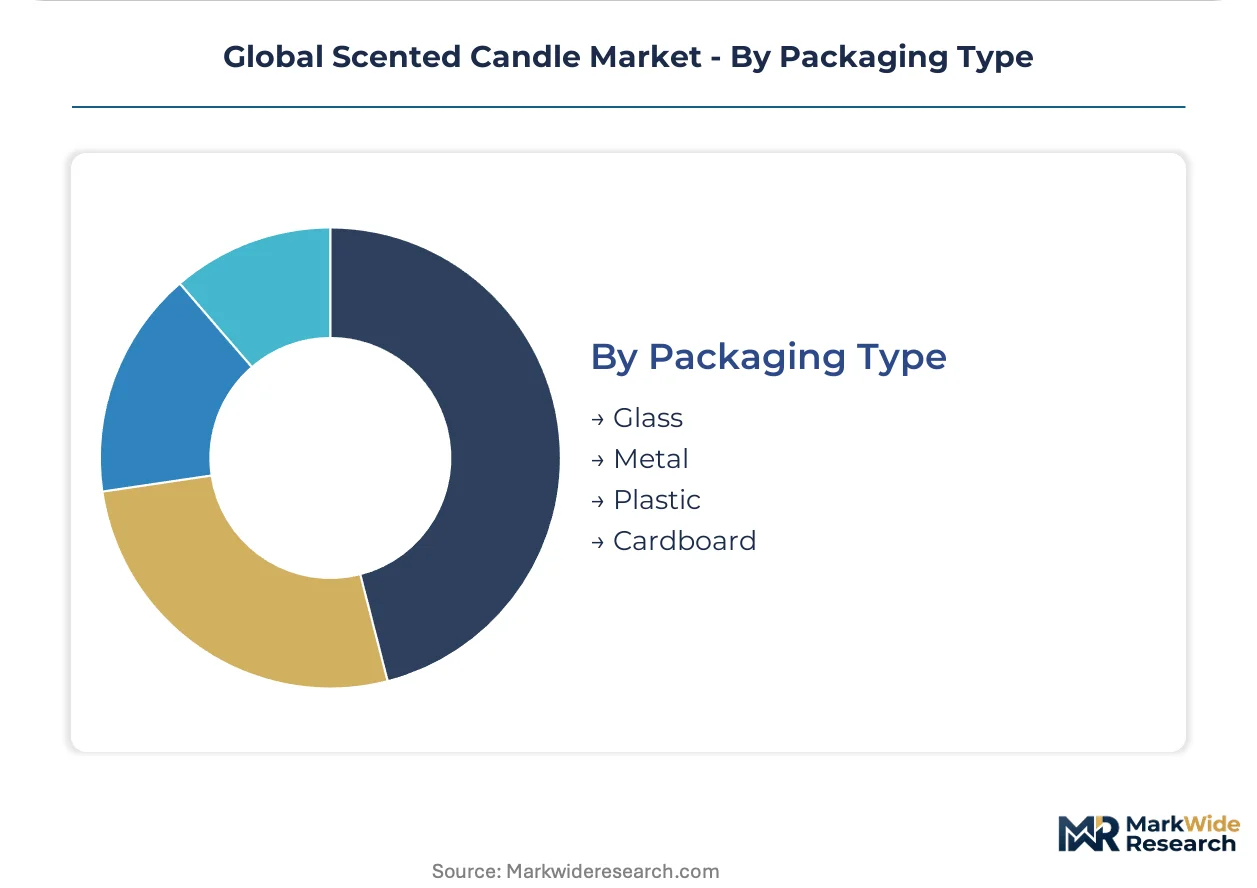
- Glass:Dominant premium tier format with kiln-fired manufacturing concentrated in Italy and Portugal. Energy cost volatility and capacity constraints create bottlenecks for limited-edition releases.
- Metal:Tin and aluminum containers capturing travel, outdoor, and hospitality amenity applications. Airline, cruise, and boutique hotel channels in Dubai and Miami displace fragile glass with these formats.
- Plastic:Compressed cost structures for mass-market and private-label positioning. EU Green Deal packaging take-back schemes are elevating compliance burdens.
- Cardboard:Emerging sustainable format for refills and subscription curation models. Recycled content quotas create first-mover advantages for brands with closed-loop programs.
Glass leads volumes today; Metal is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The scented candle industry traces its commercial origins to 19th-century European chandlery, with French and British artisans establishing the craft traditions that now define luxury positioning worldwide.
United States
Wellness hospitality programs in Austin, Brooklyn, and Los Angeles drive institutional procurement of custom-formulated candles with extended burn specifications. EPA indoor air quality protocols constrain volatile organic compound thresholds in fragrance loads, compelling reformulation investments among domestic compounders. Massachusetts and Ohio host concentrated manufacturing clusters where Yankee Candle Company leverages scale to dominate mass-market retail channels.
China
Urban middle-class consumers in Beijing, Shenzhen, and Guangzhou accelerate demand for Parisian and Nordic heritage brands with provenance narratives. GB standards for combustion emissions and SAMR labeling requirements shape market access for imported candle brands. Shanghai's tier-one retail corridors concentrate premium consumption, with hotel spa operators deploying signature scent programs as brand differentiation tools.
Germany
Health-conscious household segments in Berlin, Munich, and Hamburg drive displacement of petroleum-derived waxes through soy and beeswax adoption. ECHA's 2023 fragrance allergen disclosure expansion mandates ingredient transparency down to 0.01% concentration thresholds. The Rhine-Ruhr industrial region hosts formulation expertise combining combustion stability with olfactory performance.
United Arab Emirates
Luxury hospitality operators in Dubai and Abu Dhabi specify custom-formulated candles for spa amenity applications and boutique hotel channels. The country's national standards regulator enforces combustion safety and labeling requirements for imported home fragrance products. Dubai's retail ecosystem concentrates Gulf demand for limited-edition releases and provenance-driven heritage positioning.
India
Urban consumers in Mumbai, Bangalore, and Delhi display nascent appetite for Western home fragrance rituals, with domestic production scaling to meet price-point expectations. BIS standards for product safety and labeling compliance shape import substitution dynamics. Maharashtra and Karnataka host emerging manufacturing capacity targeting mid-range household segments.
Global Scented Candle Market Competitive Environment
The competitive structure tilts toward heritage-positioned artisans and scale-driven mass-market operators. Yankee Candle Company anchors volume leadership through manufacturing scale and North American retail channel dominance. Bath & Body Works sustains repeat purchase frequency by integrating candle releases with body care collections. Strategic moves concentrate on portfolio diversification into wellness hospitality and subscription-based scent curation.
Within the heritage-artisan tier, Diptyque and Jo Malone London exemplify Parisian and British provenance positioning that commands premium price points in selective distribution. NEST Fragrances and Voluspa occupy positions bridging artisan credibility with retail scale. These players represent the premium vector where limited-edition releases and custom-formulation capabilities differentiate offerings from mass-market alternatives.
| Leading Market Players |
|---|
| Yankee Candle Company |
| Bath & Body Works |
| Diptyque |
| NEST Fragrances |
| Voluspa |
| Jo Malone London |
| Chesapeake Bay Candle |
| Woodwick Candles |
| Village Candle |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal circularity mandates gate qualified vessel supply and premium-tier pricing access for brands seeking closed-loop glass programs. Brands without certified recycled-content quotas face exclusion from selective European retail channels, compressing margin structures for non-compliant producers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by burn specification and provenance narrative. Price differentiation hinges on certification grade (REACH-compliant formulations) and volume scale (subscription curation versus seasonal bulk). Pricing pressure stems from paraffin displacement cost penalties in mass-market tiers. Budget household segments in emerging markets exhibit highest price sensitivity; luxury buyers in tier-one cities show least elasticity.
Supply Chain Analysis
Fragrance oil supply rests on legacy European and American compounders with concentrated formulation expertise. Raw material dependencies include hydrogenated soybean oil, Egyptian long-staple cotton for wicks, and kiln-fired glass from Italian and Portuguese manufacturers. Single-source vulnerability in premium vessel production creates bottlenecks for limited-edition releases. Distribution runs through mass-market retail chains, direct-to-consumer subscription platforms, and hospitality procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with wellness hospitality procurement teams trading up to custom-formulated candles with extended burn specifications.
For Market Incumbents: Extend provenance-driven heritage positioning into wellness hospitality channels through custom-formulation capabilities. Invest in REACH-compliant reformulation infrastructure to defend against regulatory displacement. Pursue backward integration into hydrogenated soybean oil processing to capture soy wax margin premiums. For New Entrants and Emerging Players: Boutique hotel procurement teams in Dubai and Miami represent an underserved buyer archetype seeking metal-vessel travel formats. Target India's nascent urban household segment in Mumbai and Bangalore with domestically produced mid-range offerings. Launch through hospitality amenity partnerships rather than retail shelf competition. For Investors and Strategic Acquirers: Roll-up economics work for artisan heritage brands because fragrance chemist scarcity constrains new entrant R&D velocity. The five-to-ten year viability window favors provenance-positioned assets with selective distribution. Watch ECHA allergen disclosure expansion timelines as an inflection indicator for reformulation cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Vessel Program | EU Green Deal compliance secures selective retail access in Germany and France. |
| Wellness Hospitality Partnership | Custom-formulation capabilities differentiate offerings from mass-market alternatives in Dubai. |
| Subscription Curation Launch | Biometric-matched scent rotations capture millennial households in Austin and Toronto. |
| Soy Wax Capacity Expansion | Hydrogenated soybean oil processing investments displace paraffin in health-conscious segments. |
| Smart Wick Engineering Integration | Embedded temperature sensors standardize quality variance between artisan and industrial production. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with brand managers, category buyers at retailers, fragrance compounders, and hospitality procurement directors informed demand-side assessments. Secondary sources include customs records, Nielsen retail audit data, EPA air quality guidance documents, and ECHA regulatory filings. Bottom-up segment sizing and top-down macro anchoring were triangulated for consistency.
Rate-of-change decomposition across the analysis window separates volume from value growth drivers. Segmentation dimensions modeled include price tier, wax substrate chemistry, fragrance family, and vessel material. CAGRs were derived from trend extrapolation of historical consumption patterns adjusted for regulatory phase-in schedules. Forecast inputs incorporate soy wax hydrogenation yield improvements and REACH compliance cost trajectories.
Underlying measurement precision varies by segment; luxury and premium tiers carry tighter precision than budget household segments due to selective distribution concentration. Forecasts reflect assumptions about regulatory implementation timelines and hospitality recovery patterns. A small set of triggers—including ECHA allergen threshold revisions and Chinese GB standard updates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Fragrance Oil Market
Fragrances & Perfumes
Kuwait Perfume Market
Fragrances & Perfumes
Smart Fragrance Box Market
Fragrances & Perfumes
Floral Water Spray Market
Fragrances & Perfumes
Saudi Arabia E-Commerce Cosmetics and Fragrances Market
Fragrances & Perfumes
Home Fragrance Market
Fragrances & Perfumes
Natural Fragrance Market
Fragrances & Perfumes
Evaporative Diffusers Market
Fragrances & Perfumes
Fragrance Product Market
Fragrances & Perfumes
Fragrance Emulsion Market
Fragrances & Perfumes
Gulf Cooperation Council Fragrance and Perfumes Market
Fragrances & Perfumes
Mini Refillable Perfume Bottles Market
Fragrances & Perfumes
Reed Diffusers Market
Fragrances & Perfumes
Scented Oil Market
Fragrances & Perfumes
Global Fragrances and Perfumes Market
Fragrances & Perfumes
Organic Perfumes Market