
 Makeup Remover Product Market | 2026-2036
Makeup Remover Product Market Size, Share, and Industry Trends Forecast 2026-2036
Makeup Remover Product Market Analytics
Professional salon and content-creator procurement is consolidating as bridal studios, film production houses, and influencer agencies centralize bulk purchasing through dedicated supply contracts. L'Oréal S.A. leverages its dermatological testing infrastructure to serve this concentrated institutional channel. Estée Lauder Companies Inc. anchors its position through prestige spa and professional artist exclusives. Unilever competes across mass-market professional segments with standardized wipe and micellar formats.
Makeup remover products are surfactant-based or oil-in-water formulations engineered to dissolve cosmetic pigments, silicones, and film-forming polymers without compromising stratum corneum integrity; primary specifications include pH balancing between 4.5 and 5.5 and ophthalmological safety for eye-area application. Micellar water leads volume in European pharmacy channels due to its no-rinse convenience and minimal preservative load. Bi-phase removers command premium positioning in Asian markets where waterproof mascara penetration runs deepest. Wipes face structural pressure from single-use plastic directives, compressing margin pools in convenience-oriented retail.
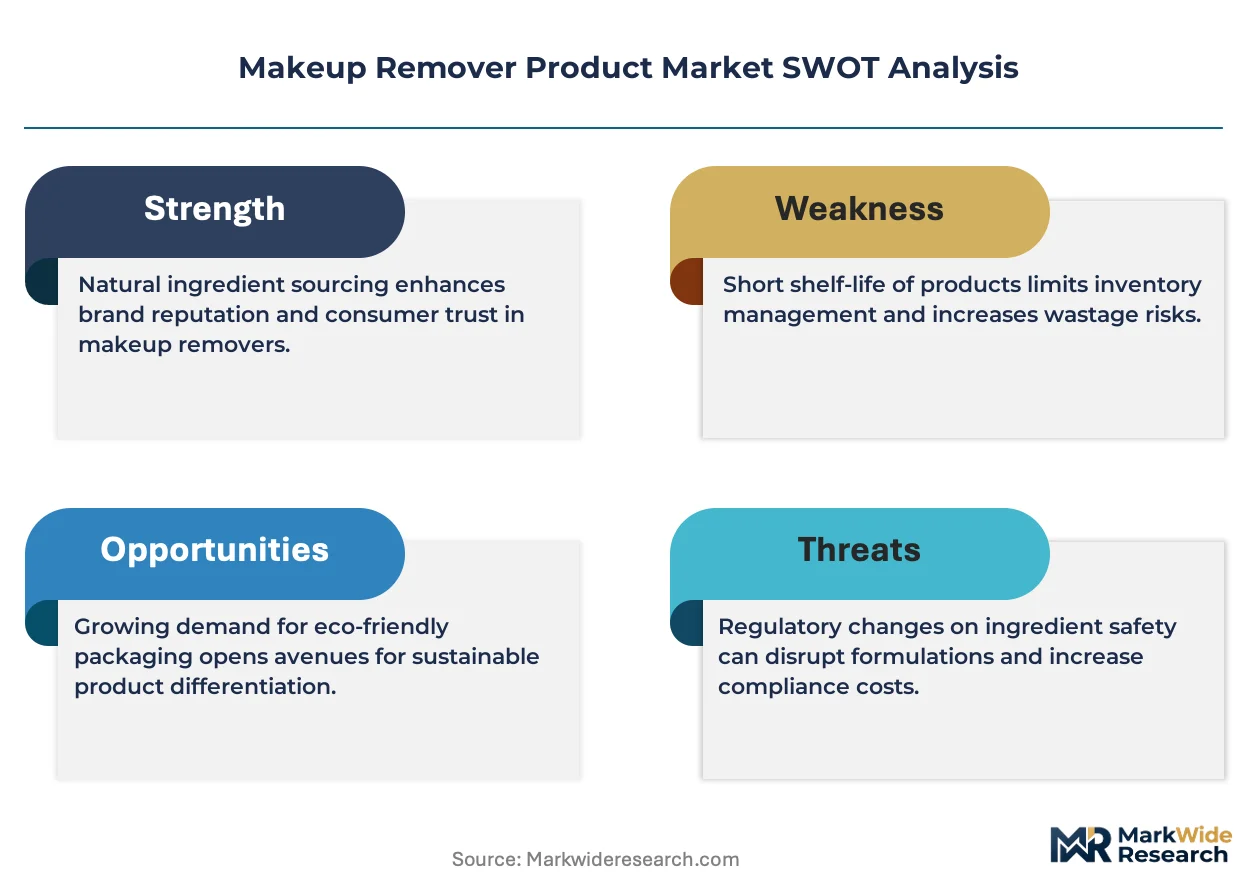
FDA cosmetic ingredient oversight and the EU REACH framework govern emollient and preservative permissibility, directly constraining formulation palettes and reformulation cycles for brands seeking cross-border distribution. China's NMPA filing requirements for imported cosmetics add compliance layers that favor established multinationals with dedicated regulatory affairs teams. Stakeholders must monitor evolving state-level microplastic bans and biodegradable surfactant mandates to anticipate raw material substitution timelines.
Market Dynamics
The EU REACH chemicals framework and tightening microplastic restrictions are forcing raw material substitutions across surfactant and emollient supply chains, compressing formulation flexibility while elevating compliance costs for cross-border brands.
Growth Catalysts
- Content creator procurement:Bridal studios and influencer agencies now centralize bulk purchasing through dedicated supply contracts, concentrating volume in professional-grade formats.
- Waterproof cosmetic penetration:Bi-phase remover adoption is accelerating in Asian markets where long-wear mascara and lash extension adhesives require solvent-oil hybrid chemistry.
- Multi-step cleansing normalization:South Korean beauty routines anchor category volume through oil cleanser-to-micellar water sequencing that doubles per-capita consumption.
Market Restraints
- Single-use plastic directives:EU and state-level microplastic bans compress margin pools in convenience-oriented wipe formats, forcing SKU rationalization.
- Petrochemical feedstock volatility:Surfactant and synthetic ester input costs fluctuate with crude oil indices, destabilizing mass-market pricing.
- Ophthalmological safety testing:Extended ocular irritation protocols add 12-18 months to new eye-area formulation launches, delaying revenue recognition.
Strategic Opportunities
- Biodegradable surfactant mandates:France's AGEC law and Germany's packaging regulations create first-mover advantage for alkyl polyglucoside and saponin-based formulations.
- Professional artist channel:Film production houses and theater companies represent underpenetrated institutional buyers with concentrated volume potential.
- Refill and concentrate systems:Waterless remover tablets and dissolvable sheets bypass liquid shipping weight restrictions while aligning with carbon-reduction commitments.
Industry Challenges
- Regulatory affairs talent scarcity:China's NMPA filing requirements and evolving state-level microplastic bans demand specialized compliance expertise that outpaces supply.
- Legacy formulation re-engineering:Decades-old emollient portfolios require complete preservative system overhauls to meet EU REACH restrictions, straining R&D bandwidth.
- Cross-border labeling complexity:Multi-jurisdiction ingredient disclosure rules fragment packaging runs and inflate working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Makeup Remover Product Market |
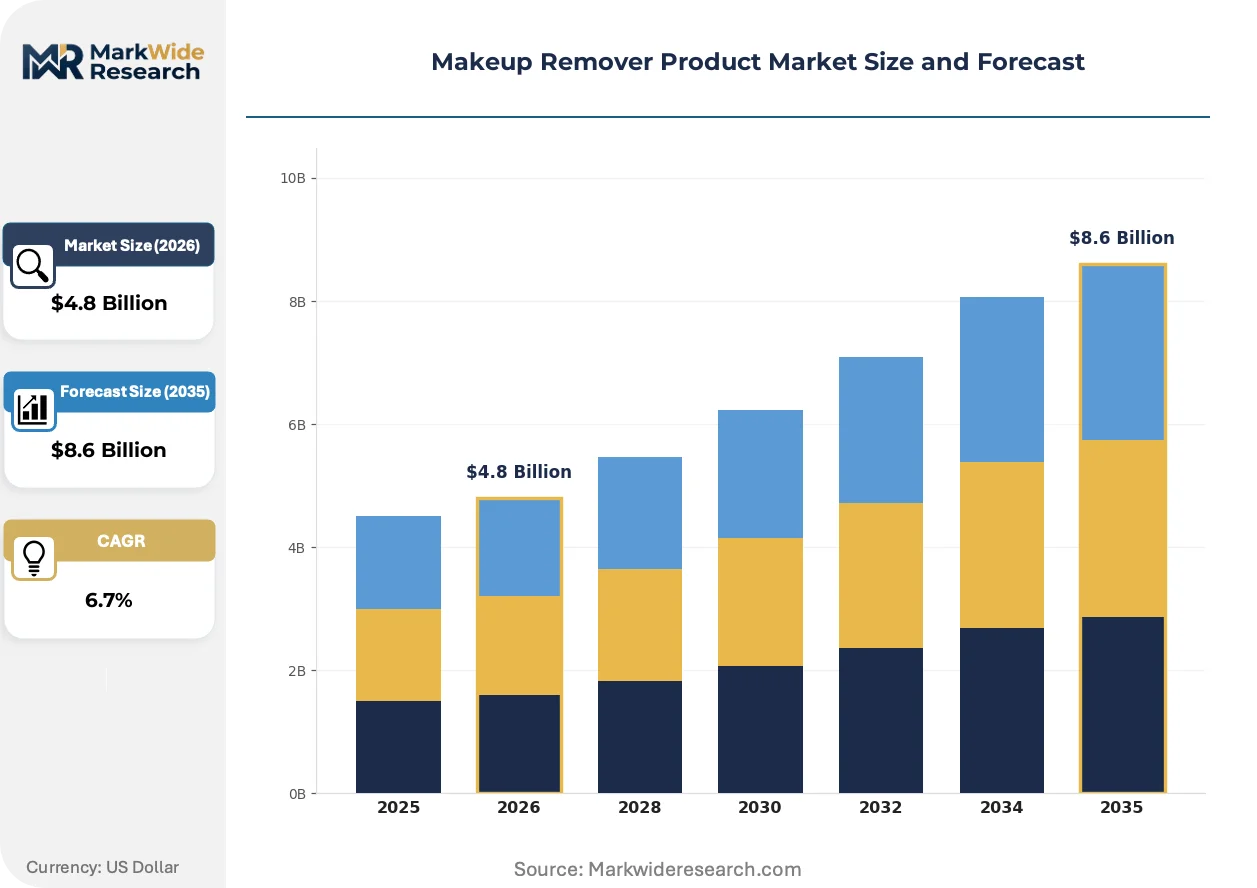
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bi-phase, Micellar Water, Wipes, Balm End User: Females, Males, Professional Makeup Artists, Beauty Enthusiasts Packaging Type: Tub, Bottle, Sachet, Pump Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Department Stores |
| Companies Covered | Unilever, Beiersdorf AG, L’Oréal S.A., Kao Corporation, Shiseido Company Inc., Procter & Gamble Co., Estée Lauder Companies Inc., Chanel SA, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Makeup Remover Product Market Evolving Landscape
Formulation chemistry and regulatory compliance are converging to reshape product architecture, with automation replacing manual quality assurance and sustainability mandates dictating raw material selection.
Artificial intelligence-driven formulation screening is automating the identification of surfactant-emollient combinations that maintain efficacy while satisfying REACH and FDA preservative restrictions. L'Oréal and Estée Lauder deploy machine learning models to predict ocular irritation profiles before clinical testing, compressing development timelines. This technology is automating the elimination of iterative lab batches, reducing reformulation cycles by half for brands serving multiple regulatory jurisdictions.
REACH Annex XVII restrictions on microplastics and France's AGEC anti-waste law are prohibiting rinse-off products containing synthetic glitter and certain film-forming polymers. Manufacturers must reformulate waterproof mascara removers with biodegradable alternatives or exit the European pharmacy channel. Bi-phase and oil cleanser categories face the steepest compliance costs, driving consolidation toward multinationals with dedicated regulatory affairs teams.
Subscription-based replenishment models are displacing supermarket impulse purchases as primary acquisition channels for core users. South Korean and Japanese consumers increasingly source micellar water through brand-direct auto-ship programs, bypassing traditional retail markups. This shift concentrates customer lifetime value data with manufacturers while fragmenting distributor influence in Seoul and Tokyo metropolitan markets.
Makeup Remover Product Market Segmentation
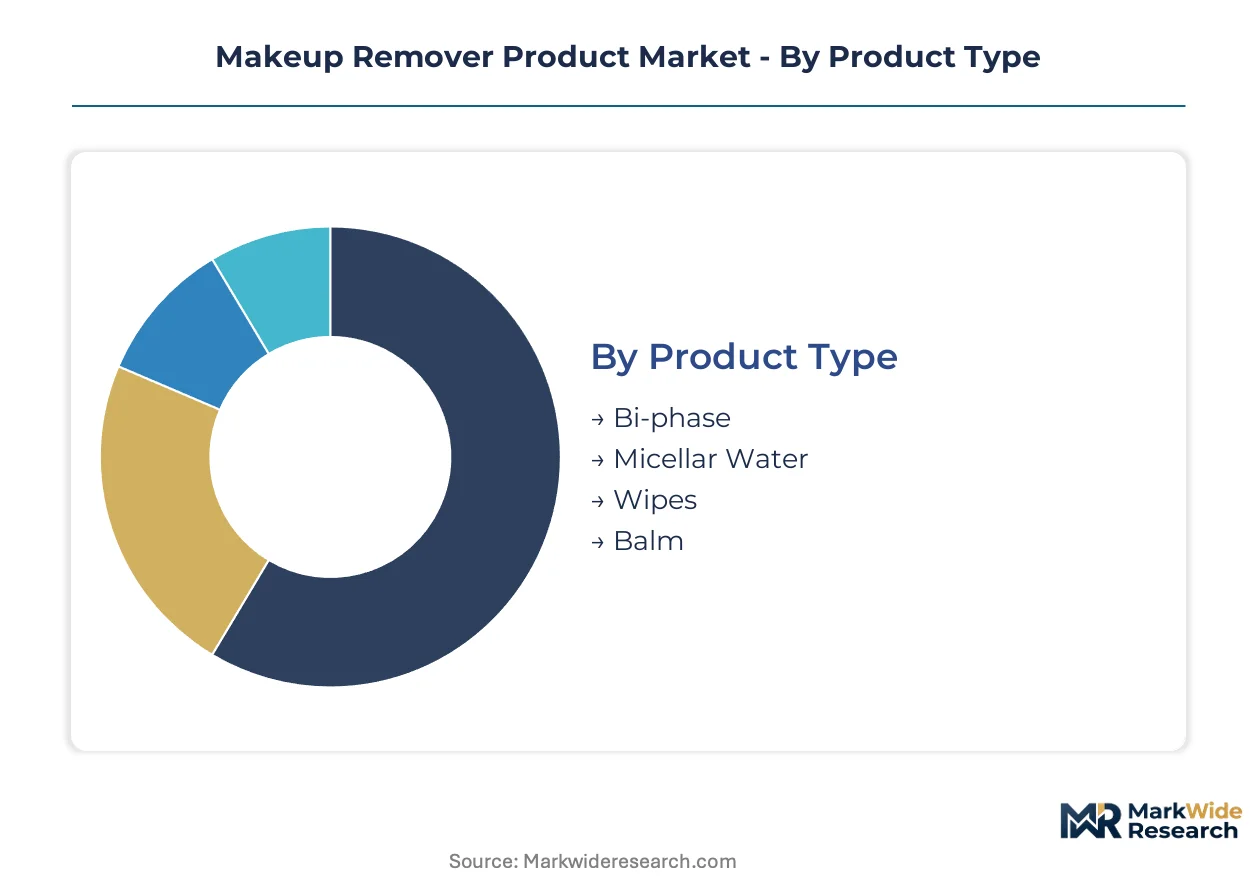
Segmentation in makeup remover products reveals how formulation chemistry, user expertise, and channel economics fragment demand. Each dimension exposes distinct margin structures and regulatory exposure that shape portfolio strategy.
Product Type:
Standardization dominates at the mass-market end, while professional and premium tiers demand customized solvent systems with specialized stability profiles.
- Bi-phase:Oil-in-water emulsions separate into polar and non-polar layers that dissolve waterproof silicones and film-forming polymers. Demand concentrates in South Korea and Japan where long-wear mascara penetration drives solvent-oil hybrid chemistry adoption. Premium positioning reflects higher raw material costs and ophthalmological testing requirements.
- Micellar Water:Surfactant micelles suspended in purified water attract oil-based cosmetic residues without disrupting stratum corneum lipid barriers. European pharmacy channels favor this format for its no-rinse convenience and minimal preservative load, though REACH Annex XVII restrictions on certain surfactants are forcing reformulation cycles.
- Wipes:Non-woven substrates impregnated with emollient-rich cleansing solutions face structural compression from EU single-use plastic directives and state-level microplastic bans.
- Balm:Solid oil-based cleansers transform from sorbet texture to milk upon emulsification with water, appealing to travel-restricted consumers and zero-waste positioning.
Leading the category by volume: Micellar Water. Expanding most quickly: Bi-phase.
End User:
Volume scales inversely with expertise level, while margin concentrates where technical application knowledge drives product sophistication.
- Females:The foundational consumer base spans mass-market micellar formats through premium bi-phase systems, with per-capita consumption doubling in markets where multi-step cleansing routines normalize.
- Professional Makeup Artists:Film production houses, bridal studios, and theater companies procure through centralized supply contracts with concentrated volume potential. This segment demands ophthalmologically tested formulations capable of removing theatrical-grade adhesives without irritating talent during repeated application cycles.
- Males:Emerging category entrants responding to expanded male grooming portfolios and gender-neutral positioning in Seoul and Tokyo metropolitan markets.
- Beauty Enthusiasts:Early adopters of waterless tablets, dissolvable sheets, and refill concentrate systems that align with carbon-reduction commitments.
Driving the most volume: Females. Steepest expansion trajectory: Professional Makeup Artists.
Packaging Type:
Logistics cost and sustainability mandates are restructuring format preferences away from water-weighted shipments toward concentrated and solid alternatives.
- Bottle:Standard PET and glass containers dominate micellar water and bi-phase segments, though France's AGEC anti-waste law is pressuring minimum recycled content thresholds.
- Pump:Airless and metered-dose systems preserve antioxidant stability in balm and oil formulations while enabling precise dosage control for professional kit integration.
- Tub:Wide-mouth containers suit solid balm formats and wipe refills, with lightweight PP construction reducing freight costs for e-commerce fulfillment.
- Sachet:Single-use foil pouches serve travel retail and hospitality amenity channels, though environmental positioning is forcing biodegradable film substrate adoption.
Highest shipment volume: Bottle. Gaining share fastest: Pump.
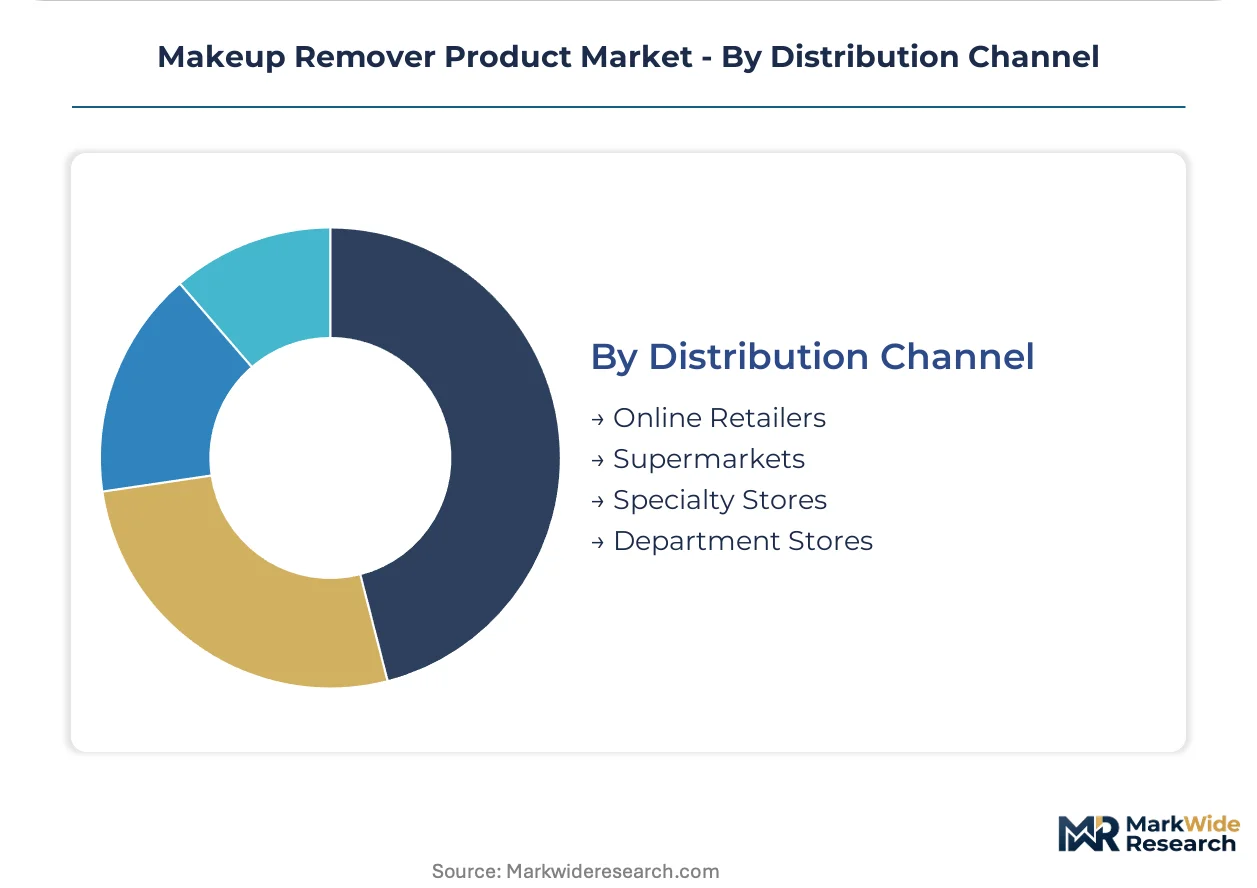
Distribution Channel:
Channel concentration reflects demographic targeting, with premium positioning requiring controlled environment presentation and mass access demanding operational efficiency.
- Specialty Stores:Sephora, Ulta, and Douglas deploy trained consultants to demonstrate bi-phase shaking technique and double-cleansing sequencing, capturing margin through service attachment.
- Online Retailers:Brand-direct auto-ship programs in South Korea and Japan are fragmenting distributor influence while concentrating customer lifetime value data with manufacturers.
- Supermarkets:Mass-market micellar water and wipe formats compete on shelf velocity and promotional depth, with private label pressure compressing branded margin pools.
- Department Stores:Prestige counters anchor gift-with-purchase strategy and seasonal bundling, though foot traffic erosion is forcing experiential activation investment.
Largest volume channel: Supermarkets. Climbing the fastest: Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for makeup remover products concentrates in East Asian metropolitan markets where multi-step cleansing routines anchor per-capita consumption at double Western levels. Regulatory divergence across major economies is fragmenting formulation standards and compliance costs. Industrial clusters in Seoul, Tokyo, and Shanghai now dictate category innovation cycles through professional artist procurement and content-creator supply chains.
South Korea
Seoul's Gangnam and Hongdae districts generate the densest professional makeup artist concentration globally, with bridal studios and K-beauty content houses centralizing bulk procurement of bi-phase removers. MFDS cosmetic safety regulations mandate ophthalmological testing protocols that extend launch timelines for eye-area formulations. The Songdo International Business District hosts contract manufacturers serving both domestic subscription auto-ship programs and cross-border e-commerce into China.
United States
Los Angeles film production houses and New York bridal agencies drive institutional procurement of theatrical-grade adhesive removers. FDA cosmetic ingredient oversight governs preservative permissibility, directly constraining emollient selection for brands seeking pharmacy distribution. California's state-level microplastic restrictions are forcing reformulation of wipe substrates ahead of federal standards.
Japan
Tokyo's Shibuya and Harajuku retail corridors anchor prestige micellar water volume through department store gift-with-purchase programs. METI packaging regulations and carbon-reduction commitments are accelerating refill system adoption among domestic manufacturers. Osaka-based formulators specialize in sorbet-to-milk balm textures for travel-restricted consumers.
Germany
Berlin's professional theater companies and Hamburg's film production facilities represent underpenetrated institutional buyers with concentrated solvent-remover demand. REACH Annex XVII microplastic restrictions and the national packaging ordinance are prohibiting certain film-forming polymers in rinse-off products. Frankfurt pharmacy chains favor minimal-preservative micellar formats that satisfy ECHA surfactant guidelines.
France
Parisian prestige counters and Lyon-based pharmacy networks anchor European micellar water distribution. The AGEC anti-waste law mandates minimum recycled content thresholds for PET bottles and pressures single-use wipe formats. Marseille contract manufacturers are piloting alkyl polyglucoside surfactant systems to preempt biodegradable mandates spreading to neighboring jurisdictions.
Makeup Remover Product Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue waterless and concentrate formats that bypass liquid shipping weight restrictions. The market presents a three-tier structure with multinationals commanding pharmacy and professional channels, mid-tier regional formulators serving auto-ship subscriptions, and niche entrants attacking zero-waste positioning. Strategic archetypes include dermatological-testing specialists, mass-market standardizers, and sustainable-format innovators. Competitive intensity centers on preservative system reformulation cycles and regulatory affairs team scale.
Within the multinational tier, L'Oréal S.A. and Estée Lauder Companies Inc. anchor professional artist and prestige spa distribution through dedicated supply contracts. Unilever occupies mass-market positioning across standardized wipe and micellar formats. Kao Corporation represents the Asia-Pacific formulation specialist archetype with concentrated exposure to Seoul and Tokyo metropolitan subscription channels.
| Leading Market Players |
|---|
| Unilever |
| Beiersdorf AG |
| L'Oréal S.A. |
| Kao Corporation |
| Shiseido Company Inc. |
| Procter & Gamble Co. |
| Estée Lauder Companies Inc. |
| Chanel SA |
| Johnson & Johnson |
| Others |
Value Network & Pricing Analysis
France's AGEC anti-waste law gates qualified supply and premium-tier pricing access by mandating minimum recycled content thresholds that only multinationals with dedicated regulatory affairs teams can satisfy, compressing margin pools for mid-tier formulators while elevating compliance costs as a price floor mechanism.
Pricing Analysis
Volume concentrates in mass-market micellar water and wipe formats where per-unit margins compress under private label pressure, while premium bi-phase and balm categories capture margin through ophthalmological certification and professional artist channel exclusivity. Price differentiation hinges on REACH compliance tier and dermatological testing depth, with EU-certified formulations commanding shelf space premiums. Pricing pressure intensifies in wipe segments as microplastic bans force substrate reformulation. Supermarket channel buyers exhibit highest price sensitivity; bridal studios and film production houses demonstrate lowest sensitivity due to concentrated contract volumes.
Supply Chain Analysis
Surfactant supply rests on German specialty chemical producers for alkyl polyglucoside systems, South Korean manufacturers for mild anionic variants, and Chinese producers for commodity-grade inputs. Key dependencies include palm-derived fatty alcohols, petroleum-based synthetic esters, and biodegradable film substrates for wipe formats. Single-source vulnerability concentrates in ophthalmological safety testing facilities certified for EU REACH Annex XVII compliance. Distribution runs through pharmacy chains and professional artist supply houses in Seoul, Tokyo, and Paris metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH Annex XVII microplastic restrictions are forcing consolidation as reformulation costs exceed R&D bandwidth for sub-scale competitors, eliminating fringe players unable to fund preservative system overhauls.
For Market Incumbents: Lock in professional artist channel control through exclusive supply contracts with film production houses and bridal studios, while accelerating backward integration into biodegradable surfactant production to preempt France's AGEC law expansion. Threat from waterless tablet entrants demands immediate capacity investment in solid format manufacturing. For New Entrants and Emerging Players: Brand-direct auto-ship programs in South Korea and Japan offer the most penetrable route, bypassing fragmented distributor networks while capturing customer lifetime value data. Target male grooming segments in Seoul metropolitan markets with gender-neutral balm positioning. Go-to-market angle: zero-waste refill systems aligned with METI carbon-reduction commitments. For Investors and Strategic Acquirers: MFDS ophthalmological testing queue lengthening is the leading indicator that regulatory affairs talent scarcity will deepen, favoring acquisition targets with established Seoul or Tokyo-based compliance infrastructure. Long-term viability centers on multinationals with cross-border filing expertise; watch for NMPA filing backlogs as the inflection signal for distressed mid-tier assets.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Surfactant Transition | Preempts France's AGEC law expansion and REACH Annex XVII enforcement across European pharmacy channels. |
| Professional Artist Channel Exclusives | Concentrates volume through bridal studios and film production houses with multi-year supply contracts. |
| Waterless Format Development | Bypasses liquid shipping weight restrictions while aligning with carbon-reduction commitments in Tokyo and Seoul. |
| Regulatory Affairs Team Scale-Up | Addresses NMPA filing requirements and MFDS ophthalmological testing queue bottlenecks for eye-area formulations. |
| Subscription Auto-Ship Launch | Fragments distributor influence in South Korea and Japan while capturing customer lifetime value data directly. |
Research Methodology
Document review covered EU REACH Annex XVII regulatory filings, MFDS cosmetic safety registrations, and NMPA import cosmetic databases, complemented by interviews with formulation chemists at contract manufacturers, regulatory affairs directors at multinationals, pharmacy chain category buyers, and professional makeup artist supply coordinators. Secondary validation drew from ECHA surfactant guidance documents, French AGEC law implementation circulars, and METI packaging regulation updates. Bottom-up triangulation across product-type volume estimates and top-down cross-checks against channel shipment data anchored the analytical framework.
Historical volume trajectories were cross-referenced against panel input from procurement leads at bridal studios and film production houses across the projection horizon. Segmentation dimensions modeled include formulation chemistry, end-user expertise tier, packaging format logistics cost, and distribution channel concentration. CAGRs were derived from growth driver elasticity analysis calibrated to professional artist procurement scaling and multi-step cleansing routine normalization. Industry-specific forecast inputs incorporated waterproof cosmetic penetration rates and microplastic ban implementation timelines.
Inputs from regulatory filing databases and channel shipment audits were available through the study window; gaps in real-time professional artist contract value data introduce uncertainty bands around institutional segment estimates. Forecasts reflect assumptions regarding REACH Annex XVII enforcement consistency and biodegradable surfactant substitution pace. Regulatory timeline slippage, feedstock price volatility, and ophthalmological testing queue extensions constitute primary revision risks. A small set of named triggers—MFDS queue lengthening, AGEC law territorial expansion, and NMPA filing backlog accumulation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Private Label Cosmetics Manufacturing Service Market
Cosmetics & Skincare
Matte Lipstick Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
K-Beauty Products Market
Cosmetics & Skincare
Face Cream Market
Cosmetics & Skincare
Moisturizing Spray Market
Cosmetics & Skincare
Tea Based Face Masks Market
Cosmetics & Skincare
J-Beauty Products Market
Cosmetics & Skincare
Anti-Pollution Skin Care Products Market
Cosmetics & Skincare
Face Wash Market
Cosmetics & Skincare
Cosmetics Private Label and Contract Manufacturing Market
Cosmetics & Skincare
Myanmar Skin Care Products Market
Cosmetics & Skincare
Global Facial Cleanser Market
Cosmetics & Skincare
Massaging Cosmetic Applicators Market
Cosmetics & Skincare
Qatar Cosmetic Products Market
Cosmetics & Skincare
Cold Pressed Soap Market