
 Middle East Fragrances Market | 2026-2036
Middle East Fragrances Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Fragrances Market Insights
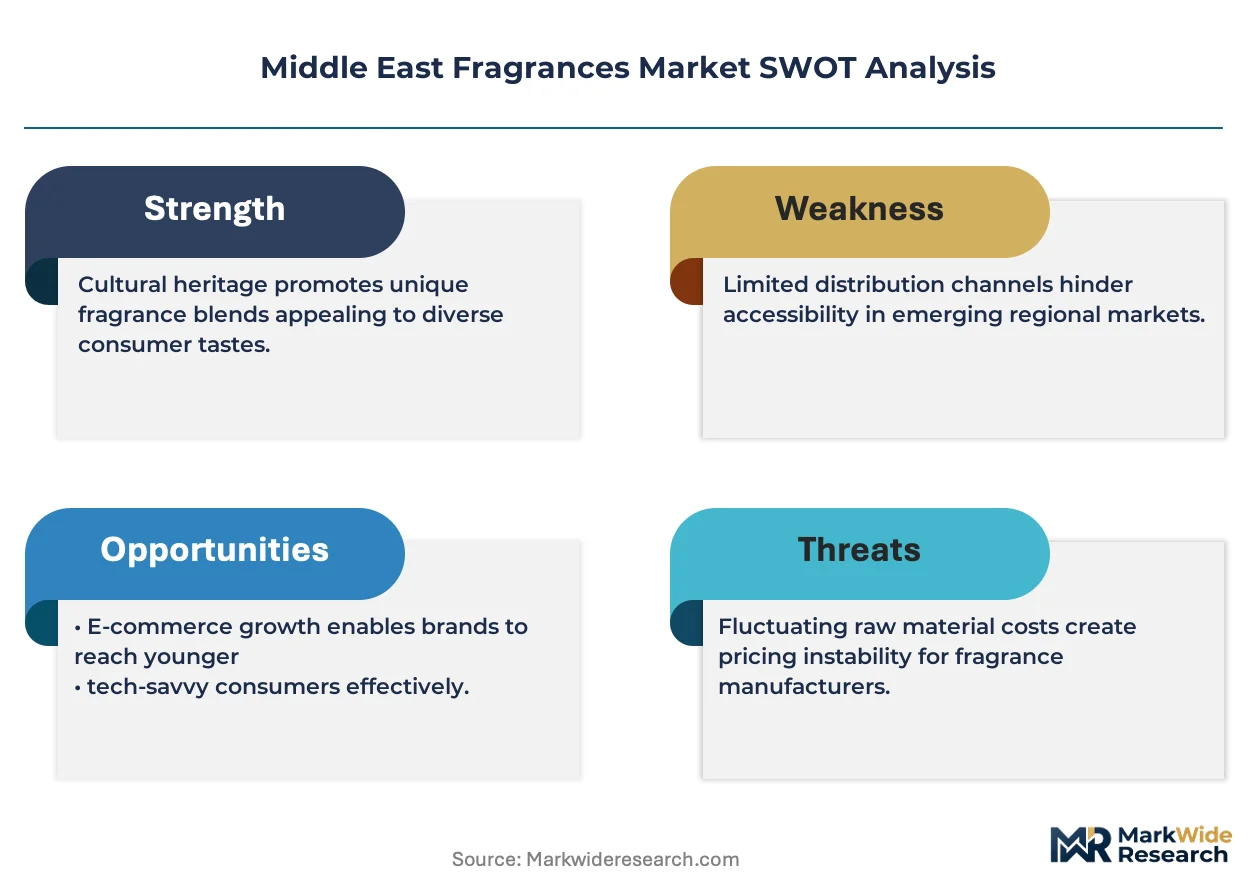
Multi-layer gift bundling of oud oils with incense and body mists is restructuring how consumers evaluate value in Middle Eastern fragrance retail. Ajmal Perfumes leverages its vertically integrated agarwood sourcing to sustain price consistency across bundled collections. Rasasi Perfumes anchors its Gulf presence through exclusive mall-based distribution networks. Amouage differentiates via high-concentration extrait formulations that occupy the ultra-premium tier in Oman and beyond.
Fragrances in the Middle East context denote alcohol-based and oil-based scent preparations with concentrations ranging from eau de toilette to pure perfume oils exceeding 20 percent aromatic compounds, traditionally formulated around oud, amber, musk, and rose accords for personal adornment and social gifting. Perfume oils command the deepest margin pools due to cultural preference for long-lasting, alcohol-free formulations in Saudi Arabia and the UAE. Eau de parfum competes for share among younger demographics seeking international-style portability, while specialty stores remain the dominant distribution channel for authenticating provenance and quality.
SFDA in Saudi Arabia and SASO enforce ingredient disclosure and import certification standards that shape product registration timelines for foreign brands entering the Kingdom. The UAE's MOHAP and Emirates Conformity Assessment Scheme regulate safety testing for fragrance allergens in retail formulations. Stakeholders must monitor evolving halal certification requirements for alcohol content and synthetic musk alternatives across Gulf regulatory frameworks.
Market Dynamics
Concentrated perfume oil formulations are displacing alcohol-based alternatives across Gulf retail channels, driven by cultural preference for long-lasting scents and tightening halal compliance requirements from Saudi Arabia's SFDA and the UAE's MOHAP.
Growth Catalysts
- Luxury hospitality integration:Five-star hotels in Dubai and Riyadh now embed bespoke oud experiences into guest loyalty programs, expanding fragrance touchpoints beyond traditional retail.
- SFDA ingredient disclosure mandates:Saudi Arabia's tightened labeling requirements for concentrated oils are accelerating formalization of previously informal attar supply chains.
- Agarwood plantation development:Cultivated oud sources in Southeast Asia are reducing wild-harvest dependency and stabilizing raw material input costs for regional formulators.
Market Restraints
- Wild agarwood depletion:CITES Appendix II restrictions on Aquilaria species continue constraining supply from Indochina, forcing reliance on higher-cost plantation grades.
- Synthetic musk substitution limits:Technical performance gaps between nitro-musks and natural alternatives persist in alcohol-free oil bases, restricting reformulation options.
- Import certification friction:SASO conformity assessment timelines for foreign fragrance houses average 14-18 weeks, delaying Saudi market entry for new entrants.
Strategic Opportunities
- Experiential retail formats:Oud blending studios in Jeddah and Abu Dhabi malls are capturing premium margins through personalized fragrance creation services.
- Halal certification convergence:Unified standards emerging across Gulf Cooperation Council frameworks are reducing multi-country compliance duplication for regional brands.
- Travel retail expansion:Dubai International Airport's fragrance precinct renovations are elevating oud and attar visibility to transit passengers from South Asia and Africa.
Industry Challenges
- Master perfumer scarcity:Traditional oud compounding expertise remains concentrated among aging practitioners in Oman and Yemen, creating knowledge transfer bottlenecks.
- Cold-chain infrastructure gaps:Temperature-controlled logistics for heat-sensitive oil formulations remain underdeveloped outside UAE and Saudi Arabia's primary corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Fragrances Market |
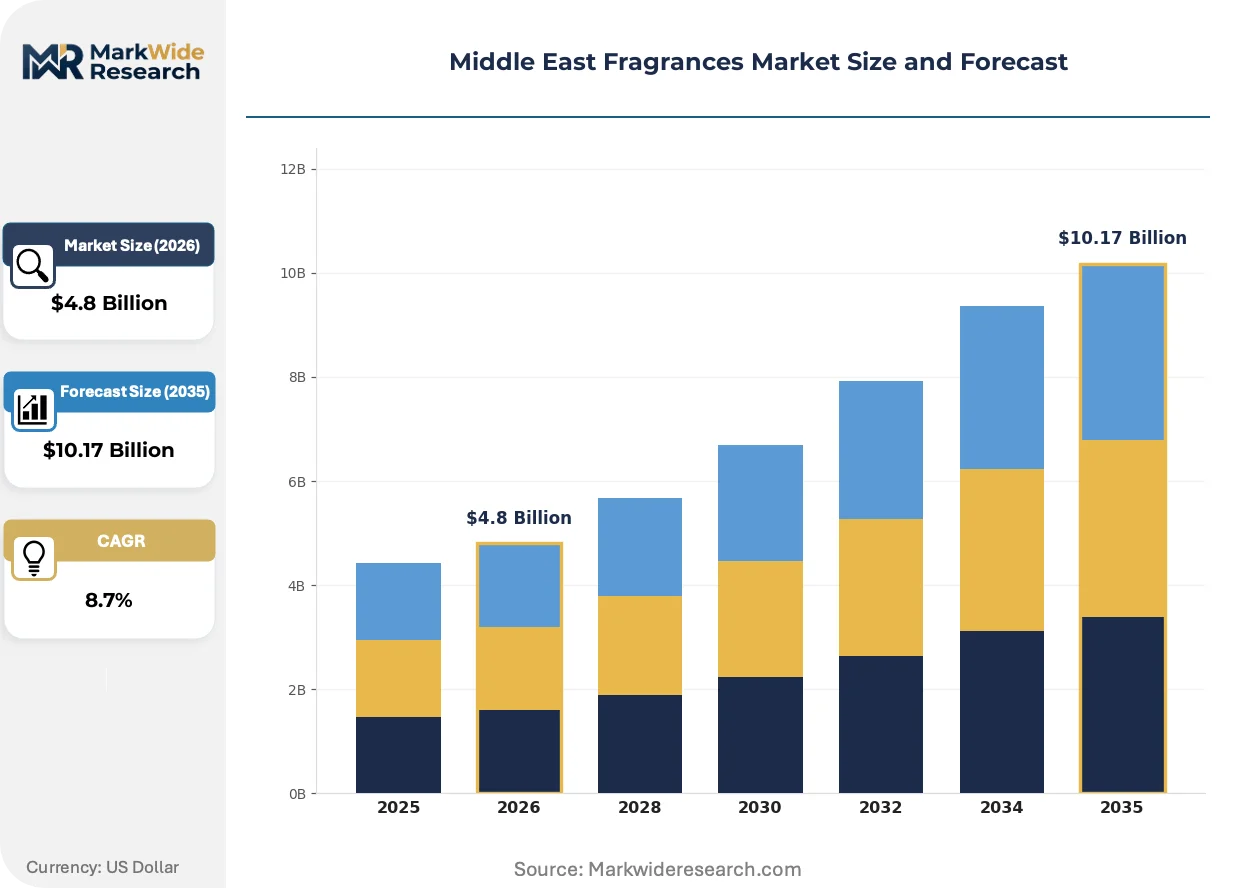
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eau de Parfum, Eau de Toilette, Perfume Oils, Body Mists End User: Men, Women, Unisex, Children Distribution Channel: Online Retail, Specialty Stores, Department Stores, Supermarkets Packaging Type: Spray Bottles, Roll-ons, Solid Perfumes, Samples |
| Companies Covered | Al Haramain Perfumes, Ajmal Perfumes, Abdul Samad Al Qurashi, Arabian Oud, Rasasi Perfumes, Lattafa, Armaf, Amouage, The Fragrance Kitchen, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Fragrances Market Trends and Innovations
Digital authentication technologies and modular production systems are restructuring how Middle Eastern fragrance houses manage provenance claims and scale artisanal formulations without sacrificing batch consistency.
Encapsulation technology for controlled scent release is modularizing how perfume oils interact with skin chemistry and ambient temperature. Premium attar producers in the UAE are adopting microsphere delivery systems to extend fragrance longevity in high-heat climates. This modularizing of release kinetics is compressing the performance gap between pure oils and Western-style eau de parfum formats.
MOHAP's expanded allergen disclosure requirements for retail fragrance formulations are forcing reformulation of legacy amber and musk accords. The Emirates Conformity Assessment Scheme now mandates quantitative labeling for 26 additional sensitizing compounds. Smaller Omani and Kuwaiti houses are responding by simplifying ingredient palettes rather than absorbing compliance testing costs.
Direct-to-consumer subscription models for oud discovery sets are disrupting mall-dependent distribution in Saudi Arabia's secondary cities. Younger buyers in Dammam and Khobar now sample curated oil collections via monthly deliveries before committing to full-bottle purchases. This channel shift is most visible among demographics under 35 seeking alternatives to family-assisted buying decisions.
Middle East Fragrances Market Segmentation
Segmentation in Middle Eastern fragrance markets reveals how cultural preferences, regulatory constraints, and retail infrastructure shape distinct consumption patterns across product formats and buyer demographics. Understanding these divides exposes where margin pools concentrate and which channels are capturing shifting purchase behaviors.
Product Type:
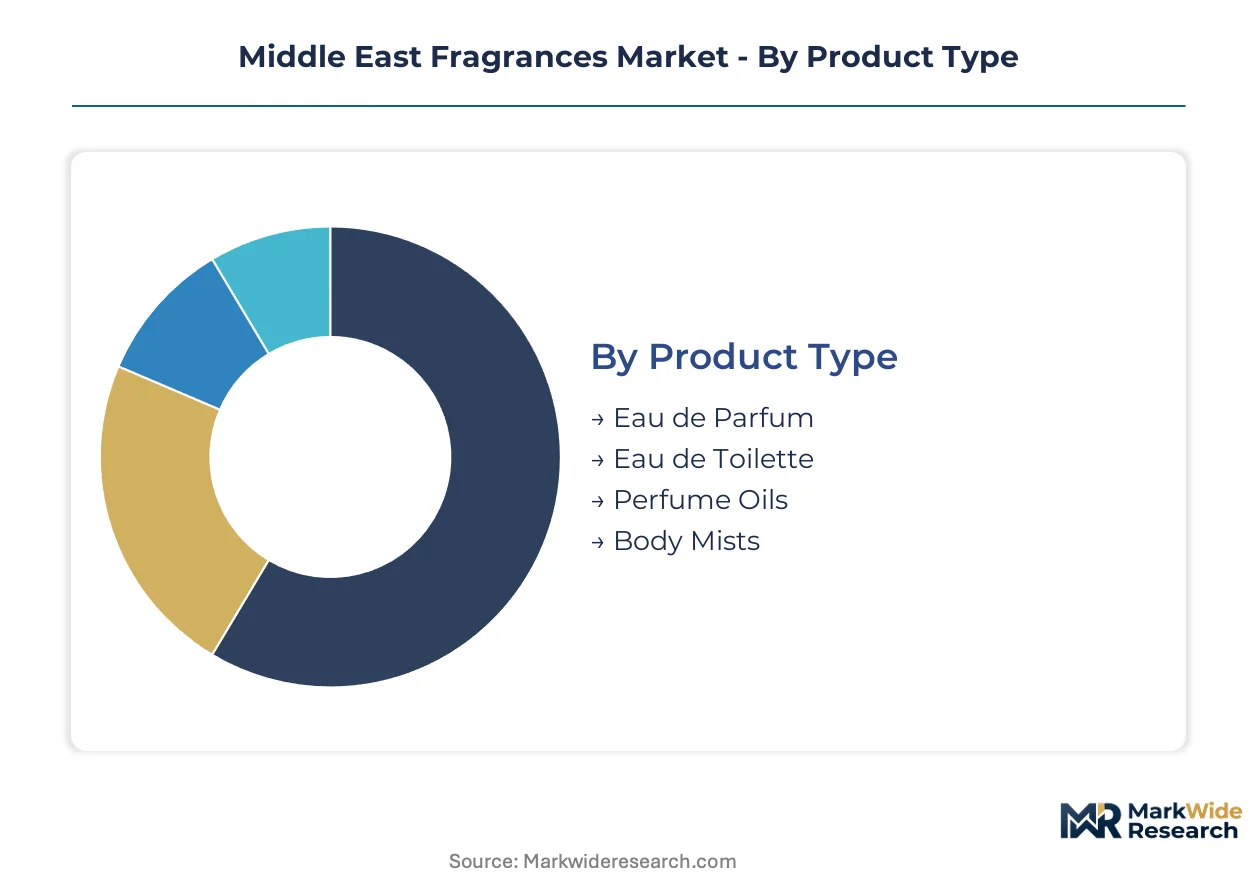
Upgrade cycles in this category accelerate as consumers move from alcohol-based formats toward higher-concentration oils that comply with tightening halal standards across Gulf markets.
- Perfume Oils:Alcohol-free formulations exceeding 20 percent aromatic compounds, traditionally centered on oud, amber, and musk accords. Saudi Arabia's SFDA labeling mandates are formalizing previously informal attar supply chains, driving demand toward certified concentrated oils in Riyadh and Jeddah retail corridors.
- Eau de Parfum:Alcohol-based scents with 15-20 percent fragrance concentration, positioned as portable alternatives for younger demographics and workplace environments. UAE mall operators in Dubai and Abu Dhabi report rising parfum sales among under-35 buyers seeking international-style formats compatible with air travel and office settings.
- Eau de Toilette:Lighter 5-15 percent concentration formulations serving entry-price positioning and humid climate adaptation.
- Body Mists:Low-concentration, high-volume spray formats targeting casual daily use and gift bundling applications.
Perfume oils sit at the top of the volume ranking, with eau de parfum climbing the fastest among format-switching younger consumers.
End User:
Cost tier stratification separates prestige gifting segments from self-purchase routines, with unisex formulations commanding premium positioning through shared household consumption economics.
- Women:Primary decision-makers for household fragrance procurement, with concentrated oud oils dominating personal collections and social gifting obligations in Saudi Arabia and the UAE.
- Men:Strong preference for concentrated attar formats in professional and religious contexts, with dedicated product lines from regional houses targeting male-coded oud and woody accords.
- Unisex:Rose-amber and white musk formulations designed for shared consumption, capturing premium margins through dual-user household economics.
- Children:Alcohol-free, hypoallergenic oil formats for special occasion use, subject to heightened MOHAP safety testing requirements in UAE retail channels.
Women's formulations retain volume leadership, while unisex positioning gains share fastest through premium positioning and reduced inventory complexity for retailers.
Distribution Channel:
Application-based channel selection tracks where authentication, convenience, or price sensitivity dominates the purchase occasion.
- Specialty Stores:Mall-based boutiques and souk perfumeries providing provenance verification, custom blending, and sensory trial. Dubai's fragrance precinct renovations and Riyadh's luxury retail expansions are elevating specialty channel visibility.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capturing discovery-set subscriptions and repeat replenishment in Saudi Arabia's secondary cities.
- Department Stores:Multi-brand counters serving tourist and expatriate segments with international fragrance portfolios.
- Supermarkets:Mass-market spray formats and gift sets for routine replenishment and impulse purchase.
Specialty stores dominate value concentration, with online retail expanding most quickly through subscription mechanics and geographic reach beyond primary urban corridors.
Packaging Type:
Supply concentration in glass manufacturing and precision molding shapes which formats achieve cost efficiency at scale.
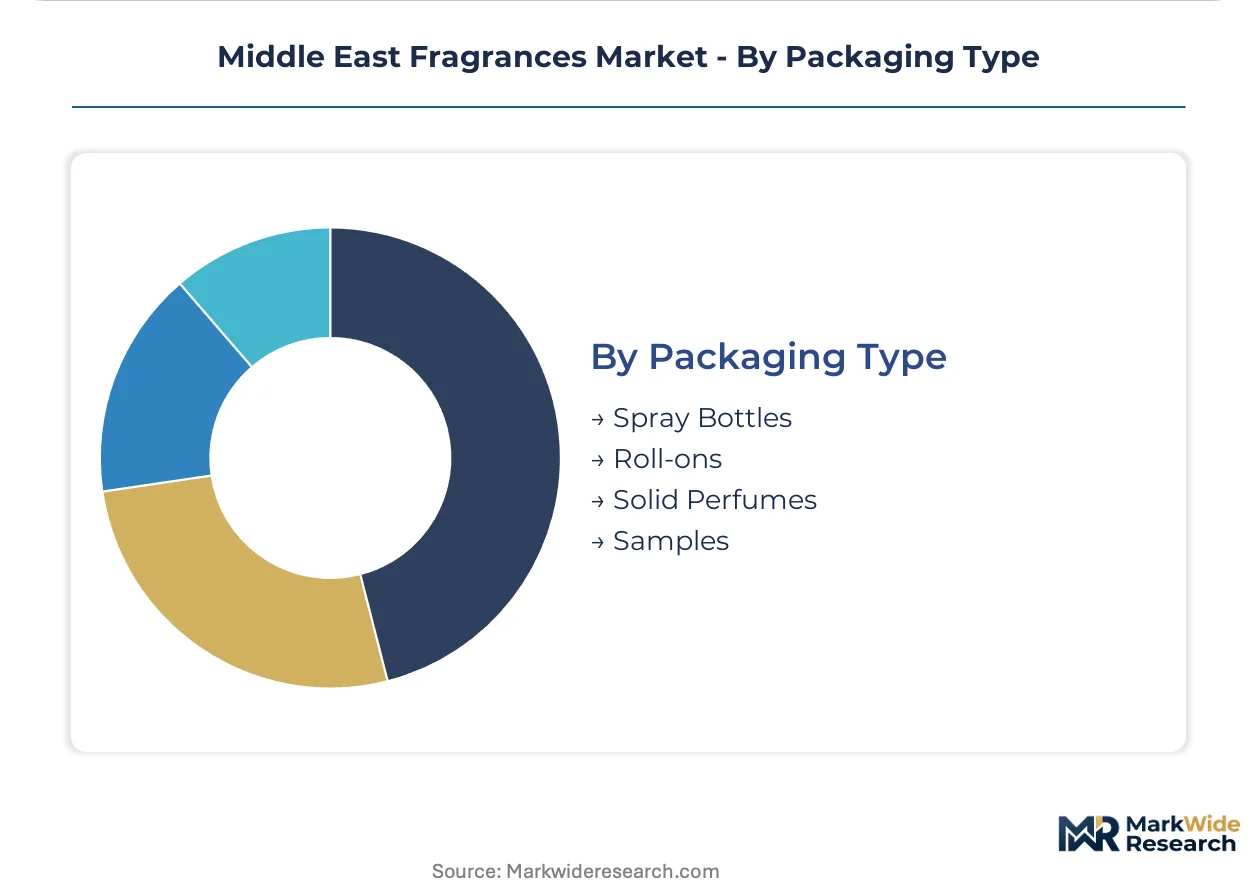
- Spray Bottles:Standard atomizer packaging for alcohol-based formulations, with UAE and Saudi Arabian converters supplying regional fragrance houses.
- Roll-ons:Glass or crystal vials with ball applicators for precise oil dispensing, preferred for concentrated attar portability and controlled application.
- Solid Perfumes:Wax-based formulations in compact cases, serving travel and religious context requirements where liquid restrictions apply.
- Samples:Miniature vials and discovery formats driving trial conversion in online subscription models and mall-based experiential retail.
Spray bottles lead absolute volume, though roll-on formats show steepest expansion trajectory as oil-based consumption displaces alcohol alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle Eastern fragrance tradition traces its commercial roots to the incense trade routes of antiquity, with modern industrial scale emerging from Dubai's duty-free revolution and Saudi Arabia's domestic oil wealth. Distinct regulatory regimes and consumption patterns now characterize each Gulf market.
Saudi Arabia
Riyadh and Jeddah concentrate demand for concentrated attar and oud oils, with household gifting obligations driving premium purchase cycles. The Saudi Food and Drug Authority enforces ingredient disclosure mandates for perfume oils, formalizing previously informal supply chains. Eastern Province cities like Dammam and Khobar are emerging as secondary consumption hubs through direct-to-consumer subscription channels targeting younger demographics.
United Arab Emirates
Dubai anchors regional distribution through Mall of the Emirates and Dubai Mall fragrance precincts, while Abu Dhabi develops parallel luxury retail corridors. The Ministry of Health and Prevention mandates expanded allergen labeling for 26 sensitizing compounds under the Emirates Conformity Assessment Scheme. Sharjah's industrial zones house precision glass converters supplying roll-on vial packaging to regional formulators.
Oman
Muscat preserves artisanal oud compounding traditions that command ultra-premium positioning in Gulf markets. The Sultanate's heritage-focused regulatory framework protects geographic indication claims for Dhofar-region frankincense integration. Salalah's agarwood trading posts historically supplied raw materials now supplemented by Southeast Asian plantation sources.
Kuwait
Kuwait City's mall-based specialty stores serve high-net-worth consumers with limited domestic production capacity. Simplified ingredient palettes are emerging among smaller houses responding to compliance cost pressures from neighboring regulatory regimes. The emirate's travel retail exposure connects South Asian transit passengers to oud discovery formats.
Qatar
Doha's luxury hospitality sector embeds bespoke fragrance experiences into guest loyalty programs at five-star properties. Regulatory alignment with GCC halal certification standards is reducing import friction for regional brands. Lusail's planned retail districts are recruiting regional fragrance houses for experiential oud blending studios.
Middle East Fragrances Market Competitive Landscape
The competitive structure tilts toward heritage-rooted regional specialists with captive agarwood sourcing relationships. Concentration remains moderate, with tiered positioning separating vertically integrated oud houses from portfolio diversifiers and international-format entrants. Three archetypes dominate: plantation-integrated raw material controllers, mall-dependent retail network builders, and ultra-premium extraction specialists. Capacity expansion in cultivated oud plantations and strategic partnerships for cold-chain distribution constitute the primary competitive vectors.
Among vertically integrated regional houses, Ajmal Perfumes exemplifies upstream control through captive agarwood sourcing, while Rasasi Perfumes anchors mall-based distribution network scale across Gulf Cooperation Council markets. Amouage occupies the ultra-premium extraction tier through high-concentration formulations originating from Oman.
| Leading Market Players |
|---|
| Al Haramain Perfumes |
| Ajmal Perfumes |
| Abdul Samad Al Qurashi |
| Arabian Oud |
| Rasasi Perfumes |
| Lattafa |
| Armaf |
| Amouage |
| The Fragrance Kitchen |
| Others |
Pricing and Supply Chain Analysis
Halal certification mandates from Saudi Arabia's SFDA and the UAE's MOHAP are forcing fragrance houses to reformulate alcohol-based inventories into oil-based alternatives, compressing margins on legacy stock while concentrating procurement power among suppliers of certified concentrated bases.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the Middle Eastern fragrance market by concentration grade and provenance certification. Price differentiation hinges on agarwood sourcing tier — plantation-grade versus wild-harvest — and halal compliance depth. Cost compression in standard-tier attar formulations is intensifying because smaller Omani and Kuwaiti houses are simplifying ingredient palettes to avoid MOHAP allergen testing costs. Mass-market buyers in Saudi Arabia's secondary cities exhibit highest price sensitivity, while ultra-premium extraction specialists serving Gulf luxury hospitality command lowest elasticity.
Supply Chain Analysis
Agarwood supply rests on plantation developments in Southeast Asia — Vietnam, Thailand, and Malaysia — supplemented by residual wild harvesting from Indochina under CITES Appendix II constraints. Raw material dependencies center on Aquilaria species resin, precision glass vial manufacturing from Sharjah's industrial zones, and synthetic musk alternatives for alcohol-free bases. Single-source vulnerability concentrates in aging master perfumer expertise concentrated in Oman and Yemen. Distribution runs through mall-based specialty boutiques in Dubai and Riyadh, with direct-to-consumer subscription channels expanding in Saudi Arabia's Eastern Province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where SFDA ingredient disclosure mandates and MOHAP allergen labeling expansions are accelerating formalization of previously informal attar supply chains, creating structural demand for certified production capacity.
For Market Incumbents: Extend captive agarwood plantation relationships through long-term offtake agreements with Southeast Asian suppliers to lock in input cost stability against CITES-driven wild harvest constraints. Deepen cold-chain distribution partnerships across secondary Gulf cities before infrastructure gaps close. Certification investment in unified GCC halal standards reduces multi-country compliance duplication and defends margin position against emerging portfolio diversifiers. For New Entrants and Emerging Players: Capture direct-to-consumer subscription white space in Saudi Arabia's Dammam and Khobar corridors where younger demographics under 35 seek alternatives to family-assisted buying decisions. Target experiential retail formats — oud blending studios in Abu Dhabi malls — where personalized fragrance creation services command premium positioning. Digital-native discovery set models offer the most penetrable entry vector against mall-dependent incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated regional houses possessing captive plantation sourcing and established GCC distribution networks. Long-term viability over the coming decade hinges on securing agarwood supply contracts ahead of plantation capacity constraints. Watch for inflection signals in cold-chain infrastructure buildout across Qatar and Kuwait, which would unlock geographic expansion for temperature-sensitive oil formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Plantation Integration | Captive agarwood sourcing from Vietnam and Thailand reduces CITES exposure and stabilizes raw material input costs. |
| Halal Certification Convergence | Unified GCC standards reduce compliance duplication for regional brands expanding across Saudi Arabia and UAE markets. |
| Experiential Retail Expansion | Oud blending studios in Jeddah and Abu Dhabi malls capture premium margins through personalized fragrance creation services. |
| Cold-Chain Infrastructure Buildout | Temperature-controlled logistics investments in Qatar and Kuwait unlock distribution for heat-sensitive oil formulations. |
| Digital Subscription Models | Direct-to-consumer discovery sets in Saudi Arabia's Eastern Province disrupt mall-dependent distribution among younger demographics. |
Research Methodology
Direct dialogue with fragrance house R&D directors, GCC regulatory affairs specialists, mall-based retail operators, and agarwood plantation managers in Southeast Asia anchored primary intelligence gathering. Secondary validation drew from SFDA and MOHAP regulatory filings, Emirates Conformity Assessment Scheme documentation, CITES trade permit records, and customs data tracking concentrated oil imports across Gulf Cooperation Council member states. Bottom-up demand modeling and top-down supply capacity assessments were triangulated to establish market sizing.
Segmentation outputs across product type, end user, distribution channel, and packaging format were generated through the analytical framework applied across the projection horizon. CAGRs were derived from regression analysis against historical consumption patterns, regulatory implementation timelines, and hospitality sector expansion trajectories. Industry-specific forecast inputs included agarwood plantation yield curves and halal certification adoption rates across regional formulators.
Wild agarwood depletion acceleration, synthetic musk substitution technical failures, and GCC regulatory divergence are the dominant revision risks to modeled outcomes. Forecasts embed assumptions around plantation-grade agarwood supply scalability and cold-chain infrastructure development pace. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Evaporative Diffusers Market
Fragrances & Perfumes
Mini Refillable Perfume Bottles Market
Fragrances & Perfumes
Fragrance Product Market
Fragrances & Perfumes
Fragrance Oil Market
Fragrances & Perfumes
Digital Fragrance Market
Fragrances & Perfumes
Home Fragrance Market
Fragrances & Perfumes
Saudi Arabia E-Commerce Cosmetics and Fragrances Market
Fragrances & Perfumes
Kuwait Perfume Market
Fragrances & Perfumes
Fragrance Emulsion Market
Fragrances & Perfumes
Cosmetic and Fragrance Retail Chain Market
Fragrances & Perfumes
Smart Fragrance Box Market
Fragrances & Perfumes
Reed Diffusers Market
Fragrances & Perfumes
Floral Water Spray Market
Fragrances & Perfumes
Gourmand Fragrance Market
Fragrances & Perfumes
Digital Scent Market
Fragrances & Perfumes
Global Fragrances and Perfumes Market