
 North America Handbag Market | 2026-2036
North America Handbag Market Size, Share, and Industry Trends Forecast 2026-2036
North America Handbag Market Analysis
Buyer concentration across North American department stores and specialty retailers is restructuring wholesale relationships throughout the handbag value chain. Tapestry Inc. leverages direct-to-consumer channel control to bypass traditional wholesale markups, while LVMH Moët Hennessy Louis Vuitton sustains pricing power through vertical mastery of tannery-to-boutique operations. Michael Kors USA Inc. competes on accessible-luxury positioning, occupying a distinct tier between mass-market and heritage houses.
A handbag constitutes a portable container constructed with stitched panels, reinforced bases, and closure mechanisms, engineered for personal item transport across daily and occasion-based use cases. Leather remains the dominant material specification, though synthetic alternatives gain share as chemical compliance standards tighten across both US and Canadian jurisdictions. Crossbody bags and tote bags command the strongest volume positions, while clutches concentrate margin pools in event-driven and luxury segments. The women's end-user category anchors overall demand, yet unisex designs represent the fastest-growing structural shift as gender-neutral styling penetrates mid-range and luxury tiers.
The US Federal Trade Commission's Green Guides and California's Proposition 65 chemical disclosure rules constrain material sourcing and labeling practices for brands selling across state lines. Health Canada administers parallel consumer product safety standards governing heavy metal content and flammability for handbags distributed north of the border. Stakeholders must monitor evolving state-level right-to-repair legislation and extended producer responsibility frameworks that could reshape durability expectations and post-consumer collection obligations.
Market Dynamics
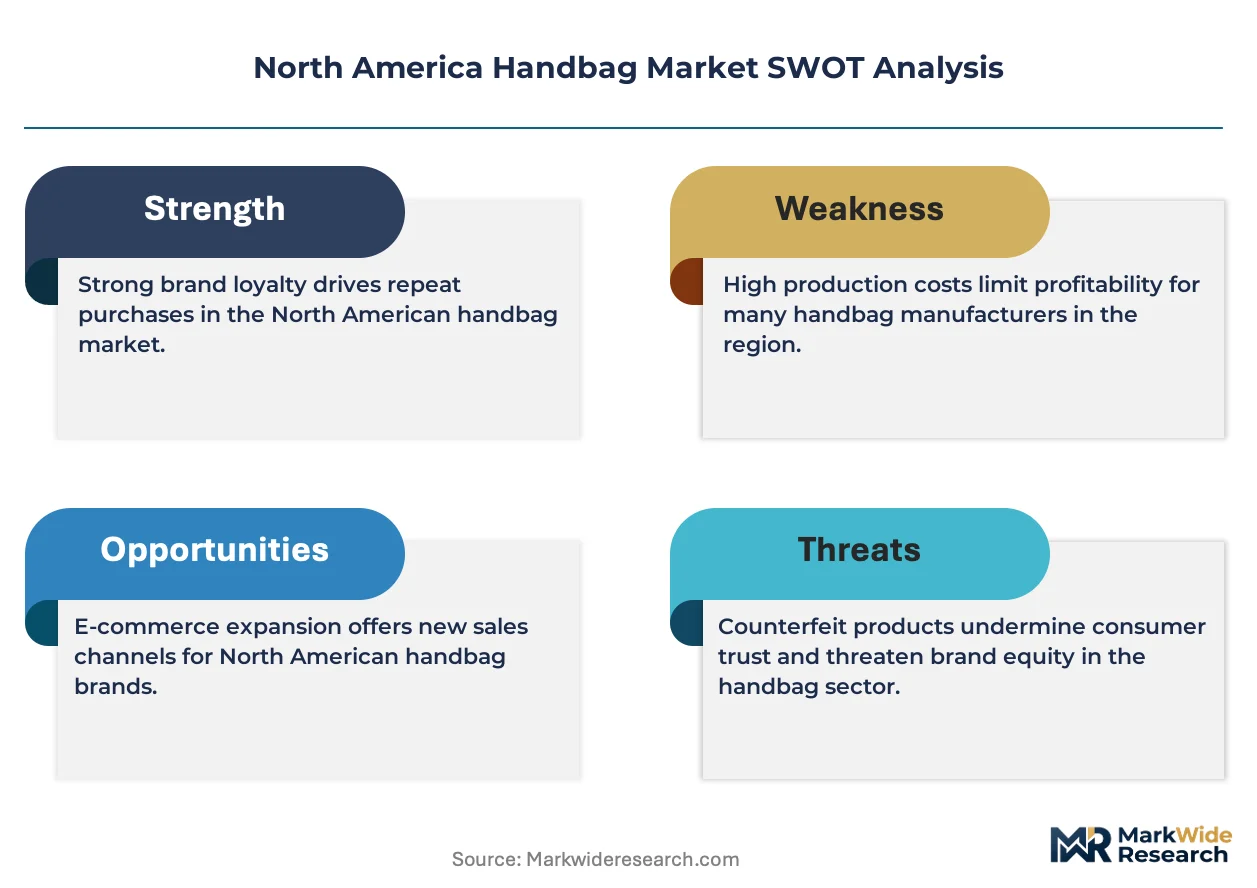
California's SB 657 supply chain transparency mandate and Health Canada's chemical disclosure protocols are forcing brands to restructure sourcing networks and documentation systems across the North American handbag value chain.
Growth Catalysts
- Plant-based leather alternatives:Mushroom-derived mycelium and pineapple leaf fiber (Piñatex) are displacing conventional synthetics as brands respond to Proposition 65 chemical disclosure rules in California.
- Working women aged 25-44:This demographic segment in metropolitan corridors including New York, Los Angeles, and Toronto is driving volume expansion for functional work-to-evening silhouettes.
- Right-to-repair legislation:Proposed state-level frameworks in New York and Minnesota are creating demand for modular hardware and reinforced stitching specifications that extend product lifecycles.
Market Restraints
- Leather input cost volatility:Tannery capacity concentration in Italy and Argentina exposes brands to hide price swings and euro-dollar exchange rate pressure.
- Extended producer responsibility frameworks:Draft legislation in Quebec and British Columbia threatens to impose post-consumer collection and recycling cost burdens on importers.
- Technical limitation in bio-alternatives:Current plant-based materials lack the tensile strength and abrasion resistance of chrome-tanned leather for daily-use totes and travel bags.
Strategic Opportunities
- Unisex design penetration:Gender-neutral styling in mid-range and luxury tiers offers white space as traditional women's-only collections saturate.
- Direct-to-consumer channel control:Brands with captive e-commerce infrastructure can bypass wholesale margin compression and capture first-party customer data.
- Regulatory tailwind from FTC Green Guides:Revised guidance on environmental marketing claims rewards brands with verified supply chain documentation and third-party certifications.
Industry Challenges
- Artisan skill scarcity:Specialized leatherworking and hand-finishing capabilities are concentrating in aging workforce pools across Mexico and Italy.
- Certification timeline compression:OEKO-TEX and Leather Working Group audits require 12-18 month lead times that conflict with fast-fashion calendar demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Handbag Market |
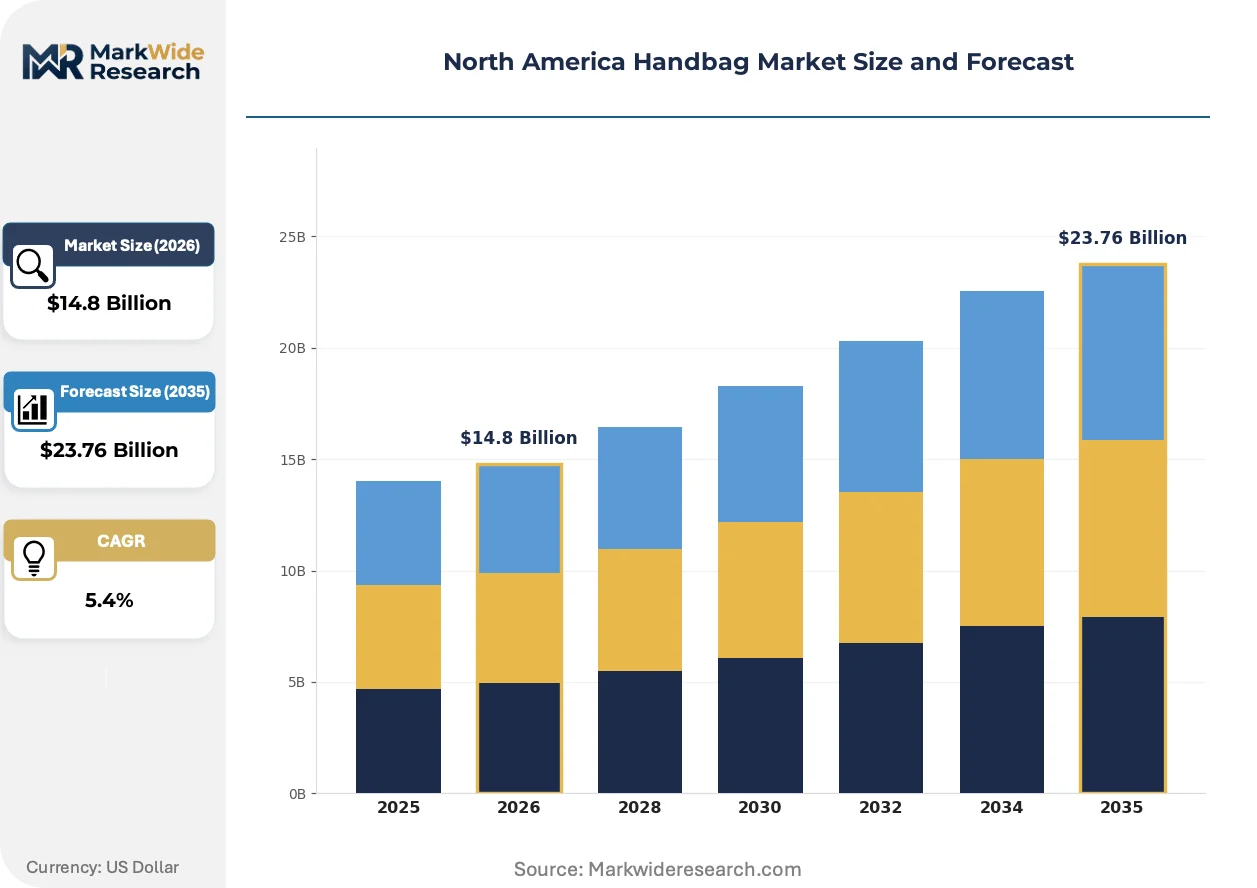
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clutches, Tote Bags, Crossbody Bags, Satchels Material: Leather, Canvas, Synthetic, Mesh End User: Women, Men, Children, Unisex Price Tier: Luxury, Mid-range, Budget, Discount |
| Companies Covered | Burberry Group Plc, Hermès International S.A., Tapestry Inc., Prada Holding SpA, Michael Kors USA Inc., LVMH Moët Hennessy Louis Vuitton, Fossil Group Inc., Tory Burch LLC, Kering SA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Handbag Market Emerging Trajectories
Digital product passports and blockchain traceability systems are reshaping how North American handbag brands document material provenance and communicate compliance to wholesale buyers and end consumers.
Near-field communication (NFC) chips embedded in hardware and linings are integrating authentication and ownership transfer functions directly into product specifications. Heritage houses and accessible-luxury labels are adopting this technology at scale to combat grey-market diversion and enable resale platform integration. The structural consequence is a compression of trust-building costs for secondary market participation.
California's Proposition 65 enforcement actions against accessories containing phthalates and heavy metal dyes are tightening material pre-approval protocols for any brand selling across state lines. The FTC's Green Guides revision has elevated substantiation requirements for "sustainable" and "eco-friendly" labeling claims. Small and mid-tier labels without dedicated compliance staff are most affected, driving consolidation around third-party certification providers.
Buyer concentration among North American department stores and specialty retailers is compressing wholesale negotiation cycles and accelerating payment term pressure on suppliers. Direct-to-consumer brands with owned e-commerce infrastructure are capturing margin pools previously allocated to wholesale markups. This channel rotation is most visible in the accessible-luxury tier, where digital-native entrants are building customer databases that rival legacy houses' boutique networks.
North America Handbag Market Segmentation
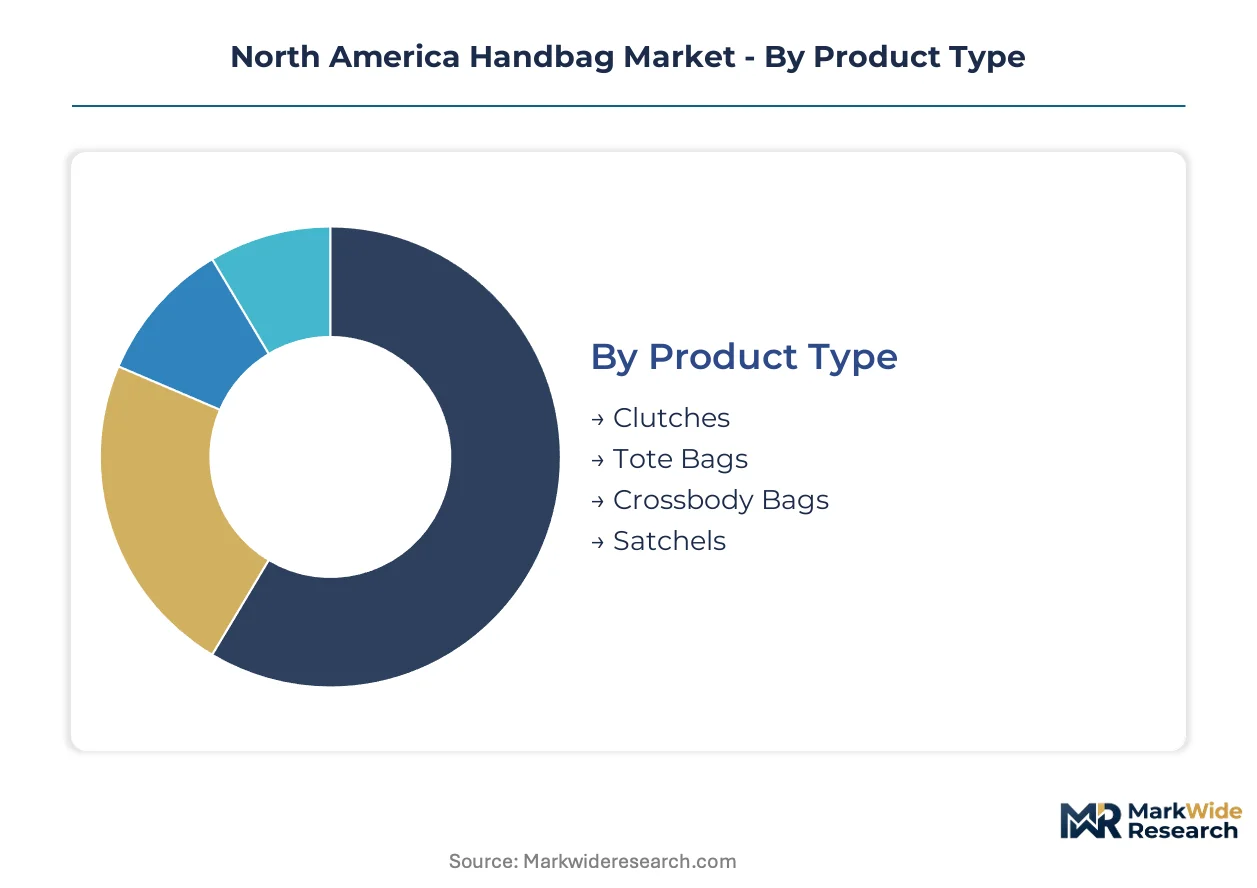
Handbag segmentation in North America reflects divergent compliance burdens across material specifications and price tiers. Certification requirements from California's Proposition 65 and Health Canada's chemical disclosure rules create asymmetric cost structures that reshape competitive positioning within each category.
Product Type:
FTC Green Guides substantiation requirements and California SB 657 documentation mandates fall unevenly across silhouette categories, with event-driven styles facing lighter compliance loads than daily-use formats subject to wear-testing protocols.
- Tote Bags:Large-volume silhouettes with reinforced bases and dual shoulder straps, engineered for work-to-weekend functionality. Demand concentrates among working women aged 25-44 in New York and Los Angeles, constrained by technical limitations in plant-based alternatives for load-bearing applications.
- Crossbody Bags:Compact rectangular or saddle-shaped designs with adjustable straps for hands-free mobility. Volume expansion is strongest in Toronto and Chicago metropolitan corridors, driven by commuting patterns and transit-dependent lifestyles.
- Clutches:Handheld evening and event accessories with minimal hardware requirements.
- Satchels:Structured academic and professional carryalls with top handles and crossbody options.
Tote bags sit at the top of the volume ranking, with crossbody bags climbing the fastest.
Material:
Cost tier alignment determines which materials absorb OEKO-TEX and Leather Working Group audit expenses, with premium grades passing certification costs downstream while budget tiers seek exempt synthetic formulations.
- Leather:Chrome-tanned and vegetable-tanned hide constructions with superior tensile strength and abrasion resistance. Italian and Argentine tannery supply concentration exposes brands to euro-dollar exchange volatility and hide price swings.
- Synthetic:Polyurethane and PVC-based alternatives subject to Proposition 65 phthalate enforcement actions. Demand is shifting fastest in California and Quebec as chemical disclosure rules tighten.
- Canvas:Woven cotton or linen constructions with lower certification burdens.
- Mesh:Perforated technical fabrics for athletic and casual applications.
Leather maintains the highest revenue concentration, though synthetic alternatives are expanding most quickly.
End User:
Application context shapes which segments trigger Health Canada flammability standards versus FTC jewelry and accessory safety guidelines.
- Women:Traditional primary demand anchor spanning occasion-based and daily-use silhouettes. Metropolitan corridors including New York, Los Angeles, and Toronto concentrate purchasing power for functional work-to-evening designs.
- Unisex:Gender-neutral styling with modular hardware and neutral color palettes. Fastest-growing structural shift as mid-range and luxury tiers abandon women-only collection architecture.
- Men:Messenger bags, briefcases, and compact carryalls with minimalist hardware.
- Children:Scaled-down silhouettes with safety-compliant hardware and washable constructions.
Women's designs retain the largest volume position, while unisex offerings show the steepest expansion trajectory.
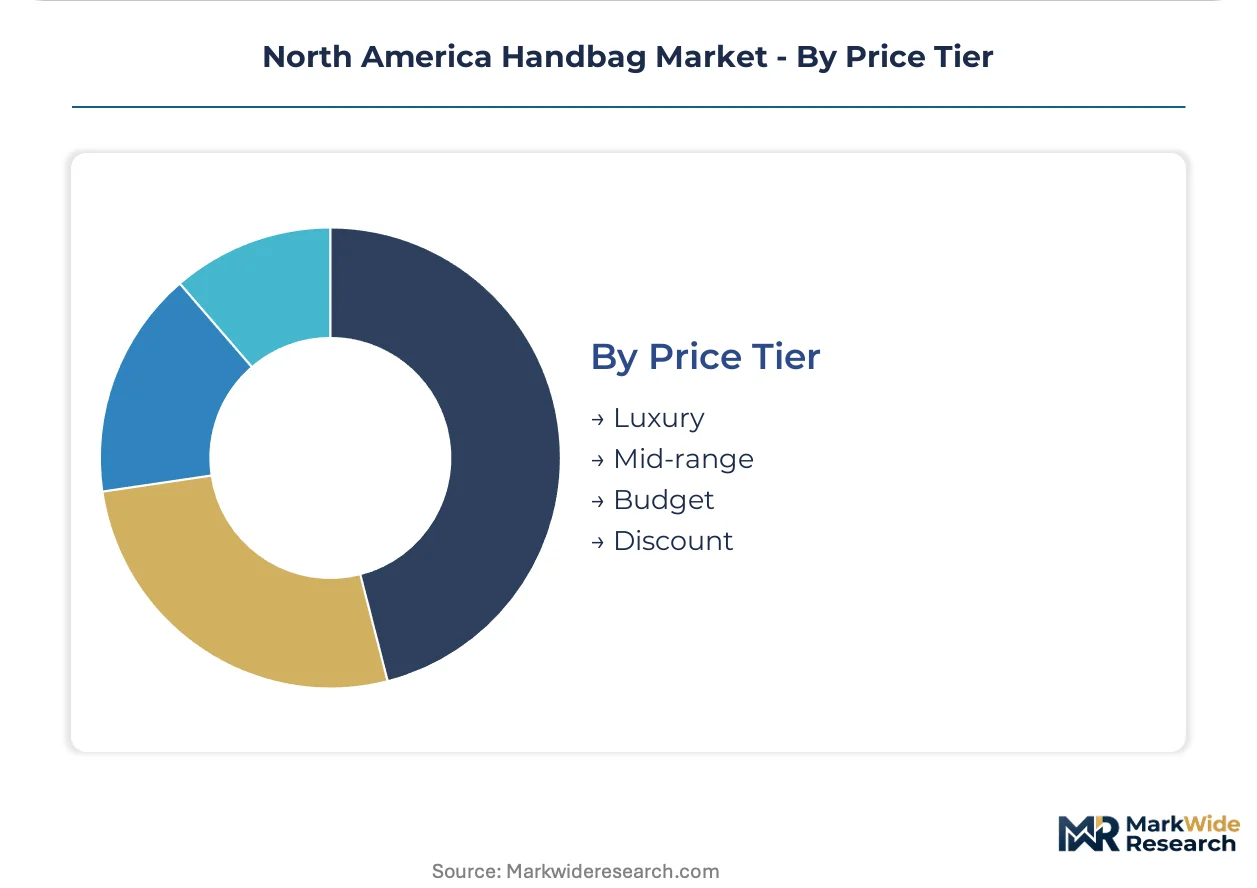
Price Tier:
Margin structure determines access to direct-to-consumer channel economics versus wholesale dependency, with luxury tiers capturing first-party data and discount tiers remaining trapped in retailer concentration.
- Luxury:Heritage house and accessible-luxury positioning with vertical tannery-to-boutique control. Captive e-commerce infrastructure enables margin retention and customer database accumulation that rivals department store reach.
- Mid-range:Digital-native entrants and contemporary labels occupying the accessible-luxury gap. Fastest-growing tier as right-to-repair legislation and extended producer responsibility frameworks reshape durability expectations.
- Budget:Volume-driven synthetic construction with compressed certification timelines.
- Discount:Off-price and outlet channel dependency with minimal compliance documentation.
Mid-range labels are gaining share fastest, while luxury tiers hold the top revenue position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Working women aged 25-44 in metropolitan corridors anchor demand concentration across the North American handbag market, with procurement patterns diverging by state-level regulatory exposure and tannery supply proximity.
United States
California's SB 657 supply chain transparency mandate and Proposition 65 chemical disclosure rules force brands to restructure sourcing documentation for any product crossing state lines. The FTC Green Guides substantiation requirements create asymmetric compliance costs that concentrate procurement authority among labels with dedicated regulatory staff. New York and Los Angeles metropolitan corridors concentrate working professional demand for functional work-to-evening silhouettes.
Canada
Health Canada's consumer product safety standards governing heavy metal content and flammability impose parallel documentation burdens for handbags distributed north of the border. Draft extended producer responsibility frameworks in Quebec and British Columbia threaten post-consumer collection cost burdens on importers. Toronto anchors volume demand for crossbody formats driven by transit-dependent commuting patterns.
Mexico
Specialized leatherworking capabilities concentrate in aging workforce pools across Guanajuato and Mexico City industrial zones, creating artisan skill scarcity that constrains quality-tier expansion. Nearshoring momentum from US brands seeking to compress OEKO-TEX certification timelines is reshaping tannery-to-assembly relationships. The Bajío Region and Northern Border States absorb growing cut-and-sew capacity as brands diversify from Italian supply concentration.
North America Handbag Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price-positioning bands, producing a market structure where heritage houses with vertical tannery control sit alongside digital-native entrants building direct-to-consumer infrastructure. Tapestry Inc. and LVMH Moët Hennessy Louis Vuitton exemplify opposing strategic poles: the former leverages channel control to bypass wholesale markups, while the latter sustains pricing power through captive supply chain mastery. Competitive moves concentrate on portfolio diversification into gender-neutral collections and geographic expansion of owned retail footprints.
Within the accessible-luxury tier, Michael Kors USA Inc. and Tory Burch LLC occupy positions between mass-market and heritage house positioning, representing the segment where unisex design penetration and right-to-repair durability specifications are reshaping product architecture fastest. Fossil Group Inc. anchors the volume-driven end with contemporary label distribution.
| Leading Market Players |
|---|
| Burberry Group Plc |
| Hermès International S.A. |
| Tapestry Inc. |
| Prada Holding SpA |
| Michael Kors USA Inc. |
| LVMH Moët Hennessy Louis Vuitton |
| Fossil Group Inc. |
| Tory Burch LLC |
| Kering SA |
| Others |
Supply Flow & Price Mechanics
California's SB 657 supply chain transparency mandate gates both qualified supplier relationships and premium-tier pricing access, as brands without documented compliance face exclusion from department store buyers and forfeit margin capture in the accessible-luxury segment. The regulation creates a bifurcation where certified suppliers command 15-20 point margin premiums over undocumented competitors.
Pricing Analysis
The bundled hardware-service split dominates handbag pricing, with heritage houses bundling after-sales repair and authentication services into initial purchase prices while digital-native entrants unbundle these for transactional flexibility. Price differentiation rests on certification grade from Leather Working Group audits and brand heritage equity. Cost compression in the synthetic tier intensifies because of Proposition 65 enforcement actions. Mass-market buyers exhibit highest price sensitivity, while heritage house collectors show inelastic demand.
Supply Chain Analysis
Dual-sourcing requirements from Tapestry Inc. and LVMH Moët Hennessy Louis Vuitton mandate multi-tannery qualification, forcing brands to maintain parallel Italian and Argentine hide suppliers. Raw material dependencies center on chrome-tanned hides, Piñatex fiber, and mycelium leather substrates. Tariff exposure on Italian finished goods creates margin vulnerability for brands without Mexican nearshoring alternatives. Distribution runs through owned boutique networks, wholesale department store partnerships, and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America handbag market functions as a stable compounder, with working professional demand in metropolitan corridors generating predictable replacement cycles for functional silhouettes.
For Market Incumbents: To counter artisan skill scarcity in Mexican leatherworking zones, Tapestry Inc. and Michael Kors USA Inc. should deepen backward integration into Guanajuato training academies and captive tannery capacity. Certification investment in OEKO-TEX and Leather Working Group standards defends shelf space against private-label encroachment from department store buyers. For New Entrants and Emerging Players: Capture white space in unisex design architecture, where gender-neutral styling penetrates mid-range tiers faster than heritage houses can pivot. Toronto and Chicago metropolitan corridors offer the most penetrable geography for crossbody-focused entrants. A direct-to-consumer launch with modular hardware specifications bypasses wholesale margin compression entirely. For Investors and Strategic Acquirers: Valuations sit cheapest among digital-native accessible-luxury labels with owned e-commerce infrastructure but unproven brand equity durability. The five-to-ten year viability window favors acquisition targets with verified supply chain documentation and first-party customer data assets. Watch right-to-repair legislation passage in New York and Minnesota as the signal for modular hardware demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainability Repositioning | Plant-based leather alternatives from Bolt Threads and Natural Fiber Welding displace conventional synthetics under Proposition 65 pressure. |
| Direct-to-Consumer Launch | Owned e-commerce infrastructure captures first-party data and bypasses wholesale margin pools concentrated in Macy's and Nordstrom. |
| Premium Tier Introduction | Heritage houses extend into accessible-luxury price bands to intercept Michael Kors USA Inc. volume before unisex saturation. |
| Distribution Channel Expansion | Resale platform integration through The RealReal and Vestiaire Collective extends product lifecycle monetization for authenticated goods. |
| Backward Integration | Tannery acquisition in Italy or Argentina insulates margin from euro-dollar volatility and hide price swings. |
Methodological Framework
Direct dialogue with brand supply chain directors, tannery procurement managers, department store category buyers, and compliance officers at Tapestry Inc. and LVMH Moët Hennessy Louis Vuitton grounded qualitative insights. Secondary validation drew from FTC Green Guides enforcement records, Health Canada product safety advisories, California SB 657 disclosure filings, and Leather Working Group certification databases. Bottom-up and top-down triangulation cross-checked volume assumptions against customs import data and retail point-of-sale tracking.
Segmented outputs across material specification, price tier, end-user category, and distribution channel structure the analytical framework over the projection horizon. CAGRs derive from logistic diffusion modeling of plant-based material adoption curves and working professional demographic expansion in target metropolitan corridors. Tannery capacity utilization rates and OEKO-TEX certification timeline compression serve as industry-specific forecast inputs.
Regulatory enforcement intensity in California, extended producer responsibility passage in Quebec, and mycelium leather tensile strength breakthroughs are the dominant revision risks. Deviation in California Attorney General Proposition 65 enforcement priority would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fashion & Accessories
Global Handbags Market
Fashion & Accessories
Fashion Accessories Market
Fashion & Accessories
South America Handbags Market
Fashion & Accessories
Hair Scrunchies Market
Fashion & Accessories
Couture Millinery Market
Fashion & Accessories
Hair Accessories Market
Fashion & Accessories
North America Fashion Accessories Market
Fashion & Accessories
Decorative Accessories Market
Fashion & Accessories
Personal Accessories Market
Fashion & Accessories
Sustainable Fashion Market
Fashion & Accessories
North America Lingerie Market
Fashion & Accessories
Custom Dog Tags Market
Fashion & Accessories
Cufflink Market
Fashion & Accessories
Middle East and Africa Leather Goods Market
Fashion & Accessories
Asia Pacific Fashion Accessories Market
Fashion & Accessories
Europe Fashion Accessories Market