
 Saudi Arabia Perfume Market | 2026-2036
Saudi Arabia Perfume Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Perfume Market Intelligence
Luxury hospitality is pivoting toward bespoke oud-based scenting for hotels and resorts, elevating procurement standards for local fragrance houses. Arabian Oud leverages its captive distillation facilities in Taif to secure raw material quality. Abdul Samad Al Qurashi sustains dominance in premium bakhoor and concentrated perfume oils through heritage positioning. Ajmal Perfumes competes via its blended portfolio spanning traditional attars and Western-format eau de parfum.
Saudi Arabia perfume comprises alcohol-based and non-alcoholic fragrance formulations, typically containing essential oils, aromatic compounds, and fixatives at concentrations ranging from five percent to forty percent, designed for personal scenting, gifting, and ambient fragrance applications. Concentrated perfume oils and eau de parfum command the highest margin pools due to premium positioning and longer wear profiles among Gulf consumers. The unisex and women's target consumer segments show structural momentum as gender-fluid fragrance marketing gains traction in Riyadh and Khobar retail channels.
SFDA oversees fragrance safety and ingredient labeling compliance, while SASO mandates conformity assessments for imported cosmetic products, and halal certification bodies govern alcohol-free formulation claims in the Kingdom. These frameworks compel reformulation investments and restrict certain synthetic musks from entry. Stakeholders must monitor evolving halal standards and digital commerce regulations as online retail captures growing share of fragrance transactions.
Market Dynamics
SFDA fragrance safety standards and halal certification protocols are compressing formulation timelines and forcing ingredient disclosure investments across Saudi Arabia's perfume supply base.
Growth Catalysts
- Luxury Hospitality Scenting:Hotels and resorts across Makkah and Medina are commissioning bespoke oud-based ambient fragrance programs, elevating procurement volumes for local distillation houses.
- SFDA Regulatory Clarity:The Kingdom's fragrance safety framework provides compliant manufacturers with competitive moats against gray-market imports lacking ingredient transparency.
- Pilgrim Gifting Cycles:Umrah and Hajj visitor flows concentrate seasonal demand spikes in Jeddah airport retail and sacred precinct souvenir channels.
Market Restraints
- Agarwood Supply Concentration:Wild oud harvesting restrictions in Southeast Asian source regions create raw material bottlenecks for Taif-based distillation facilities.
- Halal Certification Friction:Alcohol-free formulation claims require multi-layer verification from religious certification bodies, extending product launch timelines by quarters.
- Synthetic Musk Substitution:Restricted nitro musk compounds face displacement by costlier macrocyclic alternatives, compressing margin pools in mass-market segments.
Strategic Opportunities
- Eastern Province Underpenetration:Khobar and Dammam retail corridors show whitespace for mall-based specialty fragrance concepts relative to Riyadh saturation.
- Digital Commerce Tailwinds:SASO e-commerce conformity pathways are streamlining cross-border fragrance listings on regional marketplace platforms.
- Gender-Fluid Positioning:Unisex fragrance marketing is converging with Western-format eau de parfum rollouts to capture evolving consumption preferences among younger Saudi buyers.
Industry Challenges
- Master Perfumer Scarcity:Traditional attar compounding expertise resides with aging practitioners, creating knowledge transfer gaps as houses scale Western-format production.
- Reformulation Capex Burden:SFDA-mandated ingredient substitutions require laboratory investment and stability testing cycles that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Perfume Market |
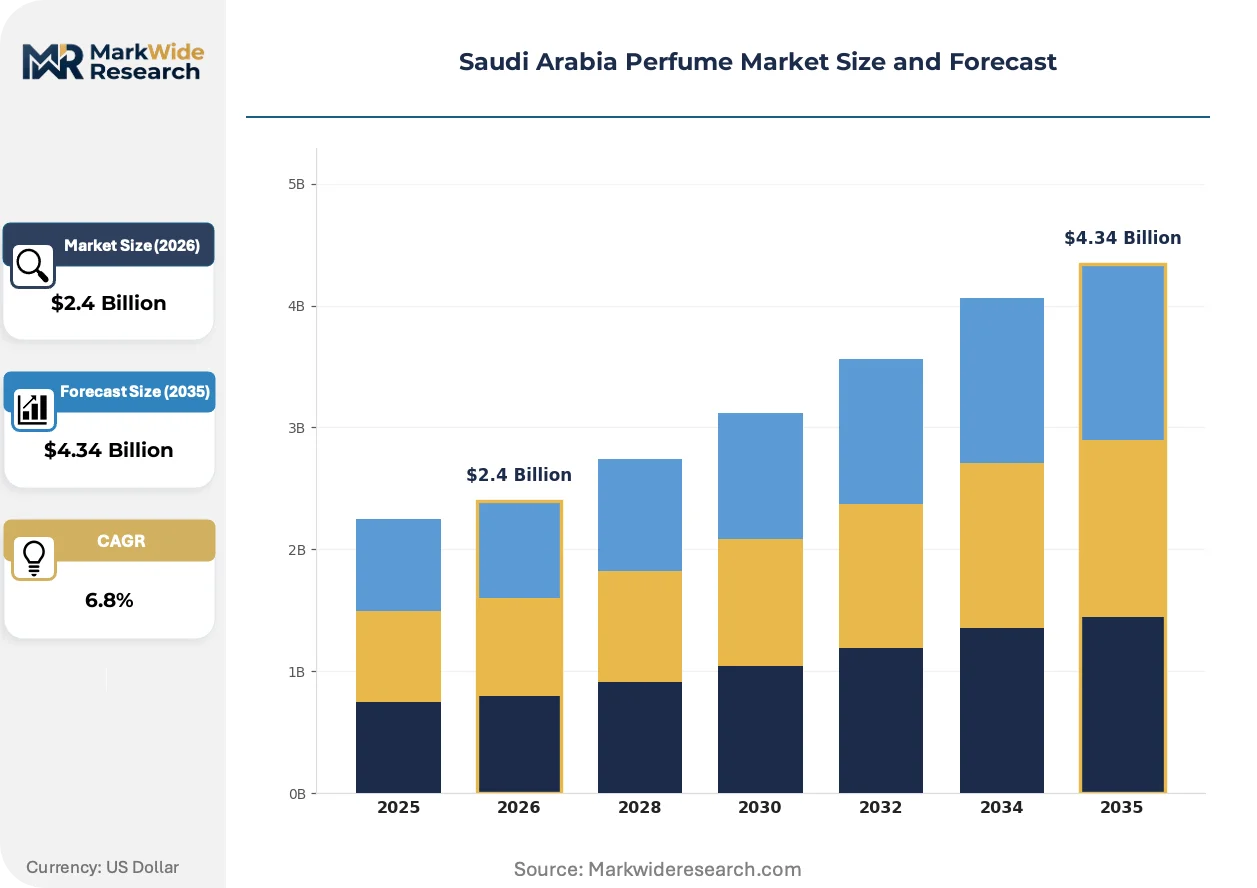
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated Perfume, Eau de Parfum, Eau de Toilette, Body Spray Target Consumer: Men, Women, Unisex, Youth Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Department Stores Fragrance Family: Floral, Woody, Oriental, Fresh |
| Companies Covered | Arabian Oud, Abdul Samad Al Qurashi, Ajmal Perfumes, Swiss Arabian, Al Haramain Perfumes, Rasasi Perfumes, Ahmed Al Maghribi Perfumes, Deraah Trading, Al Rehab Perfumes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Perfume Market Strategic Shifts & Innovations
Biotechnology and artificial intelligence are penetrating fragrance development workflows, compressing traditional compounding cycles while elevating precision in scent replication and consumer targeting.
Enzymatic oud synthesis is converging with molecular distillation techniques to reduce dependence on wild-harvested agarwood while preserving olfactory complexity. Taif-based producers are piloting these platforms to secure supply continuity. The structural consequence is a bifurcation between heritage-positioned wild oud offerings and lab-cultivated alternatives competing on sustainability claims.
SFDA's evolving fragrance safety standards are tightening disclosure requirements for allergen labeling and phototoxicity testing. Manufacturers must now submit comprehensive ingredient dossiers before market authorization. Premium concentrated perfume oil segments face the steepest compliance burden given higher essential oil loadings and corresponding sensitization risks.
Subscription-based fragrance discovery services are displacing traditional counter sampling in urban Saudi retail. Digital-native buyers across Riyadh and Jeddah are prioritizing home trial formats over mall-based consultation. This behavioral pivot is forcing heritage houses to reconfigure distribution investments toward direct-to-consumer logistics and personalized curation algorithms.
Saudi Arabia Perfume Market Segmentation
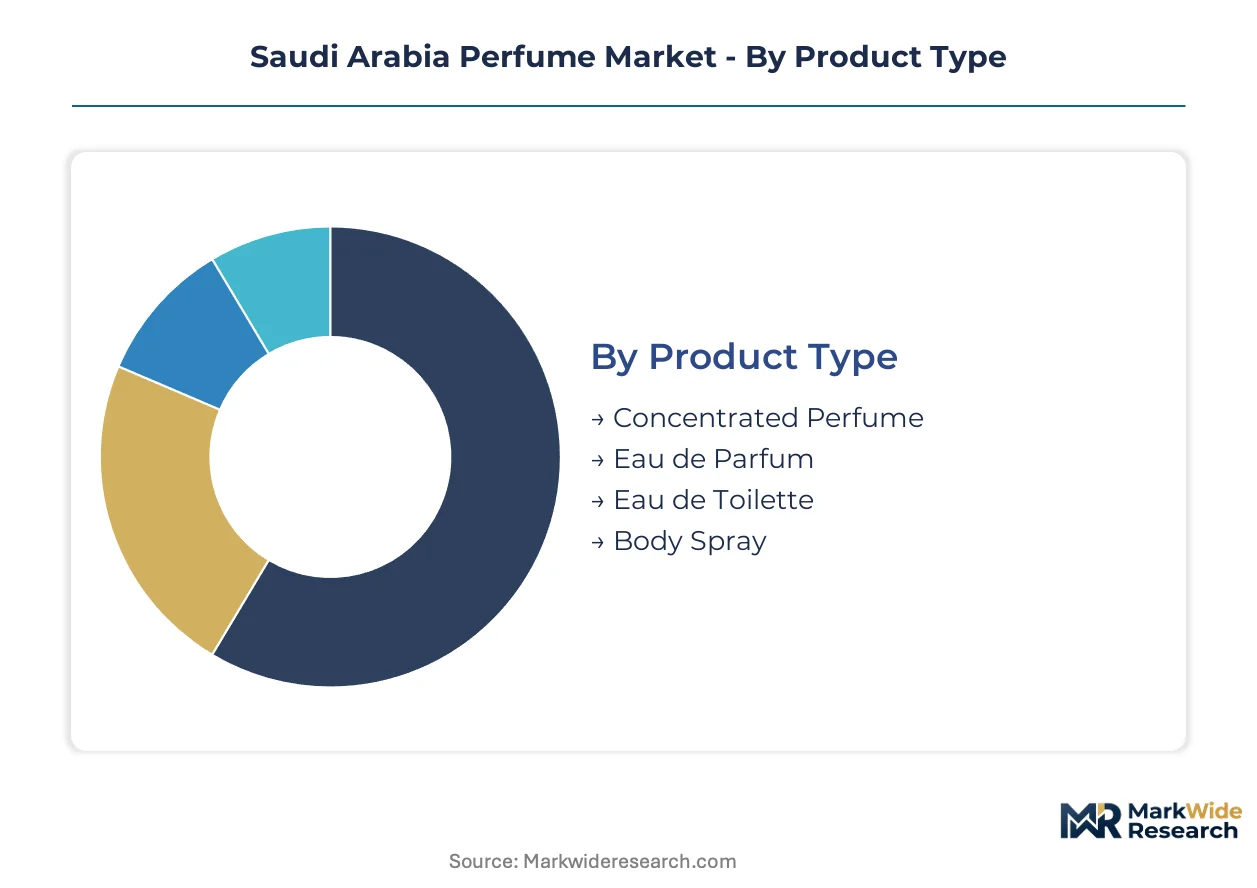
Fragmentation across Saudi Arabia's perfume market reflects divergent consumption rituals, from daily personal scenting to ceremonial gifting. Each segment carries distinct margin profiles and regulatory exposure, shaping how houses allocate formulation and distribution investments.
Product Type:
Upgrade cycles accelerate as consumers trade up from lighter formats to concentrated oils for longevity and prestige value in Gulf climates.
- Concentrated Perfume:High essential oil loadings of twenty percent to forty percent deliver extended wear profiles prized in Riyadh's heat. Heritage houses in Taif capture premium pricing through oud-based attars sold in airport retail and sacred precinct souvenir channels.
- Eau de Parfum:Alcohol-based formulations at fifteen percent to twenty percent concentration bridge Western fragrance conventions with local preferences. Jeddah mall-based specialty retailers report strongest traction among younger buyers seeking versatile daily-wear options.
- Eau de Toilette:Lighter five percent to fifteen percent concentrations target mass-market volume plays and entry-point gifting.
- Body Spray:Lowest concentration aerosol formats serve price-sensitive youth segments and ambient freshening applications.
Volume placements concentrate in Eau de Toilette; the faster expansion belongs to Concentrated Perfume.
Target Consumer:
Cost tier stratification separates heritage-positioned masculine oud offerings from emerging gender-fluid marketing investments.
- Women:Floral and oriental family preferences dominate purchasing, with concentrated oils for home use and eau de parfum for workplace contexts. Khobar retail corridors show whitespace for dedicated women's concept stores versus Riyadh saturation.
- Unisex:Gender-fluid positioning gains fastest traction among digital-native buyers across Riyadh and Jeddah, converging with Western-format rollouts that minimize traditional masculine-feminine coding.
- Men:Woody and oriental families anchor masculine portfolios, with oud-based concentrated oils commanding highest loyalty.
- Youth:Body spray and lighter eau de toilette formats capture trial-oriented consumption before trade-up to premium tiers.
Margin concentration sits with Women; Unisex claims the steepest expansion trajectory.
Distribution Channel:
Application-based channel selection separates experiential discovery from replenishment purchasing.
- Specialty Stores:Mall-based flagship concepts in Riyadh and Jeddah deliver consultation-driven discovery for concentrated perfume and premium eau de parfum. Heritage houses invest in trained advisors to justify price premiums through ingredient storytelling.
- Online Retail:Subscription discovery services and direct-to-consumer logistics reshape trial behavior among urban Saudi buyers. SASO e-commerce conformity pathways streamline cross-border fragrance listings on regional marketplace platforms.
- Supermarkets:Mass-market body spray and eau de toilette placement serves convenience-oriented replenishment.
- Department Stores:Mid-tier eau de parfum and gift sets target seasonal pilgrimage gifting cycles.
Investment intensity clusters in Specialty Stores; Online Retail posts the fastest channel expansion.
Fragrance Family:
Supply concentration in Taif's distillation infrastructure privileges locally sourced raw materials for specific olfactory profiles.
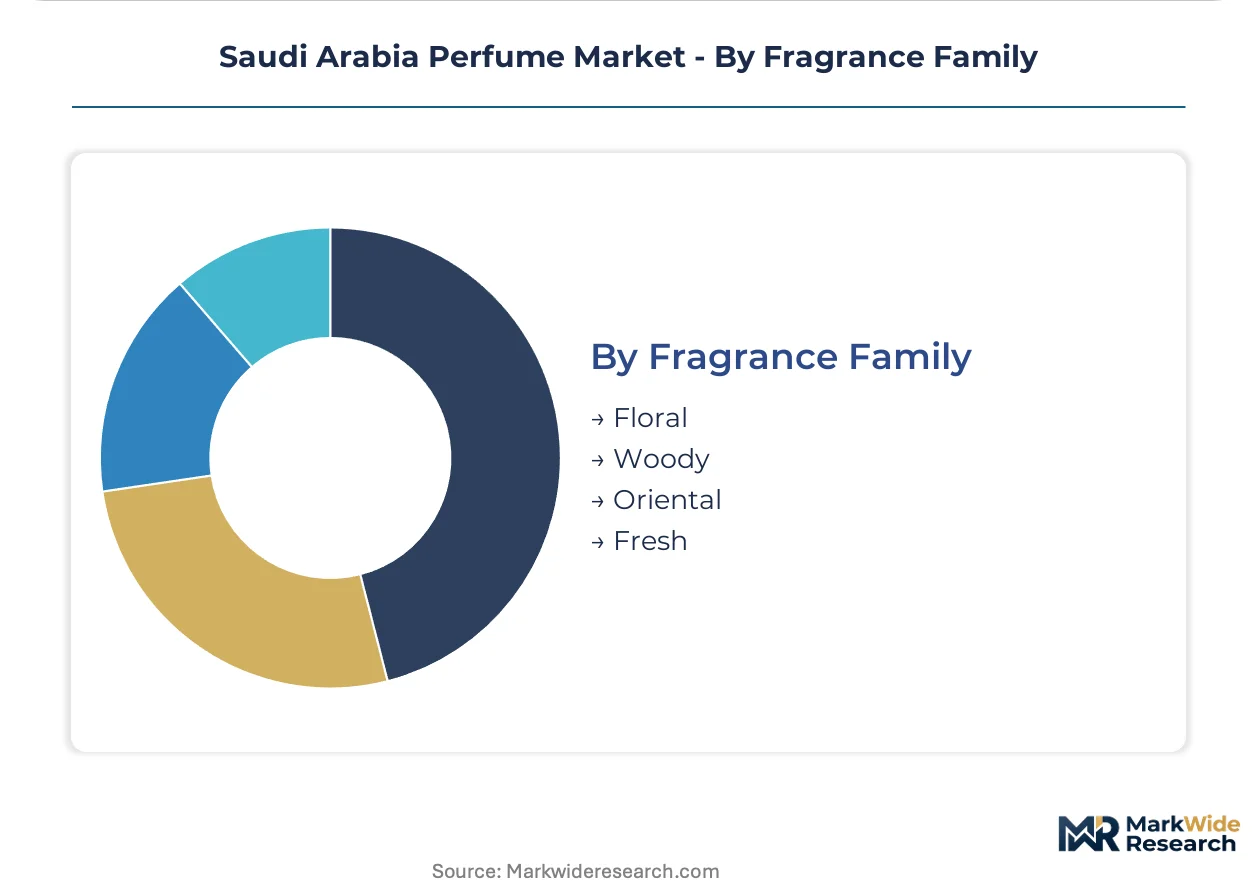
- Oriental:Oud, amber, and spice accords define Saudi heritage positioning, with Taif-based producers leveraging captive distillation for quality control. SFDA disclosure requirements for allergen labeling impose heaviest burden given complex natural ingredient loadings.
- Woody:Sandalwood and cedar foundations serve masculine unisex crossover demand, with synthetic substitutes displacing endangered species under CITES pressures.
- Floral:Rose and jasmine compositions, particularly Taif rose, anchor feminine portfolio cores.
- Fresh:Citrus and aquatic notes capture youth and seasonal summer rotations.
Heritage positioning anchors Oriental; Fresh gains share fastest among climate-responsive younger buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City and Jeddah Islamic Port free zones concentrate fragrance manufacturing and logistics investments through customs duty exemptions and streamlined SFDA pre-clearance facilities.
Riyadh
Riyadh's Tahlia Street and Kingdom Centre mall corridors anchor concentrated perfume oil retail, with heritage houses operating flagship consultation concepts. SFDA's centralized licensing procedures expedite product registration for Riyadh-based distributors. The Riyadh Season tourism calendar generates seasonal demand spikes for oud-based gifting formats.
Eastern Province
Khobar and Dammam retail corridors show whitespace for mall-based specialty fragrance concepts relative to Riyadh saturation. SASO conformity assessment facilities in Dammam Industrial City reduce import clearance timelines for cross-border fragrance shipments. Aramco-affiliated procurement channels elevate hospitality scenting contracts for local distillation houses.
Western Region
Taif's rose harvest and agarwood distillation infrastructure supply raw materials to Jeddah-based formulators. SFDA fragrance safety standards impose allergen disclosure burdens on Taif producers given complex natural ingredient loadings. Makkah and Medina sacred precinct retail channels concentrate pilgrim gifting demand during Umrah and Hajj cycles.
NEOM Northwest
The LINE and Sindalah island developments commission bespoke ambient fragrance programs for luxury hospitality positioning. NEOM's regulatory sandbox framework pilots streamlined halal certification pathways for alcohol-free formulations. Trojena and Oxagon industrial zones attract biotechnology investments in enzymatic oud synthesis platforms.
Saudi Arabia Perfume Market Key Industry Players
Top-tier vendors anchor heritage-positioned oud and attar segments, while mid-tier Western-format specialists compete on eau de parfum accessibility. The vendor base stratifies across captive distillation capabilities, retail network density, and halal certification infrastructure. Three archetypes dominate: Taif-based raw material integrators, Jeddah-Riyadh retail flagships, and blended traditional-Western portfolio houses. Competitive moves concentrate on mall-based flagship expansion and direct-to-consumer digital channel buildout.
Among heritage-positioned specialists, Arabian Oud, Abdul Samad Al Qurashi, and Ajmal Perfumes occupy positions spanning captive supply chains and multi-format retail presence. Arabian Oud exemplifies vertical control through Taif distillation facilities. Abdul Samad Al Qurashi represents premium bakhoor and concentrated oil heritage positioning. Ajmal Perfumes sits within the blended archetype, spanning traditional attar and Western-format eau de parfum portfolios.
| Leading Market Players |
|---|
| Arabian Oud |
| Abdul Samad Al Qurashi |
| Ajmal Perfumes |
| Swiss Arabian |
| Al Haramain Perfumes |
| Rasasi Perfumes |
| Ahmed Al Maghribi Perfumes |
| Deraah Trading |
| Al Rehab Perfumes |
| Others |
Cost & Logistics Intelligence
Enzymatic oud synthesis pilot programs in Taif are compressing production timelines while fragmenting raw material sourcing between heritage wild-harvested supply and lab-cultivated alternatives. This bifurcation simultaneously elevates cost structures for biotechnology investment and concentrates pricing power among distillers with captive agarwood inventories.
Pricing Analysis
Lead-time premiums for wild oud concentrates command substantial markups over spot-market synthetic alternatives, with heritage-positioned Taif producers extracting scarcity rents from pilgrim retail channels. Pricing stratifies across premium wild-distilled, standard cultivated-oud, and economy synthetic-musk tiers, with SFDA allergen disclosure requirements adding compliance premiums to natural-loaded segments. Cost compression in mass-market eau de toilette intensifies as synthetic substitutes displace restricted nitro musks, while concentrated perfume oils show lowest price sensitivity among domestic gifting buyers.
Supply Chain Analysis
Direct-to-specialty-retail channels handle premium concentrated oil distribution, while e-commerce platforms and airport duty-free operations manage volume throughput for Western-format fragrances. Raw material sourcing draws from Southeast Asian agarwood forests, Indian sandalwood plantations, and Taif rose harvests, with enzymatic synthesis platforms emerging as domestic alternatives. Single-source vulnerability concentrates in wild oud supply given CITES harvesting restrictions across Indonesian and Malaysian source regions. Distribution runs through Jeddah Islamic Port free zones with SFDA pre-clearance facilities, then fans out to Riyadh mall corridors and Makkah sacred precinct retail.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wild agarwood supply constraints prop concentrated oil pricing, with Taif distillation capacity acting as the binding bottleneck supporting heritage house margins across the projection horizon.
For Market Incumbents: Deepen captive distillation investments in Taif to secure raw material quality against synthetic substitute threats. Lock in multi-year agarwood offtake agreements before enzymatic synthesis platforms achieve cost parity. Prioritize SFDA compliance infrastructure to maintain competitive moats against gray-market entrants lacking ingredient transparency. For New Entrants and Emerging Players: Digital-native buyers in Khobar and Dammam represent the most penetrable white-space segment, with subscription-based discovery services offering lower customer acquisition costs than mall-based flagship buildout. Target Eastern Province retail corridors before Riyadh saturation intensifies. Lead with gender-fluid eau de parfum rollouts to bypass heritage house dominance in masculine oud positioning. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by heritage houses seeking biotechnology capabilities or regional marketplace platforms expanding private-label fragrance verticals. Long-term viability hinges on regulatory compliance infrastructure and captive raw material access rather than brand equity alone. Watch enzymatic oud synthesis cost curves as the critical inflection signal for heritage positioning erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Distillation Facility Expansion | Taif-based oud production secures supply continuity against Southeast Asian harvesting restrictions. |
| Enzymatic Synthesis Platform Investment | Biotechnology R&D reduces wild agarwood dependence while preserving olfactory complexity claims. |
| Direct-to-Consumer Channel Buildout | Subscription discovery services capture digital-native trial behavior displacing mall consultation. |
| SFDA Compliance Infrastructure | Allergen disclosure capabilities create competitive moats against gray-market fragrance imports. |
| Gender-Fluid Product Line Extension | Unisex positioning converges with Western-format eau de parfum to capture evolving preferences. |
Research Approach
Multi-period observation of pilgrim visitor flows, retail channel mix shifts, and regulatory filing patterns anchored the trend analysis, supplemented by interviews with heritage house master perfumers, SFDA regulatory affairs specialists, airport retail procurement managers, and e-commerce platform category heads. Secondary validation drew from SASO conformity assessment databases, customs import records, hotel hospitality contract disclosures, and halal certification body registries. Bottom-up channel volume estimates triangulated against top-down macro consumption indicators.
Segment-weighting across product type, target consumer, distribution channel, and fragrance family dimensions structured the analytical framework, with cross-segment elasticity modeling informing share-shift dynamics over the projection horizon. CAGRs derived from fitted growth curves applied to baseline volume estimates, incorporating pilgrimage cycle seasonality, regulatory implementation timelines, and biotechnology adoption S-curves as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to enzymatic synthesis cost breakthroughs, CITES enforcement intensity in Southeast Asia, and halal certification standard evolution. Projections reflect assumptions regarding sustained pilgrim visitor recovery and stable SFDA regulatory trajectory. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Fragrance Oil Market
Fragrances & Perfumes
Wax Melts Market
Fragrances & Perfumes
Perfume Vials Market
Fragrances & Perfumes
Home Fragrance Diffusers Market
Fragrances & Perfumes
GCC Perfume and Fragrance Market
Fragrances & Perfumes
Global Scented Candle Market
Fragrances & Perfumes
Digital Fragrance Market
Fragrances & Perfumes
Global Luxury Perfumes Market
Fragrances & Perfumes
Natural Fragrance Market
Fragrances & Perfumes
Cosmetic and Fragrance Retail Chain Market
Fragrances & Perfumes
Mini Refillable Perfume Bottles Market
Fragrances & Perfumes
Gulf Cooperation Council Fragrance and Perfumes Market
Fragrances & Perfumes
Fragrance Diffuser Market
Fragrances & Perfumes
Kuwait Perfume Market
Fragrances & Perfumes
UAE Perfume Market
Fragrances & Perfumes
GCC Perfume Market