
 Cosmetic and Fragrance Retail Chain Market | 2026-2036
Cosmetic and Fragrance Retail Chain Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic and Fragrance Retail Chain Market Insights
Younger beauty consumers is collapsing the historical dominance of department-store-dependent shoppers in fragrance and color cosmetics. Sephora leverages its experiential store format and exclusive brand partnerships to anchor premium traffic in North American malls. Ulta Beauty sustains a hybrid mass-prestige model that competes across price tiers under one roof. Douglas differentiates through its European footprint and localized brand curation in Germany, France, and Italy.
Cosmetic and fragrance retail chains operate fixed-location commercial networks that distribute beauty products through curated assortments, in-person consultation services, and omnichannel fulfillment systems with inventory turnover targets of 4-6 times annually; their primary purpose is to bridge brand manufacturers and end consumers while capturing margin through service differentiation and loyalty program economics. Skincare commands the highest repeat purchase frequency and margin pool across product type segments, while fragrance recovery lags in brick-and-mortar channels post-pandemic. The online distribution channel occupies the fastest-growing fulfillment path, though specialty stores retain superior conversion rates for premium and luxury price tiers where tactile trial remains essential.
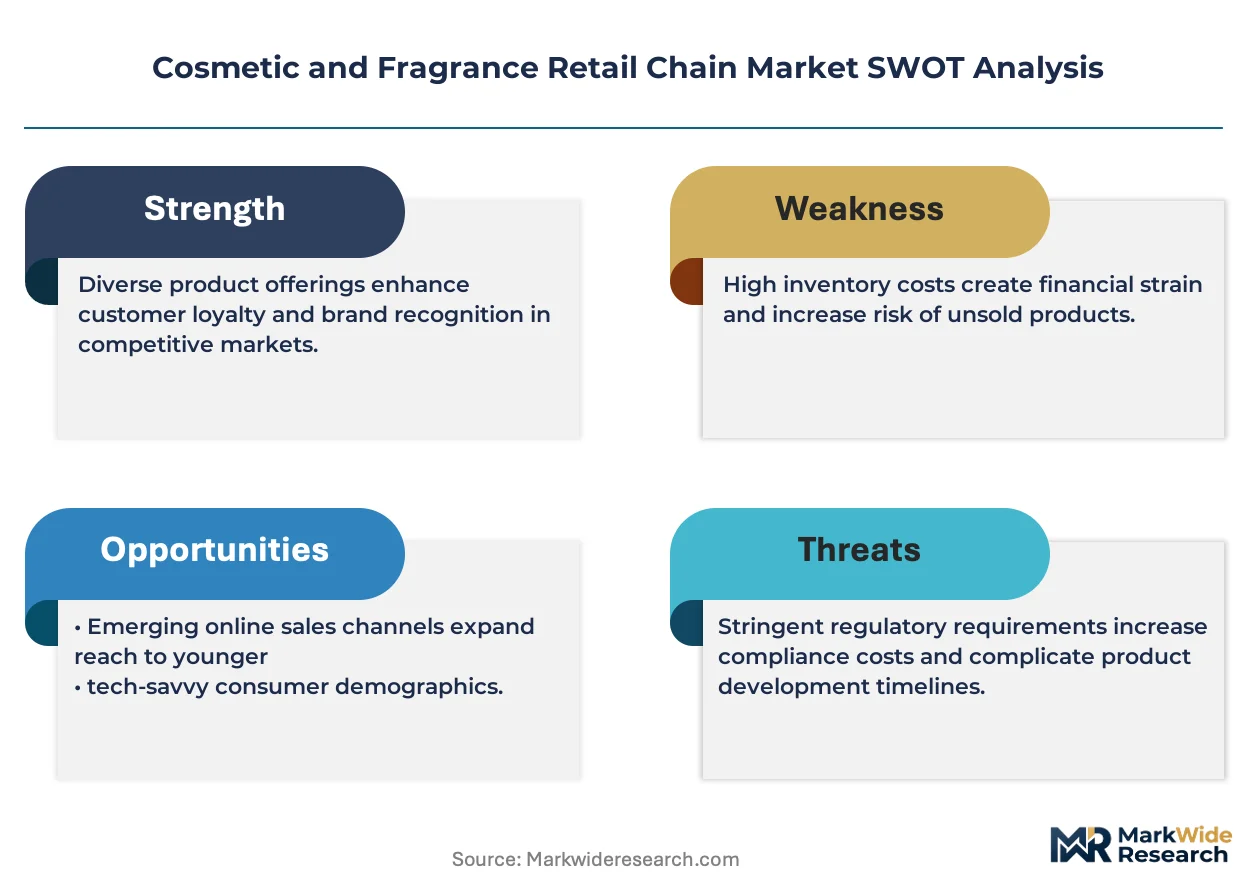
FDA oversight of cosmetic ingredient safety under the Modernization of Cosmetics Regulation Act shapes product eligibility for US retail shelves, while REACH and the EU Green Deal restrict substance portfolios available to European chains. China's SAMR enforces labeling and advertising standards that determine market access for both domestic and foreign beauty retailers. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment sourcing strategies and private-label development timelines.
Market Dynamics
Experiential retail formats are collapsing the historical dominance of department-store-dependent beauty distribution, forcing chains to reconfigure square footage toward service-intensive environments that justify premium positioning and repeat visitation.
Growth Catalysts
- EU Green Deal compliance:REACH substance restrictions and carbon-border adjustments are accelerating clean beauty certification uptake among European chains, creating first-mover margin pools for compliant assortments.
- China's tier-one city concentration:Domestic brand competition in Shanghai, Beijing, and Shenzhen is forcing international chains to localize product curation and accelerate private-label development cycles.
- AI-powered skin diagnostics:In-store diagnostic hardware is converting trial-resistant shoppers into skincare purchasers with measurable efficacy claims and personalized regimen bundling.
Market Restraints
- Ingredient supply concentration:Specialty chemical production for fragrance compounds clusters in Germany and Switzerland, exposing chains to single-source disruption risk and extended reformulation timelines.
- FDA MoCRA implementation:The Modernization of Cosmetics Regulation Act imposes facility registration and serious adverse event reporting burdens that compress operating margins for smaller chain operators.
- Commercial real estate cost structure:Mall anchor rent escalations in prime US and Chinese locations are consuming service-upgrade capital that would otherwise fund experiential renovation.
Strategic Opportunities
- India's organized retail penetration:Beauty specialist chains remain underdeveloped outside Mumbai and Delhi, creating whitespace for format experimentation before domestic conglomerates consolidate positions.
- SAMR livestreaming commerce integration:China's regulatory framework for influencer-led retail is maturing, enabling chains to merge physical inventory with broadcast commerce without platform disintermediation.
- Biotech-fermented actives:Convergence of synthetic biology and cosmetic chemistry is opening proprietary ingredient pipelines that chains can exclusive-license against mass-market competitors.
Industry Challenges
- Licensed esthetician talent scarcity:Service-intensive formats require skilled consultation staff that retail wage structures struggle to attract and retain against medical spa competitors.
- Omnichannel inventory synchronization:Real-time visibility across dark stores, fulfillment centers, and selling floors demands capex-heavy systems integration that mid-tier chains defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic and Fragrance Retail Chain Market |
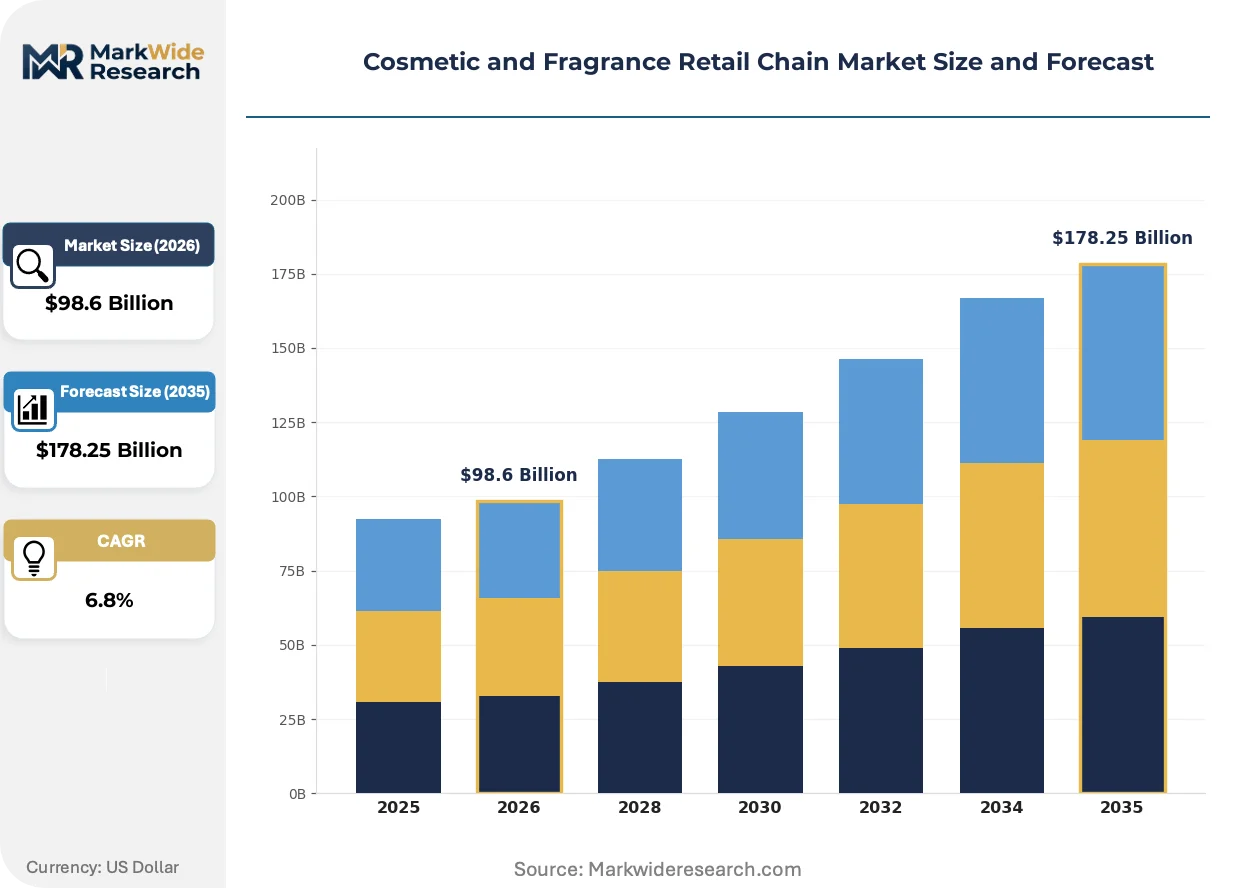
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Makeup, Skincare, Fragrance, Haircare Price Tier: Premium, Mid-Range, Budget, Luxury Distribution Channel: Online, Brick-and-Mortar, Specialty Stores, Department Stores Customer Type: Individual Consumers, Salons, Spas, Retailers |
| Companies Covered | Sephora, Ulta Beauty, A.S. Watson Group, Douglas, Boots UK, Marionnaud, ICI Paris XL, The Body Shop, Nykaa Retail, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic and Fragrance Retail Chain Market Trends and Innovations
Digital-native consumption patterns are fragmenting traditional beauty retail loyalty, compelling chains to deploy technology layers that bridge physical trial with seamless replenishment and community-driven discovery.
AI-powered virtual try-on systems are displacing physical tester hygiene concerns and enabling fragrance sampling without atomizer waste. Premium chains in South Korea and the United States are deploying these tools at scale, compressing the conversion funnel for color cosmetics and reducing shrink from damaged inventory. The structural consequence is a reallocation of floor space from tester bars to digital stations that capture zero-party data for personalized remarketing.
REACH substance restriction expansions under the EU Green Deal are forcing European chains to purge silicones and certain UV filters from core assortments. This regulatory compression is elevating clean beauty price premiums and accelerating private-label reformulation timelines. German and French retailers are responding by consolidating supplier audits and pre-certifying ingredient portfolios to maintain shelf velocity.
Subscription-based replenishment models are capturing high-repeat categories like skincare serums and sun care from traditional restock visits. Specialty chains are deploying membership tiers that bundle auto-delivery with in-store service credits, displacing pure-play e-commerce platforms for routine purchases. This behavioral shift is most visible in Japan and the United States, where convenience-oriented demographics prioritize frictionless continuity over discovery browsing.
Cosmetic and Fragrance Retail Chain Market Segmentation
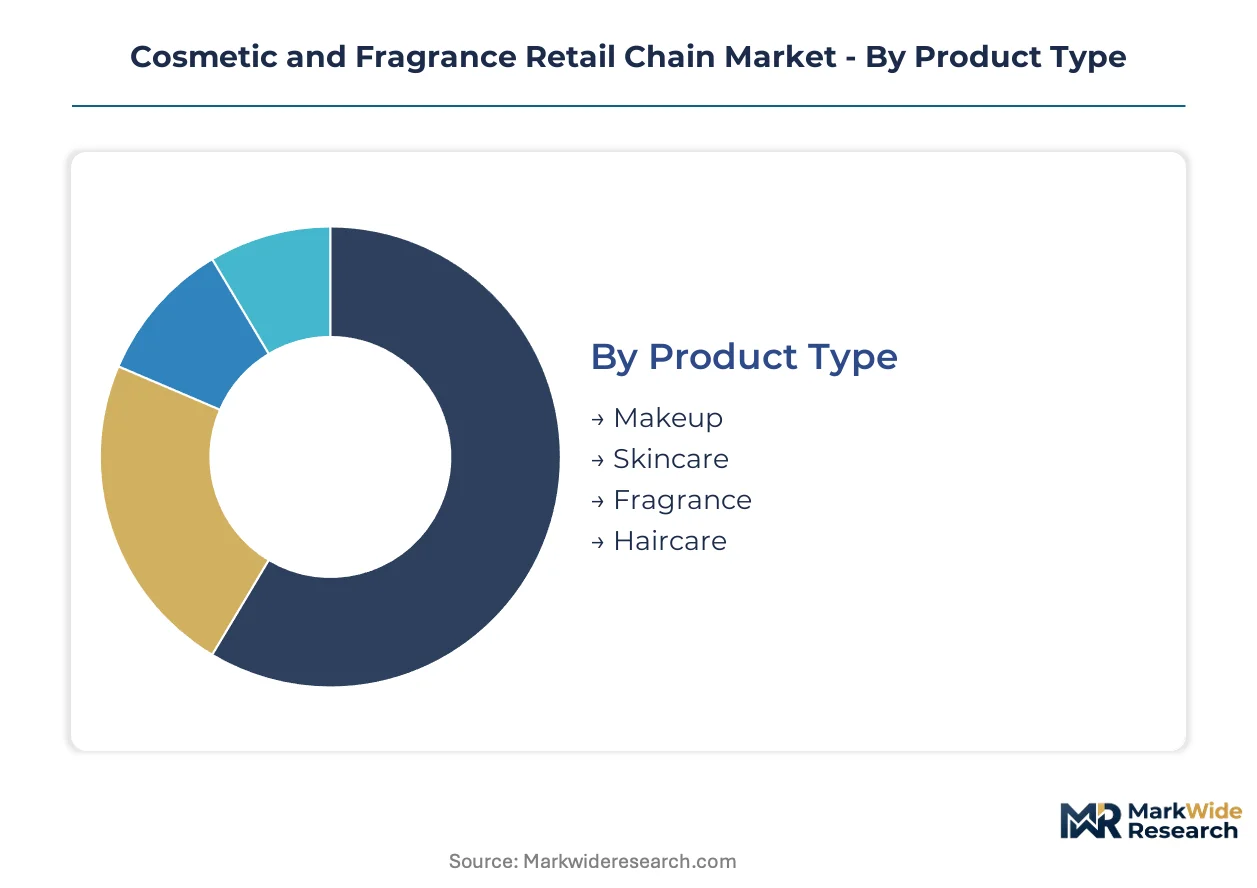
Segmentation in cosmetic and fragrance retail chains determines inventory turnover velocity, margin architecture, and format investment priorities. Distinct product categories and price tiers command divergent service intensities and replenishment cadences across channel types.
Product Type:
Skincare and fragrance segments concentrate demand in domestic tier-one cities, while makeup and haircare sustain stronger export-led growth through cross-border e-commerce channels.
- Skincare:High-repeat purchase frequency drives 4-6x annual inventory turnover for serums, moisturizers, and sun care. Demand clusters in Shanghai, Beijing, and Shenzhen where SAMR labeling enforcement elevates clean beauty premiums.
- Fragrance:Atomizer-based sampling and tactile trial remain essential conversion tools despite virtual try-on displacement in color cosmetics. Brick-and-mortar recovery lags post-pandemic, though experiential store formats in Paris and Milan sustain luxury price positioning.
- Makeup:Color cosmetics depend on in-person shade matching and seasonal trend velocity.
- Haircare:Salon-adjacent professional lines anchor B2B volume for chain-owned private labels.
Skincare holds the largest share; momentum sits with fragrance as experiential retail formats rebuild trial confidence.
Price Tier:
Cost tier stratification determines square footage allocation, with premium and luxury segments consuming disproportionate service labor per transaction.
- Premium:Bridges mass-market accessibility with prestige ingredient claims; chains deploy membership tiers and auto-replenishment to capture routine purchase loyalty in Japan and the United States.
- Luxury:Exclusive brand partnerships and limited distribution justify elevated price positioning; Douglas and Sephora leverage this tier to anchor mall traffic in Germany, France, and Italy.
- Mid-Range:Hybrid mass-prestige assortments compete across price tiers under single-roof formats.
- Budget:Private-label development accelerates in response to domestic brand competition in China's tier-one cities.
Premium commands the widest shelf presence; luxury is expanding most quickly as chains reconfigure toward service-intensive environments.
Distribution Channel:
Volume concentration varies sharply by channel maturity, with online fulfillment climbing fastest while specialty stores retain superior conversion rates for tactile-dependent categories.
- Specialty Stores:Curated assortments with in-person consultation services achieve highest conversion for premium skincare and fragrance; Ulta Beauty and Sephora anchor this channel in US malls through experiential renovation.
- Online:Fastest-growing fulfillment path supported by SAMR livestreaming commerce integration in China; chains merge physical inventory with broadcast commerce to prevent platform disintermediation.
- Brick-and-Mortar:Fixed-location networks face rent escalation pressure in prime US and Chinese locations.
- Department Stores:Historical dominance collapses as younger demographics shift toward experiential retail formats.
Specialty stores retain margin leadership; online channels are gaining share fastest through AI-powered personalization and subscription bundling.
Customer Type:
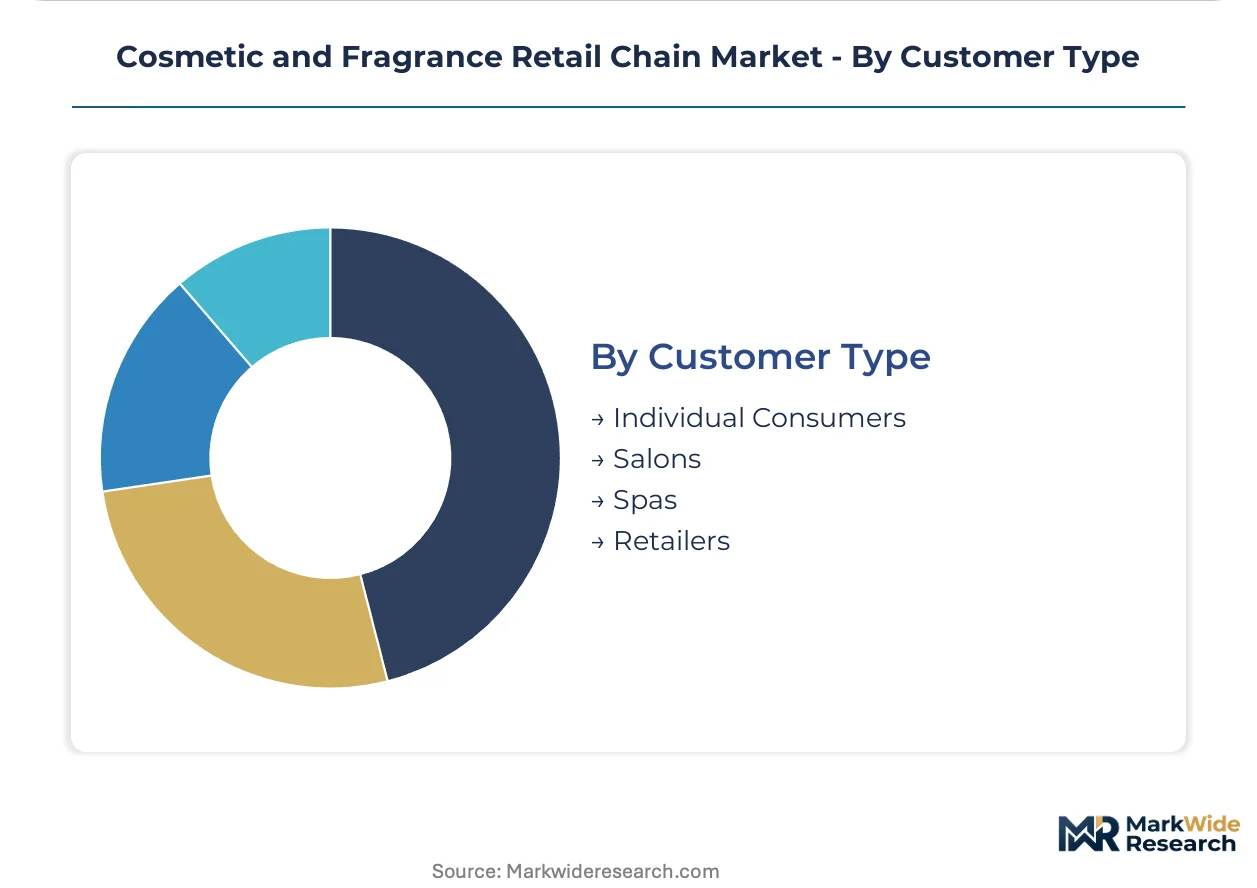
Customer segmentation dictates service model economics, with individual consumers driving frequency and B2B accounts anchoring volume contracts.
- Individual Consumers:Zero-party data capture through in-store diagnostics enables personalized regimen bundling; AI-powered skin diagnostics convert trial-resistant shoppers in South Korea and the United States.
- Salons:Professional-grade haircare and skincare lines require licensed esthetician support that retail wage structures struggle to retain against medical spa competitors.
- Spas:Service-intensive formats demand skilled consultation staff for high-margin treatment protocols.
- Retailers:Wholesale and distribution relationships sustain volume for private-label development cycles.
Individual consumers represent the deepest volume pool; salon partnerships show the steepest expansion trajectory as chains defend B2B positioning against professional supply houses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific beauty distribution, handling containerized imports for fragrance compounds and skincare actives that feed retail chains across China's eastern seaboard.
United States
Mall anchor positioning and experiential renovation drive specialty store expansion in suburban shopping centers. FDA MoCRA facility registration requirements compress operating margins for smaller operators. Greater Los Angeles and Dallas-Fort Worth concentrate distribution center investment for omnichannel fulfillment.
China
Tier-one city consumption in Shanghai, Beijing, and Shenzhen elevates clean beauty premiums through SAMR labeling enforcement. Dual carbon goals under MEE oversight accelerate supply chain decarbonization mandates for imported cosmetics. Yangtze River Delta manufacturing clusters support domestic brand competition against international chains.
Germany
REACH substance restrictions and EU Green Deal compliance elevate reformulation timelines for fragrance and skincare assortments. Douglas anchors premium traffic through localized brand curation in Frankfurt and Munich. Bavarian chemical clusters supply specialty ingredients under ECHA audit consolidation.
France
Luxury fragrance heritage sustains experiential store formats in Paris and Lyon despite brick-and-mortar recovery lags. ANSM cosmetic safety oversight aligns with EU-wide substance restriction expansions. Île-de-France retail density forces differentiation through exclusive brand partnerships and limited distribution.
India
Organized retail penetration remains underdeveloped outside Mumbai and Delhi, creating format experimentation whitespace. BIS cosmetic standards and CDSCO import registration determine shelf eligibility for international chains. Maharashtra and Karnataka urban corridors concentrate early-mover investment before domestic conglomerate consolidation.
Cosmetic and Fragrance Retail Chain Market Competitive Landscape
Listed leaders compete with private specialists across capital access and format flexibility, producing a tiered structure where scale-driven operators defend mall anchor positioning against agile domestic challengers. Three archetypes dominate: experiential format specialists leveraging exclusive brand partnerships, hybrid mass-prestige operators capturing cross-tier traffic, and digital-native entrants merging physical inventory with broadcast commerce. Competitive moves concentrate on experiential square-footage renovation and private-label development cycles accelerated by regulatory compliance requirements.
Within the experiential format tier, Sephora and Ulta Beauty occupy positions that exemplify service-intensive environment investment, while Douglas represents European footprint consolidation through localized curation. These operators anchor premium traffic through distinct format economics: Sephora through exclusive brand partnerships in North American malls, Ulta Beauty through hybrid mass-prestige assortment breadth, and Douglas through Germany-France-Italy corridor density.
| Leading Market Players |
|---|
| Sephora |
| Ulta Beauty |
| A.S. Watson Group |
| Douglas |
| Boots UK |
| Marionnaud |
| ICI Paris XL |
| The Body Shop |
| Nykaa Retail |
| Others |
Pricing and Supply Chain Analysis
Biotech-fermented active ingredient substitution is displacing petroleum-derived cosmetic chemistry, simultaneously shifting procurement gravity toward Bavarian and Swiss synthetic biology clusters while compressing formulation cost curves for compliant clean beauty assortments. This input transition elevates price premiums for REACH-certified portfolios in European chains and forces margin recapture through private-label exclusivity licensing against mass-market competitors.
Pricing Analysis
Volume-discount tiering structures separate luxury fragrance exclusives from mid-range hybrid assortments and budget private-label lines across specialty store networks. Price differentiation rests on certification grade under REACH substance restrictions and brand premium anchored by exclusive distribution partnerships. Pricing pressure stems from commercial real estate rent escalations in prime US and Chinese mall locations that consume service-upgrade capital. Budget-tier individual consumers exhibit highest price sensitivity, while luxury-tier collectors and gift purchasers demonstrate lowest elasticity.
Supply Chain Analysis
Inbound logistics costs through the Port of Shanghai fluctuate with container availability on Asia-Europe trade lanes, compressing margin buffers for fragrance compound imports. Specialty chemical production for cosmetic actives concentrates in Germany, Switzerland, and China's Yangtze River Delta manufacturing clusters. Raw material dependencies include biotech-fermented peptides, silicone alternatives, and botanical extracts subject to EU Green Deal carbon-border adjustments. Single-source vulnerability in German fragrance compound synthesis exposes chains to extended reformulation timelines. Distribution runs through dark-store fulfillment centers synchronized with experiential specialty store floors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs beauty retail as chains merge physical inventory with livestreaming commerce infrastructure, creating interoperability between in-store diagnostics and subscription replenishment ecosystems.
For Market Incumbents: Fortify experiential square-footage positioning through AI-powered skin diagnostic hardware deployment that captures zero-party data for personalized regimen bundling. Deepen exclusive brand partnerships against domestic challenger encroachment in China's tier-one cities. Accelerate private-label development cycles to recapture margin from REACH compliance cost absorption.
For New Entrants and Emerging Players: Lead with format experimentation whitespace in India's organized retail corridors outside Mumbai and Delhi before domestic conglomerate consolidation closes entry windows. Target salon-adjacent B2B professional lines where licensed esthetician talent scarcity weakens incumbent service delivery. Deploy SAMR-compliant livestreaming commerce integration as differentiated go-to-market architecture.
For Investors and Strategic Acquirers: Capital is best deployed toward experiential format specialists with proven omnichannel inventory synchronization capabilities and exclusive brand partnership portfolios. Long-term viability across the analysis window favors operators capturing subscription-based replenishment loyalty in high-repeat skincare categories. Monitor biotech-fermented active ingredient pipeline maturation as inflection signal for proprietary margin pool emergence.
| Strategic Initiative | Industry Significance |
|---|---|
| Experiential Store Format Renovation | AI-powered diagnostics in Sephora and Ulta Beauty locations convert trial-resistant shoppers into skincare purchasers. |
| Private-Label Development Acceleration | Douglas and domestic Chinese chains reformulate portfolios to capture REACH compliance margin premiums. |
| Livestreaming Commerce Integration | SAMR-regulated broadcast commerce merges physical inventory with influencer-led discovery without platform disintermediation. |
| Biotech Ingredient Exclusive Licensing | Synthetic biology partnerships create proprietary active pipelines against mass-market competitor commoditization. |
| Subscription Replenishment Membership Tiers | Auto-delivery bundling with in-store service credits displaces pure-play e-commerce for routine skincare purchases. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of retail chain SEC filings, customs import records for fragrance compounds, and EU ECHA substance restriction databases. Primary interviews engaged category buyers at specialty store networks, procurement leads at fragrance compound manufacturers, licensed estheticians in service-intensive formats, and regulatory affairs directors navigating FDA MoCRA implementation. Secondary validation drew from SAMR labeling enforcement bulletins, Nielsen retail audit data, and CDSCO import registration records. Bottom-up store-level revenue modeling triangulates against top-down market sizing across the analysis window.
Segmentation dimensions modeled include product type stratification across skincare, fragrance, makeup, and haircare; price tier architecture spanning luxury, premium, mid-range, and budget; distribution channel mix between specialty stores, online fulfillment, and remaining department store footprints; and customer type bifurcation between individual consumers and B2B salon accounts. CAGRs derive from regression analysis of historical turnover velocity against experiential format penetration rates and regulatory compliance cost trajectories. Forecast inputs incorporate AI diagnostic hardware deployment curves and biotech-fermented active ingredient pipeline maturation timelines.
The analysis sits within stated boundaries; outcomes outside sustained experiential format investment, stable regulatory enforcement intensity, or intact livestreaming commerce interoperability would require recalibration. Forecasts reflect documented assumptions regarding mall anchor rent trajectories, licensed esthetician labor market tightness, and REACH substance restriction expansion scope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Global Fragrances and Perfumes Market
Fragrances & Perfumes
North America Perfume Market
Fragrances & Perfumes
UAE Perfume Market
Fragrances & Perfumes
Wax Melts Market
Fragrances & Perfumes
Fragrance Emulsion Market
Fragrances & Perfumes
Home Fragrance Market
Fragrances & Perfumes
Clean Perfume Market
Fragrances & Perfumes
Scented Oil Market
Fragrances & Perfumes
GCC Perfume and Fragrance Market
Fragrances & Perfumes
Gulf Cooperation Council Fragrance and Perfumes Market
Fragrances & Perfumes
Saudi Arabia Perfume Market
Fragrances & Perfumes
Gourmand Fragrance Market
Fragrances & Perfumes
Fragrance Oil Market
Fragrances & Perfumes
Global Luxury Perfumes Market
Fragrances & Perfumes
Natural Fragrance Market
Fragrances & Perfumes
Kuwait Perfume Market