
 Global Fragrances and Perfumes Market | 2026-2036
Global Fragrances and Perfumes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fragrances and Perfumes Market Analysis
Prestige-tier fragrance concentration is collapsing the gap between artisanal niche houses and mainstream luxury portfolios. LVMH Moët Hennessy Louis Vuitton leverages its vertical control over raw material sourcing to secure proprietary supply chains. Chanel anchors its competitive moat through captive production of key absolutes and essences at its Grasse facility. Coty competes by extending licensed celebrity and designer portfolios across mass and prestige price points simultaneously.
Fragrances and perfumes comprise volatile aromatic compounds dissolved in ethanol or oil carriers, with concentrations ranging from parfum at 20-30% to eau de toilette at 5-15%, designed for olfactory signaling and personal grooming rituals. Eau de Parfum dominates value pools due to higher per-unit pricing and longer wear profiles that justify premium positioning. Unisex fragrances represent the fastest-growing end-user category as gender-fluid marketing and shared household purchasing erode traditional segmentation. Online stores capture expanding share through subscription sampling models and direct-to-consumer launches that bypass wholesale margin structures.
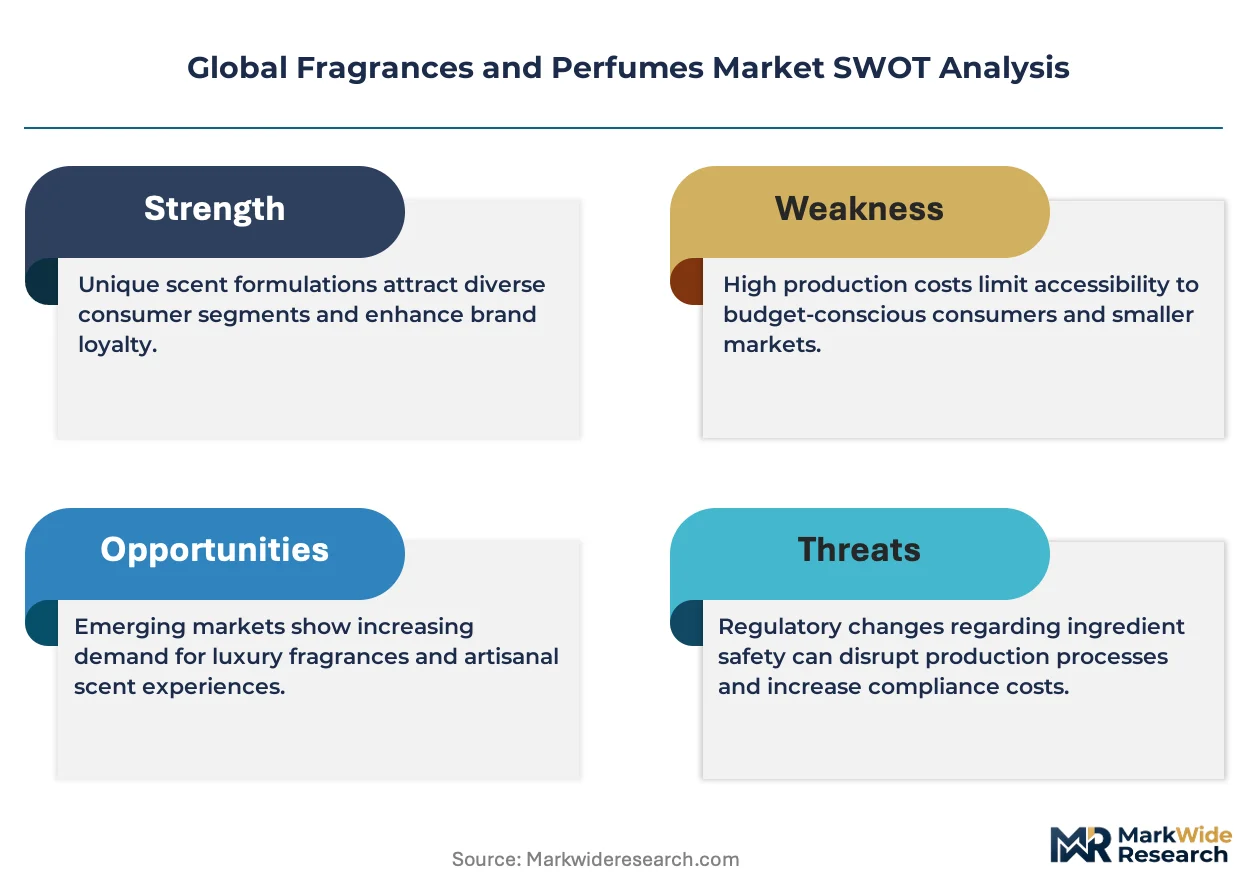
IFRA standards, REACH compliance in Europe, and FDA cosmetic labeling requirements collectively constrain formulation choices and extend product development cycles for international launches. The EU Green Deal's chemical sustainability targets are forcing reformulation investments away from synthetic musks and certain phthalate carriers toward bio-fermented and upcycled botanical alternatives. Stakeholders must monitor regulatory divergence between Brussels and Washington as divergent fragrance allergen lists threaten to fragment global SKU strategies.
Market Dynamics
Prestige fragrance houses are consolidating captive control over Grasse jasmine and rose de mai harvests as climate volatility disrupts traditional sourcing corridors across the Mediterranean basin.
Growth Catalysts
- EU Green Deal chemical sustainability targets:The framework mandates phased reduction of synthetic musks and phthalate carriers, accelerating investment in bio-fermentation capacity and upcycled botanical extraction methods.
- Male prestige-tier adoption:Grooming ritual expansion among male consumers in the United States and China is pulling concentrated parfum formats into previously underdeveloped demographic segments.
- Subscription sampling models:Direct-to-consumer platforms bypass wholesale margin structures and capture household purchasing data that enables personalized fragrance curation at scale.
Market Restraints
- Raw material concentration risk:Bulgarian rose oil and Madagascan vanilla supply clusters in narrow geographic corridors expose formulators to harvest volatility and price spikes.
- IFRA allergen disclosure tightening:The European Union's expanding restricted substance lists force reformulation cycles that extend product development timelines by 12-18 months for international launches.
- Ethanol carrier cost sensitivity:Biofuel policy competition for agricultural ethanol feedstocks compresses margin structures at mass-market price points.
Strategic Opportunities
- India personal care expansion:BIS quality mark recognition and duty-free retail growth in Mumbai and Delhi create entry points for prestige houses seeking emerging middle-class penetration.
- Biotechnology-olfactory convergence:Enzymatic synthesis of rare molecules and microbial fermentation of sandalwood alternatives reduce dependency on endangered botanical species.
- Unisex fragrance white space:Gender-fluid marketing and shared household purchasing erode traditional segmentation, opening shelf space for positioning outside masculine-feminine binaries.
Industry Challenges
- Perfumer talent scarcity:Master perfumer training programs at ISIPCA and Givaudan run 5-7 years, creating pipeline bottlenecks as heritage house retirements accelerate.
- REACH-EPA regulatory divergence:Fragmenting fragrance allergen lists between Brussels and Washington threaten to bifurcate global SKU strategies and inflate compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fragrances and Perfumes Market |
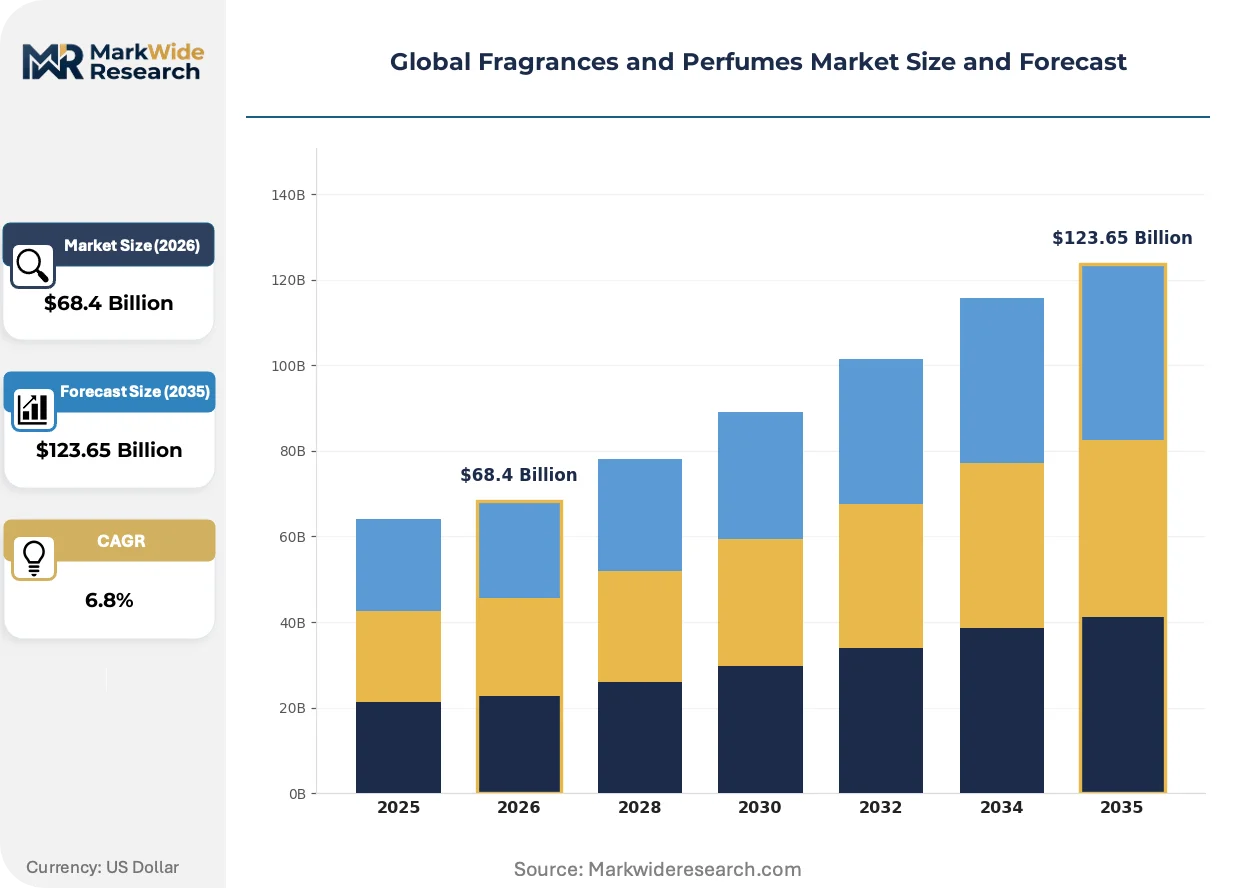
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eau de Parfum, Eau de Toilette, Eau de Cologne, Perfume Oil End User: Men, Women, Unisex, Children Sales Channel: Retail Stores, Online Stores, Department Stores, Specialty Stores Packaging Type: Glass Bottles, Plastic Bottles, Spray Cans, Roll-ons |
| Companies Covered | LVMH Moët Hennessy Louis Vuitton, Chanel, The Estée Lauder Companies, L'Oréal, Coty, Givaudan, Symrise, Firmenich, Avon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fragrances and Perfumes Market Emerging Trajectories
Synthetic biology and precision fermentation are rewriting extraction economics while regulatory pressure on petrochemical carriers forces formulation architecture redesign across every price tier.
Biotechnology-derived aromatic molecules are fragmenting the traditional absolutes market. Givaudan and Firmenich deploy engineered yeast strains to produce rare sesquiterpenes previously harvested from threatened agarwood and sandalwood species. Niche houses adopt these bio-identical materials to secure supply continuity and sustainability credentials that command premium positioning.
REACH authorization requirements under ECHA jurisdiction are eliminating certain synthetic fixatives from European formulations. The restriction on polycyclic musks and specific phthalate carriers forces houses to rebuild base accords around bio-fermented alternatives. Prestige portfolios absorb reformulation costs more readily than mass-market lines, widening competitive separation.
Direct-to-consumer sampling subscriptions are compressing wholesale dependency. Scentbird and similar platforms in the United States bypass department store concessions and capture consumer preference data that enables algorithmic matching. This channel shift fragments traditional gatekeeper power held by Sephora and Douglas while concentrating customer relationship ownership with fragrance houses themselves.
Global Fragrances and Perfumes Market Segmentation
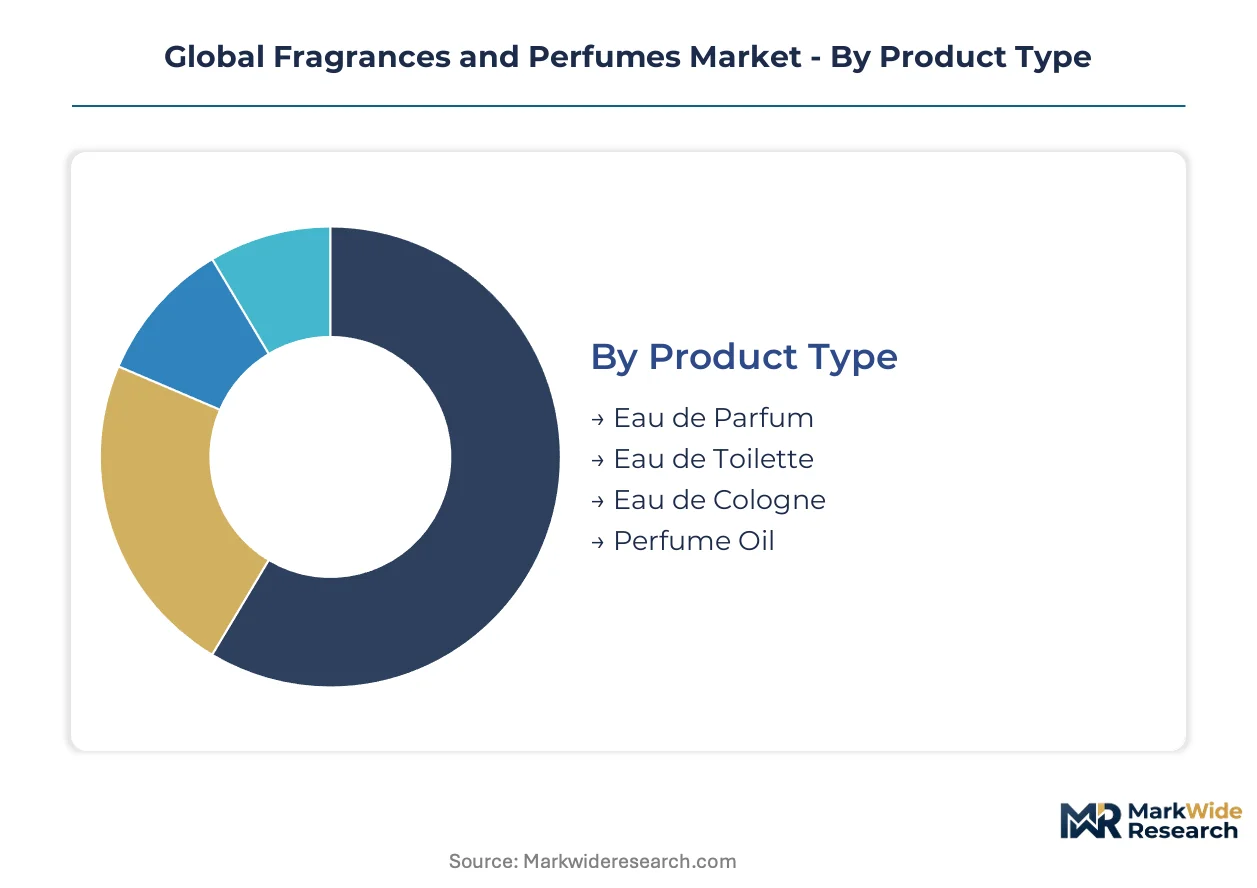
Concentration gradients across product formats and gender positioning determine margin architecture and channel strategy for fragrance houses navigating prestige-mass bifurcation. Substitution dynamics between formats and the unisex erosion of traditional gender boundaries reshape competitive allocation of formulation and marketing resources.
Product Type:
Eau de Cologne faces the most acute substitution pressure as male grooming ritual upgrades displace lighter concentrations toward parfum-strength alternatives.
- Eau de Parfum:Concentrations of 15-20% aromatic compounds in ethanol carriers deliver 6-8 hour wear profiles that justify premium pricing. United States prestige counters and Chinese duty-free corridors concentrate demand as male consumers upgrade from lighter formats.
- Eau de Toilette:5-15% concentration range dominates mass-market volume through accessible price points and frequent reapplication rituals. European pharmacy channels and Latin American retail maintain density despite gradual trade-up pressure.
- Eau de Cologne:Traditional 2-5% citrus-forward compositions face format obsolescence as male demographic preferences shift toward longer-lasting concentrations.
- Perfume Oil:Anhydrous or low-alcohol formats serve Middle Eastern preference for intense sillage and alcohol-free religious compliance.
Eau de Toilette anchors the volume base while Eau de Parfum gains share at the steepest rate.
End User:
Gender-fluid positioning is collapsing the cost-tier logic that historically separated masculine and feminine fragrance development budgets.
- Unisex:Shared household purchasing and gender-neutral marketing erode binary shelf segmentation. United States direct-to-consumer launches and Scandinavian retail corridors concentrate first-mover adoption.
- Men:Prestige parfum concentration adoption accelerates in United States and Chinese urban centers as grooming ritual expansion outpaces traditional aftershave and cologne markets.
- Women:Heritage floral and oriental franchises retain loyalty but face fragmentation as unisex alternatives capture experimental purchase occasions.
- Children:Hypoallergenic and alcohol-free formulations serve narrow pediatric segments with restricted distribution through pharmacy and specialist channels.
Women's fragrances anchor the volume base while unisex positioning climbs the fastest.
Sales Channel:
Margin compression intensity varies sharply by channel, with wholesale-dependent formats facing steepest structural pressure from direct-to-consumer bypass.
- Online Stores:Subscription sampling models and algorithmic curation capture preference data that enables personalized matching at scale. United States platforms and Chinese social commerce ecosystems concentrate growth.
- Department Stores:Concession-based prestige distribution retains tactile trial importance but loses share to direct brand relationships and specialty retail.
- Specialty Stores:Niche and artisanal houses leverage curated assortment and educated staff to justify premium positioning outside mass retail.
- Retail Stores:Mass-market pharmacy and grocery channels absorb volume for accessible price points with limited service interaction.
Department stores anchor the volume base while online stores expand most quickly.
Packaging Type:
Sustainability compliance costs and material scarcity are forcing divergence between prestige collectible formats and mass-market functional containers.
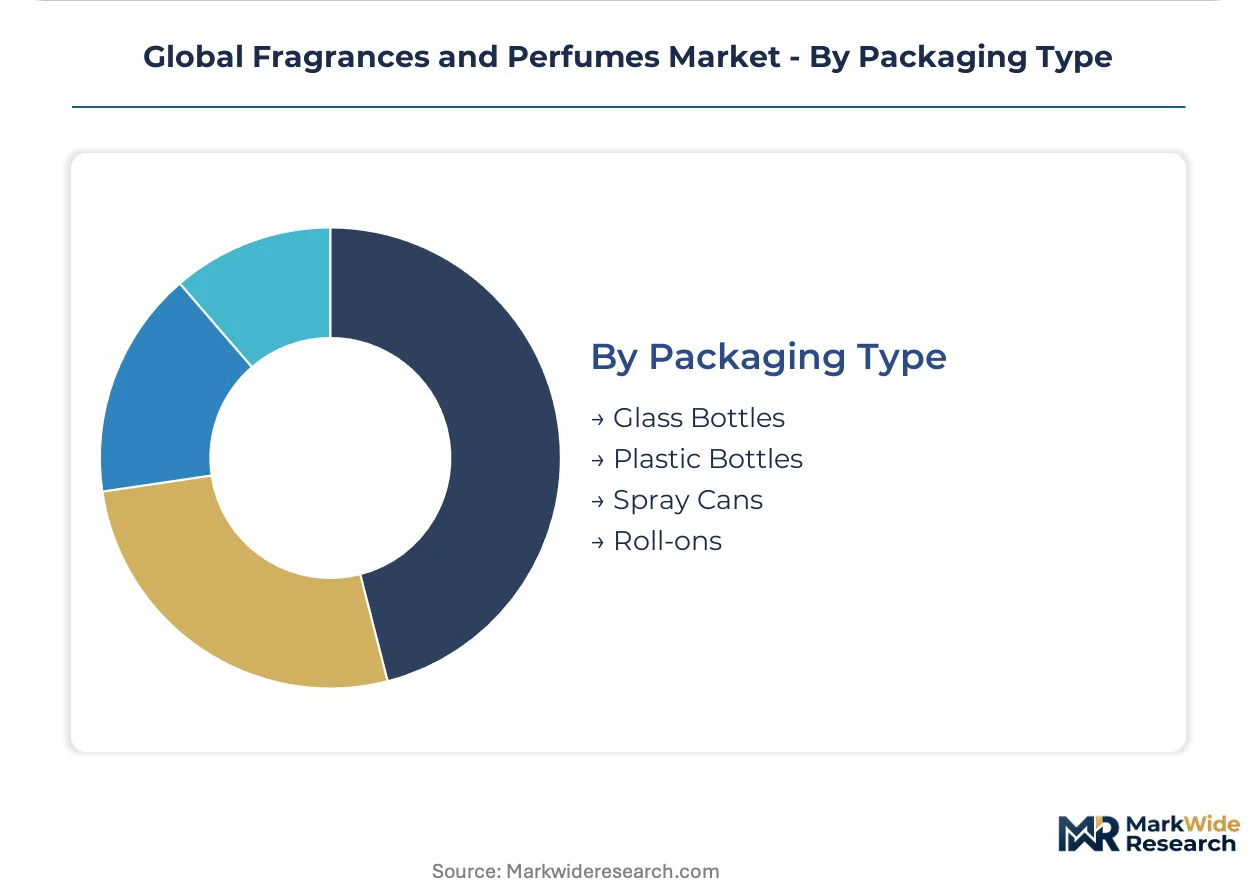
- Glass Bottles:Weighted, refillable designs serve as brand equity objects with extended lifecycle through at-home replenishment systems. European regulatory pressure on single-use plastics accelerates premium glass adoption.
- Spray Cans:Aerosol propellant formats face REACH restriction on volatile organic compounds, forcing reformulation toward pump alternatives.
- Plastic Bottles:Lightweight, shatter-resistant formats retain mass-market necessity despite EU Green Deal circularity targets and recycling infrastructure gaps.
- Roll-ons:Direct-skin application formats serve travel, sampling, and alcohol-sensitive segments with compact portability.
Glass bottles anchor the volume base while refillable and sustainable formats gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grasse jasmine and rose de mai harvests concentrate captive supply chains in southern France, while climate volatility across the Mediterranean basin forces fragrance houses to diversify botanical sourcing corridors.
United States
Male grooming ritual expansion and direct-to-consumer subscription platforms concentrate prestige fragrance demand. FDA cosmetic labeling requirements govern allergen disclosure standards. New York and Los Angeles anchor flagship retail and algorithmic curation ecosystems.
China
Duty-free retail growth and urban middle-class purchasing power accelerate parfum-strength adoption. NMPA cosmetic registration rules extend product approval timelines. Shanghai and Hainan Island concentrate luxury fragrance distribution infrastructure.
France
Heritage absolutes production and captive Grasse cultivation secure competitive moats for prestige houses. REACH authorization requirements under ECHA jurisdiction eliminate certain synthetic fixatives. The Provence-Alpes-Côte d'Azur region anchors jasmine and rose de mai extraction.
Germany
Pharmacy channel density and sustainability-conscious consumer preferences sustain mass-market volume. EU Green Deal chemical sustainability targets mandate phased reduction of synthetic musks. Cologne and Hamburg concentrate fragrance manufacturing and distribution hubs.
India
BIS quality mark recognition and duty-free retail expansion in Mumbai and Delhi create entry points for prestige penetration. CDSCO cosmetic regulations govern import and safety standards. Maharashtra and Karnataka concentrate personal care manufacturing clusters.
Global Fragrances and Perfumes Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the value chain. The market structures around vertically integrated luxury houses, specialized ingredient suppliers, and licensed portfolio operators. Three archetypes dominate: captive raw material controllers, biotechnology-enabled ingredient innovators, and celebrity-brand licensees. Competitive moves concentrate on M&A for supply chain control and direct-to-consumer channel bypass.
Within the captive supply tier, LVMH Moët Hennessy Louis Vuitton and Chanel exemplify vertical control over proprietary sourcing corridors. Among biotechnology-enabled ingredient specialists, Givaudan occupies a position representing engineered yeast strain deployment for rare molecule synthesis. These anchors illustrate the bifurcation between heritage house supply security and science-driven extraction economics.
| Leading Market Players |
|---|
| LVMH Moët Hennessy Louis Vuitton |
| Chanel |
| The Estée Lauder Companies |
| L'Oréal |
| Coty |
| Givaudan |
| Symrise |
| Firmenich |
| Avon |
| Others |
Supply Flow & Price Mechanics
Bio-fermented sandalwood alternatives displacing endangered botanical species are redrawing sourcing corridors from Madagascar and Indonesia toward biotechnology hubs in Switzerland and California, compressing traditional absolutes premiums while inflating capital requirements for fermentation capacity.
Pricing Analysis
EU Green Deal chemical sustainability targets dictate the pricing tier structure across European formulations. Three-tier pricing structure across prestige, standard, and economy levels separates heritage houses absorbing reformulation costs from mass-market lines facing margin compression. Price differentiation rests on captive raw material control versus licensed portfolio dependency. Cost compression in mass-market tiers is intensifying because biofuel policy competition for agricultural ethanol feedstocks elevates carrier costs.
Supply Chain Analysis
Inventory cycles for Bulgarian rose oil and Madagascan vanilla extend 18-24 months from harvest to finished goods, amplifying price volatility exposure. Supply concentrates in France for Grasse jasmine, Bulgaria for rose de mai, and Madagascar for vanilla bourbon. Formulation draws from ethanol carriers, synthetic musk alternatives, and upcycled botanical extracts. Single-source vulnerability in Mediterranean basin harvests threatens continuity. Distribution runs through department store concessions, direct-to-consumer platforms, and duty-free retail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as unisex positioning and gender-fluid marketing collapse traditional segmentation, creating shelf-space niches for positioning outside masculine-feminine binaries.
For Market Incumbents: Consolidate captive control over Grasse jasmine and rose de mai harvests before climate volatility disrupts Mediterranean sourcing corridors further. Deepen backward integration into biotechnology-olfactory convergence to secure rare molecule synthesis capabilities against Givaudan and Firmenich patent thickets. Anchor competitive moats through proprietary absolutes production rather than licensed celebrity dependencies. For New Entrants and Emerging Players: Lead with algorithmic curation and subscription sampling models that bypass wholesale margin structures and capture household purchasing data at scale. Target Indian duty-free retail expansion in Mumbai and Delhi as the most penetrable geography for prestige penetration among emerging middle-class consumers. Deploy direct-to-consumer launches with personalized fragrance matching as the primary go-to-market angle. For Investors and Strategic Acquirers: REACH authorization requirements under ECHA jurisdiction reshapes the acquisition landscape by eliminating certain synthetic fixatives and forcing reformulation investments. Long-term viability favors biotechnology-enabled ingredient specialists with engineered yeast strain deployment over heritage houses dependent on climate-vulnerable botanical sourcing. Monitor divergence between Brussels and Washington fragrance allergen lists as the signal indicating regulatory fragmentation risk.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Raw Material Acquisition | Secures proprietary supply chains for Grasse jasmine and rose de mai against climate volatility. |
| Bio-Fermentation Capacity Buildout | Reduces dependency on endangered agarwood and sandalwood species through microbial synthesis. |
| Direct-to-Consumer Platform Launch | Bypasses Sephora and Douglas gatekeeper power while capturing consumer preference data. |
| Unisex Fragrance Line Extension | Erodes traditional gender segmentation to capture shared household purchasing occasions. |
| India Duty-Free Retail Expansion | Leverages BIS quality mark recognition for emerging middle-class penetration in Mumbai and Delhi. |
Methodological Framework
The analysis maps prestige-tier personal fragrance, mass-market licensed portfolios, and biotechnology-derived ingredients, each validated through perfumery R&D directors, brand managers at heritage houses, category buyers at Sephora and Douglas, and supply chain planners at Givaudan and Firmenich. Primary interviews with master perfumers and regulatory affairs specialists combine with secondary validation through IFRA standards documentation, ECHA REACH authorization databases, EU Green Deal chemical sustainability targets, and customs trade data for ethanol and absolutes imports. Bottom-up volume modeling triangulates against top-down value estimates.
Consistency checks against external benchmarks validate projection outputs across the analysis window. Segmentation dimensions modeled include product concentration tier, end-user gender positioning, sales channel format, and regional regulatory cluster. CAGRs derive from iterative reconciliation between historical trajectory and forward-looking elasticity assumptions. Industry-specific forecast inputs incorporate bio-fermentation capacity expansion timelines and REACH authorization phase-out schedules.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated climate disruption in Mediterranean harvesting regions would require recalibration. Forecasts reflect documented assumptions regarding substitution dynamics between synthetic and bio-derived molecules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Natural Fragrance Market
Fragrances & Perfumes
Smart Fragrance Box Market
Fragrances & Perfumes
Home Fragrance Diffusers Market
Fragrances & Perfumes
Digital Fragrance Market
Fragrances & Perfumes
GCC Perfume and Fragrance Market
Fragrances & Perfumes
Global Perfume Market
Fragrances & Perfumes
Cosmetic and Fragrance Retail Chain Market
Fragrances & Perfumes
Global Fragrance Market
Fragrances & Perfumes
Fragrance Diffuser Market
Fragrances & Perfumes
Saudi Arabia Perfume Market
Fragrances & Perfumes
Global Luxury Perfumes Market
Fragrances & Perfumes
Digital Perfume Market
Fragrances & Perfumes
Gulf Cooperation Council Fragrance and Perfumes Market
Fragrances & Perfumes
Gourmand Fragrance Market
Fragrances & Perfumes
Middle East Fragrances Market
Fragrances & Perfumes
Fragrance Product Market