
 Fragrance Oil Market | 2026-2036
Fragrance Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Fragrance Oil Market Analysis
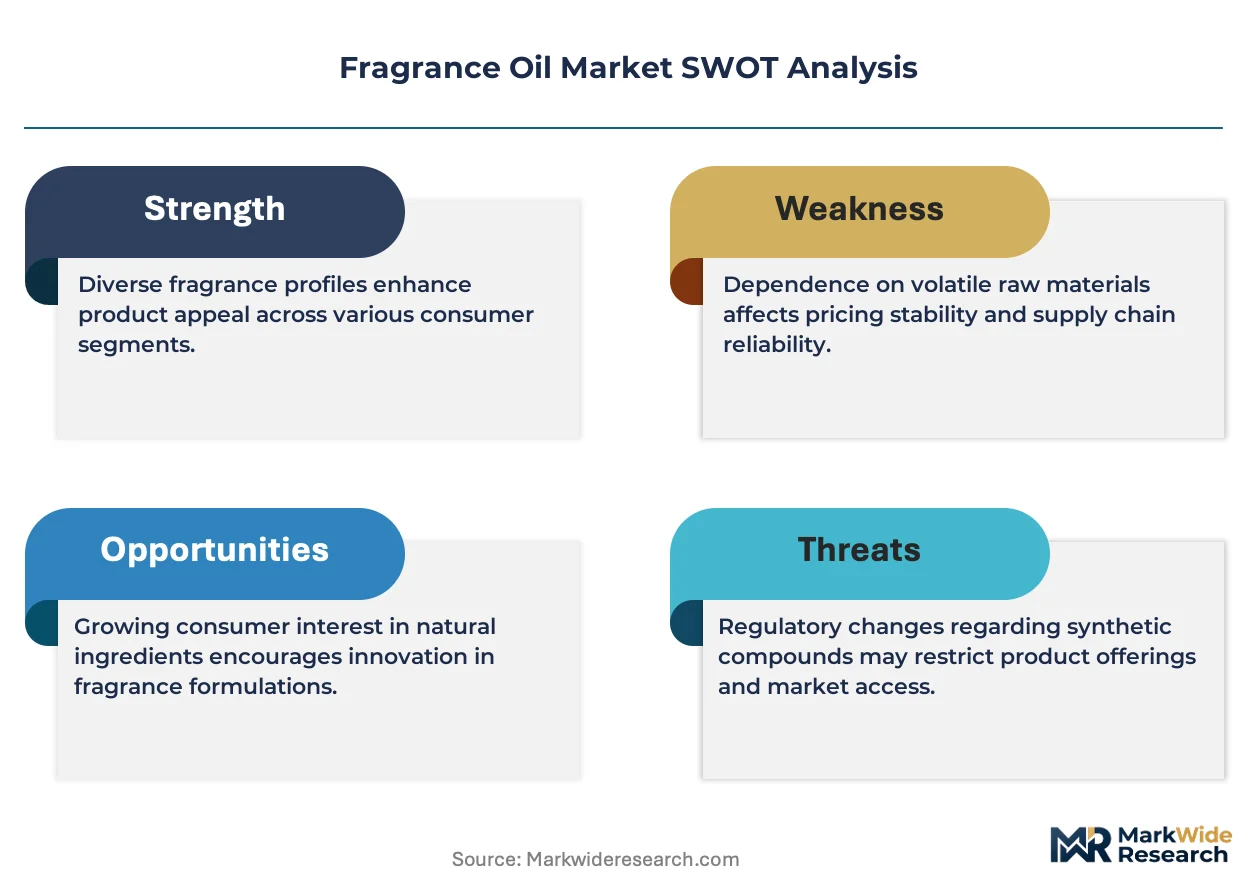
Asset-light contract manufacturing and third-party tolling arrangements is reconfiguring capital requirements for new entrants in fragrance oil production. Givaudan leverages captive biotechnology labs to secure proprietary molecule pipelines. International Flavors & Fragrances anchors its position through backward integration into natural raw material sourcing. Symrise competes via specialized fermentation-derived aroma molecules that reduce botanical dependency.
Fragrance oils are concentrated aromatic compounds, typically comprising 15-30% perfume oil dissolved in carrier solvents such as dipropylene glycol or isopropyl myristate, designed to impart scent to finished consumer products. Synthetic oils dominate volume shipments due to cost stability and reproducibility, while natural oils command premium positioning in certified clean-label cosmetics where margin pools concentrate. Personal care applications lead absolute consumption, though home care diffusion systems represent the fastest-growing demand vector as ambient scenting penetrates residential spaces.
IFRA standards govern allergen thresholds and restrict specific molecules across Europe and North America, while China's SAMR enforces GB/T labeling requirements that shape import compliance costs. REACH registration in the European Union and state-level Proposition 65 enforcement in California compel reformulation investments and supply chain documentation. Stakeholders must monitor regulatory divergence between fragrance safety frameworks and emerging biodegradability mandates to anticipate compliance-driven product redesign cycles.
Market Dynamics
Biotechnology-enabled molecule synthesis is restructuring capital efficiency and raw material security for fragrance oil producers, compressing botanical dependency while accelerating proprietary pipeline development.
Growth Catalysts
- Home Care Diffusion Systems:Residential ambient scenting installations are multiplying as consumers prioritize indoor environment quality, pulling concentrated oil formulations into smart home ecosystems.
- IFRA Allergen Disclosure Standards:Tighter allergen thresholds across Europe and North America are forcing transparency investments that premium-position compliant suppliers against non-compliant imports.
- China Domestic Brand Scaling:Indigenous Chinese fragrance houses are expanding captive oil production capacity, concentrating demand within the country's manufacturing clusters.
Market Restraints
- Natural Feedstock Volatility:Weather-dependent harvests of jasmine, rose, and sandalwood create input cost instability that synthetic alternatives partially hedge but cannot eliminate for certified clean-label segments.
- REACH Registration Burden:European Union chemical registration requirements impose documentation costs that disproportionately burden small-batch specialty oil producers.
- Biotechnology Patent Concentration:Core fermentation-derived aroma molecule patents cluster with three dominant suppliers, limiting independent R&D pathways for mid-scale competitors.
Strategic Opportunities
- India Personal Care Penetration:Underdeveloped branded fragrance consumption in tier-two and tier-three Indian cities offers white space for affordable oil formulations tailored to local olfactory preferences.
- EU Green Deal Biodegradability Mandates:Upcoming sustainability criteria will advantage suppliers with verified biodegradable molecule portfolios against legacy petrochemical-derived competitors.
- Direct-to-Consumer Subscription Channels:Home scenting brands are bypassing traditional retail through curated monthly oil deliveries, capturing lifetime value data and reformulation feedback loops.
Industry Challenges
- Biochemist Talent Scarcity:Fermentation-scale aroma molecule production requires hybrid skill sets spanning organic chemistry and industrial biotechnology that traditional perfumery training programs do not cultivate.
- Cross-Regulatory Compliance Complexity:Simultaneous adherence to IFRA standards, REACH registration, and China's GB/T labeling creates documentation redundancy that stretches quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fragrance Oil Market |
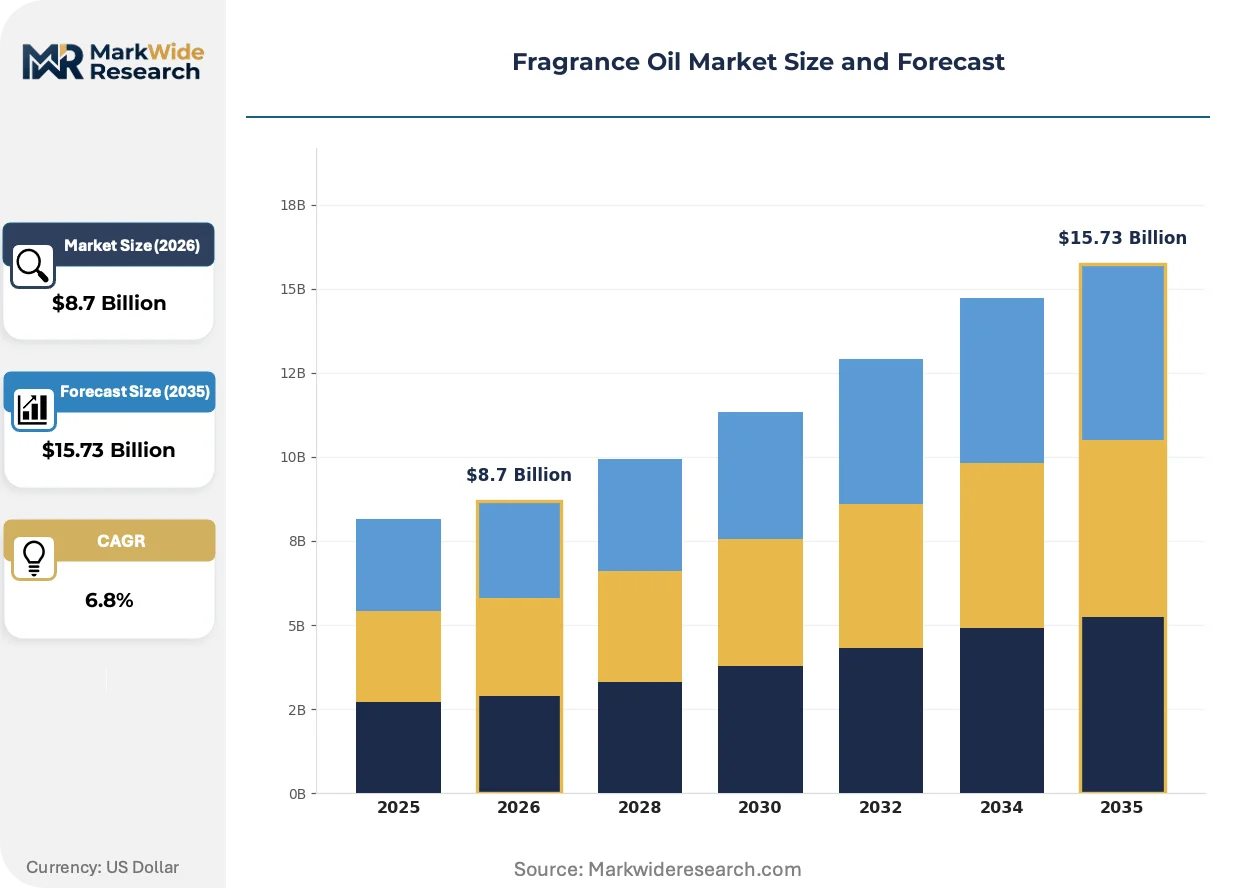
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Personal Care, Home Care, Cosmetics, Household Products Product Type: Natural Oils, Synthetic Oils, Aroma Oils, Essential Oils End User: Manufacturers, Retailers, Wholesalers, Individual Consumers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Others |
| Companies Covered | Givaudan, International Flavors & Fragrances (IFF), Firmenich, Symrise, Robertet, Mane, Takasago, Sensient Technologies Corporation, CPL Aromas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fragrance Oil Market Emerging Trajectories
Synthetic biology and precision fermentation are displacing conventional extraction methods, while regulatory fragmentation and direct-to-consumer channel expansion are simultaneously compressing margins and opening new demand vectors.
Precision fermentation for aroma molecules is migrating from pilot-scale demonstrations to commercial volumes. Cosmetic contract manufacturers in South Korea and Germany are integrating these biologically derived ingredients into certified clean-label formulations. This technology is migrating from niche premium positioning toward mass-market personal care, collapsing the historical cost premium between natural-extracted and synthetic-identical molecules.
REACH registration deadlines in the European Union are tightening substance authorization requirements for fragrance intermediates. Formulators face reformulation investments or supply discontinuation for non-registered molecules. Fine fragrance houses with legacy European supply chains are most affected, accelerating dual-sourcing strategies that incorporate Asia-Pacific biotechnology suppliers.
Subscription-based home scenting procurement is displacing episodic retail purchasing among affluent urban consumers. Direct-to-consumer brands capture consumption data that enables predictive oil replenishment and personalized scent profiling. This behavioral shift is most visible in United States and United Kingdom metropolitan markets where smart home device penetration enables automated diffusion scheduling.
Fragrance Oil Market Segmentation
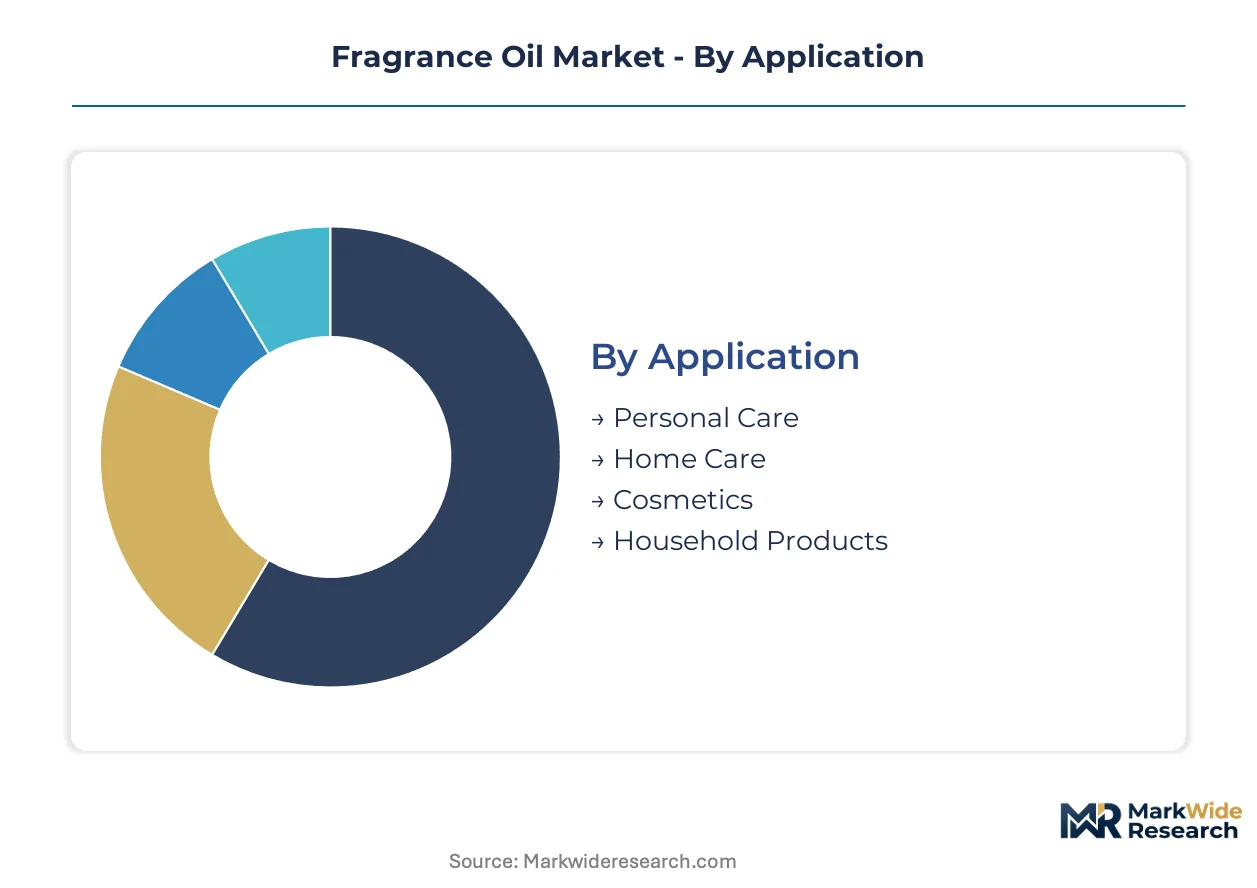
Fragrance oil segmentation determines formulation chemistry, regulatory compliance pathways, and margin architecture across divergent end-use specifications. Technical requirements for skin-contact applications differ fundamentally from ambient diffusion systems, while natural certification tiers command distinct pricing premiums.
Application:
After-sales service intensity varies sharply across application segments, with personal care requiring dermatological safety documentation and reformulation support that home care installations rarely demand.
- Personal Care:Skin-safe formulations with IFRA-compliant allergen thresholds dominate, incorporating carrier solvents like dipropylene glycol for direct body contact. Demand concentrates in South Korean and German cosmetic contract manufacturing facilities where clean-label certification commands premium positioning against standard formulations.
- Home Care:Concentrated oil systems designed for smart diffusion hardware enable automated ambient scenting in residential environments. Growth is accelerating fastest in United States and United Kingdom metropolitan markets where subscription-based replenishment models capture lifetime value data.
- Cosmetics:Color-compatible fragrance systems must survive oxidative stability testing in pigmented formulations.
- Household Products:Cost-optimized synthetic oils serve functional cleaning applications where scent persistence outweighs ingredient provenance.
By volume, personal care leads. By growth pace, home care is ahead.
Product Type:
Cost tier stratification separates certified natural extracts from commodity synthetics, with biotechnology-derived molecules collapsing historical price premiums between categories.
- Natural Oils:Botanical extractions from jasmine, rose, and sandalwood face weather-dependent harvest volatility that synthetic alternatives cannot fully hedge. Demand clusters in certified clean-label cosmetics where European Union Green Deal biodegradability mandates will advantage verified sustainable portfolios.
- Synthetic Oils:Petrochemical-derived aroma molecules offer cost stability and batch reproducibility for mass-market applications. Volume concentrates in household product manufacturing where input cost predictability outweighs natural certification requirements.
- Aroma Oils:Blended formulations combining natural and synthetic components optimize performance-to-cost ratios for mid-tier positioning.
- Essential Oils:Therapeutic-grade distillates require distillation equipment investment that limits supplier base concentration.
Synthetic oils dominate absolute shipments. Natural oils capture the steepest expansion trajectory in premium personal care.
End User:
Customer type determines order scale, technical service requirements, and formulation customization depth across the value chain.
- Manufacturers:Captive fragrance oil production by large personal care and home care formulators drives bulk procurement with dedicated quality assurance protocols.
- Retailers:Private-label fragrance programs require flexible minimum order quantities and rapid reformulation turnaround.
- Wholesalers:Inventory consolidation across multiple suppliers demands standardized specification documentation for downstream resale.
- Individual Consumers:Direct-to-consumer subscription channels bypass traditional wholesale markups through curated monthly oil deliveries.
Manufacturers account for the largest order volumes. Individual consumers are gaining share fastest through digital channel migration.
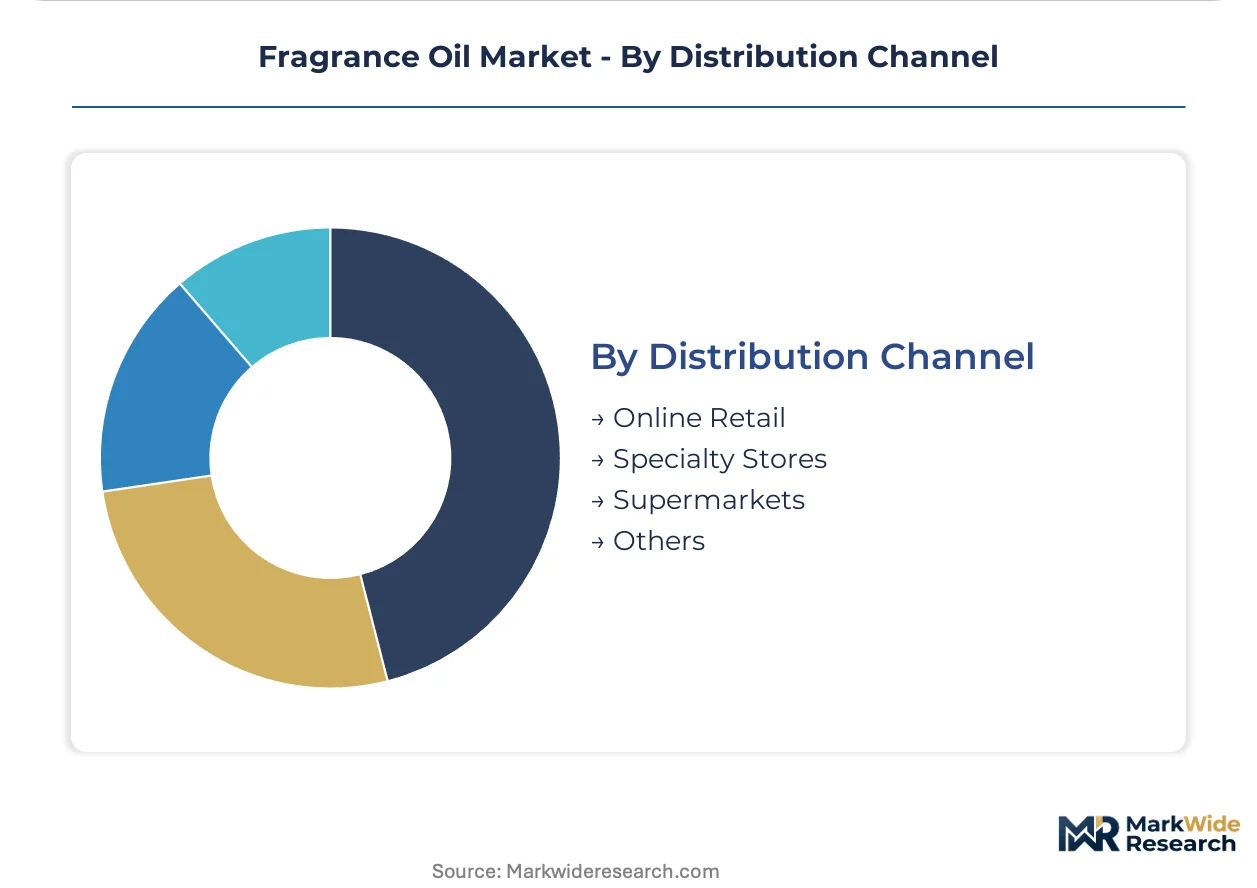
Distribution Channel:
Channel selection shapes customer acquisition economics and consumption data capture capabilities for predictive replenishment systems.
- Online Retail:E-commerce platforms enable scent profiling algorithms and automated subscription management for home diffusion systems. Penetration is deepest in United States and United Kingdom urban markets where smart home device integration supports scheduling automation.
- Specialty Stores:Curated fragrance consultations support premium natural oil discovery and personalized blending services.
- Supermarkets:Mass-market synthetic oils reach price-sensitive household product consumers through high-velocity retail placement.
- Others:Direct B2B supply agreements and professional service channels serve institutional ambient scenting installations.
Supermarkets move the highest unit volumes. Online retail is climbing the fastest as subscription models displace episodic purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal biodegradability mandates are redirecting procurement toward verified sustainable molecule portfolios across multiple jurisdictions. National fragrance safety frameworks are diverging in stringency, creating compliance complexity for multinational suppliers. Production clusters are consolidating in biotechnology hubs with established fermentation infrastructure.
United States
Smart home diffusion systems are penetrating residential markets in metropolitan corridors, pulling concentrated oil formulations into automated replenishment channels. California's Proposition 65 enforcement compels supply chain documentation for specific aroma molecules. New Jersey and New York host concentrated flavor and fragrance manufacturing facilities serving North American personal care brands.
China
Domestic fragrance houses are scaling captive oil production capacity in response to consumer preference for indigenous brands. SAMR enforces GB/T labeling requirements that shape import compliance costs for foreign suppliers. Manufacturing clusters in Shanghai and Guangzhou concentrate biotechnology-enabled aroma molecule development for regional cosmetic contract manufacturers.
Germany
REACH registration deadlines are tightening substance authorization requirements for fragrance intermediates used in fine fragrance formulations. ECHA documentation obligations disproportionately burden small-batch specialty oil producers with legacy supply chains. Cologne and Hamburg anchor European distribution networks for fermented aroma molecules targeting clean-label cosmetics.
India
Branded fragrance consumption is expanding in tier-two and tier-three cities, creating white space for affordable oil formulations. BIS standards govern ingredient disclosure requirements for personal care applications. Maharashtra and Gujarat concentrate contract manufacturing facilities serving domestic and export-oriented cosmetic brands.
United Kingdom
Subscription-based home scenting procurement is displacing episodic retail purchasing among affluent urban consumers. IFRA allergen disclosure standards align with post-Brexit regulatory autonomy negotiations. Greater London hosts direct-to-consumer fragrance brands capturing lifetime value data through curated monthly oil deliveries.
Fragrance Oil Market Vendor Landscape
On the supply side, the industry is consolidating around biotechnology-enabled molecule synthesis capabilities that compress traditional botanical extraction economics. Three strategic archetypes dominate: integrated fragrance houses with captive fermentation labs, specialized natural extraction houses serving certified clean-label segments, and regional compounders optimizing cost-performance ratios for mass-market household products. Dominant competitive moves include backward integration into natural raw material sourcing and technology licensing agreements for proprietary fermentation strains.
Within the integrated tier, Givaudan, International Flavors & Fragrances, and Symrise exemplify the capital-intensive archetype combining biotechnology pipelines with global distribution infrastructure. These Swiss and US-based entities anchor competitive positioning through hybrid capabilities spanning synthetic chemistry, precision fermentation, and botanical extraction. Regional specialists occupy mid-market positioning without comparable R&D scale.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances (IFF) |
| Firmenich |
| Symrise |
| Robertet |
| Mane |
| Takasago |
| Sensient Technologies Corporation |
| CPL Aromas |
| Others |
Supply Flow & Price Mechanics
Biotechnology patent concentration in Switzerland and the United States anchors upstream molecule supply, concentrating margin capture with integrated houses that license fermentation-derived aroma compounds to downstream formulators lacking captive R&D infrastructure.
Pricing Analysis
Certification level creates the primary spread between natural-extracted, biotechnology-derived, and petrochemical-synthetic grades. Three-tier pricing structure across premium certified-natural, mid-tier biotechnology, and economy synthetic levels dominates transactional dynamics. Cost compression in synthetic grades is intensifying because Chinese domestic brands are scaling captive production and reducing import dependency. Household product manufacturers exhibit the highest price sensitivity, while European cosmetic contract manufacturers absorb premiums for REACH-compliant, biodegradable-certified molecules.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for biotechnology-derived aroma molecules as integrated houses finance working capital for downstream cosmetic contract manufacturers. Supply concentrates in China, Switzerland, and Germany, with Shanghai and Guangzhou anchoring fermentation-scale production. Feedstock dependencies span jasmine harvests from Egypt, sandalwood from Australia, and fermentation feedstocks from corn-derived dextrose. Single-source vulnerability in precision fermentation strains creates concentration risk. Distribution runs through direct B2B supply agreements for manufacturers, with online retail channels capturing individual consumer subscription flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart home ecosystem interoperability is transforming fragrance oil procurement into a platform-attached recurring revenue model, where diffusion hardware compatibility locks in replenishment streams and captures lifetime value data.
For Market Incumbents: Build biotechnology patent moats around proprietary fermentation strains for jasmine and sandalwood mimics. Deepen backward integration into natural raw material sourcing in Egypt and Australia to hedge harvest volatility. Acquire mid-scale Indian compounders to preempt domestic brand scaling in tier-two cities. Capacity addition in Guangzhou biotechnology clusters counters Chinese import substitution. For New Entrants and Emerging Players: Build out direct-to-consumer subscription channels in United Kingdom and United States metropolitan markets where smart home device penetration enables automated replenishment. Target underpenetrated tier-two Indian cities with affordable synthetic oil formulations tailored to local olfactory preferences. Pursue white-label supply agreements with South Korean cosmetic contract manufacturers seeking clean-label certification without captive biotechnology investment. For Investors and Strategic Acquirers: Capital is best deployed toward biotechnology-enabled specialists with commercial-scale precision fermentation capabilities and existing REACH registration portfolios. Long-term viability hinges on defensible molecule pipelines and regulatory compliance infrastructure rather than brand equity. Watch for inflection when EU Green Deal biodegradability mandates trigger reformulation cycles that obsolete legacy petrochemical-derived supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Captive biotechnology production reduces botanical dependency and secures proprietary molecule pipelines against harvest volatility. |
| REACH Registration Investment | ECHA compliance documentation enables continued European market access as substance authorization deadlines tighten. |
| Direct-to-Consumer Channel Launch | Subscription models bypass retail markups and capture consumption data for predictive replenishment algorithms. |
| Backward Integration into Natural Sourcing | Upstream control over jasmine and sandalwood supply hedges input cost instability for certified clean-label segments. |
| Smart Home Ecosystem Partnership | Integration with automated diffusion hardware locks in recurring replenishment revenue and platform-dependent customer relationships. |
Methodological Framework
The analysis maps natural extraction, synthetic chemistry, and biotechnology-derived fragrance oil production, each validated through perfumery R&D directors, cosmetic contract manufacturing procurement leads, and regulatory affairs specialists at integrated houses. Primary interviews with smart home device platform engineers and subscription channel brand managers combined with secondary validation from IFRA disclosure filings, REACH registration databases, and SAMR GB/T labeling directives. Bottom-up triangulation across supplier capacity disclosures and top-down demand modeling from personal care and home care end-use consumption patterns anchored volume and value estimates.
Assumptions held fixed include continued IFRA allergen threshold tightening in Europe and North America, sustained Chinese domestic brand scaling, and biotechnology cost parity achievement with natural extraction across the projection horizon. Segmentation dimensions modeled encompass product type, application, end user, and distribution channel, with additional granularity on certification tier and biodegradability status. CAGRs were derived from fitted growth curves against historical diffusion system penetration rates and subscription channel adoption patterns. Forecast inputs incorporated smart home device installation trajectories and REACH registration compliance timelines.
Stress conditions across biotechnology patent litigation outcomes, jasmine harvest disruption events, and EU Green Deal implementation acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory trajectory and technology cost curves. Macroeconomic contraction in discretionary personal care spending, regulatory deviation from announced IFRA or Green Deal timelines, or breakthrough alternative scent delivery technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Clean Perfume Market
Fragrances & Perfumes
Fragrance Diffuser Market
Fragrances & Perfumes
Home Fragrance Diffusers Market
Fragrances & Perfumes
Middle East Fragrances Market
Fragrances & Perfumes
GCC Perfume Market
Fragrances & Perfumes
Digital Scent Market
Fragrances & Perfumes
GCC Perfume and Fragrance Market
Fragrances & Perfumes
Perfume Vials Market
Fragrances & Perfumes
Global Fragrance Market
Fragrances & Perfumes
Saudi Arabia Perfume Market
Fragrances & Perfumes
Global Fragrances and Perfumes Market
Fragrances & Perfumes
Reed Diffusers Market
Fragrances & Perfumes
Saudi Arabia E-Commerce Cosmetics and Fragrances Market
Fragrances & Perfumes
Fragrance Emulsion Market
Fragrances & Perfumes
Wax Melts Market
Fragrances & Perfumes
Natural Fragrance Market