

Perfume Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Perfume Vials Market Insights
Aftermarket refill programs is reconfiguring margin pools away from one-time vial sales toward recurring consumable revenue. Pochet Group leverages its historic Saint-Quentin glassworks to sustain artisanal production credibility with heritage fragrance houses. Gerresheimer competes through pharmaceutical-grade quality systems repurposed for luxury cosmetic applications. Albéa anchors its position via integrated decoration capabilities spanning metallization to silk-screening.
Perfume vials are precision-formed containers, typically 1 ml to 15 ml in capacity, engineered from borosilicate glass, soda-lime glass, or crystal to prevent fragrance oxidation and preserve volatile organic compounds. Glass dominates structural value due to chemical inertness and premium tactile properties demanded by luxury brands. Spray closure mechanisms lead volume distribution across travel retail and sampler segments, while screw cap configurations retain strength in gift sets where resealability matters. Crystal and metal materials command concentrated margin pools in limited-edition releases and bespoke commissions.
EU REACH restrictions on heavy metals in glass colorants and the EU Green Deal circular economy mandates reshape material sourcing and post-consumer collection obligations for vial manufacturers. FDA cosmetic container regulations govern migration limits for any plastic components in vials distributed through US prestige retail channels. Stakeholders must monitor how France's AGEC anti-waste law and emerging US state-level packaging extended producer responsibility frameworks alter minimum recycled content thresholds and collection infrastructure investments.
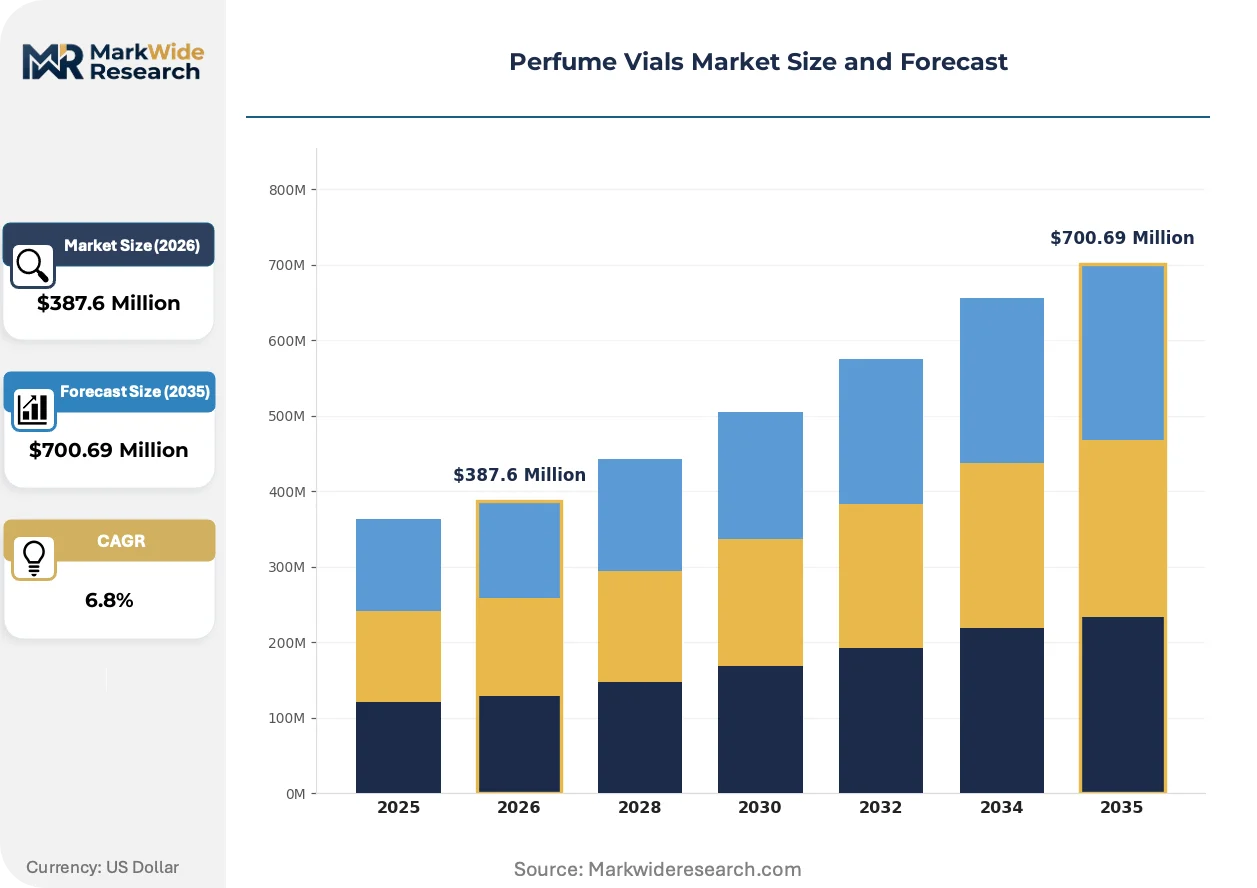
Market Dynamics
France's AGEC anti-waste law and EU REACH compliance mandates are forcing vial manufacturers to reconfigure material sourcing, decoration chemistry, and post-consumer collection infrastructure simultaneously.
Growth Catalysts
- EU Green Deal circular economy mandates:Extended producer responsibility frameworks in France and Italy compel heritage glassmakers to develop refill-compatible vial architectures, locking in long-term supply relationships with luxury fragrance houses.
- Travel retail expansion:Miniature and sampler formats below 5 ml capacity capture disproportionate margin in airport duty-free channels, where impulse purchase velocity favors portable, TSA-compliant configurations.
- Borosilicate glass thermal stability:Premium fragrance compounds with high alcohol content and reactive top notes demand chemically inert containment that soda-lime formulations cannot reliably provide.
Market Restraints
- Heavy metal pigment restrictions:ECHA REACH Annex XVII limitations on cadmium and lead in glass colorants eliminate traditional decoration palettes, forcing costly reformulation of heritage amber and cobalt tones.
- Energy-intensive furnace operations:Natural gas price volatility and EU carbon border adjustment mechanisms compress operating margins for artisanal glassworks dependent on continuous-batch melting.
- Pharmaceutical-grade polymer substitutes:Cyclic olefin copolymers and advanced barrier plastics encroach on sub-3 ml sampler segments where weight reduction and breakage elimination outweigh tactile premium.
Strategic Opportunities
- US state-level EPR frameworks:California, Oregon, and Maine packaging stewardship laws create first-mover advantage for vial manufacturers with pre-established post-consumer collection and mechanical recycling capabilities.
- Biophotonic glass integration:Violet-tinted borosilicate formulations that filter damaging light wavelengths while permitting beneficial violet rays converge wellness positioning with functional preservation for clean beauty fragrance lines.
- Direct-to-consumer refill subscriptions:Brand-owned replenishment platforms bypass traditional retail markups, enabling vial producers to capture recurring revenue through proprietary closure and pump mechanisms.
Industry Challenges
- Artisanal furnace operator scarcity:Master glassblowers capable of hand-manipulating crystal vials for limited-edition releases command premium wages that automated production cannot replicate, constraining scale-up for bespoke commissions.
- Dual certification timelines:Simultaneous FDA cosmetic container migration testing and EU REACH SVHC screening extend product qualification cycles, delaying commercialization of novel decoration chemistries.
- Legacy ERP integration with traceability systems:Batch-level serialization requirements for EU digital product passports collide with decades-old production scheduling software at mid-cap glassworks.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perfume Vials Market Trends and Innovations
Digital decoration technologies and regulatory traceability mandates are compressing traditional vial production timelines while fragmenting competitive advantage across material science, data infrastructure, and artisanal craft preservation.
Ultraviolet-cured inkjet printing with ceramic-based pigments is virtualizing the economics of small-batch customization. Niche fragrance houses in Paris and Milan now order runs below 500 units with photographic-quality imagery, collapsing minimum viable order quantities that historically favored gravure and silk-screen decoration. This capability is virtualizing the barrier between mass-market standardization and bespoke artisanal production.
EU Digital Product Passport requirements under the Ecodesign for Sustainable Products Regulation impose granular material disclosure obligations on vial importers. Glass manufacturers serving French luxury houses must now document sand sourcing, furnace energy mix, and post-consumer recycled content percentages at the SKU level. Italian crystal specialists are responding by securing third-party blockchain verification for artisanal furnace operations to differentiate from industrially produced alternatives.
Buyer consolidation among prestige beauty conglomerates concentrates procurement leverage with three holding companies controlling majority fragrance brand portfolios. This purchasing concentration forces vial suppliers to absorb extended payment terms and exclusive capacity commitments in exchange for multi-year supply agreements. The pressure manifests most acutely in Normandy and Murano, where family-owned glassworks face binary choices between scale investment and exit to private equity consolidators.
Perfume Vials Market Segmentation
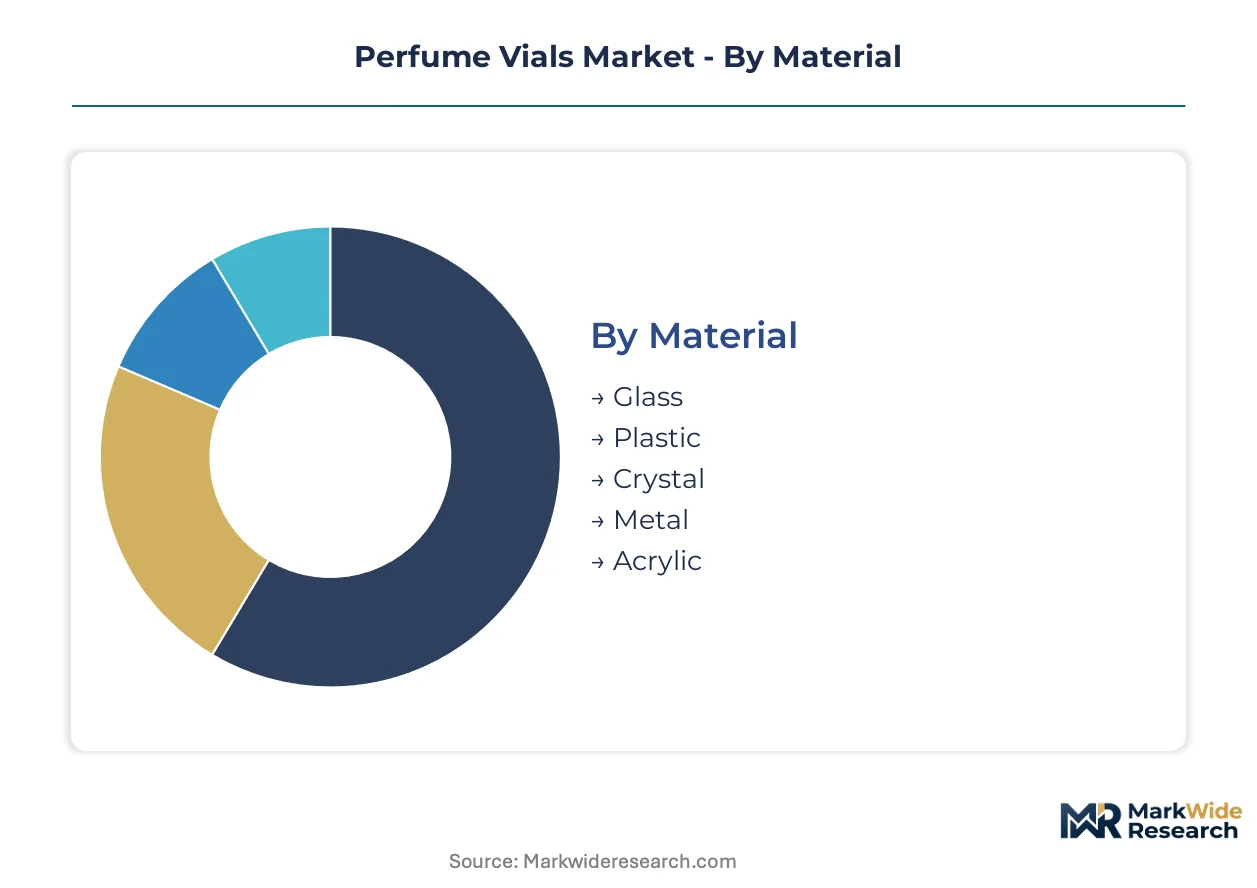
Perfume vial procurement decisions cascade through material chemistry, volumetric precision, and closure mechanics before reaching end-use application. Each segmentation dimension carries distinct regulatory footprints and margin architectures that reshape supplier competitive positioning.
Material:
Cost tier differentiation separates commodity substrates from heritage-grade compositions demanding artisanal furnace operations and precious metal integration.
- Glass:Soda-lime and borosilicate formulations dominate structural volume, with borosilicate's thermal shock resistance capturing premium fragrance houses in France and Italy. ECHA REACH Annex XVII compliance on heavy metal colorants forces reformulation of traditional amber and cobalt palettes.
- Crystal:Lead-free optical glass and hand-manipulated artisanal production command concentrated margin pools in limited-edition releases. Murano and Saint-Quentin glassworks leverage generational craft credentials to sustain pricing power against mechanized alternatives.
- Plastic:Cyclic olefin copolymers and advanced barrier polymers encroach on sampler segments where weight reduction and breakage elimination outweigh tactile premium.
- Metal:Aluminum and stainless steel configurations serve travel retail and gift set applications demanding durability alongside decorative metallization.
- Acrylic:PMMA formulations capture promotional and mass-market sampler tiers where unit cost minimization supersedes chemical inertness requirements.
Glass commands the established base. The steepest expansion runs through crystal limited editions and polymer sampler substitutes.
Capacity:
Volumetric specification directly determines distribution channel eligibility, regulatory classification, and per-unit margin realization across travel retail and prestige retail formats.
- 1 ml:Micro-sampler formats enable fragrance house customer acquisition economics through controlled trial distribution. TSA compliance and impulse velocity in airport duty-free channels sustain disproportionate margin capture.
- 3 ml:Miniature travel formats balance portability with sufficient volume for multi-day use, concentrating demand among business travelers and gift set assemblers in United States prestige retail.
- 5 ml:Standard sampler capacity dominates subscription box and promotional insertion economics.
- 10 ml:Mid-tier personal use format captures refill program adoption and direct-to-consumer replenishment platforms.
- 15 ml:Maximum portable capacity before airline liquid restrictions, serving extended travel and premium gift applications.
1 ml and 3 ml formats anchor current volume. The sharpest climb is occurring in 10 ml refill-compatible architectures.
Closure Type:
Mechanical sealing technology governs fragrance preservation integrity, user experience differentiation, and compatibility with automated filling lines.
- Spray:Aerosol pump mechanisms with crimped valve assemblies dominate travel retail and prestige counter distribution. Fine mist particle size consistency separates pharmaceutical-grade suppliers from cosmetic-tier competitors.
- Screw Cap:Threaded aluminum or phenolic closures retain strength in gift sets and collector editions where resealability and ceremonial unboxing experience matter.
- Dropper:Glass pipette configurations serve oil-based parfum concentrations and niche fragrance houses emphasizing ritualistic application.
- Stopper:Ground glass or cork stoppers preserve heritage aesthetics for limited editions and crystal vial presentations.
- Flip Top:Hinged polypropylene closures capture mass-market and promotional tiers where single-hand operation and cost minimization converge.
Spray mechanisms hold the incumbent position. The most rapid technology shift is unfolding in magnetic and snap-fit closure systems for refill programs.
End User:
Customer type segmentation reveals divergent procurement sophistication, quality tolerance thresholds, and supply chain integration depth.
- Luxury Brands:Heritage fragrance houses and prestige beauty conglomerates demand batch-level traceability, artisanal provenance documentation, and exclusive capacity commitments. EU Digital Product Passport compliance and blockchain verification of furnace operations now condition supplier qualification.
- Personal Use:Direct-to-consumer fragrance startups and independent perfumers prioritize minimum order flexibility and rapid decoration turnaround over legacy glassworks scale economies.
- Gift Sets:Seasonal assemblers and duty-free operators require coordinated multi-SKU packaging and customs-optimized logistics configurations.
- Promotional Items:Mass-market trial programs and magazine insertions prioritize unit cost minimization and high-velocity automated filling compatibility.
Luxury brands concentrate value capture. The most dynamic volume expansion is emerging in personal use direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in France and Italy exhibit low price elasticity for heritage-grade crystal and artisanal glass, while promotional-tier purchasers in the United States and emerging markets prioritize unit cost minimization over tactile premium.
France
Heritage fragrance houses anchor demand for hand-manipulated crystal vials and refill-compatible architectures. France's AGEC anti-waste law mandates extended producer responsibility for post-consumer glass collection, reshaping supplier obligations. The Saint-Quentin glassworks cluster in Hauts-de-France sustains artisanal furnace operations for limited-edition releases.
Italy
Murano glassmakers capture concentrated margin pools through generational craft credentials and bespoke commission workflows. EU REACH Annex XVII restrictions on cadmium and lead colorants force reformulation of traditional amber and cobalt decoration palettes. The Veneto region's crystal specialists are securing blockchain verification to differentiate furnace operations from industrial alternatives.
United States
Prestige retail channels and direct-to-consumer fragrance startups drive demand for TSA-compliant travel formats and rapid-decoration turnaround. FDA cosmetic container regulations govern migration limits for plastic components in vials distributed through prestige retail. California's packaging extended producer responsibility framework creates first-mover advantage for manufacturers with established mechanical recycling capabilities.
Germany
Pharmaceutical-grade quality systems and precision glass forming serve luxury cosmetic applications with batch-level traceability requirements. ECHA REACH SVHC screening extends product qualification cycles for novel decoration chemistries. The Bavarian glassmaking corridor leverages automated production scale for mid-tier fragrance house supply agreements.
China
Mass-market promotional vial production and sampler-tier acrylic formulations concentrate in manufacturing hubs serving cost-sensitive buyers. The country's national chemical safety regulator enforces migration testing for cosmetic packaging materials. The Yangtze River Delta glassworks cluster supplies high-velocity automated filling compatibility for global beauty conglomerates.
Perfume Vials Market Competitive Landscape
Capability concentration sits with heritage glassworks commanding artisanal furnace expertise; scale advantage sits with pharmaceutical-grade manufacturers repurposing quality systems for cosmetic applications. The market structure tiers between family-owned European glassworks with generational craft credentials and mid-cap specialists with integrated decoration capabilities. Two strategic archetypes dominate: heritage furnace operators leveraging provenance documentation, and diversified packaging conglomerates with metallization-to-silk-screening vertical integration. Competitive moves center on exclusive capacity commitments with prestige beauty holding companies and M&A consolidation of distressed artisanal glassworks in Normandy and Murano.
Among French heritage operators, Verescence and Pochet Group exemplify the artisanal furnace archetype, leveraging historic glassworks credentials to sustain pricing power against mechanized alternatives. Gerresheimer occupies a position representing pharmaceutical-grade quality systems repurposed for luxury cosmetic applications, anchoring the regulatory-compliance tier. These three companies collectively illustrate how competitive positioning fragments across craft provenance, quality certification depth, and decoration technology integration.
| Leading Market Players |
|---|
| Verescence |
| Pochet Group |
| Bormioli Luigi |
| Heinz-Glas |
| Gerresheimer |
| Stoelzle Glass Group |
| Albéa |
| Vitro Packaging |
| Piramal Glass |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine freight corridor's natural gas-linked transport costs compress margins for Saint-Quentin and Murano glassworks while amplifying price spreads between artisanal crystal and mass-market soda-lime vials. EU carbon border adjustment mechanisms and France's AGEC compliance obligations force dual-tier pricing that separates heritage furnace operators from automated competitors.
Pricing Analysis
Aftermarket refill subscriptions and recurring consumable revenue now anchor lifetime value calculations for vial manufacturers. Three-tier pricing structure across premium crystal, standard borosilicate, and economy acrylic levels separates heritage provenance documentation from pharmaceutical-grade certification and promotional sampler tiers. Pricing pressure stems from pharmaceutical-grade polymer substitutes encroaching on sub-3 ml segments where weight reduction outweighs tactile premium. Promotional-tier buyers in China and mass-market assemblers exhibit highest price sensitivity, while French and Italian luxury fragrance houses demonstrate lowest elasticity for hand-manipulated limited editions.
Supply Chain Analysis
Tariff exposure between China and the United States disrupts acrylic sampler supply flows for promotional-tier buyers. France, Italy, and China anchor global vial manufacturing, with Hauts-de-France and Veneto regions sustaining artisanal furnace operations while Yangtze River Delta clusters feed mass-market production. Raw material dependencies center on high-purity silica sand from Belgium and Ukraine, boron compounds from Turkey, and cobalt colorants now restricted under ECHA REACH Annex XVII. Single-source vulnerability concentrates in Murano master glassblower labor pools. Distribution runs through prestige beauty conglomerate procurement offices, duty-free logistics operators, and direct-to-consumer replenishment platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Digital Product Passport mandates and biophotonic glass innovation are disrupting competitive positioning in fragrance containment. This regulatory-technological inflection compresses qualification timelines while fragmenting advantage across material science, data infrastructure, and craft preservation.
For Market Incumbents: Pre-empt polymer substitution threats by securing exclusive capacity commitments with prestige beauty holding companies. Acquire distressed artisanal glassworks in Normandy before private equity consolidators capture furnace operator scarcity. Invest in blockchain-verified provenance documentation to differentiate from industrial competitors under EU Ecodesign compliance.
For New Entrants and Emerging Players: Build out US state-level EPR capabilities in California and Oregon to capture first-mover advantage in mechanical recycling infrastructure. Target direct-to-consumer fragrance startups requiring sub-500 unit decoration runs with ultraviolet-cured inkjet capabilities. Position through rapid turnaround flexibility rather than scale economies.
For Investors and Strategic Acquirers: Family-owned European glassworks with generational craft credentials and pre-qualified EU Digital Product Passport systems represent the priority acquisition archetype. Long-term viability hinges on refill-compatible architecture patents and exclusive relationships with heritage fragrance houses. Watch for FDA-EU dual certification completion as inflection signal for novel decoration chemistry commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Refill-Compatible Architecture Patenting | Locks in recurring revenue through proprietary closure mechanisms with L'Oréal and Estée Lauder supply agreements. |
| Blockchain Furnace Verification | Differentiates Murano and Saint-Quentin artisanal operations from industrial competitors under EU material disclosure rules. |
| Biophotonic Glass Formulation | Captures wellness-positioned clean beauty fragrance lines with violet-tinted borosilicate light-filtering technology. |
| US State EPR Infrastructure Buildout | Secures first-mover positioning in California, Oregon, and Maine packaging stewardship compliance. |
| Digital Decoration Capability Acquisition | Enables sub-500 unit photographic-quality runs for Paris and Milan niche fragrance houses. |
Research Methodology
Operator-level perspectives from glassworks plant managers, fragrance house procurement directors, luxury brand supply chain executives, and duty-free channel operators anchored the qualitative base. Primary fieldwork combined with secondary validation from ECHA REACH regulatory filings, EU Ecodesign for Sustainable Products Regulation drafts, customs trade data for borosilicate glass imports, and SEC disclosures from packaging conglomerates. Bottom-up volume modeling triangulated against top-down beauty industry spend analysis.
Scenario-bracketing framed projections across the analysis window, with CAGRs derived from segment-level growth rate reconciliation. Modeling dimensions spanned material chemistry tiers, volumetric capacity bands, closure mechanism types, end-user sophistication levels, and regional regulatory cluster intensity. Forecast inputs incorporated EU Green Deal circular economy mandate implementation pace and US state EPR framework adoption velocity.
Sensitivities concentrate around ECHA REACH colorant restriction expansion, natural gas price volatility for furnace operations, and pharmaceutical-grade polymer barrier technology advancement. Forecasts reflect documented assumptions on regulatory timeline execution and artisanal labor pool stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.