
 Fragrance Emulsion Market | 2026-2036
Fragrance Emulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Fragrance Emulsion Market Insights
Asset-light contract manufacturing and third-party toll processing is narrowing the capital barrier for mid-tier fragrance houses to enter emulsion production. Givaudan SA leverages captive biotech capabilities to sustain high-margin specialty emulsion supply. Firmenich anchors its position through integrated fragrance creation and delivery system development. Symrise competes via regional manufacturing scale across multiple continents.
A fragrance emulsion is a thermodynamically stabilized dispersion of aromatic oils within a continuous aqueous or hydro-alcoholic phase, typically achieved through high-shear homogenization or microfluidization to achieve droplet sizes below one micron for optical clarity and shelf stability. The system functions primarily to deliver controlled fragrance release while masking alcohol odor or replacing solvent-heavy formulations in skin-contact applications. Water-based emulsions command the largest volume share within the product type dimension, though oil-based variants retain premium positioning in long-wear personal care. Within applications, personal care absorbs the majority of value as brands reformulate for alcohol reduction, while home care emulsions face margin compression from private-label competition.
REACH registration requirements in Europe, EPA VOC regulations in the United States, and China's GB standards on cosmetic safety collectively determine which emulsion chemistries gain market access and which face reformulation mandates. Compliance costs disproportionately burden smaller manufacturers lacking dedicated regulatory affairs teams. Stakeholders must monitor pending amendments to fragrance allergen disclosure rules across multiple jurisdictions, as these will force label changes and potential portfolio pruning before the forecast horizon closes.
Market Dynamics
REACH compliance deadlines and EPA VOC enforcement are compressing formulation windows for fragrance emulsion manufacturers, forcing simultaneous reformulation across multiple product lines while suppliers qualify new raw material sources.
Growth Catalysts
- Alcohol-free personal care mandates:Skin-compatible water-based emulsions replace solvent-heavy fragrances as EU cosmetic safety standards tighten disclosure requirements for sensitizing ingredients.
- China GB cosmetic safety expansion:Domestic fragrance houses in Guangdong and Zhejiang provinces scale microfluidization capacity to capture export demand from Southeast Asian cosmetic brands.
- Microencapsulation technology maturation:Controlled-release shell-core structures enable 12-hour fragrance persistence in fabric care applications previously dominated by simple oil-in-water systems.
Market Restraints
- Surfactant input cost volatility:Ethoxylated emulsifiers face price pressure from ethylene oxide supply disruptions concentrated on the US Gulf Coast.
- Specialty lipid supplier concentration:Three German chemical groups control 70% of cosmetic-grade ester oil supply, creating single-source vulnerability for mid-tier emulsion houses.
- Fragrance allergen disclosure friction:Pending EU amendments to allergen labeling rules force premature portfolio pruning before scientific consensus stabilizes.
Strategic Opportunities
- India personal care penetration:Domestic Ayurvedic cosmetic brands seek alcohol-free fragrance delivery systems compliant with CDSCO cosmetic registration pathways.
- Carbon-negative emulsion chemistry:Biotechnology-derived squalane and fermented esters qualify for EU Green Deal sustainable product procurement preferences.
- Direct-to-brand digital formulation:AI-assisted emulsion design platforms compress development cycles from 18 months to 8 weeks for indie beauty startups.
Industry Challenges
- Colloid stability expertise scarcity:Formulation chemists with combined fragrance compounding and physical chemistry training command 40% salary premiums over general cosmetic scientists.
- Multi-jurisdiction dossier compilation:Simultaneous REACH, EPA TSCA, and China NMPA registration requires dedicated regulatory affairs teams smaller manufacturers cannot staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fragrance Emulsion Market |
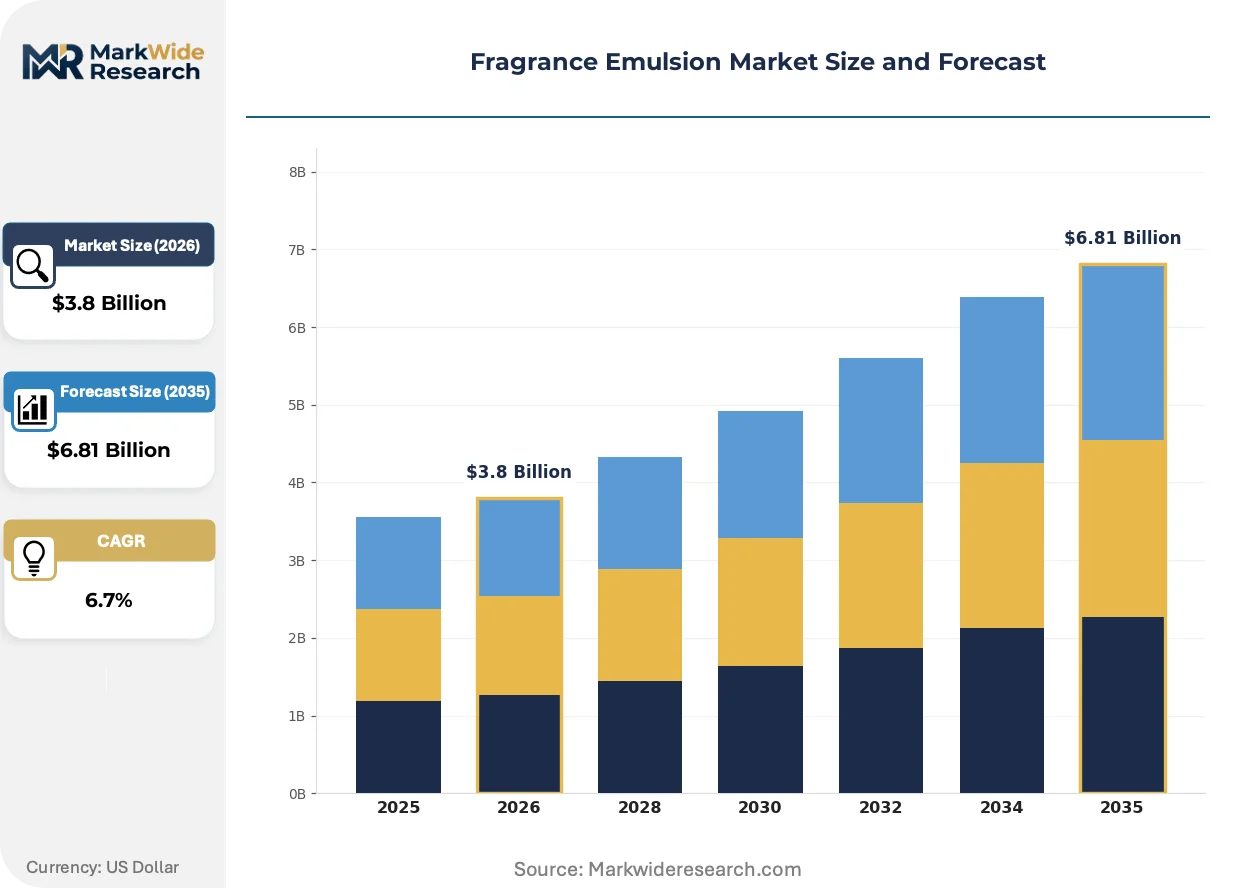
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-based, Water-based, Alcohol-based, Gel-based Application: Personal Care, Home Care, Air Fresheners, Industrial Use Form: Liquid, Cream, Spray, Stick End User: Retail Consumers, Manufacturers, Wholesalers, Distributors |
| Companies Covered | Givaudan SA, Firmenich, Symrise, International Flavors & Fragrances (IFF), Takasago International Corporation, Mane SA, Robertet SA, Sensient Technologies Corporation, ICC Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fragrance Emulsion Market Trends and Innovations
Process analytical technology and in-line droplet size monitoring are replacing offline quality control, compressing batch release timelines while tightening specification windows for optical clarity and viscosity stability.
Microfluidization equipment with real-time laser diffraction feedback is digitizing emulsion manufacturing. Premium personal care contract manufacturers in France and the United States deploy these systems to eliminate batch-to-batch variation. The technology is digitizing quality assurance workflows, reducing laboratory testing overhead by enabling continuous process verification rather than end-point sampling.
REACH authorization requirements for certain phthalate-derived fixatives are forcing substitution toward bio-based film-forming polymers. Fragrance houses must reformulate legacy emulsions before sunset dates remove key ingredients from supply. Personal care brands with European manufacturing footprints face the tightest compliance timelines and are pre-qualifying alternative chemistries two years ahead of regulatory deadlines.
Ingredient sourcing transparency now dominates procurement negotiations between personal care brands and emulsion suppliers. Third-party blockchain verification of palm-derived surfactant supply chains is replacing paper-based sustainability claims. This behavioral shift is most visible in German and Nordic cosmetic markets, where retailer sustainability scorecards determine shelf placement regardless of product performance metrics.
Fragrance Emulsion Market Segmentation
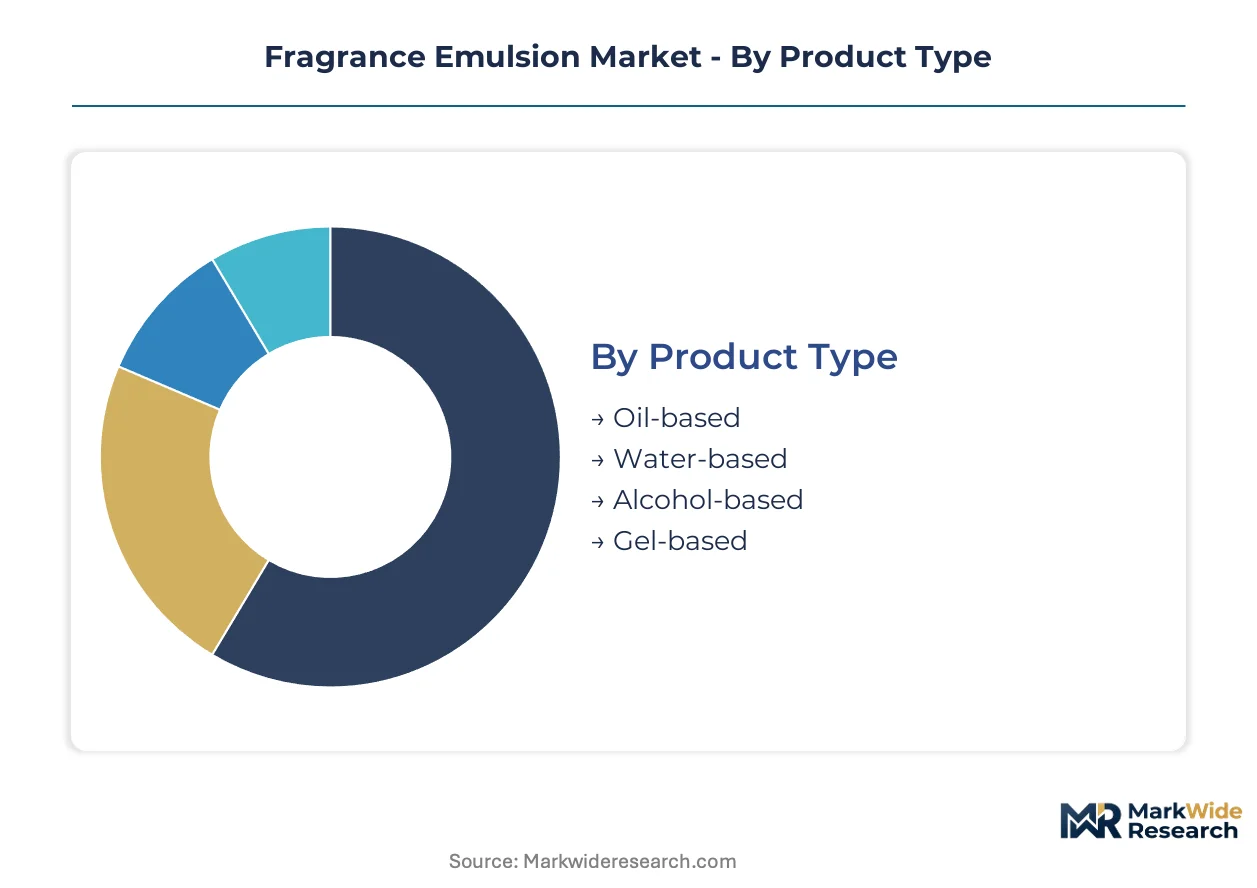
Fragrance emulsion procurement cycles vary dramatically across product chemistries and end-use applications. Cycle time differences dictate inventory strategy, R&D allocation, and supplier relationship intensity for fragrance houses and contract manufacturers alike.
Product Type:
Reformulation velocity separates segments with regulatory-driven refresh cycles from those with decade-long specification stability.
- Water-based:Dominates volume through skin-compatible, alcohol-free personal care formulations. Demand concentrates in EU cosmetic brands responding to REACH fragrance allergen disclosure mandates and alcohol reduction trends. Reformulation cycles compress to 18-24 months as regulatory windows tighten.
- Oil-based:Retains premium positioning in long-wear personal care and selective home care applications. French and Italian luxury fragrance houses specify these for extended skin adherence in high-heat climates. Specification stability extends to 5-7 years, anchoring supplier contract durations.
- Alcohol-based:Faces structural decline as VOC regulations and cosmetic safety standards displace solvent-heavy delivery systems. Remains viable in industrial applications and select air freshener formats where rapid evaporation is functional.
- Gel-based:Niche positioning in stick deodorants and targeted application formats. Korean and Japanese cosmetic brands drive incremental specification work for transparent gel clarity standards.
Water-based emulsions anchor the volume base while gel-based formats gain share at the steepest rate through format innovation in Asian cosmetic markets.
Application:
Margin structure and technical specification intensity diverge sharply between skin-contact and ambient fragrance delivery.
- Personal Care:Absorbs the majority of value as premium brands reformulate for alcohol reduction and skin microbiome compatibility. EU and US clean beauty mandates accelerate emulsion substitution for traditional perfume alcohol bases. Specification complexity peaks here with dual requirements for fragrance performance and dermatological safety.
- Home Care:Faces margin compression from private-label competition and concentrated retail buyer power. Fabric care microencapsulation commands technical premiums, while standard air freshener emulsions commoditize. Chinese and Southeast Asian manufacturing scales concentrate in this segment for export cost competitiveness.
- Air Fresheners:Volume-driven with formulation simplicity enabling rapid private-label replication. VOC compliance in California and EU markets forces incremental reformulation investment without corresponding price recovery.
- Industrial Use:Specialized odor masking for manufacturing environments and waste management. Specification stability and long-term supply contracts characterize procurement patterns.
Personal care anchors the volume base while home care microencapsulation applications expand most quickly through controlled-release technology maturation.
Form:
Manufacturing asset specificity and distribution logistics create divergent competitive economics across physical formats.
- Liquid:Standard bulk emulsion format for personal care integration and refill systems. Filling line compatibility across multiple brand owners reduces switching costs and supplier concentration.
- Cream:Higher viscosity formulations for body care and hand cream applications. Rheology specification precision demands dedicated mixing equipment and extended stability testing protocols.
- Spray:Aerosol and pump-dispersion systems requiring propellant compatibility and droplet size optimization. EPA and EU F-Gas regulations reshape propellant chemistry and equipment investment requirements.
- Stick:Solid emulsion formats for deodorant and targeted fragrance application. Format novelty commands shelf placement premiums in specialty retail channels.
Liquid formats anchor the volume base while stick formats climb the fastest through convenience positioning and travel retail expansion.
End User:
Procurement sophistication and technical dialogue intensity scale with formulation ownership and brand development capability.
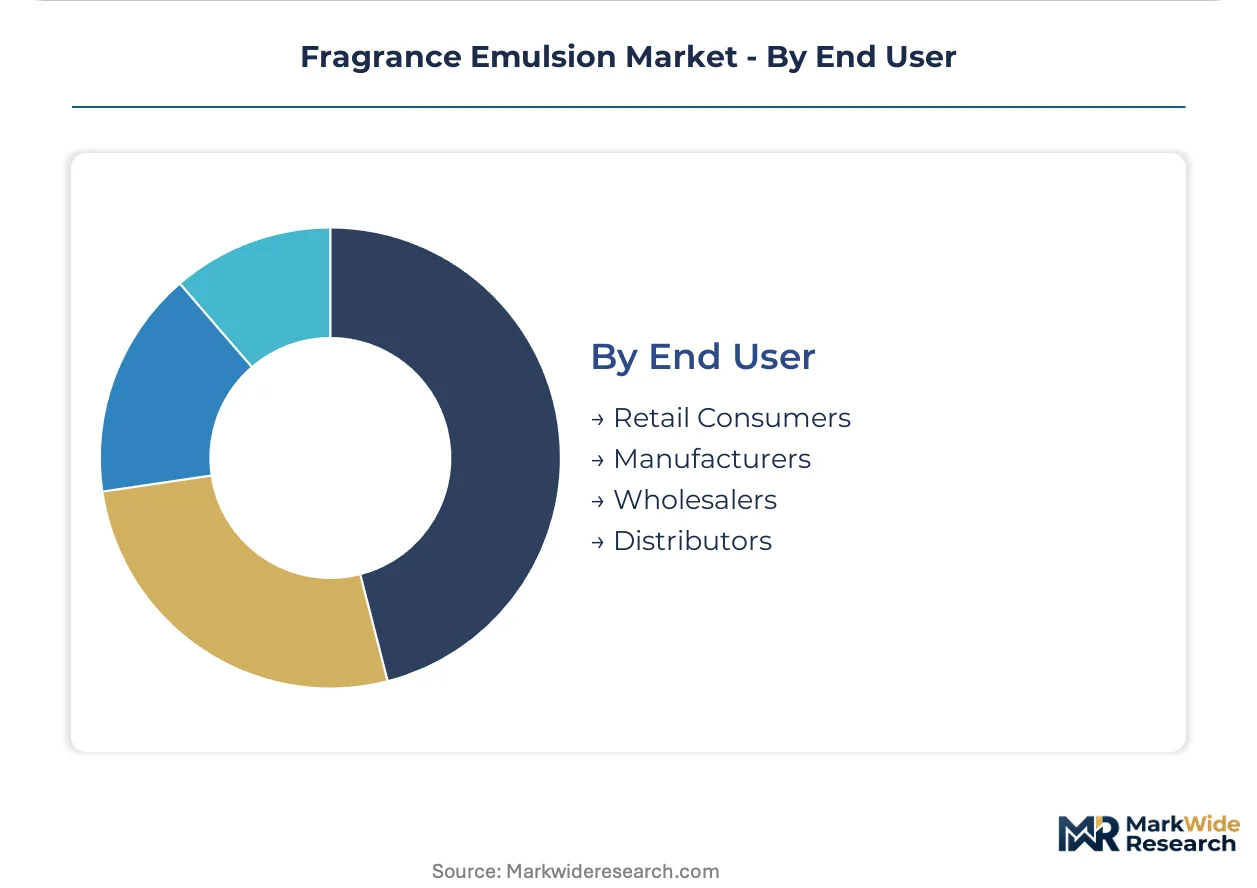
- Manufacturers:Integrated personal care and home care product companies with captive fragrance development. Direct emulsion specification, stability testing, and regulatory dossier ownership. Relationship depth with specialty chemical suppliers determines competitive position.
- Retail Consumers:Finished product purchasers with zero direct emulsion procurement. Demand signals transmit through brand owner formulation priorities and clean beauty preference shifts.
- Wholesalers:Bulk emulsion traders serving mid-tier fragrance houses without captive manufacturing. Price sensitivity and rapid supplier switching characterize relationships.
- Distributors:Regional logistics and technical service providers bridging international suppliers to local formulators. Inventory carrying and formulation advisory services differentiate competitive position.
Manufacturers anchor the volume base while distributor technical service capabilities gain share at the steepest rate as mid-tier fragrance houses outsource formulation expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France commands pricing premiums through luxury heritage positioning, while China's coastal manufacturing clusters compete on technical scale and export cost efficiency. This asymmetry shapes procurement patterns across personal care and home care supply chains. Regulatory divergence between REACH-mandated reformulation in Europe and China's expanding GB cosmetic safety standards creates parallel compliance tracks for multinational suppliers.
United States
Clean beauty mandates from California and New York Metro brands accelerate alcohol-free emulsion substitution for traditional fragrance bases. EPA VOC enforcement tightens formulation windows for aerosol and pump-dispersion systems. New Jersey and Illinois chemical manufacturing corridors host contract manufacturers deploying microfluidization equipment with real-time quality feedback.
France
Luxury fragrance houses in Paris and Grasse specify oil-based emulsions for extended skin adherence in high-heat climates. ANSM cosmetic safety guidelines enforce stringent dermatological testing protocols for skin-contact formulations. The Provence-Alpes-Côte d'Azur cluster anchors premium emulsion development through integrated fragrance creation and delivery system expertise.
Germany
Retailer sustainability scorecards in German and Nordic markets determine shelf placement regardless of performance metrics. REACH authorization requirements for phthalate-derived fixatives force substitution toward bio-based film-forming polymers. Three chemical groups in North Rhine-Westphalia and Bavaria control the majority of cosmetic-grade ester oil supply.
China
Domestic fragrance houses in Guangdong and Zhejiang provinces scale microfluidization capacity to capture export demand from Southeast Asian cosmetic brands. NMPA cosmetic registration pathways and expanding GB standards reshape supplier qualification criteria. The Yangtze River Delta and Pearl River Delta manufacturing basins concentrate technical emulsion capabilities for both local and export markets.
India
Ayurvedic cosmetic brands seek alcohol-free fragrance delivery systems compliant with CDSCO cosmetic registration pathways. BIS standards and DGFT import policies influence raw material sourcing strategies. Maharashtra and Gujarat chemical processing corridors develop contract manufacturing capacity for mid-tier fragrance houses entering emulsion production.
Fragrance Emulsion Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with captive biotech or regional manufacturing scale. The vendor base organizes around three strategic archetypes: integrated fragrance houses with captive emulsion development, specialty chemical suppliers controlling key lipid inputs, and asset-light contract manufacturers narrowing capital barriers for mid-tier entrants. Dominant competitive moves include M&A to secure biotech-derived ingredient pipelines and strategic partnerships to pre-qualify alternative chemistries ahead of regulatory sunset dates.
Within the integrated fragrance house tier, Givaudan SA and Firmenich exemplify platform dominance through combined fragrance creation and delivery system development. Symrise occupies a position anchored by regional manufacturing scale across multiple continents. These Swiss and German-origin entities represent the archetype of suppliers qualifying new raw material sources while managing simultaneous REACH, EPA, and China NMPA registration requirements.
| Leading Market Players |
|---|
| Givaudan SA |
| Firmenich |
| Symrise |
| International Flavors & Fragrances (IFF) |
| Takasago International Corporation |
| Mane SA |
| Robertet SA |
| Sensient Technologies Corporation |
| ICC Industries |
| Others |
Pricing and Supply Chain Analysis
Guangdong and Zhejiang provinces anchor fragrance emulsion manufacturing capacity expansion, with microfluidization scale-up dynamics directly compressing spot pricing for standard water-based formulations while premium oil-based variants retain configured-to-order premiums.
Pricing Analysis
Configured-to-order pricing for specialty emulsions commands spreads of 40-60% above standard catalog grades, with differentiation anchored in REACH pre-registration status and droplet size certification tiers. Cost compression in home care emulsions is intensifying because private-label replication erodes brand premiums. Indie beauty startups exhibit highest price sensitivity, while French luxury houses accept premium positioning with minimal negotiation.
Supply Chain Analysis
Upstream feedstock concentration in Germany, China, and India shapes raw material economics, with ethoxylated emulsifiers and cosmetic-grade ester oils as critical dependencies. Single-source vulnerability pervades specialty lipid supply, where three chemical groups control majority ester oil output. Distribution runs through regional distributors bridging international suppliers to mid-tier formulators lacking captive regulatory affairs teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragrance emulsion demand sits in early-cycle expansion as alcohol-free personal care mandates penetrate beyond EU regulatory origins into Asian and North American clean beauty formulations.
For Market Incumbents: Entrench position through captive biotech squalane pipelines and pre-qualification of bio-based film-forming polymers ahead of REACH sunset dates. Capacity addition in China's Yangtze River Delta manufacturing basin secures export cost competitiveness against Southeast Asian contract manufacturers. For New Entrants and Emerging Players: Establish a beachhead in India's Ayurvedic cosmetic segment, where CDSCO registration pathways favor domestic partners and alcohol-free fragrance delivery systems face underdeveloped supplier infrastructure. Direct-to-brand digital formulation platforms compress development cycles for indie beauty startups as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because simultaneous REACH, EPA, and China NMPA registration requirements create durable moats for integrated fragrance houses with dedicated compliance infrastructure. Acquisition targets should screen for colloid stability expertise scarcity, with formulation chemist retention rates as the signal to watch for operational quality inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidization Capacity Expansion | Real-time laser diffraction feedback eliminates batch-to-batch variation for premium personal care contract manufacturers. |
| Backward Integration into Biotech-Derived Squalane | Fermented ester supply secures EU Green Deal procurement preferences for carbon-negative emulsion chemistry. |
| Long-term Supply Agreement with Specialty Lipid Suppliers | Contracted ester oil volumes mitigate single-source concentration risk among German chemical groups. |
| Joint Venture for Regional Manufacturing Scale | Shared microfluidization assets in Guangdong province reduce capital barriers for mid-tier fragrance houses. |
| Regulatory Pre-Qualification Partnership | Collaborative REACH, EPA, and NMPA dossier development accelerates market access for alternative chemistries. |
Research Methodology
A standing panel of fragrance house R&D directors, contract manufacturing procurement leads, specialty chemical supplier technical sales managers, and regulatory affairs consultants provided ongoing calibration throughout the study period. Primary interview findings combined with secondary validation from ECHA REACH registration databases, EPA VOC compliance filings, China NMPA cosmetic ingredient catalogs, and customs trade flow records. Bottom-up emulsion volume estimates triangulated against top-down personal care and home care end-use market sizing.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeled by emulsion chemistry type, application end-use, physical form factor, and geographic regulatory cluster. CAGRs derived from weighted average of historical trajectory analysis and adoption curve penetration modeling. Forecast inputs incorporated microfluidization equipment deployment rates, REACH authorization sunset schedules, and clean beauty formulation substitution elasticities.
Stress conditions across ethylene oxide supply disruption severity, REACH allergen disclosure amendment timing, and China GB standard expansion pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against customs-export volume data from Guangdong and Zhejiang province manufacturing clusters is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Home Fragrance Diffusers Market
Fragrances & Perfumes
Global Fragrance Market
Fragrances & Perfumes
Saudi Arabia Perfume Market
Fragrances & Perfumes
Digital Fragrance Market
Fragrances & Perfumes
Organic Perfumes Market
Fragrances & Perfumes
Middle East Fragrances Market
Fragrances & Perfumes
UAE Perfume Market
Fragrances & Perfumes
North America Perfume Market
Fragrances & Perfumes
Wax Melts Market
Fragrances & Perfumes
Gulf Cooperation Council Fragrance and Perfumes Market
Fragrances & Perfumes
Global Perfume Market
Fragrances & Perfumes
Fragrance Diffuser Market
Fragrances & Perfumes
Smart Fragrance Box Market
Fragrances & Perfumes
Floral Water Spray Market
Fragrances & Perfumes
Natural Fragrance Market
Fragrances & Perfumes
GCC Perfume and Fragrance Market