
 Global Perfume Market | 2026-2036
Global Perfume Market Size, Share, and Industry Trends Forecast 2026-2036
Global Perfume Market Outlook
Prestige and niche fragrance tiers is reorganizing the competitive landscape as consumers trade up from mass-market alternatives. L'Oréal leverages its portfolio breadth across luxury and dermatological fragrance adjacencies to capture margin-rich segments. Chanel anchors its position through controlled distribution and in-house composition mastery at its Grasse facility. Puig differentiates via minority-stake investments in independent perfume houses that command cultural authenticity.
Perfume denotes an alcohol-based or oil-based fragrant composition containing concentrated aromatic compounds, typically at 15-40% concentration, designed for personal scent application. Industrial production centers on extraction, distillation, and maceration processes using natural essences and synthetic aroma chemicals. Eau de Parfum commands the largest value share due to higher concentration premiums and extended wear profiles. Online Retail represents the fastest-expanding distribution channel as direct-to-consumer platforms capture first-party data and reduce intermediary costs. Unisex fragrance classifications are gaining structural momentum as gender-fluid marketing reshapes product architecture.
EU REACH and the IFRA Code of Practice govern allergen disclosure and ingredient safety thresholds across European markets. The FDA regulates cosmetic labeling in the United States while China's NMPA oversees fragrance registration under updated cosmetic supervision rules. Stakeholders must monitor regulatory divergence on natural versus synthetic ingredient classifications as sustainability claims face intensifying scrutiny from ECHA and state-level consumer protection agencies.
Market Dynamics
Prestige fragrance tier expansion among millennial and Gen Z cohorts is compressing mass-market share while EU REACH allergen disclosure mandates force costly reformulation cycles across European supply chains.
Growth Catalysts
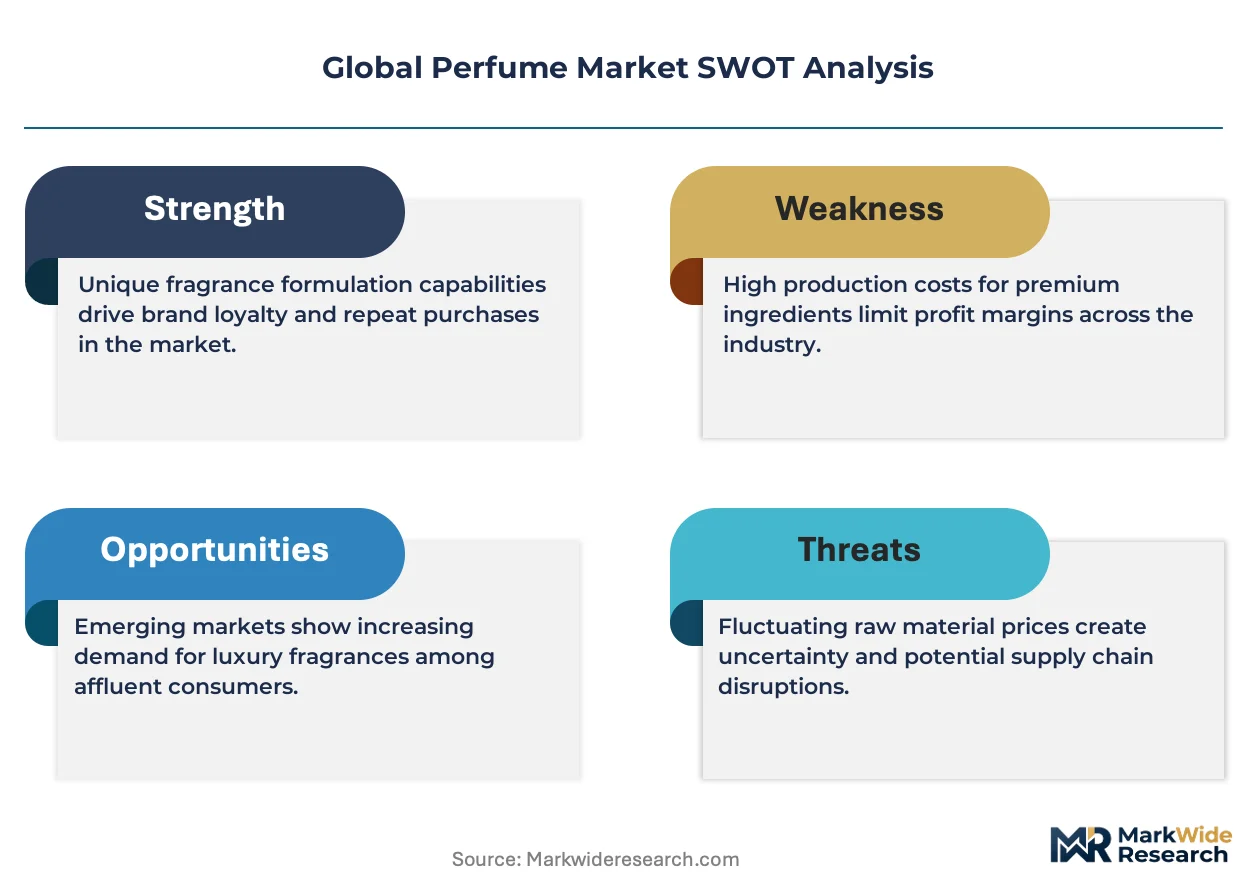
- REACH compliance investments:EU fragrance allergen labeling rules are accelerating clean-label R&D spend, creating first-mover advantages for manufacturers with advanced analytical capabilities at Grasse and Geneva facilities.
- China's cosmetic supervision updates:NMPA registration streamlining under revised rules is reducing market entry friction for imported prestige fragrances in tier-one cities.
- Synthetic biology extraction:Lab-grown musk and amber alternatives are securing supply chain resilience against natural ingredient volatility in Madagascar and Somalia sourcing corridors.
Market Restraints
- Natural essence cost volatility:Bulgarian rose otto and Indian sandalwood prices swing 40-60% seasonally, compressing gross margins for houses dependent on signature naturals.
- Grasse concentration risk:Over 60% of fine fragrance composition expertise clusters in a 50-kilometer radius of southern France, creating single-point vulnerability to climate and labor disruptions.
- Alcohol taxation regimes:Excise duties in Brazil, India, and Gulf states add 15-35% to landed costs, pricing prestige tiers out of emerging middle-class reach.
Strategic Opportunities
- Saudi Arabia luxury retail expansion:Riyadh and Jeddah fragrance consumption is outpacing global averages as Vision 2030 tourism investments create duty-free and flagship retail white space.
- Refillable packaging mandates:France's AGEC anti-waste law and similar frameworks in the Netherlands are creating regulatory tailwinds for circular business models with recurring revenue streams.
- AI-driven personalization:Machine learning scent profiling combined with direct-to-consumer platforms is enabling mass-customization at previously impossible unit economics.
Industry Challenges
- Perfumer apprenticeship gaps:Grasse-based training programs graduate fewer than 30 master perfumers annually against industry demand for 150+, forcing wage inflation and poaching cycles.
- Legacy IT integration:ERP systems at heritage houses struggle to reconcile batch-level allergen tracking required by REACH with decades-old formula databases.
- Biotech IP licensing complexity:Patent thickets around engineered yeast strains for rare molecule production are triggering multi-year negotiation delays and royalty stacking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Perfume Market |
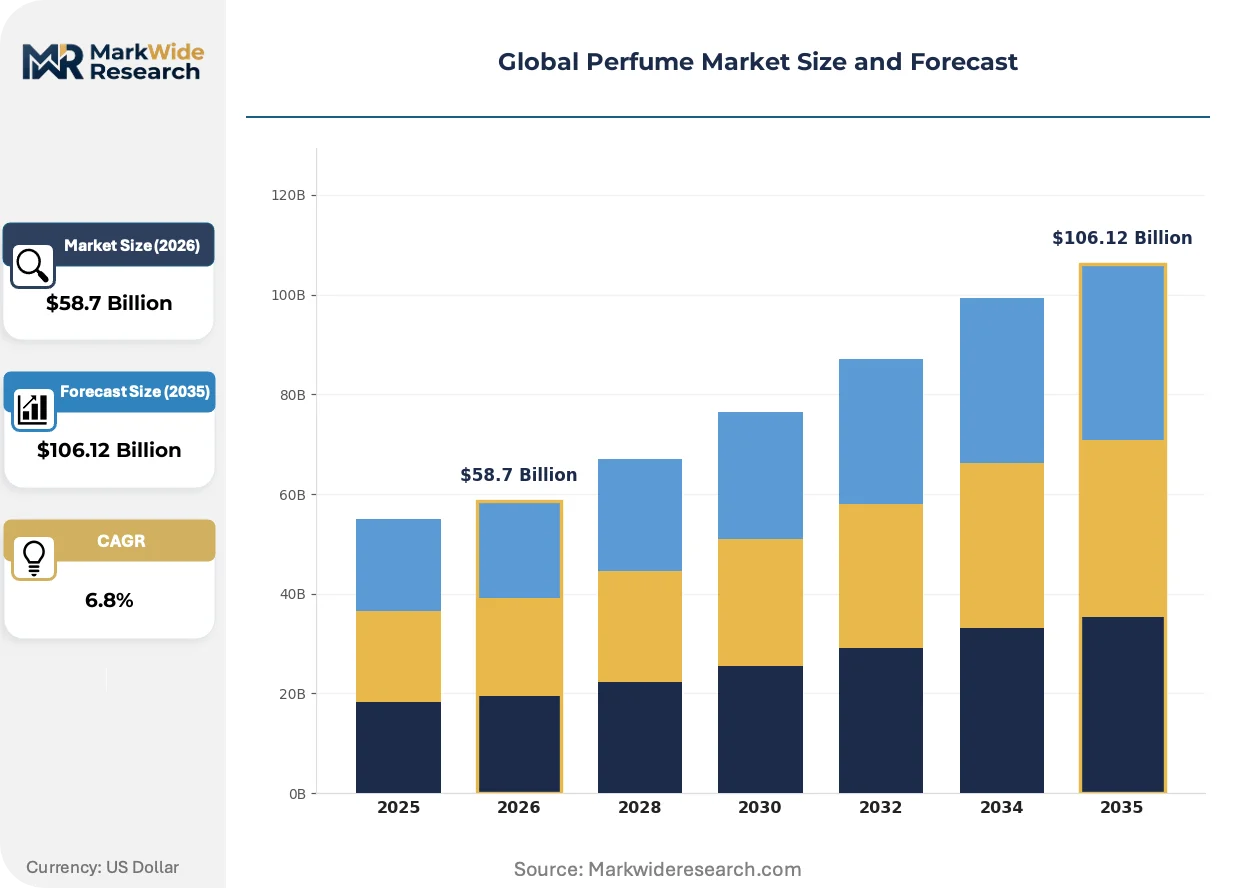
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eau de Parfum, Eau de Toilette, Eau de Cologne, Perfume Oils End User: Women, Men, Unisex, Children Distribution Channel: Online Retail, Specialty Stores, Department Stores, Duty-Free Shops Fragrance Note: Citrus, Floral, Woody, Oriental |
| Companies Covered | L'Oréal, The Estée Lauder Companies, Coty, LVMH, Chanel, Puig, Procter & Gamble, Unilever, Shiseido, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Perfume Market Strategic Shifts
Biotechnology and artificial intelligence are converging to transform fragrance creation workflows, while regulatory fragmentation on sustainability claims forces simultaneous compliance investments across multiple jurisdictions.
Enzymatic catalysis for aroma molecule synthesis is displacing traditional petrochemical routes and cold-press extraction for high-volume citrus and floral notes. Givaudan and Firmenich have scaled industrial bioreactors at their Singapore and California facilities. This displacement is compressing capital requirements for mid-tier houses while locking in supply agreements with biotech ingredient specialists.
ECHA's intensifying scrutiny of natural versus synthetic classification claims under REACH is forcing reformulation documentation at the molecular level. Manufacturers must now substantiate "natural origin" percentages through carbon-14 testing. Premium houses with in-house analytical labs in France and Switzerland are internalizing these capabilities while smaller players face third-party testing cost burdens.
Direct-to-consumer sampling subscriptions are fragmenting traditional department store discovery models. Sephora and Ulta are responding with owned-brand fragrance incubators to retain traffic. This channel rotation is most visible in the United States and United Kingdom, where online fragrance purchases reached majority share of prestige volume growth.
Global Perfume Market Segmentation
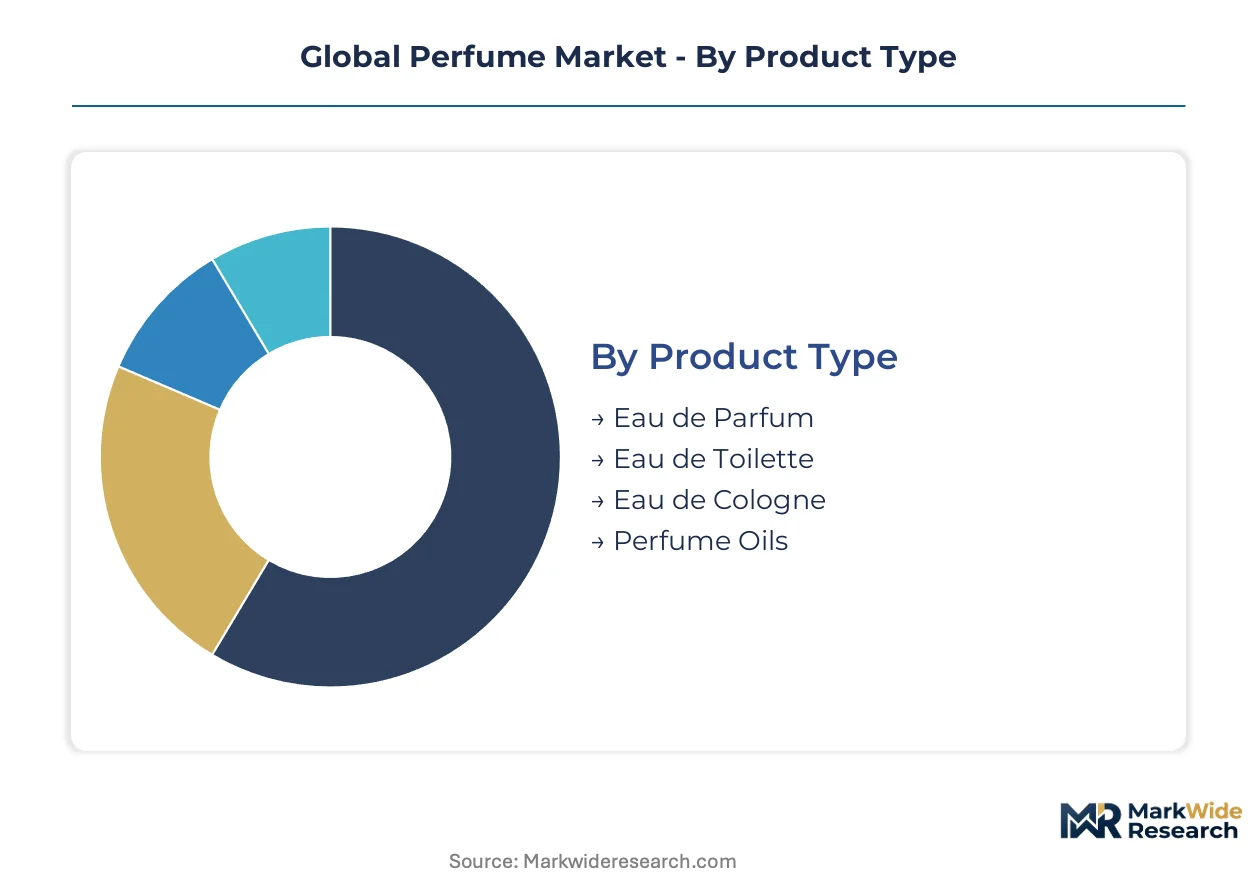
Perfume segmentation reveals how concentration tiers, gender targeting, and channel economics create distinct competitive arenas with divergent margin profiles and regulatory exposure. Understanding these fault lines clarifies where substitution threats from adjacent personal care categories are most acute.
Product Type:
Substitution pressure from solid perfumes and fragrance mists is most severe at the lower concentration tiers where price elasticity is highest and brand loyalty weakest.
- Eau de Parfum:Contains 15-20% aromatic compounds in an alcohol base, delivering 6-8 hour wear profiles that justify premium positioning. Demand concentrates in France and the United States among millennial professionals seeking signature scents with workplace-appropriate sillage, though EU REACH allergen labeling is forcing reformulation investments that compress margins for houses dependent on complex natural blends.
- Eau de Toilette:Formulated at 5-15% concentration with lighter, fresher profiles suited to warm climates and daytime application. Volume leadership sits in Germany and Japan where understated scent conventions dominate, but the segment faces acute substitution from body sprays and scented skincare as consumers trade down from alcohol-based formats.
- Eau de Cologne:Traditional 2-4% concentration citrus-forward compositions originating from Italian and German fragrance traditions. Heritage houses in Cologne and Milan anchor supply.
- Perfume Oils:Alcohol-free concentrated formats popular in Middle Eastern markets and among consumers with sensitive skin. Dubai and Jeddah retail networks drive distribution.
Eau de Parfum anchors the volume base while Perfume Oils gains share at the steepest rate.
End User:
Gender-fluid marketing is collapsing traditional binary segmentation faster in Western Europe than in Asia-Pacific, creating portfolio architecture challenges for heritage houses.
- Women:Historically the largest revenue pool with complex floral-oriental compositions and higher frequency of purchase. France and the United States remain the core demand clusters, though NMPA registration requirements in China are slowing new launch velocity for imported feminine lines.
- Unisex:Fragrances marketed without gender signifiers, typically built around woody, aromatic, or citrus profiles. Fastest-growing classification in the United Kingdom and Netherlands as retailer shelf space reallocation accelerates, with direct-to-consumer platforms capturing disproportionate trial volume through algorithmic recommendation engines.
- Men:Traditional fougère and woody categories now competing with expanded fresh-spicy and gourmand directions. Brazil and Mexico show strongest absolute growth.
- Children:Hypoallergenic, alcohol-reduced formats with strict IFRA safety thresholds. Regulatory complexity limits new entrant participation.
Women's fragrances retain the revenue base while Unisex classifications climb the fastest.
Distribution Channel:
Channel cost structures vary by a factor of three, forcing portfolio pruning as houses optimize for margin retention versus volume acquisition.
- Online Retail:Direct-to-consumer platforms and marketplace storefronts capturing first-party data for personalization. Fastest-expanding channel in the United States and China as sampling subscriptions and AI-driven scent profiling reduce purchase risk, though return rates for blind-buy transactions remain elevated versus physical trial.
- Specialty Stores:Sephora, Douglas, and regional perfumeries offering curated discovery and consultation services. France and Italy concentrate the highest productivity per square meter.
- Department Stores:Legacy channel under pressure from traffic decline in the United States and United Kingdom, though still critical for launch visibility in Japan and South Korea.
- Duty-Free Shops:Travel retail dependent on international passenger volumes, with Dubai, Singapore, and Paris CDG anchoring global throughput.
Specialty Stores anchor the volume base while Online Retail expands most quickly.
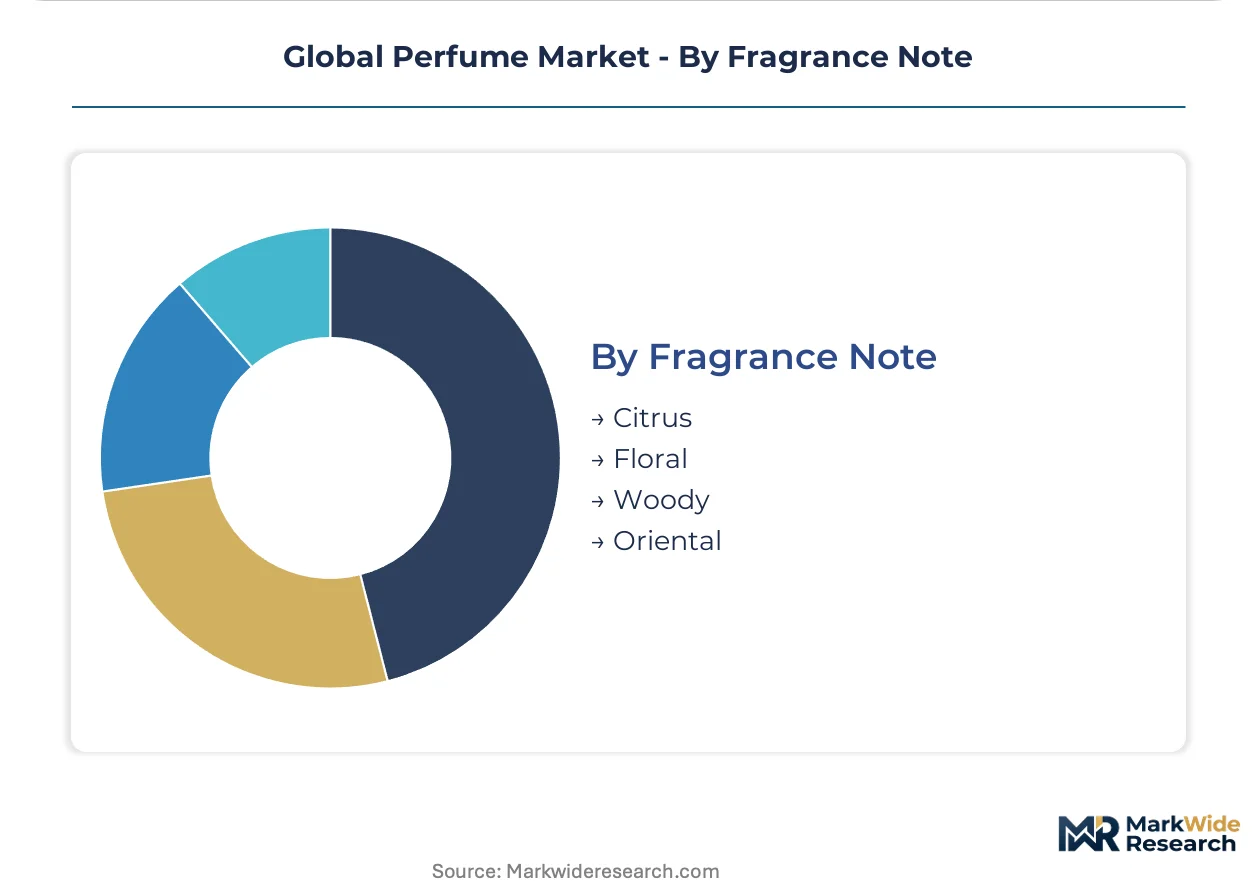
Fragrance Note:
Raw material cost volatility creates divergent margin trajectories across olfactory families, with naturals-dependent categories facing the steepest procurement headwinds.
- Floral:Rose, jasmine, and orange blossom compositions requiring high natural essence loadings. Bulgarian rose otto and Grasse jasmine supply constraints are forcing houses toward synthetic biotechnology alternatives.
- Woody:Sandalwood, cedar, and vetiver bases with strong masculine and unisex orientation. Indian sandalwood plantation maturation is easing historical scarcity.
- Citrus:Bergamot, lemon, and neroli top notes with high volatility and lower ingredient costs. Calabrian bergamot harvest fluctuations create seasonal pricing pressure.
- Oriental:Amber, vanilla, and spice accords with heavy base note concentration and extended dry-down profiles. Strongest demand in Middle Eastern markets.
Floral anchors the volume base while Woody gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fragrance buyers in India and Brazil exhibit acute price sensitivity to alcohol taxation, while consumers in France and the United States absorb premium tier markups with minimal volume elasticity. This demand-elasticity contrast shapes divergent market entry strategies across geographies.
France
Grasse-based composition houses anchor global fine fragrance supply, with millennial professionals in Paris driving prestige adoption. REACH allergen disclosure mandates from ECHA force molecular-level reformulation documentation. The Provence-Alpes-Côte d'Azur cluster concentrates over 60% of master perfumer expertise within a 50-kilometer radius.
United States
Direct-to-consumer platforms capture majority share of prestige volume growth as AI-driven scent profiling reduces purchase risk. FDA cosmetic labeling rules govern alcohol-based fragrance claims. New York and Los Angeles retail networks anchor specialty store productivity per square meter.
China
Tier-one city consumers accelerate prestige fragrance trial through online sampling subscriptions. NMPA registration streamlining under revised cosmetic supervision rules reduces import friction. Shanghai and Beijing duty-free zones anchor travel retail throughput for international houses.
Saudi Arabia
Riyadh and Jeddah fragrance consumption outpaces global averages as Vision 2030 tourism investments create retail white space. SFDA oversight governs product registration and ingredient safety. The Eastern Province concentrates oud and amber supply chain relationships with Somali and Indian sourcing corridors.
Germany
Understated scent conventions favor Eau de Toilette formats among professional demographics. EU Green Deal sustainability frameworks accelerate refillable packaging compliance investments. The North Rhine-Westphalia logistics hub anchors distribution efficiency for Central European markets.
Global Perfume Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Consolidation among luxury conglomerates with captive composition capabilities contrasts with fragmentation in mass-market private label supply. Three archetypes dominate: vertically integrated luxury houses with Grasse facilities, diversified beauty conglomerates spanning prestige and mass tiers, and independent perfume houses commanding cultural authenticity through minority-stake partnerships. Dominant competitive moves include strategic investments in biotech ingredient specialists and controlled distribution expansion to capture first-party consumer data.
Within the diversified conglomerate tier, L'Oréal and The Estée Lauder Companies exemplify portfolio breadth across luxury and dermatological fragrance adjacencies. Chanel occupies a position as a vertically integrated archetype with in-house composition mastery. Puig represents the partnership-driven model through minority-stake investments in independent houses.
| Leading Market Players |
|---|
| L'Oréal |
| The Estée Lauder Companies |
| Coty |
| LVMH |
| Chanel |
| Puig |
| Procter & Gamble |
| Unilever |
| Shiseido |
| Others |
Value Chain & Pricing Dynamics
EU REACH allergen disclosure mandates gate both supply qualification and price differentiation simultaneously, forcing manufacturers to internalize analytical capabilities at Grasse and Geneva facilities while premium houses extract margin premiums from compliant clean-label portfolios.
Pricing Analysis
Refill and subscription revenue tiers now anchor lifetime value calculations as houses pivot from transactional bottle sales to recurring replenishment models. Three-tier pricing structure across prestige, masstige, and private label levels reflects concentration gradients and brand heritage premiums. Cost compression in natural-dependent tiers is intensifying because Bulgarian rose otto and Indian sandalwood procurement swings compress gross margins. Mass-market buyers in Brazil and India exhibit acute price sensitivity to alcohol taxation, while prestige consumers in France and the United States absorb markups with minimal volume elasticity.
Supply Chain Analysis
Strategic stockpiling of rare naturals dominates inventory strategy as houses buffer against Madagascan vanilla and Somali frankincense harvest volatility. Manufacturing gravity centers on France, Switzerland, and Singapore where Givaudan and Firmenich operate industrial bioreactors. Raw material dependencies include Grasse jasmine, Calabrian bergamot, and lab-grown musk alternatives. Single-source vulnerability concentrates in the 50-kilometer Grasse composition cluster. Distribution runs through duty-free zones at Dubai, Singapore, and Paris CDG alongside direct-to-consumer platforms capturing first-party data.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment, where REACH compliance investments and master perfumer apprenticeship pipelines create switching costs that protect incumbent positions.
For Market Incumbents: Secure captive composition capabilities through backward integration into Grasse training pipelines and analytical laboratories. Fortify channel control via direct-to-consumer platform investments that capture first-party scent preference data. Synthetic biology substitution threatens signature natural-dependent portfolios; accelerate clean-label R&D spend to outpace reformulation cycles forced by ECHA carbon-14 testing mandates.
For New Entrants and Emerging Players: NMPA fast-track registration under China's revised cosmetic supervision rules opens tier-one city white space for imported prestige lines. Unisex fragrance classifications in the United Kingdom and Netherlands offer the most penetrable segment as retailer shelf space reallocation accelerates. Deploy AI-driven scent profiling on direct-to-consumer platforms to reduce trial friction and build algorithmic recommendation moats.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across biotechnology-enabled aroma molecule production as enzymatic catalysis displaces traditional extraction. Long-term viability favors houses with in-house analytical capabilities and biotech ingredient partnerships over natural-dependent heritage brands. Monitor patent thickets around engineered yeast strains for rare molecule production as the signal to watch for royalty stacking risk and negotiation delays. Revision becomes warranted when biotech IP licensing complexity crosses thresholds that freeze supply agreements.
| Strategic Initiative | Industry Significance |
|---|---|
| Refillable Packaging Infrastructure | France's AGEC law and Dutch frameworks create regulatory tailwinds for circular revenue models. |
| Biotech Ingredient Partnership | Givaudan and Firmenich Singapore facilities anchor supply resilience against natural volatility. |
| Direct-to-Consumer Platform Launch | AI-driven scent profiling reduces purchase risk while capturing first-party preference data. |
| Master Perfumer Apprenticeship Pipeline | Grasse programs graduate fewer than 30 annually against industry demand for 150-plus. |
| Saudi Arabia Flagship Expansion | Vision 2030 tourism investments create duty-free and retail white space in Riyadh and Jeddah. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with master perfumers at Grasse composition houses, regulatory affairs leads navigating REACH and NMPA frameworks, specialty retail category buyers at Sephora and Douglas, and procurement directors managing natural essence sourcing corridors. Secondary validation drew from ECHA allergen disclosure databases, NMPA cosmetic registration filings, customs trade data on essential oil imports, and SEC 10-K disclosures from listed beauty conglomerates. Bottom-up volume modeling triangulated against top-down macroeconomic consumption patterns.
Across the analysis window, the quantitative framework modeled segmentation dimensions including concentration tier, gender classification, distribution channel, and fragrance note family. CAGRs were derived from regression analysis against historical prestige adoption curves and millennial consumption elasticity. Forecast inputs incorporated REACH reformulation cost trajectories and synthetic biology scale-up curves at Singapore and California bioreactor facilities.
Decision-makers should treat outputs as directional under assumptions of stable alcohol taxation regimes and uninterrupted Grasse labor supply; material deviation would warrant model refresh. Specific risk factors include climate disruption in Provence-Alpes-Côte d'Azur, NMPA registration delays, and biotech patent litigation. Revision becomes warranted when natural essence cost volatility crosses thresholds that force mass-market exit.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
UAE Perfume Market
Fragrances & Perfumes
Gulf Cooperation Council Fragrance and Perfumes Market
Fragrances & Perfumes
Digital Perfume Market
Fragrances & Perfumes
Global Fragrances and Perfumes Market
Fragrances & Perfumes
Kuwait Perfume Market
Fragrances & Perfumes
Cosmetic and Fragrance Retail Chain Market
Fragrances & Perfumes
Middle East Fragrances Market
Fragrances & Perfumes
Scented Oil Market
Fragrances & Perfumes
Global Scented Candle Market
Fragrances & Perfumes
Global Fragrance Market
Fragrances & Perfumes
Fragrance Emulsion Market
Fragrances & Perfumes
Clean Perfume Market
Fragrances & Perfumes
Natural Fragrance Market
Fragrances & Perfumes
Global Luxury Perfumes Market
Fragrances & Perfumes
Mini Refillable Perfume Bottles Market
Fragrances & Perfumes
Gourmand Fragrance Market