
 Wax Melts Market | 2026-2036
Wax Melts Market Size, Share, and Industry Trends Forecast 2026-2036
Wax Melts Market Analytics
Asset-light licensing and contract manufacturing is rewriting competitive entry barriers for new wax melt brands. Scentsy, Inc. leverages a direct-selling network that minimizes fixed retail costs while sustaining high-margin fragrance customization. Yankee Candle Company anchors mass-market shelf presence through wholesale partnerships with mass merchandisers. Bridgewater Candle Company differentiates via cause-linked branding tied to hunger-relief donations, occupying a values-driven niche.
Wax melts are fragranced solid wax pieces, typically composed of paraffin, soy, or coconut wax blended with essential or synthetic oils at concentrations between 6% and 12% fragrance load, designed for gradual scent release via electric or tealight warmers without combustion. The product type dimension shows highly fragrant and organic variants capturing margin pools as consumers trade up from basic unscented offerings. Clamshell packaging dominates shelf-ready formats, though artisanal cubes and tarts command premium positioning in specialty and craft shop channels where handmade provenance justifies higher price points.
The U.S. Consumer Product Safety Commission monitors warming device electrical safety, while the EPA regulates volatile organic compound emissions from fragranced consumer products, and the EU REACH framework mandates full fragrance allergen disclosure across member states. These overlapping standards elevate compliance costs for synthetic fragrance formulations while creating market access advantages for brands with certified clean-ingredient supply chains. Stakeholders must monitor evolving state-level fragrance ingredient bans and warming device efficiency standards as the next wave of regulatory differentiation.
Market Dynamics
EU REACH fragrance allergen disclosure mandates are compressing synthetic formulation margins while accelerating natural wax base substitution across manufacturing footprints.
Growth Catalysts
- Millennial and Gen Z household penetration:Younger demographics are abandoning open-flame candles for electric warmer compatibility, expanding addressable household counts in suburban and urban rental markets.
- REACH compliance as brand differentiation:Transparent ingredient labeling requirements under EU chemical disclosure frameworks reward early-adopter brands with retail access advantages in member state markets.
- Soy and coconut wax processing advances:Improved natural wax pour temperatures and scent throw consistency are closing performance gaps with paraffin bases in high-fragrance-load applications.
Market Restraints
- Petroleum feedstock volatility:Paraffin wax pricing tracks crude oil futures, exposing cost structures to energy commodity swings without hedge coverage at mid-tier manufacturer scale.
- Electrical warmer safety certification delays:U.S. Consumer Product Safety Commission testing protocols for warming devices create 4-6 month product launch timelines that compress seasonal selling windows.
- Essential oil supply concentration:Lavender, eucalyptus, and citrus oil sourcing clusters in Bulgaria, Spain, and Brazil create geographic concentration risk for natural fragrance positioning.
Strategic Opportunities
- Direct-to-consumer subscription retention:Auto-replenishment models for scent refills lock in recurring revenue with lower customer acquisition costs than retail channel dependence.
- Cause-linked value propositions:Hunger-relief and reforestation donation tie-ins command 15-25% price premiums in specialty retail and gift shop channels where purchase justification extends beyond functional scent.
- Artisanal craft channel expansion:Handmade wax melt provenance justifies elevated pricing in farmers' markets and boutique consignment arrangements outside mass-merchandiser margin compression.
Industry Challenges
- Fragrance chemist talent scarcity:Formulation expertise bridging natural essential oil behavior with synthetic consistency commands premium compensation in tight labor markets.
- Clamshell packaging sustainability transitions:PET to rPET or molded fiber substitutions require capital equipment retooling without immediate consumer willingness-to-pay recovery.
- Cross-border allergen labeling complexity:Divergent state-level fragrance ingredient disclosure bills in California, New York, and Washington create patchwork compliance costs for national distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wax Melts Market |
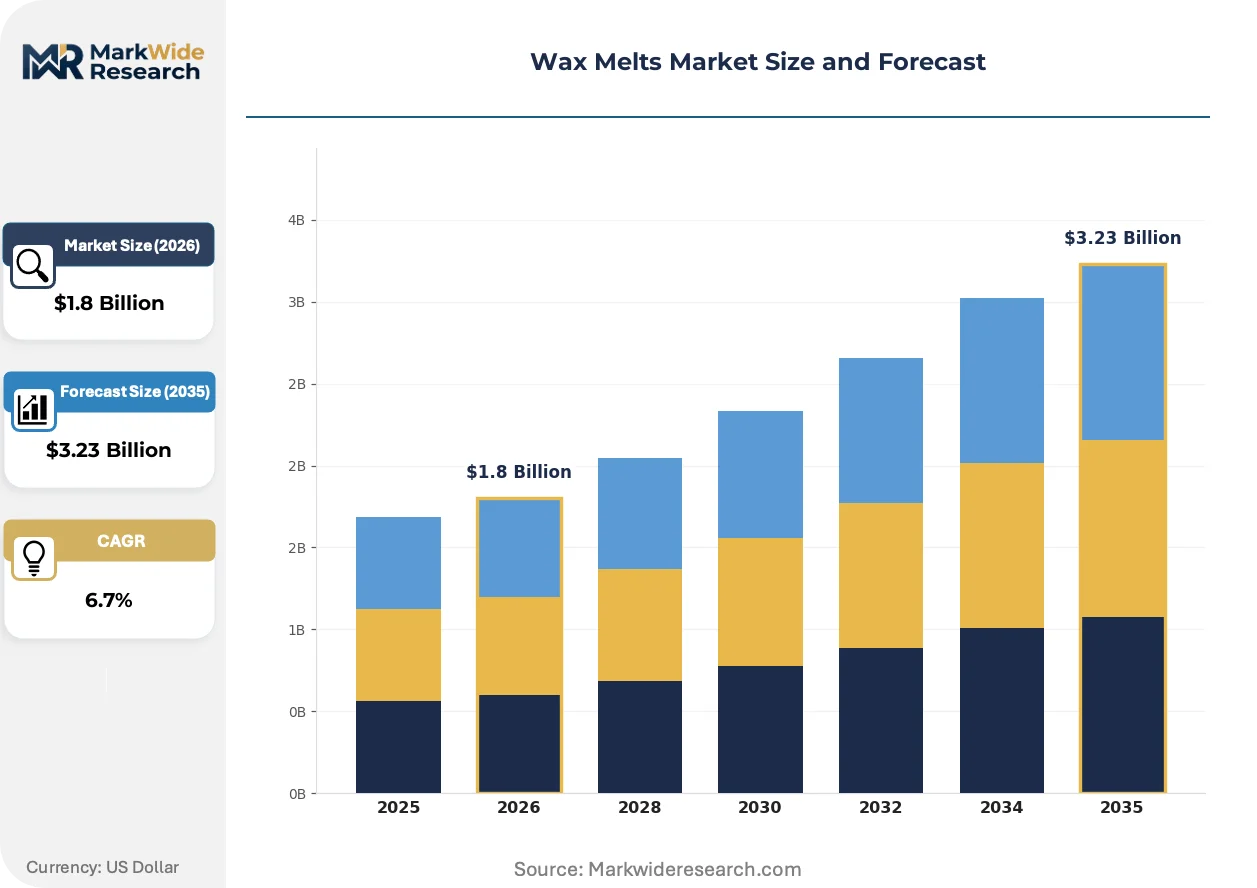
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Highly Fragrant, Unscented, Colorful, Organic Form: Clamshells, Cubes, Tarts, Chips Distribution Channel: Online Retail, Specialty Stores, Mass Merchandisers, Craft Shops End User: Households, Spa Centers, Retailers, Gift Shops |
| Companies Covered | Yankee Candle Company, Scentsy, Inc., S. C. Johnson & Son, Inc., Candle Warmers Etc., NEST Fragrances, Colonial Candle, East Coast Candle Co., Bramble Bay Candle Co., Bridgewater Candle Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wax Melts Market Evolving Landscape
Formulation chemistry, regulatory transparency mandates, and channel disintermediation are simultaneously compressing legacy manufacturing models while opening white space for agile entrants.
Smart warmer technology with Bluetooth-enabled scent intensity scheduling and usage tracking is rendering obsolete manual tealight and dial-control warming devices. Early adoption concentrates in connected-home enthusiasts and gift recipients seeking programmable ambiance. The shift is compressing margins for basic electric warmer imports while elevating firmware and app development as core competencies.
EPA volatile organic compound emission guidelines for fragranced consumer products are tightening permissible thresholds for synthetic fragrance load concentrations. Manufacturers are responding with reformulation investments and third-party emissions testing protocols. Natural wax base products with lower VOC profiles capture disproportionate shelf placement in environmentally positioned retail banners.
Subscription-based scent curation services displace single-transaction retail purchasing among fragrance-committed households. Specialty retailers and direct-selling networks are pivoting toward membership models with exclusive scent releases and loyalty pricing. The United States exhibits the deepest penetration of this model, with monthly box services and auto-replenishment portals capturing recurring wallet share from episodic brick-and-mortar visits.
Wax Melts Market Segmentation
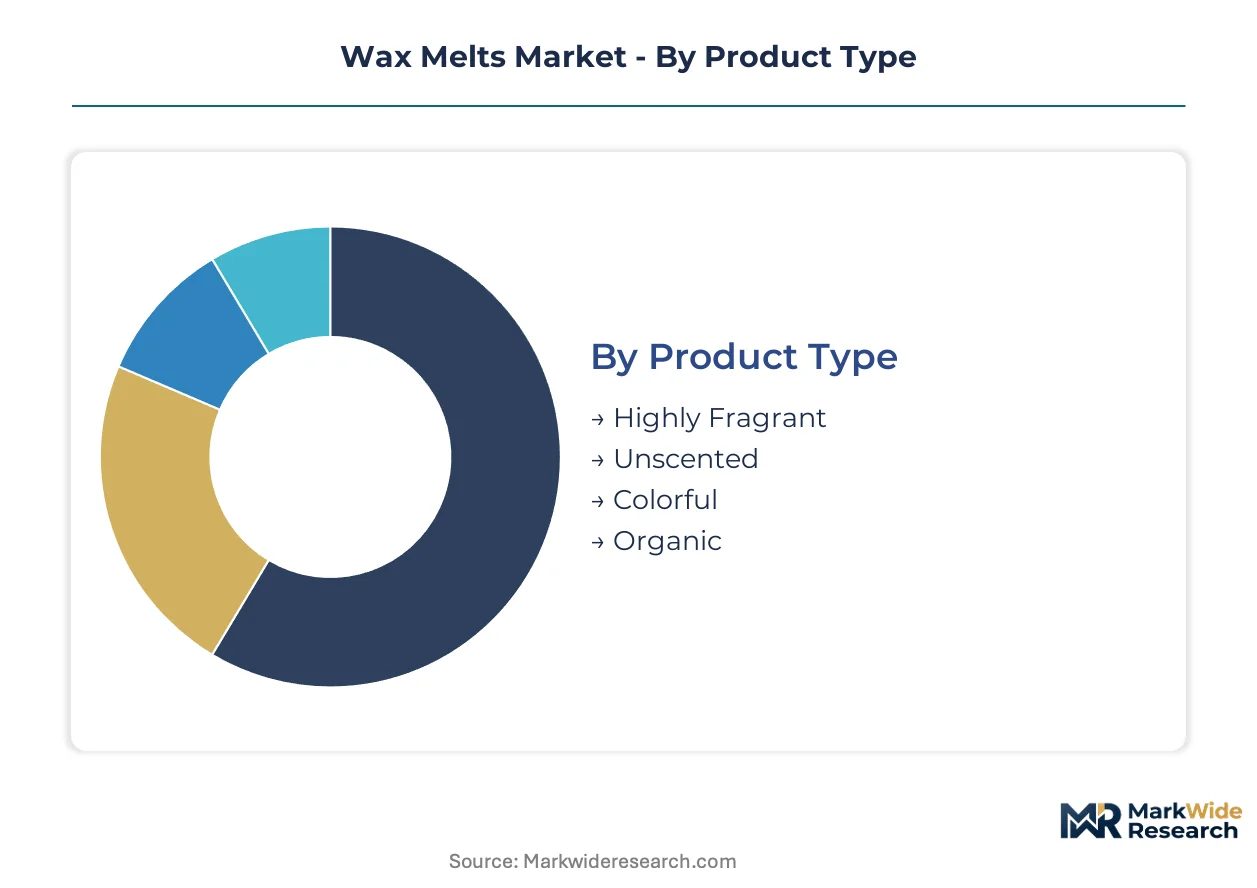
Wax melt manufacturers configure production lines and inventory buffers around distinct segment profiles. Fragrance load tolerance and warming device compatibility vary sharply across product types and forms, dictating formulation chemistry and packaging investments.
Product Type:
After-sales intensity diverges sharply across fragrance positioning, with highly fragrant variants requiring consumer education on optimal warming temperatures and organic lines demanding supply chain traceability documentation.
- Highly Fragrant:These formulations carry 10-12% fragrance oil concentration, pushing the upper limits of soy and coconut wax retention capacity. Demand concentrates in U.S. suburban households seeking candle alternatives with stronger scent throw. EPA volatile organic compound thresholds constrain synthetic formulation options.
- Organic:Certified organic wax melts use beeswax or certified organic soy with essential oil-only fragrance systems. European markets, particularly Germany and France, exhibit concentrated demand under EU REACH allergen disclosure mandates. Supply chain certification costs elevate price positioning 30-40% above conventional alternatives.
- Unscented:Pure wax bases without fragrance additives serve DIY consumers and candle-making hobbyists blending custom scents.
- Colorful:Pigmented wax melts incorporate cosmetic-grade dyes for visual appeal in gift and seasonal applications.
Highly fragrant variants hold the largest share; momentum sits with organic positioning as regulatory transparency rewards certified clean-ingredient supply chains.
Form:
Manufacturing cost tiers separate clamshell formats from artisanal alternatives, with capital equipment requirements and labor intensity driving margin structure divergence.
- Clamshells:Thermoformed PET packaging dominates mass-market shelf presence with standardized 2.5-3 ounce six-cell configurations. U.S. big-box retailers mandate this format for planogram compliance. Sustainability transitions to rPET or molded fiber create capital retooling pressures without immediate price recovery.
- Cubes:Hand-poured cube formats command premium positioning in specialty retail channels where handmade provenance justifies elevated pricing. Farmers' market vendors and boutique consignment arrangements favor this form for differentiation against mass-market clamshells.
- Tarts:Traditional tart shapes target heritage candle consumers familiar with vintage warming accessories.
- Chips:Irregular chip formats enable fragrance blending customization for enthusiast segments.
Clamshells dominate volume; cubes are expanding most quickly through artisanal channel penetration.
Distribution Channel:
Customer acquisition economics vary threefold across channels, with subscription retention rates and seasonal purchase patterns dictating working capital requirements.
- Online Retail:Direct-to-consumer platforms and marketplace listings capture auto-replenishment models with lower customer acquisition costs than retail dependence. U.S. penetration runs deepest here, with monthly box services displacing episodic brick-and-mortar visits.
- Specialty Stores:Curated fragrance boutiques and home décor specialists stock premium and cause-linked brands. Gift shop channels reward hunger-relief and reforestation donation tie-ins with 15-25% price premiums.
- Mass Merchandisers:Walmart and Target shelf placement demands clamshell standardization and wholesale margin compression.
- Craft Shops:Hobby retailers serve DIY segments with unscented bases and fragrance oil accessories.
Mass merchandisers move the most units; specialty stores deliver the steepest expansion trajectory through values-driven premium positioning.
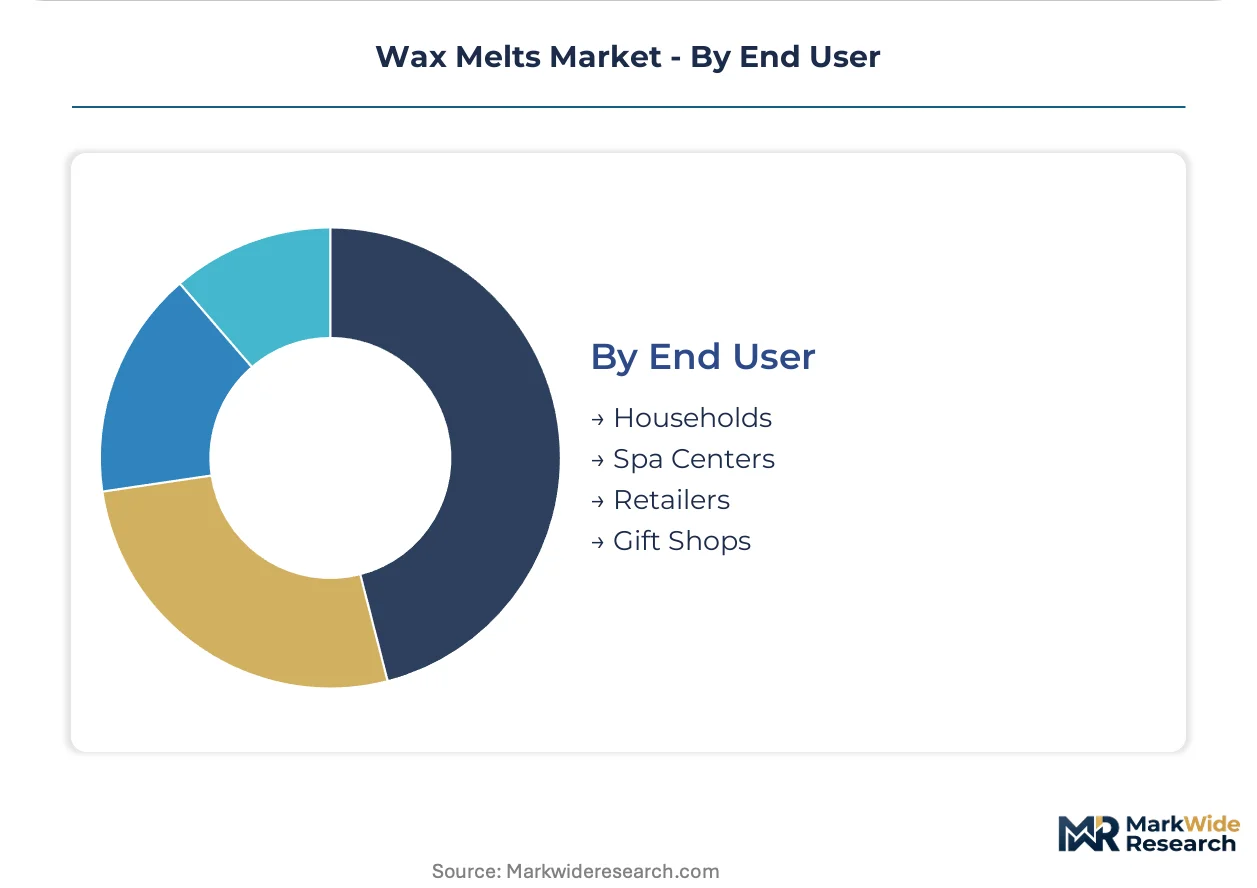
End User:
Application maturity separates household consumption from commercial deployment, with usage frequency and scent rotation preferences driving product configuration.
- Households:Millennial and Gen Z rental households favor electric warmer compatibility over open-flame candles, expanding addressable counts in urban and suburban markets. Subscription retention models lock in recurring revenue with exclusive scent releases.
- Spa Centers:Wellness facilities demand low-VOC, essential oil-only formulations for treatment room ambiance. EU REACH compliance creates procurement screening criteria for European spa chains.
- Retailers:Reseller channels require private-label and bulk configurations with margin structures supporting markup.
- Gift Shops:Seasonal and occasion-based purchasing concentrates in boutique retail with premium packaging requirements.
Households represent the established revenue base; spa centers are gaining share fastest through wellness sector fragrance positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH fragrance allergen disclosure mandates are compressing synthetic formulation margins while accelerating natural wax base substitution across manufacturing footprints. The United States anchors direct-to-consumer subscription penetration. Germany and France concentrate organic certification demand.
United States
Millennial and Gen Z rental households favor electric warmer compatibility over open-flame candles, expanding addressable counts in urban and suburban markets. The EPA regulates volatile organic compound emissions from fragranced consumer products, tightening permissible thresholds for synthetic fragrance load concentrations. Subscription-based scent curation services in the United States capture recurring wallet share from episodic brick-and-mortar visits through auto-replenishment models.
Germany
Certified organic wax melts command concentrated demand under EU REACH allergen disclosure mandates, with consumers trading up for transparent ingredient labeling. The ECHA framework mandates full fragrance allergen disclosure across member states, elevating compliance costs for synthetic formulations. Berlin and Hamburg host specialty retailers stocking premium and cause-linked brands with hunger-relief donation tie-ins.
France
Wellness facilities in Paris and Lyon demand low-VOC, essential oil-only formulations for treatment room ambiance, driving spa center procurement screening criteria. ANSM oversees cosmetic-grade dye safety in pigmented wax melts for gift and seasonal applications. Provence-Alpes-Côte d'Azur clusters lavender oil sourcing for natural fragrance positioning, though geographic concentration risk persists.
United Kingdom
Heritage candle consumers familiar with vintage warming accessories sustain demand for traditional tart shapes in London and Southeast England. The UK's national chemical regulator enforces alignment with EU REACH disclosure standards post-Brexit, maintaining transparency requirements. Midlands manufacturing footprints specialize in clamshell thermoforming for mass-market shelf presence.
Canada
Health Canada monitors fragranced consumer product safety, creating parallel compliance pathways for cross-border distribution from U.S. manufacturers. Ontario and Quebec concentrate specialty retail expansion for artisanal cube formats commanding premium positioning. Pacific Northwest climate patterns favor electric warmer adoption over open-flame alternatives in Vancouver and Seattle metro spillover demand.
Wax Melts Market Competitive Landscape
On the supply side, the industry is structured around three distinct competitive tiers. Direct-selling networks minimize fixed retail costs while sustaining high-margin fragrance customization. Mass-market wholesale partnerships anchor shelf presence through standardized clamshell formats. Cause-linked branding occupies values-driven niches with donation tie-ins commanding price premiums. Dominant competitive moves include subscription retention model deployment and artisanal craft channel expansion.
Within the direct-selling archetype, Scentsy, Inc. exemplifies asset-light network structures that bypass traditional retail overhead. Yankee Candle Company anchors mass-market positioning through wholesale partnerships with mass merchandisers. Bridgewater Candle Company occupies the values-driven tier, with cause-linked branding tied to hunger-relief donations differentiating specialty retail presence.
| Leading Market Players |
|---|
| Yankee Candle Company |
| Scentsy, Inc. |
| S. C. Johnson & Son, Inc. |
| Candle Warmers Etc. |
| NEST Fragrances |
| Colonial Candle |
| East Coast Candle Co. |
| Bramble Bay Candle Co. |
| Bridgewater Candle Company |
| Others |
Value Network & Pricing Analysis
Overcapacity in Southeast Asian soy wax processing facilities is compressing supplier margins while forcing mid-tier manufacturers toward paraffin blending to preserve pricing posture. This utilization dynamic simultaneously elevates natural wax premiums in European markets and accelerates contract manufacturing consolidation among asset-light brand owners.
Pricing Analysis
Certification level creates the primary spread between mass-market and premium positioning, with EU REACH-compliant organic variants commanding 30-40% elevation above conventional clamshell formats. Three-tier pricing structure across premium organic, standard blended, and economy paraffin levels segments buyer archetypes, with subscription-based households showing lowest price sensitivity and mass-merchandiser wholesale accounts demanding maximum compression. Cost compression in synthetic fragrance formulations is intensifying because EPA volatile organic compound thresholds constrain high-load paraffin alternatives. Spa centers and cause-linked specialty retailers represent the least price-sensitive procurement segments.
Supply Chain Analysis
Contract manufacturing concentration rests with mid-sized U.S. Midwest processors and Bulgarian essential oil distillers holding seasonal lavender and rose capacity. Raw material sourcing draws from Malaysian palm derivatives, Brazilian citrus terpenes, and domestic petroleum refineries for paraffin feedstock. Single-source vulnerability concentrates in Bulgarian lavender oil clusters, where climate volatility and agricultural labor shortages threaten fragrance consistency. Distribution runs through direct-selling networks, specialty retail consignment, and mass-merchandiser wholesale with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as the core defensive moat, with EU REACH compliance costs and EPA emissions thresholds creating asymmetric barriers for unqualified entrants.
For Market Incumbents: Build switching-cost moats through auto-replenishment subscription lock-in and exclusive scent release calendars. Deepen backward integration into certified organic soy supply to defend against essential oil price volatility and emerging clean-ingredient challengers. Prioritize firmware development for Bluetooth-enabled warmers to compress basic electric import margins.
For New Entrants and Emerging Players: Pursue artisanal craft channel expansion with hand-poured cube formats in underserved Canadian and UK boutique markets. Target spa center procurement with low-VOC essential oil-only formulations, where EU REACH screening criteria favor transparent supply chains. Deploy farmers' market consignment as the primary go-to-market angle to bypass mass-merchandiser margin compression.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across direct-selling network infrastructure as asset-light licensing models displace fixed retail footprints. Viability over the medium-term horizon hinges on subscription retention economics and regulatory compliance scalability. Monitor state-level fragrance ingredient disclosure bills in California, New York, and Washington as the inflection signal for compliance cost acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Retention Model Deployment | Auto-replenishment locks recurring revenue with lower acquisition costs than retail dependence. |
| EU REACH Compliance Certification | Transparent ingredient labeling secures retail access advantages in member state markets. |
| Artisanal Craft Channel Expansion | Hand-poured provenance justifies premium pricing outside mass-merchandiser margin compression. |
| Smart Warmer Technology Integration | Bluetooth-enabled scheduling elevates firmware development as core competency against basic imports. |
| Cause-Linked Brand Repositioning | Hunger-relief donation tie-ins command 15-25% price premiums in specialty gift shop channels. |
Research Methodology
Cross-validation between primary interviews with fragrance chemists, contract manufacturing procurement leads, and specialty retail buyers anchors the qualitative findings. Secondary validation draws from EPA emissions filings, EU ECHA allergen disclosure registries, and customs trade data for soy and paraffin wax imports. Bottom-up triangulation across product type, form, and distribution channel dimensions converges with top-down macroeconomic calibration.
Calibration against historical CAGRs and elasticity assumptions shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include fragrance positioning, packaging format, distribution channel, and end-user application. CAGRs were derived from demand elasticity modeling and input cost trajectory analysis, with essential oil supply concentration and warmer device safety certification timelines as industry-specific forecast inputs.
Sensitivities concentrate around petroleum feedstock volatility, state-level fragrance disclosure legislation, and essential oil harvest yields. Forecasts reflect documented assumptions on regulatory enforcement intensity and consumer willingness-to-pay for certified organic positioning. Quarterly review of EPA emissions threshold revisions and EU REACH enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Smart Fragrance Box Market
Fragrances & Perfumes
Scented Oil Market
Fragrances & Perfumes
Fragrance Oil Market
Fragrances & Perfumes
Fragrance Product Market
Fragrances & Perfumes
Gulf Cooperation Council Fragrance and Perfumes Market
Fragrances & Perfumes
GCC Perfume and Fragrance Market
Fragrances & Perfumes
Organic Perfumes Market
Fragrances & Perfumes
Kuwait Perfume Market
Fragrances & Perfumes
Middle East Fragrances Market
Fragrances & Perfumes
Perfume Vials Market
Fragrances & Perfumes
Global Scented Candle Market
Fragrances & Perfumes
Digital Perfume Market
Fragrances & Perfumes
Mini Refillable Perfume Bottles Market
Fragrances & Perfumes
Global Perfume Market
Fragrances & Perfumes
Saudi Arabia Perfume Market
Fragrances & Perfumes
Digital Scent Market