
 North America Nematicides Market | 2026-2036
North America Nematicides Market Size, Share, and Industry Trends Forecast 2026-2036
North America Nematicides Market Analytics
EPA registration under FIFRA is redrawing competitive boundaries for nematicide suppliers. Bayer AG leverages its biologicals pipeline to sustain positions in soil-applied segments. Corteva Agriscience anchors its portfolio through seed-treatment nematicide platforms. FMC Corporation differentiates via proprietary delivery technologies for liquid formulations.
Nematicides comprise chemical and biological agents engineered to suppress plant-parasitic nematode populations, typically formulated as granular matrices or liquid suspensions with specified active ingredient concentrations between 10% and 50% w/w. These products protect root architecture and yield integrity across agricultural systems. Biological nematicides derived from microbial fermentation occupy expanding margin pools as residue-sensitive export crops drive substitution from synthetic chemistry. Application through drip irrigation in greenhouse environments commands premium positioning due to precision delivery requirements and reduced operator exposure profiles.
EPA registration timelines under FIFRA, state-level Department of Agriculture permitting in California and Florida, and Mexico's COFEPRIS agricultural chemical standards collectively determine product availability and label claims across the tri-national market. Compliance costs favor scaled registrants with dedicated regulatory affairs infrastructure. Stakeholders must monitor biopesticide pathway harmonization between the EPA's Biopesticides and Pollution Prevention Division and Health Canada's Pest Management Regulatory Agency to anticipate cross-border product mobility.
Market Dynamics
EPA's organophosphate re-registration requirements are forcing accelerated portfolio transitions toward biological actives and seed-treatment delivery systems across North American nematicide suppliers.
Growth Catalysts
- Biological substitution momentum:Export-oriented specialty crop operations in California's Central Valley are replacing synthetic chemistry with microbial fermentation-derived nematicides to meet residue thresholds in European and Asian destination markets.
- Protected agriculture expansion:Mexico's greenhouse vegetable sector around Querétaro and Sinaloa is scaling precision drip application infrastructure that pairs naturally with liquid biological nematicide formulations.
- Regulatory pathway clarity:Health Canada's PMRA and the EPA's Biopesticides and Pollution Prevention Division are harmonizing biopesticide registration standards, reducing duplicative trials for cross-border product submissions.
Market Restraints
- Active ingredient supply concentration:Fermentation capacity for Purpureocillium lilacinum and Bacillus firmus strains concentrates with a limited set of North American contract manufacturing organizations.
- Application equipment retrofit costs:Granular nematicide applicators in Midwest corn-soy systems require capital expenditure for liquid biological compatibility, slowing grower transition timelines.
- Shelf-life and storage constraints:Live microbial formulations demand cold-chain integrity that stretches distribution infrastructure in Florida's subtropical storage environments.
Strategic Opportunities
- Underpenetrated Mexican open-field row crops:Sinaloa's tomato and pepper operations outside protected structures represent conversion potential from untreated acres to biological nematicide programs.
- Seed-treatment convergence:Biological nematicide coatings combined with fungicide and insecticide stacks are creating bundled premium offerings for Midwest corn seed distributors.
- State-level incentive alignment:California Department of Pesticide Regulation's sustainable pest management roadmap is channeling cost-share funding toward reduced-risk nematicide adoption in almond and grape vineyards.
Industry Challenges
- Field efficacy validation capacity:Nematology expertise for region-specific population monitoring and product performance assessment remains concentrated with university extension services in Florida and California.
- Multi-year residue study requirements:EPA's data call-ins for soil metabolite profiles extend registration timelines and consume regulatory affairs bandwidth at smaller biologicals developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Nematicides Market |
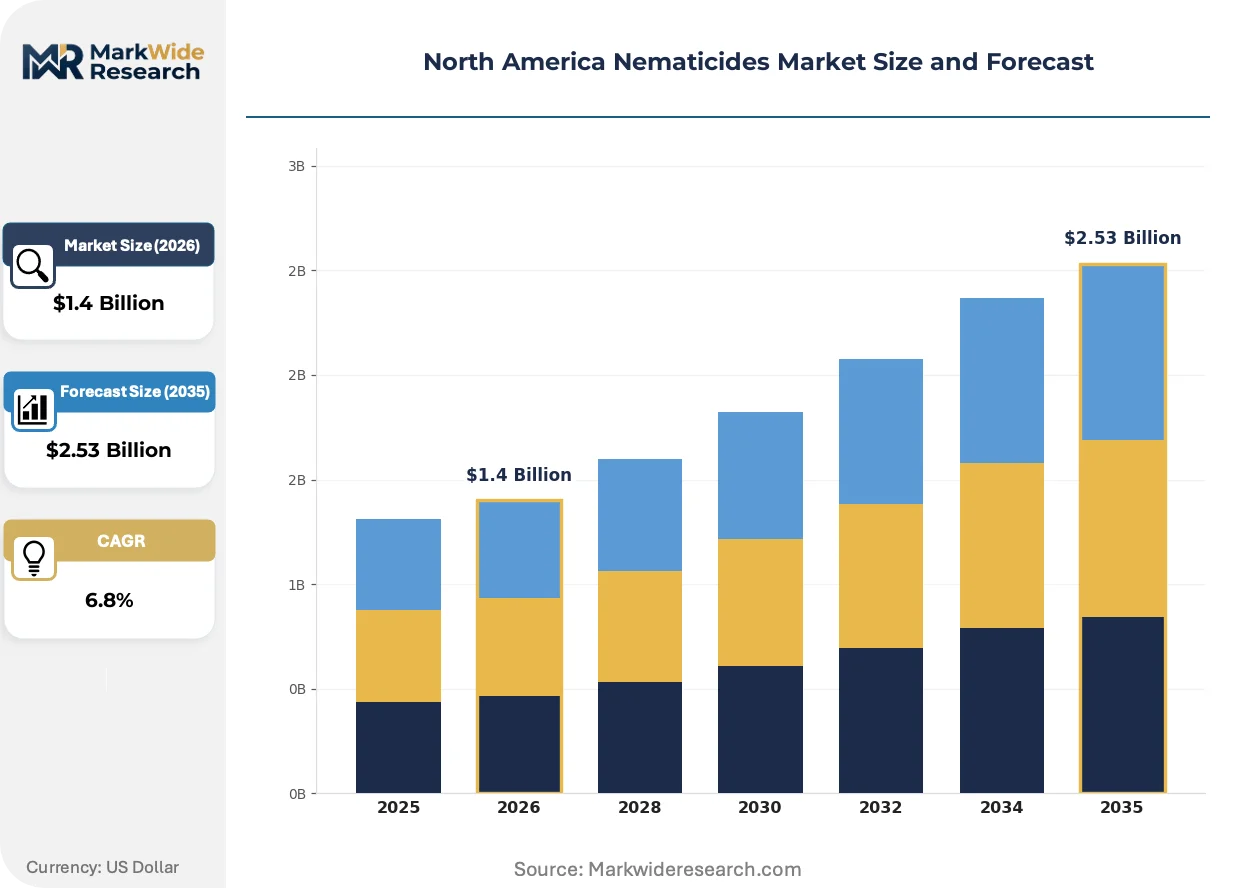
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical, Biological, Granular, Liquid Application: Agricultural Fields, Greenhouses, Turf, Ornamentals End User: Farmers, Agricultural Cooperatives, Research Institutions, Garden Centers Pest Type: Nematodes, Insects, Weeds, Fungi |
| Companies Covered | FMC Corporation, Corteva Agriscience, Bayer AG, Syngenta AG, BASF SE, American Vanguard Corporation, UPL Limited, Marrone Bio Innovations, Certis USA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Nematicides Market Evolving Landscape
Formulation chemistry and delivery precision are converging to reshape competitive positioning in soil-applied crop protection, with biological actives commanding expanded development pipelines.
Microencapsulation technologies for Pasteuria spore formulations are displacing conventional granular matrices in high-value permanent crop segments. California almond and Florida citrus operations are adopting these shelf-stable alternatives at accelerated procurement cycles. The shift is compressing market space for older organophosphate chemistries while elevating margin capture for suppliers with proprietary encapsulation IP.
EPA's revised ecological risk assessment frameworks for soil invertebrates are tightening label restrictions on synthetic nematicide application windows. The regulatory consequence is reduced flexibility for Midwest corn growers in timing soil-incorporated treatments. Seed-treatment biological alternatives are capturing displaced volume as growers seek pre-plant certainty without seasonal application constraints.
Direct purchasing from biologicals manufacturers is bypassing traditional agronomic retail channels in Mexico's protected vegetable sector. Large greenhouse operations in Querétaro are establishing technical service relationships with registrants rather than distributor intermediaries. This disintermediation is most visible in tomato and cucumber production clusters where precision irrigation integration requires specialized application engineering support.
North America Nematicides Market Segmentation
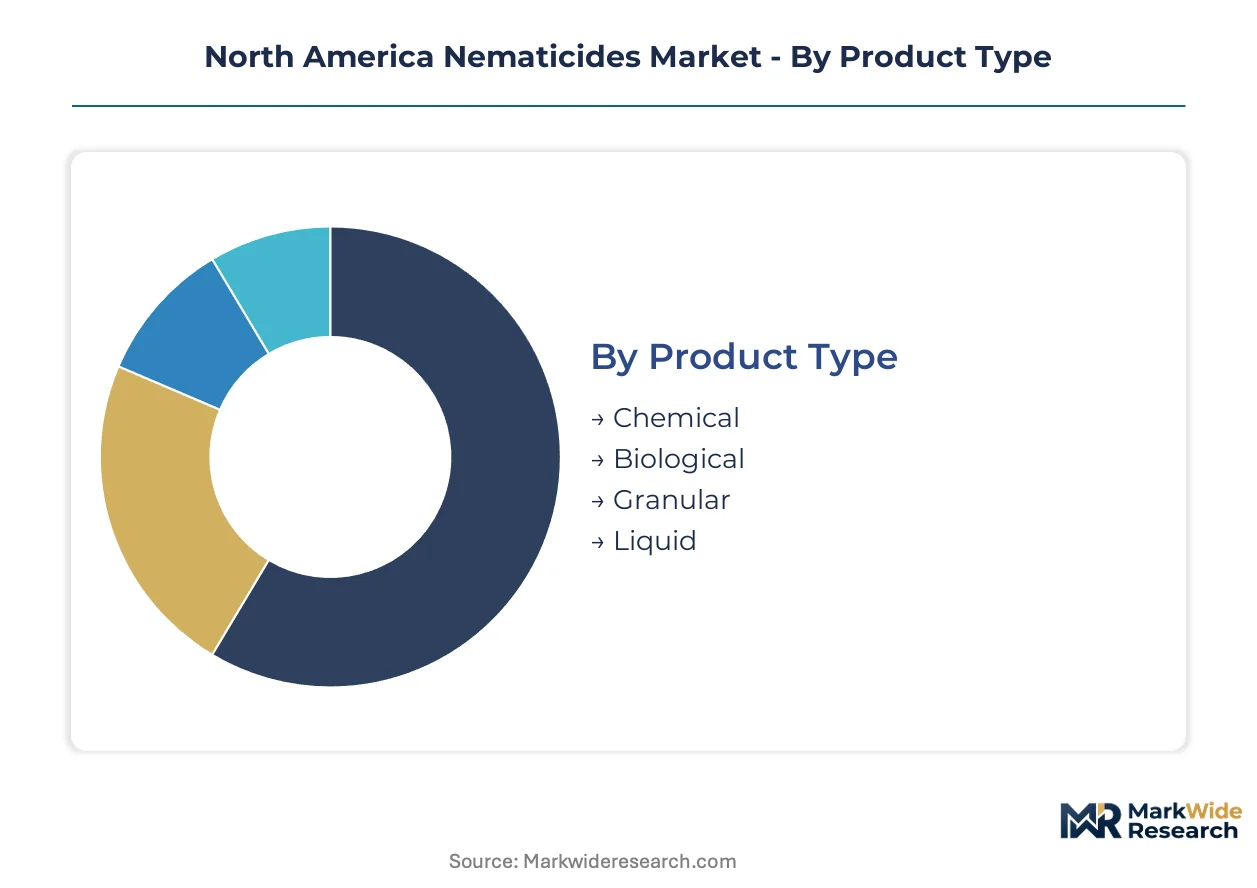
Segmentation in nematicides reflects divergent technical requirements across soil systems, protected environments, and regulatory jurisdictions. Product form and application setting determine margin capture more than volume throughput in this specialized crop protection category.
Product Type:
Margin pools concentrate in fermentation-derived biologicals where proprietary strain libraries create defendable positions, while chemical actives face compressed returns from generic competition and regulatory sunset pressures.
- Chemical:Synthetic organophosphate and carbamate chemistries deliver rapid nematode mortality through cholinesterase inhibition. Midwest corn-soy rotations in Iowa and Illinois sustain residual demand despite EPA re-registration pressures, though label restrictions are narrowing application windows and elevating compliance costs for growers.
- Biological:Microbial fermentation products derived from Purpureocillium lilacinum, Bacillus firmus, and Pasteuria species parasitize nematode eggs and juveniles without residue accumulation. California almond and strawberry operations are converting acreage fastest to meet European MRL thresholds for export-bound fruit.
- Granular:Clay-based carriers impregnated with active ingredients enable soil-incorporated application through standard planting equipment. Compatibility with existing Midwest applicator fleets sustains relevance in transitional markets where liquid biological retrofit costs deter immediate conversion.
- Liquid:Suspension concentrates and emulsifiable concentrates integrate with precision drip irrigation systems in Mexico's protected vegetable sector. Querétaro greenhouse operations specify liquid biological formulations for fertigation compatibility and reduced operator exposure profiles.
Chemical nematicides hold installed capacity across millions of Midwest corn acres. Biological formulations are rotating up the share rankings in California specialty crops and Mexican protected agriculture.
Application:
Volume concentration diverges sharply between open-field row crops with price-sensitive procurement and protected environments where precision delivery commands formulation premiums.
- Agricultural Fields:Broadcast or banded soil applications protect extensive row-crop systems including corn, soybean, and cotton across the US Midwest and Delta regions. Equipment standardization and seasonal labor windows constrain adoption of application-intensive biological alternatives despite regulatory pressure on synthetic chemistry.
- Greenhouses:Enclosed production environments in Mexico's Querétaro and Sinaloa corridors enable closed-loop irrigation systems that pair with liquid biological nematicides. Controlled conditions reduce environmental variability that complicates microbial efficacy in open-field settings.
- Turf:Golf course and sports field maintenance programs in Florida and Arizona deploy nematicides against Belonolaimus longicaudatus and Meloidogyne species. Aesthetic performance requirements and high renovation costs justify premium pricing for rapid-acting chemistries alongside biological rotation programs.
- Ornamentals:Nursery stock and floriculture operations in California's Central Coast and Florida's Lake Alfred district require nematode suppression for root-ball integrity. Phytosanitary certification for interstate shipment elevates treatment documentation requirements above commodity crop standards.
Agricultural fields dominate volume throughput. Greenhouse applications are climbing the fastest as Mexico's protected vegetable sector scales precision infrastructure.
End User:
Procurement authority fragments across direct grower purchases, cooperative aggregation, and institutional channels with divergent technical service expectations.
- Farmers:Individual growers in California's Central Valley and Florida's citrus belt select nematicides based on crop-specific nematology extension recommendations. Direct relationships with biologicals manufacturers are displacing traditional retail channels in large specialty crop operations.
- Agricultural Cooperatives:Member-owned supply organizations across the Midwest aggregate purchasing volume and distribute granular nematicides through seasonal input programs. Cooperative agronomists influence product selection through customized fertility and pest management recommendations.
- Research Institutions:University extension services in Florida and California maintain nematology laboratories that validate regional product performance and inform regulatory comment periods. Field trial partnerships with registrants generate data supporting label expansion claims.
- Garden Centers:Retail channels serve homeowner ornamental and vegetable garden segments with consumer-packaged biological nematicides. Shelf-space competition from generalist fertilizers and multi-purpose pest controls limits category visibility.
Farmers retain direct procurement authority in specialty crop districts. Agricultural cooperatives are rotating up the share rankings in Midwest row-crop consolidation.
Pest Type:
Product development pipelines concentrate on nematode-specific actives, though combination formulations address multi-pest pressure in integrated management systems.
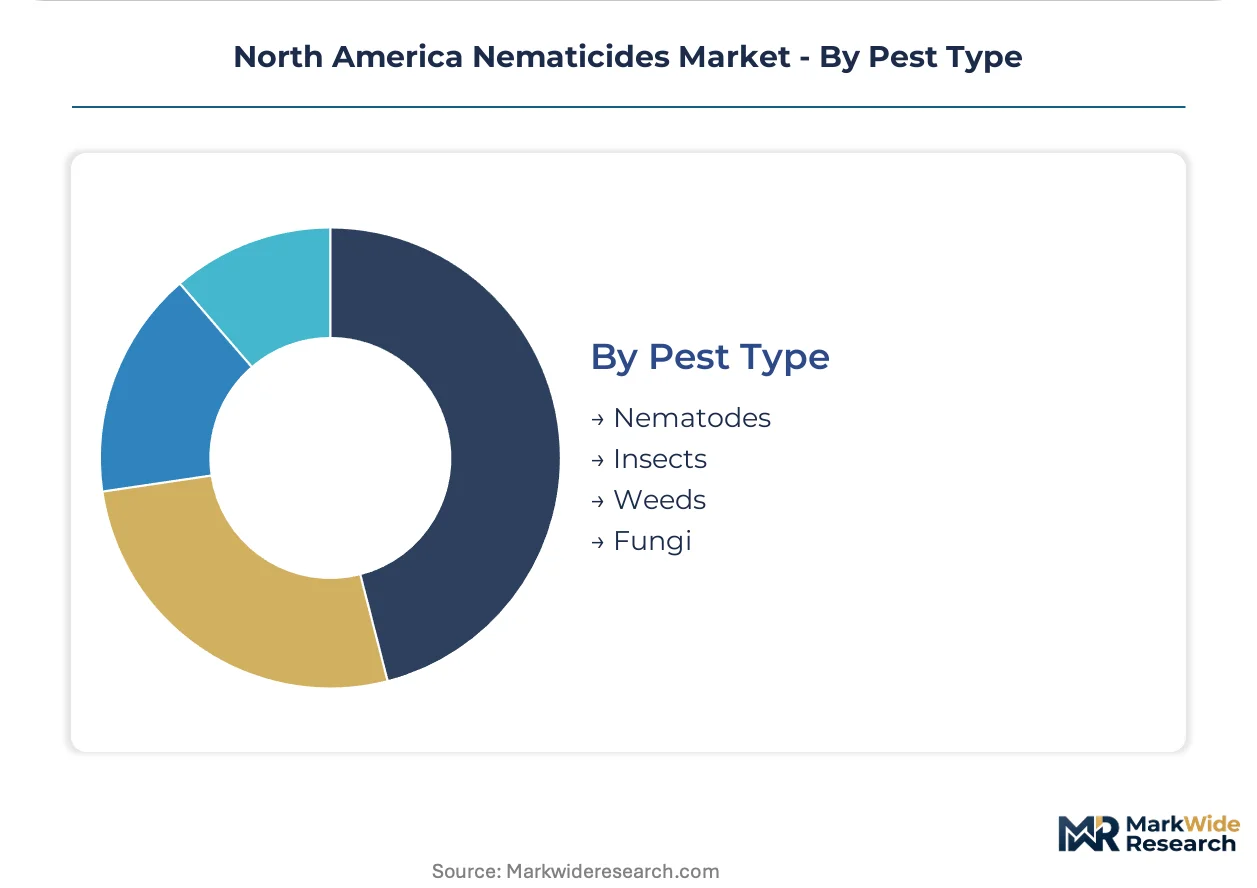
- Nematodes:Plant-parasitic roundworms including Meloidogyne, Heterodera, and Pratylenchus species infest root systems and depress yields in virtually all North American cropping systems. Dedicated nematicide labels target this pest class with specialized delivery modes distinct from foliar-applied chemistries.
- Insects:Soil-dwelling insect pests including corn rootworm and wireworm overlap with nematodes in damage symptoms and treatment timing. Combination seed-treatment products stack nematicide and insecticide actives to address joint pressure in single application passes.
- Weeds:Herbicide-resistant weed management programs occasionally incorporate soil-applied products with incidental nematode suppression claims. This cross-functional positioning expands addressable market though dilutes technical differentiation.
- Fungi:Soil-borne fungal pathogens including Fusarium and Pythium species co-infect nematode-damaged root systems. Biological nematicides with secondary fungistatic properties capture bundled positioning in integrated disease management protocols.
Nematode-specific actives hold installed capacity across professional agriculture. Fungi-targeting biologicals are rotating up the share rankings as multi-functional fermentation products gain formulation sophistication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Department of Pesticide Regulation cost-share programs are accelerating biological nematicide adoption across specialty crop districts. Mexico's COFEPRIS streamlined registration pathways for biopesticides are drawing cross-border manufacturing investment. Health Canada's PMRA harmonization with EPA biopesticide standards is reducing duplicative field trial requirements for registrants.
United States
Midwest corn-soy rotations in Iowa and Illinois sustain granular nematicide demand despite EPA organophosphate re-registration pressures. The EPA's FIFRA data call-ins for soil metabolite profiles are extending registration timelines for legacy chemistries. California's Central Valley almond and strawberry operations are converting acreage fastest to microbial fermentation products to meet European MRL thresholds.
Mexico
Protected vegetable operations around Querétaro and Sinaloa are scaling precision drip irrigation infrastructure that pairs with liquid biological formulations. COFEPRIS agricultural chemical standards determine product availability and label claims across the national market. Large greenhouse tomato and cucumber producers are establishing direct technical service relationships with biologicals manufacturers, bypassing traditional distributor channels.
Canada
Prairie canola and pulse growers in Saskatchewan and Alberta are evaluating seed-treatment biological nematicides as alternatives to soil-applied synthetics. Health Canada's PMRA is harmonizing biopesticide registration standards with the EPA's Biopesticides and Pollution Prevention Division. Ontario's greenhouse vegetable sector around Leamington is adopting liquid microbial formulations for closed-loop irrigation compatibility.
North America Nematicides Market Competitive Landscape
Listed leaders compete with private specialists across regulatory affairs capacity and fermentation infrastructure. The vendor base concentrates around scaled registrants with dedicated EPA, PMRA, and COFEPRIS compliance teams. Three archetypes dominate: integrated agrochemical conglomerates with biologicals pipelines, pure-play microbial fermentation specialists, and regional distributors with technical service integration. Competitive moves center on proprietary strain library acquisition and precision delivery technology licensing.
Within the integrated conglomerate tier, Bayer AG and Corteva Agriscience exemplify archetypes leveraging seed-treatment platforms and biologicals pipelines to anchor soil-applied segment positions. FMC Corporation occupies a position among formulation technology specialists, differentiating via proprietary liquid delivery systems. Marrone Bio Innovations represents the pure-play biologicals archetype, sitting within the microbial fermentation specialist tier with concentrated expertise in live strain formulation.
| Leading Market Players |
|---|
| FMC Corporation |
| Corteva Agriscience |
| Bayer AG |
| Syngenta AG |
| BASF SE |
| American Vanguard Corporation |
| UPL Limited |
| Marrone Bio Innovations |
| Certis USA |
| Others |
Value Network & Pricing Analysis
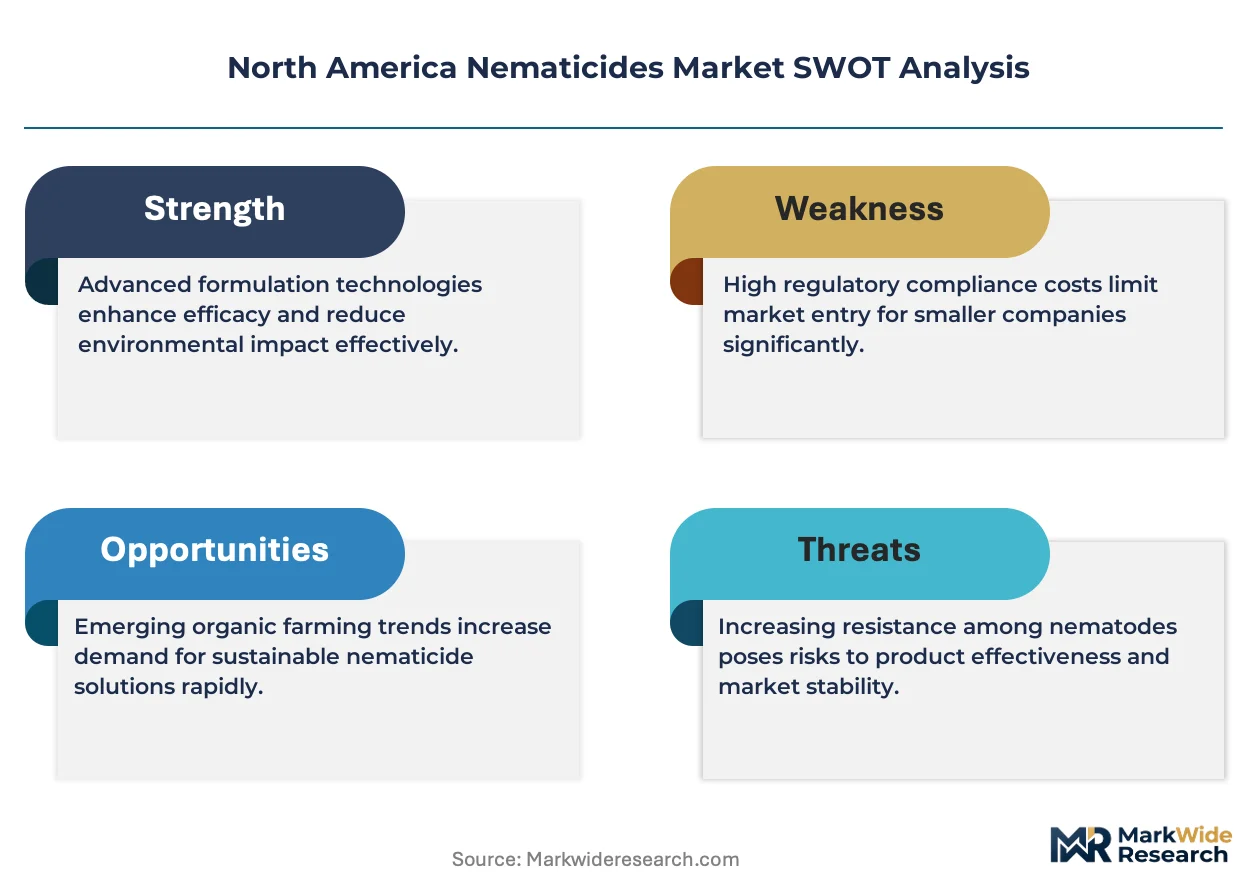
EPA registration under FIFRA gates both supply qualification and price differentiation simultaneously, as registrants with dedicated regulatory affairs infrastructure capture premium positioning while smaller developers face compressed margins from extended compliance timelines.
Pricing Analysis
Certification level (EPA biopesticide registration tier) creates the primary spread between premium biological formulations and commodity chemical alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity, with microencapsulated Pasteuria products commanding top-tier positioning. Cost compression in synthetic organophosphate segments is intensifying because of re-registration data call-ins. Midwest corn-soy cooperatives exhibit highest price sensitivity, while California almond exporters prioritize residue compliance over unit cost.
Supply Chain Analysis
United States and Mexico anchor fermentation capacity for Purpureocillium lilacinum and Bacillus firmus strains, with contract manufacturing organizations concentrated in California's Central Valley and Querétaro's industrial corridor. Live microbial formulations draw from specialized cold-chain infrastructure and sterile fermentation vessels. Single-source vulnerability concentrates in North American contract manufacturing capacity for proprietary strain libraries. Distribution runs through agricultural cooperative networks in the Midwest and direct technical service relationships in Mexico's protected vegetable sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery driven by EPA organophosphate re-registration pressures accelerating biological substitution programs across specialty crop districts.
For Market Incumbents: Secure proprietary strain libraries through exclusive licensing arrangements with university extension services in Florida and California. Deepen backward integration into fermentation capacity to offset contract manufacturing bottlenecks for Pasteuria microencapsulation. Channel control through seed-treatment platform partnerships offers defensive positioning against pure-play biological specialists. For New Entrants and Emerging Players: Anchor in Sinaloa's open-field tomato and pepper operations outside protected structures, where untreated acreage represents immediate conversion potential. Target direct technical service relationships with large greenhouse operators in Querétaro bypassing distributor intermediaries. Precision irrigation integration expertise serves as the critical go-to-market angle for liquid biological formulations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across microbial fermentation infrastructure as COFEPRIS streamlined pathways draw cross-border manufacturing investment. Long-term viability over the coming decade hinges on regulatory affairs scalability across EPA, PMRA, and COFEPRIS jurisdictions. Acquisition target archetype: pure-play biologicals developers with validated strain libraries but constrained compliance bandwidth. Watch EPA biopesticide registration approval velocity as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Strain Library Acquisition | Exclusive Purpureocillium lilacinum isolates from UC Davis nematology programs defendable formulations. |
| Fermentation Capacity Expansion | Querétaro manufacturing footprint captures COFEPRIS streamlined biopesticide registration advantages. |
| Seed-Treatment Platform Integration | Corn belt distributor partnerships bundle biological nematicides with fungicide and insecticide stacks. |
| Precision Irrigation Compatibility Certification | Greenhouse operator technical specifications in Sinaloa and Querétaro demand fertigation-validated liquid formulations. |
| Cross-Border Registration Harmonization | EPA-PMRA biopesticide pathway alignment reduces duplicative field trials for US-Canada product mobility. |
Research Methodology
A spread of perspectives from EPA regulatory affairs directors, California Department of Pesticide Regulation officials, nematology extension specialists at University of Florida and UC Davis, and procurement managers at Midwest agricultural cooperatives converged on the working assumptions. Secondary validation drew from EPA registration databases, COFEPRIS agricultural chemical filings, Health Canada PMRA submission records, and USDA National Agricultural Statistics Service crop acreage reports. Bottom-up acreage conversion estimates and top-down manufacturer revenue triangulation anchored the analytical framework.
Segmentation dimensions modeled include product type (chemical versus biological), application setting (agricultural fields versus greenhouses), and end-user procurement channel (direct grower purchases versus cooperative aggregation). CAGRs were derived from trend extrapolation of biological substitution rates in California specialty crops and protected agriculture expansion trajectories in Mexico. Industry-specific forecast inputs incorporated EPA re-registration timeline assumptions and COFEPRIS regulatory pathway efficiency metrics.
Material uncertainties — EPA data call-in scope expansion, COFEPRIS enforcement consistency, and fermentation capacity construction delays — sit outside the modeled envelope. Forecasts reflect assumptions about biological efficacy validation capacity and residue-sensitive export crop demand continuity. Recalibration cycles align with material shifts in EPA organophosphate registration decisions and COFEPRIS biopesticide approval velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
Hungary Crop Protection Chemicals Market
Crop Protection
Soil Fumigant Market
Crop Protection
South America Molluscicides Market
Crop Protection
Global Phosphine Fumigation Market
Crop Protection
Inorganic Fungicide Market
Crop Protection
Global Organophosphate Pesticide Market
Crop Protection
Fumigation Market
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Russia Crop Protection Chemicals Market
Crop Protection
Trapping and Mating Disruption Systems Market
Crop Protection
Canada Nematicides Market
Crop Protection
Isoxaflutole Market
Crop Protection
North America Acaricides Market
Crop Protection
Sweet Potato Fly Market
Crop Protection
Specialty Pesticides Market