
 US Turf and Ornamental Protection Market | 2026-2036
US Turf and Ornamental Protection Market Size, Share, and Industry Trends Forecast 2026-2036
US Turf and Ornamental Protection Market Insights
The US turf and ornamental protection sector is decoupling along a clear fault line between premium biological formulations and commodity synthetic chemistries. Corteva Agriscience leverages its seed-to-spray pipeline to dominate proprietary trait-linked protection bundles for golf courses and sports turf. FMC Corporation anchors its position through deep R&D intensity in novel insecticide modes of action that sustain patent-protected margins against generic erosion. Syngenta Group differentiates through integrated agronomic service platforms that extend beyond product sales into seasonal turf management protocols.
US turf and ornamental protection encompasses chemical and biological inputs formulated to manage weeds, insects, fungal pathogens, and plant growth in non-crop ornamental and recreational grass environments, typically requiring EPA-registered active ingredients applied at precise rates measured per thousand square feet. These products serve to maintain aesthetic standards, playability, and plant health across managed landscapes where failure carries immediate visual and economic consequences. Herbicides command the largest product type position due to persistent weed pressure in warm-season and cool-season turf zones, while biological growth regulators represent the fastest-expanding segment as golf course managers reduce mowing frequency and fuel costs. The application split favors golf courses and commercial landscapes where concentrated acreage justifies professional applicator contracts, though residential lawns generate steadier recurring revenue through seasonal pre-emergent and post-emergent programs.
EPA registration and state-level Department of Agriculture enforcement shape product availability and label restrictions across all fifty states, with California's DPR imposing additional toxicity thresholds that frequently exceed federal baselines. The Federal Insecticide, Fungicide, and Rodenticide Act mandates efficacy and environmental fate testing that extends development timelines and elevates barriers for new active ingredient introduction. State-by-state neonicotinoid prohibitions and pollinator protection plans are fragmenting the addressable market for certain insecticide classes. Stakeholders must monitor pending EPA Endangered Species Act consultations that threaten to redraw application windows and buffer zones for widely used chemistries in high-value turf markets.
Market Dynamics
Precision application technology is compressing input volumes across US golf courses and commercial landscapes while elevating service contract values for applicators who integrate soil sensing, drone scouting, and variable-rate equipment into seasonal programs.
Growth Catalysts
- Biological growth regulators:Golf course superintendents deploy these products to reduce mowing cycles, cut fuel consumption, and redirect labor toward playability improvements.
- California DPR toxicity thresholds:Stricter state-level standards than federal EPA baselines accelerate formulation upgrades that command premium positioning in West Coast markets.
- Sun Belt warm-season turf concentration:Year-round maintenance contracts in Florida, Texas, and Arizona generate recurring revenue streams unavailable in cool-season zones with dormant winter periods.
Market Restraints
- Active ingredient re-registration costs:EPA-mandated environmental fate and efficacy testing extends development timelines and elevates capital barriers for new chemistry introduction.
- Neonicotinoid prohibitions:State-by-state bans fragment addressable markets for systemic insecticides and force inventory segmentation across distributor networks.
- Generic herbicide erosion:Patent expiration on core chemistries compresses margins for commodity weed control products in residential lawn segments.
Strategic Opportunities
- Residential subscription programs:Direct-to-homeowner seasonal pre-emergent and post-emergent bundles bypass traditional retail channels and capture recurring revenue.
- EPA Endangered Species Act consultations:Pending buffer zone and application window restrictions create first-mover advantage for biological alternatives with favorable ecological profiles.
- Drone-based spot spraying:Aerial precision platforms reduce total chemical load per acre while justifying higher per-application service fees.
Industry Challenges
- Certified applicator licensing bottlenecks:State Department of Agriculture testing backlogs delay workforce expansion for professional lawn care operators.
- Soil sensor integration complexity:Legacy irrigation and fertility management systems require costly retrofitting to accept real-time turf health data feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Turf and Ornamental Protection Market |
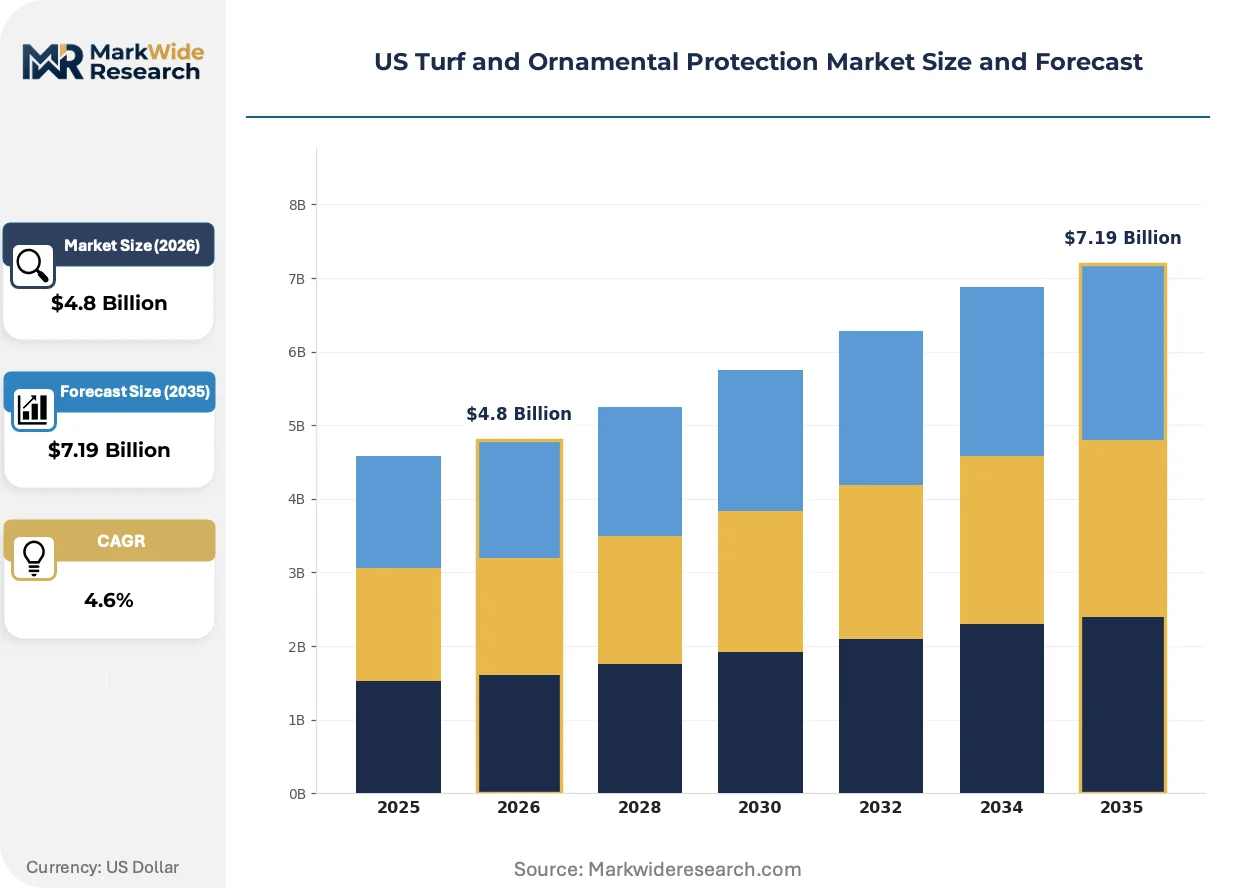
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Growth Regulators Application: Golf Courses, Parks, Residential Lawns, Commercial Landscapes End User: Homeowners, Landscape Contractors, Golf Course Managers, Agricultural Producers Distribution Channel: Online Retailers, Garden Centers, Wholesale Distributors, Agricultural Supply Stores |
| Companies Covered | Corteva Agriscience, BASF SE, FMC Corporation, Syngenta Group, Nufarm Ltd, American Vanguard Corporation, Environmental Science US LLC (Envu), Bayer AG, UPL Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Turf and Ornamental Protection Market Trends and Innovations
Formulation chemistry and application hardware are converging to reduce per-acre input volumes while shifting competitive advantage toward service-integrated delivery models that bundle diagnostics, prescriptions, and compliance documentation.
Microencapsulated herbicide delivery systems are absorbing market share from conventional emulsifiable concentrates by extending residual control windows and reducing volatilization losses. Golf course superintendents in Arizona and Florida adopt these formulations to maintain weed-free playing surfaces through intense summer stress periods. The technology is absorbing volume from older chemistries that require more frequent reapplication and carry higher buffer zone liabilities.
EPA re-registration requirements for conventional active ingredients are tightening formulation standards and compressing the product development pipeline. Manufacturers face extended environmental fate testing timelines that delay new chemistry launches by multiple growing seasons. The golf course segment absorbs these delays through accelerated adoption of biological alternatives that face lower regulatory barriers.
Service bundling is displacing standalone product sales as the dominant commercial model across professional turf maintenance contracts. Lawn care operators in Texas and Georgia now package soil testing, prescription mapping, and application execution into fixed-fee seasonal programs. This shift concentrates purchasing power with multi-location service providers who negotiate direct manufacturer relationships.
US Turf and Ornamental Protection Market Segmentation
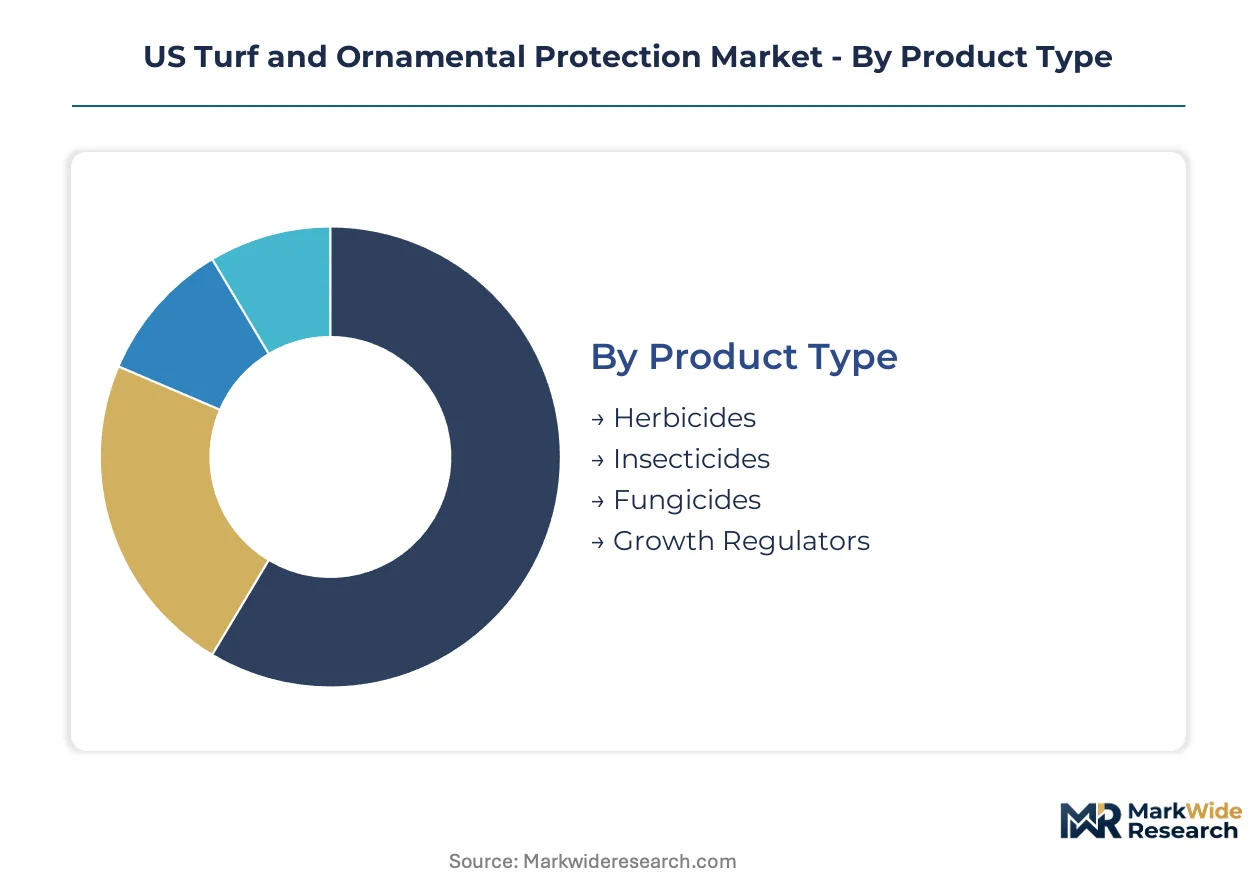
US turf and ornamental protection segments align with distinct EPA registration pathways and state-level enforcement intensity. Each category carries specific compliance burdens that shape product development timelines and go-to-market strategies.
Product Type:
EPA registration requirements vary sharply across chemistry classes, with conventional active ingredients facing extended environmental fate testing versus streamlined biological pathways.
- Herbicides:Formulations targeting grassy and broadleaf weeds dominate maintenance budgets across warm-season and cool-season turf zones. Golf course managers in Florida and Texas allocate disproportionate spend to pre-emergent and post-emergent programs for bermudagrass and zoysiagrass fairways.
- Insecticides:Systemic and contact chemistries manage white grubs, armyworms, and billbugs in high-value recreational turf. State-by-state neonicotinoid prohibitions fragment addressable markets and force inventory segmentation for lawn care operators spanning multiple jurisdictions.
- Fungicides:Preventive and curative treatments address dollar spot, brown patch, and Pythium blight pressure during humid growing seasons.
- Growth Regulators:Biological formulations suppress vertical shoot growth to reduce mowing frequency and redirect labor toward playability improvements.
Herbicides sit at the top of the volume ranking, with growth regulators climbing the fastest.
Application:
Cost tier stratification separates capital-intensive recreational facilities from recurring-revenue residential programs.
- Golf Courses:Precision application technology and integrated agronomic service platforms justify premium pricing for championship facilities. Superintendents in Arizona and Georgia adopt drone scouting and variable-rate equipment to compress input volumes while elevating playability standards.
- Commercial Landscapes:Corporate campuses, retail centers, and municipal properties demand consistent aesthetic performance across concentrated acreage. Professional applicator contracts in Sun Belt states generate year-round revenue streams unavailable in dormant cool-season zones.
- Parks:Public recreation facilities balance budget constraints with safety and visual standards for high-traffic community spaces.
- Residential Lawns:Seasonal subscription bundles bypass traditional retail channels and capture recurring pre-emergent and post-emergent revenue.
Golf courses command the highest per-acre service fees, with residential lawns expanding most quickly through direct-to-consumer channels.
End User:
Customer type determines purchasing power concentration and technical specification complexity.
- Golf Course Managers:Certified superintendents leverage professional networks and direct manufacturer relationships to negotiate trait-linked protection bundles. Their technical expertise drives adoption of novel formulations with favorable ecological profiles ahead of regulatory mandates.
- Landscape Contractors:Multi-location service providers consolidate purchasing power through seasonal program bundling that integrates soil testing, prescription mapping, and compliance documentation.
- Homeowners:DIY consumers respond to subscription convenience and simplified application instructions for seasonal lawn care programs.
- Agricultural Producers:Nursery and sod farm operations require crop protection inputs that maintain plant health through production cycles and post-harvest establishment.
Golf course managers anchor premium product demand, with landscape contractors gaining share fastest through service integration.
Distribution Channel:
Supply concentration favors wholesale networks with certified applicator training infrastructure over fragmented retail.
- Wholesale Distributors:Regional networks maintain inventory depth and technical support capabilities for professional applicators. Their direct relationships with manufacturers enable volume pricing and early access to reformulated products ahead of EPA re-registration deadlines.
- Garden Centers:Seasonal retail presence captures homeowner demand for branded consumer packaged goods with simplified label instructions.
- Online Retailers:E-commerce platforms expand geographic reach for specialty biological formulations with lower regulatory shipping restrictions.
- Agricultural Supply Stores:Rural locations serve agricultural producers and landscape contractors with overlapping equipment and input needs.
Wholesale distributors retain the largest volume position, with online retailers expanding most quickly through subscription fulfillment models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada maintains stricter federal pesticide oversight than the United States, while Mexico's agricultural chemical registration pathways create divergent market entry timelines for turf protection products across North America.
Southeast (Florida/Georgia)
Year-round bermudagrass and zoysiagrass maintenance contracts drive concentrated demand for pre-emergent herbicide programs. EPA re-registration requirements for conventional active ingredients force formulation upgrades ahead of federal deadlines. Orlando and Atlanta anchor commercial landscape service provider networks that negotiate direct manufacturer relationships.
Southwest (Texas/Arizona)
Golf course superintendents deploy precision application technology to compress input volumes across dormant winter ryegrass overseeding transitions. State Department of Agriculture enforcement of certified applicator licensing creates workforce expansion bottlenecks for professional lawn care operators. Phoenix and Dallas-Fort Worth concentrate multi-location landscape contractors consolidating seasonal program purchasing power.
California
The Department of Pesticide Regulation imposes toxicity thresholds exceeding federal EPA baselines, accelerating premium biological formulation adoption. DPR's Proposition 65 listing requirements and surface water monitoring programs restrict application windows for legacy chemistries. Los Angeles and San Diego metropolitan areas generate concentrated demand for low-volatility herbicide formulations meeting air quality district standards.
Pacific Northwest
Cool-season turfgrass dormancy compresses the active maintenance window, intensifying demand for rapid-establishment fungicide programs during abbreviated growing seasons. State-level neonicotinoid prohibitions in Oregon and Washington fragment addressable markets for systemic insecticides. Seattle and Portland anchor municipal park systems balancing budget constraints with visual performance standards.
US Turf and Ornamental Protection Market Competitive Landscape
Top-tier vendors anchor integrated agronomic service platforms, while mid-tier specialists compete through biological formulation differentiation and regional distribution density. The market structure consolidates around R&D-intensive patent portfolios and direct manufacturer relationships with multi-location service providers. Three archetypes dominate: seed-to-spray pipeline integrators, novel chemistry mode-of-action developers, and subscription-based direct-to-consumer platforms. Competitive moves concentrate on EPA re-registration timing advantages and precision application technology bundling.
Within the integrated platform tier, Corteva Agriscience and Syngenta Group exemplify archetypes leveraging proprietary trait-linked protection bundles and seasonal turf management protocols respectively. FMC Corporation occupies a position representing novel insecticide R&D intensity. These three anchors illustrate how patent-protected margins and service integration capabilities separate premium positioning from commodity synthetic erosion.
| Leading Market Players |
|---|
| Corteva Agriscience |
| BASF SE |
| FMC Corporation |
| Syngenta Group |
| Nufarm Ltd |
| American Vanguard Corporation |
| Environmental Science US LLC (Envu) |
| Bayer AG |
| UPL Limited |
| Others |
Pricing and Supply Chain Analysis
Multi-location landscape contractors in Texas and Georgia concentrate purchasing power through seasonal program bundling, forcing manufacturers toward subscription-based pricing models that embed diagnostics and compliance documentation. This buyer concentration elevates service contract values while compressing margins on standalone product sales.
Pricing Analysis
Service bundling versus unbundled product sales defines the pricing split across US turf protection markets. Three-tier pricing structure across premium biological formulations, standard synthetic chemistries, and economy generic herbicides separates Corteva's trait-linked bundles from commodity alternatives. Cost compression in residential lawn segments intensifies as patent expiration erodes margins on core weed control chemistries. Golf course superintendents exhibit lowest price sensitivity due to playability failure costs, while DIY homeowners drive hardest bargain negotiations.
Supply Chain Analysis
Regional distribution centers in Houston, Orlando, and Phoenix anchor hub-and-spoke patterns that feed professional applicator networks across Sun Belt states. Active ingredient manufacturing draws from China, India, and domestic US facilities for EPA-registered chemistries. Supply chain risk centers on single-source vulnerability for novel biological fermentation inputs. Distribution runs through wholesale networks with certified applicator training infrastructure rather than fragmented retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US turf and ornamental protection constitutes a late-cycle quality story as golf course managers shift specification requirements toward EPA-favored biological alternatives ahead of pending Endangered Species Act consultations.
For Market Incumbents: Hedge patent cliff exposure through accelerated biological formulation pipelines that bypass extended EPA environmental fate testing timelines. Deepen backward integration into microbial strain libraries to secure proprietary active ingredient access before generic manufacturers replicate fermentation processes. California DPR toxicity thresholds threaten to disqualify legacy chemistries from West Coast markets without reformulation investment. For New Entrants and Emerging Players: Capture residential subscription white space through direct-to-consumer platforms that bypass wholesale distributor markups. Drone-based spot spraying services represent the most penetrable application segment, with Arizona and Florida golf courses already piloting variable-rate aerial platforms. Lead with soil sensor integration partnerships that retrofit legacy irrigation systems rather than competing on chemistry alone. For Investors and Strategic Acquirers: Agricultural input conglomerates with seed-to-spray pipelines are the most active acquirer in this space, seeking service integration capabilities that extend beyond product sales. Five-to-ten year viability hinges on biological formulation portfolios with favorable ecological profiles. Acquisition target archetype: regional lawn care operators with consolidated purchasing power and direct manufacturer relationships. Monitor EPA Endangered Species Act consultation timelines as signal for accelerated biological substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Formulation Pipeline Investment | Accelerates product launches ahead of EPA re-registration deadlines for conventional chemistries. |
| Precision Application Technology Bundling | Compresses input volumes while elevating per-acre service fees for golf course contracts. |
| Direct-to-Consumer Subscription Launch | Bypasses wholesale distributor networks to capture recurring residential lawn care revenue. |
| Soil Sensor Integration Partnership | Retrofits legacy irrigation systems to accept real-time turf health diagnostics from golf superintendents. |
| Certified Applicator Training Program | Alleviates state Department of Agriculture licensing bottlenecks constraining workforce expansion. |
Research Methodology
Coverage spans the Southeast, Southwest, California, and Pacific Northwest regions, with primary inputs from each. The analysis combines structured interviews with golf course superintendents, landscape contractor procurement leads, wholesale distributor technical directors, and EPA regulatory affairs specialists with secondary validation from FIFRA registration databases, state Department of Agriculture enforcement records, and SEC filings from listed agricultural chemical manufacturers. Bottom-up volume modeling triangulates against top-down market sizing across product type, application, and end user segments.
Rate-of-change decomposition separates volume growth from price realization effects across the projection horizon. Segmentation dimensions modeled include chemistry class, application setting, customer type, and distribution channel, with additional granularity on EPA registration pathway and state-level regulatory intensity. CAGRs derive from historical trajectory analysis adjusted for identified catalysts and restraints. Industry-specific forecast inputs incorporate golf course maintenance budget surveys and neonicotinoid prohibition legislative tracking.
Pending EPA Endangered Species Act consultations, California DPR threshold adjustments, and biological formulation efficacy validation are the dominant revision risks. Forecasts reflect documented assumptions about regulatory timeline adherence and adoption curve steepness for precision application technologies. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Trapping and Mating Disruption Systems Market
Crop Protection
Fosthiazate Market
Crop Protection
Global Termite Control Market
Crop Protection
Global SDHI Fungicide Market
Crop Protection
Germany Crop Protection Chemicals Market
Crop Protection
Iprodione Market
Crop Protection
France Crop Protection Chemicals Market
Crop Protection
China Fungicide Market
Crop Protection
India Insecticide Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
Sweet Potato Fly Market
Crop Protection
Soil Sterilizers Market
Crop Protection
Crop Protection Chemicals Market
Crop Protection
Africa Crop Protection Chemicals Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
South America Fungicide Market