
 North America Eggs Market | 2026-2036
North America Eggs Market Size, Share, and Industry Trends Forecast 2026-2036
North America Eggs Market Analytics
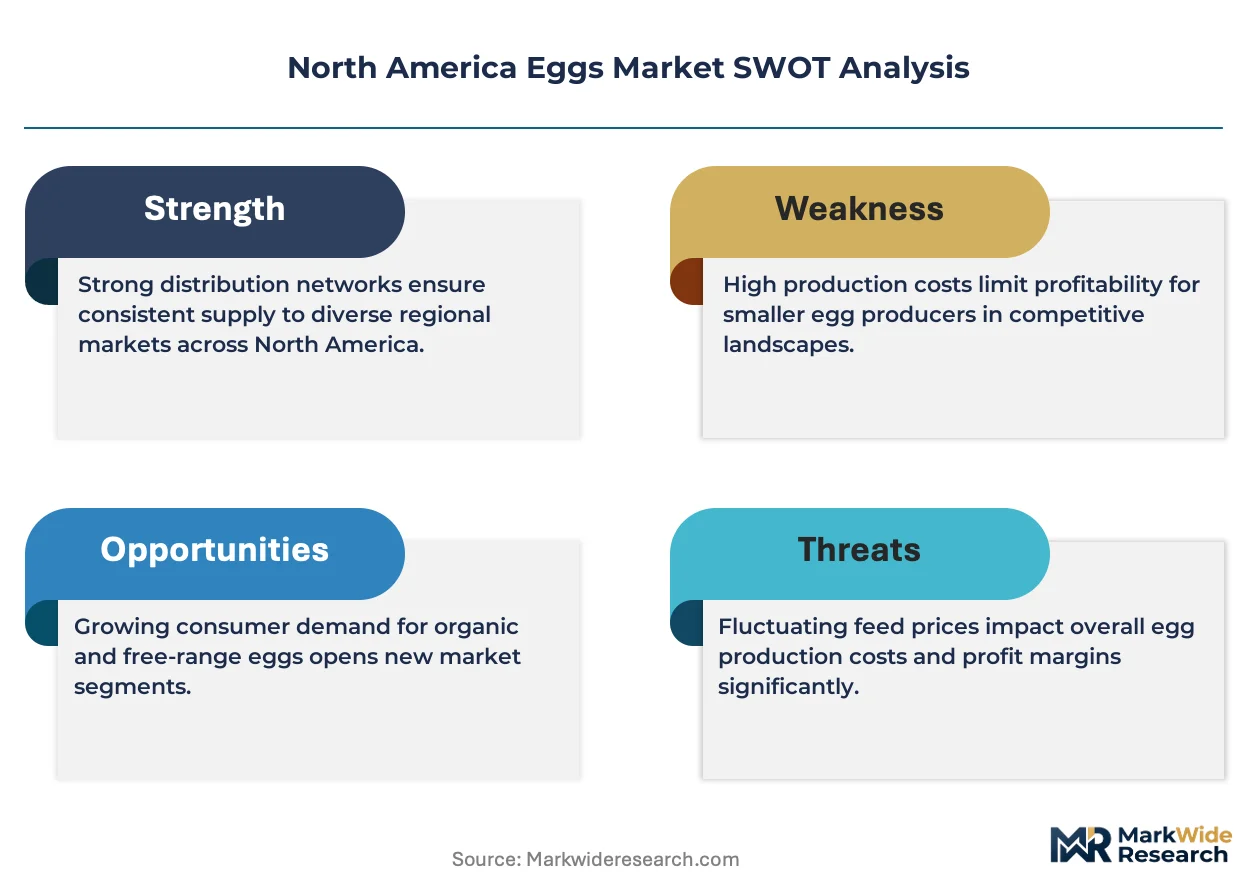
Layer farm labor availability is collapsing across the Upper Midwest, forcing operators to automate collection and grading lines or reduce flock sizes. Cal-Maine Foods sustains the largest shell egg production network in the United States through backward integration into feed milling and pullet rearing. Rose Acre Farms leverages its multi-state facility footprint to navigate regional supply disruptions and maintain retail shelf presence. Hillandale Farms anchors institutional supply contracts with food service distributors through dedicated cage-free volume commitments.
Eggs are the intact reproductive structures of domesticated Gallus gallus domesticus, comprising approximately 12% shell, 58% white, and 30% yolk by mass, with standardized USDA grading by interior quality and shell cleanliness determining commercial destination. Their primary commercial purpose spans direct retail consumption, ingredient functionality in emulsification and leavening, and prepared food manufacturing where binding and texture properties prove essential. Cage-free eggs now command disproportionate shelf space growth as retailers respond to corporate sustainability pledges, while conventional eggs retain volume leadership in commodity food processing channels where cost sensitivity dominates procurement decisions. The bakery sector pulls increasing volumes of pasteurized liquid and dried egg products for formulation consistency and pathogen control.
USDA grading standards and FDA egg safety rules under the Egg Safety Final Rule shape product handling requirements and interstate commerce eligibility, while state-level cage-free mandates in California, Massachusetts, and Colorado are forcing housing system conversions that raise capital requirements and thin marginal producer ranks. The Federal Trade Commission monitors carton labeling claims including "pasture-raised" and "humane certified," creating compliance exposure for packers without third-party audit trails. Stakeholders must track which state legislatures advance housing ballot measures, as fragmented regulatory geography will determine which production assets retain market access and which face stranded investment.
Market Dynamics
State-level cage-free mandates are forcing capital-intensive housing conversions across the United States, compressing marginal producers while rewarding operators with balance sheet capacity to absorb retrofit costs and extended depreciation schedules.
Growth Catalysts
- California Proposition 12:This animal welfare mandate extends market access requirements to out-of-state producers, pulling national supply chains toward uniform cage-free standards and expanding addressable premium shelf space.
- Food service protein diversification:Quick-service chains and institutional cafeterias are expanding egg-based breakfast and all-day menu items, creating sustained pull for shell eggs and liquid pasteurized products.
- Midwest feed grain concentration:Iowa and Ohio maintain captive access to corn and soybean meal supplies, insulating integrated layer operations from input cost volatility affecting coastal competitors.
Market Restraints
- Soybean meal price volatility:Layer ration formulations depend on this protein source, and commodity futures swings directly compress flock margin forecasts and working capital requirements.
- Upper Midwest labor scarcity:Rural depopulation and competitive wages from manufacturing and logistics sectors have collapsed applicant pools for collection and grading line positions.
- Conventional egg demand plateau:Commodity food processing channels exhibit extreme cost sensitivity, limiting price recovery for producers without cage-free certification premiums.
Strategic Opportunities
- Colorado and Massachusetts mandate expansion:These state-level frameworks create first-mover advantages for producers with converted housing assets already operational.
- Pasteurized liquid egg penetration:Bakery and prepared food manufacturers are substituting shell eggs with pathogen-controlled alternatives to reduce liability and formulation variability.
- Direct-to-foodservice distribution:Bypassing traditional retail consolidation through dedicated cage-free volume contracts locks in premium pricing and reduces shelf-slotting fee exposure.
Industry Challenges
- FTC labeling audit trails:Third-party verification for "pasture-raised" and "humane certified" claims requires documentation systems many mid-tier packers lack.
- Automated collection capex cycles:Robotic grading and packing lines demand seven-figure investments with payback periods stretching across volatile margin environments.
- FDA Egg Safety Rule compliance:Refrigeration, testing, and traceback mandates impose operational complexity on multi-state distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Eggs Market |
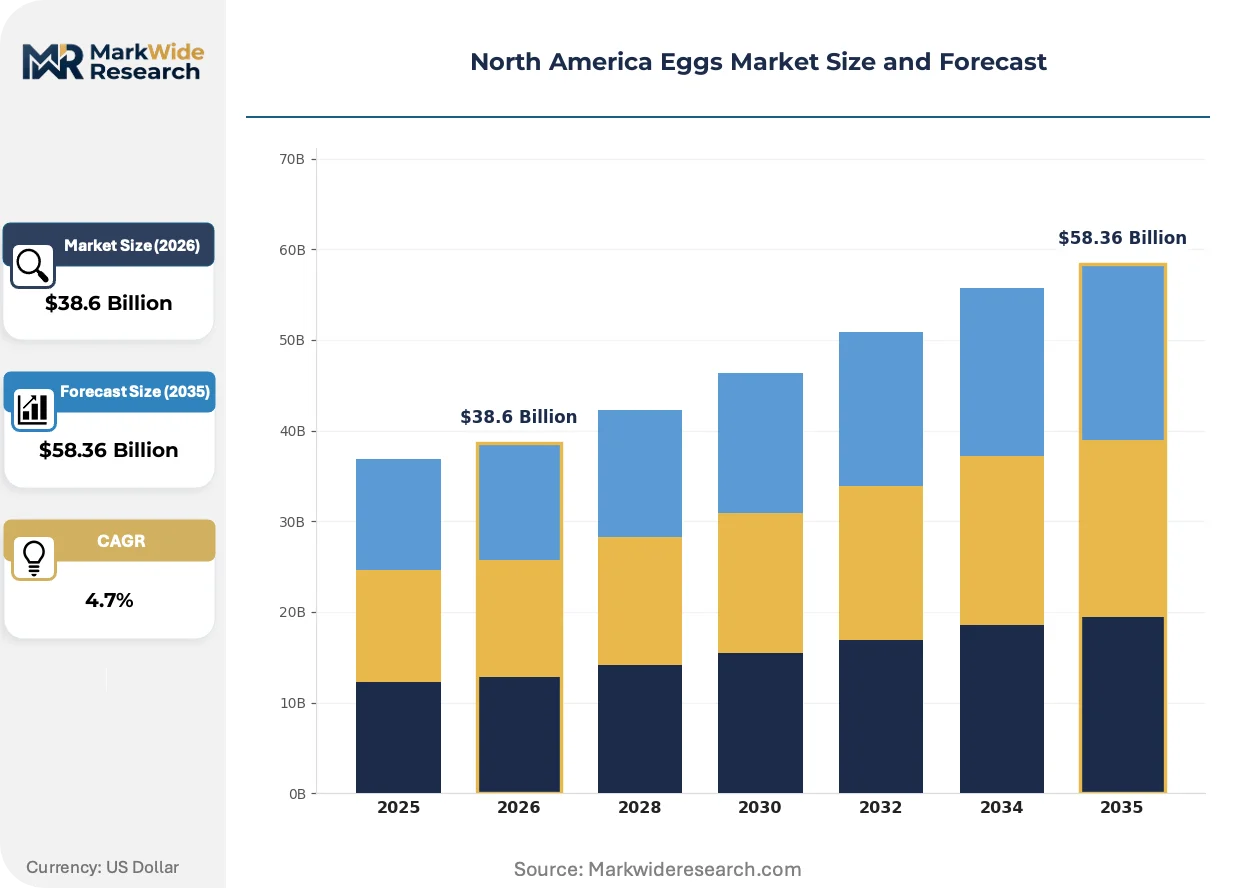
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.36 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Eggs, Organic Eggs, Free-Range Eggs, Cage-Free Eggs Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Farmers' Markets End User: Households, Food Service, Bakery Sector, Food Processing Packaging Type: Cartons, Trays, Bulk Packs, Clamshells |
| Companies Covered | Cal-Maine Foods, Inc., Rose Acre Farms, Inc., Hillandale Farms, Versova Holdings LLP, Rembrandt Foods, Michael Foods, Inc., Herbruck's Poultry Ranch, Inc., Sparboe, Daybreak Foods, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Eggs Market Evolving Landscape
Automation and housing system redesign are compressing labor dependence while regulatory fragmentation forces geographic specialization. These shifts are redrawing competitive boundaries between integrated and non-integrated producers.
In-ovo sexing technology is bifurcating hatchery operations by eliminating male chick culling, a practice facing legislative bans across multiple European jurisdictions and mounting activist pressure in North America. Large integrated producers in Iowa and Ohio are piloting optical and spectroscopic systems at scale, while smaller hatcheries delay adoption pending cost curves and regulatory clarity. This capability is compressing the addressable market for conventional hatchery equipment and creating premium positioning for certified humane supply chains.
The USDA Organic seal and state-level cage-free frameworks are tightening the definitional boundary between premium and commodity egg categories, forcing packers to segregate supply streams at the farm level. This regulatory layering raises compliance costs for multi-specification operators while creating stranded asset risk for producers with conventional housing in mandate-locked states. Retailers in California and Massachusetts are responding by consolidating supplier lists to reduce audit burden and liability exposure.
Buyer concentration among national food service distributors is compressing negotiation timelines and demanding dedicated cage-free volume commitments with penalty clauses for shortfall. This procurement consolidation favors producers with multi-state facility footprints capable of geographic redundancy and supply assurance. The bakery sector in the Upper Midwest exhibits the most visible shift, with regional manufacturers substituting shell eggs for pasteurized liquid to reduce pathogen testing costs and formulation inconsistency.
North America Eggs Market Segmentation
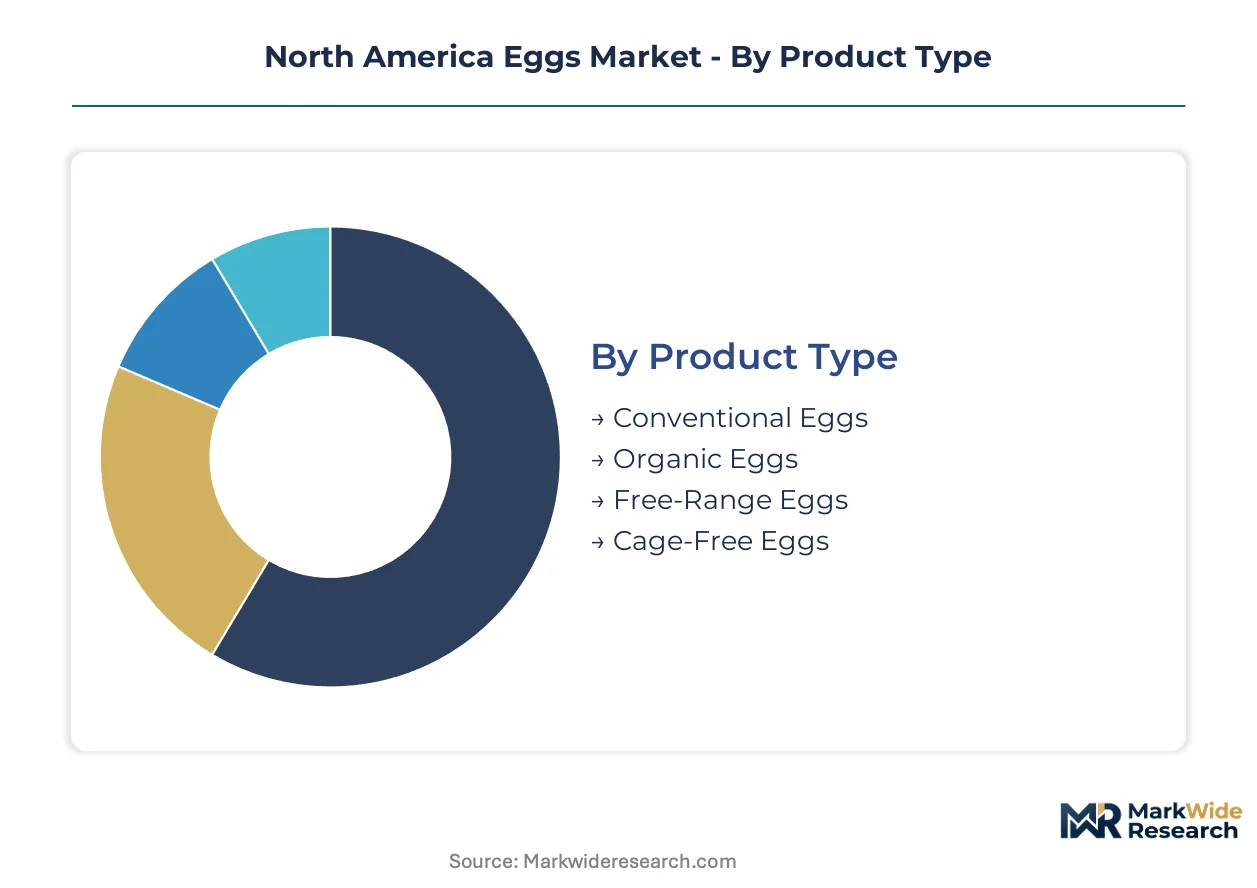
Egg market segmentation tracks how housing certification, distribution reach, and end-use functionality split margin pools across distinct supply streams. Understanding these divisions reveals which production assets command premium pricing and which face commoditization pressure.
Product Type:
Premium certification tiers capture disproportionate shelf space growth as state mandates reshape housing economics.
- Cage-Free Eggs:Hens housed in aviary or barn systems without restrictive enclosures, meeting California Proposition 12 and Massachusetts ballot measure requirements. Retailers in mandate states now allocate dominant shelf positioning to this category, while food service distributors demand dedicated volume commitments with penalty clauses for shortfall.
- Conventional Eggs:Standard housing with conventional cages retains volume leadership in commodity food processing channels where procurement teams prioritize unit cost over certification status. Midwest integrated producers leverage captive feed grain access to defend margin position against coastal competitors facing higher input logistics.
- Organic Eggs:USDA Organic seal requires outdoor access and organic feed rations, commanding price premiums in natural grocery channels.
- Free-Range Eggs:Outdoor access mandates vary by certifier, creating labeling complexity that FTC audit trails must document.
Cage-Free holds installed capacity. Organic is rotating up the share rankings.
Distribution Channel:
Channel selection determines working capital intensity and price realization, with direct routes bypassing retail slotting fees.
- Supermarkets:National and regional grocery chains dominate volume throughput, using category management to consolidate supplier lists and reduce audit burden for multi-certification egg programs. Shelf space allocation increasingly favors cage-free SKUs in mandate-state markets.
- Food Service:Quick-service chains and institutional cafeterias pull sustained shell egg and liquid pasteurized volumes for expanded all-day breakfast menus, creating direct procurement relationships that lock in premium pricing through dedicated cage-free contracts.
- Online Retail:E-commerce grocery platforms enable subscription models and direct-to-consumer fulfillment for specialty egg tiers.
- Farmers' Markets:Local producer direct sales capture hyper-premium positioning with minimal packaging overhead.
Supermarkets hold installed capacity. Food Service is rotating up the share rankings.
End User:
Application-driven demand splits between pathogen-sensitive prepared food manufacturing and raw shell egg consumption.
- Food Processing:Bakery and prepared food manufacturers substitute shell eggs with pasteurized liquid and dried products to reduce liability exposure and achieve formulation consistency. Regional manufacturers in the Upper Midwest exhibit the most visible shift, driven by pathogen testing cost reduction.
- Households:Retail consumers purchase shell eggs for direct consumption, with purchasing patterns increasingly influenced by housing certification labels and corporate sustainability pledges from national grocery banners.
- Food Service:Institutional cafeterias and restaurant chains require both shell eggs for cook-to-order applications and liquid pasteurized for batch production.
- Bakery Sector:Specialized emulsification and leavening requirements pull specific egg product formats with functional property guarantees.
Households hold installed capacity. Food Processing is rotating up the share rankings.
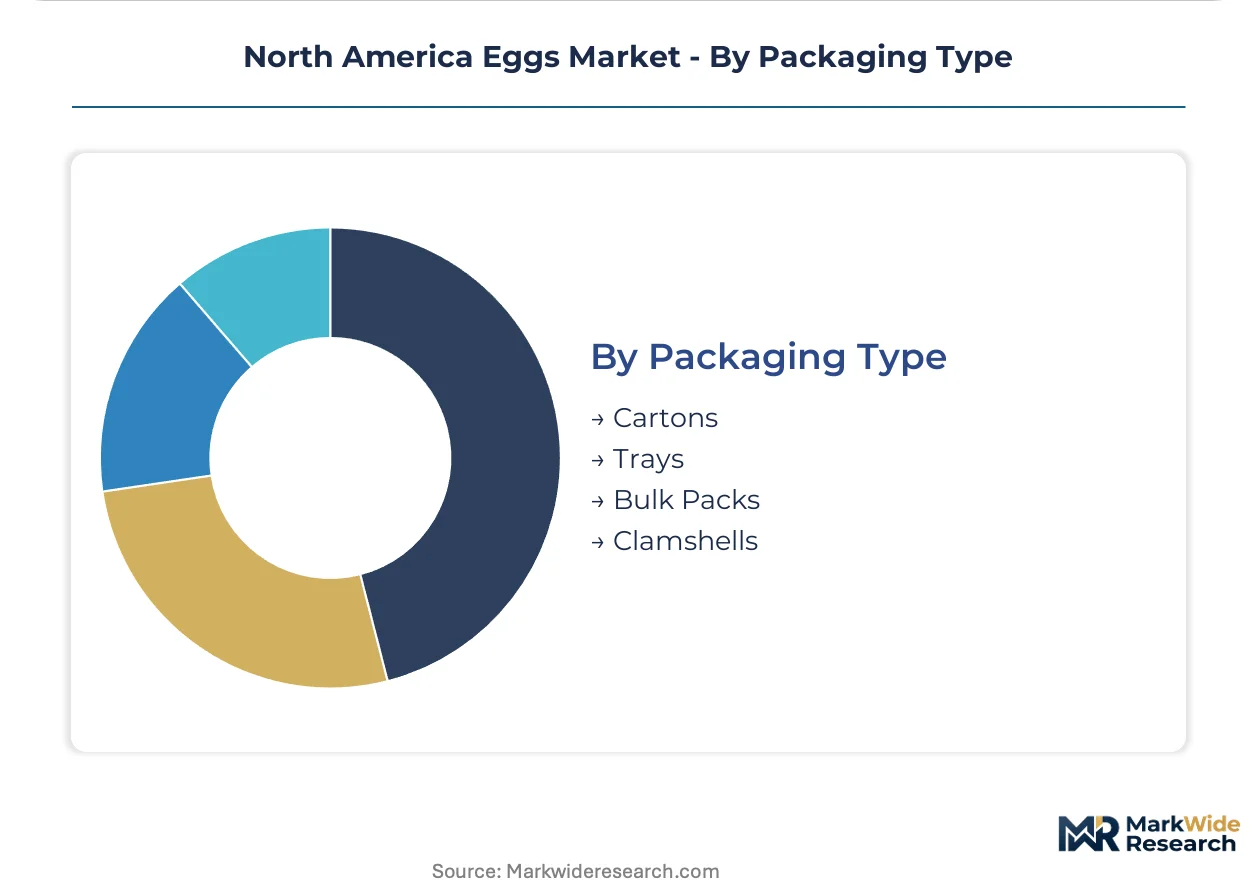
Packaging Type:
Packaging configuration aligns with channel handling requirements and automation compatibility at grading facilities.
- Cartons:Standard retail packaging in dozen and eighteen-count configurations dominates supermarket shelf presence, with fiber-based materials replacing polystyrene in response to retailer sustainability pledges.
- Clamshells:Transparent hinged containers enable visual quality assessment and protect shell integrity through distribution, commanding preference in premium retail tiers.
- Trays:Flat corrugated formats suit food service and bakery sector bulk handling with minimal material cost.
- Bulk Packs:Loose egg configurations for industrial food processing minimize packaging overhead at scale.
Cartons hold installed capacity. Clamshells is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA and FDA regulations anchor the United States as the dominant geography, with state-level cage-free mandates fragmenting compliance requirements across jurisdictions. Canada maintains parallel federal standards through Health Canada and the Canadian Food Inspection Agency. Mexico operates under distinct sanitary frameworks administered by COFEPRIS and SENASICA.
United States
California Proposition 12 and Massachusetts ballot measures pull national supply chains toward uniform cage-free standards. The FDA Egg Safety Final Rule imposes refrigeration, testing, and traceback mandates on interstate distribution. Iowa and Ohio concentrate production infrastructure, with automated grading facilities expanding across the Midwest farm belt to offset labor scarcity.
California
Retailers allocate dominant shelf positioning to cage-free SKUs under Proposition 12 enforcement. The California Department of Food and Agriculture audits out-of-state producer compliance for market access eligibility. Central Valley layer operations face stranded asset risk for conventional housing systems unable to meet aviary conversion timelines.
Canada
Ontario and Quebec processors pull increasing volumes of pasteurized liquid eggs for bakery sector formulation consistency. Health Canada and CFIA administer parallel egg safety and grading standards to USDA frameworks. Prairie Provinces concentrate feed grain production, insulating integrated operations from soybean meal price volatility affecting coastal competitors.
Mexico
COFEPRIS sanitary registration requirements shape import eligibility for U.S. shell egg and processed product flows. Northern Border States concentrate cross-border processing facilities serving food service distributors in Texas and California. SENASICA veterinary oversight mandates traceability systems for commercial layer operations supplying formal retail channels.
North America Eggs Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the North America Eggs Market. Tier-one operators control captive feed milling, pullet rearing, and multi-state distribution networks. Mid-tier packers concentrate on single-state production or specific certification tiers. Competitive moves center on housing system conversion capex cycles and direct-to-foodservice contract consolidation.
Among U.S.-based integrated producers, Cal-Maine Foods, Inc., Rose Acre Farms, Inc., and Hillandale Farms occupy positions across the premium and conventional supply tiers. These entities exemplify archetypes ranging from backward-integrated feed control to multi-state geographic redundancy and dedicated cage-free volume commitments for institutional distribution.
| Leading Market Players |
|---|
| Cal-Maine Foods, Inc. |
| Rose Acre Farms, Inc. |
| Hillandale Farms |
| Versova Holdings LLP |
| Rembrandt Foods |
| Michael Foods, Inc. |
| Herbruck's Poultry Ranch, Inc. |
| Sparboe |
| Daybreak Foods, Inc. |
| Others |
Value Network & Pricing Analysis
Seven-day shell egg inventory cycles in Iowa and Ohio layer operations concentrate pricing power with integrated producers holding captive feed milling capacity, while coastal buyers absorb elevated logistics premiums to access Midwest supply basins. This lead-time compression tightens margin pools for non-integrated packers lacking upstream grain control.
Pricing Analysis
Midwest-to-coastal price spreads of 15-20 cents per dozen reflect feed grain proximity advantages and cage-free certification premiums. Three-tier pricing structure across cage-free, conventional, and organic levels stratifies by housing system compliance and USDA grade. Pricing pressure stems from soybean meal futures volatility compressing flock margins. Commodity food processors exhibit extreme price sensitivity, while direct-to-foodservice cage-free contracts command premium realization.
Supply Chain Analysis
Fourteen-day cold chain lead times from Iowa grading facilities to Northeast retail distribution centers anchor supply scheduling. Production concentrates in Iowa, Ohio, and Indiana, drawing from regional corn and soybean meal supplies. Single-source vulnerability sits with concentrated Midwest feed grain sourcing. Distribution runs through national food service distributors and retail consolidation networks, with direct cage-free volume contracts bypassing traditional slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Eggs Market functions as a regulatory-entrenchment defensive moat, where state-level cage-free mandates create switching costs for buyers locked into certified supply chains and capital barriers for prospective entrants.
For Market Incumbents: Fortify backward integration into pullet rearing and feed milling to isolate margin compression from soybean meal volatility. Accelerate aviary housing conversions in Colorado and Massachusetts ahead of enforcement timelines to capture stranded competitor volume. Channel control through dedicated food service distributor contracts locks in premium pricing against retail slotting fee erosion.
For New Entrants and Emerging Players: American Humane Certified fast-track programs in Texas and Georgia offer white-space entry with lower retrofit capex than mandate-locked states. Target direct-to-institutional procurement channels in the Upper Midwest where labor scarcity has thinned incumbent grading capacity. Go-to-market positioning around pasteurized liquid egg products bypasses shell egg shelf space consolidation.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because fragmented mid-tier packer assets face stranded conventional housing risk in California and Massachusetts regulatory jurisdictions. Acquisition targets cluster around multi-state facility footprints with operational cage-free capacity and existing food service distributor relationships. The signal to watch is accelerated supplier list consolidation by national grocery banners reducing audit burden.
| Strategic Initiative | Industry Significance |
|---|---|
| Aviary Housing Conversion | California Proposition 12 compliance secures market access for out-of-state producers. |
| Backward Integration into Feed Milling | Captive corn and soybean meal supply insulates flock margins from commodity volatility. |
| Pasteurized Liquid Egg Capacity Expansion | Bakery sector pathogen control requirements drive substitution away from shell eggs. |
| Direct-to-Foodservice Distribution Contracts | Dedicated cage-free volume commitments bypass retail slotting fees and lock premium pricing. |
| Automated Grading Line Deployment | Robotic collection systems offset Upper Midwest labor scarcity in Iowa and Ohio operations. |
Research Methodology
The analysis maps cage-free, conventional, organic, and free-range supply tiers, each validated through layer farm operators, food service procurement directors, retail category managers, and feed grain suppliers. Primary interview intelligence triangulates against USDA production statistics, FDA Egg Safety Rule compliance filings, state-level housing mandate legislative records, and SEC 10-K disclosures from integrated producers. Bottom-up volume modeling from state-level flock counts reconciles with top-down consumption estimates derived from Nielsen retail audit data and food service distribution channel reports.
Consistency checks against American Egg Board production surveys and USDA National Agricultural Statistics Service hen inventory reports validate forecast outputs. The projection framework segments by housing certification, distribution channel, end-use application, and packaging format, with CAGRs derived from regression analysis of historical price realization and input cost trajectories. Forecast inputs incorporate feed grain futures curves, state regulatory enforcement timelines, and automation adoption rates across Midwest grading facilities.
Decision-makers should treat outputs as directional under assumptions of continued state-level mandate expansion and stable feed grain supply; material deviation in soybean meal price volatility or regulatory enforcement timing would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Sorghum by-Products Market
Agriculture and Agri Products
Organic Soybean Market
Agriculture and Agri Products
Asia-Pacific Artificial Humus Market
Agriculture and Agri Products
North America Bonsai Market
Agriculture and Agri Products
Canada Backyard Poultry Feed Market
Agriculture and Agri Products
South America Compound Feed Market
Agriculture and Agri Products
France Alfalfa Hay Market
Agriculture and Agri Products
Asia-Pacific Chaga Mushroom Market
Agriculture and Agri Products
Japan Animal Protein Market
Agriculture and Agri Products
China Animal Protein Market
Agriculture and Agri Products
Manufactured Garden Soil Market
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
Australia Animal Protein Market
Agriculture and Agri Products
Saudi Arabia Eggs Market
Agriculture and Agri Products
France Animal Protein Market
Agriculture and Agri Products
Agrimony Market