
 Inorganic Fungicide Market | 2026-2036
Inorganic Fungicide Market Size, Share, and Industry Trends Forecast 2026-2036
Inorganic Fungicide Market Foresight
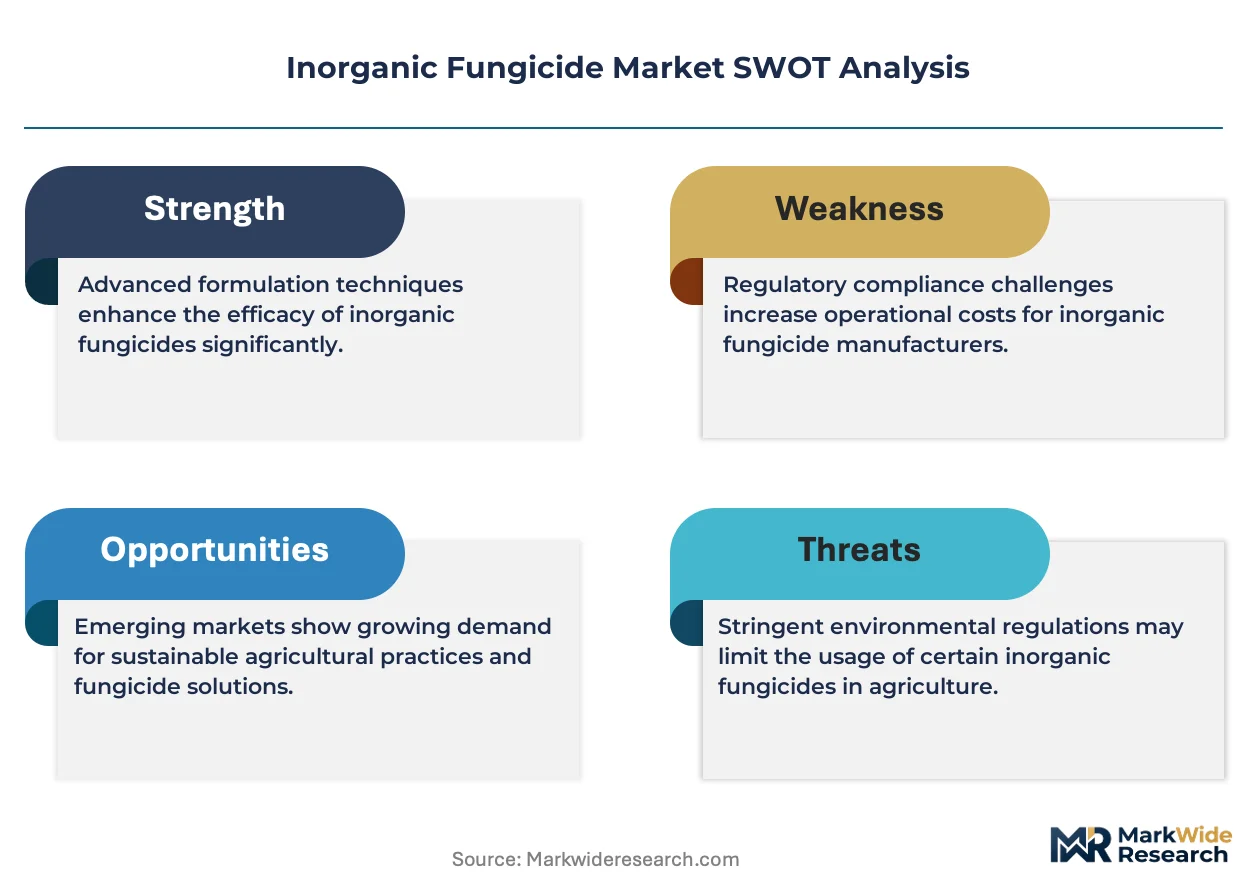
Horticulture is expanding its share of inorganic fungicide consumption as protected cultivation of tomatoes, peppers, and leafy greens intensifies worldwide. Bayer AG leverages its R&D infrastructure to sustain patent-protected formulations in high-value crop segments. Syngenta Group anchors its position through integrated seed-and-crop-protection bundles that lock in fungicide demand across major growing regions. BASF SE differentiates via specialized liquid concentrate formulations designed for precision application equipment.
Inorganic fungicides are synthetic or mineral-derived crop protection agents, typically based on copper, sulfur, or dithiocarbamate chemistry, formulated to inhibit fungal spore germination and mycelial growth through multisite biochemical disruption; copper sulfate formulations generally contain metallic copper at concentrations ranging from fifteen to fifty percent by weight, depending on intended crop and disease target. The primary commercial purpose centers on protecting field crops, fruits, and vegetables from downy mildew, blight, and rust pathogens where systemic alternatives face resistance constraints. Mancozeb and chlorothalonil dominate volume sales due to broad-spectrum activity and established residue tolerance databases, though copper sulfate is gaining share in organic-compliant farming systems where synthetic fungicides face restrictions. Liquid concentrates command premium positioning in large-scale mechanized agriculture, while soluble powders retain cost advantages in smallholder markets across South Asia and sub-Saharan Africa.
The EPA regulates inorganic fungicide registration under FIFRA, with re-registration reviews periodically restricting older active ingredients based on ecological risk assessments, while the EU's REACH and MDR frameworks impose stringent hazard classification and maximum residue limits that reshape product portfolios. India's CDSCO and Central Insecticides Board coordinate parallel approval processes that determine market access timelines for imported and domestically manufactured formulations. Stakeholders must monitor evolving residue tolerance harmonization between CODEX, EPA, and EFSA standards, as divergent limits threaten to fragment export markets for treated produce.
Market Dynamics
The EU Green Deal and F-Gas Regulation are systematically delisting legacy copper and sulfur formulations, forcing manufacturers to reformulate around stricter ecological hazard classifications while greenhouse operators absorb higher input costs.
Growth Catalysts
- Protected Cultivation Expansion:Greenhouse vegetable production in Spain and the Netherlands is intensifying copper-based preventive spraying cycles to manage humidity-driven downy mildew pressure.
- India's PLI Scheme:The Production Linked Incentive scheme for agrochemical manufacturing is drawing investment into domestic copper sulfate granulation and packaging capacity.
- Organic-Compliant Substitution:Copper hydroxide formulations are displacing synthetic systemic fungicides in certified organic operations where residue restrictions block conventional chemistry.
Market Restraints
- Active Ingredient Delisting:EFSA's ongoing mancozeb hazard reclassification is compressing approved uses across Europe and triggering export market fragmentation.
- Copper Price Volatility:Concentrate supply from Chilean smelters fluctuates with energy costs, destabilizing formulation economics for sulfur-copper blends.
- Biological Substitution:Bacillus subtilis and Trichoderma-based biocontrol products are capturing share in high-value horticulture where pre-harvest intervals favor non-chemical options.
Strategic Opportunities
- Precision Application Integration:Drone-mounted electrostatic sprayers are enabling variable-rate copper deposition in Vietnamese rice paddies, reducing unit application rates.
- Sub-Saharan Smallholder Access:Soluble powder sachet packaging distributed through Kenyan agro-dealer networks addresses capital constraints in informal vegetable supply chains.
- EU Carbon Border Adjustment:The CBAM mechanism creates cost advantages for European-manufactured copper oxychloride versus imported Chinese formulations.
Industry Challenges
- Residue Harmonization Complexity:Divergent CODEX, EPA, and EFSA maximum residue limits force exporters to maintain multiple formulation variants for the same crop.
- Application Equipment Calibration:Smallholder operators lack technical support to adjust knapsack sprayer nozzles for optimal copper droplet size distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inorganic Fungicide Market |
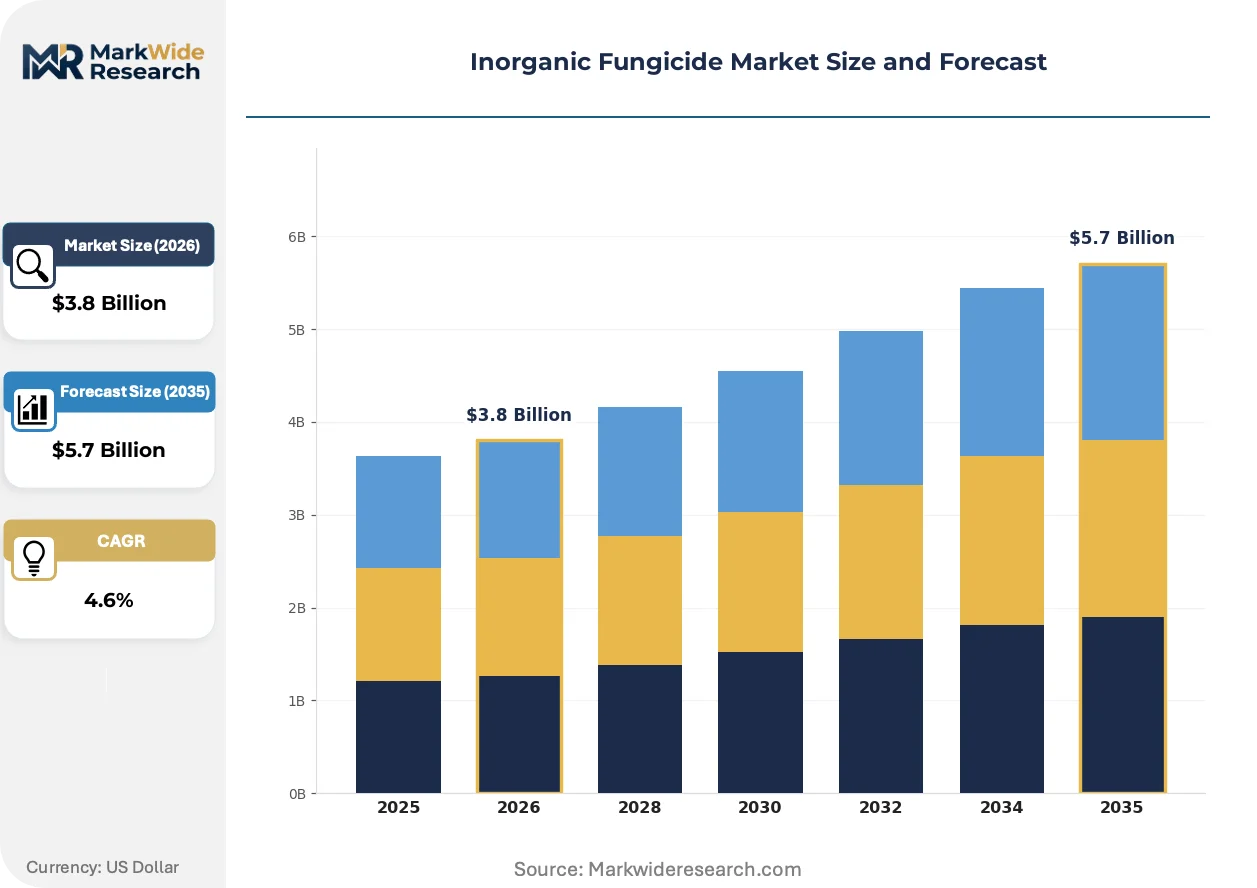
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chlorothalonil, Copper Sulfate, Mancozeb, Zinc Oxide End Use Industry: Agriculture, Horticulture, Turf Management, Ornamentals Application: Crops, Soil Treatment, Seed Treatment, Post-Harvest Formulation: Granules, Soluble Powders, Liquid Concentrates, Emulsifiable Concentrates |
| Companies Covered | UPL Limited, Bayer AG, Nufarm Ltd., Albaugh LLC, Certis Biologicals, BASF SE, Syngenta Group, Corteva Agriscience, FMC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inorganic Fungicide Market Shifts & Advancements
Formulation chemistry and application hardware are converging to reduce metallic copper loadings per hectare while maintaining protective efficacy against resistant pathogen populations.
Nano-copper suspension concentrates are electrifying disease management protocols by enabling sub-micron particle distribution that adheres to leaf cuticles more uniformly than conventional formulations. Large-scale tomato and pepper greenhouse operators in Mexico and Morocco are adopting these concentrates to cut metallic copper application rates. This particle size reduction is electrifying competitive positioning among formulation specialists capable of stabilizing colloidal suspensions without rapid sedimentation.
REACH authorization timelines for dithiocarbamate active ingredients are extending registration maintenance costs for legacy products. The European Chemicals Agency's substance evaluation work program is demanding additional chronic toxicity data that many generic manufacturers lack resources to generate. Mancozeb-dependent suppliers are accelerating portfolio pivots toward copper-calcium formulations with established Annex XV dossiers.
Certification-driven procurement is consolidating buyer power among GlobalGAP-aligned vegetable exporters who mandate pre-approved supplier lists with residue testing documentation. Kenyan and Peruvian fresh produce exporters are excluding small formulation brands lacking third-party laboratory partnerships. This compliance layering favors integrated agrochemical distributors with in-house residue monitoring capabilities over independent traders.
Inorganic Fungicide Market Segmentation
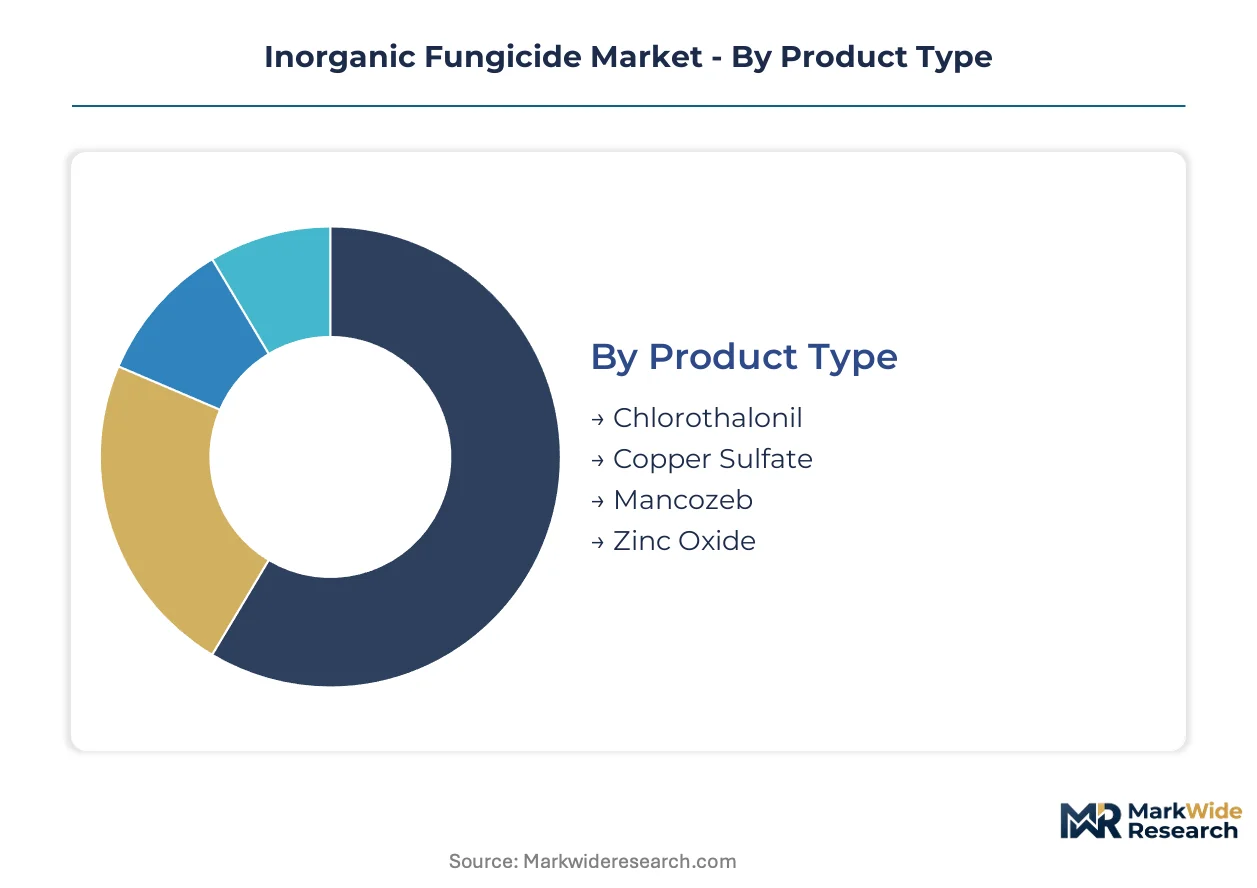
Inorganic fungicide manufacturers configure production lines around specific active ingredient chemistries and formulation physics. Segmentation reveals where capital deployment concentrates and which product architectures command premium positioning.
Product Type:
Copper sulfate granulation and mancozeb synthesis demand the heaviest fixed-asset investment due to multi-stage chemical processing and environmental containment requirements.
- Copper Sulfate:Metallic copper content ranges from fifteen to fifty percent by weight in commercial formulations. Greenhouse vegetable producers in Spain and the Netherlands deploy copper sulfate preventively against humidity-driven downy mildew, absorbing higher input costs under EU Green Deal reformulation mandates.
- Mancozeb:A dithiocarbamate fungicide delivering broad-spectrum activity through multisite biochemical disruption. EFSA's ongoing hazard reclassification is compressing approved uses across Europe, forcing suppliers to accelerate portfolio pivots toward copper-calcium alternatives.
- Chlorothalonil:Nitrile-based protectant fungicide with established residue tolerance databases in EPA and CODEX frameworks.
- Zinc Oxide:Micronutrient-carrying formulation used in seed treatment applications for fungal suppression and early plant vigor.
Mancozeb absorbs the bulk of installed capacity; copper sulfate is expanding most quickly.
End Use Industry:
Customer procurement patterns diverge sharply between commodity field crops and high-value protected cultivation, reshaping margin structures.
- Agriculture:Field crop applications dominate volume consumption, with wheat and rice producers in India driving demand for cost-effective sulfur-copper blends under the PLI scheme.
- Horticulture:Protected cultivation of tomatoes, peppers, and leafy greens intensifies copper-based preventive spraying cycles. GlobalGAP-aligned exporters in Kenya and Peru mandate pre-approved supplier lists with residue testing documentation.
- Turf Management:Golf course and sports field maintenance requires specialized application timing around human exposure windows.
- Ornamentals:Nursery and floriculture operations prioritize aesthetic crop protection with minimal phytotoxicity risk.
Agriculture captures the greatest absolute volume; horticulture climbs the fastest on value-per-hectare metrics.
Application:
Application timing relative to crop phenology determines formulation selection and regulatory residue compliance burden.
- Crops:Foliar spraying of field and vegetable crops constitutes the primary commercial purpose, with downy mildew and blight pathogens driving repeat application cycles.
- Seed Treatment:Pre-plant fungal protection concentrates in commercial maize and soybean operations where systemic alternatives face resistance constraints.
- Soil Treatment:Pre-plant incorporation of copper-based products for soil-borne pathogen suppression in intensive vegetable systems.
- Post-Harvest:Citrus and pome fruit packing lines apply protective coatings to prevent storage rot during extended cold chain distribution.
Crop foliar applications dominate current volumes; seed treatment is gaining share fastest through precision agriculture integration.
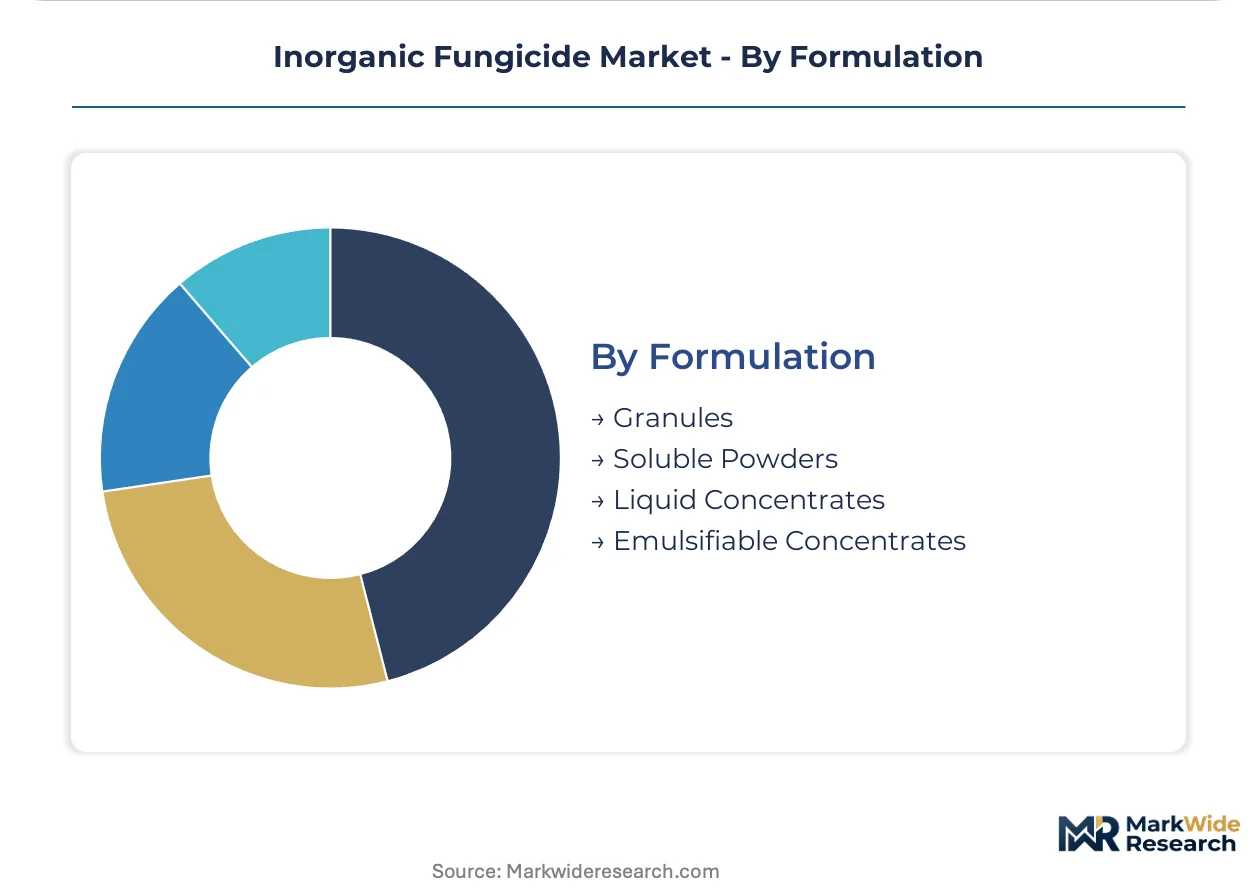
Formulation:
Physical form factor dictates packaging investment, distribution logistics, and end-user application equipment requirements.
- Liquid Concentrates:Specialized formulations designed for precision application equipment command premium positioning in large-scale mechanized agriculture. BASF SE differentiates via liquid concentrate chemistry optimized for drone-mounted electrostatic sprayers in Vietnamese rice paddies.
- Soluble Powders:Cost-advantaged dry formulations retain dominance in smallholder markets across South Asia and sub-Saharan Africa. Kenyan agro-dealer networks distribute sachet packaging that addresses capital constraints in informal vegetable supply chains.
- Granules:Slow-release matrix formulations for soil incorporation and extended protection windows.
- Emulsifiable Concentrates:Oil-based carriers enabling improved leaf cuticle penetration and rainfastness in tropical climates.
Soluble powders hold the widest geographic penetration; liquid concentrates are expanding most quickly through precision agriculture adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in China and India, while consumption concentrates in European greenhouse operations and Brazilian field crop applications. This geographic split shapes trade flows and regulatory compliance burdens across the value chain.
India
The PLI scheme for agrochemical manufacturing is accelerating domestic copper sulfate granulation investments in Gujarat and Maharashtra. CDSCO and the Central Insecticides Board coordinate parallel approval processes that compress market access timelines for locally manufactured formulations. Mumbai-Pune industrial corridor facilities now supply sulfur-copper blends to wheat and rice producers across the Indo-Gangetic Plain.
Spain
Almería and Murcia greenhouse complexes drive intensive copper-based preventive spraying cycles against humidity-driven downy mildew in tomato and pepper cultivation. EU Green Deal reformulation mandates are forcing operators to absorb higher input costs for compliant copper hydroxide products. Valencia formulation packagers are retrofitting lines to meet REACH authorization timelines for residual dithiocarbamate chemistry.
Brazil
Soybean and maize producers in Mato Grosso and Paraná deploy mancozeb protectant programs where systemic alternatives face resistance constraints. ANVISA maintains residue tolerance databases that diverge from CODEX standards, complicating export compliance for treated grain shipments. São Paulo-based distributors are consolidating procurement power through integrated seed-and-crop-protection bundles.
United States
EPA FIFRA re-registration reviews are periodically restricting older active ingredients based on ecological risk assessments in the Corn Belt and California Central Valley. Fresno County vegetable operations balance chlorothalonil applications against pre-harvest interval requirements for leafy green exports. Midwest formulation terminals are optimizing liquid concentrate logistics for precision application equipment deployment.
China
Shandong and Jiangsu provinces concentrate copper sulfate synthesis capacity serving both domestic rice paddies and export markets. MEE environmental enforcement is tightening effluent standards for sulfur-chemical processing facilities along the Yangtze River Delta. Qingdao port packagers are adapting soluble powder specifications to Kenyan and Peruvian agro-dealer network requirements.
Inorganic Fungicide Market Competitive Landscape
Top-tier vendors anchor integrated agrochemical platforms, while mid-scale specialists concentrate on formulation chemistry and regional distribution networks. The structure tilts toward consolidation at the active ingredient synthesis level and fragmentation in application-specific packaging. Three archetypes dominate: multinational crop science conglomerates with seed-protection bundles, copper mining-integrated chemical processors, and regional formulation packagers serving smallholder supply chains. Competitive moves concentrate on portfolio diversification away from delisted actives and backward integration into copper concentrate sourcing.
Among the integrated crop science majors, Bayer AG and Syngenta Group exemplify platform-scale positioning through bundled input offerings. BASF SE occupies a specialized tier focused on liquid concentrate chemistry optimized for precision equipment. UPL Limited represents the emerging market-anchored archetype with manufacturing presence in India and distribution reach across sub-Saharan Africa and Southeast Asia.
| Leading Market Players |
|---|
| UPL Limited |
| Bayer AG |
| Nufarm Ltd. |
| Albaugh LLC |
| Certis Biologicals |
| BASF SE |
| Syngenta Group |
| Corteva Agriscience |
| FMC Corporation |
| Others |
Supply & Pricing Matrix
EU Green Deal reformulation mandates gate qualified supply and premium-tier pricing access by forcing copper hydroxide and calcium-copper alternatives through REACH authorization timelines, compressing margins for non-compliant manufacturers while rewarding European-manufactured formulations with CBAM cost advantages.
Pricing Analysis
Margin tightening in liquid concentrate tiers reflects precision application equipment bundling and drone-mounted electrostatic sprayer compatibility requirements. Three-tier pricing structure across premium, standard, and economy levels separates GlobalGAP-certified formulations with residue documentation from generic copper sulfate granules and soluble powder sachets. Price differentiation hinges on metallic copper concentration grades and third-party laboratory certification partnerships. Smallholder markets across South Asia and sub-Saharan Africa exhibit highest price sensitivity; greenhouse operators in Spain and the Netherlands absorb premium positioning for compliant copper hydroxide.
Supply Chain Analysis
Freight cost volatility from Chilean copper concentrate smelters to Shandong and Jiangsu synthesis facilities destabilizes sulfur-copper blend economics. Manufacturing gravity centers on China and India, with Gujarat and Maharashtra granulation capacity expanding under PLI scheme incentives. Raw material dependencies include Chilean copper concentrate, elemental sulfur from petroleum refining, and dithiocarbamate intermediates. Single-source vulnerability concentrates in Chilean smelter supply. Distribution runs through integrated agrochemical distributors with in-house residue monitoring capabilities rather than independent traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH authorization timelines and EFSA hazard reclassifications erect barrier-to-entry moats favoring integrated majors with dossier generation resources.
For Market Incumbents: Deploy backward integration into copper concentrate sourcing to offset Chilean smelter price volatility and secure formulation cost stability. Accelerate portfolio pivots from mancozeb toward copper-calcium alternatives with established Annex XV dossiers ahead of EFSA delisting decisions. Channel control through GlobalGAP-aligned supplier list pre-approval locks out generic competitors lacking third-party laboratory partnerships. For New Entrants and Emerging Players: Agro-dealer networks in Kenyan and Peruvian fresh produce export corridors represent the most penetrable channel infrastructure for soluble powder sachet distribution. Precision application equipment bundling for Vietnamese rice paddy drone operators offers white-space positioning against liquid concentrate incumbents. Target organic-compliant substitution demand where copper hydroxide displaces synthetic systemic fungicides in certified operations. For Investors and Strategic Acquirers: EFSA's mancozeb hazard reclassification acceleration is the leading indicator that copper-calcium formulation specialists will command scarcity premiums. Long-term viability favors integrated platforms with seed-protection bundles and in-house residue monitoring capabilities over standalone generic manufacturers. Acquisition target archetype: regional formulation packagers with CDSCO approval track records and sub-Saharan distribution reach.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Concentrate | Captive supply from Chilean smelter relationships insulates margin volatility from energy cost fluctuations. |
| REACH Authorization Dossier Investment | Copper-calcium formulation approvals ahead of mancozeb delisting secure European market access continuity. |
| Precision Application Equipment Bundling | Drone-mounted electrostatic sprayer compatibility in Vietnamese rice paddies reduces metallic copper application rates. |
| GlobalGAP Supplier List Pre-Approval | Third-party laboratory partnerships with Kenyan and Peruvian exporters lock in residue-compliant procurement channels. |
| PLI Scheme Manufacturing Expansion | Domestic copper sulfate granulation in Gujarat and Maharashtra compresses CDSCO approval timelines for local supply. |
Research Methodology
Multi-period observation of active ingredient approval trajectories, greenhouse operator input cost absorption, and copper concentrate price volatility anchored the trend analysis, supplemented by interviews with formulation R&D directors, agrochemical procurement leads at integrated distributors, CDSCO regulatory affairs specialists, and GlobalGAP certification auditors. Secondary validation drew from EFSA substance evaluation work programs, EPA FIFRA re-registration dockets, Central Insecticides Board approval databases, and customs trade flow records. Bottom-up capacity installation tracking across Shandong and Jiangsu provinces triangulated against top-down consumption estimates from greenhouse operator surveys.
Input-output matrices modeled copper loading per hectare, formulation physics adoption curves, and regional regulatory cluster divergence across the projection horizon. Segmentation dimensions included active ingredient chemistry, physical formulation type, end-use crop category, application timing relative to phenology, and customer scale archetype. CAGRs derived from installed capacity expansion schedules, PLI scheme incentive uptake rates, and substitution elasticity between copper-based and biological alternatives. Industry-specific forecast inputs incorporated REACH authorization timeline probabilities and EFSA hazard reclassification scenario weights.
Several conditions sit outside the modeled scope, including unannounced EPA ecological risk assessment outcomes, sudden Chilean smelter supply disruptions from labor or energy events, and breakthrough biological fungicide efficacy improvements that could accelerate substitution beyond baseline elasticity assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
South America Nematicides Market
Crop Protection
Sweet Potato Fly Market
Crop Protection
Canada Nematicides Market
Crop Protection
Asia-Pacific Crop Protection Chemicals Market
Crop Protection
Fumigation Market
Crop Protection
North America Molluscicides Market
Crop Protection
France Crop Protection Chemicals Market
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
Global Turf Protection Market
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
Global Phosphine Fumigation Market
Crop Protection
Larvicides Market
Crop Protection
Low-Odor, Enclosed-Greenhouse Foliar Protection Market
Crop Protection
Global Algaecides Market
Crop Protection
Sustainable Crop Protection Chemicals Market