
 Fumigation Market | 2026-2036
Fumigation Market Size, Share, and Industry Trends Forecast 2026-2036
Fumigation Market Analysis
India's warehousing infrastructure expansion is reconfiguring regional service demand for phosphine and sulfuryl fluoride applications. Rentokil leverages its integrated pest management platform to sustain contract density across South Asian port zones. Terminix anchors North American residential termite fumigation through technician-trained branch networks. Truly Nolen differentiates via proprietary tenting systems and localized brand recognition in Florida and Gulf Coast markets.
Fumigation denotes the controlled release of gaseous pesticides into sealed enclosures to eliminate pests across all life stages, typically requiring concentrations of 1,000–50,000 ppm and exposure periods of 24–72 hours depending on target species and temperature. The process serves critical phytosanitary functions in international trade, preventing cross-border pest transmission and meeting import quarantine requirements. Chemical fumigation dominates value generation due to established efficacy against stored-product insects, though biopesticide alternatives are gaining traction in organic-certified commodity channels. Warehouse applications command substantial revenue share as grain stockpiling rises and food security programs expand storage capacity. Soil fumigation remains concentrated in high-value horticultural zones where nematode and fungal pathogen pressure justifies treatment costs.
EPA registration requirements under the Federal Insecticide, Fungicide, and Rodenticide Act govern active ingredient approval and application certification in the United States, while India's Central Insecticides Board mandates product registration and operator licensing under the Insecticides Act. FAO's International Standards for Phytosanitary Measures shape cross-border treatment protocols and residue limits, directly influencing equipment specifications and aeration timing. Stakeholders must monitor evolving methyl bromide phase-out schedules and emerging resistance profiles when allocating R&D budgets across chemical portfolios.
Market Dynamics
Methyl bromide phase-out schedules under the Montreal Protocol are forcing accelerated phosphine and sulfuryl fluoride adoption across commodity-exporting corridors, reshaping treatment protocols and aeration infrastructure investments worldwide.
Growth Catalysts
- FAO Phytosanitary Standards:Import quarantine mandates in grain-importing nations are mandating certified fumigation certificates for cross-border commodity flows, expanding service contract volumes at port facilities.
- India's FSSAI Warehouse Mandates:Food safety regulations requiring upgraded storage treatment protocols are driving phosphine system installations across the country's grain storage corridor.
- Precision Aeration Systems:Sensor-based gas monitoring technology is reducing exposure periods and labor costs, accelerating replacement cycles for legacy manual detection equipment.
Market Restraints
- Active Ingredient Supply Concentration:Phosphine tablet manufacturing concentrates in Chinese chemical clusters, creating vulnerability to export licensing delays and freight cost volatility.
- EPA FIFRA Registration Timelines:Multi-year approval pathways for novel fumigant chemistries extend commercialization horizons and elevate R&D capital requirements.
- Heat Treatment Substitution:Thermal disinfestation systems for organic-certified commodities are capturing share in premium grain segments where chemical residues face buyer rejection.
Strategic Opportunities
- Brazil's ANVISA Residue Monitoring:Expanded phosphine adoption protocols for agricultural exporters create service expansion potential in South American port zones.
- Organic Channel Biopesticide Convergence:Essential oil vapor formulations and modified atmosphere technologies are opening certified-organic commodity treatment segments previously closed to synthetic chemistry.
- Integrated Pest Management Platforms:Bundling fumigation with remote monitoring and predictive analytics is creating multi-year service contracts with warehouse operators seeking operational consolidation.
Industry Challenges
- Certified Fumigator Shortages:Operator licensing requirements under national insecticide acts are constraining technician supply in high-demand agricultural regions, extending service scheduling windows.
- Legacy Equipment Integration:Retrofitting automated gas monitoring into existing sealed storage structures requires structural modifications that disrupt warehouse operations during installation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fumigation Market |
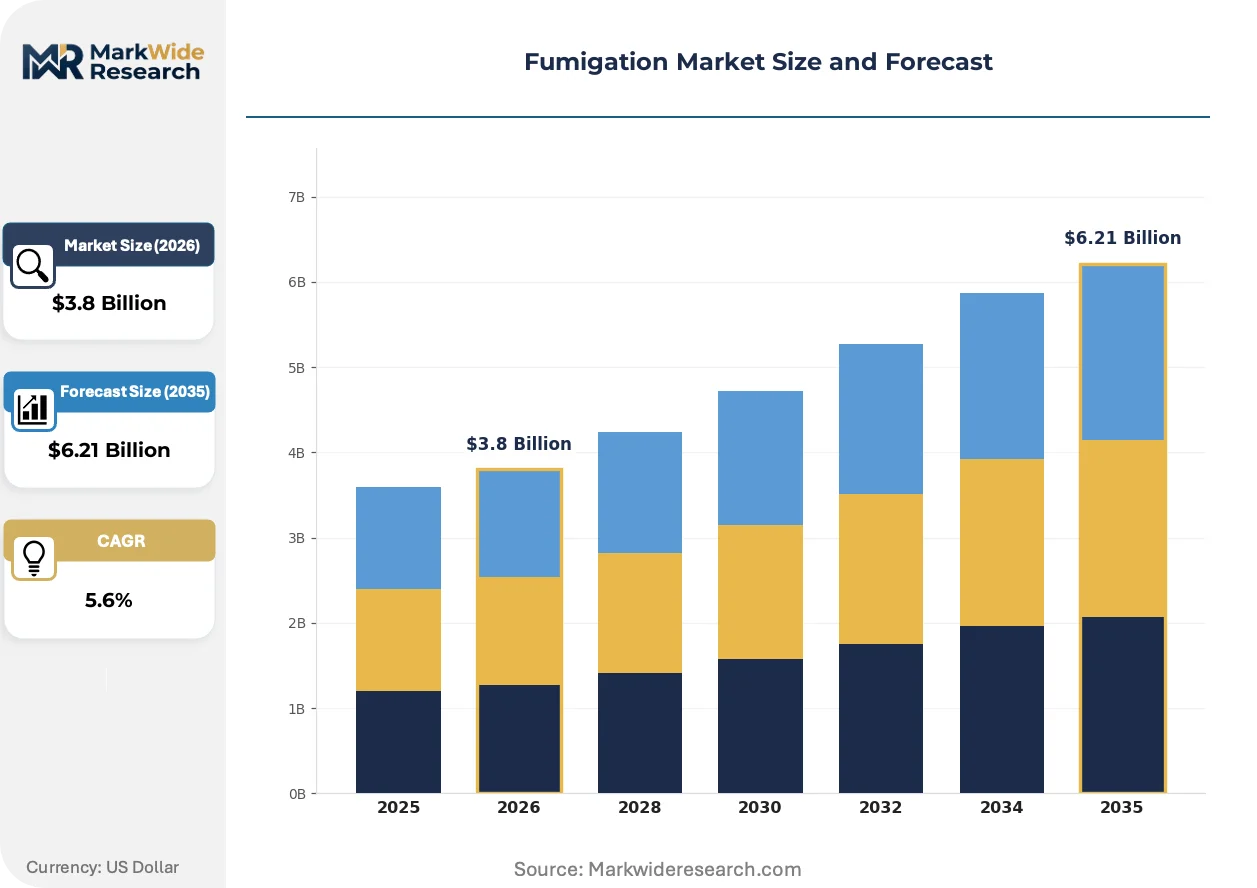
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methyl Bromide, Phosphine, Sulfuryl Fluoride, Chloropicrin Application: Warehouse, Shipping Container, Soil, Commodity Technology: Heat Treatment, Chemical Fumigation, Biopesticides, Aeration End User: Agriculture, Food Processing, Pest Control Services, Pharmaceutical |
| Companies Covered | Ehrlich, Hawx, Terminix, Turner Pest Control, TruGreen, Orkin, Aptive, Truly Nolen, Rentokil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fumigation Market Emerging Trajectories
Remote sensing and automated gas management systems are digitizing treatment workflows, compressing labor requirements while tightening concentration control. This technological pivot is redrawing competitive advantage around data integration capabilities rather than chemical supply alone.
Wireless sensor networks is digitizing real-time phosphine and sulfuryl fluoride concentration monitoring across warehouse enclosures. Large-scale grain handlers in Australia and the United States are deploying these systems to replace manual gas detection tubes and clipboard logging. The technology is digitizing compliance documentation for FAO phytosanitary certification while reducing aeration timing errors that previously caused shipment delays.
REACH authorization timelines for remaining methyl bromide critical-use exemptions are compressing availability windows in European Union horticultural zones. Strawberry and tomato producers in Spain and Italy face accelerated transitions to chloropicrin and 1,3-dichloropropene alternatives. High-value crop segments are responding with precision application equipment investments that reduce dosage rates and buffer zone requirements.
Commodity traders are consolidating fumigation procurement under integrated logistics contracts rather than spot-service arrangements. Large agricultural exporters in Brazil and Argentina now specify treatment-inclusive freight pricing, displacing standalone service relationships with port-zone fumigation providers. This pattern is most visible in soybean and corn export corridors where volume concentration gives buyers negotiating leverage over treatment scheduling and documentation formats.
Fumigation Market Segmentation
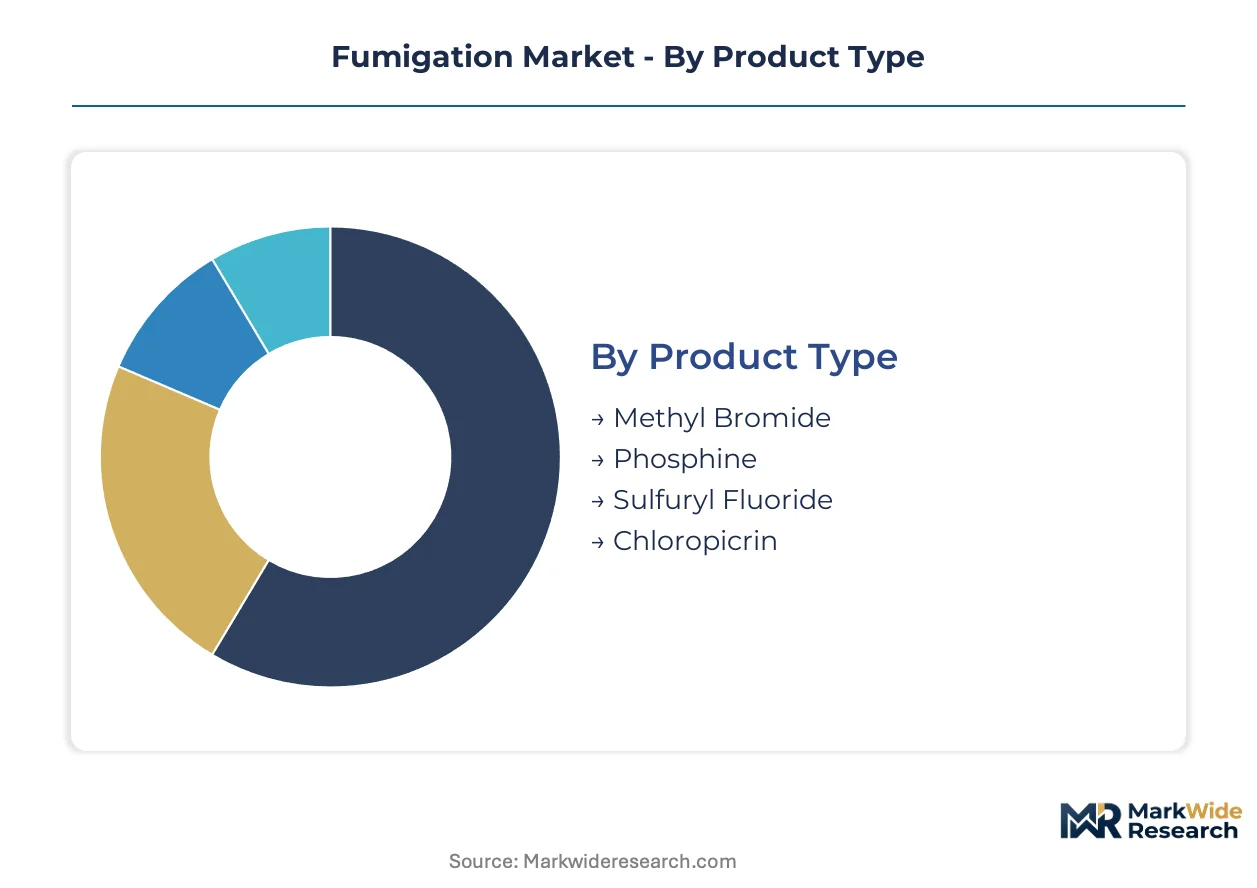
Fumigation market segmentation reveals how treatment chemistry, application infrastructure, and end-use requirements create distinct commercial pockets. Each dimension carries different regulatory burdens, equipment investments, and margin structures that shape vendor positioning.
Product Type:
Use cases span from legacy broad-spectrum sterilization to precision-targeted pest elimination, with each chemistry carrying distinct handling protocols and residue profiles.
- Methyl Bromide:A halogenated hydrocarbon with ozone-depleting properties now restricted to critical-use exemptions under Montreal Protocol schedules. Strawberry producers in Spain and Italy retain limited access for soil-borne pathogen control, though phase-out timelines are compressing availability windows.
- Phosphine:Metal phosphide formulations generating hydrogen phosphide gas dominate grain storage applications through tablet, pellet, and sachet delivery systems. India's FSSAI-mandated warehouse upgrades are accelerating phosphine system installations across the country's grain storage corridor, displacing legacy contact insecticide treatments.
- Sulfuryl Fluoride:A fluorinated sulfone compound penetrating wood matrices and commodity piles without leaving corrosive residues. Structural fumigation contractors in the United States favor this chemistry for termite and drywood pest elimination in residential and commercial properties.
- Chloropicrin:A tear gas derivative serving as both standalone fumigant and warning agent in combination formulations. Soil fumigation in California's Central Valley vegetable production zones relies on chloropicrin for nematode suppression where methyl bromide alternatives fall short.
Established volume favors phosphine; emerging adoption favors sulfuryl fluoride.
Application:
Physical enclosure characteristics dictate gas containment requirements, aeration infrastructure, and labor intensity across treatment settings.
- Warehouse:Large-volume sealed structures treating bulk grain, oilseed, and pulse commodities against stored-product insects. Australian grain handlers deploy wireless sensor networks for real-time phosphine monitoring, replacing manual detection tubes and clipboard logging.
- Shipping Container:Standardized twenty-foot and forty-foot enclosures requiring portable generator systems and rapid aeration turnaround. Port facilities in Brazil's Santos corridor process soybean and corn export volumes under ANVISA residue monitoring protocols.
- Soil:Pre-plant field applications suppressing nematodes, fungi, and weed seeds through shank injection or drip chemigation. High-value horticultural zones in California, Spain, and Italy justify treatment costs for strawberry and tomato production.
- Commodity:Targeted treatment of specific agricultural products—coffee, cocoa, spices, dried fruit—prior to export certification. FAO phytosanitary standards mandate certified fumigation certificates for cross-border flows, expanding service contract volumes at origin port facilities.
Revenue concentration sits with warehouse applications; container treatment offers the steepest expansion trajectory.
Technology:
Method selection balances efficacy speed, residue constraints, capital requirements, and organic certification eligibility.
- Heat Treatment:Thermal disinfestation raising commodity temperatures to insecticidal thresholds without chemical residues. Organic-certified grain segments in Germany and the Netherlands adopt heat systems where synthetic chemistry faces buyer rejection.
- Chemical Fumigation:Gaseous pesticide release into sealed enclosures at controlled concentrations and exposure periods. This approach retains dominance due to established efficacy against all life stages of stored-product insects.
- Biopesticides:Essential oil vapor formulations and microbial agents targeting organic commodity channels. Modified atmosphere technologies using nitrogen or carbon dioxide displacement are gaining traction in premium food segments.
- Aeration:Post-treatment gas evacuation and residue dissipation systems, increasingly automated through sensor-based monitoring. Precision aeration technology is reducing exposure periods and labor costs, accelerating replacement cycles for legacy manual detection equipment.
Capital intensity peaks with heat treatment; contract flexibility favors chemical fumigation.
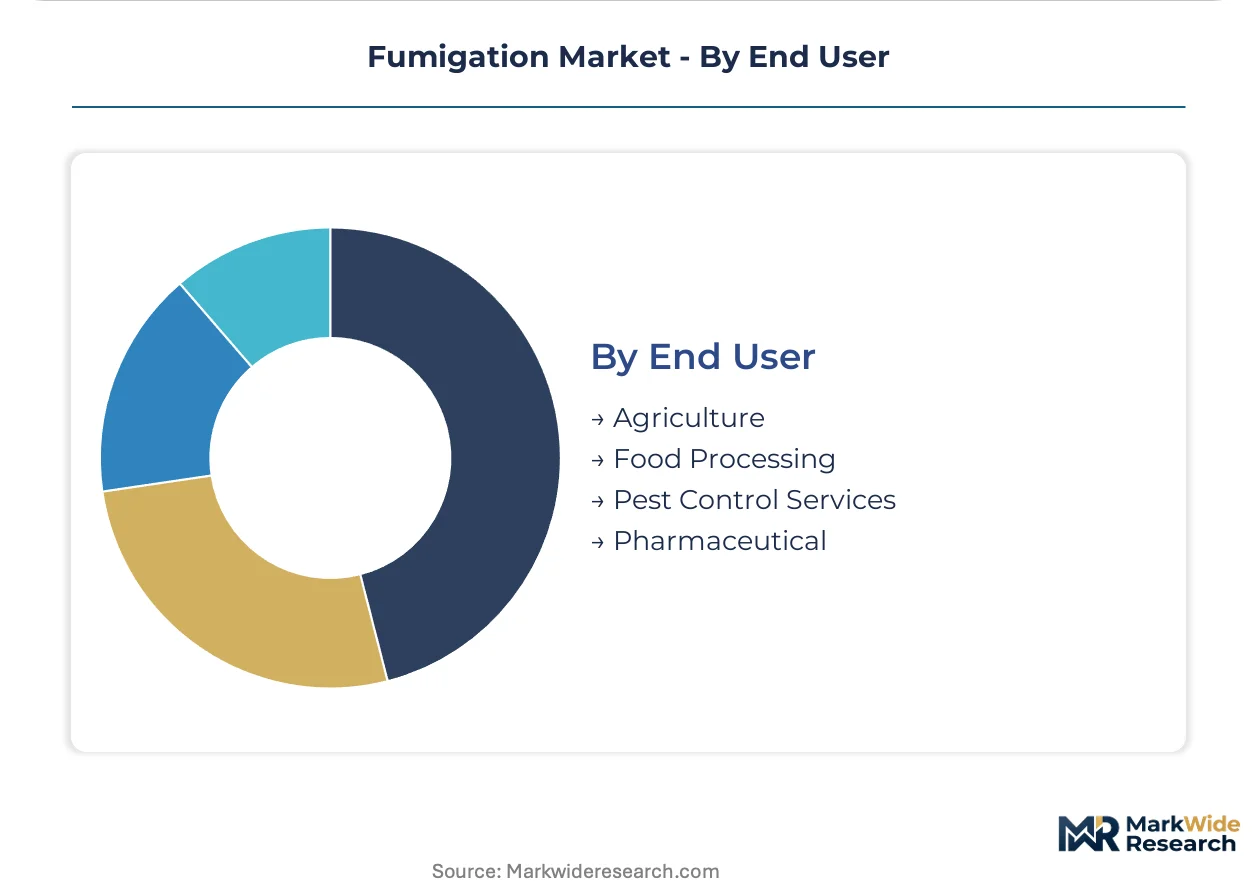
End User:
Customer archetypes span from price-sensitive bulk commodity handlers to compliance-driven pharmaceutical manufacturers.
- Agriculture:Farmers, cooperatives, and grain elevators managing pre-harvest and post-harvest pest pressure. Brazil's agricultural commodity exporters are expanding phosphine-based treatment adoption under ANVISA residue monitoring protocols.
- Food Processing:Milling, baking, and packaged goods facilities requiring ingredient protection and finished product integrity. FSSAI mandates in India drive warehouse fumigation upgrades across the grain storage corridor.
- Pest Control Services:Specialized contractors delivering structural and commodity treatment through certified technician networks. EPA FIFRA registration requirements govern operator certification and service delivery in the United States.
- Pharmaceutical:Manufacturers requiring sterile supply chains and documented treatment protocols for active ingredient protection. Stringent residue limits and documentation requirements elevate service specifications above agricultural norms.
Volume scale concentrates in agriculture; margin capture peaks with pharmaceutical contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA registration requirements under FIFRA anchor the United States as the regulatory benchmark for fumigant chemistry approval and operator certification standards. Treatment protocols established by this framework cascade through export-dependent economies seeking phytosanitary equivalence for commodity trade.
United States
Residential termite fumigation drives sulfuryl fluoride demand across Florida, California, and Gulf Coast states. EPA FIFRA mandates govern active ingredient registration and technician certification requirements. Structural fumigation contractors concentrate in Miami-Dade, Orange County, and Houston metro areas where humidity accelerates drywood pest pressure.
Brazil
Agricultural commodity exporters in São Paulo and Paraná states expand phosphine-based treatment adoption for soybean and corn export certification. ANVISA residue monitoring protocols require documented treatment records for cross-border shipments. Port facilities at Santos and Paranaguá process volume through integrated logistics contracts bundling fumigation with freight pricing.
India
FSSAI warehouse mandates drive phosphine system installations across Maharashtra, Gujarat, and Punjab grain storage corridors. The Central Insecticides Board requires product registration and operator licensing under the Insecticides Act. Large-scale grain handlers in Haryana deploy wireless sensor networks for real-time gas concentration monitoring.
Australia
Grain export phytosanitary requirements sustain phosphine treatment volumes for wheat and barley shipments to Asian markets. The country's national agricultural regulator enforces treatment documentation for FAO certification compliance. Bulk handlers in Western Australia and South Australia lead automated gas monitoring adoption.
Germany
Organic-certified grain segments in Bavaria and Lower Saxony adopt heat treatment systems where synthetic chemistry faces buyer rejection. REACH authorization timelines compress methyl bromide availability for remaining critical-use exemptions. Precision aeration technology investments concentrate in Stuttgart and Munich industrial zones.
Fumigation Market Vendor Landscape
Integrated pest management platforms and specialized structural fumigation contractors split the market along service bundling versus technical execution lines. The vendor base concentrates around three strategic archetypes: multinational facility management conglomerates with pest control divisions, regional specialists with certified technician networks, and technology-integrated service platforms bundling monitoring with treatment. Dominant competitive moves include M&A to consolidate port-zone service density and vertical integration into sensor hardware for automated gas management.
Among North American residential specialists, Terminix, Orkin, and Truly Nolen occupy positions anchored in technician-trained branch networks and geographic brand recognition. Rentokil represents the integrated facility management archetype with multi-service contract penetration across commercial and industrial segments. These players exemplify divergent strategic postures: scale-driven platform consolidation versus localized execution density.
| Leading Market Players |
|---|
| Ehrlich |
| Hawx |
| Terminix |
| Turner Pest Control |
| TruGreen |
| Orkin |
| Aptive |
| Truly Nolen |
| Rentokil |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese phosphine tablet manufacturing clusters is compressing export pricing power while simultaneously accelerating supplier consolidation around integrated formulation-to-distribution platforms. This utilization dynamic feeds directly into buyer procurement leverage across Indian and Brazilian grain storage corridors.
Pricing Analysis
Contract-based long-term offtake dominates pricing structures across port-zone fumigation services, with premium-mid-economy pricing differentiation anchored in certification grade and after-sales sensor monitoring bundling. Price compression runs through standard-tier phosphine applications as generic tablet suppliers multiply in Shandong and Jiangsu provinces. Bulk commodity handlers exhibit highest price sensitivity due to thin margins on grain storage operations, while pharmaceutical manufacturers accept premium positioning for documented residue compliance.
Supply Chain Analysis
Aluminum phosphide feedstock production concentrates in China, India, and Germany, with formulated tablets and pellets drawing from metal phosphide precursors, packaging films, and desiccant materials. Single-source vulnerability sits with Chinese export licensing delays that disrupt tablet availability during peak agricultural seasons. Distribution runs through regional chemical distributors serving certified fumigation contractors, with direct procurement relationships emerging among large-scale grain handlers seeking volume guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-based monitoring subscriptions and predictive analytics layers are expanding faster than hardware sales, converting one-time chemical transactions into recurring revenue streams across warehouse and shipping container applications.
For Market Incumbents: Pre-empt heat treatment substitution in organic-certified grain segments by embedding biopesticide vapor formulations within existing service contracts. Backward integration into phosphine tablet manufacturing insulates margin pressure from Chinese supply volatility while ANVISA and FSSAI documentation requirements tighten.
For New Entrants and Emerging Players: Pursue certified fumigator shortages in India's Punjab and Haryana grain corridors as the most penetrable white-space target, deploying technician training partnerships with state agricultural universities as the primary go-to-market angle. Essential oil vapor biopesticides for organic coffee and spice exporters offer secondary entry points with lower capital barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across automated gas monitoring hardware as sensor commoditization accelerates, shifting returns toward software and service layers. Acquisition targets should display dense port-zone contract books in Brazil or India, with wireless sensor network adoption rates serving as the signal to watch for operational inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphide Manufacturing | Captive supply of aluminum phosphide precursors insulates margin pressure from Chinese export licensing volatility. |
| Sensor Hardware Platform Integration | Wireless phosphine monitoring systems from Australian grain handlers create recurring revenue attachment to chemical sales. |
| Technician Certification Network Expansion | Licensed operator pipelines under India's Insecticides Act address service scheduling constraints in high-demand corridors. |
| Biopesticide Formulation Development | Essential oil vapor products open organic-certified commodity segments previously closed to synthetic chemistry. |
| Port-Zone Service Density Consolidation | Integrated logistics contracts at Santos and Paranaguá displace standalone fumigation relationships with bundled pricing. |
Methodological Framework
Operator-level perspectives from certified fumigation technicians, warehouse operations managers, phosphine tablet procurement leads, and port-zone logistics coordinators anchored the qualitative base. Secondary validation drew from EPA FIFRA registration databases, ANVISA residue monitoring protocols, FAO phytosanitary certification records, and customs trade data for aluminum phosphide formulations. Bottom-up service contract enumeration and top-down chemical consumption estimates were triangulated against regional grain storage capacity figures.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling treatment chemistry, application infrastructure, technology method, and end-user archetype as core segmentation dimensions. CAGRs were derived from volume trajectory analysis incorporating methyl bromide phase-out schedules, FSSAI mandate implementation timelines, and wireless sensor adoption curves among large-scale grain handlers.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity trade volumes, freight rate volatility, or currency fluctuations in Brazil and India would shift the trajectory. Cross-checking against FAO phytosanitary treatment documentation volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Poland Crop Protection Chemicals Market
Crop Protection
North America Acaricides Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
Argentina Crop Protection Chemicals Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
Pest Control Market
Crop Protection
Crop Bactericides Market
Crop Protection
US Pest Control Market
Crop Protection
Vietnam Fungicide Market
Crop Protection
Sweet Potato Fly Market
Crop Protection
Global Integrated Pest Management (IPM) Pheromones Market
Crop Protection
China Insecticide Market
Crop Protection
South Korea Crop Protection Chemicals Market
Crop Protection
IPM Pheromones Market
Crop Protection
Thailand Crop Protection Chemicals Market
Crop Protection
Generic Crop Protection Chemicals Market