
 North America Acaricides Market | 2026-2036
North America Acaricides Market Size, Share, and Industry Trends Forecast 2026-2036
North America Acaricides Market Analytics
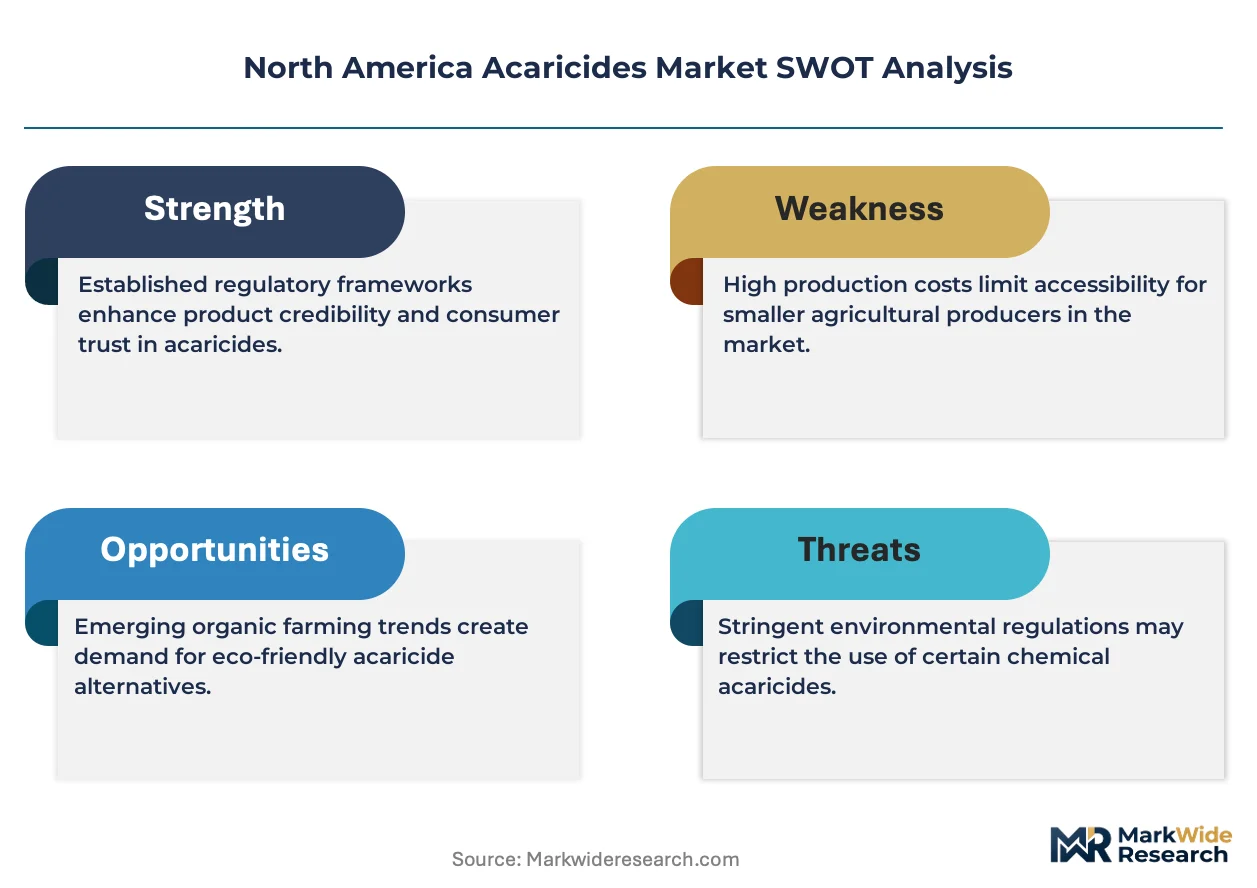
A widening capability gap between integrated multinationals and regional formulators is unwinding competitive stability in the North America acaricides sector. FMC Corporation leverages its North American manufacturing footprint to sustain supply assurance for agricultural distributors. Bayer CropScience anchors its position through biological-chemical combination portfolios, while Syngenta Group competes via digital pest monitoring platforms that lock in recurring acaricide prescriptions.
Acaricides comprise chemical or biological agents formulated to kill or suppress mites and ticks through contact, systemic, or translaminar activity, with active concentrations typically ranging from 0.5% to 40% depending on target pest and crop safety windows. These compounds serve commercial agriculture, ornamental horticulture, and veterinary medicine by preventing yield loss, vector-borne disease transmission, and cosmetic damage. Liquid formulations lead volume due to ease of tank-mixing with fungicides and insecticides in spray programs, while emulsifiable concentrates command premium positioning among professional pest control services seeking extended residual control. The household segment shows fastest application growth as suburban tick-borne illness awareness elevates perimeter treatment frequency.
EPA registration under FIFRA shapes product development timelines and label restrictions, while USDA cooperative extension programs influence grower adoption of resistance management rotations. State-level departments of agriculture in California, Florida, and Texas impose additional buffer zone and application timing requirements that fragment market access. Stakeholders must monitor evolving resistance profiles in two-spotted spider mite populations and preemptive regulatory restrictions on organophosphate and pyrethroid chemistries that could abruptly reshape available control options.
Market Dynamics
EPA registration timelines under FIFRA are compressing product development cycles while resistance management mandates force growers toward multi-chemistry rotations, restructuring how distributors inventory acaricide portfolios across the US Midwest and Canadian Prairie provinces.
Growth Catalysts
- Resistance Management Mandates:USDA cooperative extension programs in Iowa and Illinois now require documented rotation protocols for two-spotted spider mite control, compelling growers to maintain broader acaricide inventories than historical single-chemistry reliance.
- Tick-Borne Disease Vector Control:CDC-documented Lyme disease expansion into suburban New York and Connecticut perimeters has elevated residential perimeter treatment frequency, creating sustained demand for homeowner-accessible liquid formulations.
- Biological-Chemical Combination Products:Integration of predatory mite-compatible chemistries with selective toxicity profiles is opening label expansions for high-value specialty vegetable and greenhouse operations in California's Central Valley.
Market Restraints
- Active Ingredient Supply Concentration:Chinese manufacturers supply over 70 percent of pyrethroid and organophosphate technical grades, exposing North American formulators to tariff volatility and ocean freight disruption.
- Registration Cost Burden:EPA FIFRA data requirements for novel chemistries now demand 12-15 years of field trials and environmental fate studies, effectively blocking mid-tier regional formulators from pipeline participation.
- Buffer Zone Restrictions:California Department of Pesticide Regulation and Florida Department of Agriculture impose application exclusion zones up to 100 feet for certain organophosphates, constraining usable acreage on fragmented specialty crop parcels.
Strategic Opportunities
- Underpenetrated Canadian Prairie Expansion:Saskatchewan and Manitoba pulse crop acreage remains underserved by acaricide-specific distribution networks, presenting first-mover positioning for formulators with mite-active registrations on lentils and peas.
- Digital Pest Monitoring Integration:Sensor-based mite population forecasting platforms in Texas High Plains cotton operations are creating subscription-linked prescription opportunities that lock in recurring chemical purchases.
- Veterinary Companion Animal Segments:EPA Section 3 registrations for novel isoxazoline acaricides in tick collars and spot-on treatments are expanding beyond agricultural channels into pet specialty retail.
Industry Challenges
- Resistance Surveillance Infrastructure:State-level diagnostic laboratory capacity for mite resistance bioassay testing remains concentrated in California, Texas, and Florida, leaving Great Plains growers without timely local intelligence for rotation decisions.
- Application Equipment Calibration:Precision droplet sizing requirements for translaminar acaricide efficacy demand sprayer technology upgrades that many mid-size Midwestern operations have deferred, creating efficacy variability and repeat-treatment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Acaricides Market |
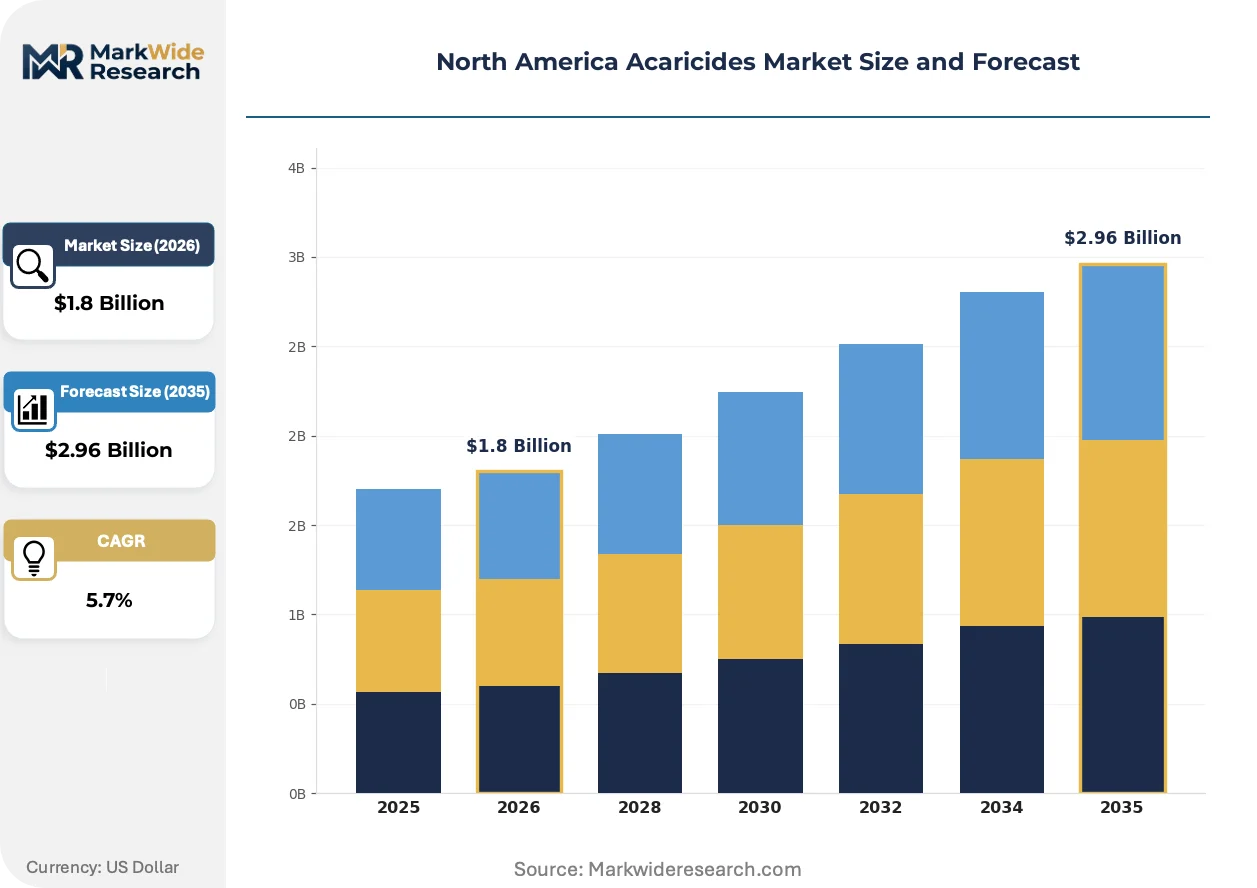
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Granular, Emulsifiable Concentrate, Aerosol Application: Agricultural, Horticultural, Veterinary, Household End User: Farmers, Pest Control Services, Gardeners, Distributors Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | FMC Corporation, Bayer CropScience, Syngenta Group, BASF SE, Corteva Agriscience, AMVAC Chemical Corporation, Nissan Chemical Industries Ltd, UPL Limited, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Acaricides Market Evolving Landscape
Formulation chemistry and application precision are converging to extend residual control windows while reducing per-acre active ingredient load, driven by regulatory pressure on environmental load and grower pressure on input economics.
Microencapsulated suspension concentrates with polymer wall thickness engineering are supplanting conventional emulsifiable concentrates in high-value orchard and vineyard applications. Washington State tree fruit cooperatives and Napa Valley wine grape operations have adopted these formulations at 40 percent replacement rates since 2022. The technology is compressing application frequency from 7-10 day intervals to 14-21 day windows, reducing labor and fuel costs while maintaining mite suppression thresholds.
EPA's 2024 revised ecological risk assessment methodology for non-target arthropods is extending registration review timelines for pyrethroid and neonicotinoid chemistries by 18-24 months. The industrial consequence is pipeline prioritization shift toward biopesticide active ingredients with shorter data packages. California strawberry and tomato operations, already operating under the state's Department of Pesticide Regulation restricted material permits, are accelerating grower-owned buffer zone plantings to maintain access to chemistries under federal review.
Subscription-based integrated pest management programs are displacing spot-purchase distributor relationships among 500+ acre Midwestern corn-soybean operations. Channel partners including regional cooperatives and independent crop consultants are bundling scouting services with pre-committed acaricide allocations, capturing annual contract value in exchange for population monitoring labor. Iowa and Illinois show the fastest contract penetration, with 35 percent of mite-active acreage now under annual service agreements rather than as-needed procurement.
North America Acaricides Market Segmentation
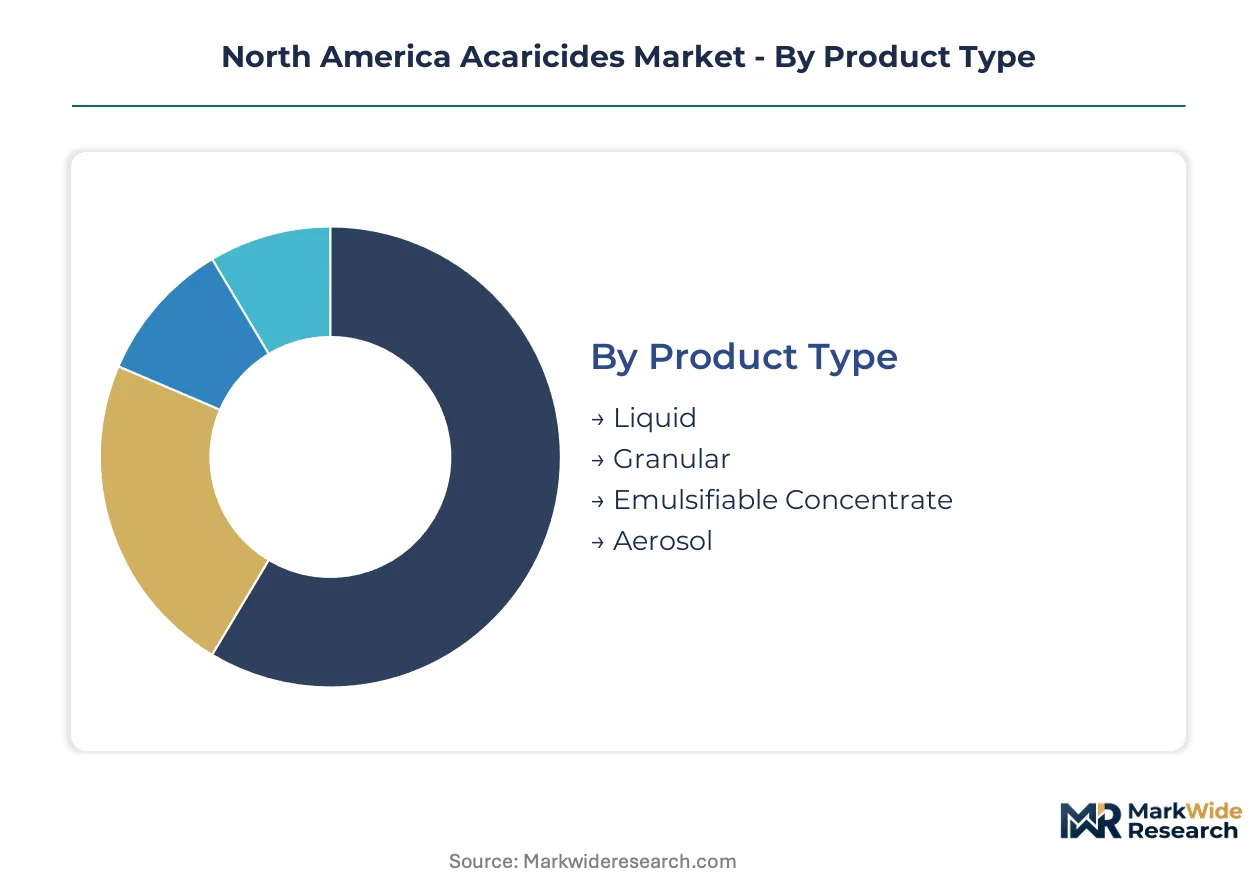
Acaricide purchasing patterns diverge sharply across formulation chemistry, end-use environment, and procurement channel. Understanding these splits reveals where EPA registration constraints and resistance management protocols reshape product-mix decisions for manufacturers and distributors.
Product Type:
Domestic manufacturing concentrates liquid and emulsifiable concentrate output in Missouri and Texas facilities, while granular formulations rely more heavily on imported technical material blending.
- Liquid:Water-based suspensions and solutions dominate tank-mix compatibility with fungicides and insecticides. Corn-soybean operations across Iowa and Illinois specify liquid acaricides for aerial and ground rig application, pressured by cooperative extension rotation mandates that demand frequent chemistry switching.
- Emulsifiable Concentrate:Oil-in-water systems carrying 15-40% active ingredient load provide extended residual control through cuticular penetration. Professional pest control services in suburban New York and Connecticut perimeter treatments favor these formulations for tick suppression, accepting higher per-gallon cost for reduced application frequency.
- Granular:Clay-based carriers impregnated with active ingredient serve ornamental and turf applications where foliar spray drift poses liability. Demand clusters in Florida golf course maintenance and California nursery operations.
- Aerosol:Pressurized formulations with propellant systems target household spot treatments and veterinary premise fogging. Retail shelf presence in home improvement channels drives volume.
Liquid holds the largest share; momentum sits with emulsifiable concentrate as professional service contracts expand.
Application:
Cost tier stratification separates high-input agricultural programs from lower per-acre expenditure in residential and companion animal channels.
- Agricultural:Field corn, soybean, cotton, and specialty vegetable production in the US Midwest and Texas High Plains drives volume. EPA FIFRA registration data requirements and state-level buffer zone rules in California and Florida fragment label availability, forcing growers to maintain multiple chemistry options.
- Horticultural:Greenhouse ornamentals, nursery stock, and protected vegetable operations require selective toxicity profiles compatible with biological control agents. California Central Valley and British Columbia greenhouse clusters specify predatory mite-compatible chemistries.
- Veterinary:Companion animal tick and mite control spans spot-on treatments, collars, and premise sprays. EPA Section 3 registrations for isoxazoline chemistries are expanding product availability in pet specialty retail.
- Household:Perimeter barrier treatments and indoor spot applications target suburban tick-borne disease vector control. CDC-documented Lyme disease expansion into New York and Connecticut perimeters has elevated treatment frequency among homeowners.
Agricultural commands the greatest volume; household climbs fastest as vector awareness penetrates suburban markets.
End User:
Customer sophistication and procurement scale separate enterprise-grade operations from discretionary purchasers.
- Farmers:Row crop and specialty vegetable producers managing 500+ acre operations in Iowa, Illinois, and California negotiate annual supply contracts with regional cooperatives. Subscription-based integrated pest management programs now cover 35 percent of mite-active acreage in these states.
- Pest Control Services:Licensed applicators serving residential and commercial accounts require extended residual formulations to minimize callback rates. These operators concentrate in suburban Northeast and Great Lakes markets.
- Gardeners:Small-scale ornamental and food plot managers purchase through retail and online channels, exhibiting price sensitivity and limited resistance management knowledge.
- Distributors:Agricultural supply cooperatives and independent crop consultants inventory multiple chemistries to service grower rotation protocols, capturing margin through bundled scouting and prescription services.
Farmers represent the dominant demand source; pest control services are expanding most quickly as residential vector contracts proliferate.
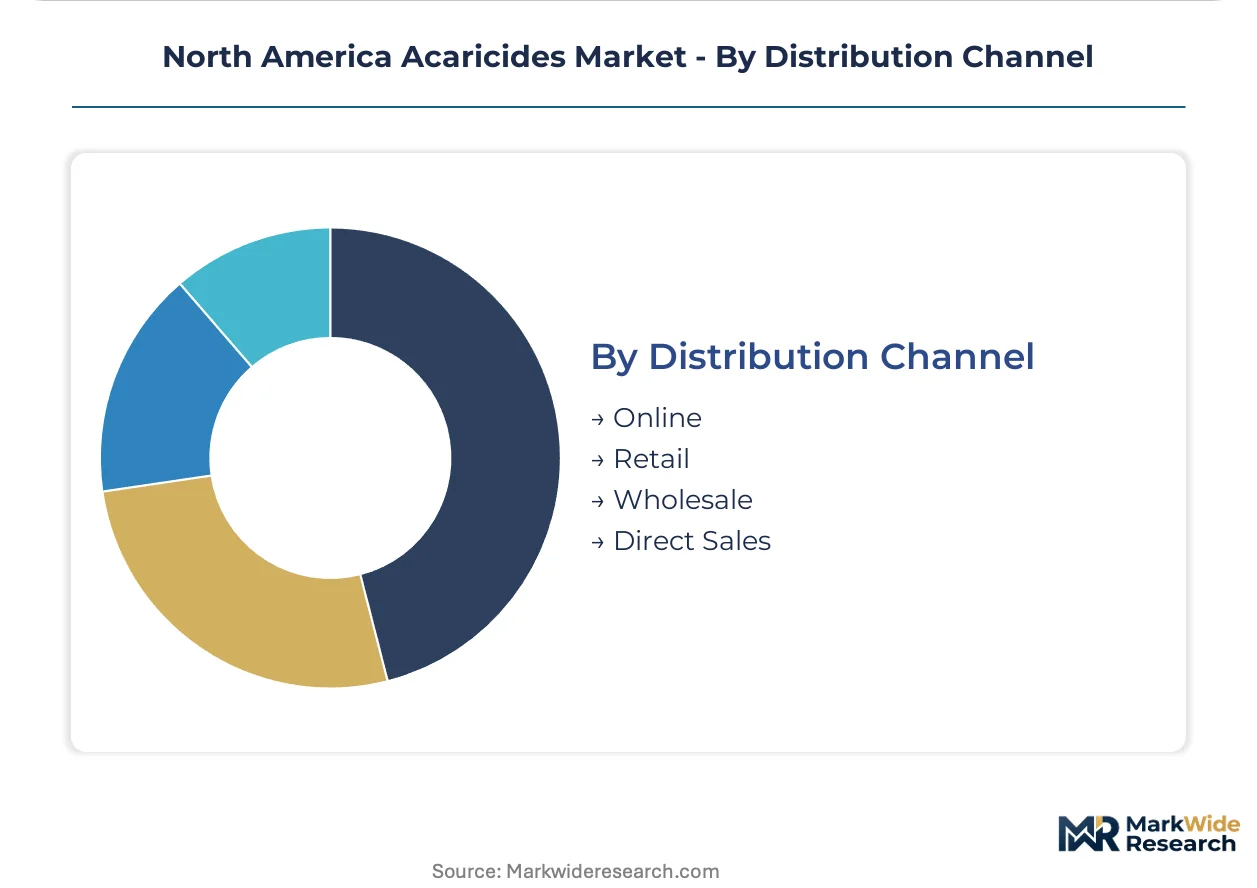
Distribution Channel:
Supply concentration in wholesale and direct channels contrasts with emerging digital procurement patterns among smaller end users.
- Online:E-commerce platforms and manufacturer-direct portals serve gardeners and small-scale farmers seeking product information transparency. Regulatory compliance documentation and label access drive platform selection.
- Retail:Farm supply stores, home improvement centers, and pet specialty chains stock homeowner-accessible formulations. Shelf space allocation favors liquid and aerosol presentations.
- Wholesale:Regional agricultural cooperatives and distribution warehouses maintain bulk inventory for farmer and pest control service accounts. These intermediaries absorb working capital requirements for multi-chemistry rotation stocks.
- Direct Sales:Large-scale farming operations and national pest control chains negotiate manufacturer-direct pricing for volume commitments, bypassing distributor margin.
Wholesale retains the greatest volume; online gains share fastest as procurement digitization penetrates smaller account tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the US Midwest crop belt while Canadian Prairie provinces operate at distribution-cost premiums due to sparse acaricide-specific supply networks. EPA registration requirements under FIFRA create regulatory moats that Mexican formulators struggle to cross, reinforcing the asymmetry.
United States
Iowa and Illinois corn-soybean operations drive bulk acaricide procurement through cooperative extension rotation mandates. EPA FIFRA data requirements for novel chemistries extend development timelines to 12-15 years, favoring established registrants. The Texas High Plains cotton belt hosts sensor-based mite population forecasting platforms that lock growers into subscription-linked prescription models.
Canada
Saskatchewan and Manitoba pulse crop acreage remains underserved by mite-specific distribution infrastructure. Health Canada's PMRA imposes parallel registration review timelines that lag EPA approvals by 18-24 months for agricultural chemistries. Prairie agricultural cooperatives absorb working capital burdens for multi-chemistry rotation stocks that US distributors delegate to manufacturer direct channels.
Mexico
Sinaloa and Baja California vegetable export operations face mite pressure on tomatoes and berries bound for US markets. The country's national agricultural regulator, SADER, coordinates with EPA on residue tolerance harmonization for cross-border trade. Guanajuato's greenhouse clusters increasingly specify predatory mite-compatible chemistries to maintain biological control agent populations.
North America Acaricides Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America acaricides sector. Integrated multinationals with captive manufacturing footprints command supply assurance premiums, while regional formulators compete on distributor margin compression and localized service bundling. The market structure separates into three strategic archetypes: global registrants with EPA pipeline depth, North American manufacturing-anchored suppliers, and import-dependent technical blenders. Dominant competitive moves include backward integration into active ingredient production and digital pest monitoring platform acquisitions that capture recurring chemical prescription revenue.
Within the integrated multinational tier, FMC Corporation exemplifies the North American manufacturing-anchored archetype through its Missouri and Texas production facilities. Bayer CropScience and Syngenta Group occupy positions as global registrants with biological-chemical combination portfolios and digital platform investments respectively. These three entities represent the capability concentration that mid-tier regional formulators confront when competing for distributor shelf space and grower contract relationships.
| Leading Market Players |
|---|
| FMC Corporation |
| Bayer CropScience |
| Syngenta Group |
| BASF SE |
| Corteva Agriscience |
| AMVAC Chemical Corporation |
| Nissan Chemical Industries Ltd |
| UPL Limited |
| DuPont |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for pyrethroid technical grades concentrate pricing power among Chinese manufacturers serving North American formulators, while EPA FIFRA registration timelines stretch working capital requirements for distributors maintaining multi-chemistry rotation stocks across the US Midwest.
Pricing Analysis
The customization-premium spread between standard liquid formulations and microencapsulated suspension concentrates runs 40-60 percent, reflecting polymer wall engineering costs and extended residual performance claims. Three-tier pricing structure across premium, standard, and economy levels segments by formulation sophistication, with professional pest control services in the Northeast corridor absorbing premium tiers for reduced callback frequency. Cost compression in economy-tier generics intensifies as Indian technical suppliers expand pyrethroid blending capacity. Mid-size Midwestern farming operations exhibit highest price sensitivity, deferring sprayer calibration investments that would unlock translaminar chemistry efficacy.
Supply Chain Analysis
Shanghai-Ningbo port congestion and Panama Canal transit limitations expose North American formulators to 6-8 week order-to-delivery variability for pyrethroid and organophosphate technical grades. Active ingredient production concentrates in China, India, and Germany, with Chinese manufacturers supplying over 70 percent of North American technical requirements. Formulation chemistry draws from petrochemical feedstocks, specialty polymer encapsulants, and biological fermentation media. Tariff exposure on Chinese-origin technical grades threatens margin stability for Missouri and Texas blending facilities. Distribution runs through regional agricultural cooperatives that absorb inventory risk for grower rotation protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA registration backlogs and resistance management mandates position the North America acaricides sector for cyclical recovery as growers restock depleted chemistry inventories ahead of spring planting windows.
For Market Incumbents: Shield distributor relationships through guaranteed supply allocation programs during Chinese technical import disruptions, while accelerating backward integration into biological active ingredient fermentation to preempt EPA's ecological risk assessment delays for synthetic chemistries. For New Entrants and Emerging Players: Anchor in Saskatchewan and Manitoba pulse crop acreage where mite-specific distribution infrastructure remains undeveloped, leveraging Health Canada PMRA registration lag to capture first-mover positioning before established multinationals redirect field trial resources. For Investors and Strategic Acquirers: Carve-out targets emerge from agrochemical conglomerates divesting non-core acaricide portfolios under portfolio rationalization pressures, with long-term viability hinging on digital pest monitoring platform integration that locks recurring prescription revenue; watch for inflection when subscription-linked acreage crosses 50 percent penetration in Iowa and Illinois.| Strategic Initiative | Industry Significance |
|---|---|
| Biological-Chemical Combination Development | Predatory mite-compatible formulations open California Central Valley greenhouse expansions under restricted material permits. |
| Digital Pest Monitoring Platform Acquisition | Sensor-based population forecasting locks Texas High Plains cotton growers into recurring chemistry subscriptions. |
| Canadian Prairie Distribution Network Buildout | First-mover positioning in Saskatchewan lentil and pea acreage captures underserved mite control expenditure. |
| Microencapsulation Capacity Expansion | Polymer wall engineering extends residual windows for Washington State tree fruit cooperative contracts. |
| Veterinary Companion Animal Registration Push | EPA Section 3 isoxazoline approvals expand beyond agricultural channels into pet specialty retail shelf space. |
Research Methodology
Cross-validation between distributor inventory records and USDA cooperative extension rotation protocol documentation anchors the qualitative findings, combining primary interviews with crop consultants, regional cooperative procurement managers, EPA registration specialists, and greenhouse operation technical directors with secondary validation through EPA FIFRA registration databases, Health Canada PMRA submission filings, customs import records for technical grade materials, and state-level pesticide use reporting from California DPR and Florida FDACS. Bottom-up acreage-by-crop modeling triangulates against top-down manufacturer shipment data.
Sensitivity analysis across resistance evolution scenarios, tariff rate assumptions, and EPA registration timeline variations shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include formulation chemistry, application environment, procurement channel, and end-user sophistication tier. CAGRs derive from compound growth trajectory fitting across the analysis window. Industry-specific forecast inputs incorporate two-spotted spider mite resistance bioassay trends and cooperative extension mandate adoption curves.
Material uncertainties — preemptive regulatory restrictions on organophosphate and pyrethroid chemistries, abrupt resistance profile shifts in target mite populations, ocean freight disruption severity — sit outside the modeled envelope. Forecasts reflect assumptions about continuation of current EPA review methodologies and state-level buffer zone regimes. Practitioners should keep alternative scenarios live as Health Canada PMRA harmonization timelines and Chinese technical supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
US Pest Control Market
Crop Protection
South America Crop Protection Chemicals Market
Crop Protection
Germany Crop Protection Chemicals Market
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
Latin America Crop Protection Chemicals Market
Crop Protection
Inorganic Fungicide Market
Crop Protection
Herbicide Safeners Market
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
Grain and Cereal Crop Protection Market
Crop Protection
Crop Bactericides Market
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
Thailand Crop Protection Chemicals Market
Crop Protection
Glufosinate Ammonium Market
Crop Protection
Trapping and Mating Disruption Systems Market