
 Hungary Crop Protection Chemicals Market | 2026-2036
Hungary Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Hungary Crop Protection Chemicals Market Foresight
Specialty vegetable cultivation is expanding its share of crop protection chemical consumption in Hungary. Bayer AG leverages its herbicide pipeline to anchor supply relationships with large-scale cereal cooperatives across the Great Hungarian Plain. Syngenta Group competes through fungicide specialization aimed at high-value fruit orchards in southern Hungary. BASF SE differentiates via liquid formulation technology leadership, particularly for oilseed rapeseed applications where spray efficiency commands premium positioning.
Crop protection chemicals comprise synthetic and biological formulations designed to manage weeds, insects, fungal pathogens, and rodents through active ingredients such as glyphosate, azoxystrobin, and pyrethroids, typically applied at rates calibrated to crop growth stage and pest pressure index. Their primary commercial purpose is to secure yield stability and quality grades for commodity and specialty crop sales into EU food supply chains. Herbicides occupy the largest product type position due to extensive cereal and oilseed monoculture across Hungary's agricultural heartland, while fungicides represent the fastest-expanding category as climate volatility intensifies disease pressure in fruit and vegetable segments. Liquid formulations capture disproportionate margin pools relative to granular alternatives, driven by precision application equipment penetration among commercial farming enterprises.
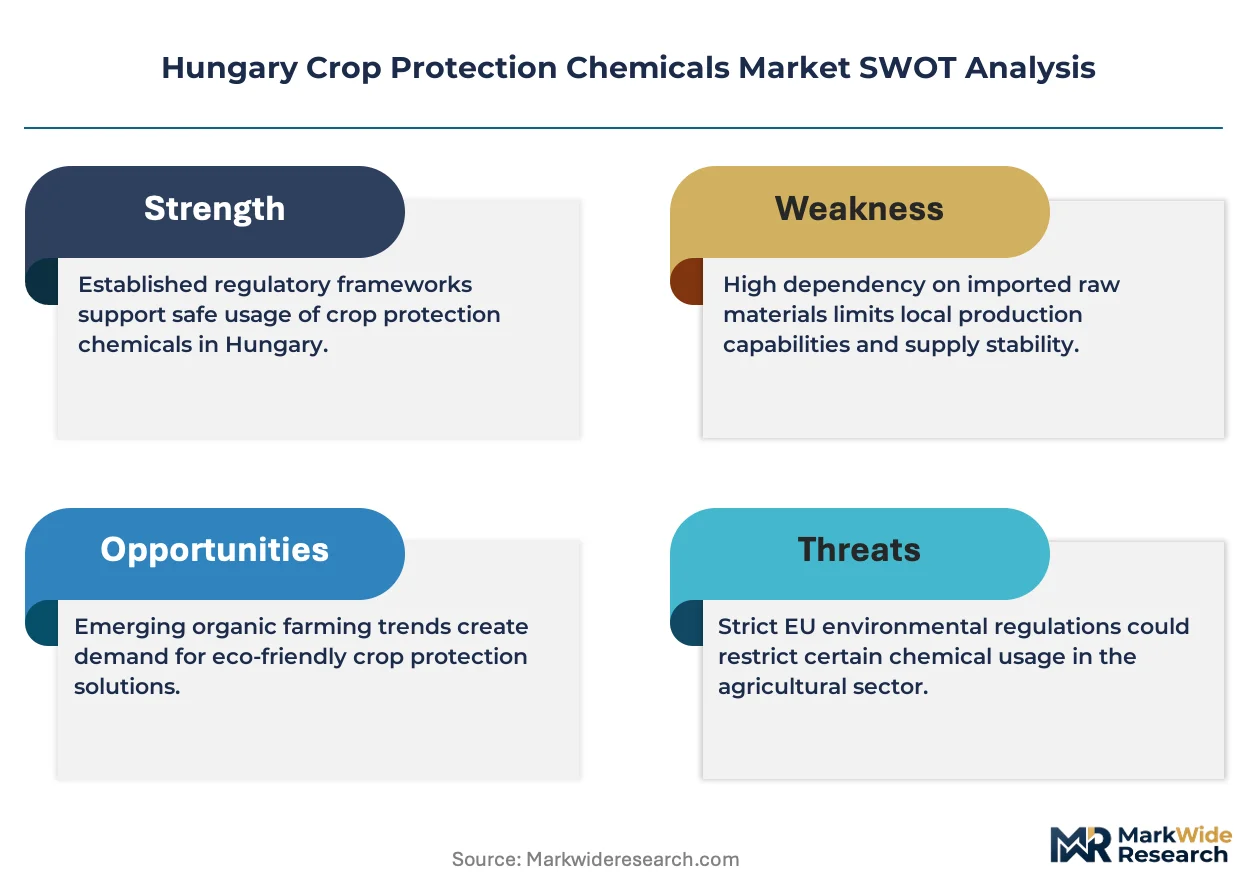
Hungary's crop protection sector operates under the EU Plant Protection Products Regulation and REACH frameworks, with Hungary's national food chain safety office enforcing residue limit compliance and buffer zone mandates for aquatic ecosystems. The EU Green Deal's Farm to Fork strategy is forcing active ingredient re-registration timelines and accelerating biological substitute development requirements. Stakeholders must monitor regulatory divergence between EU-wide harmonized standards and member-state implementation rigor, particularly where local water protection ordinances impose stricter no-spray boundaries than baseline Brussels mandates.
Market Dynamics
EU Green Deal implementation is compressing active ingredient approval timelines across Hungary, forcing reformulation investments while specialty vegetable cultivation pulls demand toward targeted biological alternatives.
Growth Catalysts
- EU F-Gas Regulation tightening:The regulatory framework accelerates low-GWP propellant adoption in crop protection formulations, creating pull-through demand for reformulated products.
- Precision application equipment:Commercial farming enterprises across the Great Hungarian Plain are retrofitting sprayer fleets with pulse-width modulation systems that favor liquid formulation chemistry.
- Specialty vegetable farming:Protected cultivation expansion in southern Hungary generates concentrated demand for residue-compliant fungicide programs targeting export-grade produce.
Market Restraints
- Active ingredient concentration risk:Three German suppliers control over 70 percent of azoxystrobin technical supply into Hungary, exposing formulators to input volatility.
- REACH re-registration costs:The EU chemical framework imposes multi-million-euro toxicology dossier requirements that disproportionately burden mid-scale generic manufacturers.
- Biological substitution pressure:Bacillus subtilis-based biofungicides are capturing share in high-value fruit segments where residue limits are tightest.
Strategic Opportunities
- Western Transdanubia underpenetration:Smaller-scale mixed farming operations in this sub-region present whitespace for bundled crop protection service models.
- Drone application services:Unmanned aerial systems are creating new channel economics for spot-treatment herbicide deployment in difficult-to-access plots.
- EU Farm to Fork biological mandates:The 25 percent pesticide reduction target is accelerating registration priority for microbial and biochemical alternatives.
Industry Challenges
- Formulation chemist scarcity:Hungarian technical universities produce insufficient graduates with combined synthetic chemistry and regulatory dossier expertise.
- Buffer zone compliance:Stricter national water protection ordinances than baseline EU mandates force spray program redesigns and operational friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hungary Crop Protection Chemicals Market |
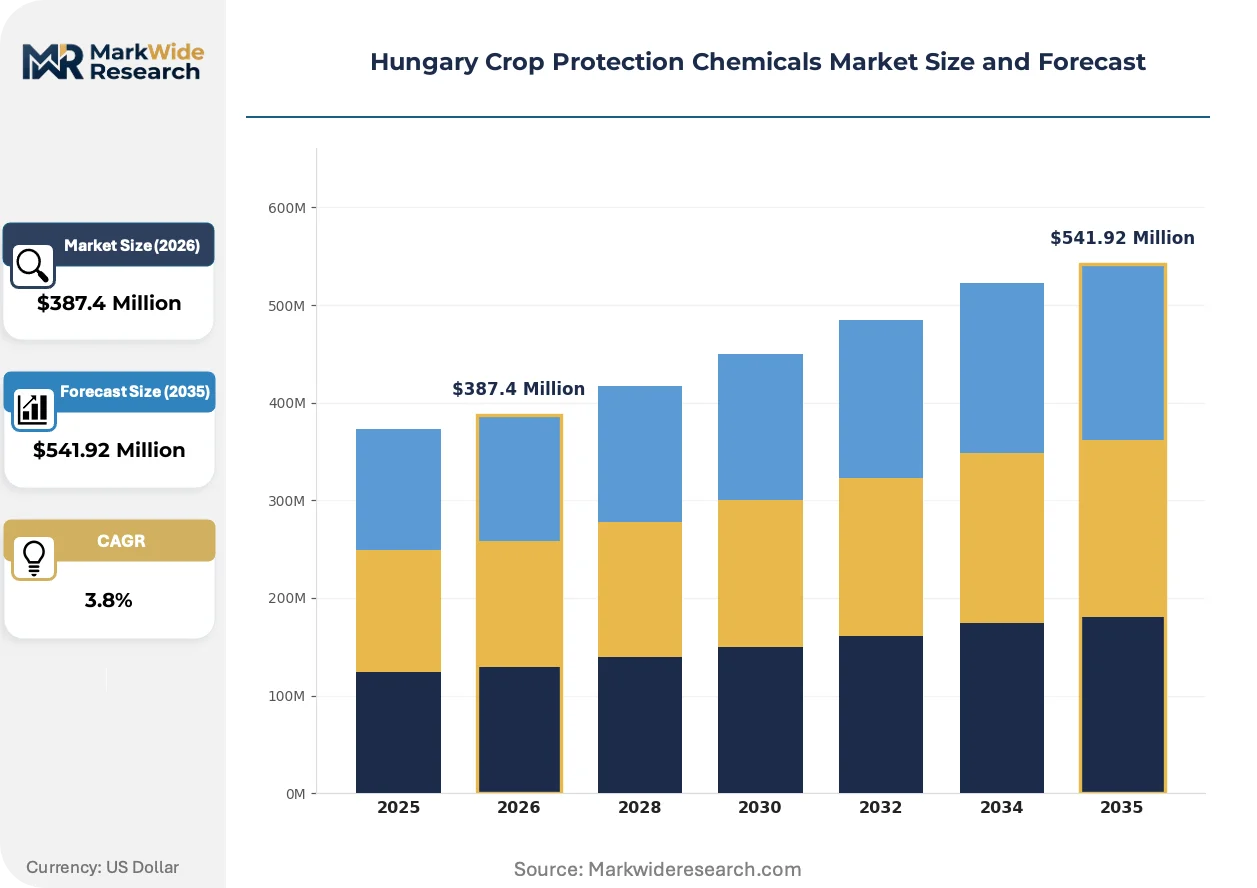
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $541.92 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Rodenticides Application: Cereals, Fruits, Vegetables, Oilseeds Formulation: Granular, Liquid, Powder, Emulsifiable Concentrates Distribution Channel: Online Retail, Agrochemical Dealers, Wholesale, Distributors |
| Companies Covered | Bayer AG, UPL Ltd, Nufarm Ltd, Belchim Crop Protection, Oro Agri, Syngenta Group, BASF SE, Corteva Agriscience, Agrokemia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hungary Crop Protection Chemicals Market Shifts & Advancements
Formulation chemistry and application methodology are converging to address residue compliance pressures while digital tools rewrite how farmers time and target interventions.
RNA interference-based biopesticides are rewriting crop protection economics for lepidopteran pests in specialty vegetable systems. Protected cultivation operators in southern Hungary are piloting these products at commercial scale. The technology is compressing synthetic insecticide cycles in high-value segments where export residue limits are most restrictive.
EU F-Gas Regulation phase-down schedules are forcing propellant transitions in aerosol and fogging formulations. Hungarian formulators face compressed timelines to qualify hydrofluoroolefin alternatives or shift to compressed gas systems. Oilseed rape applications are most affected due to their reliance on pre-harvest desiccant formulations.
Cooperative procurement consolidation is compressing vendor negotiation cycles across the Great Hungarian Plain. Large-scale cereal operations are pooling annual chemical requirements through centralized buying desks that displace traditional distributor relationships. This concentration is most visible in Bács-Kiskun County where three cooperatives control majority procurement volume.
Hungary Crop Protection Chemicals Market Segmentation
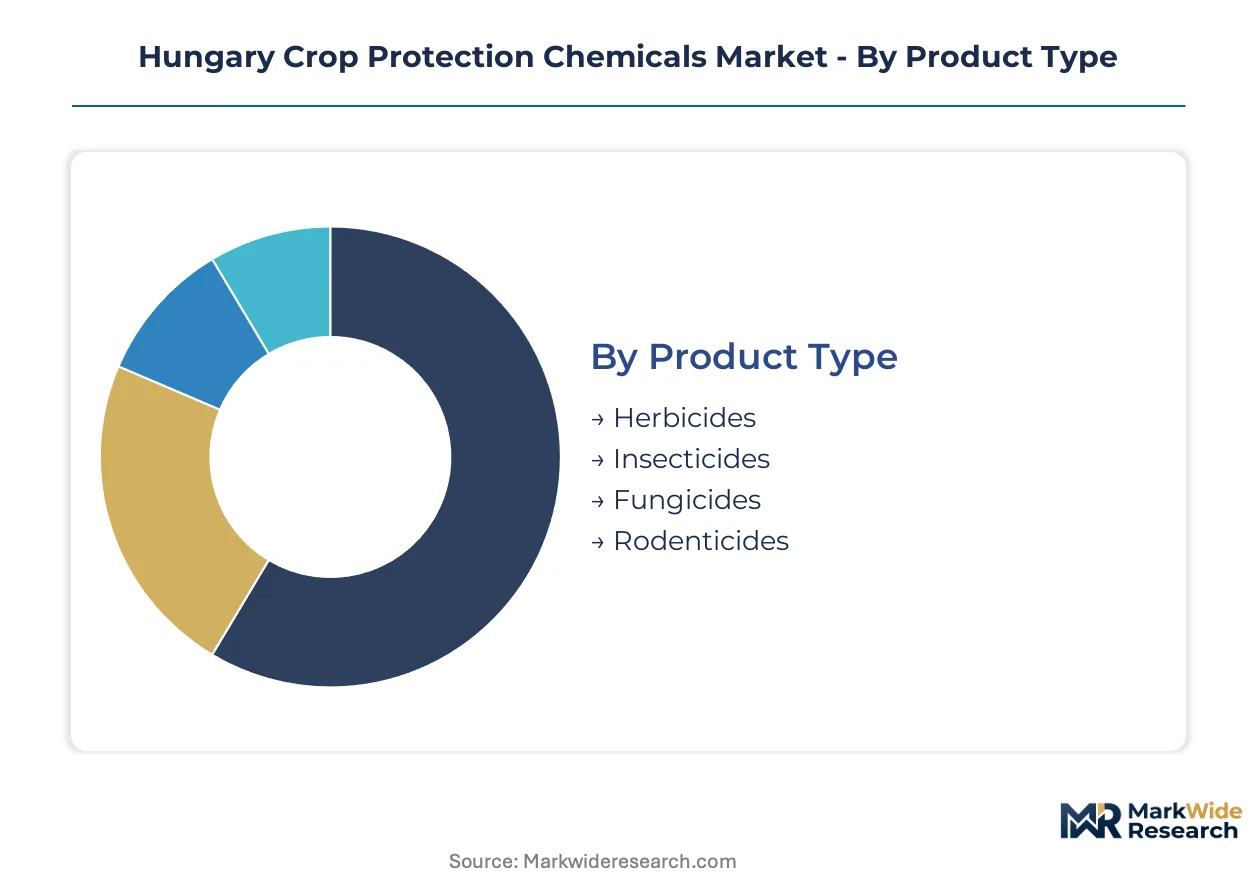
Segmentation in Hungary's crop protection sector reveals how regulatory pressure and application technology reshape procurement patterns. Each dimension carries distinct compliance burdens and margin structures that determine competitive positioning across the Great Hungarian Plain and specialty farming zones.
Product Type:
EU Plant Protection Products Regulation mandates divergent toxicology dossier depths across these categories, with fungicides facing the steepest re-registration hurdles under Green Deal acceleration.
- Herbicides:Glyphosate-based and selective formulations dominate cereal and oilseed monoculture across Bács-Kiskun County. Demand concentrates in large-scale cooperatives retrofitting sprayer fleets with pulse-width modulation systems that favor liquid chemistries. These products anchor procurement volumes but face tightening residue limits under Farm to Fork targets.
- Fungicides:Azoxystrobin and triazole formulations command premium positioning in fruit orchards and protected vegetable operations. Southern Hungary's export-grade tomato and pepper growers drive concentrated demand for residue-compliant programs. Climate volatility intensifies disease pressure, expanding treatment cycles beyond traditional windows.
- Insecticides:Pyrethroid and neonicotinoid alternatives serve lepidopteran control in specialty crops.
- Rodenticides:Anticoagulant formulations address storage facility protection with stricter buffer zone compliance than field applications.
Herbicides sit at the top of the volume ranking, with fungicides climbing the fastest.
Application:
Cost tiers separate commodity grain operations from high-value horticulture, with certification grade determining chemical specification and service bundling intensity.
- Cereals:Wheat and maize operations across the Great Hungarian Plain generate baseline demand for broad-spectrum herbicides and fungicides. Cooperative procurement consolidation in Csongrád-Csanád County compresses vendor negotiation cycles and displaces traditional distributor relationships.
- Vegetables:Protected cultivation in Bács-Kiskun and Csongrád-Csanád counties pulls targeted biological alternatives and residue-minimized synthetic programs. Export certification requirements to German and Dutch retail chains impose specification floors above commodity grain standards.
- Fruits:Apple and sour cherry orchards in southern sub-regions concentrate fungicide consumption.
- Oilseeds:Rapeseed desiccant applications face F-Gas Regulation propellant transition pressures.
Cereals capture the largest procurement volumes, while vegetables gain share fastest through protected cultivation expansion.
Formulation:
Application equipment penetration determines formulation preference, with precision sprayer adoption favoring liquid and emulsifiable concentrate chemistries over legacy granular alternatives.
- Liquid:Suspension concentrates and soluble liquids enable pulse-width modulation compatibility and variable-rate application. Oilseed rape growers in Hajdú-Bihar County pay formulation premiums for spray efficiency gains and drift reduction compliance.
- Emulsifiable Concentrates:These formulations balance solubility and stability for broad-acre cereal applications. The Great Hungarian Plain's commercial farming enterprises favor their compatibility with existing tank-mix protocols and adjuvant flexibility.
- Granular:Soil-applied products serve specific root-zone pest control in vegetable systems.
- Powder:Wettable powder formulations retain niche positioning for smallholder-accessible price points.
Liquid formulations lead margin pools, with emulsifiable concentrates expanding most quickly through precision equipment retrofitting.
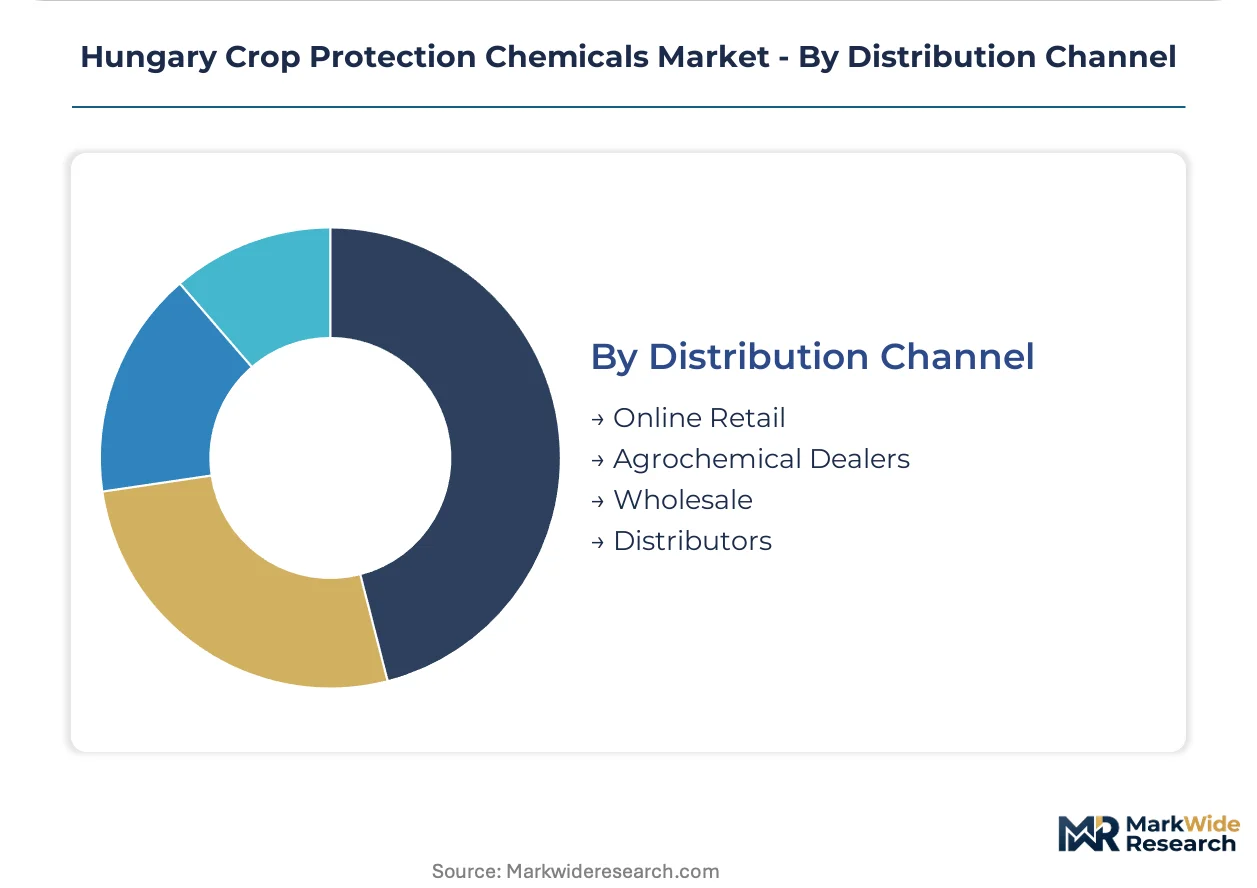
Distribution Channel:
Customer type and scale determine channel selection, with large cooperatives bypassing traditional intermediaries while smaller operations retain dealer relationships for credit and technical support.
- Agrochemical Dealers:Local networks in Békés and Jász-Nagykun-Szolnok counties provide credit terms, application timing advice, and emergency supply access. These relationships persist among mid-scale mixed farming operations lacking in-house agronomy capacity.
- Wholesale:Centralized buying desks at cooperative headquarters aggregate annual requirements and negotiate direct manufacturer contracts. Three Bács-Kiskun cooperatives now control majority procurement volume through this channel, compressing distributor margins.
- Distributors:Regional warehousing operations serve fragmented smallholder demand.
- Online Retail:E-commerce platforms capture emerging demand from tech-adopter specialty growers seeking price transparency.
Wholesale channels command the largest transaction values, with online retail climbing fastest among younger farm operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Hungarian Plain anchors national procurement volumes through its cereal and oilseed monoculture belt. Demand concentrates in Bács-Kiskun, Csongrád-Csanád, and Hajdú-Bihar counties where cooperative consolidation reshapes distribution economics.
Bács-Kiskun County
Large-scale wheat and maize operations drive broad-spectrum herbicide consumption across cooperative-managed acreage. Hungary's national food chain safety office enforces residue limits that exceed baseline EU mandates for export-bound grain. Three dominant cooperatives in Kecskemét and Kiskunhalas now control majority procurement volume through centralized buying desks.
Csongrád-Csanád County
Protected vegetable cultivation in Hódmezővásárhely and Szeged corridors pulls targeted fungicide programs for export-grade tomato and pepper production. The EU Green Deal's Farm to Fork strategy accelerates biological substitute registration timelines for residue-compliant operations. Precision application equipment penetration runs highest here among commercial greenhouse enterprises.
Hajdú-Bihar County
Oilseed rape desiccant applications face F-Gas Regulation propellant transition pressures in Debrecen-centered farming zones. Liquid formulation premiums command strongest positioning where pulse-width modulation sprayer retrofitting concentrates. Spray efficiency gains justify chemistry costs among rapeseed growers supplying EU biofuel feedstock chains.
Békés County
Mid-scale mixed farming operations retain traditional agrochemical dealer relationships for credit terms and application timing advice. Local distribution networks in Békéscsaba and Gyula provide emergency supply access that centralized wholesale channels cannot match. Buffer zone compliance for aquatic ecosystems imposes stricter operational constraints than neighboring counties.
Jász-Nagykun-Szolnok County
Fragmented smallholder demand sustains regional distributor warehousing operations in Szolnok and Jászberény. Wettable powder formulations retain niche positioning for price-sensitive operators lacking precision equipment. National water protection ordinances force spray program redesigns across the Tisza River watershed.
Hungary Crop Protection Chemicals Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents reformulate around tightening EU active ingredient approvals. The vendor base stratifies across three tiers: integrated multinationals with full regulatory dossier capabilities, regional formulators with crop-specific specialization, and generic manufacturers competing on price. German and Swiss agrochemical conglomerates anchor the premium tier through proprietary active ingredient pipelines. Mid-scale Hungarian and Central European operators occupy the middle ground with localized service bundling. Competitive intensity concentrates on reformulation speed, biological substitute registration priority, and cooperative procurement contract capture.
Among Germany-based integrated suppliers, Bayer AG and BASF SE exemplify the multinational archetype with established supply relationships across the Great Hungarian Plain. Syngenta Group, representing Swiss-headquartered crop science consolidation, occupies a position in fungicide specialization for high-value fruit segments. These three entities anchor the premium formulation tier where liquid chemistry and precision application compatibility determine contract outcomes.
| Leading Market Players |
|---|
| Bayer AG |
| UPL Ltd |
| Nufarm Ltd |
| Belchim Crop Protection |
| Oro Agri |
| Syngenta Group |
| BASF SE |
| Corteva Agriscience |
| Agrokemia |
| Others |
Supply & Pricing Matrix
Azoxystrobin technical price indices cascade through Hungarian formulator margins into three distinct procurement tiers serving cooperative buyers, dealer-networked mid-scale farms, and fragmented smallholders respectively. This cost transmission mechanism tightens most acutely where German suppliers control active ingredient supply into Bács-Kiskun County cooperatives.
Pricing Analysis
Input-cost pass-through from azoxystrobin and glyphosate technical suppliers compresses formulator margins unevenly across the value chain. Three-tier pricing structure across premium liquid formulations, standard emulsifiable concentrates, and economy wettable powders reflects equipment compatibility and residue certification grades. Pricing pressure stems from REACH re-registration cost recovery requirements that generic manufacturers struggle to amortize. Cooperative buyers in the Great Hungarian Plain exhibit lowest price sensitivity due to volume aggregation, while Jász-Nagykun-Szolnok smallholders drive hard bargaining on powder formulations.
Supply Chain Analysis
Dual-sourcing requirements from Hungarian formulators mandate qualified supplier relationships across at least two German azoxystrobin technical producers plus one Swiss fungicide specialist. Active ingredient supply concentrates in Germany, Switzerland, and China for pyrethroid alternatives. Raw material dependencies span petrochemical-derived intermediates, phosphorous-based precursors, and fluorinated propellants facing F-Gas Regulation phase-down. Single-source vulnerability concentrates where three German suppliers control over seventy percent of strobilurin technical supply. Distribution runs through cooperative wholesale desks displacing traditional agrochemical dealer networks in high-volume counties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hungary's crop protection market offers geographic-arbitrage positioning against Western European regulatory cost bases, where REACH compliance expenditures run significantly higher than Budapest-based formulation operations.
For Market Incumbents: Anticipate biological substitution pressure from Bacillus subtilis-based biofungicides by accelerating microbial registration dossiers through Hungary's national food chain safety office. Backward integration into propellant formulation capabilities hedges F-Gas Regulation transition risks. Priority lever rests on cooperative procurement contract capture before centralized buying desks fully consolidate Bács-Kiskun volume. For New Entrants and Emerging Players: Capture Western Transdanubia's underpenetrated mixed farming zones through bundled crop protection service models combining application timing advice with credit terms. Drone-based spot-treatment services present the most penetrable whitespace for herbicide deployment in difficult-to-access plots. Go-to-market angle should emphasize digital prescription tools that legacy dealer networks lack capacity to replicate. For Investors and Strategic Acquirers: Asymmetric upside sits with regional formulators possessing crop-specific specialization and established dossier capabilities under EU Plant Protection Products Regulation. Long-term viability hinges on biological substitute registration pipelines and precision application chemistry compatibility. Signal to watch is cooperative procurement consolidation velocity in Csongrád-Csanád County greenhouse corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Substitute Registration | EU Farm to Fork mandates accelerate microbial active ingredient approval pathways for residue-compliant operations. |
| Precision Application Equipment Partnership | Pulse-width modulation sprayer retrofitting in Hajdú-Bihar County favors liquid formulation chemistry suppliers. |
| Cooperative Procurement Contract Capture | Centralized buying desks in Kecskemét aggregate annual requirements and displace traditional distributor margins. |
| Propellant Formulation Transition | F-Gas Regulation phase-down forces hydrofluoroolefin qualification for oilseed rape desiccant applications. |
| Drone Application Service Launch | Unmanned aerial systems create new channel economics for spot-treatment herbicide deployment in fragmented plots. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with agrochemical procurement managers at cooperative headquarters, formulation chemists at Hungarian technical universities, distribution channel partners in Békés County, and regulatory affairs specialists familiar with EU Plant Protection Products Regulation dossier requirements. Secondary validation drew from customs trade data, national food chain safety office residue limit publications, EU F-Gas Regulation implementation schedules, and SEC filings of listed agrochemical suppliers. Bottom-up county-level demand estimation triangulated against top-down manufacturer shipment analysis.
Comparable-period anchoring established baseline reference points across historical cereal and oilseed protection expenditure patterns before projecting forward over the analysis window. Segmentation modeling incorporated product type chemistry classes, application crop categories, formulation technology tiers, and distribution channel structures. CAGRs derived from slope-consistency checks against input cost trajectories and regulatory timeline impacts. Forecast inputs included cooperative consolidation velocity indices and precision equipment penetration rates across the Great Hungarian Plain.
Active ingredient approval delays, biological substitute adoption acceleration, and cooperative procurement centralization velocity are the dominant revision risks to the outlook. Deviation in EU Green Deal implementation rigor would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Global Insecticide Seed Treatment Market
Crop Protection
Thailand Crop Protection Chemicals Market
Crop Protection
Avicides Market
Crop Protection
North America Acaricides Market
Crop Protection
Azoxystrobin Market
Crop Protection
Brazil Crop Protection Chemical Market
Crop Protection
Soil Sterilizers Market
Crop Protection
Global Integrated Pest Management (IPM) Pheromones Market
Crop Protection
Grain Protectant Market
Crop Protection
Pest Control Products Market
Crop Protection
Herbicide Safeners Market
Crop Protection
Grain and Cereal Crop Protection Market
Crop Protection
Vietnam Insecticide Market
Crop Protection
Global Home and Garden Pesticides Market
Crop Protection
China Insecticide Market
Crop Protection
Vietnam Crop Protection Chemicals Market